
 Children Furniture Market | 2026-2036
Children Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Children Furniture Market Analysis
Direct-to-consumer e-commerce is tilting the balance of power away from traditional brick-and-retail networks in children furniture. Wayfair leverages its digital-native platform to capture search-driven purchase journeys, while IKEA anchors its position through flat-pack logistics and in-store experience hybrids. Delta Children competes on certified safety credentials and mass-market accessibility across North American big-box channels.
Children furniture encompasses beds, desks, chairs, and storage units engineered to dimensional, ergonomic, and safety specifications for users from toddler through teenage years, typically manufactured from wood, metal, plastic, or fabric composites with rounded edges, non-toxic finishes, and adjustable height mechanisms to accommodate developmental stages. Beds and storage units command the largest revenue share due to replacement cycles tied to age transitions, while desks are gaining momentum as dedicated study spaces become standard in homes with school-age children. Wood materials dominate premium positioning because of durability perceptions and aesthetic versatility, though plastic segments capture volume in toddler-focused price tiers.
The CPSC enforces mandatory safety standards for cribs and juvenile products in the United States, while REACH and the EU Green Deal constrain chemical inputs and carbon footprints for European suppliers, and China's GB standards govern structural stability and labeling for domestic consumption. Regulatory divergence across these jurisdictions forces manufacturers to maintain multiple certification pipelines, adding cost but also creating barriers against uncertified imports. Stakeholders must track how evolving extended producer responsibility frameworks in Europe and state-level furniture flammability amendments in the United States will reshape compliance budgets and sourcing geographies.
Market Dynamics
Urban middle-class households in China are compressing replacement cycles for children's bedroom furniture, while REACH chemical compliance and CPSC juvenile product standards are forcing parallel certification pipelines that reshape cost structures for cross-border suppliers.
Growth Catalysts
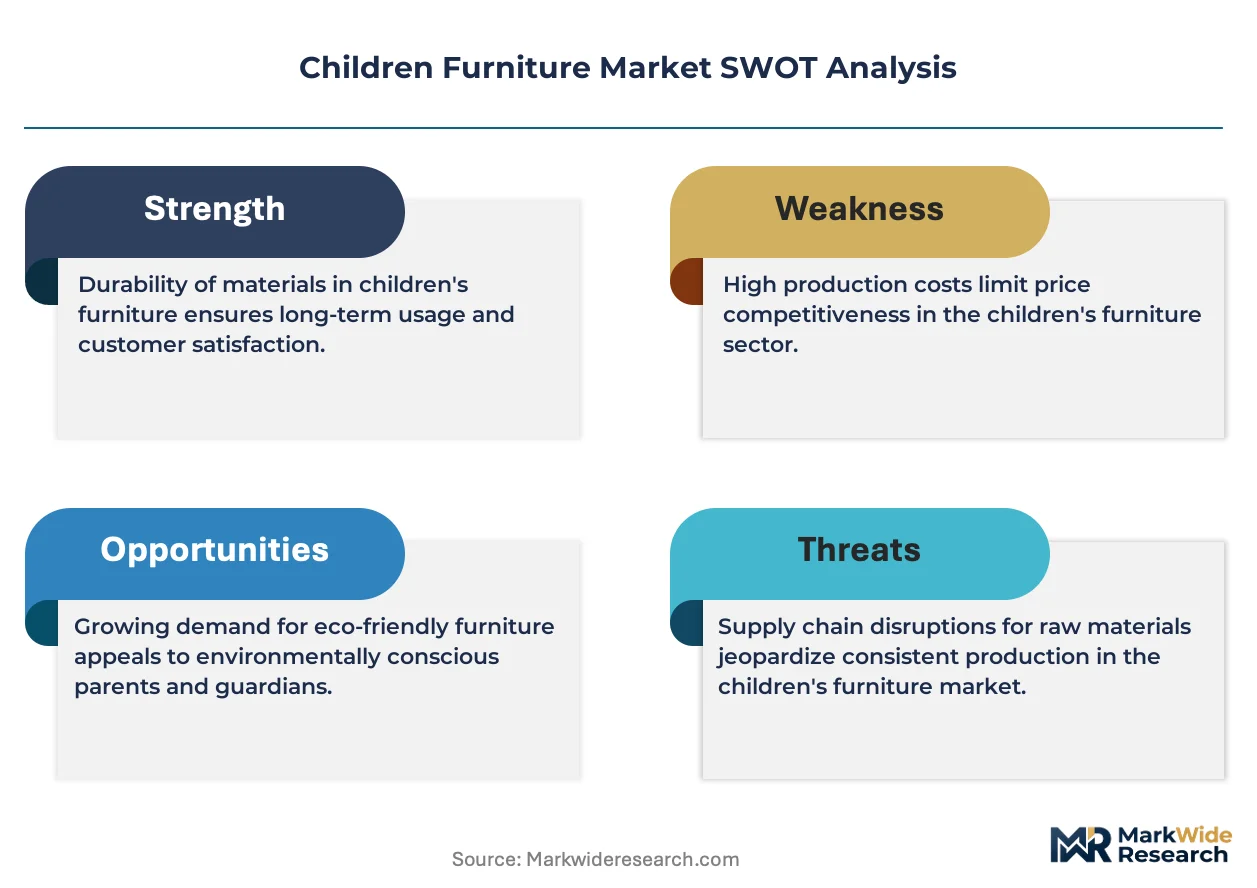
- EU Green Deal carbon constraints:Manufacturers investing in low-emission finishing processes gain preferential access to European retail channels and public procurement frameworks.
- Adjustable-height desk mechanisms:Ergonomic hardware innovation extends product lifespans across developmental stages, reducing parental replacement hesitation.
- Urban density in Chinese tier-1 cities:Smaller apartment footprints drive demand for multifunctional storage-integrated bed systems.
Market Restraints
- Baltic birch plywood supply concentration:Sourcing dependency on specific forest certification regions creates input cost volatility for premium wood segments.
- REACH SVHC screening requirements:European chemical substance restrictions extend compliance timelines and testing expenditures for imported components.
- Flat-pack assembly complexity:Technical limitations in tool-free connection systems limit durability perceptions among repeat buyers.
Strategic Opportunities
- India's urban nuclear family formation:Underpenetrated organized retail penetration in secondary cities creates whitespace for safety-certified imported brands.
- Extended Producer Responsibility frameworks:EU circular economy mandates incentivize take-back programs and modular repairable designs.
- Augmented reality visualization tools:Convergence of spatial computing with e-commerce platforms collapses purchase decision friction in remote buying journeys.
Industry Challenges
- Third-party laboratory certification backlogs:CPSC-accredited testing facility capacity constraints delay product launch timelines for seasonal selling windows.
- Legacy ERP integration with traceability systems:Supply chain reconfiguration friction impedes real-time material origin documentation required by European customs authorities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Children Furniture Market |
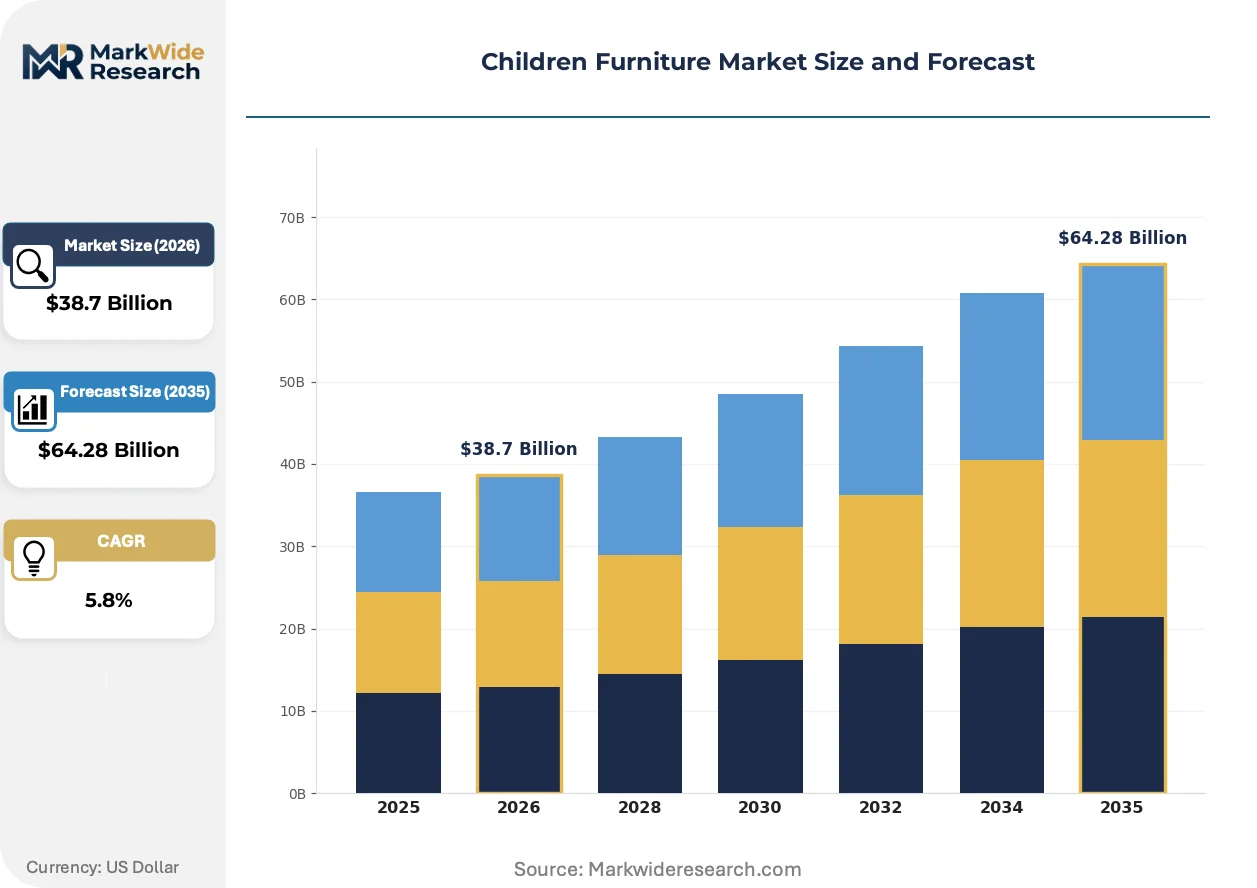
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beds, Desks, Chairs, Storage Units Material: Wood, Metal, Plastic, Fabric Age Group: Toddlers, Preschool, Elementary, Teenagers Style: Modern, Rustic, Themed, Minimalist |
| Companies Covered | IKEA, Delta Children, Ashley Furniture Industries, Williams-Sonoma, Pottery Barn Kids, Wayfair, KidKraft, Casa Kids, Circu Magical Furniture, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Children Furniture Market Emerging Trajectories
Material science advances and digital channel evolution are restructuring how children's furniture is specified, certified, and delivered to household buyers across income tiers.
Cross-laminated timber panels engineered from fast-growth plantation species are collapsing the cost gap between solid hardwood and composite alternatives in mid-market bed frames. Scandinavian manufacturers have accelerated adoption, compressing traditional three-tier material stratification into two dominant grades. The structural consequence is collapsing premium positioning for conventional oak and maple suppliers.
REACH Annex XVII restrictions on formaldehyde emissions in wood-based panels are tightening allowable thresholds for European-market children's furniture. Manufacturers must reformulate adhesive systems or source certified zero-add alternatives, increasing R&D allocation for suppliers serving German and French retail chains. The segment most affected is particleboard-based storage furniture, where reformulation costs are being passed through to wholesale pricing.
Parents of school-age children are compressing purchase research into mobile-native discovery platforms, displacing traditional big-box showroom visits. Direct-to-consumer brands with 3D configuration tools and virtual room placement are capturing consideration-phase traffic previously owned by legacy retailers. This behavioral shift is most visible in United States suburban markets where two-income households prioritize convenience over tactile pre-purchase evaluation.
Children Furniture Market Segmentation
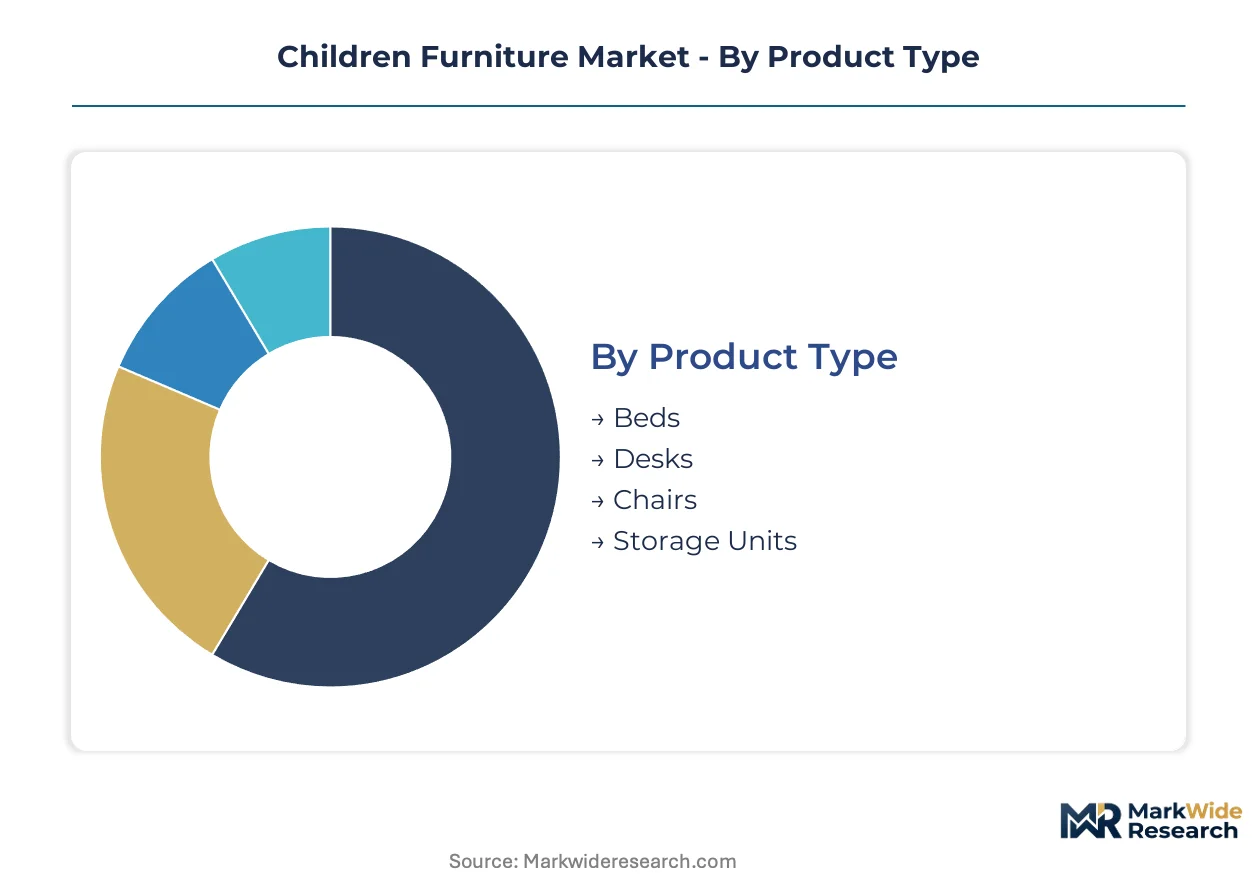
Children furniture segmentation reveals divergent replacement dynamics across age transitions and material durability perceptions. Manufacturers calibrate inventory depth and warranty terms against these cycle-time differentials.
Product Type:
Beds and storage units turn over every 5-7 years as children age through height milestones, while desks and chairs compress replacement windows through adjustable mechanism upgrades.
- Beds:Platform and bunk configurations dominate revenue concentration, engineered with reinforced slat systems for weight progression through teenage years. Chinese urban middle-class households drive premium upgrades for multifunctional storage-integrated systems in tier-1 cities.
- Storage Units:Modular closet systems and toy organizers command repeat purchase frequency as family size and space constraints evolve. REACH formaldehyde restrictions on particleboard substrates elevate certified zero-add alternatives in German and French retail channels.
- Desks:Height-adjustable study surfaces extend functional lifespan across developmental stages.
- Chairs:Ergonomic seating with lumbar support targets school-age children in dedicated homework spaces.
Beds anchor the volume base while desks gain share at the steepest rate.
Material:
Cost tier stratification separates premium durability positioning from volume accessibility, with certification requirements adding friction at each price band.
- Wood:Solid hardwood and cross-laminated timber panels dominate premium positioning through durability perceptions and aesthetic versatility. Baltic birch plywood sourcing concentration creates input cost volatility for mid-market suppliers.
- Plastic:Injection-molded polypropylene captures toddler-focused price tiers with rounded-edge safety compliance. CPSC juvenile product standards mandate specific impact resistance thresholds for US-market distribution.
- Metal:Powder-coated steel frames serve institutional and commercial childcare applications.
- Fabric:Upholstered headboards and seating components require flame-retardant treatments under state-level US amendments.
Wood commands margin leadership while plastic expands volume accessibility most aggressively.
Age Group:
Customer lifetime value concentrates in early-stage segments with higher per-child spend, while teenage transitions compress unit economics through extended replacement intervals.
- Toddlers:Crib-to-bed conversion products and low-profile storage systems carry the shortest replacement cycles as safety standards evolve rapidly. CPSC mandatory standards for cribs and juvenile products enforce rigorous third-party testing protocols.
- Preschool:Activity tables and scaled seating align with early learning environment replication in homes. Parents in this segment demonstrate rising purchase frequency for developmental stage matching.
- Elementary:Dedicated study furniture becomes standard as homework routines formalize.
- Teenagers:Full-size bed transitions and personalized aesthetic expression drive final household furniture investments per child.
Preschool segments generate the highest repeat purchase velocity while toddler safety compliance costs concentrate manufacturer R&D allocation.
Style:
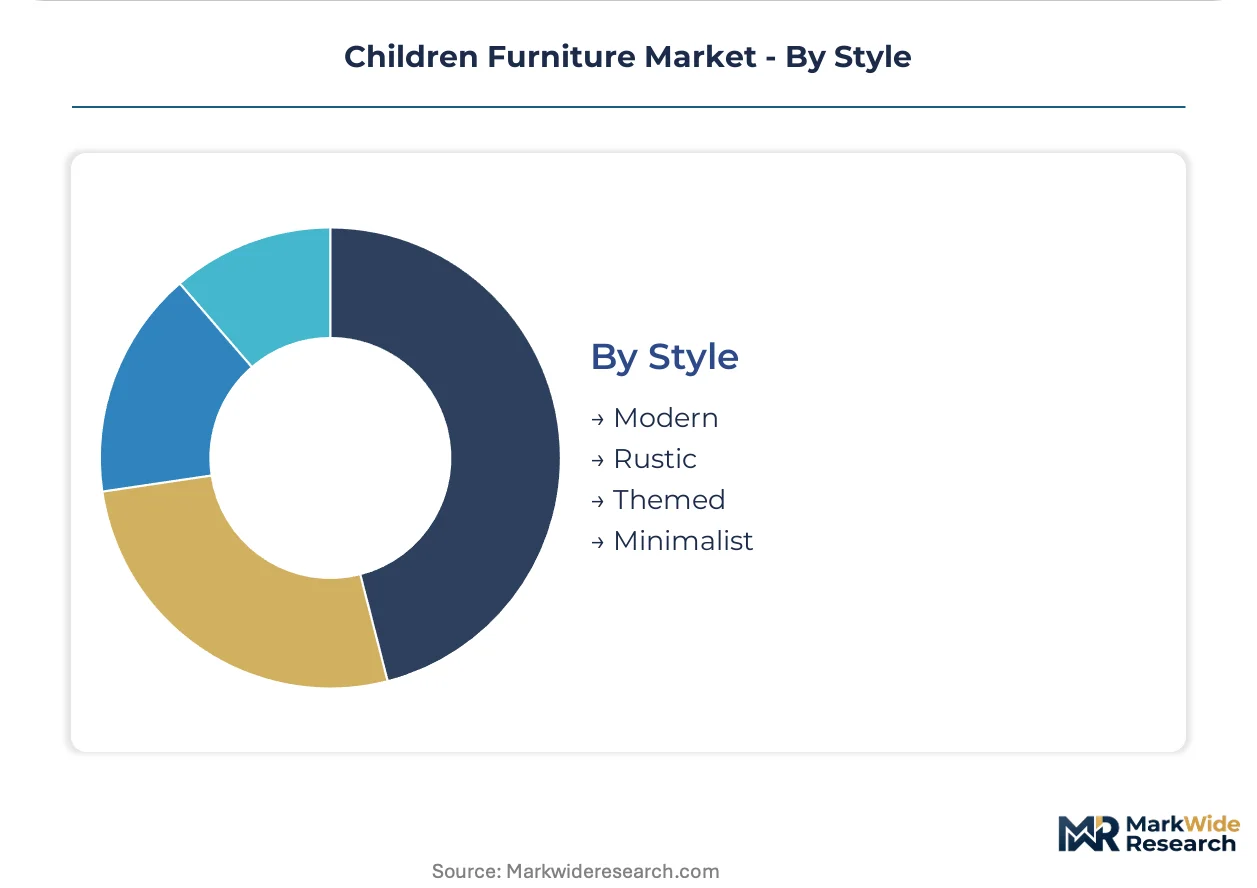
Design orientation segments align parental identity expression with functional requirements, creating distinct channel and marketing investment profiles.
- Modern:Clean lines and neutral palettes dominate direct-to-consumer e-commerce photography and 3D visualization tools. Scandinavian manufacturers have accelerated cross-laminated timber adoption, compressing traditional material stratification.
- Rustic:Distressed finishes and visible wood grain target farmhouse aesthetic preferences in US suburban markets.
- Themed:Licensed character and fantasy motifs capture gift purchase occasions with shorter functional lifespans.
- Minimalist:Concealed hardware and monochromatic schemes align with urban density constraints in Chinese tier-1 cities.
Modern styling leads e-commerce conversion rates while themed designs exhibit the steepest seasonal demand fluctuation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH chemical safety standards and CPSC juvenile product guidelines are forcing parallel certification investments across major demand centers, compressing margins for cross-border suppliers while creating protected markets for compliant domestic producers.
United States
Suburban two-income households prioritize convenience-driven e-commerce channels for children's bedroom furniture purchases. CPSC mandatory standards for cribs and juvenile products enforce rigorous third-party testing protocols that extend product launch timelines. The Southeast manufacturing corridor around North Carolina furniture clusters concentrates domestic production capacity for mass-market wooden bed frames.
China
Urban middle-class families in tier-1 cities compress replacement cycles for multifunctional storage-integrated bed systems. GB standards govern structural stability and labeling requirements for domestic consumption, while MIIT industrial policies incentivize low-emission finishing process upgrades. The Yangtze River Delta manufacturing belt around Shanghai anchors export-oriented production for European and North American retailers.
Germany
REACH Annex XVII formaldehyde emission restrictions drive reformulation of adhesive systems in wood-based panel furniture. The EU Green Deal carbon constraints favor manufacturers investing in certified zero-add alternatives for public procurement frameworks. The Baden-Württemberg industrial region hosts specialized suppliers of ergonomic adjustable-height desk mechanisms.
India
Nuclear family formation in secondary cities creates whitespace for safety-certified imported brands entering organized retail channels. BIS standards for furniture safety and quality provide baseline compliance frameworks as the market formalizes. The Maharashtra-Gujarat industrial corridor concentrates domestic manufacturing capacity for plastic and metal toddler-focused furniture segments.
United Kingdom
Direct-to-consumer brands with 3D configuration tools capture consideration-phase traffic from legacy big-box showroom visits. CE marking requirements align with REACH chemical substance restrictions for European market access. The Midlands furniture manufacturing cluster maintains specialized capabilities for premium solid hardwood children's bed production.
Children Furniture Market Vendor Landscape
On the supply side, the industry is structured around three distinct tiers: mass-market volume players, mid-market safety-certified specialists, and premium design-forward brands. Digital-native retailers and flat-pack logistics innovators compete against traditional brick-and-mortar networks with in-store experience hybrids. Strategic archetypes include safety credential aggregators, ergonomic hardware innovators, and direct-to-consumer platform operators. Competitive moves concentrate on e-commerce capability building and certified supply chain reconfiguration.
Among Scandinavian-origin flat-pack specialists, IKEA exemplifies logistics-anchored market penetration through in-store and digital channel integration. Delta Children occupies a position within the North American safety-certified mass-market tier, leveraging CPSC compliance credentials across big-box retail distribution. Wayfair represents the digital-native platform archetype, capturing search-driven purchase journeys through spatial computing and visualization tools.
| Leading Market Players |
|---|
| IKEA |
| Delta Children |
| Ashley Furniture Industries |
| Williams-Sonoma |
| Pottery Barn Kids |
| Wayfair |
| KidKraft |
| Casa Kids |
| Circu Magical Furniture |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta manufacturing belt around Shanghai anchors export-oriented production capacity for European and North American retailers, concentrating finishing expertise and flat-pack logistics infrastructure that translates into downstream pricing power for compliant suppliers serving REACH and CPSC markets.
Pricing Analysis
Certification level creates the primary spread between premium and volume tiers, with REACH zero-add formaldehyde credentials and CPSC juvenile product testing separating certified suppliers from commodity competitors. Three-tier pricing structure across premium solid hardwood, mid-market cross-laminated timber, and economy particleboard segments reflects material durability perceptions and regulatory compliance costs. Cost compression in particleboard storage furniture is intensifying as adhesive reformulation expenses pass through to wholesale pricing. Mass-market big-box buyers exhibit highest price sensitivity, while urban Chinese middle-class households in tier-1 cities demonstrate lowest sensitivity for multifunctional storage-integrated systems.
Supply Chain Analysis
Contract manufacturers concentrated in China's Yangtze River Delta, Vietnam's northern industrial provinces, and Poland's woodworking clusters hold capacity for European and North American retail private-label programs. Baltic birch plywood sourcing from certified forest regions in Estonia, Latvia, and Finland feeds premium wood segment production, while fast-growth plantation eucalyptus from Brazil and Indonesia supplies cross-laminated timber panel alternatives. Single-source vulnerability in CPSC-accredited third-party testing facilities creates launch timeline risk for seasonal selling windows. Distribution runs through direct-to-consumer e-commerce platforms, big-box retail consolidation centers, and IKEA's hybrid in-store and digital fulfillment network.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of integrated safety certification and ergonomic hardware engineering capabilities constrains competitive entry, privileging incumbents with established CPSC and REACH compliance pipelines and penalizing suppliers lacking real-time material traceability systems.
For Market Incumbents: Harden defensive positions by deepening backward integration into certified zero-add adhesive production and captive Baltic birch plywood supply, insulating margin structures from input cost volatility. Accelerate ERP integration with blockchain-enabled material origin documentation to preempt European customs authority requirements. Prioritize ergonomic hardware R&D investment in adjustable-height desk mechanisms to extend product lifespans and compress competitor replacement windows.
For New Entrants and Emerging Players: Pursue whitespace in India's secondary cities where nuclear family formation outpaces organized retail penetration for safety-certified children's furniture. Target direct-to-consumer e-commerce entry with augmented reality visualization tools to collapse purchase decision friction among mobile-native parents. Leverage modular repairable design architectures to align with EU Extended Producer Responsibility take-back program incentives.
For Investors and Strategic Acquirers: Long-term, this sits as a certification-anchored consolidation play because REACH and CPSC compliance pipelines create durable barriers against uncertified imports and reward scale economies in testing expenditure. Acquisition targets should exhibit integrated safety credential portfolios and established big-box retail distribution relationships. Monitor CPSC laboratory certification backlog durations as an inflection indicator for launch timeline risk and working capital pressure across the supplier base.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH Zero-Add Adhesive Reformulation | Reformulation investment secures German and French retail channel access under tightening formaldehyde emission thresholds. |
| Ergonomic Hardware Patent Portfolio | Adjustable-height mechanism IP extends functional lifespan and differentiates against commodity bed frame competitors. |
| Direct-to-Consumer AR Platform Launch | Spatial computing integration captures mobile-native parent consideration-phase traffic from legacy showroom networks. |
| EU Take-Back Program Infrastructure | Modular repairable design and reverse logistics capability align with Extended Producer Responsibility circular economy mandates. |
| Baltic Birch Plywood Supply Security | Long-term offtake agreements with Estonian and Latvian certified forest operators reduce input cost volatility exposure. |
Methodological Framework
Cross-validation between primary interviews with product development directors at Scandinavian flat-pack manufacturers, CPSC compliance officers at North American mass-market suppliers, and category buyers at German retail chains anchors the qualitative findings. Secondary validation draws from customs trade data for wood-based panel imports, SEC 10-K filings for publicly listed furniture retailers, REACH SVHC substance restriction updates, and CPSC recall databases. Bottom-up demand modeling across age group transitions and material durability perceptions triangulates with top-down market sizing from production capacity estimates in the Yangtze River Delta and Baden-Württemberg industrial regions.
Calibration against historical replacement cycle data for beds, storage units, and desks refines projection parameters across the modeling period. Segmentation dimensions include product type, material grade tier, age group developmental stage, and regional regulatory cluster. CAGRs derive from regression analysis of urban household formation rates, premium upgrade propensity in Chinese tier-1 cities, and compliance cost pass-through elasticity. Industry-specific forecast inputs incorporate REACH Annex XVII amendment timelines and CPSC juvenile product standard revision schedules.
Sensitivities concentrate around REACH formaldehyde threshold tightening, CPSC laboratory capacity constraints, and Baltic birch plywood supply disruption from forest certification region weather events. Forecasts reflect documented assumptions regarding middle-class income trajectory in Chinese urban centers and e-commerce penetration rates among suburban US households. Quarterly review of CPSC recall frequency, REACH SVHC candidate list expansions, and Yangtze River Delta manufacturing PMI readings is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Sanded Plywood Market
Furniture
Lecterns Market
Furniture
Russia Home Furniture Market
Furniture
Furniture & Cabinet Hardware Market
Furniture
Fireplace Mantels Market
Furniture
Outdoor Furniture and Grills Market
Furniture
North America Free Standing Electrical Height-Adjustable Tables Market
Furniture
UK Multifunctional Furniture Market
Furniture
North America High-End Furniture Market
Furniture
Canada Home Furniture Market
Furniture
Asia-Pacific Free Standing Electrical Height-Adjustable Tables Market
Furniture
Rattan Furniture Market
Furniture
Global Multifunctional Furniture Market
Furniture
China Furniture Market
Furniture
Italy Furniture Market
Furniture
Europe Sustainable Furniture Market