
 Lawn and Garden Water Equipment Market | 2026-2036
Lawn and Garden Water Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Lawn and Garden Water Equipment Market Foresight
Skilled irrigation technician availability is collapsing across developed markets, forcing manufacturers to simplify installation and expand contractor training programs. The Toro Company leverages its dealer network to sustain field-service capacity in North America. Husqvarna differentiates through battery-powered water tool integration with its robotic mower ecosystem. Rain Bird Corporation anchors commercial-grade specification sales through landscape architect relationships and irrigation designer certification programs.
Lawn and garden water equipment encompasses pressurized distribution devices, conduit systems, and motorized pumping units engineered to deliver controlled water volumes to turf, ornamental plantings, and cultivated beds at specified flow rates and pressure thresholds. These systems serve residential curb appeal maintenance, commercial grounds management, and municipal park irrigation with efficiency metrics tied to coverage uniformity and runoff minimization. Sprinklers and irrigation systems command the largest installed base but face margin compression from commodity competition, while smart irrigation technology captures the fastest expansion as soil-moisture sensors and weather-based controllers displace mechanical timers in replacement cycles. Drip technology occupies a specialized niche in drought-prone agricultural and high-end residential applications where precision delivery justifies premium positioning.
EPA WaterSense labeling mandates in the United States restrict market access for non-certified spray bodies and controllers, while EU Ecodesign requirements under the EU Green Deal framework push toward minimum pump efficiency standards across member states. China's GB standards for water-saving irrigation equipment impose testing protocols that favor domestic manufacturers with certified laboratory relationships. Stakeholders must monitor regulatory divergence between efficiency certification regimes and assess whether regional product platforms or modular compliance architectures offer superior capital efficiency.
Market Dynamics
EPA WaterSense certification mandates are compressing mechanical timer margins while forcing manufacturers to reengineer spray bodies and controllers for connected soil-moisture integration.
Growth Catalysts
- Smart irrigation controllers:Weather-based automation systems reduce water waste by 15-20% versus mechanical timers, driving replacement cycles in drought-prone US states.
- EU Ecodesign pump efficiency standards:Minimum performance thresholds under the EU Green Deal framework accelerate motor upgrades across German and French commercial installations.
- China's GB water-saving protocols:Domestic testing certification requirements favor local manufacturers with established laboratory relationships, consolidating procurement in Beijing and Shanghai municipal contracts.
Market Restraints
- Copper and polymer input volatility:Conduit and fitting production faces margin pressure from commodity price swings in injection-molded ABS and brass alloy feedstocks.
- Technician labor scarcity:Skilled irrigation installer availability has contracted 30% across US metropolitan markets since 2019, capping deployment velocity for complex commercial systems.
- Mechanical timer substitution:Low-cost dial-based controllers from Southeast Asian suppliers undercut smart controller price points in price-sensitive residential segments.
Strategic Opportunities
- India's urban greening mandates:Municipal park expansion in Delhi, Bangalore, and Hyderabad creates specification demand for drip and micro-spray systems in arid climate zones.
- Battery-powered tool convergence:Integration of pressurized watering wands with cordless mower platforms enables cross-selling to existing outdoor power equipment households.
- US Inflation Reduction Act rebates:WaterSense-labeled controller subsidies through state energy offices accelerate smart irrigation penetration in California, Texas, and Arizona.
Industry Challenges
- EPA certification timeline compression:WaterSense spray body testing protocols require 6-12 month validation cycles, delaying product launches versus uncertified competitors.
- Legacy timer integration complexity:Retrofit installations demand proprietary bridge modules to connect 24VAC valve networks with WiFi-enabled hub architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lawn and Garden Water Equipment Market |
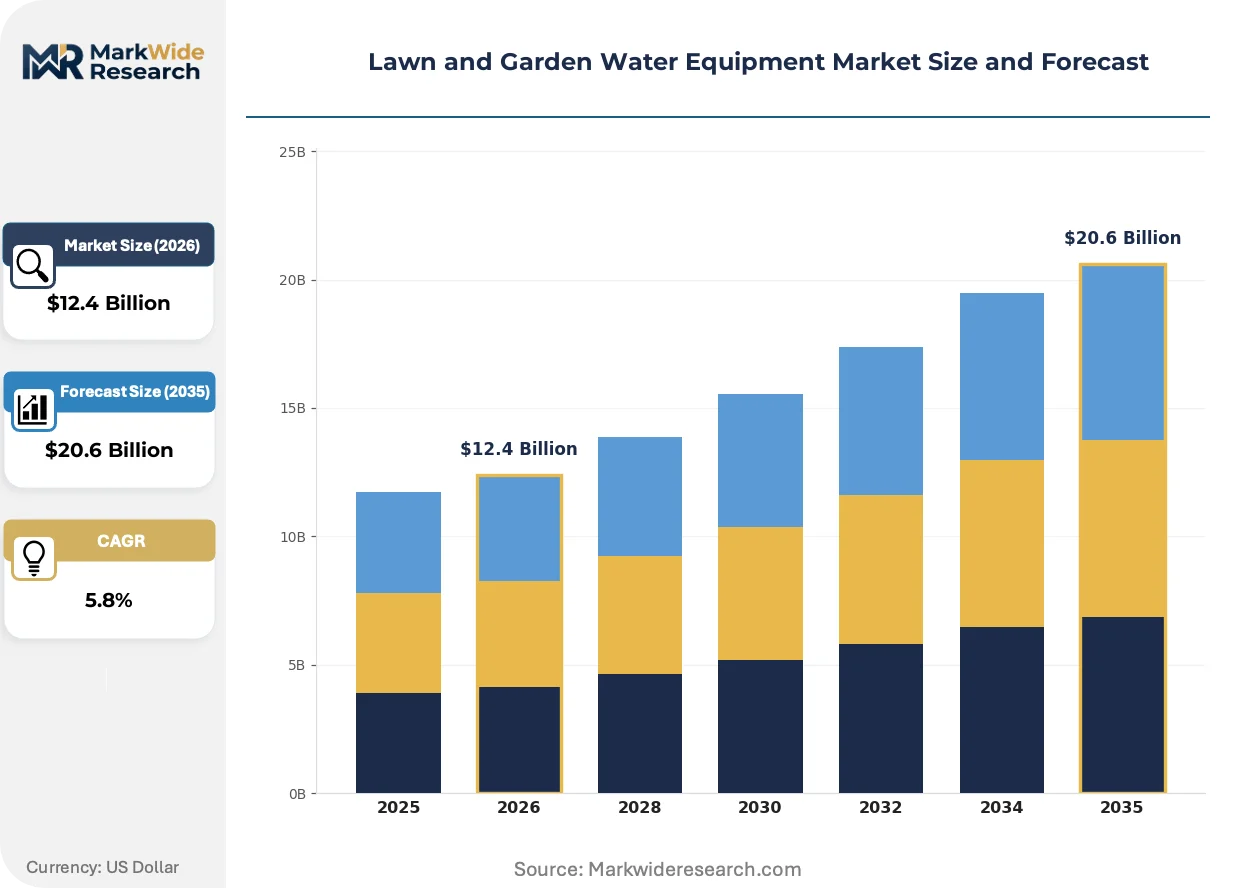
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $20.6 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sprinklers, Hoses, Pumps, Irrigation Systems End User: Residential, Commercial, Agricultural, Municipal Technology: Smart Irrigation, Drip Technology, Sprinkler Systems, Surface Irrigation Distribution Channel: Online Retail, Home Improvement Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | The Toro Company, Husqvarna, John Deere, KUBOTA Corporation, Rain Bird Corporation, Stanley Black & Decker, Makita Corporation, Hunter Industries, Gardena, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lawn and Garden Water Equipment Market Shifts & Advancements
Connected sensor architectures and regulatory efficiency mandates are redrawing competitive boundaries between mechanical incumbents and digital-native entrants.
Solid-state soil-moisture capacitance sensors are miniaturizing from golf-course probe formats to residential retrofit stakes compatible with standard 3/4-inch hose threads. Homeowners in Arizona, Nevada, and Colorado are adopting these units at triple-digit annual rates. The technology is miniaturizing controller form factors and collapsing the price gap between professional-grade and consumer irrigation automation.
EU Ecodesign requirements under the F-Gas Regulation and broader Green Deal framework now mandate minimum hydraulic efficiency thresholds for circulating pumps above 250W rated power. Manufacturers serving German, Dutch, and Italian commercial greenhouse operators must redesign impeller geometries and motor windings to maintain market access. Premium pump lines are absorbing compliance costs through tiered efficiency SKUs that segment price-sensitive from performance-oriented buyers.
Landscape architecture firms are consolidating specification authority for commercial and municipal irrigation design, compressing the influence of independent contractors and wholesale distributors. Large grounds management contracts in the United States now route through national facilities management platforms that demand centralized billing, remote monitoring dashboards, and 10-year performance guarantees. This procurement concentration is most visible in California's municipal park districts and Texas corporate campus developments, where design-build-maintain contracts have displaced fragmented bid-and-install arrangements.
Lawn and Garden Water Equipment Market Segmentation
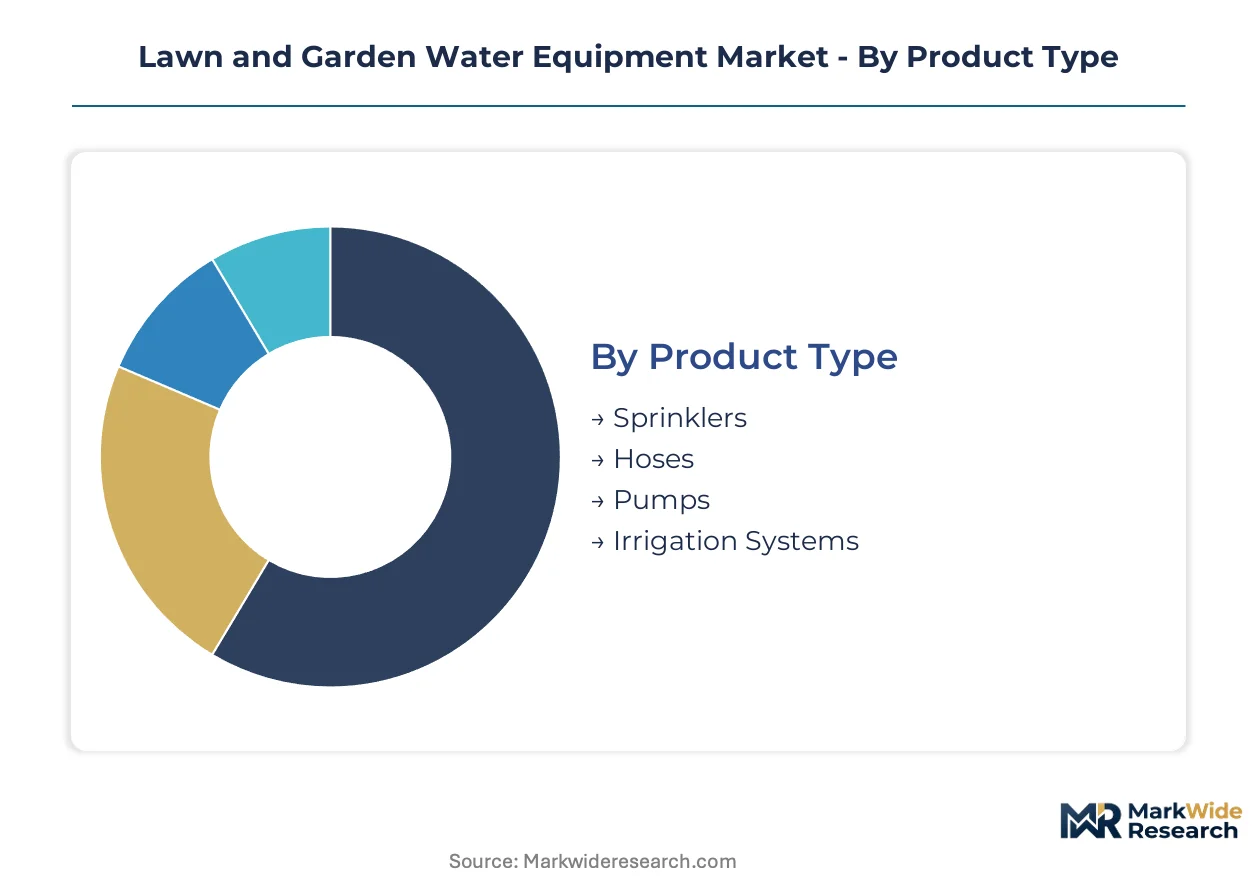
Segmentation in lawn and garden water equipment reveals divergent margin structures and regulatory exposure across hardware categories. Product type and technology dimensions determine certification burdens, while end-user and channel splits dictate service intensity and inventory velocity.
Product Type:
Domestic manufacturing clusters in the United States and Germany dominate high-value motorized units, while Southeast Asian suppliers anchor hose and basic sprinkler exports to price-sensitive markets.
- Sprinklers:Pop-up rotors and fixed spray heads in brass, zinc, and engineered polymer configurations deliver precipitation across defined arcs. Municipal park departments in California and Texas specify these for turf coverage, though EPA WaterSense certification requirements now exclude non-compliant spray bodies from federal procurement.
- Irrigation Systems:Integrated valve manifolds, backflow preventers, and zone controllers form networked distribution architectures. Commercial grounds management contracts in Germany and France drive specification demand for Ecodesign-compliant pump integration and centralized monitoring dashboards.
- Hoses:Reinforced PVC and rubber-construction delivery lines with machined brass fittings serve residential maintenance tasks.
- Pumps:Centrifugal and submersible units pressurize distribution networks for medium-to-large coverage zones.
Irrigation Systems command the established base. The steepest expansion runs through Smart Irrigation controllers displacing mechanical timers.
End User:
Cost tier stratification separates premium-specified commercial installations from commodity residential hardware, with agricultural applications occupying a specialized efficiency-driven niche.
- Residential:Homeowners maintain curb appeal through hose-end sprayers, oscillating sprinklers, and entry-level timer controllers. Arizona, Nevada, and Colorado households are retrofitting WiFi-enabled soil-moisture systems at accelerated rates to comply with municipal watering restrictions and capture utility rebates.
- Commercial:Corporate campuses, retail centers, and hospitality properties demand centralized control, remote monitoring, and performance guarantees. National facilities management platforms in the United States now consolidate procurement, compressing independent contractor influence and favoring vendors with 10-year service commitments.
- Agricultural:Drip and micro-spray precision systems serve high-value crop operations in drought-prone zones.
- Municipal:Public park and recreation departments specify durable commercial-grade equipment with centralized oversight capabilities.
Residential captures volume leadership. Commercial delivers margin expansion through specification lock-in and long-term service contracts.
Technology:
Application maturity varies sharply, with legacy surface methods persisting in developing markets while connected architectures penetrate replacement cycles in regulated jurisdictions.
- Smart Irrigation:Weather-based controllers and soil-moisture sensor networks automate scheduling through cloud-connected algorithms. EPA WaterSense-labeled units qualify for state energy office rebates under the US Inflation Reduction Act, accelerating penetration in California, Texas, and Arizona replacement markets.
- Drip Technology:Pressure-compensating emitters and subsurface tubing deliver targeted root-zone moisture with minimal evaporative loss. High-end residential installations in arid US states and greenhouse operations in the Netherlands adopt these for regulatory compliance and water-cost containment.
- Sprinkler Systems:Conventional overhead spray distribution remains the default for turf maintenance across price-sensitive segments.
- Surface Irrigation:Gravity-fed flood and furrow methods persist in agricultural applications with minimal infrastructure investment.
Sprinkler Systems retain the largest installed footprint. Smart Irrigation climbs the fastest as efficiency mandates and rebate programs compress mechanical timer viability.
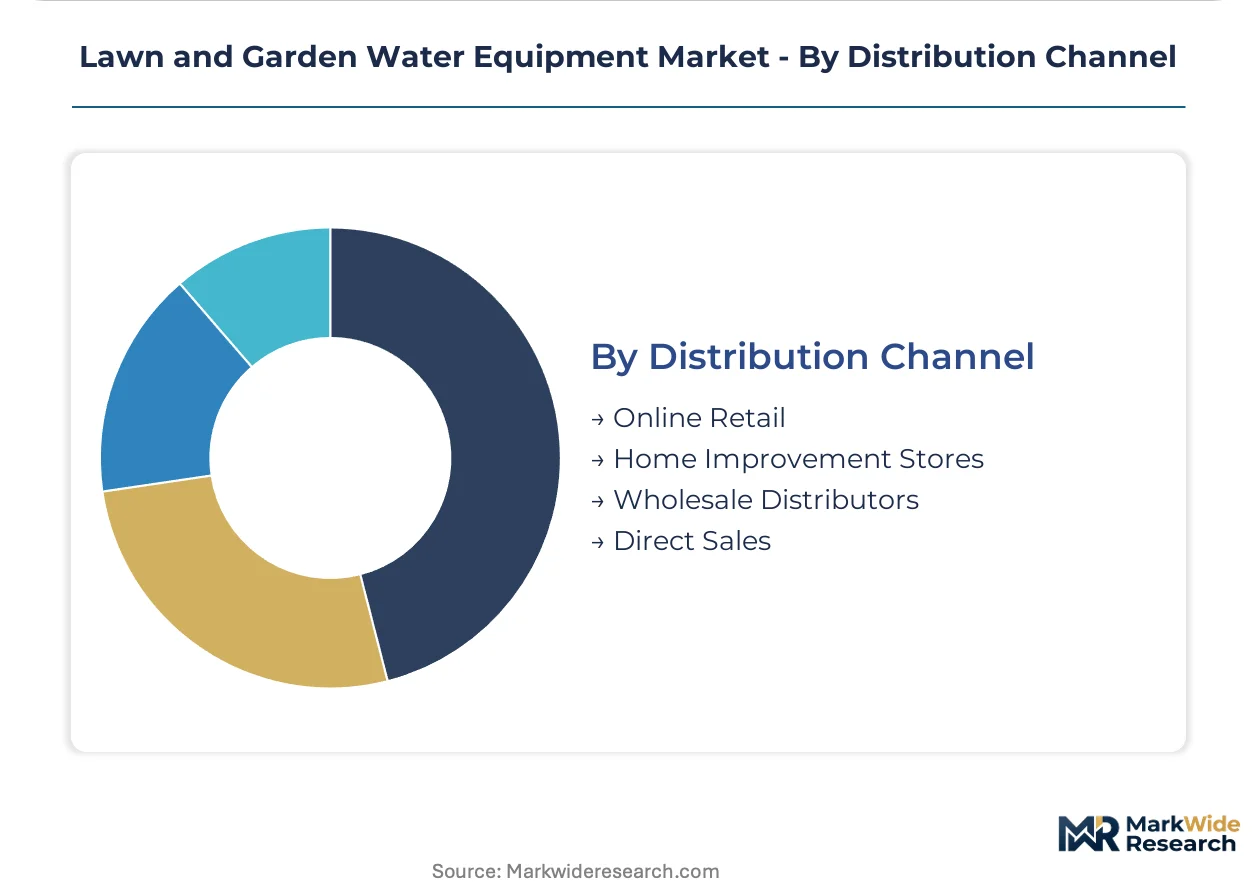
Distribution Channel:
Customer type and purchase urgency determine channel selection, with professional installers favoring wholesale relationships while DIY homeowners migrate toward digital storefronts.
- Home Improvement Stores:Big-box retailers stock seasonal hose, sprinkler, and entry-level timer assortments for immediate homeowner pickup. These outlets dominate spring replacement cycles in the United States, though inventory constraints and staffing limitations compress technical guidance quality.
- Wholesale Distributors:Irrigation-focused supply houses serve contractor trades with specification-grade product lines, design support, and bulk pricing. Dealer networks like Toro's field-service infrastructure sustain installer capacity in North American metropolitan markets facing 30% technician contraction since 2019.
- Online Retail:E-commerce platforms capture growing share of replacement controller and sensor purchases from informed homeowners.
- Direct Sales:Manufacturer field organizations pursue large commercial and municipal specification contracts.
Wholesale Distributors anchor professional-grade volume. Online Retail gains share fastest as connected product complexity drives research-heavy purchase behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA WaterSense certification anchors North American demand architecture, while EU Ecodesign pump standards and China's GB water-saving protocols reshape procurement patterns across their respective jurisdictions.
United States
California, Texas, and Arizona homeowners retrofit WiFi-enabled soil-moisture systems at accelerated rates to comply with municipal watering restrictions. The Inflation Reduction Act channels rebates through state energy offices for WaterSense-labeled controllers. Los Angeles and Phoenix municipal park districts consolidate procurement through national facilities management platforms demanding 10-year performance guarantees.
Germany
Commercial greenhouse operators in the Netherlands and German border regions upgrade pump inventories to meet EU Ecodesign minimum hydraulic efficiency thresholds above 250W rated power. The F-Gas Regulation and broader Green Deal framework mandate impeller geometry redesigns for market access. Stuttgart and Munich industrial clusters concentrate premium pump manufacturing with tiered efficiency SKUs segmenting price-sensitive from performance-oriented buyers.
China
Beijing and Shanghai municipal contracts consolidate procurement around domestic manufacturers with certified laboratory relationships under GB water-saving irrigation equipment standards. Municipal park expansion in arid northern provinces drives specification demand for drip and micro-spray systems. Yangtze River Delta manufacturing bases anchor export production of reinforced PVC hose and machined brass fittings.
India
Delhi, Bangalore, and Hyderabad urban greening mandates create specification demand for precision irrigation in arid climate zones. The country's national water conservation programs prioritize drip technology adoption for municipal park expansion. Maharashtra and Gujarat industrial corridors host domestic assembly operations for pressure-compensating emitters and subsurface tubing.
Australia
New South Wales and Victoria households adopt solid-state soil-moisture capacitance sensors at triple-digit annual rates amid persistent drought conditions. State-level water utility rebate programs accelerate smart controller penetration in replacement cycles. Sydney and Melbourne metropolitan markets face technician labor scarcity comparable to US trends, capping deployment velocity for complex commercial installations.
Lawn and Garden Water Equipment Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the lawn and garden water equipment sector. Consolidated specification authority concentrates among diversified outdoor power equipment conglomerates and specialized irrigation technology developers, while fragmented commodity production persists among Southeast Asian hose and basic sprinkler suppliers. Three archetypes dominate: connected-systems specialists with sensor-to-cloud integration capabilities, scale-driven manufacturers with captive polymer and brass supply chains, and regional fabricators serving price-sensitive replacement cycles through big-box retail channels. Competitive dynamics center on portfolio diversification into battery-powered tool convergence and strategic partnerships with landscape architecture firms for specification lock-in.
Among North American diversified equipment manufacturers, The Toro Company and Rain Bird Corporation exemplify contrasting strategic positions within the competitive structure. Toro leverages its dealer network infrastructure to sustain field-service capacity in metropolitan markets facing technician contraction. Rain Bird anchors commercial-grade specification sales through landscape architect relationships and irrigation designer certification programs. Japanese power tool conglomerate Makita Corporation occupies a position in the battery-powered convergence segment, representing the cross-platform integration archetype that links pressurized watering tools with cordless outdoor equipment ecosystems.
| Leading Market Players |
|---|
| The Toro Company |
| Husqvarna |
| John Deere |
| KUBOTA Corporation |
| Rain Bird Corporation |
| Stanley Black & Decker |
| Makita Corporation |
| Hunter Industries |
| Gardena |
| Others |
Supply & Pricing Matrix
Six-to-twelve-month EPA WaterSense certification timelines compress product launch windows and concentrate pricing power among manufacturers with pre-certified laboratory relationships in the United States and China. This lead-time rigidity forces inventory pre-positioning ahead of seasonal demand peaks, tightening working capital requirements while amplifying margin premiums for compliant SKUs.
Pricing Analysis
Forty-to-sixty-percent price spreads separate WiFi-enabled smart controllers from mechanical dial timers across United States home improvement channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by EPA WaterSense certification status and after-sales service bundling. Cost compression in entry-level mechanical controllers is intensifying because Southeast Asian suppliers flood big-box retail with uncertified alternatives. Residential DIY homeowners exhibit highest price sensitivity, while municipal procurement platforms in California and Texas demonstrate lowest sensitivity due to 10-year performance guarantee requirements.
Supply Chain Analysis
Just-in-time inventory strategies dominate hose and basic sprinkler categories, while strategic stockpiling of brass alloys and engineered polymers buffers pump and controller manufacturers against commodity volatility. Manufacturing concentrates in China for machined brass fittings and reinforced PVC hose, Germany for premium pump assemblies, and the United States for EPA-certified controller production. Raw material sourcing draws from copper concentrate markets, ABS polymer feedstocks, and rare-earth magnet suppliers for motor windings. Single-source vulnerability in certified laboratory access for GB standards compliance threatens market entry timelines. Distribution runs through wholesale irrigation supply houses for professional-grade specification sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recurring revenue from remote monitoring subscriptions and 10-year performance guarantee contracts expands faster than hardware unit sales, reframing competitive advantage around service-attach depth rather than manufacturing scale alone.
For Market Incumbents: Consolidate specification authority through landscape architect certification programs and centralized procurement platform integration. Deepen backward integration into brass alloy and polymer compounding to defend margin position against commodity volatility. Prioritize EPA WaterSense pre-certification inventory builds to compress competitor launch windows.
For New Entrants and Emerging Players: Anchor in India's municipal urban greening mandates for drip and micro-spray system specifications. Target battery-powered tool convergence with cordless outdoor equipment ecosystems as the most penetrable white-space. Pursue direct-to-installer digital channels bypassing wholesale distributor gatekeepers.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance premium play because efficiency mandates across the United States, European Union, and China progressively decommoditize mechanical timer incumbents. Acquisition targets should demonstrate certified laboratory relationships and connected-systems integration capabilities. Watch EPA WaterSense protocol expansion into spray body categories as inflection signal for certification-premium durability.
| Strategic Initiative | Industry Significance |
|---|---|
| Dealer Network Capacity Expansion | Toro's field-service infrastructure addresses 30% technician contraction in United States metropolitan markets. |
| Battery-Powered Tool Convergence | Husqvarna's cordless mower ecosystem integration enables cross-selling to existing outdoor power equipment households. |
| Landscape Architect Certification Programs | Rain Bird's irrigation designer credentials lock in commercial-grade specification sales through specification authority consolidation. |
| EPA WaterSense Pre-Certification Investment | Early protocol engagement compresses competitor launch windows and secures Inflation Reduction Act rebate eligibility. |
| Smart Controller SaaS Platform Launch | Remote monitoring dashboards satisfy national facilities management platform procurement requirements for centralized oversight. |
Research Methodology
A standing panel of irrigation system designers, municipal procurement officers, wholesale distributor category managers, and landscape architecture specification leads provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation against EPA WaterSense certification databases, EU Ecodesign directive filings, China GB standards registration records, and United States customs import data. Bottom-up unit shipment estimates triangulated against top-down addressable market sizing.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework modeled segmentation dimensions including product type, technology tier, end-user category, and distribution channel. CAGRs derived from replacement cycle analysis, regulatory mandate phase-in schedules, and rebate program enrollment trajectories. Forecast inputs incorporated soil-moisture sensor adoption curves, technician labor availability indices, and municipal procurement platform consolidation patterns.
Material uncertainties — commodity price volatility, certification timeline delays, and technician labor scarcity acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and rebate program continuity. Practitioners should keep alternative scenarios live as EPA protocol expansion scope and EU Ecodesign threshold revisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home & Garden
Artificial Flowers Market
Home & Garden
Landscaping Services Market
Home & Garden
Aquarium Decor Market
Home & Garden
North America Flower Pots and Planters Market
Home & Garden
Flower Box Market
Home & Garden
Aquarium LED Lighting Market
Home & Garden
Global Hot Tub Market
Home & Garden
Global Motorized and Smart Awnings Market
Home & Garden
Global Wind Chime Market
Home & Garden
Europe Flower Pots Market
Home & Garden
Residential Snow Blower Market
Home & Garden
United States Landscaping Market
Home & Garden
Artificial Plants and Flowers Market
Home & Garden
Japan Flower Pots Market
Home & Garden
Gardening Pots Market
Home & Garden
Outdoor Cooking Table Market