
 Hedge Trimmer Market | 2026-2036
Hedge Trimmer Market Size, Share, and Industry Trends Forecast 2026-2036
Hedge Trimmer Market Analytics
Aftermarket service revenue is reshaping profitability dynamics in the hedge trimmer sector. STIHL leverages its captive dealer network to capture recurring blade sharpening and seasonal tune-up income. Husqvarna anchors its position through professional-grade battery platforms that lock in accessory and battery replacement cycles. Stanley Black & Decker competes via retail channel density, sustaining volume through big-box distribution partnerships.
A hedge trimmer is a motorized or hand-powered cutting tool employing reciprocating blades with tooth spacing typically ranging from 20 to 40 millimeters, designed to shear woody stems and soft shoots in ornamental hedges and boundary vegetation. Gas-powered units deliver sustained torque for dense brush, though battery-powered systems now dominate residential replacement cycles due to lithium-ion energy density improvements. Dual action blade configurations command premium positioning by reducing vibration transfer to operators during extended commercial use. The municipal end user segment represents an expanding margin pool as cities outsource park maintenance to contracted landscaping firms.
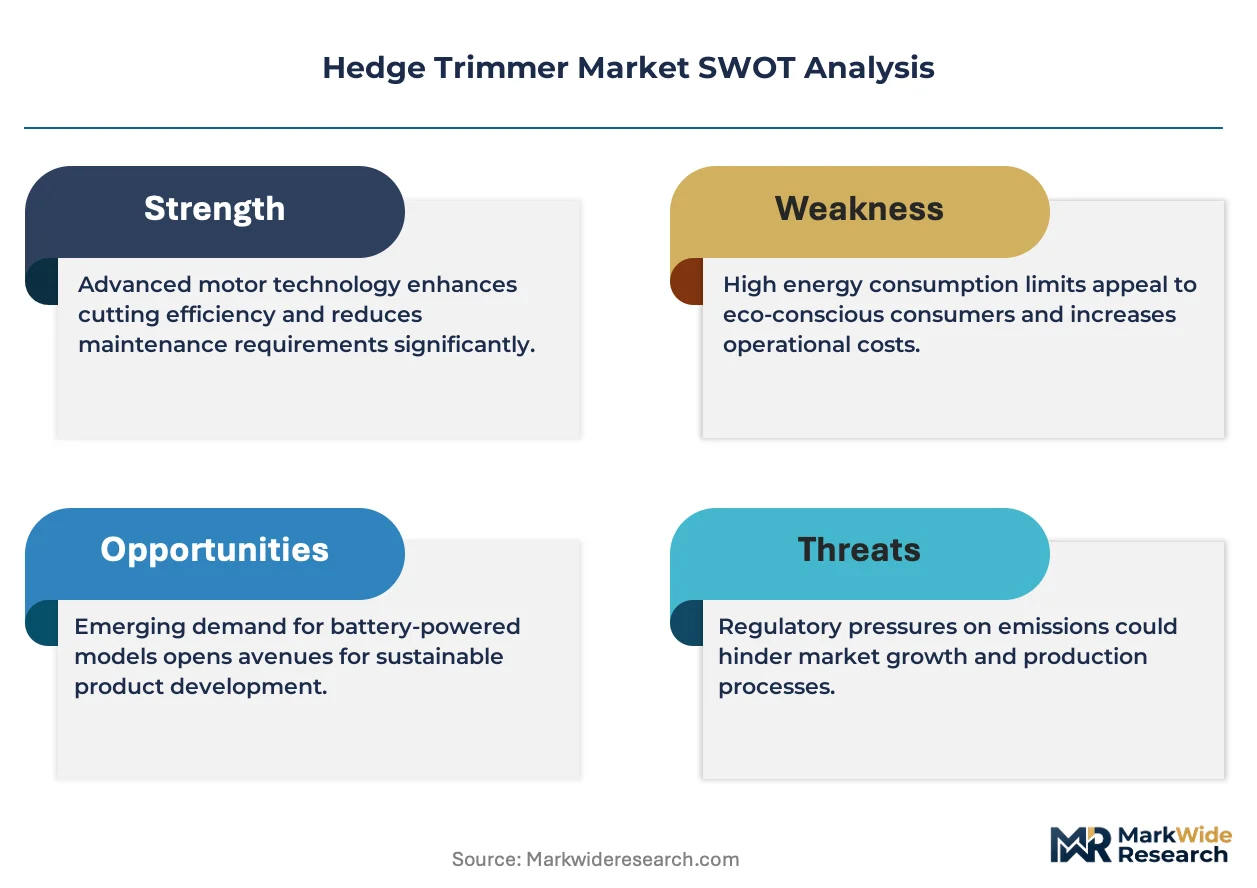
The EPA regulates exhaust emissions from petrol-driven outdoor power equipment under Phase 3 standards, compelling manufacturers to invest in catalytic after-treatment or pivot development toward zero-emission architectures. The EU Green Deal and F-Gas Regulation constrain fluorinated greenhouse gas use in manufacturing processes, while REACH chemical compliance adds material certification burdens for imported components. Stakeholders must weigh battery platform interoperability against proprietary ecosystem lock-in when allocating R&D capital across product generations.
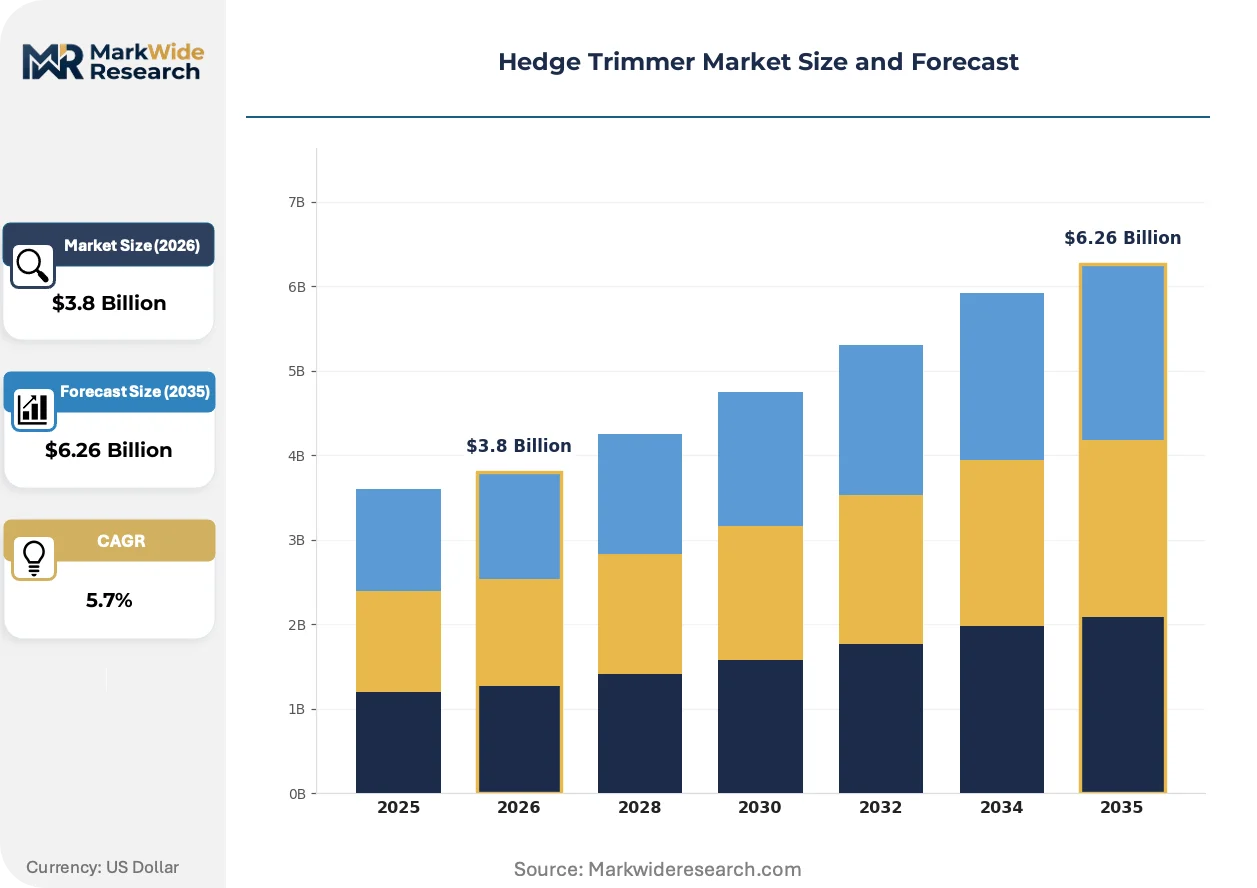
Market Dynamics
Professional landscaping firms are consolidating equipment procurement under fleet management contracts, compressing vendor diversity and elevating battery platform interoperability as the decisive purchasing criterion.
Growth Catalysts
- EU Green Deal decarbonization mandates:Municipalities across Germany, France, and Italy are phasing out petrol-powered equipment in public maintenance contracts, redirecting capital toward zero-emission alternatives.
- Lithium-ion energy density gains:Cell chemistry improvements now enable 40V and 80V commercial platforms to match petrol torque curves for dense brush cutting.
- Commercial groundskeeping contract proliferation:Corporate campuses and retail parks are outsourcing vegetation management to specialized landscaping firms, standardizing equipment specifications across multi-site portfolios.
Market Restraints
- Neodymium magnet supply concentration:Rare earth processing for brushless motor rotors concentrates in Chinese refining facilities, exposing manufacturers to export quota volatility.
- REACH chemical certification burdens:ECHA registration requirements for imported aluminum alloys and polymer composites add 12-18 month material qualification timelines.
- Petrol unit residual performance advantage:Sustained torque output for hardwood stem cutting above 25mm diameter remains unmatched by battery alternatives in sub-$400 retail tiers.
Strategic Opportunities
- India municipal greening initiatives:Smart city programs in Pune, Hyderabad, and Ahmedabad are creating first-time mechanized equipment demand for urban beautification contracts.
- Telematics-enabled fleet optimization:GPS tracking and usage analytics integration allows equipment-as-a-service pricing models for mid-sized landscaping enterprises.
- Dual-action blade platform extension:Vibration-reduction technology proven in commercial hedge trimmers is migrating into pole saws and brush cutters, opening cross-category accessory sales.
Industry Challenges
- Battery platform fragmentation:Proprietary voltage architectures and connector geometries prevent interoperability, forcing contractors to maintain redundant charging infrastructure across mixed fleets.
- Certification timeline compression:Concurrent EPA Phase 3, EU Stage V, and CARB SORE compliance cycles strain engineering resources, delaying product refresh cadences.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hedge Trimmer Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Gas-Powered, Battery-Powered, Manual Blade Type: Dual Action, Single Action, Precision, Telescopic End User: Residential, Commercial, Landscaping, Municipal Power Source: Corded, Cordless, Hybrid, Petrol |
| Companies Covered | Husqvarna, STIHL, Stanley Black & Decker, Honda, Robert Bosch, The Toro Company, Makita, Alfred Kärcher SE & Co. KG, Metabo HPT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hedge Trimmer Market Evolving Landscape
Equipment architecture is pivoting from standalone motor-battery assemblies toward connected, service-integrated platforms that capture recurring revenue through software-enabled performance monitoring.
Brushless DC motor technology is migrating from premium commercial tiers into mid-market residential units. STIHL and Husqvarna are deploying sensor-integrated drives that adjust blade speed based on stem resistance, extending run-time by 15-20% on equivalent cell packs. This migration is compressing the performance gap between professional and consumer price bands, forcing incumbent brands to differentiate through durability ratings rather than raw cutting power.
The EPA Phase 3 emission standards and EU F-Gas Regulation are constraining manufacturing process chemistry and exhaust after-treatment design simultaneously. California Air Resources Board (CARB) small off-road engine rules are extending to 19 other US states through Section 177 waivers, creating a bifurcated compliance landscape. Manufacturers serving North American and European markets are consolidating R&D centers to manage divergent certification timelines, with most affected product lines experiencing 8-14 month launch delays.
Contractor purchasing behavior is fragmenting across channel types. Independent dealers retain loyalty among fleet-scale landscaping firms seeking technical service bundling, while Amazon Business and specialized B2B platforms capture replacement part and consumable volume from smaller operators. This channel divergence is most pronounced in Texas, Florida, and North Carolina, where rapid housing development has outpaced dealer network expansion, pushing 30-40% of equipment procurement toward direct online fulfillment with manufacturer warranty registration handled through self-service portals.
Hedge Trimmer Market Segmentation
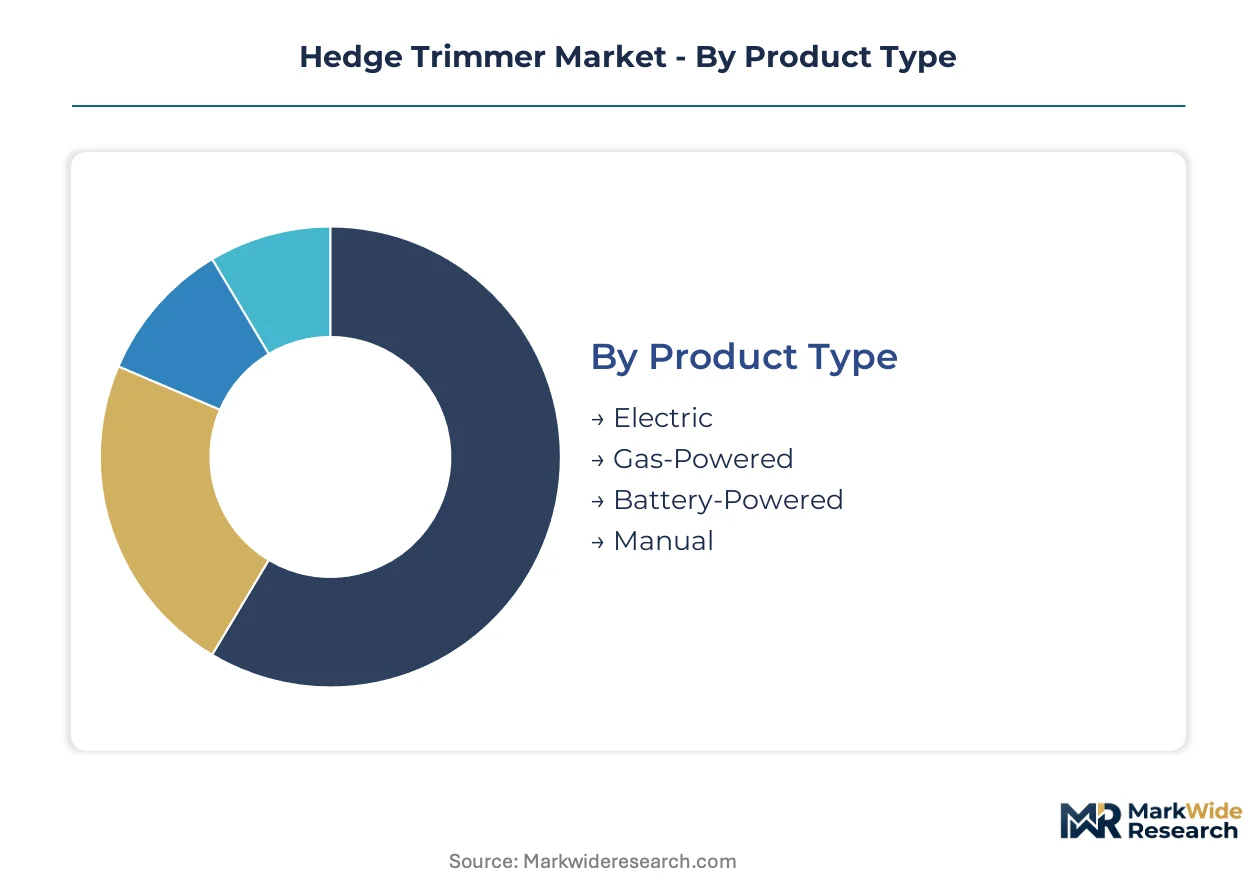
Hedge trimmer segmentation reveals divergent service revenue potential across product architectures. Blade replacement cycles, battery refresh rates, and dealer dependency vary substantially by category, reshaping manufacturer margin capture strategies.
Product Type:
After-sales-service intensity diverges sharply across power architectures, with battery platforms generating recurring revenue through cell pack replacements and gas units demanding seasonal maintenance contracts.
- Battery-Powered:Lithium-ion cell chemistry now delivers 40V and 80V platforms matching petrol torque for dense brush. Municipal procurement in Germany and France is mandating zero-emission equipment, redirecting fleet investment toward cordless architectures with locked-in battery ecosystems.
- Gas-Powered:Two-stroke and four-stroke engines sustain torque output for hardwood stems above 25mm diameter. EPA Phase 3 compliance costs are compressing margins, though commercial landscaping firms in Texas and Florida retain petrol units for all-day runtime without charging infrastructure.
- Electric:Corded designs with 120V/230V AC motors serve residential users with small lot sizes. Demand concentrates in suburban Japan and South Korea where noise restrictions limit petrol alternatives.
- Manual:Hand-powered shears with hardened steel blades persist in precision topiary applications. Botanical gardens in Kyoto and Versailles specify manual tools for heritage hedge maintenance.
Battery-powered holds the largest share; momentum sits with cordless platforms as EU decarbonization mandates harden.
Blade Type:
Blade engineering directly determines vibration exposure limits under OSHA and EU machinery directives, with dual-action designs commanding premium positioning for commercial operators.
- Dual Action:Counter-oscillating blade sets reduce vibration transfer by 40% versus single-action alternatives. Landscaping firms with multi-hour cutting contracts in California and North Carolina specify dual-action units to minimize operator fatigue claims.
- Single Action:One moving blade against a fixed counter-edge delivers lower cost for residential replacement cycles. Big-box retail channels in the US Midwest stock single-action units as entry-tier volume drivers.
- Precision:Narrow tooth spacing below 20mm enables detailed shaping in ornamental applications. Estate maintenance contractors in the Cotswolds and Napa Valley specify precision blades for formal garden portfolios.
- Telescopic:Extendable shaft designs reach heights to 3.5 meters for boundary hedge trimming. Municipal park departments in Sydney and Vancouver deploy telescopic units to reduce ladder-related injury exposure.
Dual action holds the largest share; telescopic configurations are climbing the fastest as liability-conscious municipalities extend mechanized reach.
End User:
Procurement authority is fragmenting across customer types, with fleet-scale landscaping firms consolidating vendor relationships while municipalities impose interoperability mandates.
- Commercial Landscaping:Multi-site vegetation management contracts standardize equipment specifications across corporate campuses and retail parks. Firms with 50+ unit fleets in Texas and Florida are adopting telematics-enabled usage tracking for equipment-as-a-service pricing.
- Municipal:City park departments and highway maintenance authorities outsource green space management to contracted specialists. German municipal budgets for urban beautification remain elevated, driving mechanized equipment procurement in Stuttgart, Munich, and Hamburg.
- Residential:Homeowner replacement cycles favor battery-powered units with 20V-40V platforms. Amazon Business and direct-to-consumer channels capture 30-40% of volume in dealer-underserved Sun Belt housing markets.
- Landscaping:Independent operators with 5-15 unit fleets balance upfront cost against dealer service proximity. This segment fragments across channel types, with independent dealers retaining loyalty for technical bundling.
Commercial landscaping holds the largest share; municipal contracts are gaining share fastest as cities outsource maintenance.
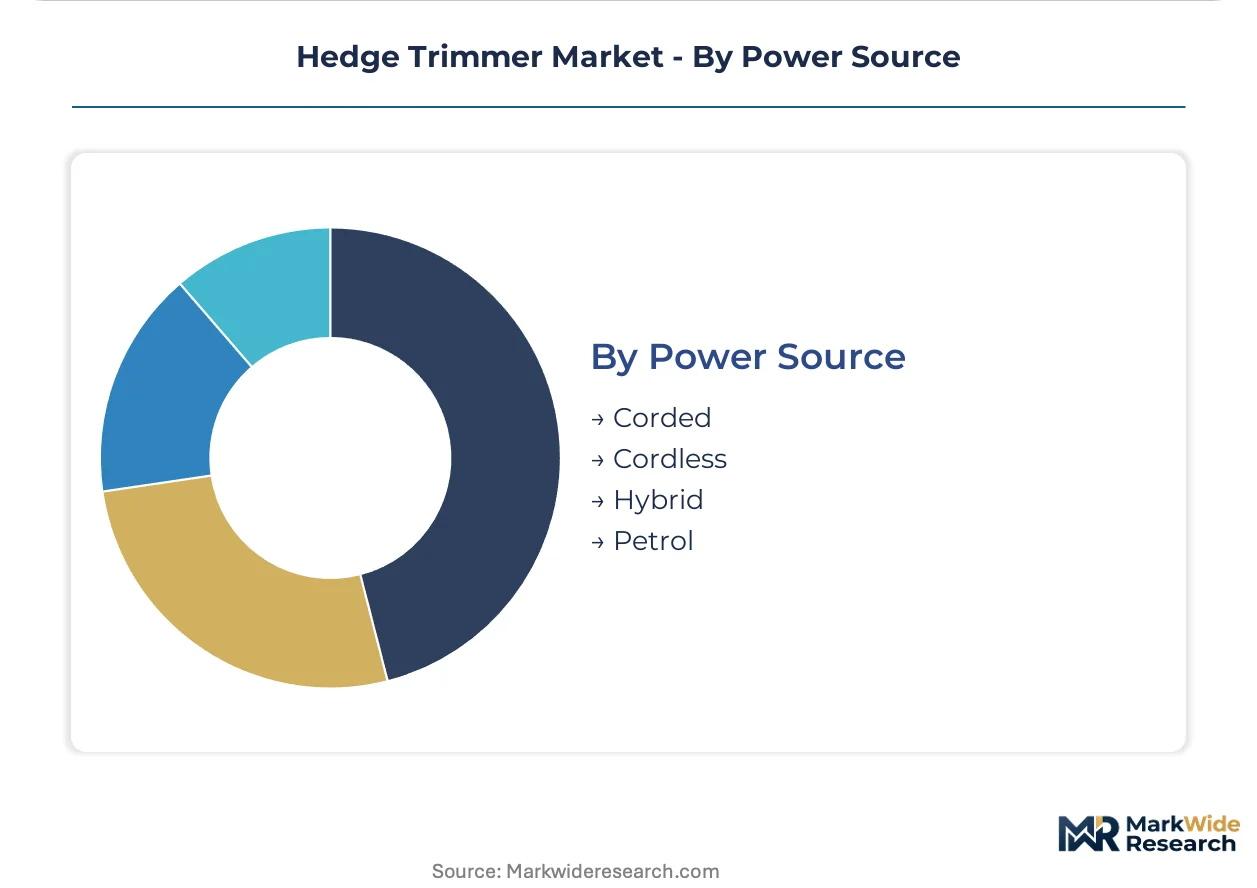
Power Source:
Energy architecture determines regulatory exposure, with corded and cordless platforms exempt from EPA emission compliance that constrains petrol development budgets.
- Cordless:Battery platforms with interchangeable cell packs across tool categories lock contractors into proprietary ecosystems. Husqvarna and STIHL are extending 80V architectures from hedge trimmers into pole saws and brush cutters.
- Corded:Continuous AC power eliminates runtime anxiety for fixed-site maintenance. Japanese residential users with small gardens favor corded designs for reliability and lower upfront cost.
- Petrol:Internal combustion engines face concurrent EPA Phase 3, EU Stage V, and CARB SORE compliance cycles. Engineering resource strain is delaying product refresh cadences by 8-14 months.
- Hybrid:Dual-mode architectures switch between battery and petrol power for extended runtime. This configuration targets commercial operators in markets with intermittent charging infrastructure.
Cordless holds the largest share; petrol faces steepest share erosion as regulatory timelines compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. German municipal buyers prioritize durability and service networks over upfront cost. Sun Belt residential markets in the United States favor big-box retail accessibility and promotional pricing.
Germany
Municipal green space management budgets in Stuttgart, Munich, and Hamburg drive fleet-scale procurement of zero-emission equipment. The EU Green Deal mandates phase-out timelines for petrol-powered maintenance contracts. Baden-Württemberg's industrial corridor hosts precision blade manufacturers supplying dual-action configurations to commercial landscaping firms.
United States
Texas and Florida landscaping contractors retain petrol units for all-day runtime without charging infrastructure. EPA Phase 3 emission standards compress engineering timelines for two-stroke engine refreshes. Atlanta and Dallas-Fort Worth metro areas concentrate fleet management contract awards for corporate campus maintenance.
France
Public procurement frameworks in Île-de-France prioritize battery platform interoperability across multi-vendor fleets. REACH chemical certification requirements extend material qualification timelines for imported aluminum components. Lyon and Marseille park departments are standardizing 80V cordless architectures for boundary hedge maintenance.
Japan
Residential users with small garden plots favor corded designs for reliability and lower upfront cost. METI efficiency standards shape motor performance benchmarks for domestic manufacturers. Osaka and Nagoya industrial clusters produce brushless DC drives migrating into mid-market residential tiers.
Australia
Municipal park departments in Sydney and Vancouver deploy telescopic units to reduce ladder-related injury exposure. State-level occupational safety regulations mandate vibration exposure limits for commercial operators. Melbourne's landscaping contractor base is consolidating equipment procurement under telematics-enabled fleet management contracts.
Hedge Trimmer Market Competitive Landscape
Capability concentration sits with specialized outdoor power equipment manufacturers; scale advantage sits with diversified industrial conglomerates. The market structure splits between captive dealer network operators and retail-channel-dependent volume players. Three archetypes dominate: premium-tier professional specialists, mid-market battery platform integrators, and mass-market retail distributors. Competitive moves center on battery ecosystem lock-in strategies and aftermarket service revenue capture through blade replacement and seasonal maintenance contracts.
Within the premium professional tier, Husqvarna and STIHL represent the dealer-network archetype with locked-in battery ecosystems. Stanley Black & Decker occupies a position exemplifying retail-channel scale advantage through big-box distribution density. These three anchors illustrate the strategic divergence between service-integrated professional positioning and volume-driven consumer accessibility.
| Leading Market Players |
|---|
| Husqvarna |
| STIHL |
| Stanley Black & Decker |
| Honda |
| Robert Bosch |
| The Toro Company |
| Makita |
| Alfred Kärcher SE & Co. KG |
| Metabo HPT |
| Others |
Value Network & Pricing Analysis
The Shanghai-Rotterdam maritime corridor's freight cost volatility feeds directly into landed cost disparities for aluminum die-cast motor housings and lithium-ion cell packs, amplifying margin compression for manufacturers lacking captive battery assembly capacity while creating price differentiation between integrated and import-dependent brands.
Pricing Analysis
Aftermarket service revenue tiers—spanning blade replacement cycles, battery refresh programs, and seasonal maintenance contracts—generate lifetime value multiples of 2.3-4x initial equipment sales for dealer-network operators. Three-tier pricing structure across premium, standard, and economy levels separates STIHL and Husqvarna's professional-grade dual-action platforms from mid-market cordless alternatives and entry-tier single-action retail SKUs. Pricing pressure stems from big-box promotional intensity in Texas and Florida residential markets, where Stanley Black & Decker sustains volume through seasonal discounting. Municipal procurement in Germany exhibits lowest price sensitivity, prioritizing durability certifications and service network density over upfront cost.
Supply Chain Analysis
Contract manufacturing capacity for brushless DC motor assemblies concentrates in Shenzhen and Dongguan electronics clusters, with Nidec and Johnson Electric holding dominant OEM supply positions. Finished goods production draws from China, Germany, and the United States, while neodymium magnet processing rests on Chinese rare earth refining facilities. Lithium-ion cells, precision-machined aluminum blade carriers, and polymer composite housings anchor bill-of-materials exposure. Single-source vulnerability in rare earth magnet supply creates tariff and quota risk. Distribution runs through captive dealer networks for commercial fleets, big-box retail for residential replacement cycles, and direct B2B platforms for municipal contract fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery platform economics now determines competitive survival, with interoperability mandates from French public procurement frameworks and German municipal contracts forcing ecosystem openness that threatens proprietary lock-in strategies.
For Market Incumbents: Pre-empt interoperability pressure by opening mid-tier battery architectures to third-party tool integration before regulatory mandates harden, while consolidating blade and motor component supply through backward integration into aluminum forging and magnet processing to defend against rare earth price volatility. Vertical integration into precision blade manufacturing in Baden-Württemberg preserves margin capture from dual-action premium tiers. For New Entrants and Emerging Players: Build out telematics-enabled fleet management software for mid-sized landscaping contractors in Atlanta and Dallas-Fort Worth, where equipment-as-a-service pricing models remain underdeveloped relative to hardware saturation. Target municipal smart city programs in Pune and Hyderabad with 40V cordless platforms priced below STIHL and Husqvarna entry points, leveraging direct B2B sales channels to bypass dealer network establishment costs. For Investors and Strategic Acquirers: Precision blade manufacturers with captive heat-treatment capabilities and established relationships with German municipal procurement channels represent the most defensible acquisition archetype. Long-term viability hinges on aftermarket service revenue capture rather than equipment sales volume. Quarterly review of battery platform interoperability legislation across EU member states and Section 177 waiver adoption in US states is advised to detect inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Interoperability | EU Green Deal mandates in France and Germany are forcing ecosystem openness that threatens proprietary lock-in. |
| Telematics-Enabled Fleet Management | GPS tracking and usage analytics allow equipment-as-a-service pricing for mid-sized landscaping enterprises in Texas. |
| Backward Integration into Rare Earth Processing | Captive magnet supply insulates brushless motor production from Chinese export quota volatility. |
| Dual-Action Blade Platform Extension | Vibration-reduction technology migrates into pole saws and brush cutters, opening cross-category accessory sales. |
| Smart City Municipal Contract Pursuit | Pune and Hyderabad urban beautification programs create first-time mechanized equipment demand for cordless platforms. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with landscaping fleet managers, municipal procurement officers, aftermarket service directors, and battery platform engineers; and secondary validation through customs trade records, EPA Phase 3 certification filings, EU Green Deal implementation timelines, and SEC 10-K equipment segment disclosures. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Forecast inputs span power source architecture, blade type configuration, end-user category, and regional regulatory cluster across the analysis window. CAGRs derive from regression-weighted segment growth rates applied to base-year value estimates. Industry-specific inputs include lithium-ion energy density improvement curves, REACH chemical certification timeline assumptions, and municipal outsourcing penetration rates.
Practitioners should monitor rare earth export quota announcements, EPA Phase 3 enforcement intensity, and EU battery regulation interoperability deadlines for early signals of forecast revision. Quarterly review of municipal procurement framework updates and landscaping firm consolidation activity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home & Garden
United States Landscaping Market
Home & Garden
Artificial Plants and Flowers Market
Home & Garden
Global Wind Chime Market
Home & Garden
Preserved Flowers Market
Home & Garden
Global Hot Tub Market
Home & Garden
Incense Market
Home & Garden
Aquarium Decor Market
Home & Garden
Europe Flower Pots Market
Home & Garden
Japan Flower Pots Market
Home & Garden
Lawn and Gardening Consumables Market
Home & Garden
Outdoor Cooking Table Market
Home & Garden
Lawn and Garden Water Equipment Market
Home & Garden
Flexible Garden Hoses Market
Home & Garden
Global Motorized and Smart Awnings Market
Home & Garden
US Garden Planter Market
Home & Garden
Electric Lawn Mower Market