
 Automated Blinds and Shades Market | 2026-2036
Automated Blinds and Shades Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Blinds and Shades Market Analytics
Aftermarket service revenue is reconfiguring margin capture across the automated blinds and shades value chain. Hunter Douglas leverages its direct-to-installer channel to sustain recurring calibration and maintenance income. Lutron Electronics anchors premium specification-grade projects through proprietary wireless protocols. Somfy SA competes in motor and control supply, extending its position into third-party OEM partnerships across Europe.
Automated blinds and shades are motorized window coverings integrating tubular motors, wireless control modules, and light sensors to manage solar heat gain, glare, and privacy in built environments. Roller blinds lead commercial specification due to their compatibility with building management system integration and clean architectural profiles. Smart home integration represents the fastest-expanding technology segment as Matter protocol adoption standardizes cross-platform connectivity. The hospitality end user segment occupies a concentrated margin pool where brand-standard requirements drive specification consolidation toward certified suppliers.
The EU Green Deal and REACH chemical compliance frameworks shape product material selection and motor efficiency thresholds for European market access. The US Department of Energy's appliance standards program and state-level stretch codes in California and New York directly influence motor specification requirements. Stakeholders must monitor interoperability certification timelines and building electrification policy shifts to anticipate procurement channel migration.
Market Dynamics
The automated blinds and shades market is restructuring around building electrification mandates that force motor efficiency upgrades and wireless control retrofits across existing commercial stock. Procurement channels are migrating from traditional specification routes toward direct-to-installer platforms that bundle hardware with ongoing calibration services.
Growth Catalysts
- EU Green Deal building efficiency mandates:Germany's retrofit requirements for residential and commercial properties are accelerating motorized shading upgrades as landlords seek compliance with thermal performance targets.
- Utility rebate programs:United States electricity providers in California and New York offer per-unit incentives for automated shading installation, compressing payback periods for commercial building operators.
- Matter protocol standardization:Cross-platform smart home connectivity is virtualizing integration barriers, enabling single-app control across previously incompatible motor and sensor ecosystems.
Market Restraints
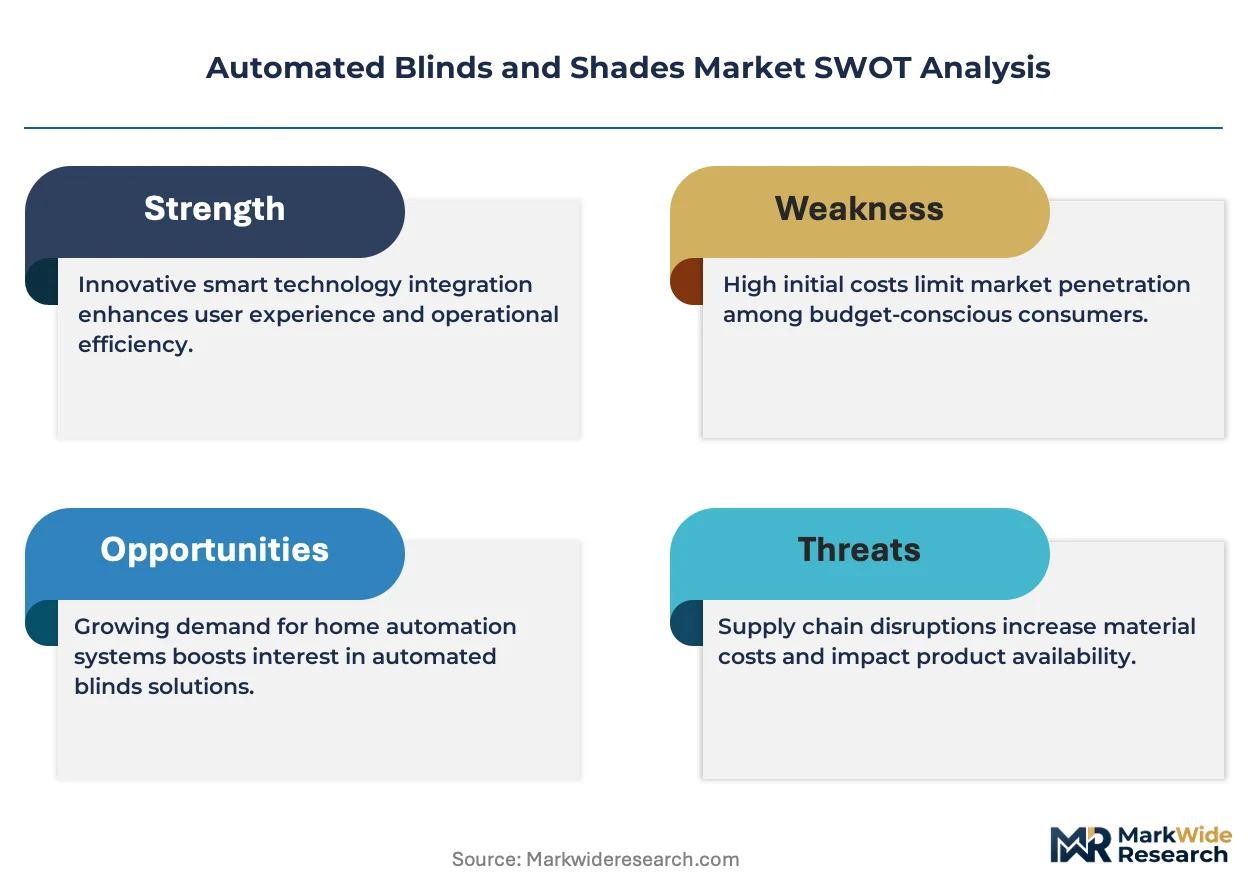
- Copper and rare-earth motor input volatility:Tubular motor production depends on concentrated Chinese rare-earth processing and Chilean copper supply, exposing manufacturers to price swings that compress margin predictability.
- REACH chemical compliance friction:European market access requires reformulation of fabric coatings and polymer components, extending product development timelines and certification costs.
- Manual shade substitution in cost-sensitive segments:Budget residential retrofits in secondary markets frequently default to corded or basic spring-loaded alternatives, capping penetration in price-driven channels.
Strategic Opportunities
- India's building automation underpenetration:Commercial real estate development in Bangalore and Mumbai is adopting LEED-equivalent standards without installed shading automation, creating first-mover specification windows.
- LEED certification requirement expansion:United States commercial projects pursuing Gold and Platinum ratings must demonstrate daylight autonomy controls, mandating automated shading in new construction and major renovation.
- Sensor-to-BMS convergence:Integration of photovoltaic sensors with BACnet and Modbus building management protocols is enabling centralized energy optimization contracts that bundle shading with HVAC load management.
Industry Challenges
- Wireless protocol certification backlog:FCC and CE marking timelines for new radio frequency modules in motor controls are extending product launch windows, delaying revenue recognition for platform refreshes.
- Installer technical skill fragmentation:Motor calibration, limit setting, and mesh network commissioning require training that existing window treatment trades lack, forcing manufacturers to absorb education costs or restrict channel access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Blinds and Shades Market |
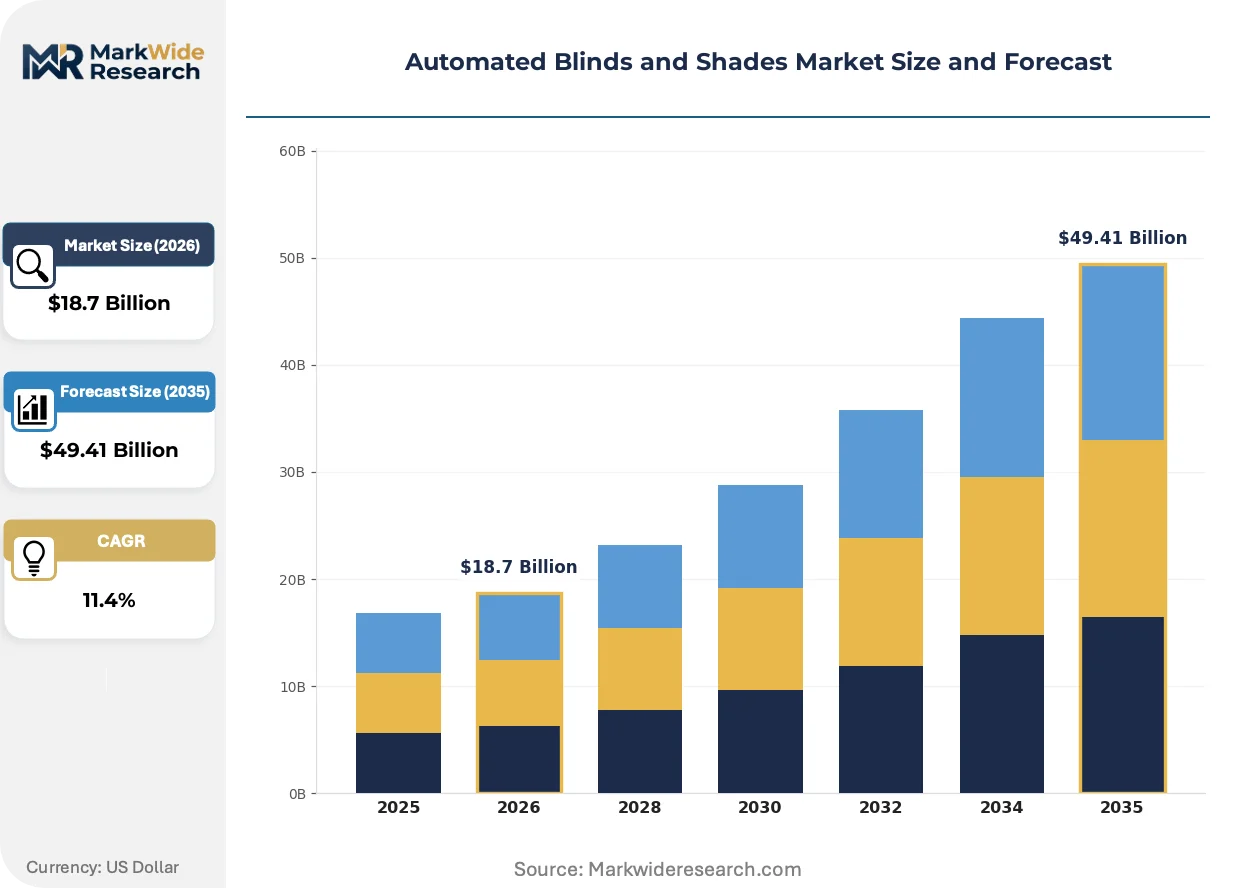
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roller Blinds, Roman Shades, Venetian Blinds, Honeycomb Shades Technology: Smart Home Integration, Remote Control, Voice Control, Mobile App Control End User: Residential, Commercial, Hospitality, Institutions Installation: Indoor Installation, Outdoor Installation, Retrofitting, New Construction |
| Companies Covered | Hunter Douglas, Lutron Electronics, Legrand SA, Somfy SA, Springs Window Fashions, MechoShade Systems, Crestron Electronics, QMotion Incorporated, Warema Renkhoff SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Blinds and Shades Market Evolving Landscape
Wireless control architectures are virtualizing hardware boundaries between shading systems and broader building automation infrastructure. Three convergent developments are compressing traditional specification cycles and opening new service revenue models.
Photovoltaic-powered motor units with integrated energy harvesting are virtualizing the need for hardwired electrical infrastructure in retrofit applications. Hospitality operators in Spain and Portugal are specifying these units for historic building renovations where conduit installation is prohibited. The technology is compressing project timelines from weeks to days while shifting margin capture toward commissioning services.
REACH chemical compliance and the EU Green Deal's embodied carbon tracking are forcing fabric suppliers to disclose polymer chain-of-custody data. German and French specification architects are now requiring Environmental Product Declarations for shading textiles in public procurement. Motor manufacturers are responding by qualifying alternative bio-based polymers that maintain flame resistance ratings.
Direct-to-installer digital platforms are displacing traditional distribution layers in the United States residential retrofit channel. California and Texas contractors are sourcing motors and fabric through manufacturer-branded apps that embed automated sizing tools and same-day logistics. The model is concentrating volume with vertically integrated suppliers while fragmenting independent distributor margins.
Automated Blinds and Shades Market Segmentation
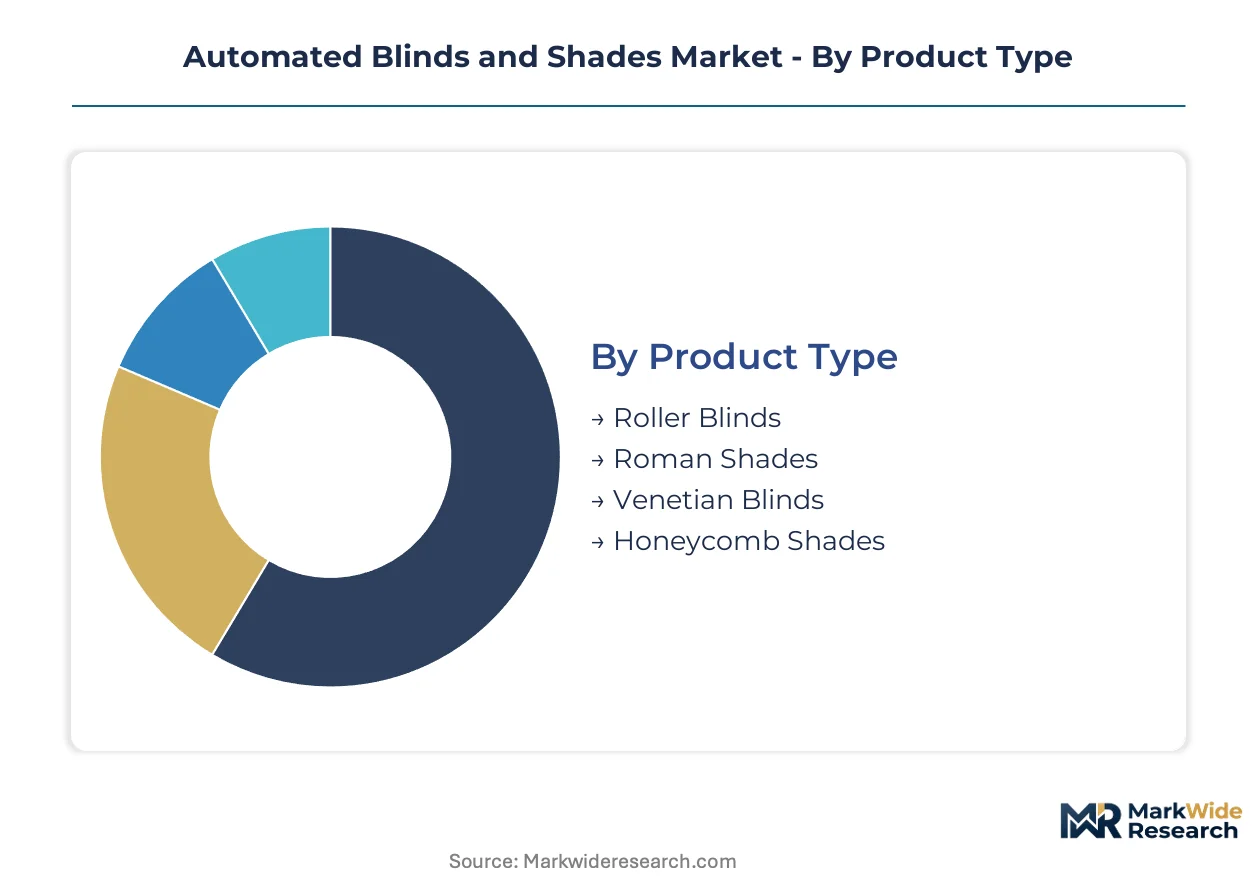
Segmentation in automated blinds and shades reveals how specification requirements diverge across building types and control architectures. Procurement patterns cluster around integration complexity, installation constraints, and end-user technical sophistication rather than price alone.
Product Type:
Mature architectural formats dominate commercial specification while emerging geometries capture residential retrofit interest.
- Roller Blinds:Tubular motor housings integrate cleanly into ceiling recesses and building management system architectures. Demand concentrates in United States commercial office towers where LEED daylight autonomy requirements mandate automated solar control.
- Honeycomb Shades:Cellular air pockets deliver thermal insulation values that satisfy EU Green Deal retrofit mandates in Germany and France. German residential landlords specify these units to meet thermal bridge reduction targets in existing building stock.
- Roman Shades:Fabric folding mechanisms suit hospitality interiors requiring soft aesthetic profiles with motorized operation.
- Venetian Blinds:Slat angle adjustability offers precise glare control for workstation daylighting in Nordic commercial buildings.
Roller blinds retain volume leadership; honeycomb shades hold the steepest expansion curve.
Technology:
Control sophistication stratifies across customer technical readiness and existing infrastructure investment levels.
- Smart Home Integration:Matter protocol compatibility enables cross-platform operation across previously isolated motor ecosystems. United States residential retrofit contractors bundle these controls with HVAC and lighting automation for whole-home energy management contracts.
- Mobile App Control:Bluetooth and Wi-Fi direct connectivity eliminates hub requirements for single-room installations. Spanish and Portuguese hospitality operators deploy these for historic building renovations where electrical infrastructure cannot support hardwired systems.
- Remote Control:Handheld RF transmitters serve cost-sensitive commercial retrofits with basic open-close-stop functionality.
- Voice Control:Alexa and Google Assistant integration targets premium residential segments in English-speaking markets.
Smart home integration commands specification priority; mobile app control is climbing the fastest among retrofit channels.
End User:
Customer type determines margin structure through certification requirements and service attachment rates.
- Commercial:Building management system integration and energy optimization contracts drive specification toward BACnet-compatible motor platforms. California and New York utility rebate programs compress payback calculations for large-floorplate buildings.
- Hospitality:Brand-standard requirements consolidate procurement toward certified suppliers with global installation networks. Marriott and Hilton property standards in Spain and Portugal mandate automated shading for guest room categories above select-service tier.
- Residential:Smart home ecosystem compatibility influences purchasing decisions in German and United States retrofit markets.
- Institutions:Public procurement rules in France and Germany require Environmental Product Declaration documentation for shading textiles.
Commercial installations retain volume leadership; hospitality applications deliver the highest service attachment margins.
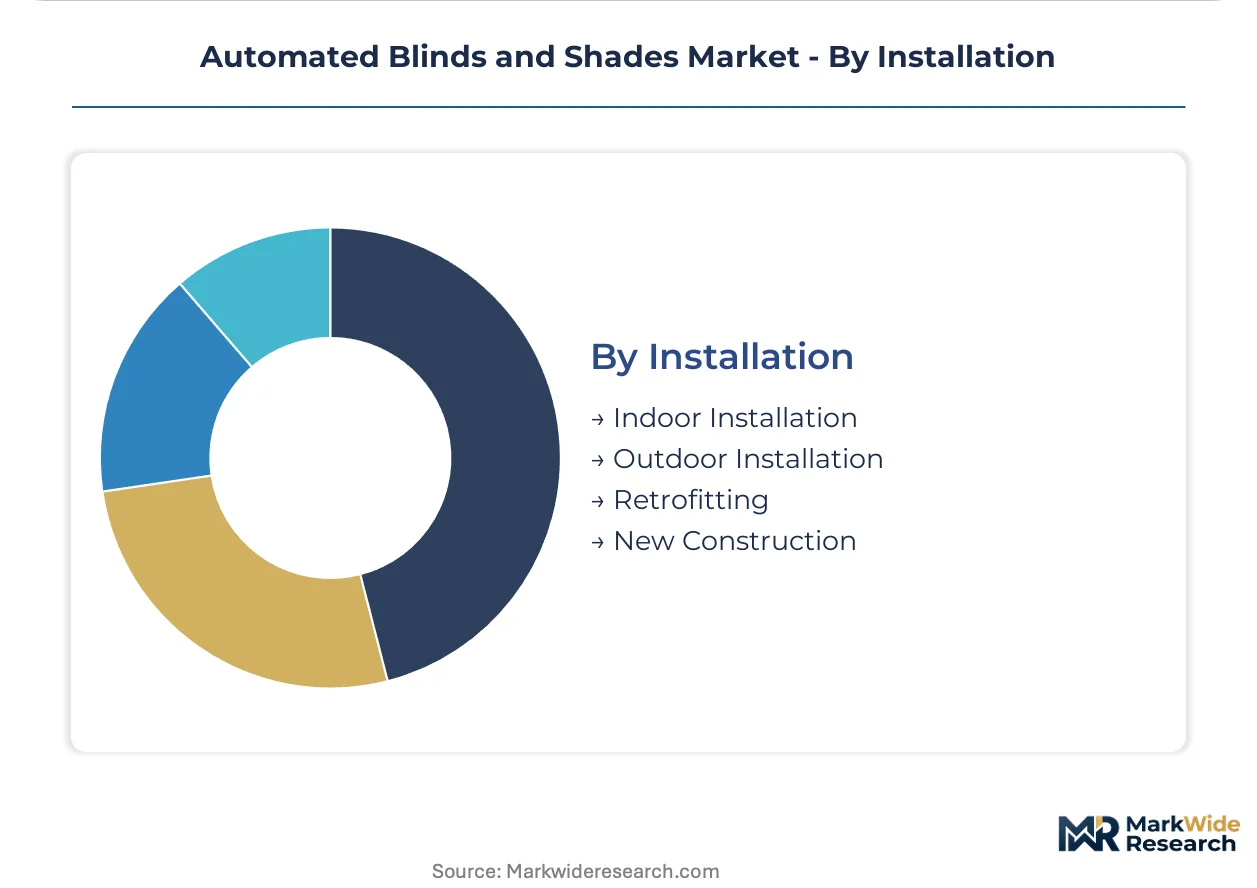
Installation:
Installation modality shapes channel economics and manufacturer margin capture through service bundling requirements.
- Retrofitting:Battery and photovoltaic-powered motor units eliminate electrical rough-in requirements. German residential landlords deploy these for EU Green Deal compliance without tenant displacement during construction.
- New Construction:Hardwired motor integration during electrical rough-in enables centralized control architectures. United States commercial developers specify these for LEED Gold and Platinum certification pathways.
- Indoor Installation:Climate-controlled environments dominate volume across all end-user categories.
- Outdoor Installation:Weatherized motor housings serve Mediterranean hospitality terraces and Nordic commercial atriums with solar exposure management requirements.
Retrofitting captures the fastest-growing project pipeline; new construction retains higher per-unit system values.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tubular motor production clusters in Germany and China concentrate supply-side leverage, while specification demand disperses across utility-regulated markets in the United States and EU Green Deal jurisdictions. Procurement channel migration toward direct-to-installer platforms is compressing traditional distributor margins in high-penetration economies.
United States
Utility rebate programs in California and New York accelerate commercial building automation procurement for LEED certification pathways. The Department of Energy's appliance standards program mandates motor efficiency thresholds that reshape specification requirements. Los Angeles and New York City building electrification codes drive retrofit demand for wireless-controlled shading systems.
Germany
EU Green Deal thermal performance targets compel residential landlords to deploy motorized honeycomb shades in existing building stock. REACH chemical compliance frameworks force fabric coating reformulations, extending certification timelines. Munich and Frankfurt commercial developments specify BACnet-integrated roller blinds for daylight autonomy compliance.
China
Rare-earth processing concentration for tubular motor magnets creates input cost volatility that ripples through global supply chains. GB standards for building energy efficiency establish motor performance baselines in new construction. Shanghai and Shenzhen smart home ecosystems drive Matter protocol adoption for cross-platform shading control.
India
LEED-equivalent standards in Bangalore and Mumbai commercial real estate create first-mover specification windows for building automation. The Bureau of Indian Standards (BIS) certification requirements for electrical appliances establish motor safety protocols. Hyderabad and Pune technology campus developments integrate automated shading into centralized energy management contracts.
Spain
Photovoltaic-powered motor units eliminate electrical rough-in barriers for historic building renovations in hospitality applications. The country's national building efficiency regulator enforces thermal performance disclosure for commercial properties. Barcelona and Madrid hotel operators specify battery-operated Roman shades to meet brand-standard automation requirements without structural modification.
Automated Blinds and Shades Market Competitive Landscape
Vertically integrated fabricators and specialized motor suppliers split the market between specification-grade projects and mass-market retrofit channels. The vendor base stratifies across three tiers: premium architectural specification houses, mid-market smart home integrators, and component OEMs serving private-label assemblers. Dominant competitive moves include proprietary wireless protocol development and backward integration into sensor manufacturing.
Among premium-tier specification specialists, Hunter Douglas and Lutron Electronics occupy positions defined by direct-to-installer channel control and proprietary control architecture. Somfy SA exemplifies the component OEM archetype, supplying motors and wireless modules to third-party shade fabricators across European markets. These three anchors represent divergent margin capture models: recurring calibration services, premium hardware specification, and volume component supply.
| Leading Market Players |
|---|
| Hunter Douglas |
| Lutron Electronics |
| Legrand SA |
| Somfy SA |
| Springs Window Fashions |
| MechoShade Systems |
| Crestron Electronics |
| QMotion Incorporated |
| Warema Renkhoff SE |
| Others |
Value Network & Pricing Analysis
Rare-earth magnet export controls from China determine both pricing tier spreads and supply chain shape in automated blinds and shades, compressing margin predictability for tubular motor suppliers while forcing European and North American manufacturers toward alternative sourcing strategies or captive magnet production investments.
Pricing Analysis
REACH chemical compliance dictates the pricing tier structure across European market access, separating EPD-certified premium specifications from reformulation-delayed standard tiers. Three-tier pricing structure across premium, standard, and economy levels reflects certification investment recovery, with BACnet-integrated commercial systems commanding the highest attachment rates. Cost compression in economy residential retrofits is intensifying because manual shade substitution limits motorized penetration in price-driven channels. Budget residential contractors in secondary United States markets exhibit the greatest price sensitivity, while hospitality brand-standard procurement shows the least.
Supply Chain Analysis
Export restrictions on rare-earth processing technology limit tubular motor magnet flows from China, forcing diversification efforts. Tubular motor production draws from concentrated rare-earth processing in China, copper refining in Chile, and precision manufacturing in Germany. Neodymium magnet supply, copper winding wire, and polymer fabric coatings constitute critical input dependencies. Single-source vulnerability in Chinese rare-earth concentrate creates exposure to quota-driven price spikes. Distribution runs through direct-to-installer digital platforms that displace traditional wholesale layers in United States residential channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automated blinds and shades market sits in a cyclical recovery phase driven by building electrification code implementation across California, New York, and Germany, with retrofit demand acceleration creating favorable conditions for specification-grade suppliers and component OEMs with installer channel control.
For Market Incumbents: Pre-empt emerging competition from photovoltaic-powered motor specialists by securing backward integration into sensor manufacturing and qualifying bio-based polymer alternatives ahead of EU Green Deal embodied carbon tracking mandates. Expand direct-to-installer platform coverage in Texas and Florida to capture residential retrofit volume before mid-market aggregators consolidate channel access. Certification investment in Matter protocol interoperability represents the critical defensive lever against smart home ecosystem lockout.
For New Entrants and Emerging Players: Mid-market commercial buildings in India's Bangalore and Mumbai technology corridors represent the most penetrable entry point, with LEED-equivalent standards mandating daylight autonomy controls without established supplier relationships. Battery-powered retrofit solutions for German residential landlords facing EU Green Deal thermal performance targets offer a secondary white-space opportunity. A go-to-market strategy bundling hardware with commissioning service contracts bypasses incumbent installer network advantages.
For Investors and Strategic Acquirers: The market sits at a specification-consolidation phase that favors vertically integrated fabricators with proprietary wireless protocol control and recurring service revenue attachment. Acquisition targets should demonstrate direct-to-installer channel density in California or Germany, plus BACnet integration capabilities for commercial building management system procurement. The signal to watch is utility rebate program expansion or contraction in United States electricity markets, which directly compresses or extends commercial retrofit payback calculations.
| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Cross-platform smart home integration eliminates ecosystem lock-in barriers for residential retrofit contractors. |
| Photovoltaic Motor Development | Energy-harvesting units bypass electrical rough-in requirements in historic European hospitality renovations. |
| Direct-to-Installer Platform Launch | Manufacturer-branded apps with automated sizing tools concentrate volume and fragment independent distributor margins. |
| Bio-Based Polymer Qualification | Alternative materials maintain flame resistance ratings while satisfying EU Green Deal embodied carbon disclosure. |
| BMS Integration Partnership | BACnet and Modbus protocol convergence enables bundled energy optimization contracts with HVAC load management. |
Research Methodology
A spread of perspectives from motor manufacturing engineers, commercial building automation specifiers, residential retrofit contractors, and hospitality procurement directors converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with shade fabricator technical leads and smart home integration specialists, validated against secondary sources including FCC equipment authorization databases, EU EPD registration systems, and utility rebate program filings. Bottom-up project pipeline assessment and top-down building stock penetration modeling were triangulated against motor shipment data and BIS certification records.
Demand-supply balance dynamics shaped the analytical framework across the projection horizon, with segmentation modeled by product type, control technology sophistication, end-user category, and installation modality. CAGRs were derived from installation volume trajectories and average system value evolution, incorporating motor efficiency standard thresholds from the Department of Energy appliance standards program and EU Green Deal thermal performance benchmarks as structural constraints.
Stress conditions across rare-earth magnet quota volatility, REACH chemical compliance timeline extensions, and utility rebate program funding levels were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding Matter protocol adoption velocity and building electrification code implementation schedules. Material shifts in Chinese export control enforcement or United States federal energy efficiency policy would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home & Garden
Incense Market
Home & Garden
Landscaping and Gardening Service Market
Home & Garden
United States Landscaping Market
Home & Garden
US Garden Planter Market
Home & Garden
Garage Organization and Storage Market
Home & Garden
Lawn and Gardening Consumables Market
Home & Garden
North America Flower Pots and Planters Market
Home & Garden
Japan Flower Pots Market
Home & Garden
United States Lawn Care Market
Home & Garden
Europe Robotic Lawn Mower Market
Home & Garden
Hedge Trimmer Market
Home & Garden
Artificial Plants and Flowers Market
Home & Garden
Global Hot Tub Market
Home & Garden
North America Flowerpots Market
Home & Garden
Electric Lawn Mower Market
Home & Garden
Preserved Flowers Market