
 Candle Market | 2026-2036
Candle Market Size, Share, and Industry Trends Forecast 2026-2036
Candle Market Analysis
Specialty retail distribution is narrowing as direct-to-consumer platforms capture premium fragrance buyers. Diptyque leverages its Parisian heritage to sustain pricing power in luxury boutiques. Newell Brands anchors mass-market shelf space through Yankee Candle's retail footprint. Scentsy competes via independent consultant networks that control recurring revenue streams.
A candle is a solid fuel source comprising a wick embedded in wax, designed to produce light, heat, or aromatic vapor through controlled combustion at temperatures typically between 800°C and 1400°C. Paraffin wax dominates material inputs due to low cost and reliable burn performance, though soy wax gains traction among clean-label positioning. Jar candles command the largest value share as container formats extend burn time and justify premium pricing. Votive formats serve high-turnover hospitality procurement where replacement frequency matters more than unit margin.
REACH in Europe mandates full fragrance allergen disclosure, while FDA oversight in the United States governs cosmetic claims on scented products. California's Proposition 65 adds state-level warning requirements that reshape formulation choices for national brands. Stakeholders must monitor evolving chemical restriction lists that determine which wax blends and fragrance compounds retain market access.
Market Dynamics
REACH compliance in Europe is forcing full fragrance allergen disclosure across wax formulations, compressing formulation flexibility while simultaneously opening premium positioning for compliant clean-label products. This regulatory pressure intersects with hospitality sector procurement standards that now mandate chemical transparency in ambient scenting programs.
Growth Catalysts
- Hospitality Ambient Scenting:Hotels and resorts deploy branded fragrance programs to differentiate guest experiences. Candle-based scenting offers controlled burn rates that HVAC diffusion cannot replicate.
- REACH Disclosure Mandates:Europe's chemical transparency requirements reward early compliance. Brands with pre-positioned clean formulations capture shelf space from laggards facing reformulation delays.
- Soy Wax Process Innovation:Hydrogenation advances improve soy wax scent throw and burn stability. Clean-label positioning now matches paraffin performance at acceptable cost premiums.
Market Restraints
- Petroleum Feedstock Volatility:Paraffin wax pricing tracks crude oil futures. Manufacturers lack hedging instruments sized to candle industry volumes.
- Fragrance Compound Concentration:Three suppliers dominate IFRA-compliant fragrance houses. Formulators face allocation constraints during peak seasonal demand.
- Combustion Emission Scrutiny:California Proposition 65 warning requirements for soot and volatile organic compounds limit formulation choices for national distribution.
Strategic Opportunities
- India Premium Home Fragrance:Urban households in Mumbai and Delhi demonstrate willingness to pay import-equivalent prices for scented jar candles. Local production partnerships reduce landed cost barriers.
- Subscription Replenishment Models:Direct-to-consumer platforms automate seasonal scent rotation. Recurring revenue streams reduce customer acquisition cost amortization.
- EU Green Deal Alignment:Bio-based wax certifications and carbon footprint labeling qualify products for public procurement preferences and green retail placement.
Industry Challenges
- Perfumer Talent Scarcity:Fragrance development for combustion products requires specialized stability expertise. Training pipelines have not expanded with market demand.
- Multi-Jurisdiction Labeling Complexity:Simultaneous compliance with FDA cosmetic claims, EPA pesticide regulations for insect-repellent candles, and state-level warning requirements fragments packaging runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Candle Market |
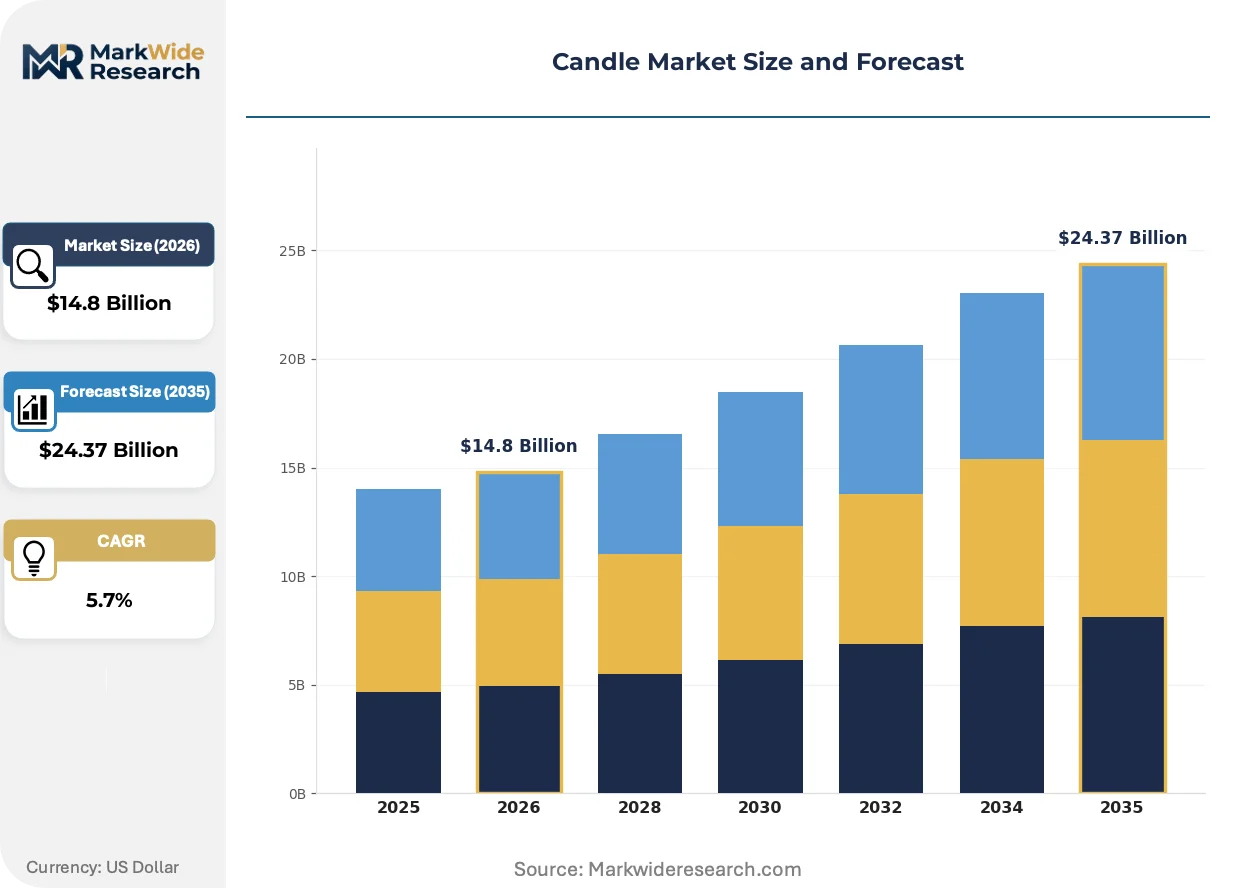
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tea Light, Pillar, Votive, Jar Material: Wax, Soy, Paraffin, Beeswax Fragrance Type: Floral, Citrus, Spicy, Herbal End User: Retail, Hospitality, Personal Use, Events |
| Companies Covered | Diptyque, Hyfusin Group Holdings, Newell Brands, NEST New York, Scentsy, Bath & Body Works, Empire Candle, Jo Malone London, Bolsius International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Candle Market Emerging Trajectories
Wax chemistry and combustion engineering are converging to solve the historical trade-off between clean burn credentials and fragrance performance. This convergence is reshaping R&D priorities across material suppliers and finished goods manufacturers.
Plant-based wax blends is hybridizing paraffin performance with renewable credentials. Hospitality procurement teams in the United States and Germany now specify minimum bio-content thresholds. This hybridization is compressing the market share of pure paraffin offerings while raising barriers for unblended soy alternatives with weaker scent throw.
REACH fragrance allergen disclosure mandates in Europe now extend to online sales listings. E-commerce platforms must display full ingredient breakdowns before purchase completion. Luxury segment players with pre-established transparency protocols capture traffic from mass-market brands scrambling to reformat digital assets.
Direct sampling through mail subscription boxes is displacing in-store olfactory testing for new customer acquisition. Independent consultant networks and DTC platforms ship miniature votives to households in the United States and United Kingdom. This channel shift compresses traditional retail markup structures while expanding geographic reach beyond boutique catchment areas.
Candle Market Segmentation
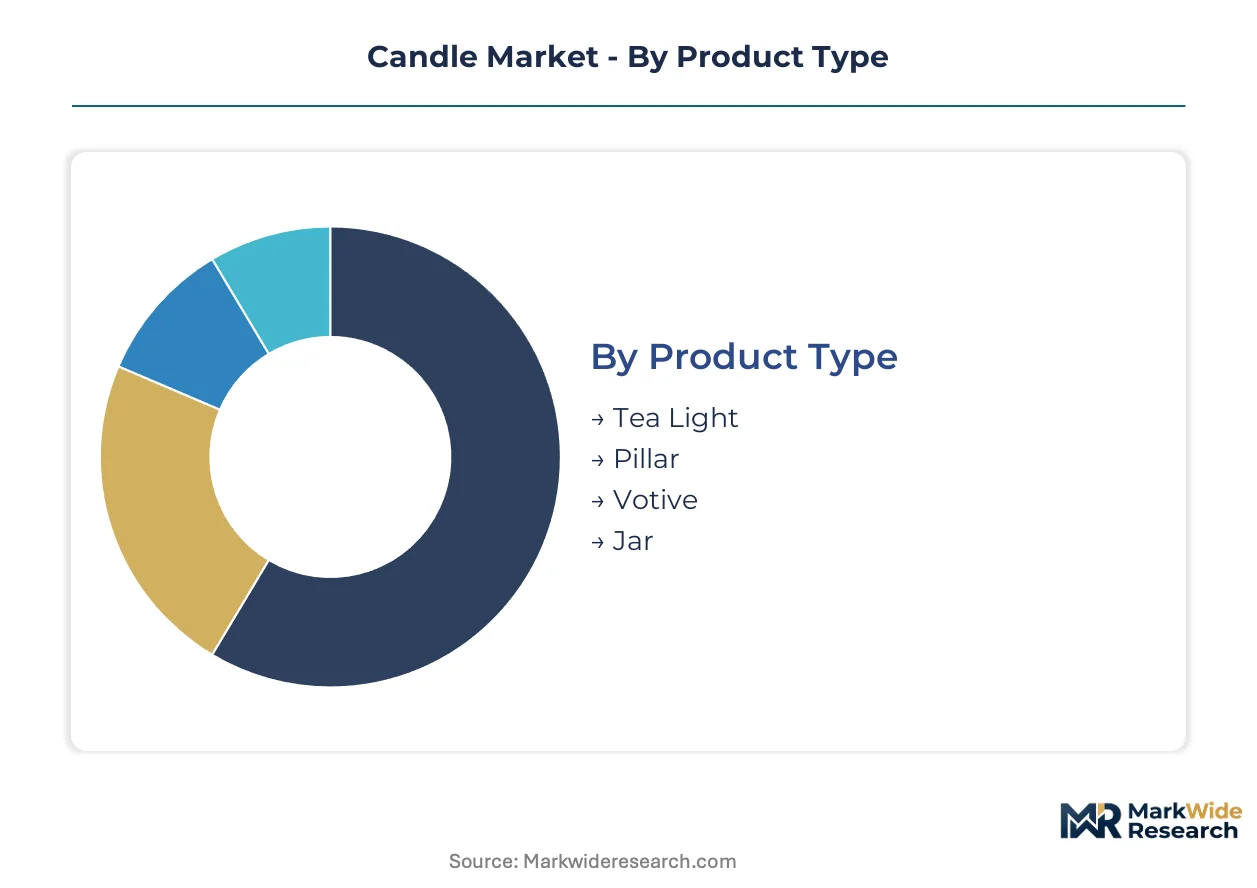
Candle manufacturers optimize formulation and format specifications against distinct burn-time requirements, scent-throw expectations, and procurement economics. Segmentation discipline separates commodity replenishment from premium positioning opportunities.
Product Type:
Cost tier determines margin structure and channel placement across container formats.
- Jar:Glass containers extend burn duration to 60-120 hours while enabling layered fragrance releases. Premium home fragrance buyers in the United States concentrate demand here, with direct-to-consumer platforms capturing recurring replenishment through subscription models.
- Votive:Compact 1.5-2.5 hour burn cycles suit high-turnover hospitality procurement. Hotels in Germany and France specify votive formats for guest room turndown services where replacement frequency outweighs unit margin capture.
- Pillar:Freestanding cylinders deliver 30-50 hour burn performance without container cost. Event planners and religious institutions drive volume procurement.
- Tea Light:Aluminum-cupped miniatures serve food warming and decorative accent applications. Mass retail channels dominate distribution.
Jar holds installed capacity. Votive is rotating up the share rankings.
Material:
Supply concentration and feedstock volatility differentiate wax chemistry choices.
- Paraffin:Petroleum-derived wax delivers superior scent throw and color stability at lowest unit cost. REACH compliance deadlines in Europe are compressing formulation flexibility, with ECHA disclosure mandates accelerating clean-label substitution.
- Soy:Hydrogenated soybean oil enables renewable content claims and cleaner combustion profiles. United States manufacturers lead process innovation, with Iowa and Illinois processing clusters supplying hydrogenation advances that narrow performance gaps with paraffin.
- Beeswax:Natural secretion from honeycomb construction offers longest burn duration and dripless performance. Niche premium positioning targets allergen-sensitive consumers.
- Wax:Blended and proprietary formulations combine bio-content thresholds with performance specifications. Hospitality procurement teams increasingly specify minimum renewable percentages.
Paraffin retains volume leadership. Soy is climbing the fastest.
Fragrance Type:
Customer type and occasion context drive olfactory preference clustering.
- Floral:Rose, jasmine, and lavender compounds dominate residential bedroom and bathroom applications. IFRA-compliant European fragrance houses control supply allocation.
- Citrus:Bergamot, grapefruit, and lemon notes target kitchen and workspace energizing. United Kingdom direct-to-consumer platforms report strongest subscription retention for citrus-forward seasonal rotations.
- Spicy:Cinnamon, clove, and nutmeg formulations concentrate in fourth-quarter seasonal procurement. Limited production windows strain compound availability.
- Herbal:Eucalyptus, sage, and mint profiles align with wellness positioning. California Proposition 65 warning requirements for certain botanical extracts constrain formulation choices.
Floral maintains baseline demand. Citrus is gaining share fastest.
End User:
Application context separates contract procurement from discretionary purchase behavior.
- Hospitality:Branded ambient scenting programs at hotel chains and resort properties require chemical transparency documentation. REACH-compliant suppliers capture procurement contracts from laggards facing reformulation delays.
- Retail:Supermarket, specialty boutique, and e-commerce channels serve household replenishment. Private-label penetration is compressing branded margin structures.
- Personal Use:Individual consumers select for occasion-based gifting and home décor expression. Independent consultant networks control recurring revenue streams through relationship-based selling.
- Events:Wedding planners and corporate function coordinators procure bulk votive and tea light formats. Seasonal demand concentration creates inventory financing challenges.
Hospitality holds contract value concentration. Personal Use is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium jar candles in the United States command unit prices triple those in India, creating a pricing-power asymmetry that shapes cross-border investment flows and local production strategies.
United States
Premium home fragrance spending persists despite macroeconomic headwinds, with direct-to-consumer platforms capturing recurring revenue through subscription replenishment models. California's Proposition 65 imposes state-level warning requirements for soot and volatile organic compounds that reshape national formulation choices. Iowa and Illinois processing clusters supply hydrogenation advances that narrow soy wax performance gaps with petroleum-derived alternatives.
Germany
Hotels in Frankfurt and Munich specify votive formats for guest room turndown services where replacement frequency outweighs unit margin capture. REACH mandates through ECHA force full fragrance allergen disclosure across wax formulations, compressing flexibility for non-compliant imports. The North Rhine-Westphalia industrial corridor hosts blending facilities that serve hospitality procurement teams across the Benelux region.
France
Parisian heritage positioning sustains pricing power in luxury boutiques serving affluent domestic and tourist consumers. ANSM oversees cosmetic claims on scented products sold through pharmacy channels, adding a secondary compliance layer beyond REACH. The Île-de-France region concentrates headquarters operations for houses leveraging artisanal narrative in global export markets.
India
Urban households in Mumbai and Delhi demonstrate willingness to pay import-equivalent prices for scented jar candles, though landed cost barriers limit volume penetration. BIS certification requirements for product safety create entry friction for unregistered foreign suppliers. Maharashtra and Gujarat host emerging local production partnerships that reduce logistics costs for premium positioning trials.
United Kingdom
Direct-to-consumer platforms report strongest subscription retention for citrus-forward seasonal rotations among London and Southeast England households. The country's national chemical regulator enforces REACH-aligned disclosure standards for e-commerce listings that display full ingredient breakdowns before purchase completion. Midlands-based fulfillment centers service independent consultant networks controlling recurring revenue streams.
Candle Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream, supplying wax blends and fragrance compounds to finished goods manufacturers. The vendor base separates into three distinct strata: heritage houses with Parisian or London provenance, mass-market conglomerates with retail shelf dominance, and relationship-driven networks using independent consultants. Consolidation pressure concentrates at the mass-market tier where private-label penetration compresses branded margin structures. Dominant competitive moves include geographic licensing agreements that extend brand reach without capital-intensive retail buildout, and backward integration into captive wax processing to secure bio-content thresholds for hospitality procurement.
Among heritage-positioned houses, Diptyque and Jo Malone London occupy positions where provenance narrative justifies sustained pricing power in boutique and department store channels. Newell Brands exemplifies the scale-driven conglomerate archetype, anchoring mass-market shelf space through established retail footprints. Scentsy represents the relationship-network model, sitting within the independent consultant tier that controls recurring revenue streams through direct selling rather than third-party retail placement.
| Leading Market Players |
|---|
| Diptyque |
| Hyfusin Group Holdings |
| Newell Brands |
| NEST New York |
| Scentsy |
| Bath & Body Works |
| Empire Candle |
| Jo Malone London |
| Bolsius International |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Iowa and Illinois soy wax processing clusters is compressing supplier margins while simultaneously narrowing the cost premium against petroleum-derived paraffin. This utilization dynamic forces blenders to absorb feedstock volatility rather than pass through costs, reshaping pricing power across container formats and material tiers.
Pricing Analysis
Configured-to-order jar candles with custom fragrance layering command unit prices triple standard votive formats. Three-tier pricing structure across premium, standard, and economy levels stratifies by burn duration certification and bio-content thresholds. Pricing pressure stems from private-label penetration in mass retail channels, where branded margin structures face compression. Hospitality procurement teams demonstrate lowest price sensitivity, prioritizing chemical transparency documentation over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk profiles for fragrance compound imports. Paraffin wax production centers on Texas and Louisiana petroleum refining corridors, while soy wax hydrogenation clusters in Iowa and Illinois. Formulators draw from IFRA-compliant European fragrance houses, creating allocation constraints during peak seasonal demand. Distribution runs through direct-to-consumer platforms and independent consultant networks that bypass traditional retail markup structures.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized perfumer expertise for combustion product stability represents a binding constraint on formulation innovation. This capability gap separates houses with captive fragrance development from competitors dependent on external compound suppliers.
For Market Incumbents: Entrench pricing power through backward integration into captive wax processing facilities that secure bio-content thresholds for hospitality procurement. Invest in REACH pre-compliance certification to capture shelf space from reformulation-lagged competitors facing ECHA disclosure delays. Prioritize direct-to-consumer platform control to defend margin structures against private-label compression. For New Entrants and Emerging Players: Build out local production partnerships in Maharashtra and Gujarat to reduce landed cost barriers for premium jar candle trials in Mumbai and Delhi households. Target subscription replenishment models with citrus-forward seasonal rotations, where United Kingdom platforms demonstrate strongest retention metrics. Deploy independent consultant networks to bypass capital-intensive retail footprint requirements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer platforms with automated scent rotation programs. Long-term viability favors acquisition targets with established transparency protocols and pre-positioned clean formulations that capture traffic from mass-market brands scrambling to reformat digital assets. Monitor REACH enforcement acceleration as inflection indicator for compliant supplier valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wax Processing | Captive bio-content thresholds secure hospitality procurement contracts requiring minimum renewable percentages. |
| REACH Pre-Compliance Certification | ECHA disclosure mandates reward early positioning with shelf space from reformulation-delayed competitors. |
| Direct-to-Consumer Platform Launch | Subscription replenishment models reduce customer acquisition cost amortization through automated seasonal rotation. |
| Local Production Partnership in India | Maharashtra and Gujarat facilities reduce logistics costs for premium positioning trials in Mumbai and Delhi. |
| Independent Consultant Network Expansion | Relationship-based selling controls recurring revenue streams without third-party retail placement dependence. |
Methodological Framework
Initial hypotheses were tested against primary input from fragrance development executives, hospitality procurement managers, wax processing plant managers, and direct-to-consumer platform operators and refined through secondary validation. Trade data from customs records, SEC filings from publicly traded parent companies, REACH registration databases, and Nielsen retail audit data anchored supply-side and demand-side estimates. Bottom-up capacity modeling and top-down expenditure calibration triangulated volume and value outputs.
Demand-supply-balance framing structured the analytical approach across the projection horizon. Segmentation dimensions modeled include product format, material chemistry, fragrance type, and end-use application context. CAGRs were derived from trajectory fitting against historical elasticity patterns and forward-looking procurement intention surveys. Industry-specific inputs incorporated hydrogenation process innovation timelines and hospitality ambient scenting program adoption curves.
Practitioners should monitor petroleum feedstock volatility, REACH enforcement acceleration, and private-label penetration rates for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home & Garden
Global Hot Tub Market
Home & Garden
Japan Flower Pots Market
Home & Garden
Flexible Garden Hoses Market
Home & Garden
Landscaping Products Market
Home & Garden
Landscaping and Gardening Service Market
Home & Garden
Artificial Flowers Market
Home & Garden
North America Flowerpots Market
Home & Garden
United States Landscaping Market
Home & Garden
Automated Blinds and Shades Market
Home & Garden
Artificial Plants and Flowers Market
Home & Garden
Artificial Plants Market
Home & Garden
Lawn and Garden Consumables Market
Home & Garden
Lawn and Garden Water Equipment Market
Home & Garden
Residential Snow Blower Market
Home & Garden
Global Motorized and Smart Awnings Market
Home & Garden
Incense Market