
 United States Compound Feed Market | 2026-2036
United States Compound Feed Market Size, Share, and Industry Trends Forecast 2026-2036
United States Compound Feed Market Analytics
Buyer concentration among large livestock integrators is shifting procurement toward volume-contracted feed supply. CHS Inc. leverages its farmer-owned cooperative structure to control origination-to-feed mill logistics. Cargill Incorporated anchors Midwest production geography through vertically integrated grain handling and formulation facilities. Archer Daniels Midland Company competes on oilseed processing scale that supplies captive protein meal streams to compound feed operations.
Compound feed denotes nutritionally complete mixtures of milled grains, protein meals, vitamins, and minerals formulated to specified metabolizable energy and crude protein percentages for targeted livestock species. Poultry feed dominates volume throughput due to vertically integrated broiler operations demanding uniform diet specifications across grow-out cycles. Ruminant feed draws margin from customized premix services and ionophore inclusion protocols. Aquafeed represents the fastest-growing product type as inland recirculating aquaculture systems expand species diversification beyond traditional channel catfish.
The FDA enforces the Veterinary Feed Directive restricting medically important antibiotics to veterinary oversight, reshaping additive formulation portfolios. USDA grading standards for feed grains and EPA Clean Water Act nutrient discharge permits for concentrated animal feeding operations jointly determine ingredient sourcing and facility siting decisions. State departments of agriculture in Iowa, Minnesota, and Nebraska administer additional feed labeling and inspection protocols. Stakeholders must monitor emerging precision livestock feeding technologies and evolving antibiotic-alternative regulatory thresholds to align R&D allocation with compliance-bound demand.
Market Dynamics
Precision livestock feeding technologies are compressing formulation cycles while the FDA's Veterinary Feed Directive forces antibiotic-free additive portfolios, creating a dual squeeze on mill R&D budgets and procurement specifications across the Corn Belt.
Growth Catalysts
- Precision Feeding Hardware:Automated feed delivery systems with real-time intake monitoring are enabling integrators to reduce feed conversion ratios in broiler operations.
- EPA Nutrient Management:Concentrated animal feeding operation discharge permits are accelerating demand for low-phosphorus formulations that reduce environmental compliance costs.
- Recirculating Aquaculture Systems:Inland fish farming expansion in the Great Lakes corridor is generating species-specific aquafeed demand beyond traditional channel catfish diets.
Market Restraints
- Grain Price Volatility:Corn and soybean meal input costs swing with drought cycles and export demand, compressing formulation margins unpredictably.
- Midwest Supply Concentration:Over sixty percent of national feed milling capacity clusters within Iowa, Illinois, and Nebraska, creating origination risk during regional weather events.
- Antibiotic Alternative Efficacy Gap:Phytogenic and probiotic additives have not matched ionophore performance consistency in ruminant feed trials.
Strategic Opportunities
- Southeast Poultry Belt:Georgia and Alabama integrators are expanding grow-out capacity faster than local mill infrastructure, creating contract manufacturing openings.
- Carbon Accounting Integration:USDA Climate-Smart Commodities grants are incentivizing feed mills to certify low-carbon intensity formulations for branded protein programs.
- Blockchain Traceability:Ingredient provenance tracking from elevator to feedlot is enabling premium pricing for verified origin grain streams.
Industry Challenges
- Formulation Chemist Shortage:Universities are graduating fewer animal nutrition PhDs than mills require for precision diet modeling.
- Legacy ERP Integration:Real-time formulation software requires retrofitting decades-old mill control systems that lack API connectivity.
- Organic Certification Timelines:Three-year land transition requirements delay organic feed line launches and tie up working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Compound Feed Market |
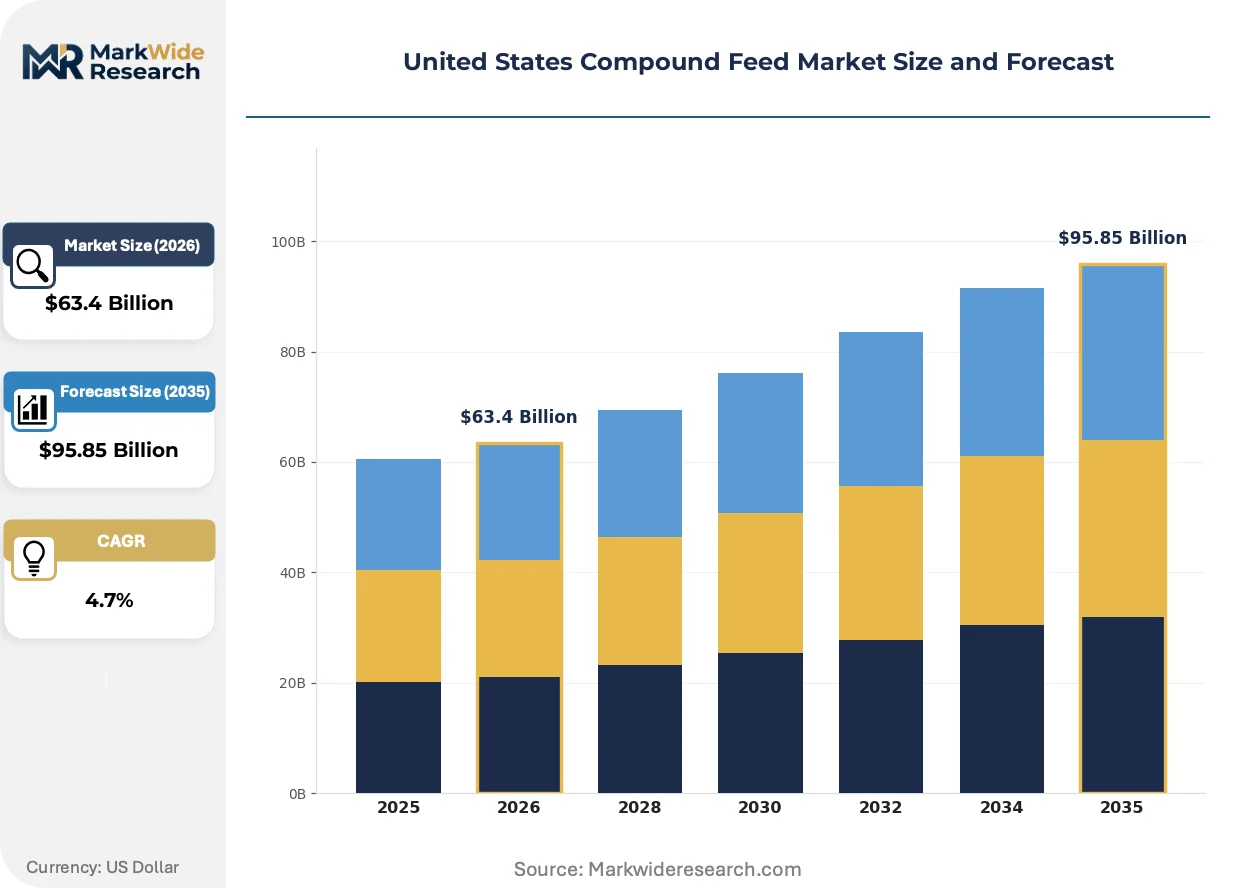
| Market Size in 2026 | $63.4 Billion |
| Market Size in 2035 | $95.85 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Poultry Feed, Ruminant Feed, Swine Feed, Aquafeed Ingredient Type: Cereal Grains, Oilseed Meals, Nutritional Additives, By-products End User: Farmers, Feed Manufacturers, Livestock Producers, Aquaculture Suppliers Distribution Channel: Direct Sales, Retail, Online Sales, Wholesalers |
| Companies Covered | CHS Inc., J.D. Heiskell & Co., Archer Daniels Midland Company, Perdue AgriBusiness, Kent Nutrition Group, Cargill Incorporated, Alltech, Smithfield Foods, Land O'Lakes, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Compound Feed Market Evolving Landscape
Feed formulation is migrating from static nutrient matrices toward dynamic, real-time adjusted diets that respond to individual animal performance data and environmental conditions.
Near-infrared spectroscopy coupled with cloud-based formulation algorithms is decentralizing quality control from central laboratories to individual feed trucks and farm silos. Large integrators in the Delmarva Peninsula are deploying mobile NIR units that adjust diets within hours rather than days. This compression of the formulation feedback loop is decentralizing technical decision-making from nutritionist teams to on-site operations managers.
The FDA's Veterinary Feed Directive continues tightening medically important antibiotic access, forcing mills to rebuild additive portfolios around phytogenics, organic acids, and targeted probiotics. Formulation teams must now document veterinary prescriptions for ionophore inclusion, adding administrative overhead to every ruminant premix order. Poultry feed operations have adapted fastest due to shorter grow-out cycles that accelerate trial-and-error testing.
Volume-contracted supply agreements are displacing spot-market grain purchases among the top twenty livestock integrators. These arrangements lock origination prices six to twelve months forward and specify quality premiums for low-mycotoxin corn. The shift is most visible in Texas Panhandle cattle feedyards, where captive corn supply from the High Plains now dominates procurement planning.
United States Compound Feed Market Segmentation
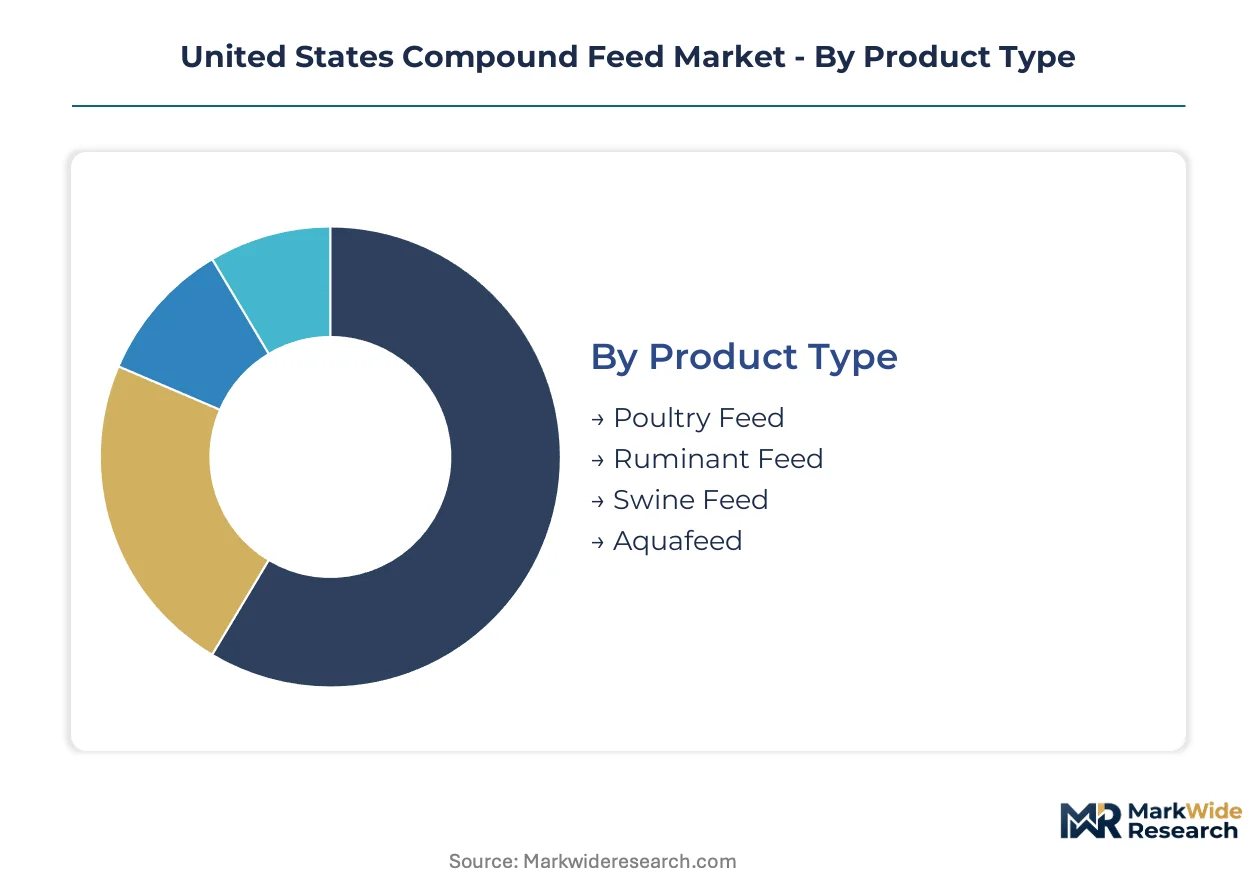
Compound feed segmentation reflects the tension between standardized volume production for integrators and customized formulation for specialized livestock operations. Specification requirements vary sharply across species metabolism, regulatory thresholds, and environmental compliance burdens.
Product Type:
Formulation complexity escalates with animal digestive physiology and grow-out cycle duration.
- Poultry Feed:Corn-soybean meal bases dominate, with metabolizable energy specifications typically ranging 3,000-3,200 kcal/kg for broiler starters. Georgia and Alabama integrators drive demand for uniform pellet durability across automated delivery systems, with the FDA's Veterinary Feed Directive accelerating ionophore-free additive trials.
- Ruminant Feed:Customized premix services incorporating ionophores, buffers, and bypass proteins command premium positioning. Texas Panhandle feedyards concentrate procurement of steam-flaked corn formulations that optimize rumen fermentation efficiency while meeting EPA nutrient discharge permit thresholds.
- Swine Feed:Phase-feeding protocols segment diets by growth stage from nursery through finishing, with lysine-to-energy ratios precisely calibrated.
- Aquafeed:Species-specific formulations for recirculating aquaculture systems in the Great Lakes corridor are climbing the fastest, driven by diversification beyond channel catfish into yellow perch and walleye.
Mature deployment sits with poultry feed. Newer deployment is concentrated in aquafeed.
Ingredient Type:
Cost structure and supply security hinge on origination geography and processing integration depth.
- Cereal Grains:Corn dominates caloric density at 60-70% of typical formulations, with Iowa and Illinois elevators supplying low-mycotoxin premiums to volume-contracted integrators. Drought cycles in the Corn Belt inject price volatility that compresses mill margins unpredictably.
- Oilseed Meals:Soybean meal supplies 44-48% crude protein standards, with Archer Daniels Midland's processing scale anchoring Midwest protein meal streams to captive compound feed operations.
- Nutritional Additives:Vitamin premixes, trace minerals, and amino acid supplements enable precision diet modeling.
- By-products:Distillers dried grains with solubles and wheat middlings substitute for corn on price spreads, with inclusion rates varying by species tolerance.
Volume concentration rests with cereal grains. Margin expansion concentrates in nutritional additives.
End User:
Procurement sophistication separates spot-market buyers from integrated supply chain operators.
- Livestock Producers:Large-scale cattle feedyards and dairy operations in California's Central Valley and the Southwest negotiate six-to-twelve-month forward contracts specifying quality premiums and origination traceability. These arrangements displace spot-market purchases and lock formulation costs against grain price swings.
- Feed Manufacturers:Independent mills in the Southeast poultry belt face capacity constraints as Georgia and Alabama integrators expand grow-out operations faster than local infrastructure.
- Farmers:Small-to-midscale operations purchase bagged feed through retail channels with limited formulation customization.
- Aquaculture Suppliers:Recirculating system operators demand specialized floating and sinking pellet formats with extended water stability.
Contract sophistication peaks with livestock producers. Service intensity concentrates with aquaculture suppliers.
Distribution Channel:
Logistics integration determines delivery reliability and formulation freshness.
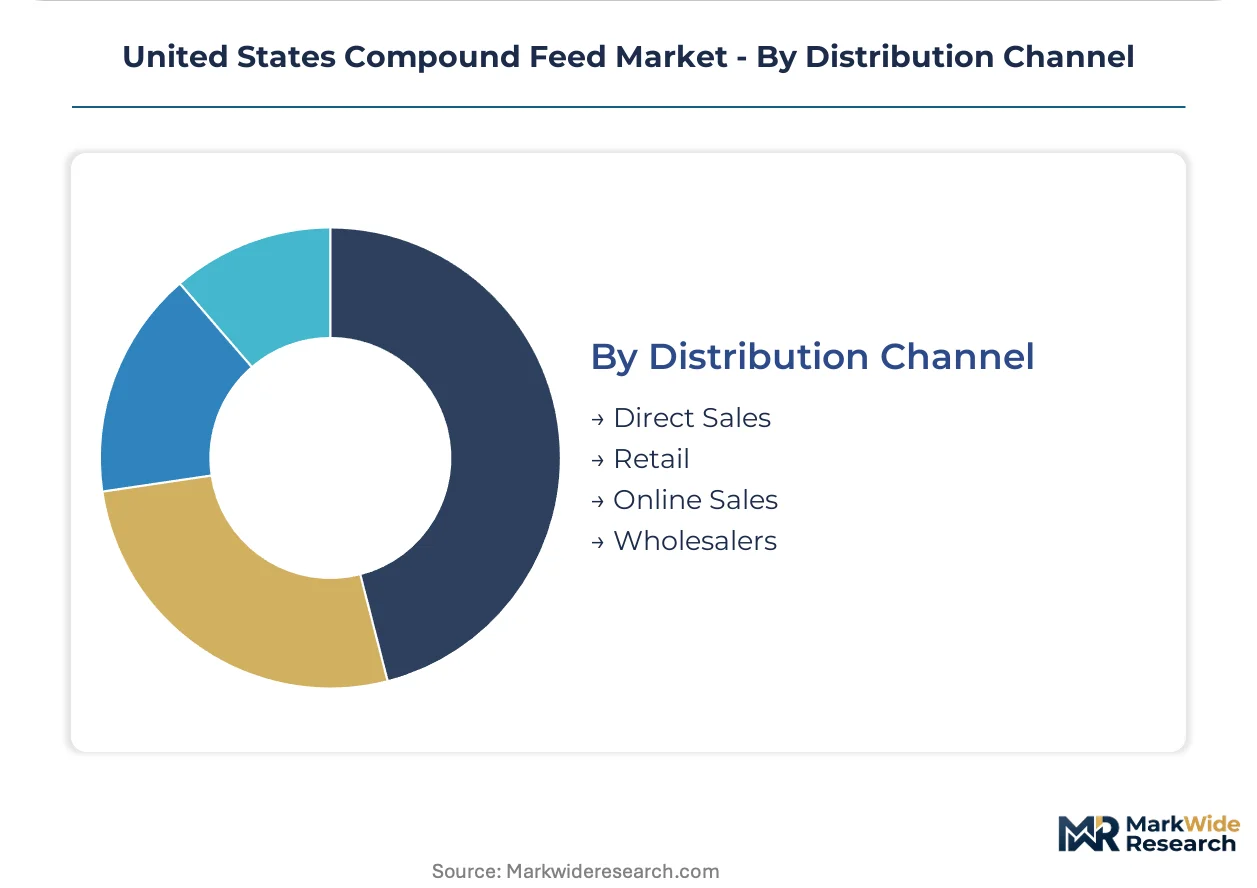
- Direct Sales:CHS Inc.'s farmer-owned cooperative structure controls origination-to-feed mill logistics, with volume-contracted supply agreements specifying just-in-time delivery to concentrated animal feeding operations. This channel captures the largest throughput share among top-twenty integrators.
- Wholesalers:Regional distributors aggregate smaller livestock producer demand across Nebraska and Kansas, buffering mills against order fragmentation.
- Retail:Farm supply stores serve hobby farmers and small-scale operations with bagged product.
- Online Sales:E-commerce penetration remains limited to specialty additives and small-batch organic formulations with extended lead times.
Scale efficiency sits with direct sales. Channel experimentation concentrates in online sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large livestock integrators concentrate procurement in the Corn Belt states where feed milling capacity clusters near grain origination points. Iowa, Illinois, and Nebraska house over sixty percent of national milling infrastructure. State-level nutrient management rules and the FDA's Veterinary Feed Directive are tightening formulation requirements across all producing regions.
Iowa
Broiler integrators and large-scale hog operations drive demand for precision-formulated corn-soybean meal diets. The Iowa Department of Agriculture and Land Stewardship administers feed labeling and inspection protocols that exceed federal minimums. Sioux City and Des Moines anchor concentrated milling corridors where CHS Inc.'s farmer-owned cooperative structure controls origination-to-feed mill logistics.
Illinois
Dairy operations in the northern counties and cattle feedyards in the western regions require customized premix services with ionophore inclusion protocols. EPA Clean Water Act nutrient discharge permits for concentrated animal feeding operations determine ingredient sourcing decisions. Decatur hosts Archer Daniels Midland's oilseed processing scale that supplies captive protein meal streams to compound feed operations.
Nebraska
Beef cattle feedyards in the Panhandle negotiate six-to-twelve-month forward contracts specifying quality premiums for low-mycotoxin corn. The Nebraska Department of Agriculture enforces additional state-level feed inspection requirements beyond FDA standards. Grand Island and Omaha concentrate independent mill capacity that serves spot-market buyers across the High Plains.
Georgia
Poultry integrators are expanding grow-out capacity faster than local mill infrastructure can accommodate, creating contract manufacturing openings. The Georgia Department of Agriculture coordinates with FDA on Veterinary Feed Directive enforcement for ionophore-free additive trials. Gainesville and Athens anchor the Southeast poultry belt where automated feed delivery systems with real-time intake monitoring are reducing feed conversion ratios.
California
Large-scale dairy operations in the Central Valley and cattle feedyards in the Imperial Valley demand low-phosphorus formulations that reduce environmental compliance costs. The California Department of Food and Agriculture implements stricter feed safety standards than federal baselines. Tulare and Fresno counties concentrate procurement sophistication among integrators locking formulation costs against grain price swings through volume-contracted supply agreements.
United States Compound Feed Market Competitive Landscape
Corn Belt producers anchor one tier; Southeast specialists hold contract manufacturing positions as integrator expansion outpaces local infrastructure. The vendor base concentrates around farmer-owned cooperatives, agribusiness conglomerates with oilseed processing scale, and independent regional mills serving fragmented livestock producer demand. Three strategic archetypes dominate: vertically integrated grain-to-feed operators controlling origination logistics, premix specialists delivering customized additive portfolios, and cooperative structures leveraging farmer ownership for supply security. M&A activity concentrates on acquiring captive corn supply origination points, while capacity expansion targets the Southeast poultry belt where mill infrastructure lags grow-out growth.
Within the cooperative archetype, CHS Inc. exemplifies farmer-owned structures that control elevator-to-mill logistics across the Upper Midwest. Cargill Incorporated and Archer Daniels Midland Company occupy positions among agribusiness conglomerates with oilseed processing scale anchoring Midwest production geography. These three names represent the dominant competitive positioning patterns: cooperative origination control, conglomerate processing integration, and captive protein meal supply chains.
| Leading Market Players |
|---|
| CHS Inc. |
| J.D. Heiskell & Co. |
| Archer Daniels Midland Company |
| Perdue AgriBusiness |
| Kent Nutrition Group |
| Cargill Incorporated |
| Alltech |
| Smithfield Foods |
| Land O'Lakes |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between organic and conventional feed streams manifests in both pricing premiums and captive origination networks, with USDA organic standards requiring three-year land transition timelines that lock working capital while commanding 15-40% price markups over commodity formulations.
Pricing Analysis
Volume-mass versus margin-premium splits dominate the pricing architecture, with commodity corn-soybean meal formulations competing on per-ton efficiency while customized premix services with ionophore protocols capture value through veterinary oversight documentation. Price differentiation rests on metabolizable energy guarantees and mycotoxin certification tiers, with low-aflatoxin premiums widening during drought cycles in Iowa and Illinois. Cost compression in standard poultry feed intensifies as Georgia integrators consolidate procurement through six-to-twelve-month forward contracts. Small-to-midscale livestock producers purchasing through retail channels exhibit highest price sensitivity, while large feedyards locking origination prices demonstrate lowest sensitivity to spot-market swings.
Supply Chain Analysis
Rail freight and barge rates from Corn Belt elevators to Southeast poultry operations constitute 8-12% of delivered feed costs, with drought-induced water level disruptions on the Mississippi River system periodically forcing costlier truck alternatives. Geographic supply concentration centers on Iowa, Illinois, and Nebraska, where over sixty percent of national milling capacity clusters within 150 miles of corn origination points. Raw material dependencies include corn for caloric density, soybean meal for protein standards, and distillers dried grains for cost-advantaged substitution. Single-source vulnerability runs through concentrated animal feeding operation discharge permits that restrict facility siting. Distribution runs through farmer-owned cooperative structures controlling elevator-to-mill logistics for top-twenty integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mill infrastructure expansion in the Southeast poultry belt lags integrator grow-out capacity additions, constraining supply response and supporting pricing power for existing capacity holders.
For Market Incumbents: Hedge formulation margin exposure through backward integration into captive corn origination in the High Plains, securing low-mycotoxin supply streams before drought cycles compress availability. Deepen veterinary feed directive compliance infrastructure to defend against antibiotic-free additive portfolio shifts that threaten ionophore-dependent ruminant premix revenue. Prioritize ERP retrofit investments that enable real-time formulation software integration before precision feeding technologies obsolete static nutrient matrix competitors. For New Entrants and Emerging Players: The FDA's Veterinary Feed Directive in the United States opens a window for phytogenic and probiotic additive specialists to capture share from legacy ionophore formulations in ruminant premix services. Target contract manufacturing openings in Georgia and Alabama where poultry integrators expand grow-out capacity faster than local mill infrastructure. Pursue carbon accounting certification partnerships with USDA Climate-Smart Commodities grant recipients to differentiate low-carbon intensity formulations for branded protein programs. For Investors and Strategic Acquirers: Re-rating potential sits with independent regional mills possessing Southeast poultry belt proximity given integrator capacity expansion and limited local supply response. Long-term viability favors operators with backward integration into origination logistics rather than spot-market dependent formulation businesses. Monitor EPA nutrient discharge permit issuance rates in the Texas Panhandle as inflection indicator for cattle feedyard formulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Origination | Captive supply from Iowa and Nebraska elevators locks low-mycotoxin premiums against drought volatility. |
| Precision Feeding Technology Deployment | Real-time intake monitoring systems enable integrators to reduce feed conversion ratios in broiler operations. |
| Antibiotic-Free Additive Portfolio Rebuild | Phytogenic and probiotic formulation capabilities align with FDA Veterinary Feed Directive compliance requirements. |
| Carbon Accounting Certification Program | USDA Climate-Smart Commodities grant eligibility opens premium pricing for verified low-carbon intensity feeds. |
| Southeast Poultry Belt Capacity Expansion | Georgia and Alabama contract manufacturing positions capture integrator demand outpacing local mill infrastructure. |
Research Methodology
Multi-period observation of feed conversion ratio trends, ionophore inclusion rates, and volume-contracted supply agreement penetration anchored the trend analysis, supplemented by interviews with feed mill operations managers, poultry integrator procurement directors, veterinary nutritionists, and grain elevator origination specialists. Secondary validation drew from USDA feed grain statistics, FDA Veterinary Feed Directive enforcement disclosures, EPA concentrated animal feeding operation permit databases, and state agriculture department inspection records. Bottom-up capacity utilization modeling triangulated against top-down livestock inventory projections.
Input-output matrices mapped corn and soybean meal price elasticity against formulation substitution patterns across poultry, ruminant, swine, and aquaculture species segments. Segmentation dimensions included product type, ingredient composition, end-user procurement sophistication, and distribution channel integration depth. CAGRs were derived from regression analysis of historical throughput data projected across the modeling period. Industry-specific forecast inputs incorporated drought cycle frequency patterns and precision livestock technology adoption curves.
Caveats apply where EPA nutrient discharge permit moratoria, Mississippi River logistics disruptions, or organic certification timeline extensions could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Greenhouse Horticulture Market
Agriculture and Agri Products
Pure Plant Oil Market
Agriculture and Agri Products
Honeysuckle Market
Agriculture and Agri Products
North America Shiitake Mushroom Market
Agriculture and Agri Products
Specialty Egg Market
Agriculture and Agri Products
Netherlands Floriculture Market
Agriculture and Agri Products
China Compound Feed Market
Agriculture and Agri Products
Flower Pot Market
Agriculture and Agri Products
US Greenhouse Horticulture Market
Agriculture and Agri Products
Asia-Pacific Alfalfa Market
Agriculture and Agri Products
United States Alfalfa Market
Agriculture and Agri Products
Japan Compound Feed Market
Agriculture and Agri Products
North America Bonsai Market
Agriculture and Agri Products
Africa Olive Market
Agriculture and Agri Products
France Alfalfa Hay Market
Agriculture and Agri Products
Global Commercial Seaweeds Market