
 Global Jet Mill Market | 2026-2036
Global Jet Mill Market Size, Share, and Industry Trends Forecast 2026-2036
Global Jet Mill Market Foresight
Multi-source procurement for precision milling components is decoupling from traditional single-vendor relationships in the jet mill supply base. Hosokawa Micron Corporation leverages its Japanese manufacturing heritage to sustain leadership in air-classification systems. Erich NETZSCH GmbH & Co. Holding KG anchors European demand through specialized fluid energy designs. The Jet Pulverizer Company, Inc. dominates niche pharmaceutical contracts with custom micronization services.
A jet mill pulverizes feed material through high-velocity particle-on-particle collisions within confined gas streams, typically achieving particle sizes below 10 microns at temperatures near ambient due to adiabatic expansion cooling. This mechanism serves industries requiring tight particle-size distributions without thermal degradation, particularly in drug formulation and specialty chemical synthesis. Continuous-type configurations lead capital deployment because pharmaceutical manufacturers prioritize throughput scalability over batch flexibility. Fluid energy technology occupies the deepest margin pools as patent-protected nozzle geometries command premium pricing from API producers. Cosmetics applications represent the fastest-growing demand segment as micronized pigments and mineral sunscreens gain formulation share.
FDA process validation protocols and EU MDR conformity requirements are elevating documentation burdens for jet mill suppliers serving pharmaceutical end users. ISO 9001 and cGMP frameworks now function as baseline market-access credentials rather than differentiators. REACH compliance in Europe and EPA emission thresholds in the United States constrain lubricant and seal material choices in equipment design. Stakeholders must monitor evolving pharmacopeial standards for particle characterization methods to anticipate certification-driven replacement cycles.
Market Dynamics
Pharmaceutical process validation requirements are compressing equipment replacement cycles as FDA and EMA documentation burdens force manufacturers toward certified micronization systems. This regulatory tightening is reshaping supplier qualification protocols across active ingredient production networks.
Growth Catalysts
- API Micronization Mandates:FDA process validation guidelines and EU MDR conformity requirements are elevating purity thresholds for fine particle production. Drug manufacturers must retrofit milling infrastructure to meet pharmacopeial standards.
- Cosmetics Pigment Demand:Mineral sunscreen and color cosmetic formulations are expanding jet mill deployment in personal care manufacturing. Micronized titanium dioxide and zinc oxide require sub-10 micron particle distributions.
- Precision Engineering Clusters:Germany's concentration of advanced manufacturing capabilities supports localized equipment deployment and aftermarket service density for pharmaceutical OEMs.
Market Restraints
- High-Purity Gas Costs:Nitrogen and compressed air systems for inert milling environments represent substantial operating expenditures. Energy price volatility in European markets strains facility-level economics.
- Component Supply Concentration:Precision nozzles and ceramic grinding chambers depend on specialized Japanese and German suppliers. Geopolitical friction threatens lead time reliability.
- Fluid Energy Patent Thickets:Proprietary nozzle geometries and classification chamber designs create licensing barriers for equipment manufacturers entering premium pharmaceutical segments.
Strategic Opportunities
- Indian Pharmaceutical Expansion:CDSCO alignment with ICH guidelines is accelerating domestic API manufacturing capacity. Local equipment assembly partnerships can capture replacement demand from multinational subsidiaries.
- Battery Materials Processing:Cathode precursor micronization for lithium-ion cells represents an emerging application segment. Solid-state battery R&D programs require novel particle engineering capabilities.
- Continuous Manufacturing Incentives:FDA's support for process analytical technology integration favors continuous-type jet mill configurations over batch systems in new facility design.
Industry Challenges
- Multidisciplinary Talent Scarcity:Equipment optimization requires simultaneous competence in fluid dynamics, particle engineering, and pharmaceutical cGMP protocols. Universities produce few graduates at this intersection.
- Legacy System Integration:Brownfield pharmaceutical facilities must reconcile new jet mill installations with existing batch record systems and building management infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Jet Mill Market |
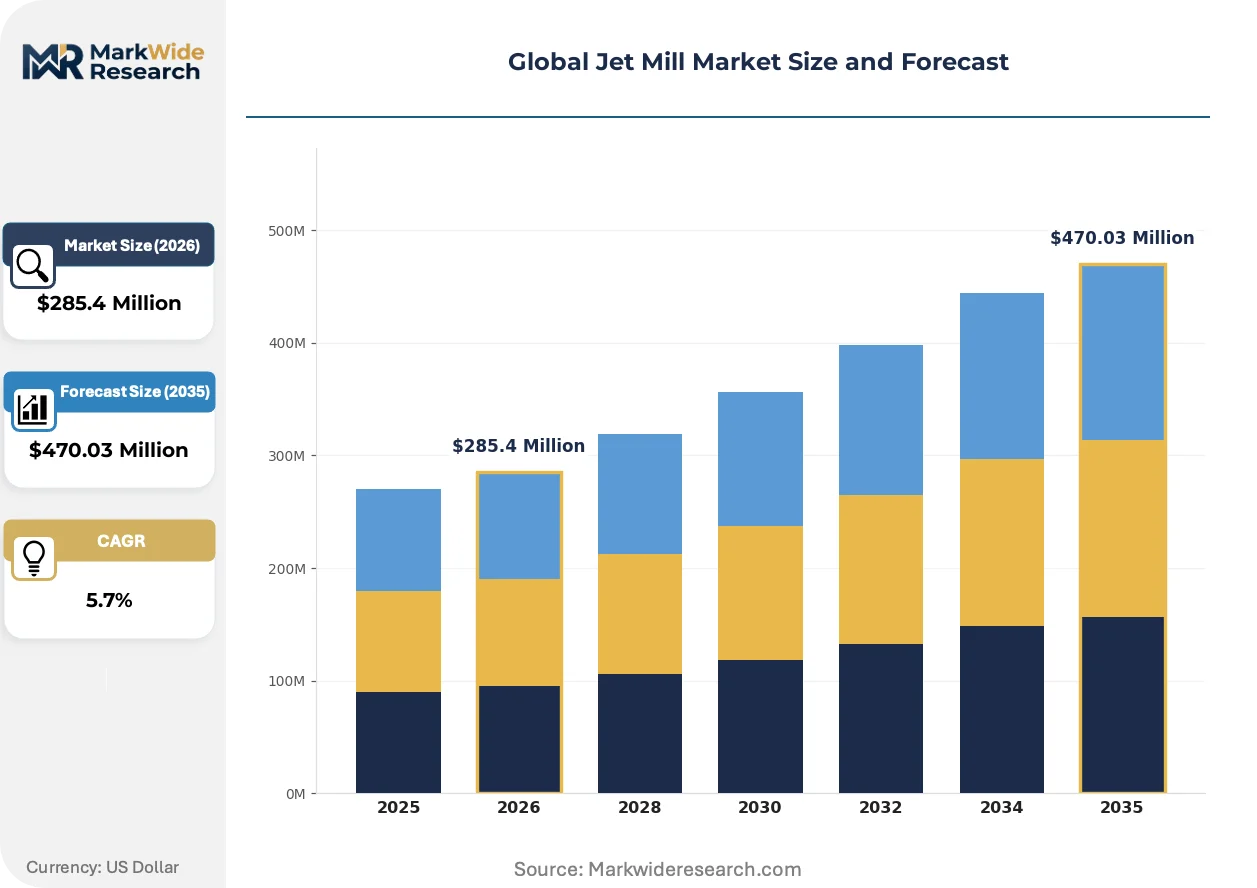
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $470.03 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed Type, Open Type, Batch Type, Continuous Type Technology: Fluid Energy, Impact Milling, Air Milling, Pin Milling Application: Chemical Processing, Mineral Processing, Food Production, Pharmaceuticals, Cosmetics End User: Pharmaceutical Manufacturers, Chemical Manufacturers, Cosmetic Producers, Food Processing Plants |
| Companies Covered | Loesche GmbH, Kunshan Unique Machinery Co. Ltd., Erich NETZSCH GmbH & Co. Holding KG, Promas Engineers Private Limited, Kurimoto Ltd., Fluid Energy Group, FREUND Corporation, The Jet Pulverizer Company, Inc., Hosokawa Micron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Jet Mill Market Shifts & Advancements
Equipment architecture is converging around real-time particle monitoring and automated process control. This integration is compressing the gap between laboratory-scale validation and commercial production throughput.
Computational fluid dynamics simulation is unifying equipment design cycles with operational performance prediction. Engineering teams at pharmaceutical contractors now model collision dynamics before prototype fabrication. This capability is collapsing development timelines for custom micronization configurations and reducing scale-up risk in technology transfer programs.
REACH authorization procedures are constraining lubricant and seal material selections in European equipment supply chains. Manufacturers must reformulate bearing assemblies to eliminate Substances of Very High Concern. German and Swiss OEMs are accelerating fluoropolymer-free designs to preempt regulatory discontinuation of perfluorinated compounds.
Service contracting is fragmenting from bundled maintenance toward unbundled performance guarantees. Pharmaceutical procurement teams now separate spare parts logistics from technical support retainers. This unbundling is most pronounced in North American facilities where centralized corporate purchasing drives vendor rationalization programs.
Global Jet Mill Market Segmentation
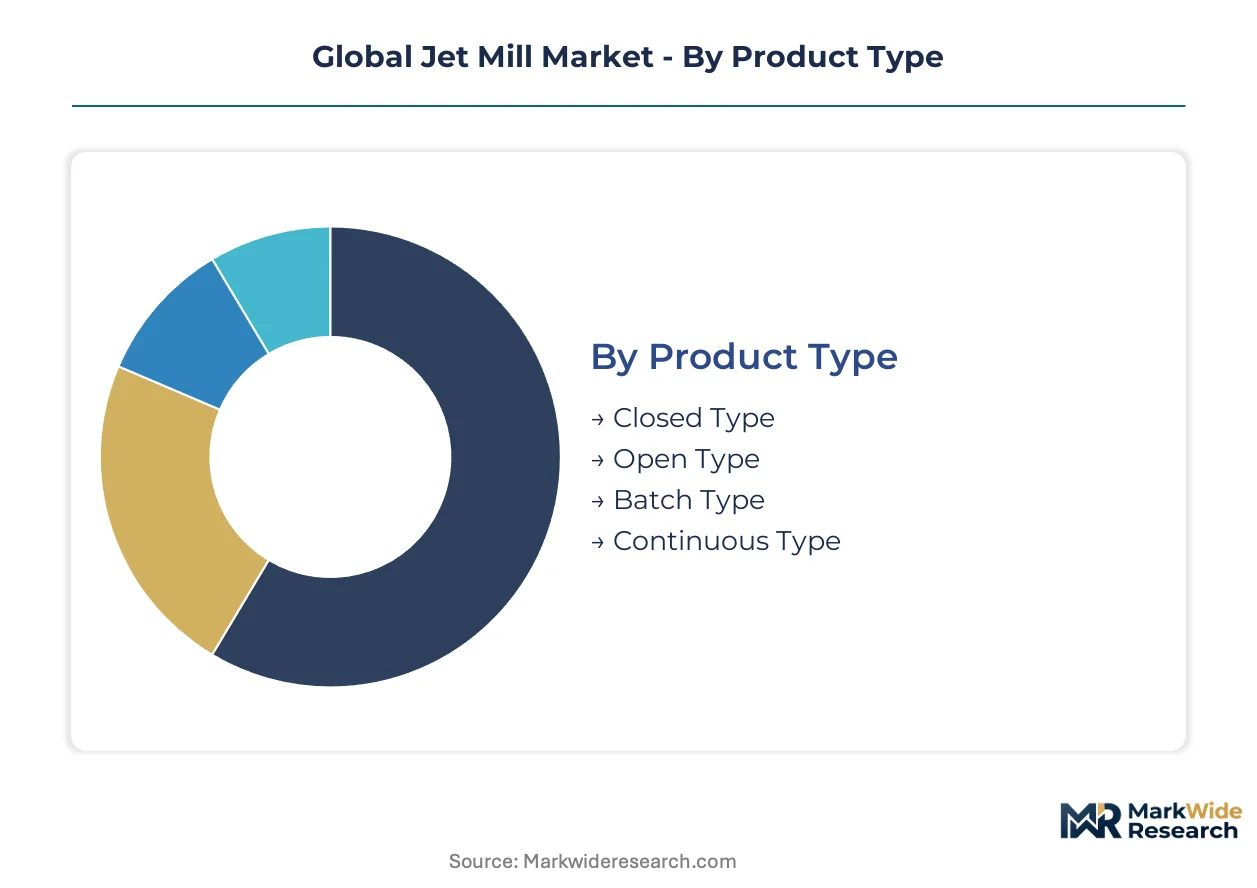
Jet mill procurement decisions pivot on process integration requirements, regulatory compliance burdens, and throughput economics. Equipment specification varies sharply across pharmaceutical validation protocols versus mineral processing volume demands. Understanding segment boundaries clarifies where technology premiums apply and where commodity configurations suffice.
Product Type:
Capital allocation intensity and contamination risk tolerance drive product type selection across end-use verticals.
- Continuous Type:Uninterrupted material flow through integrated classification chambers supports pharmaceutical manufacturers scaling API micronization under FDA process validation protocols. CDSCO-aligned Indian facilities are deploying these configurations to meet ICH guideline harmonization deadlines. Continuous systems lead on scale; Cosmetics applications lead on momentum.
- Closed Type:Sealed processing environments with nitrogen inerting satisfy EU MDR purity mandates for high-potency active ingredients. German precision engineering clusters dominate fabrication of these containment-optimized systems. Batch Type leads on installed base; Continuous Type leads on new order intake.
- Open Type:Atmospheric discharge configurations serve mineral processing and coarse chemical grinding where inerting costs outweigh contamination risks.
- Batch Type:Discrete charge processing retains relevance in R&D-scale pharmaceutical development and specialty chemical campaign manufacturing.
Continuous Type leads on scale; Closed Type leads on momentum.
Technology:
Intellectual property density and energy efficiency benchmarks differentiate technology selection in premium versus commodity applications.
- Fluid Energy:High-velocity gas streams drive particle-on-particle collisions without mechanical wear, preserving heat-sensitive pharmaceutical actives. Patent-protected nozzle geometries from Japanese and German suppliers command licensing premiums in API production. REACH compliance constraints on seal materials are reshaping European equipment specifications.
- Air Milling:Turbulent air classification achieves sub-10 micron distributions for cosmetic pigments and mineral sunscreens. Personal care formulators in France and Switzerland specify these systems for titanium dioxide micronization. Fluid Energy leads on margin capture; Air Milling leads on volume expansion.
- Impact Milling:Mechanical collision mechanisms serve coarse grinding applications in chemical processing where thermal sensitivity is secondary to throughput.
- Pin Milling:Rotating pin configurations handle fibrous or elastic feed materials in food production where jet milling's brittle fracture mechanism proves ineffective.
Fluid Energy leads on scale; Air Milling leads on momentum.
Application:
Regulatory documentation burden and particle size specification precision determine application-level pricing power.
- Pharmaceuticals:Active ingredient micronization demands ISO 9001 and cGMP certification as baseline market access, with FDA and EMA validation protocols compressing equipment replacement cycles. German and Swiss OEMs anchor supply for European formulation networks.
- Cosmetics:Mineral sunscreen and color pigment micronization requires sub-10 micron distributions without agglomeration. Formulation trends in South Korea and Japan are accelerating equipment deployment for zinc oxide processing. Pharmaceuticals leads on revenue concentration; Cosmetics leads on expansion velocity.
- Chemical Processing:Specialty synthesis applications leverage jet milling for consistent particle engineering in catalyst and pigment production.
- Mineral Processing:Abrasive material grinding favors wear-resistant ceramic chamber designs from specialized Japanese suppliers.
- Food Production:Flavor encapsulation and nutraceutical milling operate under FSSAI and FDA food safety frameworks with lower purity thresholds than pharmaceutical segments.
Pharmaceuticals leads on scale; Cosmetics leads on momentum.
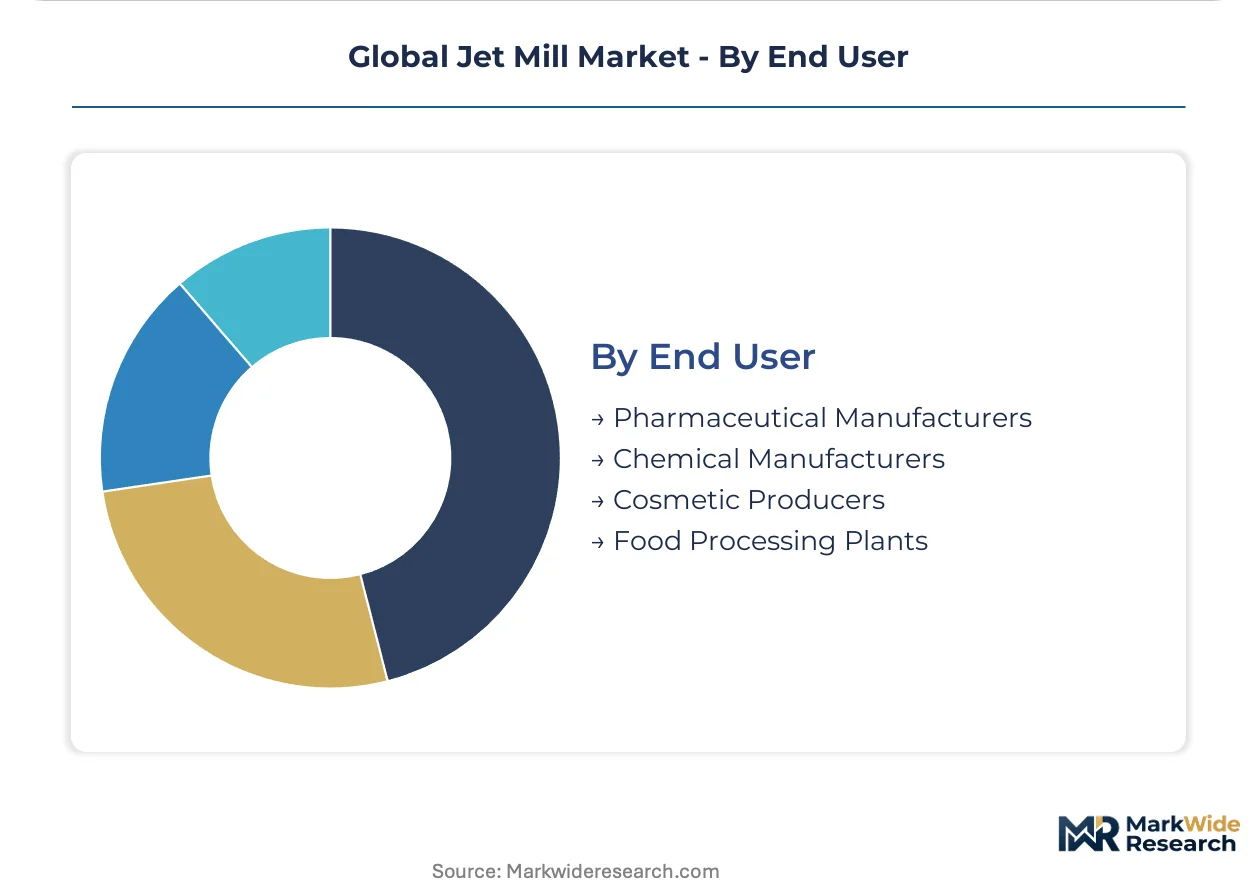
End User:
Procurement sophistication and service contracting fragmentation vary across consolidated pharmaceutical multinationals versus fragmented cosmetic compounders.
- Pharmaceutical Manufacturers:Centralized corporate purchasing drives vendor rationalization and unbundled performance guarantees separating spare parts logistics from technical support. North American facilities lead this contracting evolution.
- Chemical Manufacturers:Process analytical technology integration demands favor continuous configurations in new facility design, particularly for battery cathode precursor programs. Pharmaceutical Manufacturers leads on contract value; Chemical Manufacturers leads on technology adoption speed.
- Cosmetic Producers:Campaign manufacturing flexibility and rapid formulation changeover prioritize batch-type configurations with modular cleaning protocols.
- Food Processing Plants:Sanitary design requirements and allergen control protocols constrain equipment material selection without imposing pharmaceutical-grade documentation burdens.
Pharmaceutical Manufacturers leads on scale; Chemical Manufacturers leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision engineering clusters anchor jet mill deployment across pharmaceutical and chemical processing networks. FDA and EMA validation protocols compress equipment replacement cycles in developed markets. CDSCO-aligned regulatory harmonization accelerates capital deployment in emerging manufacturing hubs.
United States
Pharmaceutical manufacturers in New Jersey and North Carolina retrofit milling infrastructure to meet FDA process validation guidelines. EPA emission thresholds constrain lubricant and seal material selections in equipment design. Greater Boston's biotech corridor drives demand for containment-optimized closed-type configurations.
Germany
API micronization mandates under EU MDR conformity requirements elevate purity thresholds for fine particle production. REACH authorization procedures force reformulation of bearing assemblies to eliminate Substances of Very High Concern. Baden-Württemberg's precision engineering clusters dominate fabrication of containment-optimized systems.
India
CDSCO alignment with ICH guidelines accelerates domestic API manufacturing capacity expansion. Multinational pharmaceutical subsidiaries drive replacement demand for certified micronization systems. Maharashtra's pharmaceutical manufacturing belt attracts equipment assembly partnerships from global OEMs.
Japan
Cosmetics formulators in Osaka and Tokyo accelerate deployment for zinc oxide and titanium dioxide micronization. METI standards influence equipment specification for battery materials processing programs. Kansai region's specialty chemical producers pioneer solid-state battery cathode precursor applications.
China
Battery materials processing for lithium-ion cathode precursors represents an emerging application segment. NMPA pharmaceutical guidelines shape equipment qualification protocols for domestic API producers. Yangtze River Delta chemical parks integrate continuous-type configurations under process analytical technology mandates.
Global Jet Mill Market Competitive Landscape
Global majors compete with regional champions across certification depth and service proximity. The supplier base organizes around three tiers: integrated precision engineering conglomerates with full vertical scope, specialized fluid energy technology licensors, and regional fabricators serving price-sensitive mineral processing segments. Consolidation pressure intensifies as pharmaceutical procurement teams rationalize vendor panels and unbundle performance guarantees from spare parts logistics.
Within the precision engineering tier, Erich NETZSCH GmbH & Co. Holding KG and Hosokawa Micron Corporation exemplify archetypes of European and Japanese manufacturing heritage respectively. Kunshan Unique Machinery Co. Ltd. occupies a position among Asia-based fabricators addressing localized pharmaceutical expansion. The Jet Pulverizer Company, Inc. represents the specialist model focused on custom micronization services for niche pharmaceutical contracts.
| Leading Market Players |
|---|
| Loesche GmbH |
| Kunshan Unique Machinery Co. Ltd. |
| Erich NETZSCH GmbH & Co. Holding KG |
| Promas Engineers Private Limited |
| Kurimoto Ltd. |
| Fluid Energy Group |
| FREUND Corporation |
| The Jet Pulverizer Company, Inc. |
| Hosokawa Micron Corporation |
| Others |
Supply & Pricing Matrix
Captive in-house production of precision nozzles and ceramic grinding chambers anchors supply positioning for German and Japanese OEMs while insulating them from nitrogen cost volatility and energy price swings that erode margin pools for outsourced fabricators.
Pricing Analysis
Input-cost pass-through from high-purity nitrogen and compressed air systems runs directly into equipment pricing tiers, with pharmaceutical-grade fluid energy systems commanding premium positioning against mineral-processing configurations. Price differentiation hinges on FDA validation documentation depth and ISO 9001 certification tier, with unbundled service contracting compressing margins for aftermarket-dependent suppliers. Pricing pressure stems from CDSCO-aligned Indian facilities demanding localized assembly partnerships at reduced cost points. Chemical manufacturers and mineral processors exhibit highest price sensitivity; pharmaceutical OEMs prioritize validation certainty over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from FDA and EMA procurement teams mandate qualified secondary suppliers for precision nozzles, forcing equipment manufacturers to maintain relationships across Japanese ceramic specialists and German precision engineering clusters. Geographic supply concentration centers on Germany, Japan, and China for critical components including fluoropolymer-free bearing assemblies and containment-optimized chamber designs. Raw material dependencies include technical ceramics, high-grade stainless alloys, and REACH-compliant seal formulations. Single-source vulnerability threatens lead time reliability for proprietary nozzle geometries. Distribution runs through direct OEM sales for pharmaceutical validation segments and regional distributor networks for mineral processing applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory demand through EU MDR conformity deadlines and FDA process validation protocols that compress equipment replacement cycles across active ingredient production networks.
For Market Incumbents: Deploy patent-protected nozzle geometry licensing to defend margin pools against emerging fluid energy technology licensors. Deepen backward integration into ceramic grinding chamber fabrication to preempt supply disruption from Japanese specialist concentration. Fortify cGMP documentation capabilities as CDSCO-aligned Indian facilities accelerate qualification requirements.
For New Entrants and Emerging Players: Enter via battery materials processing partnerships with solid-state battery R&D programs in Japan and China, where cathode precursor micronization specifications remain unsettled. Target cosmetics pigment micronization in South Korea and Japan as the most penetrable segment given formulation trend velocity. Pursue unbundled performance guarantee contracting to bypass incumbent spare parts logistics dominance.
For Investors and Strategic Acquirers: Consolidation pressure builds where vendor rationalization programs fragment service contracting and compress standalone aftermarket profitability. Long-term viability favors precision engineering conglomerates with captive ceramic fabrication and multi-regional certification depth. Acquisition target archetype: specialized fluid energy licensors with proprietary classification chamber IP. Signal to watch: CDSCO enforcement intensity against non-certified equipment in Maharashtra's pharmaceutical belt.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Investment | FDA process validation documentation secures replacement cycle capture from EMA-aligned European facilities. |
| Backward Integration into Ceramics | In-house grinding chamber production insulates against Japanese supplier lead time volatility. |
| Continuous Manufacturing Partnership | PAT-integrated configurations align with FDA incentives for pharmaceutical facility greenfield design. |
| Battery Materials Application Development | Cathode precursor micronization opens lithium-ion and solid-state battery supply chain positioning. |
| Fluoropolymer-Free Design Transition | REACH-compliant bearing assemblies preempt regulatory discontinuation of perfluorinated compounds. |
Research Methodology
Direct dialogue with pharmaceutical process engineers, equipment procurement managers at API manufacturers, aftermarket service directors, and regulatory affairs specialists grounded qualitative findings in operational constraints. Secondary validation drew from FDA guidance documents, EMA conformity assessment procedures, CDSCO circulars on ICH harmonization, and REACH authorization candidate lists. Bottom-up triangulation against customs trade data for precision milling equipment and top-down reconciliation with pharmaceutical capital expenditure disclosures ensured cross-verification.
Bottom-up modeling segmented volume and value across product type, technology, application, and end-user dimensions, with additional stratification by regional regulatory cluster and certification tier. CAGRs were derived from equipment replacement cycle compression rates and greenfield facility deployment pipelines. Forecast inputs incorporated nitrogen pricing volatility indices, battery materials R&D program announcements, and cosmetics formulation patent filings for mineral sunscreen applications.
Inputs from pharmaceutical OEM procurement teams and precision engineering supplier technical documentation were available through the study window; gaps in real-time CDSCO enforcement data and solid-state battery commercialization timelines introduce uncertainty bands around emerging application projections. Deviation in EU MDR implementation strictness or REACH authorization acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Elastomeric Couplings Market
Industrial Materials
Gravity Die Casting Market
Industrial Materials
Shock Mat Market
Industrial Materials
Pultrusion Products Market
Industrial Materials
Global Cenospheres Market
Industrial Materials
Stainless Steel Cable Ties Market
Industrial Materials
Flat Enameled Wires Market
Industrial Materials
Extruders and Compounding Machines Market
Industrial Materials
Middle East Activated Carbon Market
Industrial Materials
Mesh Nozzle Plates Market
Industrial Materials
Plastic Compounding Machinery Market
Industrial Materials
Saudi Arabia Industrial Insulation Market
Industrial Materials
Plastic Gears Market
Industrial Materials
2-in-1 Material Rack Correction Machine Market
Industrial Materials
Compression Gas Spring Market
Industrial Materials
Europe Wood Activated Carbon Market