
 Diamond Tester Market | 2026-2036
Diamond Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Diamond Tester Market Insights
Pawn shops and secondhand dealers are redrawing demand patterns for diamond testers as resale channels multiply and consumer wariness about lab-grown stones intensifies. Presidium leverages its established brand strength in handheld thermal conductivity devices to anchor North American distribution. Gemlogis competes through spectroscopy-based platforms that target laboratory-grade precision. Sykessler specializes in compact units engineered for high-volume retail counters, sustaining its position in Asian markets.
A diamond tester is an electronic or optical instrument that measures thermal conductivity, electrical conductivity, or spectroscopic signatures to distinguish natural diamonds from simulants and synthetics, typically operating at resolutions of one to three millimeters probe tip diameter and calibrated against reference standards traceable to gemological institutes. Portable testers command the broadest installed base among product types due to their deployment flexibility across jewelry showrooms and trade events, while spectroscopy-based systems capture premium margin pools by serving grading laboratories that require definitive origin determination. Multi-functional testers that combine thermal and electrical measurement are gaining fastest in pawn shop and secondary market applications where single-parameter devices risk false positives against moissanite.
The United States Federal Trade Commission enforces strict gemstone marketing disclosures that elevate tester accuracy requirements, while ISO 17025 accreditation standards for gemological laboratories mandate traceable calibration protocols that shape equipment procurement criteria. India's Bureau of Indian Standards has introduced conformity assessment pathways for testing instruments used in export-oriented diamond processing, tightening market access for uncertified devices. Stakeholders must weigh spectroscopy investment against thermal conductivity refresh cycles as synthetic diamond production techniques advance detection complexity.
Market Dynamics
Synthetic diamond production techniques, particularly chemical vapor deposition, have outpaced thermal conductivity detection capabilities, forcing equipment manufacturers toward spectroscopy-based platforms that can definitively distinguish lab-grown stones from natural origin.
Growth Catalysts
- FTC disclosure enforcement:The United States Federal Trade Commission mandates strict gemstone marketing standards that compel retailers to invest in certified verification equipment. Jewelry showrooms across California and Texas upgrade testing protocols to avoid penalties.
- Surat processing cluster throughput:India's diamond cutting and polishing hub requires mass-scale verification infrastructure to handle export volumes. Processing centers deploy multi-station testing arrays to maintain throughput.
- Moissanite thermal signature overlap:Simulant materials generate false positives on single-parameter devices, driving replacement demand for dual-measurement testers. Pawn shops in Florida and Illinois lead this refresh cycle.
Market Restraints
- Spectroscopy component concentration:High-precision optical sensors concentrate among Japanese and German suppliers, exposing equipment manufacturers to input cost volatility and supply disruption risks.
- ISO 17025 calibration mandates:Gemological laboratories must maintain traceable reference standards, creating ongoing compliance overhead that slows procurement cycles for smaller testing facilities.
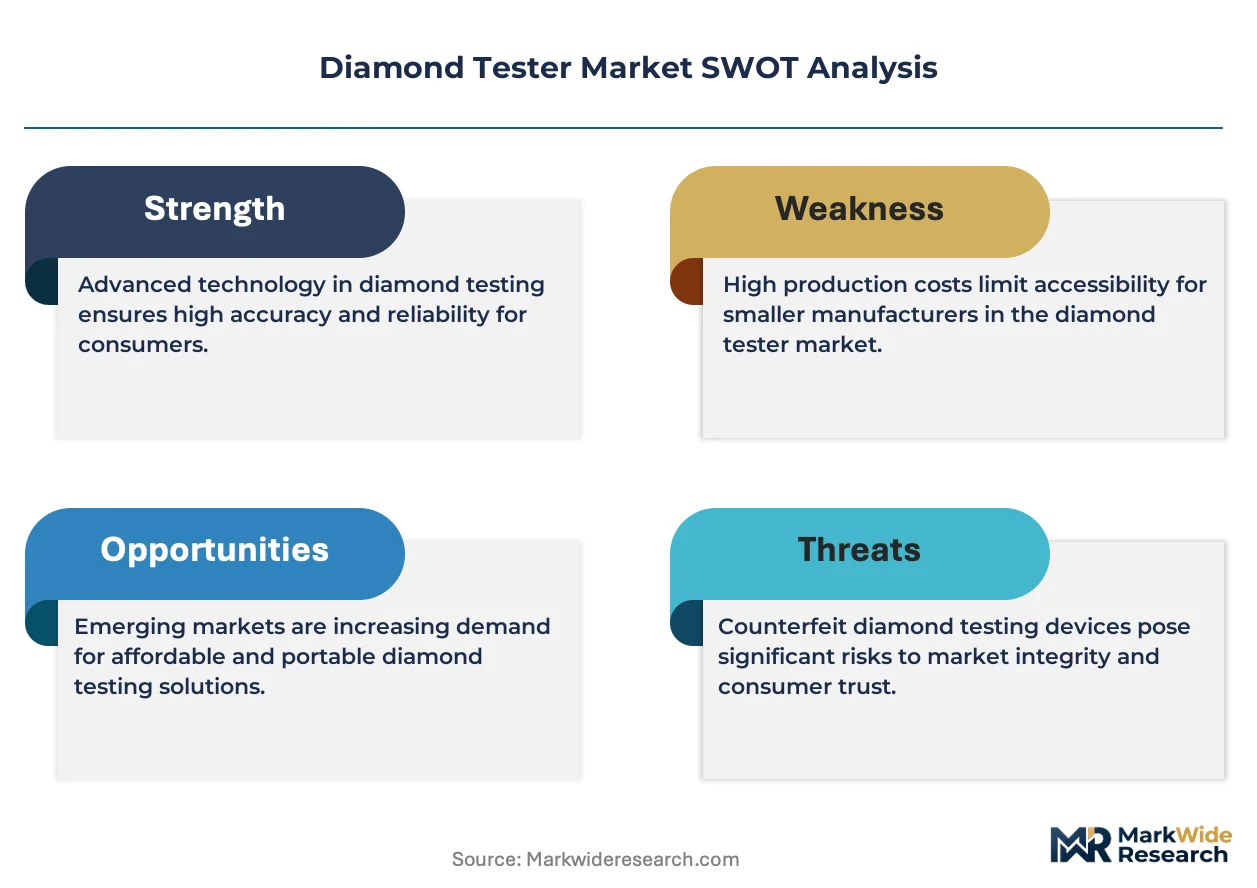
- Secondhand channel substitution:Consumer-to-consumer gemstone resale platforms bypass professional verification entirely, capping addressable market expansion in the pre-owned jewelry segment.
Strategic Opportunities
- Brazilian retail formalization:São Paulo's jewelry district lacks standardized testing infrastructure, creating first-mover advantage for portable device distributors targeting independent retailers.
- Blockchain origin certification convergence:Integration of spectroscopic data with distributed ledger systems enables immutable provenance records. Luxury brands pilot this pairing for high-value inventory.
- United Arab Emirates free zone incentives:Dubai's designated trading zones offer tariff exemptions for precision testing equipment, reducing landed cost for distributors serving Middle Eastern markets.
Industry Challenges
- Spectroscopy technician scarcity:Operation of laboratory-grade systems requires specialized training in photoluminescence interpretation. Certification programs at GIA and similar institutes face enrollment bottlenecks.
- Legacy thermal device stranded asset risk:Retailers holding single-parameter inventories face write-downs as CVD diamond detection failures damage credibility. Equipment financing complicates refresh decisions.
- Cross-border calibration traceability:National metrology institutes in India, the United States, and Belgium maintain divergent reference protocols, complicating multinational laboratory accreditation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diamond Tester Market |
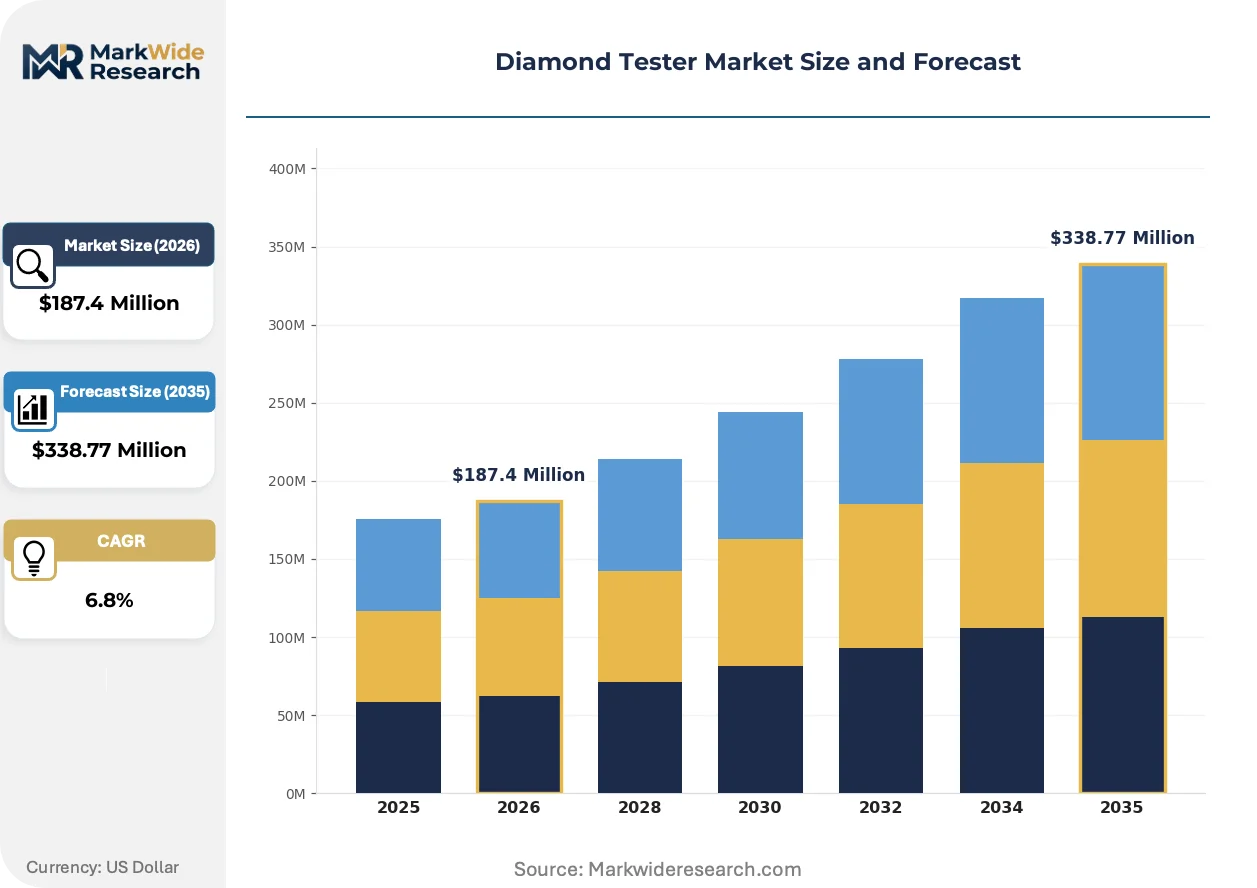
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Testers, Desktop Testers, Multi-Functional Testers, High-End Testers End User: Jewelry Retailers, Gemologists, Laboratories, Pawn Shops Technology: Electrical Conductivity, Thermal Conductivity, UV Fluorescence, Spectroscopy Application: Quality Inspection, Fraud Detection, Grading, Verification |
| Companies Covered | Presidium, Gemlogis, GemOro Superior Instruments, SmartPro, TRI, Sykessler, PCE, RS Mizar, HDE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diamond Tester Market Trends and Innovations
Detection technology is fragmenting into two distinct performance tiers as synthetic diamond sophistication accelerates, separating portable retail tools from laboratory-grade origin determination systems.
Spectroscopic platforms utilizing photoluminescence and infrared absorption is bifurcating the equipment landscape. Grading laboratories in Antwerp and Mumbai adopt these systems to meet insurer requirements for definitive synthetic-natural discrimination. The technology is bifurcating margin pools, compressing returns on thermal conductivity devices while concentrating premium pricing power among spectroscopy specialists serving certification-heavy channels.
India's Bureau of Indian Standards has introduced conformity assessment pathways for export-oriented testing instruments. Equipment lacking BIS certification faces exclusion from government-supported processing facilities. Surat-based exporters now prioritize certified device procurement to maintain access to preferential financing schemes, reshaping vendor selection criteria toward compliance-documented suppliers.
Secondary market buyers now demand independent verification before completing transactions, unbundling testing from traditional retail purchase. Pawn shops in Chicago and Houston build verification fees into lending structures, while online resale platforms partner with regional gemologists for escrow-based testing. This pattern concentrates most visibly in the United States, where consumer wariness about undisclosed synthetics drives explicit testing clauses in private sales contracts.
Diamond Tester Market Segmentation
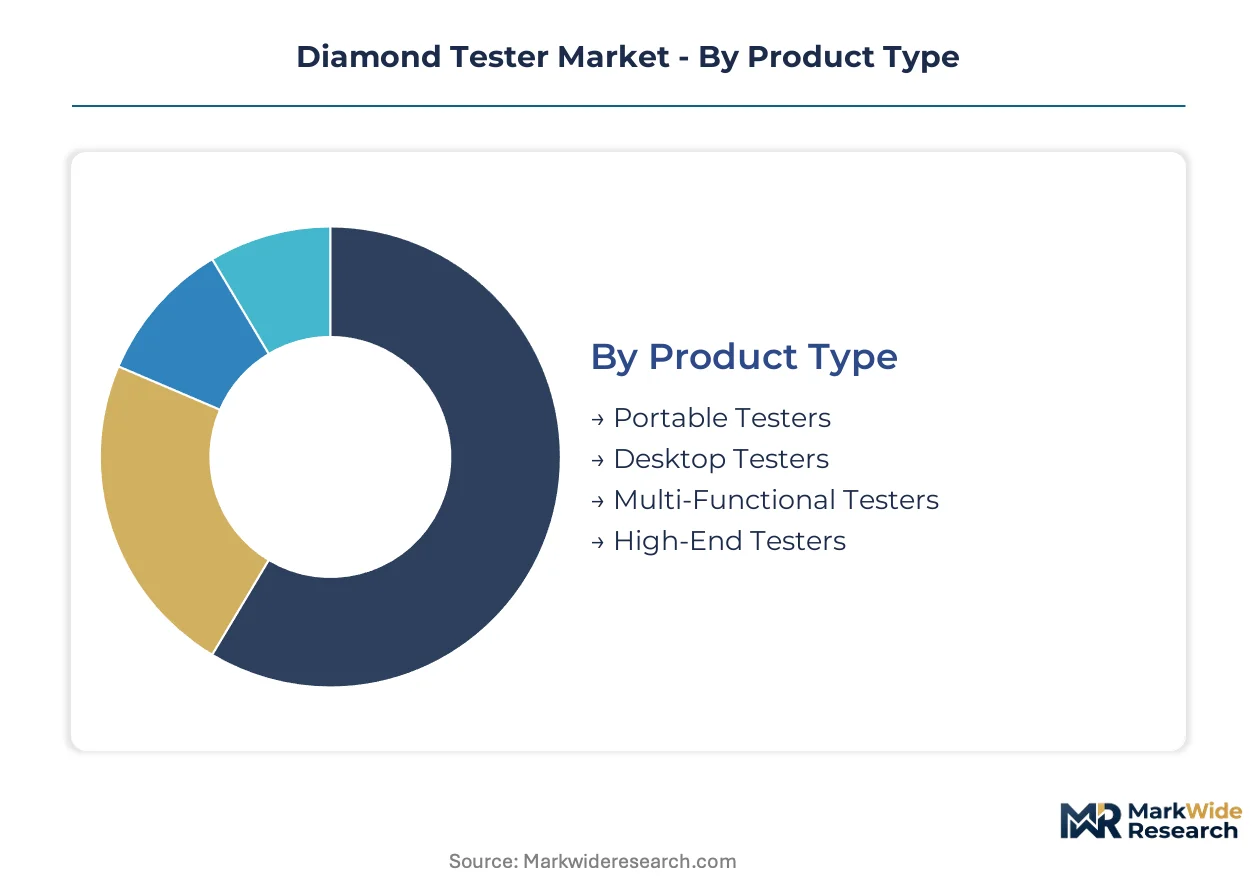
Equipment differentiation in diamond testing follows divergent detection requirements across retail floors, grading laboratories, and secondary market channels. Substitution threats from synthetic diamond production techniques reshape which product configurations retain commercial viability.
Product Type:
Portable testers face the most acute substitution pressure as single-parameter thermal devices fail against chemical vapor deposition synthetics, while spectroscopy-integrated platforms command defensive positioning.
- Portable Testers:Handheld units measuring 150-300 grams deploy thermal or electrical conductivity probes for rapid field verification. Jewelry showrooms in Surat and Mumbai favor these for customer-facing screening despite mounting false-positive risks against moissanite.
- Multi-Functional Testers:Combined thermal-electrical measurement architectures address simulant detection gaps that plague single-parameter devices. Pawn shops across Florida and Texas drive replacement demand as dual-measurement units become minimum viable for collateral valuation.
- Desktop Testers:Stationary units with expanded probe arrays serve medium-volume processing centers requiring throughput without laboratory-grade capital expenditure.
- High-End Testers:Spectroscopy-integrated systems with photoluminescence capabilities target certification laboratories serving insurer-mandated origin verification.
Portable testers retain volume leadership; multi-functional testers hold the steepest expansion curve as single-parameter obsolescence accelerates refresh cycles.
End User:
Customer procurement authority concentrates in channels where regulatory disclosure liability creates non-negotiable accuracy requirements.
- Jewelry Retailers:FTC disclosure enforcement in the United States compels showroom investment in certified verification equipment. California and Texas retailers upgrade testing protocols to avoid penalty exposure from undisclosed synthetic sales.
- Pawn Shops:Secondary market lenders integrate testing fees into collateral structures as consumer wariness about lab-grown stones intensifies. Chicago and Houston operators lead adoption of dual-measurement units for moissanite discrimination.
- Gemologists:Independent practitioners require portable precision for trade show and estate appraisal mobility.
- Laboratories:ISO 17025-accredited facilities mandate traceable calibration protocols that shape equipment procurement toward spectroscopy platforms.
Jewelry retailers dominate unit shipments; pawn shops are climbing the fastest as resale channel formalization expands addressable demand.
Technology:
Detection methodology selection tracks synthetic diamond production sophistication, separating adequate retail screening from definitive origin determination.
- Thermal Conductivity:Measures heat dissipation rates through probe contact, historically the dominant portable architecture. Surat cutting centers retain these for rough sorting despite CVD detection failures.
- Spectroscopy:Photoluminescence and infrared absorption platforms serve Antwerp and Mumbai grading laboratories requiring insurer-grade synthetic-natural discrimination. Component concentration among Japanese and German optical sensor suppliers elevates input cost volatility.
- Electrical Conductivity:Distinguishes diamond from moissanite through semiconductor properties, often paired with thermal measurement in multi-functional designs.
- UV Fluorescence:Secondary screening layer detecting characteristic luminescence patterns under ultraviolet excitation.
Thermal conductivity retains installed base dominance; spectroscopy commands the steepest expansion trajectory as certification requirements harden.
Application:
Use case prioritization reflects divergent accuracy thresholds across commercial screening versus forensic documentation.
- Verification:Point-of-sale confirmation of natural origin claims, now requiring dual-measurement minimums in FTC-regulated United States markets. Dubai luxury retailers pilot blockchain-integrated spectroscopic verification for high-value inventory.
- Fraud Detection:Identification of undisclosed synthetics and simulants in secondary market transactions. Online resale platforms partner with regional gemologists for escrow-based testing clauses in private sales contracts.
- Quality Inspection:Rough sorting and manufacturing process control in Surat processing clusters.
- Grading:Certification documentation supporting insurance valuation and export compliance.
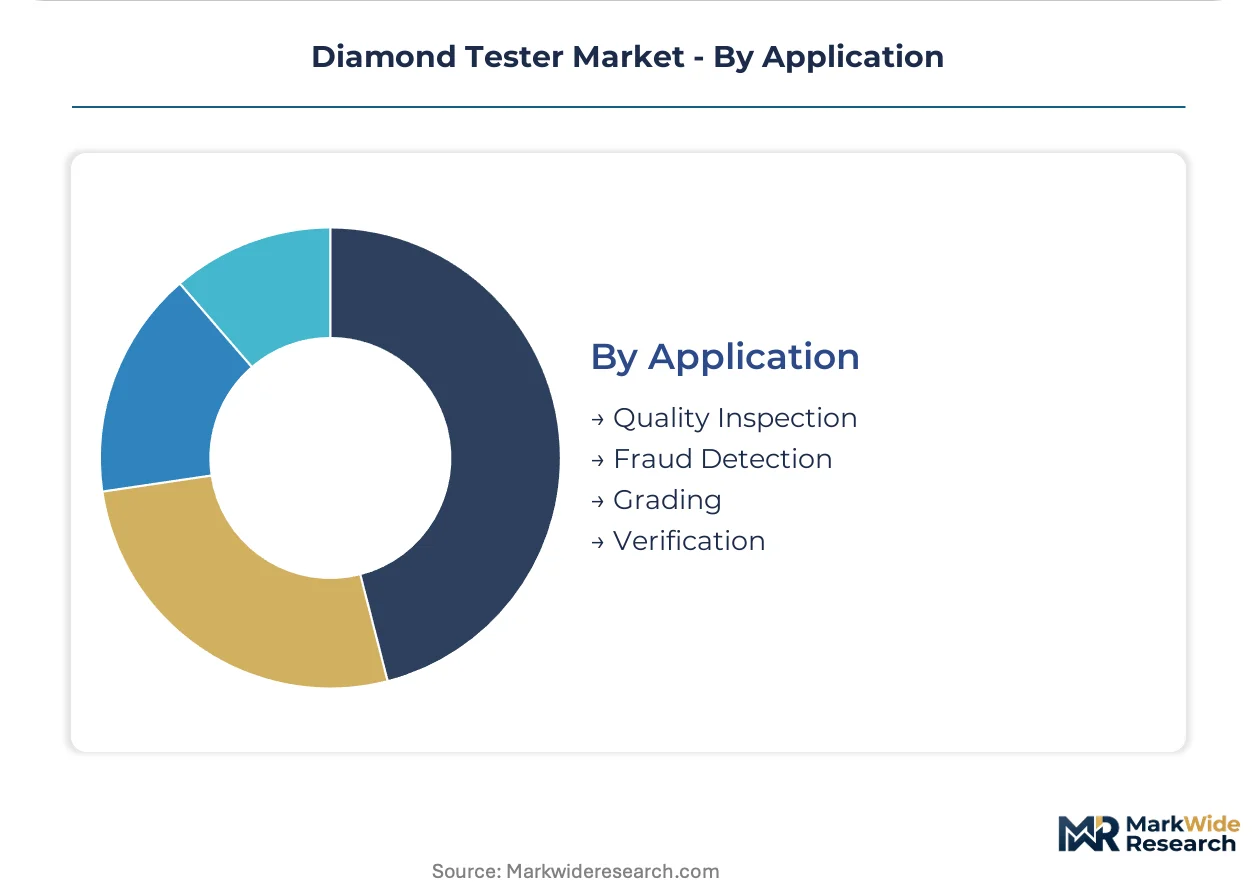
Verification captures the broadest deployment base; fraud detection is gaining share fastest as consumer-to-consumer resale platforms proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Antwerp's diamond trading infrastructure underwrites Belgium's centrality in gemstone certification, while Dubai's Jebel Ali Free Zone enables tariff-efficient equipment distribution across Middle Eastern markets.
United States
FTC disclosure enforcement drives jewelry retailer investment in certified verification equipment. California and Texas showrooms upgrade testing protocols to avoid penalty exposure from undisclosed synthetic sales. Chicago and Houston pawn shops integrate dual-measurement units into collateral valuation workflows.
India
Surat's diamond cutting and polishing cluster requires mass-scale verification infrastructure for export throughput. BIS conformity assessment pathways for testing instruments reshape vendor selection toward compliance-documented suppliers. Processing centers deploy multi-station testing arrays to maintain volume handling capacity.
Belgium
Antwerp grading laboratories adopt spectroscopy-integrated systems for insurer-mandated origin verification. National metrology institutes maintain divergent reference protocols that complicate multinational laboratory accreditation. The city's diamond bourse anchors European demand for laboratory-grade detection equipment.
United Arab Emirates
Dubai's designated trading zones offer tariff exemptions for precision testing equipment, reducing landed cost for regional distributors. Luxury retailers pilot blockchain-integrated spectroscopic verification for high-value inventory. The emirate's gemstone trading infrastructure concentrates Middle Eastern procurement authority.
Brazil
São Paulo's jewelry district lacks standardized testing infrastructure, creating first-mover opportunity for portable device distributors. Independent retailers seek verification capabilities as consumer wariness about undisclosed synthetics intensifies. The country's national gemstone regulator has yet to mandate certification-equivalent disclosure standards.
Diamond Tester Market Competitive Landscape
Concentration sits with established handheld thermal conductivity specialists and emerging spectroscopy platform developers. The vendor base spans three tiers: legacy portable device manufacturers defending installed bases, laboratory-grade system specialists capturing premium margins, and Asian compact unit producers serving high-volume retail counters. Strategic moves center on technology licensing partnerships and geographic distribution expansion into underpenetrated secondary markets.
Within the established portable device tier, Presidium anchors North American distribution through brand recognition in handheld thermal conductivity equipment. Gemlogis occupies a position among spectroscopy-based platform developers targeting laboratory-grade precision requirements. Sykessler exemplifies the compact unit specialization engineered for high-volume retail counter deployment across Asian markets. These three represent distinct archetype positions rather than direct competitive overlap, with each anchoring different performance tiers and geographic emphases.
| Leading Market Players |
|---|
| Presidium |
| Gemlogis |
| GemOro Superior Instruments |
| SmartPro |
| TRI |
| Sykessler |
| PCE |
| RS Mizar |
| HDE |
| Others |
Pricing and Supply Chain Analysis
Ninety-day inventory cycles at Surat processing centers expose equipment manufacturers to demand volatility that concentrates pricing power among Japanese and German optical sensor suppliers. This lead-time compression forces tiered pricing separation between thermal conductivity units and spectroscopy-integrated platforms, with procurement officers accepting premium outlays for certified calibration traceability.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs equipment transactions, with laboratory-grade spectroscopy systems commanding substantial premiums over handheld thermal units. Price differentiation hinges on ISO 17025 certification tier and after-sales calibration service bundling. Pricing pressure stems from CVD synthetic diamond detection failures eroding confidence in single-parameter devices. Pawn shops and independent retailers exhibit acute price sensitivity, while Antwerp grading laboratories prioritize accuracy over unit cost.
Supply Chain Analysis
Japan and Germany anchor high-precision optical sensor fabrication for spectroscopy platforms, while China and Taiwan supply thermal probe assemblies and electronic subassemblies. Component sourcing draws from specialized photonics foundries, rare-earth optical materials, and semiconductor-grade silicon detectors. Single-source vulnerability concentrates in photoluminescence sensor supply, with tariff exposure elevating landed costs for European and North American equipment assemblers. Distribution runs through authorized gemological equipment distributors serving regional laboratory networks and retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of trained spectroscopy technicians capable of photoluminescence interpretation constrains laboratory capacity expansion and elevates service pricing, creating defensive moats for incumbent equipment vendors with embedded training ecosystems.
For Market Incumbents: Shield installed base value by accelerating dual-measurement tester refresh programs before CVD detection failures trigger credibility damage. Secure backward integration into calibration reference standards to reduce dependency on national metrology institutes. Vertical control over traceable certification protocols preserves margin position against low-cost Asian competitors. For New Entrants and Emerging Players: Lead with portable spectroscopy miniaturization targeting São Paulo's informal jewelry district, where standardized testing infrastructure remains absent. Brazil's regulatory vacuum offers first-mover positioning before ANVISA or comparable bodies mandate disclosure-equivalent standards. Partner with regional gemological associations for channel credibility rather than competing on unit economics alone. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because FTC enforcement and BIS certification pathways institutionalize recurring equipment refresh demand. Target acquisition profiles favor spectroscopy platform developers with existing ISO 17025 documentation and established relationships with Antwerp or Mumbai grading laboratories. Watch enrollment bottlenecks at GIA certification programs as the signal indicating technician scarcity intensity and service revenue expansion potential.| Strategic Initiative | Industry Significance |
|---|---|
| Spectroscopy Platform Miniaturization | Shrinks laboratory-grade accuracy into portable form factors for retail deployment. |
| Calibration Service Subscription Model | Generates recurring revenue streams from ISO 17025 traceability requirements. |
| BIS Certification Pre-Positioning | Secures access to Indian government-supported processing facility procurement. |
| Blockchain Verification Integration | Enables immutable provenance records for Dubai luxury retailer pilot programs. |
| Technician Certification Program Partnership | Captures scarcity rent from GIA enrollment bottlenecks limiting laboratory capacity. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and gemological institute certification records. Primary interviews engaged equipment procurement managers at Surat processing centers, laboratory directors at Antwerp grading facilities, pawn shop operators in Chicago and Houston, and optical sensor procurement leads at Japanese component manufacturers. Secondary sources encompassed BIS conformity assessment documentation, FTC enforcement actions, ISO 17025 accreditation registries, and import-export statistics from diamond trading hubs. Bottom-up demand modeling triangulated against top-down market sizing from equipment shipment aggregations.
Segmentation dimensions modeled span product type, end-user channel, detection technology, and application use case across the projection horizon. Analytical framework incorporated equipment replacement cycles driven by synthetic diamond production technique evolution, regulatory disclosure mandate expansion, and secondary market formalization patterns. CAGRs derived from installed base growth, refresh rate acceleration, and average selling price trajectories by performance tier. Industry-specific inputs included CVD synthetic diamond penetration rates and spectroscopy component cost curves.
The analysis sits within stated boundaries; outcomes outside sustained FTC enforcement intensity, BIS certification pathway durability, or CVD detection capability advancement would require recalibration. Forecasts reflect assumptions regarding technician training pipeline expansion, optical sensor supply stability, and secondary market platform verification clause adoption. Recalibration cycles align with material shifts in synthetic diamond production sophistication, national disclosure regulation amendments, and metrology institute protocol harmonization initiatives.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Leak Testing Machine Market
Test and Measurement
Power Semiconductor Wafer-Level Reliability Test Equipment Market
Test and Measurement
Modular Test Equipment Market
Test and Measurement
In-Process Composite Layup Monitoring Sensors and Test Equipment Market
Test and Measurement
Fiber Optic Tester Market
Test and Measurement
Cooling Laser Power Measurement Sphere Market
Test and Measurement
Impedance Tester Market
Test and Measurement
Pump Testers Market
Test and Measurement
EMC Testing Market
Test and Measurement
Asia-Pacific Nondestructive Testing Equipment Market
Test and Measurement
Global Leak Test Equipment Market
Test and Measurement
Gigabit Ethernet Test Equipment Market
Test and Measurement
Europe Nondestructive Testing Equipment Market
Test and Measurement
IoT Testing Equipment Market
Test and Measurement
Telescopic Inspection Mirror Market
Test and Measurement
Product Design Verification and Validation Solution Market