
 United States Blueberry Market | 2026-2036
United States Blueberry Market Size, Share, and Industry Trends Forecast 2026-2036
United States Blueberry Market Analytics
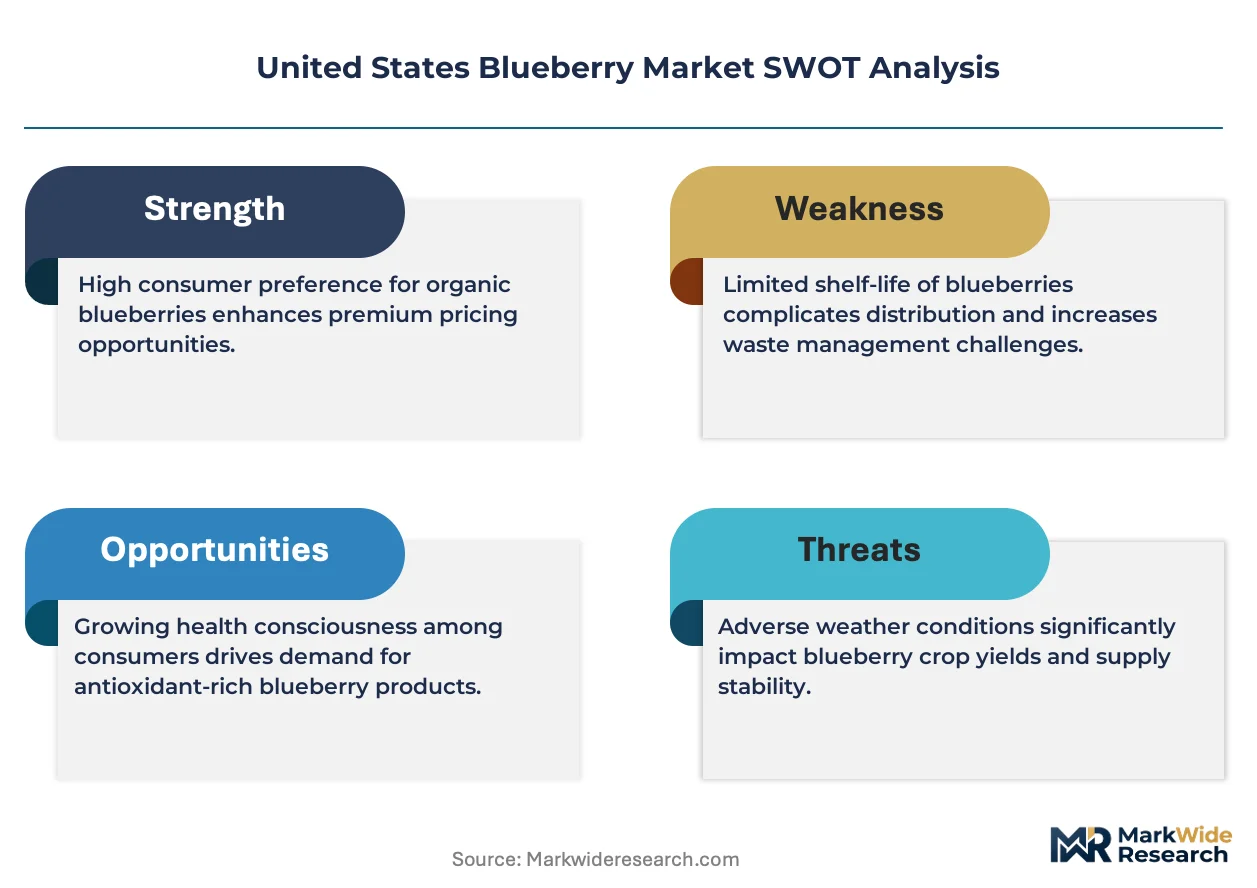
USDA Organic certification is bifurcating the United States blueberry supply base into qualified and non-qualified growers. Driscoll's Inc. leverages its integrated breeding-to-retail platform to dominate branded fresh berry shelf space. Naturipe Farms LLC anchors cooperative volume across multiple growing states. Camposol S.A. competes through counter-seasonal Peruvian supply that extends year-round availability.
Blueberries are deciduous perennial berries of the genus Vaccinium section Cyanococcus, typically harvested at 12-16% soluble solids and flash-cooled to 0-2°C within four hours of picking to preserve anthocyanin content and shelf stability; they serve food manufacturing, foodservice, and retail channels as antioxidant-rich ingredients and standalone produce. Fresh blueberries generate the highest per-unit margins but face compressed windows, while frozen blueberries capture institutional demand from food processing buyers seeking standardized brix and year-round supply. Dried blueberries and juice occupy smaller volume positions but command premium placement in health-oriented retail and beverage formulations.
The USDA Agricultural Marketing Service administers grade standards that condition wholesale pricing and export eligibility, while the FDA enforces Food Safety Modernization Act rules governing preventive controls for fresh and minimally processed fruit. State departments of agriculture in Oregon, Washington, and Georgia implement additional inspection protocols for pesticide residues and cooling chain verification. Stakeholders must monitor evolving FSMA traceability requirements and water quality regulations that will determine which growing regions maintain cost-competitive compliance.
Market Dynamics
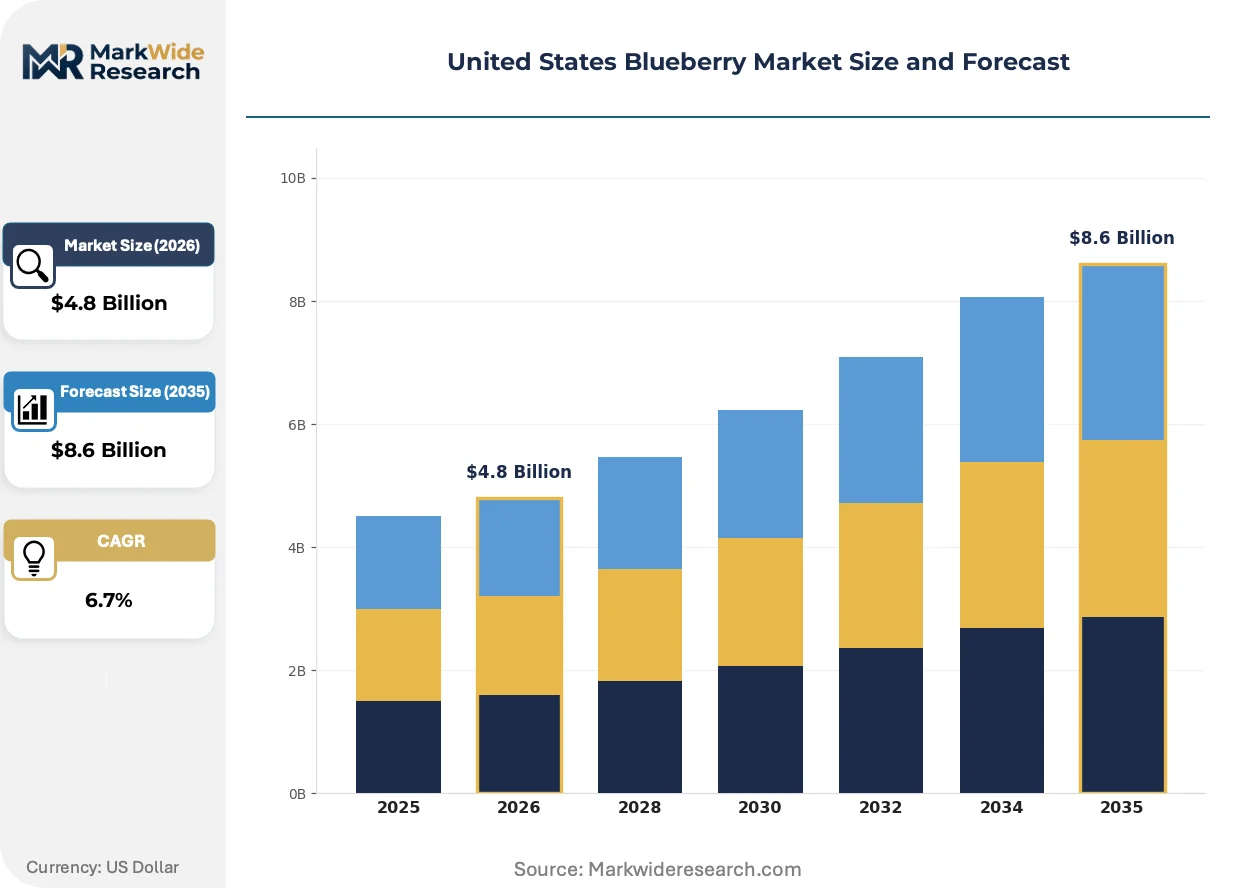
USDA Organic certification requirements are restructuring planting decisions across Pacific Northwest and Southeast growing zones, creating qualified and non-qualified supply tiers that reshape competitive positioning in fresh and processed channels.
Growth Catalysts
- Controlled-environment agriculture:Precision irrigation and substrate systems in Oregon's Willamette Valley expand viable acreage beyond traditional soil-based cultivation.
- FDA Food Safety Modernization Act:Preventive controls mandates institutionalize food safety investments that lock in large-scale processor contracts for compliant growers.
- Food manufacturing demand:Cereal, snack bar, and baked goods producers absorb rising frozen and dried blueberry volumes for year-round formulation flexibility.
Market Restraints
- Labor cost volatility:Hand-harvesting requirements for fresh market grades expose operations to H-2A visa program uncertainty and wage inflation.
- Water rights concentration:California's Central Valley growers face allocation cuts from state water project curtailments that restrict expansion.
- Peruvian counter-seasonal supply:Camposol S.A. and Peruvian competitors compress domestic fresh pricing windows during October-March import surges.
Strategic Opportunities
- Controlled-atmosphere storage technology:Post-harvest infrastructure investments extend fresh market windows by 6-8 weeks for premium retail placement.
- USDA Organic certification gap:Southeast growing zones retain underpenetrated organic acreage relative to Pacific Northwest saturation.
- Direct-to-foodservice channels:Restaurant and institutional buyers bypass traditional wholesale layers for traceable volume commitments.
Industry Challenges
- Anthocyanin preservation protocols:Flash-cooling to 0-2°C within four hours requires capital-intensive field infrastructure that small operations struggle to deploy.
- FSMA traceability compliance:FDA record-keeping mandates for lot tracking impose system integration costs across fragmented grower networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Blueberry Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Blueberries, Frozen Blueberries, Dried Blueberries, Juice Distribution Channel: Supermarkets, Direct-to-Consumer, Online Retail, Wholesale End User: Food Processing, Bakeries, Restaurants, Households Packaging Type: Clamshells, Bulk Containers, Pouches, Cans |
| Companies Covered | Fruitist, Camposol S.A., Driscoll's Inc., Complejo Agroindustrial Beta S.A., Hortifrut Peru SAC, Naturipe Farms LLC, AMFRESH, Agrovision Peru SAC, Agroberries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Blueberry Market Evolving Landscape
Precision agriculture and post-harvest technologies are restructuring how blueberries move from field to shelf, with certification requirements and channel specialization driving divergence in operational models.
Machine vision sorting systems paired with near-infrared spectroscopy are bifurcating packhouse operations into high-throughput automated facilities and manual specialty-grade lines. Large fresh-market shippers deploy optical sorters for defect detection and brix measurement, while smaller organic handlers retain hand-grading for premium berry certification. This technology divergence is compressing mid-scale operations that lack capital for automation or niche positioning.
The FDA Food Safety Modernization Act Section 204 traceability rule imposes lot-level tracking from farm to retail, forcing packers to retrofit legacy inventory systems with interoperable data standards. Compliance deadlines are compressing investment timelines for operations supplying Walmart, Kroger, and institutional foodservice accounts. Washington State Department of Agriculture inspection protocols now align with federal requirements, reducing audit duplication for Columbia Basin exporters.
Retail buyer consolidation toward club stores and e-commerce fulfillment centers is reshaping packaging and palletization standards. Costco and Amazon Fresh specifications for traceable case counts and temperature-logged shipments displace traditional wholesale lot sizes. California's Central Valley shippers have reconfigured box dimensions and cooling protocols to match these requirements, while Southeast growers lag in format adaptation.
United States Blueberry Market Segmentation
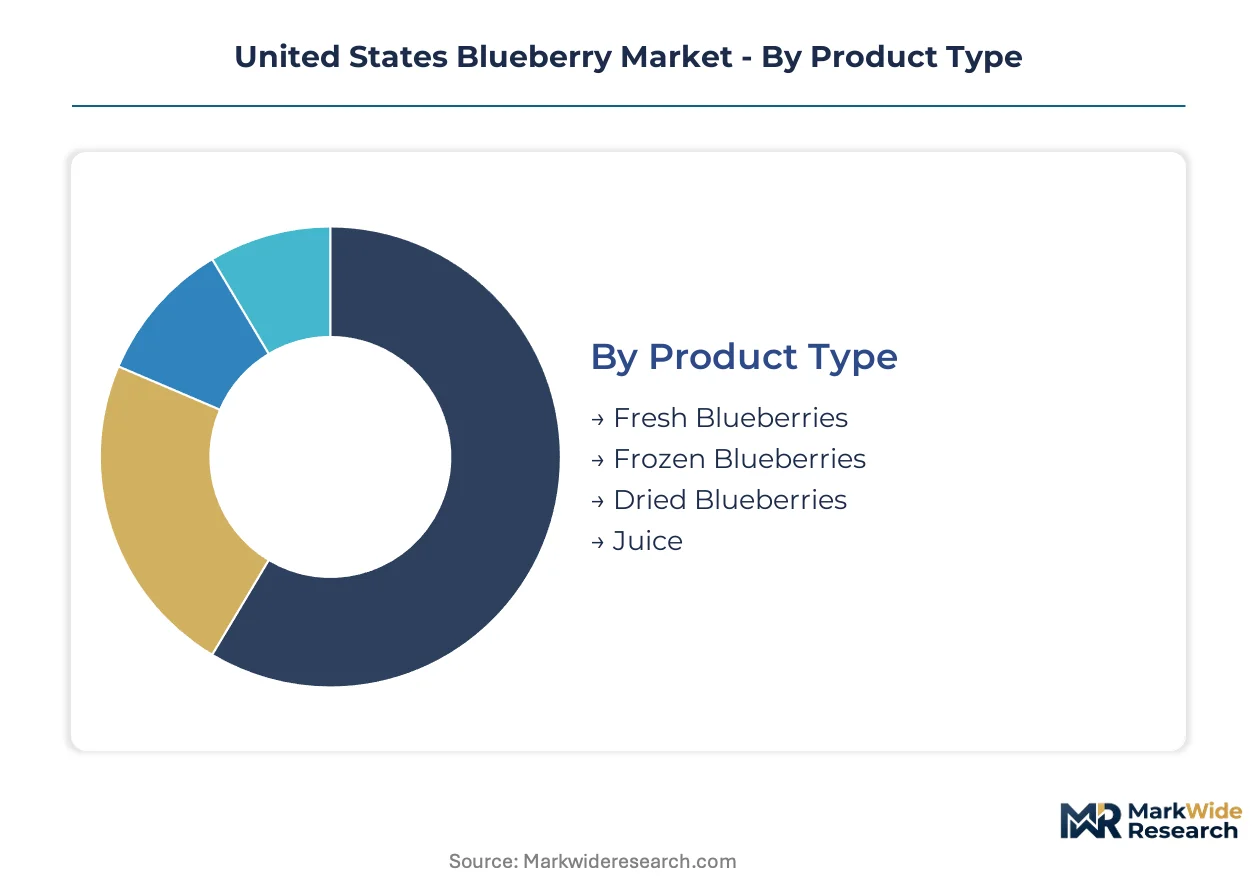
Channel and form factor choices in the United States blueberry market determine margin capture, shelf-life economics, and compliance burden. Each segmentation axis reveals divergent cost structures and customer concentration patterns that reshape competitive positioning.
Product Type:
Margin pools concentrate in fresh formats where per-unit premiums offset harvest labor intensity and cooling infrastructure costs.
- Fresh Blueberries:Harvested at 12-16% soluble solids and flash-cooled to 0-2°C within four hours to preserve anthocyanin content. California's Central Valley and Oregon's Willamette Valley shippers dominate retail placement, though compressed seasonal windows expose pricing to Peruvian counter-seasonal imports.
- Frozen Blueberries:Individually quick-frozen for year-round supply standardization. Food processing facilities in cereal, snack bar, and baked goods segments absorb rising volumes seeking formulation flexibility and consistent brix specifications.
- Dried Blueberries:Dehydrated formats command premium placement in health-oriented retail channels with extended shelf stability reducing cold chain dependency.
- Juice:Beverage formulations occupy smaller volume positions with concentration in antioxidant-focused functional drink segments.
The dominant share belongs to Fresh Blueberries, while Frozen Blueberries is closing the gap fastest as manufacturing demand institutionalizes.
Distribution Channel:
Channel selection dictates traceability investment requirements and palletization standards under evolving FDA Food Safety Modernization Act mandates.
- Supermarkets:Traditional retail absorbs the largest volume flow with standardized case counts and temperature-logged shipments. Kroger and Walmart specifications now require lot-level tracking compliance that filters supplier eligibility.
- Direct-to-Consumer:Farm subscription models and farmers market channels bypass wholesale layers, capturing margin premiums through traceability narratives and regional provenance claims.
- Online Retail:Amazon Fresh and e-commerce fulfillment centers impose packaging reconfigurations with specific box dimensions and cooling protocols that Southeast growers lag in adopting.
- Wholesale:Traditional foodservice distributors face compression as restaurant and institutional buyers pursue direct volume commitments for traceable supply.
Supermarkets retain the volume anchor position, though Online Retail is expanding most quickly as fulfillment infrastructure matures.
End User:
End-use concentration shapes harvest timing decisions and grade standard compliance across USDA Agricultural Marketing Service protocols.
- Food Processing:Cereal manufacturers, snack bar producers, and baked goods facilities demand frozen and dried formats with standardized brix and moisture specifications for year-round formulation.
- Bakeries:Regional and national bakery chains source both fresh and frozen blueberries with specific size grading for uniform distribution in muffin and pastry applications.
- Restaurants:Foodservice operators increasingly bypass wholesale tiers for direct grower relationships requiring FSMA-compliant lot tracking and cooling chain verification.
- Households:Retail consumers drive fresh market premiums with quality sensitivity to firmness, bloom retention, and packaging presentation in clamshell formats.
Food Processing commands the largest volume absorption, while Restaurants is gaining share fastest through direct procurement channel development.
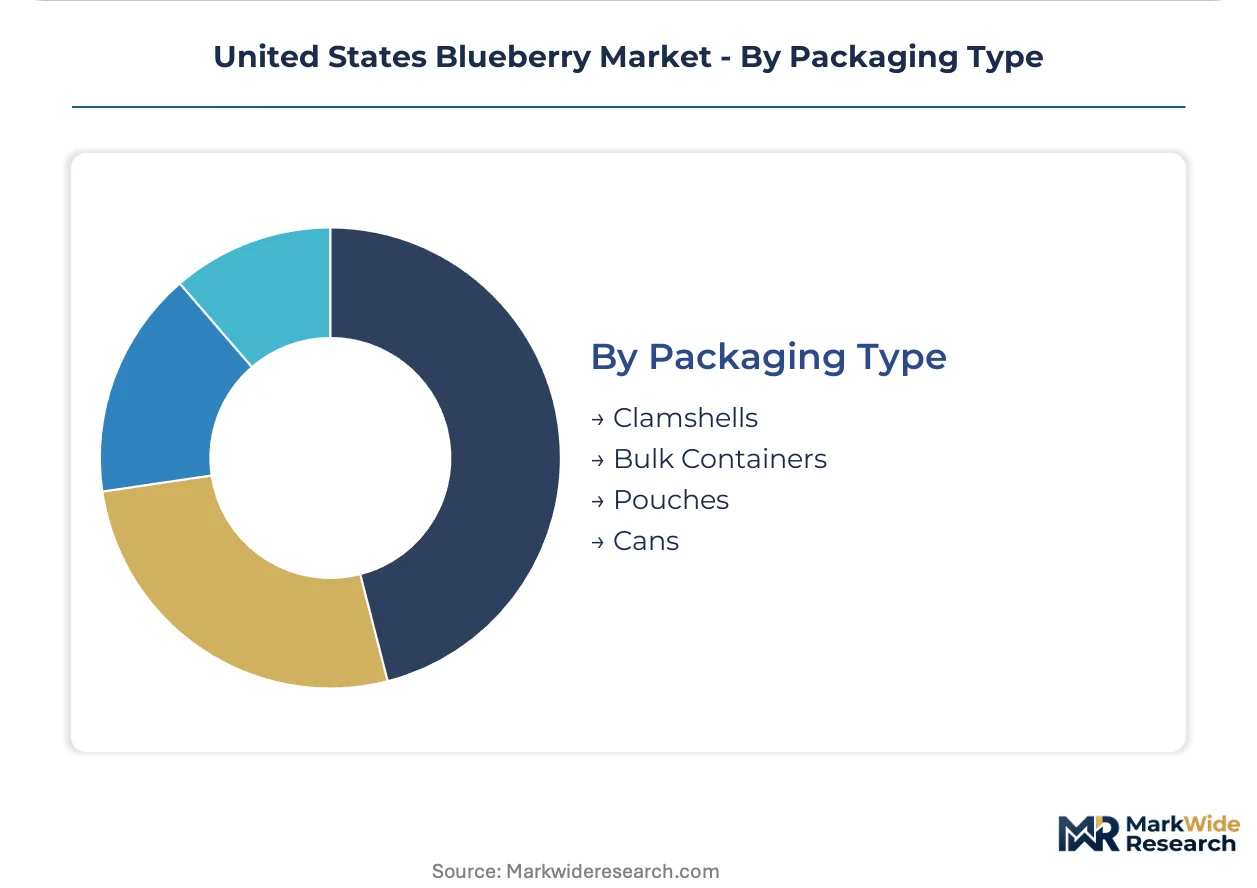
Packaging Type:
Packaging configuration determines cooling efficiency, shelf-life extension, and retail display economics across club store and e-commerce specifications.
- Clamshells:Recyclable PET containers dominate fresh retail with vented designs optimizing airflow and moisture control for 2-3 week shelf stability in refrigerated distribution.
- Bulk Containers:Corrugated bins and totes serve food processing and foodservice channels with volume efficiency and reduced per-pound packaging cost for frozen and dried formats.
- Pouches:Flexible packaging gains placement in dried blueberry segments and single-serve snack applications with lightweight shipping economics.
- Cans:Metal packaging retains niche positioning in juice and processed blueberry products with extended ambient shelf stability.
Clamshells hold the structural lead in fresh channels, while Bulk Containers is climbing the fastest as manufacturing scale concentrates procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA Organic certification incentives and state water project allocations are restructuring planting decisions across Pacific Northwest and Southeast growing zones, concentrating investment in regions with compliant infrastructure and reliable irrigation access.
Pacific Northwest
Oregon's Willamette Valley and Washington's Columbia Basin absorb the majority of controlled-environment agriculture investment, with precision irrigation and substrate systems expanding viable acreage beyond traditional soil-based cultivation. Washington State Department of Agriculture inspection protocols now align with FDA Food Safety Modernization Act requirements, reducing audit duplication for exporters. Yakima Valley packhouses deploy machine vision sorting systems for high-throughput automated operations serving Costco and Amazon Fresh specifications.
California Central Valley
State water project curtailments restrict expansion in Fresno and Kern counties despite strong food processing demand for frozen and dried formats. California Department of Food and Agriculture implements additional pesticide residue inspection protocols that condition wholesale pricing and export eligibility. Merced County shippers reconfigure box dimensions and cooling protocols to match club store and e-commerce fulfillment center requirements.
Southeast Growing Zone
Georgia and Florida retain underpenetrated organic acreage relative to Pacific Northwest saturation, creating certification gap opportunities for growers willing to absorb transition costs. State departments of agriculture in Georgia implement cooling chain verification requirements for fresh market grades. Alachua County, Florida, operations face compressed seasonal windows from Peruvian counter-seasonal imports during October-March surges.
Southeast Michigan
Michigan's blueberry ridge along Lake Michigan maintains heritage production for processing channels with standardized brix specifications for cereal and baked goods manufacturers. Michigan Department of Agriculture and Rural Development enforces grade standards that condition institutional procurement contracts. Van Buren County packhouses retain manual specialty-grade lines for organic handlers serving premium retail placement.
United States Blueberry Market Competitive Landscape
Player mix skews toward integrated breeding-to-retail platforms and cooperative volume aggregators, with structure consolidating around scale-driven compliance advantages under FDA Food Safety Modernization Act mandates. Strategic archetypes include vertically integrated fresh market specialists, multi-state cooperative networks, and counter-seasonal import distributors. Dominant competitive moves encompass controlled-atmosphere storage infrastructure investments and direct-to-foodservice channel development bypassing traditional wholesale tiers.
Within the integrated platform tier, Driscoll's Inc. and Naturipe Farms LLC exemplify divergent scale strategies, with the former anchoring branded retail shelf space and the latter cooperative volume across multiple growing states. Camposol S.A. occupies a position representing counter-seasonal supply archetypes that extend year-round availability through Peruvian production. These three entities collectively illustrate how certification compliance, geographic diversification, and channel specialization separate premium positioning from commodity pressure.
| Leading Market Players |
|---|
| Fruitist |
| Camposol S.A. |
| Driscoll's Inc. |
| Complejo Agroindustrial Beta S.A. |
| Hortifrut Peru SAC |
| Naturipe Farms LLC |
| AMFRESH |
| Agrovision Peru SAC |
| Agroberries |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Pacific Northwest growers and institutional food processing buyers lock in frozen blueberry supply access while establishing price visibility across volatile harvest cycles. These arrangements insulate cereal and snack bar manufacturers from spot market swings in California's Central Valley and Oregon's Willamette Valley, where water allocation uncertainty and labor cost inflation concentrate pricing power among compliant, large-scale operators.
Pricing Analysis
Certification level creates the primary spread between USDA Organic and conventional grades, with organic premiums reflecting three-year transition costs and ongoing compliance investments. Fresh market pricing stratifies across premium clamshell retail, standard wholesale tote, and economy processing-grade tiers, with Peruvian counter-seasonal imports during October-March compressing domestic windows. Pricing pressure stems from H-2A wage inflation and cooling infrastructure capital requirements. Food processing buyers exhibit lowest price sensitivity due to formulation lock-in, while spot market purchasers face highest volatility exposure.
Supply Chain Analysis
Inventory cycles compress to 6-8 weeks for fresh formats, extending to 12-18 months for individually quick-frozen stockpiles held by cereal manufacturers. Supply concentrates in Oregon, Washington, and California, with Peruvian imports filling October-March gaps. The chain draws from specialized substrate suppliers, precision irrigation equipment vendors, and H-2A labor contractors. Single-source vulnerability sits with concentrated cooling chain infrastructure in the Willamette Valley. Distribution runs through direct-to-processor pipelines for frozen volumes and retail consolidation networks for fresh clamshell placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States blueberry market is recovering from cyclical margin compression driven by Peruvian import surges and input cost inflation, with structural tailwinds from food manufacturing demand and organic certification premiums supporting medium-term normalization.
For Market Incumbents: Compound defensive positioning through controlled-atmosphere storage infrastructure investments that extend fresh windows by 6-8 weeks, and deepen backward integration into proprietary breeding programs to differentiate from commodity Peruvian supply. Lock in multi-year offtake agreements with institutional foodservice buyers before FSMA traceability compliance costs filter smaller competitors from direct channel eligibility.
For New Entrants and Emerging Players: Lead with organic certification in Southeast growing zones where Pacific Northwest saturation leaves acreage gaps, targeting Georgia and Florida transition opportunities with three-year runway planning. Pursue direct-to-foodservice channel development bypassing wholesale consolidation, emphasizing traceability narratives and cooling chain verification that restaurant procurement committees now mandate.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated platforms with captive breeding-to-retail infrastructure and existing organic certification portfolios that compound compliance advantages under tightening FDA traceability mandates. Monitor H-2A visa program policy shifts as the primary inflection signal for labor cost trajectory and mechanization investment urgency across the analysis window.
| Strategic Initiative | Industry Significance |
|---|---|
| Controlled-Atmosphere Storage Buildout | Extends fresh market windows for premium retail placement against Peruvian imports. |
| USDA Organic Certification Investment | Captures widening premium spreads in Southeast zones with underpenetrated acreage. |
| Direct-to-Foodservice Channel Development | Bypasses wholesale compression with traceable volume commitments to restaurant procurement. |
| Precision Irrigation Infrastructure | Expands viable acreage in water-constrained California Central Valley and Oregon valleys. |
| FSMA Traceability System Integration | Locks in supplier eligibility for Walmart, Kroger, and institutional accounts under Section 204. |
Research Methodology
Operator-level perspectives from blueberry farm operators, packhouse managers, food processing procurement directors, and foodservice distribution executives anchored the qualitative base for this study. These primary insights combined with secondary validation from USDA Agricultural Marketing Service grade standard filings, FDA Food Safety Modernization Act guidance documents, state department of agriculture inspection protocols, and agricultural trade association production surveys. Bottom-up acreage and yield modeling triangulated against top-down consumption flow analysis across fresh, frozen, dried, and juice format channels.
Sensitivity analysis tested forecast outputs against variable assumptions for water allocation cuts in California, H-2A wage inflation trajectories, and Peruvian import volume elasticity. The analytical framework modeled product type, distribution channel, end user, and packaging type segmentation dimensions across the projection horizon, with CAGRs derived from trend extrapolation adjusted for structural shift inflections. Industry-specific inputs included anthocyanin preservation protocol adoption rates and controlled-environment agriculture investment pipelines.
Underlying assumptions cover stable FDA traceability implementation timelines and continued food manufacturing demand growth for frozen formats, with deviation risk concentrated in climate-driven harvest volatility and trade policy shifts affecting Peruvian import flows. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
GCC Fruits and Vegetables Market
Fruits and Vegetables
North America Freeze-Dried Fruits and Vegetables Market
Fruits and Vegetables
Asia Pacific Orange Market
Fruits and Vegetables
Camellia Oil Market
Fruits and Vegetables
Fruit and Vegetable Pulp Market
Fruits and Vegetables
Fruit Packaging Market
Fruits and Vegetables
Global Pickle Market
Fruits and Vegetables
US Fruit and Vegetables Market
Fruits and Vegetables
Fermented Cucumber Market
Fruits and Vegetables
Frozen Fruits and Vegetables Market
Fruits and Vegetables
Asia Pacific Olive Market
Fruits and Vegetables
Dill Pickles Market
Fruits and Vegetables
Yacon Fruit Extract Market
Fruits and Vegetables
Uruguay Fruits and Vegetables Market
Fruits and Vegetables
Brined Vegetable Market
Fruits and Vegetables
US Fruit Puree Market