
 US Fruit Puree Market | 2026-2036
US Fruit Puree Market Size, Share, and Industry Trends Forecast 2026-2036
US Fruit Puree Market Intelligence
The USDA Organic certification is collapsing the price gap between conventional and premium specialty purees, intensifying competition. This market shift pressures established players to refine their value propositions beyond simple price points. Del Monte Foods, Inc. leverages its extensive distribution network across the US to maintain market presence. Meanwhile, Tree Top, Inc. specializes in apple and pear-based ingredients for industrial clients, while The J.M. Smucker Company competes on brand recognition in consumer-facing retail channels.
Fruit puree is a processed food product derived from mashing or sieving fruits, with quality often defined by viscosity and Brix level. Its primary commercial purpose is as a functional ingredient providing flavor, color, and texture in beverages, dairy items, and baked goods. Organic puree formats are commanding significant price premiums over conventional offerings, driving margin. The infant food producers segment remains a critical, high-specification end-use market where traceability and purity are paramount.
The Food and Drug Administration (FDA) enforces strict food safety and labeling rules, particularly through the Food Safety Modernization Act (FSMA). The United States Department of Agriculture (USDA) governs the standards for organic certification, a critical market access and pricing differentiator. These regulatory frameworks shape both product formulation and supply chain management. Securing reliable, long-term contracts for specific fruit varieties and origins will define supplier success.
Market Dynamics
The central dynamic in the US fruit puree market is the pressure from the USDA's organic certification standards. This regulatory framework is narrowing the price differential between conventional and organic products, forcing manufacturers to compete on factors beyond cost, such as traceability and specific fruit varietals.
Growth Catalysts
- Infant Food Segment Demand:The infant food industry's stringent requirements for purity, traceability, and low microbial counts create consistent demand for high-specification fruit purees, particularly organic and single-fruit varieties.
- Clean-Label Consumer Preference:A consumer shift towards foods and beverages with simple, recognizable ingredients is boosting the use of fruit puree as a natural sweetener, colorant, and texturizer in products like yogurt, baked goods, and smoothies.
- Food Safety Modernization Act (FSMA):This FDA framework favors suppliers with robust, documented food safety protocols. Compliance with FSMA's preventive controls provides a competitive advantage, especially when supplying large-scale food processors.
Market Restraints
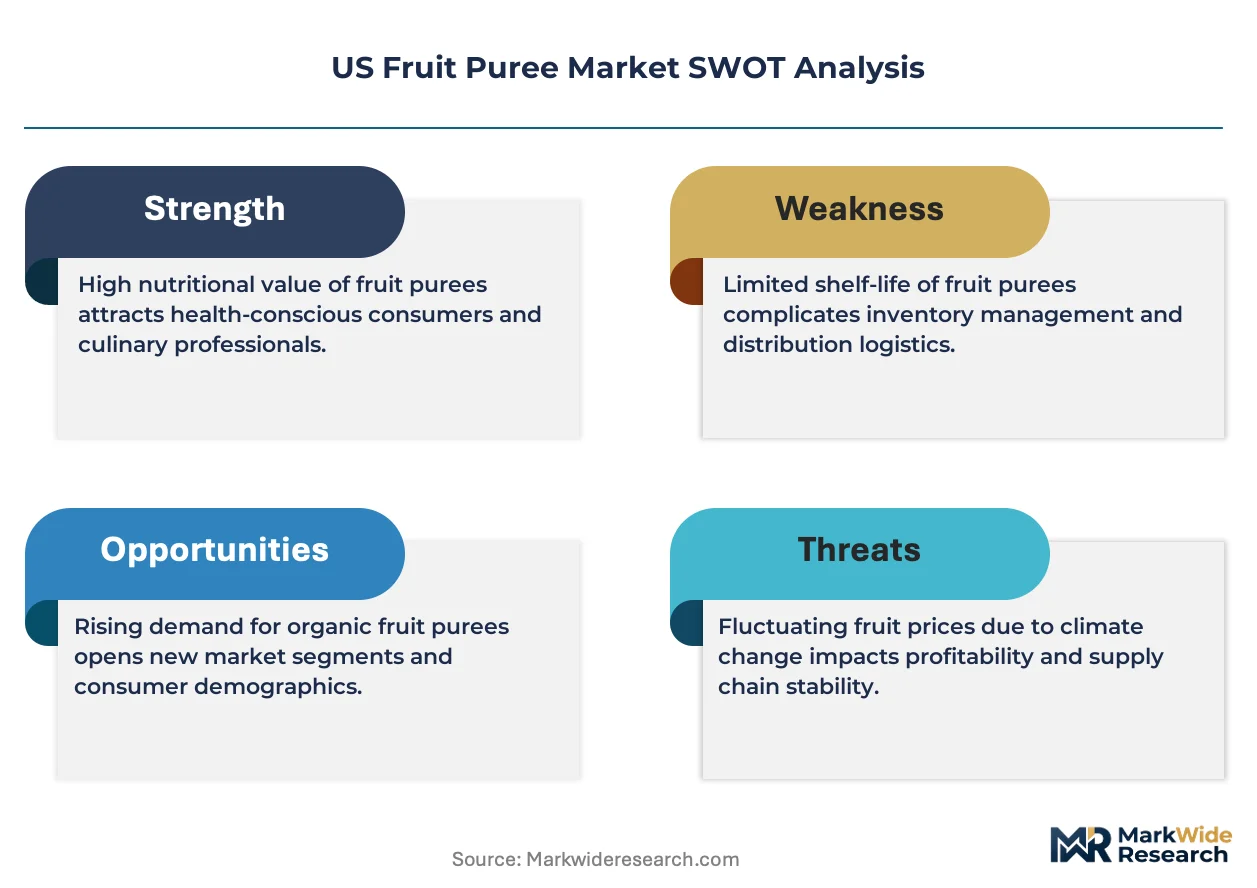
- Input Cost Volatility:The market is subject to price fluctuations driven by agricultural variables, including climate events affecting fruit harvests in key growing regions like California and Florida, which can impact crop yield and quality.
- Supply Chain Concentration:A heavy reliance on a few specific agricultural states for primary fruit cultivation creates vulnerability. A regional disruption from weather, disease, or labor shortages can significantly impact the national supply of certain purees.
- Substitution from Concentrates:In cost-sensitive applications like some beverages and confections, fruit purees face competition from lower-cost fruit juice concentrates and artificial flavor systems that can mimic fruit profiles.
Strategic Opportunities
- Functional Food Applications:There is a growing opportunity to position fruit purees, especially those from antioxidant-rich fruits like berries and pomegranates, as functional ingredients for the health and wellness food and beverage sector.
- Foodservice Channel Expansion:The US foodservice industry represents an underpenetrated channel for specialty purees, which can be used to create unique sauces, glazes, marinades, and craft cocktail bases for restaurants and bars.
- Direct-to-Consumer Models:Niche producers of exotic or single-origin organic purees can leverage e-commerce platforms to build a brand and sell directly to consumers, bypassing traditional retail gatekeepers.
Industry Challenges
- Organic Certification Burden:Achieving and maintaining USDA Organic certification is a resource-intensive process that requires meticulous record-keeping and segregation throughout the supply chain, from farm to final packaging.
- Cold Chain Logistics:Preserving the quality of aseptic and frozen purees demands an unbroken cold chain. Managing temperature control across transportation and storage is a significant logistical and cost challenge for suppliers.
- Product Consistency:Maintaining consistent viscosity, Brix levels, and flavor profiles from batch to batch and year to year is a major operational challenge due to natural variations in fruit crops.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Fruit Puree Market |
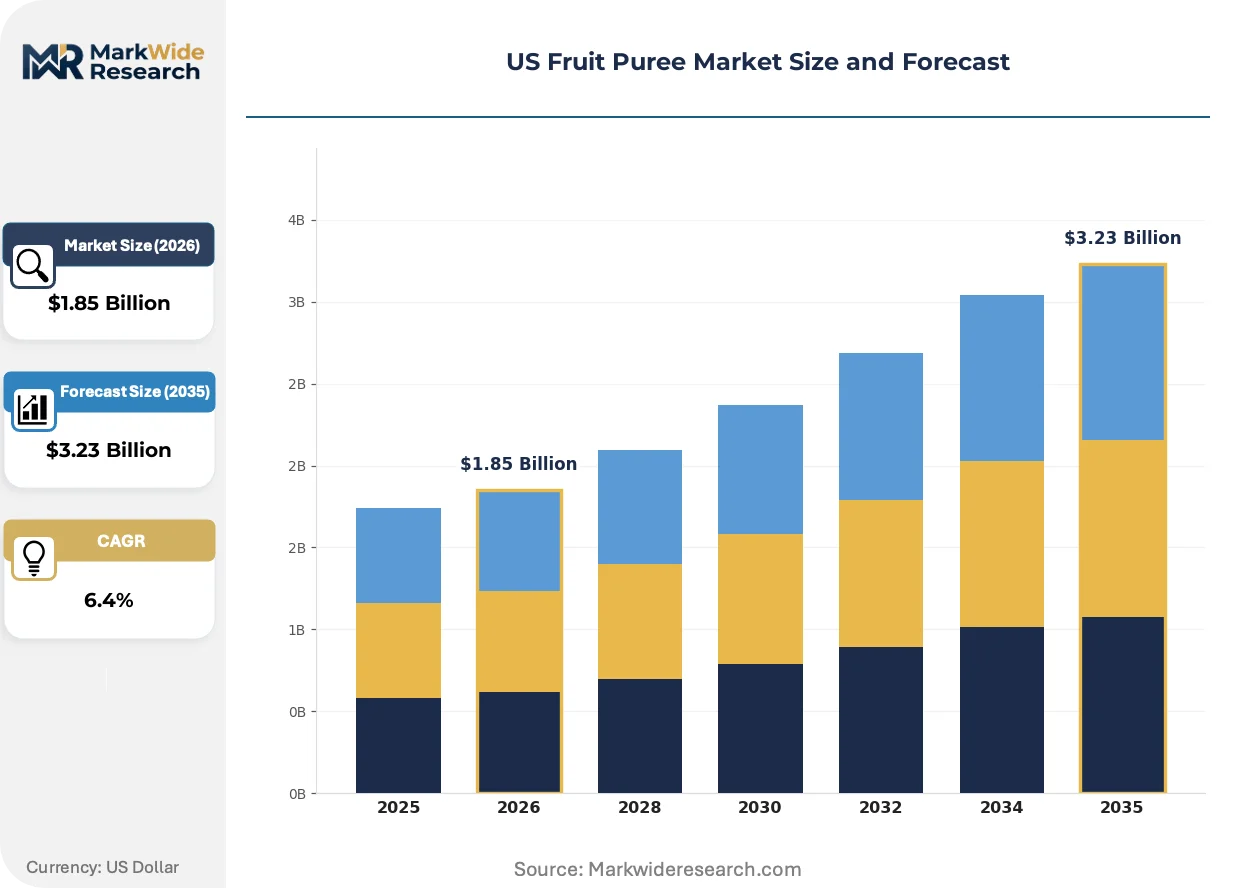
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Puree, Conventional Puree, Frozen Puree, Dried Powder End User: Food Manufacturers, Restaurants, Bakeries, Infant Food Producers Packaging Type: Tubs, Pouches, Jars, Cans Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Food Service |
| Companies Covered | Del Monte Foods, Inc., AGRANA Beteiligungs-AG, The J.M. Smucker Company, Grünewald International, Ingredion Incorporated, Tree Top, Inc., Döhler Group, Kerry Group, SunOpta Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Fruit Puree Market Strategic Shifts & Innovations
Product development is increasingly focused on clean-label formulations and enhanced nutritional value, driven by consumer demand for transparency. This shift compels ingredient suppliers to innovate in processing methods and secure supply chains that can deliver on specific quality and origin attributes.
Advanced processing technologies like high-pressure processing (HPP) and aseptic flash-cooling are gaining traction for their ability to preserve the natural color, flavor, and nutrient content of fruit. Premium beverage brands and infant food producers are the primary adopters of these methods. This technological divergence is fragmenting the market, creating a distinct top tier of minimally processed purees that command higher prices than those produced via traditional thermal pasteurization.
The FDA’s proposed rule to update the definition of "healthy" on food packaging is influencing product reformulation across the food industry. This regulatory shift incentivizes the use of nutrient-dense ingredients, such as fruit purees, that contribute to a food's nutritional profile without significant added sugars. The snack bar and breakfast cereal categories are particularly affected, as manufacturers re-engineer recipes to qualify for the "healthy" front-of-pack claim.
A notable behavioral change is the move away from spot-market buying toward establishing long-term, variety-specific supply contracts. This trend disrupts the traditional model of sourcing generic purees based on price, replacing it with strategic partnerships that secure access to specific fruit types like 'Hayward' kiwi or 'Hass' avocado. This procurement evolution is most prominent among large-scale yogurt and premium juice manufacturers in California's food processing centers.
US Fruit Puree Market Segmentation
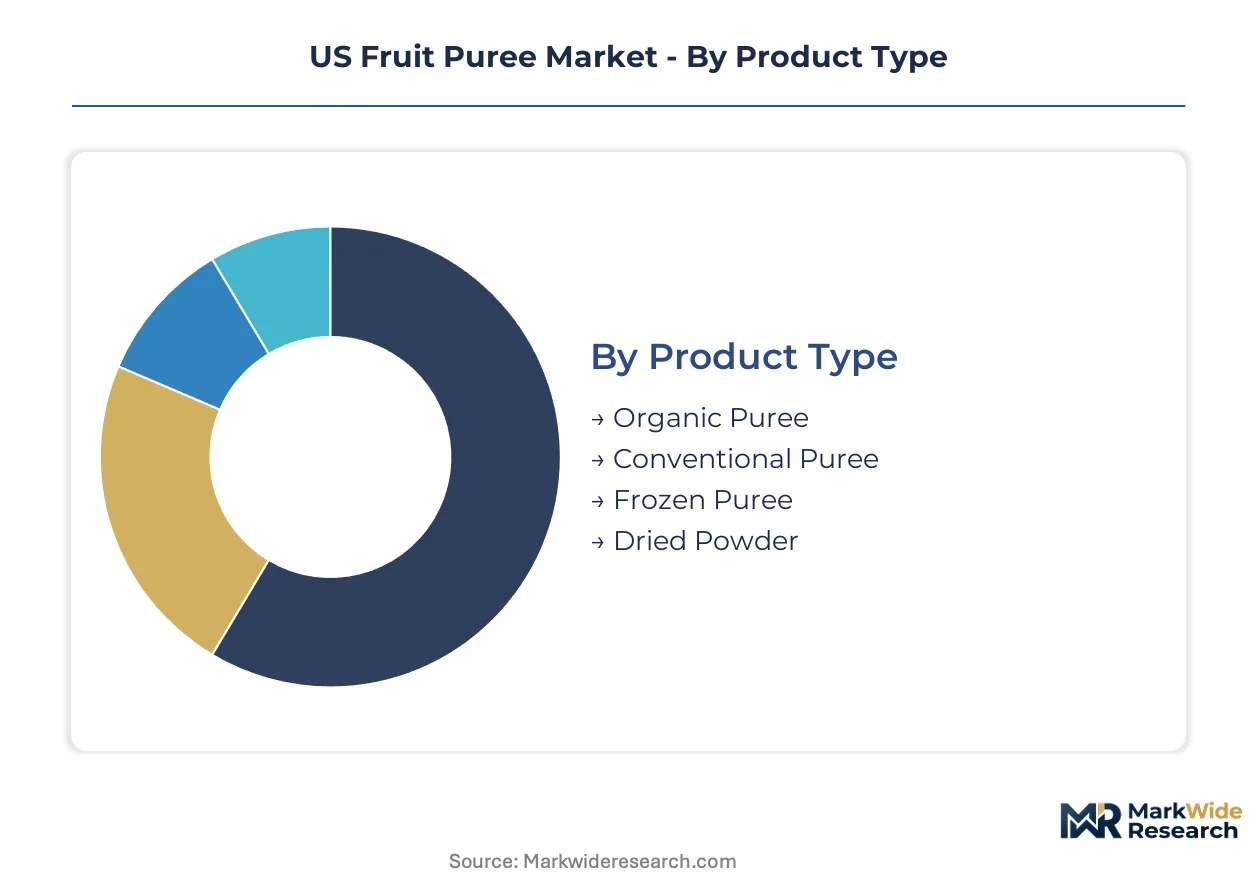
The US fruit puree market segmentation helps clarify diverse product offerings and target specific end-user requirements. Understanding these segments is crucial for manufacturers to tailor product development, optimize distribution strategies, and capture distinct value pools within the market.
Product Type:
The market's product types flow through distinct distribution channels, catering to varied industrial and consumer requirements.
- Organic Puree:Processed from fruits grown without synthetic pesticides or fertilizers, certified by USDA standards. Demand is concentrating in the infant food segment due to stringent purity and traceability requirements.
- Conventional Puree:Derived from traditionally farmed fruits, offering a cost-effective ingredient for various food applications. This product type sees significant demand from large-scale food manufacturers in California and Florida.
- Frozen Puree:Pureed fruit preserved through freezing, maintaining natural flavor and nutritional integrity for extended periods.
- Dried Powder:Dehydrated fruit puree, providing concentrated flavor and a longer shelf life for specific ingredient applications.
Conventional Puree dominates the installed base. Organic Puree is where expansion concentrates.
End User:
End-user categories define the specific application needs and quality specifications for fruit purees across the food industry.
- Infant Food Producers:Require purees with rigorous specifications for purity, low microbial counts, and single-fruit varieties. This segment's high-spec demand drives innovation in processing methods like HPP.
- Food Manufacturers:Utilize purees as functional ingredients for flavor, color, and texture in a wide array of products including beverages and dairy. This end-user group represents the largest volume consumer in the US market.
- Restaurants:Incorporate purees into sauces, glazes, desserts, and craft beverages, seeking consistent quality and flavor profiles.
- Bakeries:Use fruit purees for fillings, toppings, and natural sweeteners in various baked goods, valuing specific viscosity and Brix levels.
Infant Food Producers represent the fastest-growing trajectory, while Food Manufacturers currently constitute the largest volume segment.
Packaging Type:
Packaging types influence shelf life, transport efficiency, and consumer convenience across different market segments.
- Pouches:Flexible, single-serving containers often designed for infant food or on-the-go snacks, offering convenience and reduced waste. This format is expanding rapidly in consumer retail channels, particularly for organic varieties.
- Tubs:Larger format containers typically used for bulk supply to foodservice operators or industrial manufacturers. These provide efficient storage and handling for high-volume applications in commercial kitchens.
- Jars:Traditional glass containers, commonly found in retail for shelf-stable fruit purees and baby food products.
- Cans:Metal containers offering extended shelf life and durability, primarily used for industrial and institutional puree applications.
Pouches are gaining share fastest among consumer-facing formats, with Tubs remaining critical for bulk industrial supply.
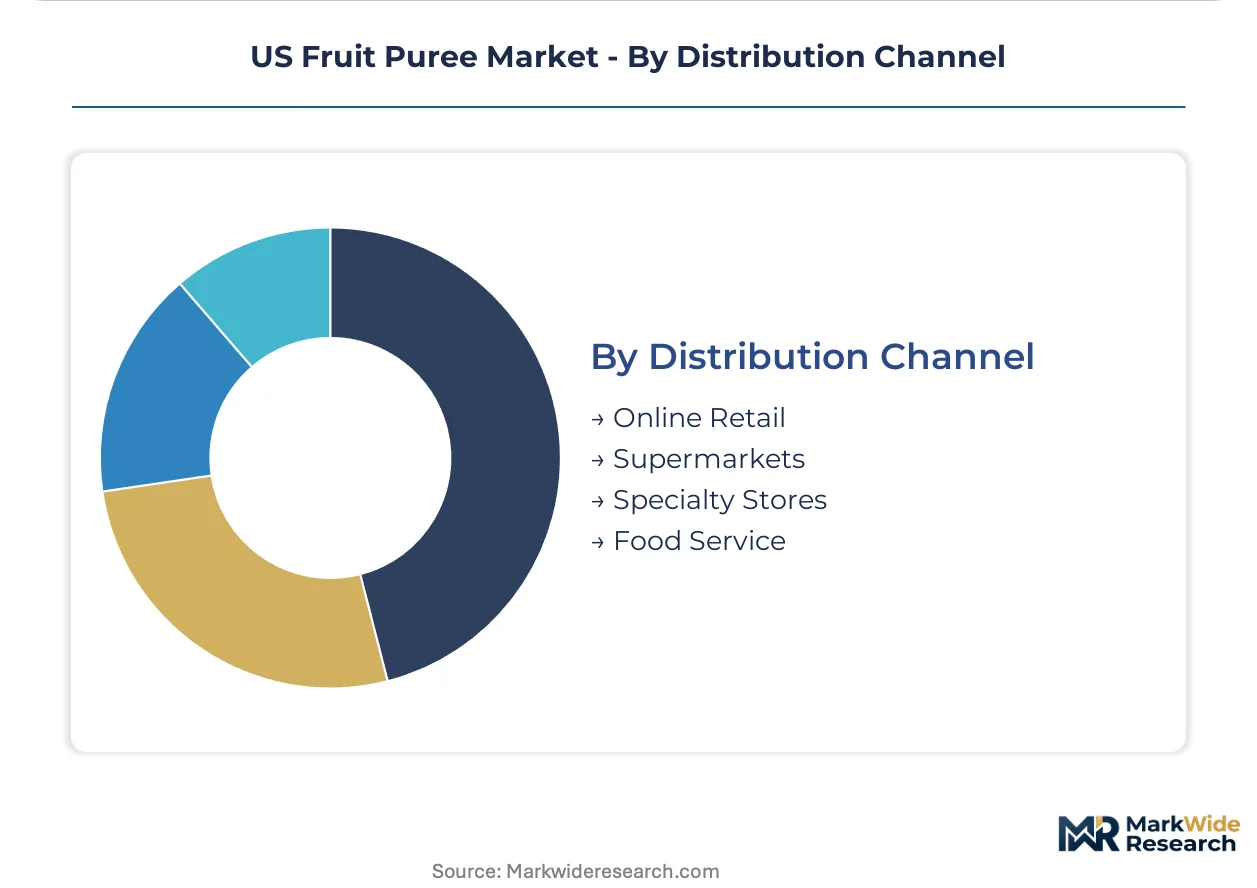
Distribution Channel:
Distribution channels determine market access and reach, segmenting the market based on buyer type and purchasing patterns.
- Online Retail:E-commerce platforms facilitate direct-to-consumer sales, allowing niche producers to reach specific customer segments without traditional brick-and-mortar presence. This channel supports brand building for exotic or single-origin organic purees.
- Supermarkets:Primary retail channel for consumer-packaged purees, including baby food and cooking ingredients, reaching a broad customer base. These stores drive high volume sales of both conventional and organic puree formats across the US.
- Specialty Stores:Focus on organic, gourmet, or unique purees, catering to consumers seeking premium or health-focused ingredients.
- Food Service:Supplies restaurants, cafes, and institutional kitchens with purees for culinary applications, representing an underpenetrated market.
Supermarkets maintain a significant volume presence, while Online Retail exhibits a steep expansion trajectory for niche products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA Organic certification standards, along with FDA regulations, significantly influence the US fruit puree market dynamics across different sub-regions. These frameworks dictate sourcing practices and product formulation, particularly for high-specification segments. Regional agricultural output and established food processing infrastructure further shape local market activity.
California
Demand for processed fruit ingredients and organic purees remains robust within California's extensive food processing hubs. The USDA Organic certification influences sourcing for many manufacturers operating here. Major food processing centers in the Central Valley and Southern California drive significant volume for both conventional and organic puree formats.
Florida
Florida's fruit puree market is driven by its strong citrus and tropical fruit cultivation, feeding local food processing. Climate events affecting fruit harvests in Florida can impact crop yield and quality. Food processing hubs around Orlando and Tampa utilize purees for beverages and other food products.
Midwest
The Midwest sees substantial demand from large-scale food manufacturers, particularly for infant food producers and dairy applications. FDA's Food Safety Modernization Act (FSMA) compliance is a critical competitive advantage for suppliers in this region. Food manufacturing centers in Illinois and Ohio are significant consumers of purees.
Northeast Corridor
The Northeast Corridor, including major metropolitan areas, exhibits strong consumer preference for clean-label and functional food applications. The FDA's proposed rule on "healthy" food packaging incentivizes nutrient-dense ingredients like fruit purees here. New York Metro and Pennsylvania food producers focus on specialty purees for health and wellness products.
US Fruit Puree Market Key Industry Players
Player mix skews toward a tiered structure, encompassing large-scale industrial ingredient providers and specialized organic puree producers. Strategic archetypes include volume-driven commodity suppliers, brand-focused consumer product companies, and high-specification ingredient specialists. Dominant competitive moves involve securing long-term supply contracts for specific fruit varieties and portfolio diversification into functional food applications.
On the industrial ingredient vector, Tree Top, Inc. exemplifies a specialist focused on apple and pear-based ingredients for industrial clients. The J.M. Smucker Company occupies a position anchored by strong brand recognition in consumer-facing retail channels. Del Monte Foods, Inc. represents a player leveraging an extensive distribution network across the US to maintain broad market presence.
| Leading Market Players |
|---|
| Del Monte Foods, Inc. |
| AGRANA Beteiligungs-AG |
| The J.M. Smucker Company |
| Grünewald International |
| Ingredion Incorporated |
| Tree Top, Inc. |
| Döhler Group |
| Kerry Group |
| SunOpta Inc. |
| Others |
Cost & Logistics Intelligence
USDA Organic certification gates both supply qualification and price differentiation simultaneously within the US fruit puree market. This regulatory framework notably impacts sourcing practices and the competitive landscape for manufacturers.
Pricing Analysis
Certification level, specifically USDA Organic status, creates the primary spread in fruit puree pricing. The market operates on contract-based long-term offtake agreements for industrial buyers, alongside commodity spot pricing for conventional purees. Price differentiation stems from the specific fruit varietals and advanced processing technologies like HPP. Pricing pressure stems from the narrowing gap between conventional and organic puree costs. Infant food producers exhibit the least price sensitivity due to stringent quality requirements, while some large-scale food manufacturers remain highly price-sensitive.
Supply Chain Analysis
Inbound logistics costs, particularly related to specialized cold chain transport, influence the supply chain for fruit purees. Geographic supply concentrates in California and Florida, regions known for extensive fruit cultivation. The market relies on specific fruit varieties like 'Hayward' kiwi or 'Hass' avocado for specialized applications. Input cost volatility, driven by climate events affecting fruit harvests, represents a significant structural supply chain risk. Distribution runs through industrial ingredient suppliers for bulk applications and retail channels for consumer-packaged purees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US fruit puree market presents a significant fragmentation opportunity, driven by consumer preference for clean-label ingredients and functional food applications.
For Market Incumbents: Consolidate existing supply relationships by securing long-term contracts for high-demand fruit varietals. Invest in advanced processing technologies such as HPP to meet evolving quality specifications and differentiate offerings against substitute technologies like concentrates. Leverage extensive distribution networks to maintain market presence and counter pressure from niche organic producers. Reinforce USDA Organic certification investments across the portfolio.
For New Entrants and Emerging Players: Anchor in specific white-space opportunities within the functional food applications segment, particularly for antioxidant-rich purees. Target underpenetrated channels like the foodservice industry with specialty purees for craft beverages and culinary uses. A direct-to-consumer e-commerce model offers a viable go-to-market angle for niche organic or exotic fruit puree offerings. Focus on high-specification, single-fruit varieties to build initial brand equity.
For Investors and Strategic Acquirers: Carve-out targets emerge from large food corporations seeking to divest non-core ingredient divisions. The market demonstrates long-term viability, driven by sustained demand for clean-label and high-specification ingredients over the next decade. Acquisition archetypes include vertically integrated specialists in organic purees or those with proprietary processing technologies. Increased M&A activity within the functional ingredient space serves as a critical signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Variety Sourcing | Secures consistent supply of high-demand fruit types for premium product lines. |
| Advanced Processing Investment | Preserves natural qualities and nutritional value for discerning end-user segments. |
| Functional Ingredient Diversification | Expands market reach into the health and wellness food and beverage sectors. |
| E-commerce Channel Development | Establishes direct consumer relationships for niche organic puree offerings. |
| USDA Organic Certification Expansion | Captures premium pricing and meets stringent infant food segment requirements. |
Research Approach
A standing panel of food technologists, procurement managers, regulatory compliance officers, and market development specialists provided ongoing calibration throughout the analysis. This study combined primary interviews with industry stakeholders and secondary validation from diverse sources. Secondary data included USDA reports, FDA guidance documents, trade association publications, and company financial statements. Both bottom-up and top-down triangulation methods were applied to ensure data accuracy.
Outputs were validated against external benchmarks to ensure consistency across the modeling period. The analytical framework integrated segmentation dimensions including product type, end-user, packaging type, distribution channel, and fruit varietal. Compound annual growth rates were derived from regression analysis of historical data and projected forward. Key forecast inputs included fruit harvest yields in major growing regions and evolving consumer dietary shifts.
Decision-makers should treat outputs as directional under base assumptions of a stable regulatory environment and predictable agricultural cycles; material deviation would warrant model refresh. Forecasts reflect assumptions that unforeseen climate events or significant shifts in trade policy could revise. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Peach Extract Market
Fruits and Vegetables
Romanesco Broccoli Market
Fruits and Vegetables
Guanabana Market
Fruits and Vegetables
Dried Kiwi Fruit Market
Fruits and Vegetables
Gold Kiwifruit Market
Fruits and Vegetables
Date Fruit Market
Fruits and Vegetables
Avocado-Based Products Market
Fruits and Vegetables
Asia-Pacific Shiitake Mushroom Market
Fruits and Vegetables
Dragon Fruit Powder Market
Fruits and Vegetables
Fruit Packaging Market
Fruits and Vegetables
Infused Dried Fruits Market
Fruits and Vegetables
Asia-Pacific Fruit and Vegetable Ingredient Market
Fruits and Vegetables
Fresh Figs Market
Fruits and Vegetables
Fruit and Vegetable Cleaners Market
Fruits and Vegetables
Tunisia Fruit and Vegetable Market
Fruits and Vegetables
Europe Dried Mushroom Market