
 North America Freeze-Dried Fruits and Vegetables Market | 2026-2036
North America Freeze-Dried Fruits and Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
North America Freeze-Dried Fruits and Vegetables Market Insights
Specialty retail distribution is fragmenting as direct-to-consumer platforms and outdoor recreation channels capture growing freeze-dried produce volumes. Harmony House Foods leverages its backpacking and preparedness specialty to sustain brand loyalty among outdoor enthusiasts. Mercer Foods anchors commercial supply relationships with food manufacturers seeking clean-label ingredients. OFD Foods differentiates through custom freeze-drying services for private-label clients across North America.
Freeze-dried fruits and vegetables undergo sublimation dehydration at pressures below 611 pascals and temperatures between minus 50 and minus 80 degrees Celsius, preserving cellular structure, color, and nutrient density while reducing moisture content below 5 percent for shelf-stable storage without refrigeration. Fruits dominate current volume given established demand in breakfast applications and snack formats, though mixed blends represent the fastest-expanding category as meal-kit manufacturers seek ingredient streamlining. Food service channels capture widening margin pools as restaurants incorporate freeze-dried components into premium menu offerings for flavor intensity and operational consistency.
The FDA's Food Safety Modernization Act mandates preventive controls for human food, while USDA organic certification requirements shape premium product positioning across the United States and Canada. Canada's Safe Food for Canadians Regulations impose additional traceability and preventive control obligations on cross-border suppliers. Stakeholders must monitor evolving state-level extended producer responsibility packaging laws and decide whether to front-run compliance through compostable pouch investments or absorb incremental cost pass-through risks.
Market Dynamics
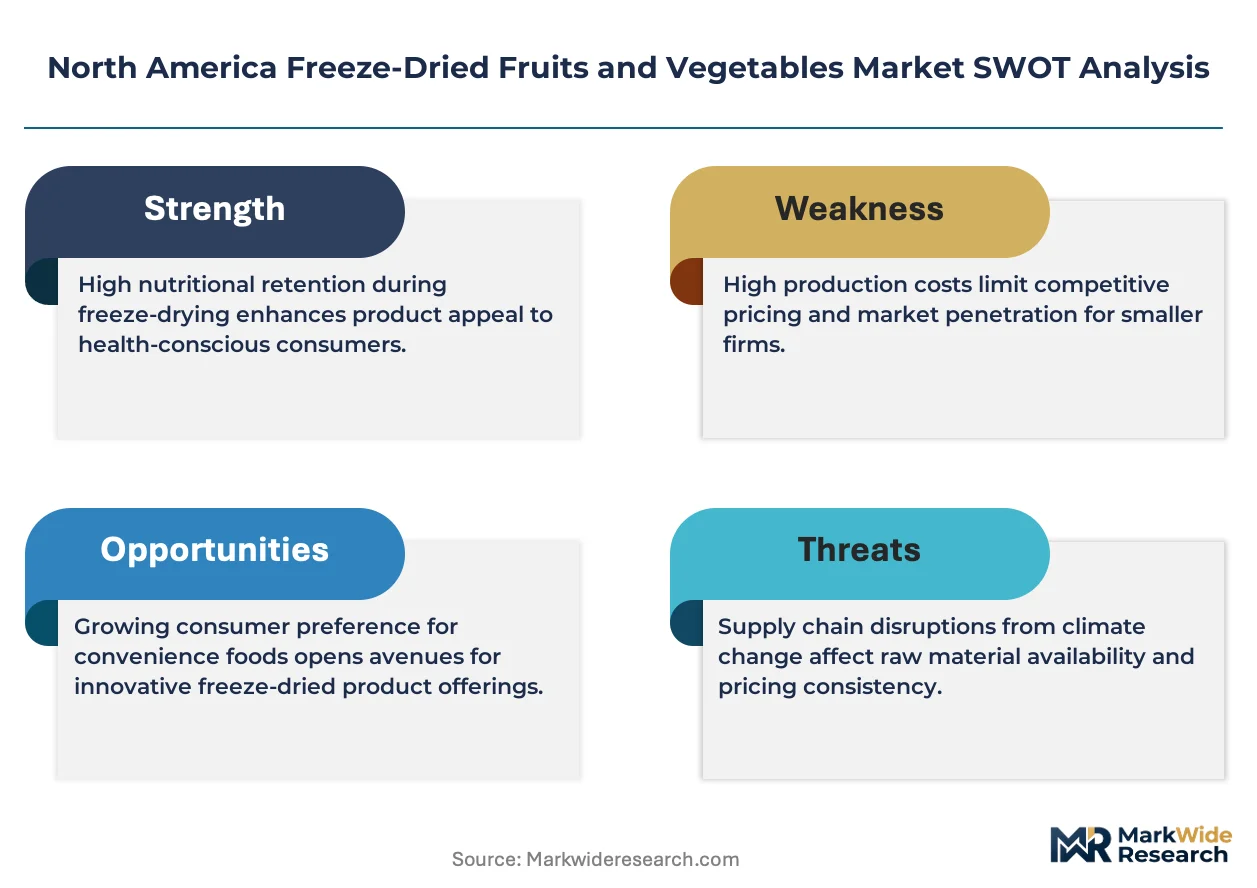
California's Central Valley processing corridor concentrates freeze-drying capacity, creating supply-side bottlenecks that amplify price volatility when agricultural input flows disrupt. The FDA's Food Safety Modernization Act preventive controls mandate capital-intensive facility upgrades across the United States and Canada.
Growth Catalysts
- Backpacking demand surge:Outdoor recreation participation across the United States and Canada drives lightweight, shelf-stable nutrition requirements. Trail-ready meal formats command premium positioning.
- FSMA compliance infrastructure:The FDA's preventive controls for human food mandate HACCP-aligned processing systems. Certified facilities capture institutional buyer trust.
- Emergency preparedness stockpiling:Federal and state-level disaster readiness programs across the United States channel procurement toward long-shelf-life food reserves. Civil defense contracts stabilize seasonal demand.
Market Restraints
- Energy cost volatility:Sublimation dehydration demands sustained vacuum pump operation and cryogenic cooling. Natural gas and electricity price spikes in California and Texas directly compress processor margins.
- Single-region supply concentration:California's Central Valley hosts over 70 percent of North American freeze-drying capacity. Drought, wildfire, or seismic events threaten continental supply continuity.
- Fresh produce substitution:Cold chain improvements and flash-frozen vegetable quality advances erode freeze-dried positioning in food service. Restaurants revert to fresh when logistics permit.
Strategic Opportunities
- Canadian Prairie expansion:Saskatchewan and Manitoba agricultural processors possess surplus grain drying infrastructure convertible to freeze-drying. Proximity to pulse and berry production reduces input transport costs.
- Meal-kit ingredient streamlining:Mixed freeze-dried blends replace multiple fresh SKUs in subscription box assembly. Portion-controlled pouches eliminate kitchen prep labor for time-constrained subscribers.
- USDA organic certification premium:The National Organic Program seal commands 15-30 percent price multiples in natural retail. Transitioning conventional lines captures clean-label positioning.
Industry Challenges
- Specialized technician scarcity:Vacuum system maintenance and lyophilization cycle optimization require hybrid mechanical-refrigeration expertise. Technical colleges in Fresno and Modesto lack aligned training programs.
- Extended organic transition timelines:USDA organic certification demands 36 months of land history and processing facility segregation. Capital sits idle during qualification periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Freeze-Dried Fruits and Vegetables Market |
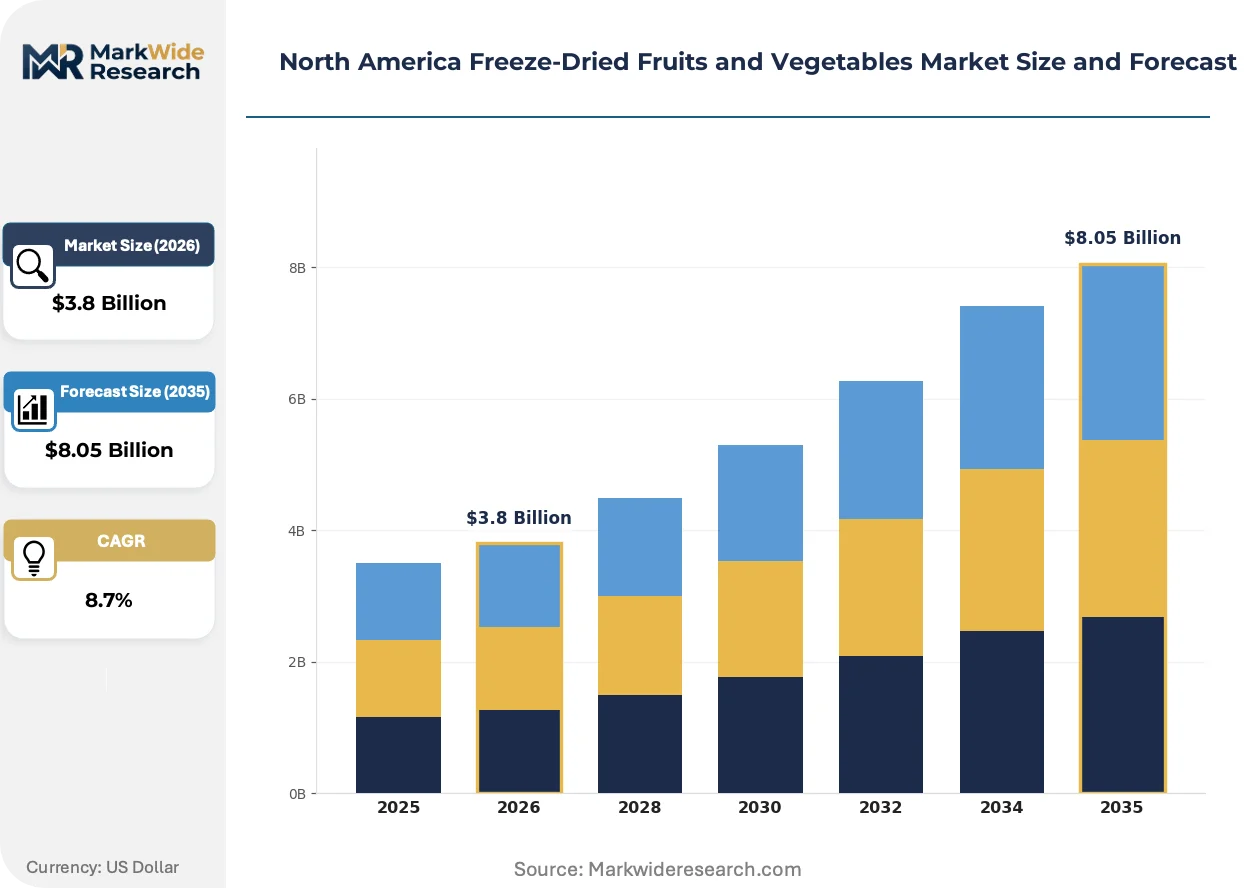
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Mixed Blends, Snacks Packaging Type: Bags, Pouches, Jars, Bulk Distribution Channel: Online, Supermarkets, Health Stores, Food Service End User: Retail Consumers, Food Manufacturers, Restaurants, Catering Services |
| Companies Covered | Harmony House Foods Inc., Mercer Foods, OFD Foods, R. J. Van Drunen & Sons, Freeze-Dry Foods Ltd., European Freeze Dry Ltd., Döhler Group SE, Kanegrade Ltd., Chaucer Foods Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Freeze-Dried Fruits and Vegetables Market Trends and Innovations
Smart monitoring systems and alternative energy integration are compressing operational costs while regulatory traceability mandates reshape processing workflows across North American freeze-drying facilities.
Radio-frequency identification tagging coupled with blockchain ledgering is virtualizing lot traceability from field to finished good. Large-scale processors in California's Central Valley deploy these systems to satisfy Walmart and Costco vendor compliance requirements. The technology is virtualizing paper-based record-keeping, cutting audit preparation labor by half while enabling real-time contamination traceback.
The FDA's Food Safety Modernization Act Section 204 food traceability rule mandates granular lot tracking for high-risk foods including fresh-cut fruits and vegetables. Freeze-dried processors must implement electronic sortable spreadsheets and maintain records for 24 months. Small and mid-sized operators in Oregon and Washington face disproportionate compliance burdens relative to integrated California competitors with existing enterprise resource planning infrastructure.
Direct-to-consumer subscription platforms displace traditional natural foods distributors for premium freeze-dried produce. Outdoor recreation enthusiasts in Colorado, Utah, and the Pacific Northwest source backpacking meals through brand-owned websites rather than REI or Bass Pro Shops. This channel compression captures margin previously allocated to wholesale markups while generating first-party consumption data for product development.
North America Freeze-Dried Fruits and Vegetables Market Segmentation
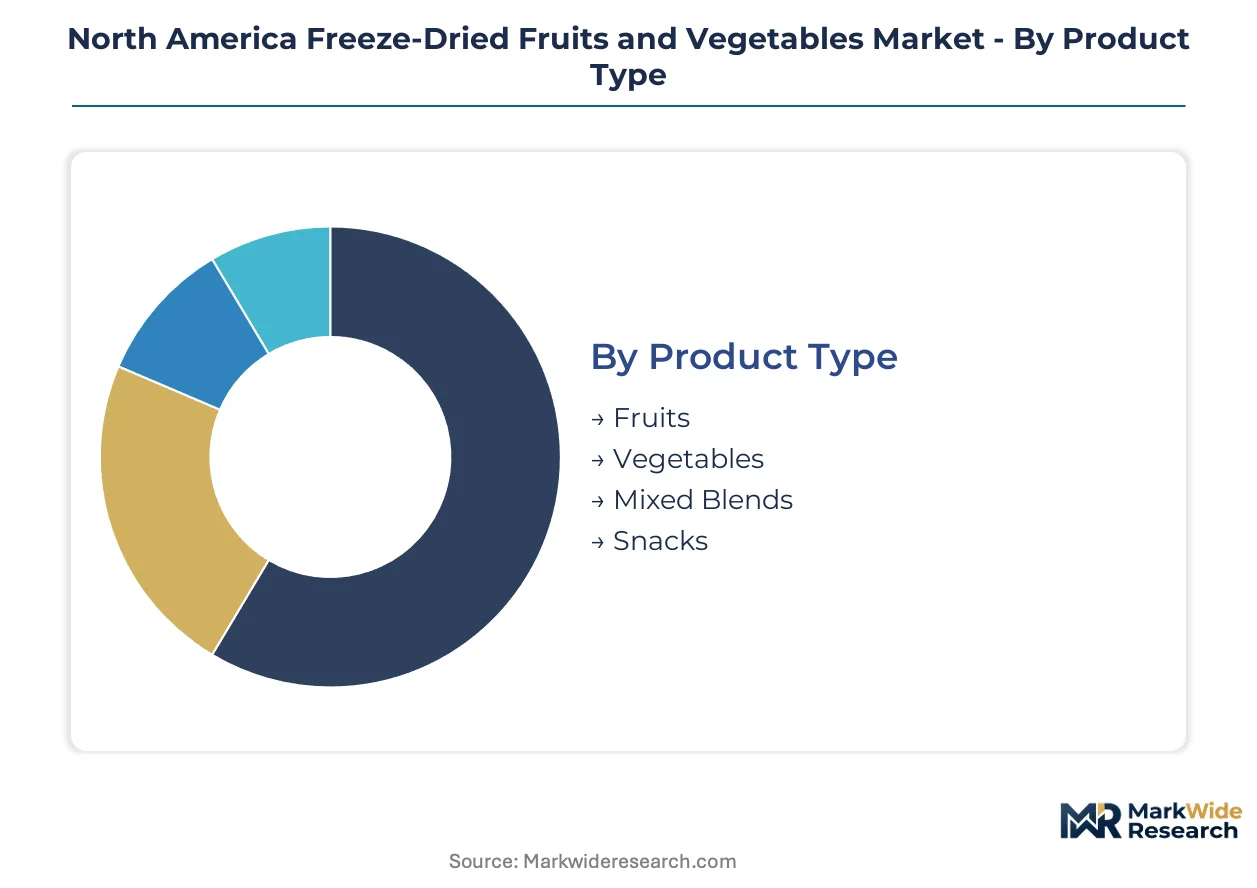
Segmentation reveals how freeze-dried produce flows through divergent channels with distinct margin profiles and technical requirements. Each dimension exposes pressure points where supply concentration meets demand fragmentation across the United States and Canada.
Product Type:
Mature categories anchor revenue stability while emerging formats capture shifting consumption patterns.
- Fruits:Individual berries, sliced apples, and tropical pieces retain cellular integrity through sublimation. Breakfast cereal manufacturers in Battle Creek, Michigan and snack brands in California's Central Valley specify low-moisture fruit inclusions for texture consistency. Drought-driven strawberry supply volatility in California squeezes input costs unpredictably.
- Mixed Blends:Pre-combined vegetable medleys and fruit-vegetable fusions streamline meal-kit assembly. Portland and Denver subscription box operators source portion-controlled pouches to eliminate kitchen labor. Clean-label positioning commands shelf space in natural retail channels.
- Vegetables:Diced peppers, corn kernels, and leafy greens serve soup and sauce manufacturers seeking year-round ingredient availability.
- Snacks:Standalone crunchy formats target on-the-go consumption with minimal preparation requirements.
Fruits handle the majority of throughput; mixed blends are expanding most quickly on share.
Packaging Type:
Cost tiers separate premium positioning from commodity bulk flows.
- Pouches:Multi-layer metallized films with oxygen barriers below 0.1 cc/m²/day protect shelf stability for 25 years. Emergency preparedness distributors in Utah and Texas specify military-grade pouch specifications for federal contract compliance. Extended producer responsibility laws in California and Oregon threaten cost pass-through viability.
- Bulk:Food manufacturers receive 50-pound fiber drums for industrial reprocessing into cereals, bars, and baking mixes. Minneapolis and Chicago ingredient buyers negotiate annual contracts with volume-tiered pricing.
- Bags:Standard polyethylene-lined paper sacks serve club store retail with intermediate shelf-life requirements.
- Jars:Glass containment targets gift markets and premium pantry display with moisture-sensitive resealable closures.
Pouches capture the highest margin per unit; bulk moves the greatest tonnage.
Distribution Channel:
Customer type determines service intensity and inventory velocity requirements.
- Online:Brand-direct platforms generate first-party consumption data while bypassing wholesale markups. Colorado and Pacific Northwest outdoor enthusiasts purchase backpacking meals through proprietary websites rather than REI or Bass Pro Shops. Subscription auto-ship programs stabilize seasonal demand fluctuations.
- Food Service:Restaurant chains specify freeze-dried components for flavor intensity and portion control consistency. National accounts demand lot traceability compliant with FDA Food Safety Modernization Act Section 204.
- Supermarkets:Mass retail placement requires slotting fee investments and promotional calendar coordination.
- Health Stores:Natural channel placement demands USDA organic certification and non-GMO verification for premium positioning.
Food Service handles the majority of throughput; online is climbing the fastest on share.
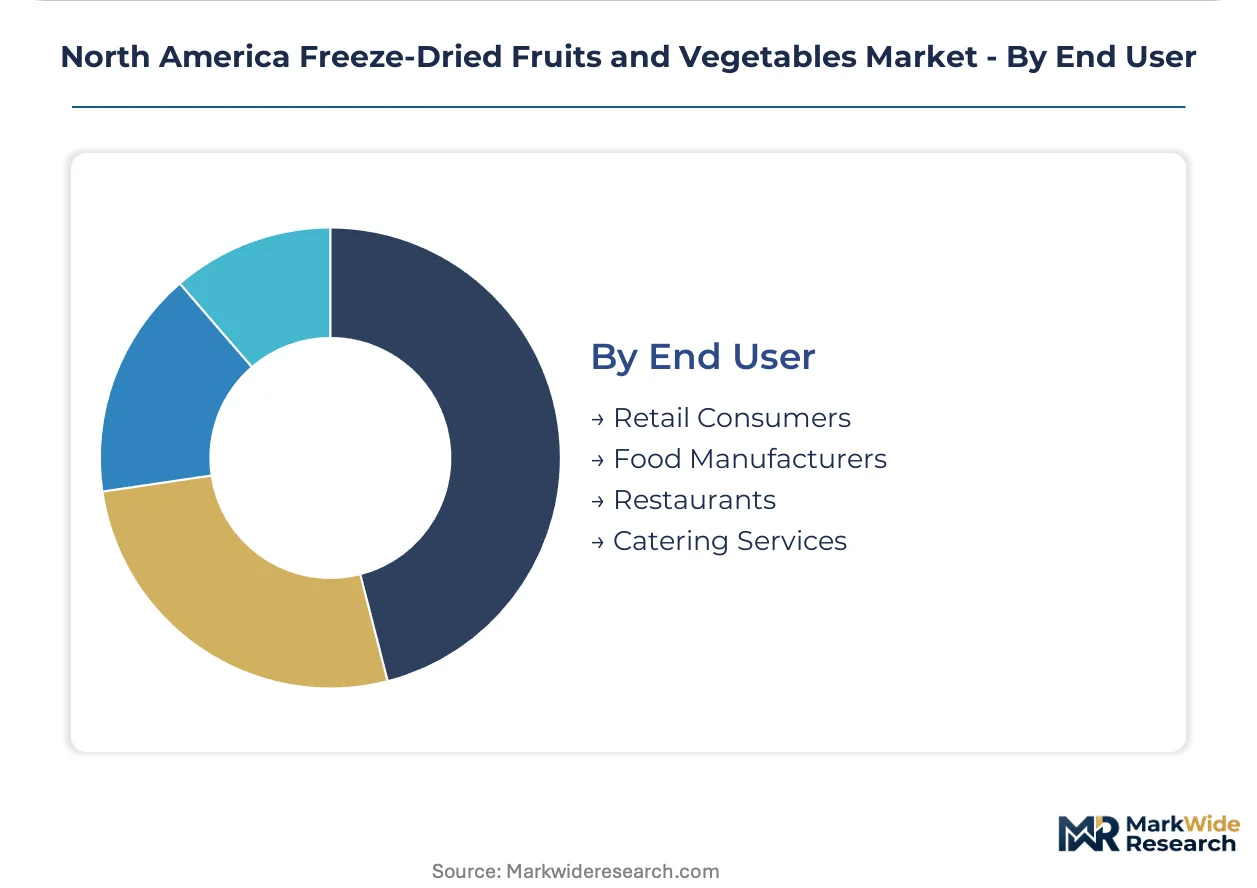
End User:
Application specificity drives formulation customization and technical service depth.
- Food Manufacturers:Cereal, bar, and baking mix producers specify precise moisture content, particle size distribution, and rehydration ratios. Minneapolis and Chicago procurement teams audit California Central Valley facilities for FSMA preventive controls compliance.
- Retail Consumers:Backpackers and emergency preppers in the United States and Canada prioritize shelf stability and pack weight over unit cost. Direct-to-consumer brands cultivate loyalty through outdoor recreation community engagement.
- Restaurants:Fine dining establishments incorporate freeze-dried elements for textural contrast and concentrated flavor delivery.
- Catering Services:Event operators value reduced refrigeration requirements and simplified logistics for remote venue service.
Food Manufacturers handle the majority of throughput; Retail Consumers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Union Pacific and BNSF rail networks channel agricultural inputs from Midwest growing regions into California's Central Valley processing corridor, underwriting North America's freeze-dried produce infrastructure.
United States
Backpacking communities in Colorado and Utah drive lightweight nutrition demand through direct-to-consumer channels. The FDA's Food Safety Modernization Act mandates preventive controls and electronic traceability for human food processors. California's Central Valley hosts concentrated freeze-drying capacity where drought and wildfire threats amplify supply volatility.
Canada
Emergency preparedness stockpiling across Prairie Provinces and Ontario stabilizes seasonal procurement for long-shelf-life reserves. Canada's Safe Food for Canadians Regulations impose traceability and preventive control obligations on cross-border suppliers. Saskatchewan and Manitoba agricultural processors possess convertible grain drying infrastructure near pulse and berry production zones.
Mexico
Strawberry and tropical fruit production in Michoacán and Guanajuato supplies raw material to US processors seeking year-round input availability. Mexico's Federal Commission for Protection against Sanitary Risk (COFEPRIS) aligns food safety protocols with FDA standards for integrated supply chains. Baja California and Sonora developing clusters serve cross-border logistics corridors into Arizona and California.
North America Freeze-Dried Fruits and Vegetables Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in ingredient supply. The North American freeze-dried fruits and vegetables market structures around three tiers: large-scale processors with integrated drying capacity, mid-size specialists serving private-label and food service accounts, and regional operators focused on subscription and outdoor recreation channels. Strategic archetypes include backpacking-focused direct-to-consumer brands, commercial ingredient suppliers anchoring food manufacturer relationships, and custom lyophilization service providers. Dominant competitive moves center on geographic diversification beyond California's supply concentration and channel compression through proprietary e-commerce platforms.
Within the specialty outdoor recreation tier, Harmony House Foods occupies a position exemplifying backpacking and preparedness community engagement. Among commercial ingredient suppliers, Mercer Foods and OFD Foods represent archetypes of food manufacturer relationship anchoring and custom freeze-drying service provision respectively.
| Leading Market Players |
|---|
| Harmony House Foods Inc. |
| Mercer Foods |
| OFD Foods |
| R. J. Van Drunen & Sons |
| Freeze-Dry Foods Ltd. |
| European Freeze Dry Ltd. |
| Döhler Group SE |
| Kanegrade Ltd. |
| Chaucer Foods Ltd. |
| Others |
Pricing and Supply Chain Analysis
California's Central Valley processing corridor concentrates over 70 percent of North American freeze-drying capacity, anchoring margin capture at the facility level while downstream buyers in Minneapolis and Chicago negotiate annual volume contracts for bulk ingredient supply. Energy-intensive sublimation dehydration ties processor margins directly to California and Texas electricity price volatility, creating asymmetric pricing power where capacity scarcity meets fragmented demand across food manufacturers and outdoor recreation channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates USDA organic certified product from conventional clean-label SKUs and commodity bulk ingredients. Quality grade and certification level drive price differentiation, with organic positioning commanding shelf space premiums in natural retail. Pricing pressure stems from drought-driven strawberry input volatility squeezing processor margins. Food manufacturers exhibit highest price sensitivity through annual contract negotiations, while emergency preparedness distributors absorb premium positioning for military-grade pouch specifications.
Supply Chain Analysis
Export-control regimes on vacuum pump technology and lyophilization equipment limit facility expansion velocity, constraining supply growth to domestic equipment fabrication capabilities. The supply chain draws from California's Central Valley, Mexico's Michoacán strawberry zones, and Canadian Prairie pulse production. Raw material dependencies center on seasonal berry harvests, natural gas for cryogenic cooling, and metallized film oxygen barriers. Single-region concentration in California creates seismic and wildfire vulnerability. Distribution runs through Union Pacific and BNSF rail networks into Minneapolis and Chicago ingredient hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hybrid mechanical-refrigeration expertise for vacuum system maintenance and lyophilization cycle optimization represents the critical capability gap constraining facility expansion, with technical training programs in Fresno and Modesto failing to align with processor hiring requirements.
For Market Incumbents: Build regulatory certification moats through USDA organic transition and FDA FSMA preventive controls compliance ahead of competitors. Deepen backward integration into California strawberry growing operations to hedge drought-driven input volatility. Expand capacity in Saskatchewan and Manitoba to reduce seismic concentration risk while capturing Prairie berry and pulse proximity advantages. For New Entrants and Emerging Players: Establish a beachhead in direct-to-consumer subscription channels serving Colorado and Pacific Northwest backpacking communities, where brand loyalty defends against incumbent scale advantages. Target Canadian Prairie processing infrastructure conversion from grain drying to freeze-drying, leveraging surplus capacity near raw material sources. Deploy proprietary e-commerce platforms to capture first-party consumption data and bypass wholesale margin extraction. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale processors with existing FSMA-compliant facilities and convertible Prairie infrastructure, where capability scarcity supports sustained margin capture. Long-term viability hinges on geographic diversification beyond California concentration and channel control through direct-to-consumer platforms. Watch for inflection signals in California electricity price volatility and extended producer responsibility packaging law enforcement.| Strategic Initiative | Industry Significance |
|---|---|
| Prairie Infrastructure Conversion | Saskatchewan and Manitoba grain drying facilities reduce California seismic risk while lowering berry and pulse transport costs. |
| Direct-to-Consumer Platform Launch | Proprietary e-commerce captures margin from REI and Bass Pro Shops while generating product development data. |
| USDA Organic Certification Investment | National Organic Program positioning commands shelf space premiums in natural retail channels. |
| FSMA Preventive Controls Compliance | FDA-aligned HACCP systems capture institutional buyer trust from Minneapolis and Chicago procurement teams. |
| Compostable Packaging Transition | California and Oregon extended producer responsibility laws threaten cost pass-through viability for conventional pouches. |
Research Methodology
Operator-level perspectives from freeze-drying facility managers, food manufacturer procurement leads, outdoor recreation channel buyers, and USDA organic certification auditors anchored the qualitative base. Secondary validation drew from FDA FSMA guidance documents, USDA National Organic Program standards, California agricultural production statistics, and Union Pacific freight flow data. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates.
Scenario-bracketing around energy price volatility, drought frequency, and regulatory enforcement intensity bounded the projection horizon. Segmentation dimensions included product type, packaging format, distribution channel, and end-user application. CAGRs derived from facility capacity expansion timelines, organic transition cohorts, and channel shift elasticity. Forecast inputs incorporated California electricity futures, strawberry acreage reports, and backpacking participation surveys.
Macroeconomic conditions sit as an overlay; deviation in natural gas pricing, California drought severity, or federal emergency preparedness funding would shift the trajectory. Forecasts reflect documented assumptions about FSMA enforcement consistency and Prairie infrastructure conversion rates. Material shifts in California seismic event frequency or USDA organic certification timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Farro Market
Fruits and Vegetables
Arecanut Market
Fruits and Vegetables
Fresh Lemons Market
Fruits and Vegetables
Europe Frozen Fruits and Vegetables Market
Fruits and Vegetables
Japan Avocado Market
Fruits and Vegetables
South America Olive Market
Fruits and Vegetables
Fresh Pumpkin Market
Fruits and Vegetables
Dried Red Jujube Market
Fruits and Vegetables
Vaccinium Myrtillus Market
Fruits and Vegetables
Banana Puree Market
Fruits and Vegetables
Global Fresh Fruits and Vegetables Market
Fruits and Vegetables
Global Maqui Berries Market
Fruits and Vegetables
Saudi Arabia Fruits and Vegetables Market
Fruits and Vegetables
Aronia Berries Market
Fruits and Vegetables
Acai Berry Market
Fruits and Vegetables
Brined Vegetable Market