
 Fruit and Vegetable Pulp Market | 2026-2036
Fruit and Vegetable Pulp Market Size, Share, and Industry Trends Forecast 2026-2036
Fruit and Vegetable Pulp Market Analytics
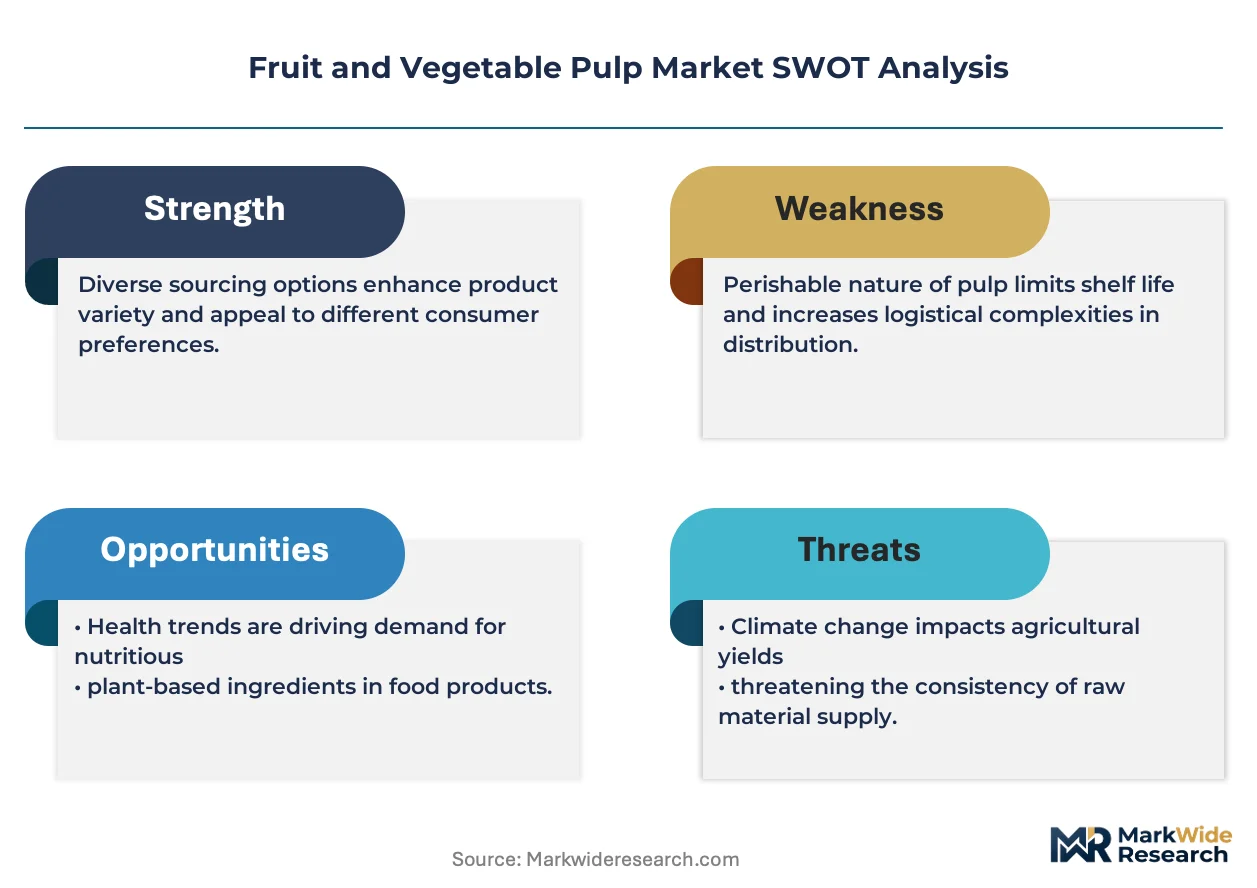
Ingredient processing margins is narrowing as commodity pulp commoditizes and branded concentrate formulations capture value upstream. Dohler GmbH leverages its European flavor systems integration to sustain premium positioning in beverage concentrates. ABC Fruits anchors South Asian supply chains through direct farm partnerships and regional puree specialization. PepsiCo, Inc. competes by controlling retail shelf space for smoothie and snack applications that absorb bulk pulp volumes.
Fruit and vegetable pulp consists of mechanically processed fibrous material retaining natural sugars, pectin, and cellular structure, typically processed through enzymatic liquefaction or cold-pressing to achieve 8-32 Brix soluble solids for industrial use. The material serves primarily as a viscosity modifier, natural sweetener carrier, and fiber enrichment source across formulated foods and beverages. Puree formulations occupy the largest volume position due to their direct incorporation into infant foods and sauces, while concentrate segments command higher margins through reduced water content and extended shelf stability. Extract categories are gaining fastest traction within nutraceutical applications where standardized polyphenol content drives procurement specifications.
The FDA enforces Hazard Analysis and Critical Control Points protocols that elevate pasteurization documentation burdens for importers, while the EFSA's evolving pesticide residue thresholds reshape sourcing patterns toward controlled-agriculture suppliers. India's FSSAI mandates incremental labeling disclosures on added pulp percentages, tightening formulation transparency for domestic processors. Stakeholders must monitor how dual carbon goals in major producing jurisdictions recalibrate energy-intensive evaporation and aseptic filling investments against margin compression in commodity grades.
Market Dynamics
Commodity pulp pricing compression is forcing processors to recalibrate toward value-added concentrate formulations and captive flavor system integration. The FDA's traceability mandates under FSMA Section 204 are accelerating capital deployment into digital lot-tracking infrastructure across North American processing facilities.
Growth Catalysts
- Cold-pressed extraction technology:Enzymatic liquefaction at lower thermal loads preserves volatile aromatic compounds for premium beverage applications. Equipment suppliers report order backlogs from smoothie manufacturers seeking cleaner label positioning.
- India's PLI scheme for food processing:Central government incentives for aseptic puree capacity are drawing multinational co-manufacturers into Maharashtra and Gujarat processing corridors.
- EFSA's revised dietary fiber guidelines:Elevated daily intake recommendations are reformulating bakery and snack specifications toward pulp-enriched fiber carriers.
Market Restraints
- Input cost volatility:Weather-driven citrus and tropical fruit harvest variability in Brazil and Southeast Asia creates margin squeeze for non-integrated processors lacking forward-contract coverage.
- Supply concentration risk:Aseptic filling equipment and sterile bag packaging capacity clusters with three European machinery OEMs, creating procurement bottlenecks for mid-scale entrants.
- Regulatory friction:The FDA's Foreign Supplier Verification Program imposes disproportionate compliance burdens on small-volume importers without dedicated regulatory affairs functions.
Strategic Opportunities
- Nutraceutical polyphenol standardization:Extract segments with verified antioxidant content are commanding specification premiums from functional beverage formulators in Germany and Switzerland.
- Direct-to-manufacturer procurement platforms:Digital marketplaces connecting Indian mango and guava growers to European puree buyers are compressing traditional broker margins.
- EU Green Deal carbon accounting:Processors with verified renewable energy inputs in their evaporation stages are securing preferred supplier status with sustainability-scored retail private labels.
Industry Challenges
- Specialized technician scarcity:Aseptic systems maintenance and HACCP documentation expertise shortages in India's emerging processing hubs are extending commissioning timelines for new capacity.
- Legacy ERP integration:Lot-level traceability requirements are forcing mid-tier processors to replace inventory management systems without disrupting just-in-time delivery contracts to beverage manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fruit and Vegetable Pulp Market |
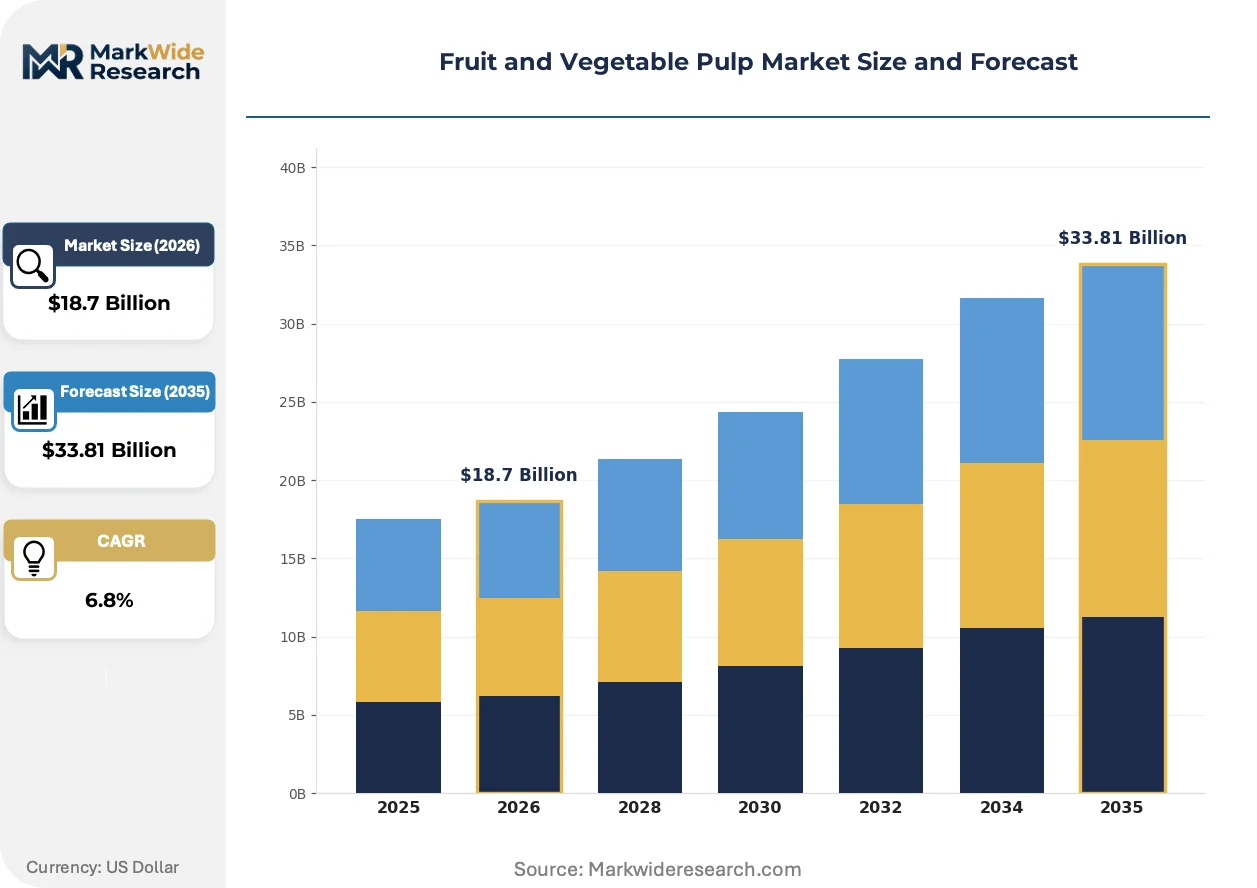
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Puree, Concentrate, Extract, Residue End User: Food Processing, Beverage Industry, Nutraceuticals, Cosmetics Distribution Channel: Direct Sales, Online Retail, Wholesalers, Supermarkets Application: Jams, Sauces, Snacks, Smoothies |
| Companies Covered | Keventer Agro Limited, Conagra Brands, Inc., PepsiCo, Inc., ABC Fruits, Dohler GmbH, AGRANA Beteiligungs-AG, Pursuit Industries Private Limited, Iprona AG, Kiril Mischeff Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fruit and Vegetable Pulp Market Evolving Landscape
Processing technology convergence with digital quality assurance is compressing batch-to-batch variation while enabling mass customization of pulp specifications. Regulatory pressure on residue testing and carbon disclosure is simultaneously elevating capital requirements and opening differentiation pathways.
Pulsed electric field pasteurization is hybridizing traditional thermal processing with non-thermal microbial reduction. Premium juice manufacturers in California and the Netherlands are piloting systems that reduce thermal degradation of heat-sensitive vitamins while maintaining FDA-mandated pathogen log reductions. This technology is hybridizing equipment supplier value propositions toward integrated process-intelligence platforms rather than standalone machinery sales.
The EU's Corporate Sustainability Reporting Directive is mandating Scope 3 emissions disclosure for food and beverage processors above defined revenue thresholds. Suppliers to European retail private labels must now provide granular energy and water intensity data across their puree and concentrate operations. Mid-scale Indian and Mexican exporters are responding by engaging third-party verification bodies to maintain shelf access in German and French retail channels.
Consolidated beverage manufacturers are unbundling traditional broker relationships in favor of direct farm-origin contracts with traceability documentation. This pattern compresses intermediary margins while transferring quality assurance liability upstream to processors capable of certifying pesticide residue compliance and harvest-lot provenance. The shift is most visible in North American smoothie and infant food supply chains where retailer liability concerns have intensified supplier qualification requirements.
Fruit and Vegetable Pulp Market Segmentation
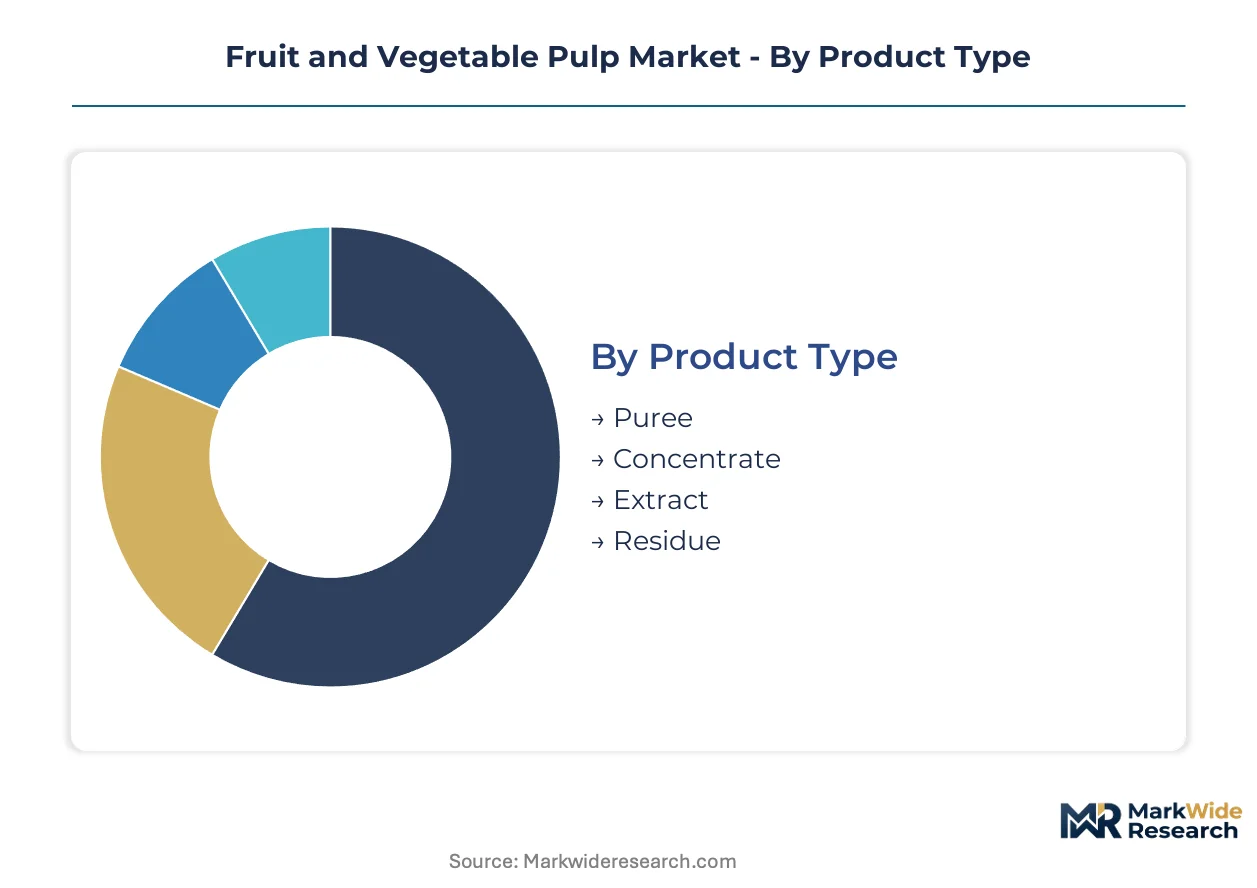
Pulp processors configure product specifications around viscosity requirements, shelf stability needs, and end-use integration constraints. Segmentation reveals how commodity grades compete on volume while functional extracts capture specification premiums from nutraceutical formulators.
Product Type:
Mature puree formats dominate procurement volumes while emerging extract categories command the steepest margin expansion.
- Puree:Mechanically processed fibrous material retaining 8-18 Brix soluble solids with intact cellular structure and natural pectin content. Infant food manufacturers in Germany and sauce processors in Italy concentrate procurement here, driven by direct-incorporation simplicity and clean-label positioning requirements.
- Concentrate:Water-reduced formulations achieving 28-32 Brix through evaporative processing, enabling extended shelf stability and reduced logistics costs. Beverage manufacturers in California and the Netherlands scale procurement for smoothie base formulations, constrained by energy-intensive evaporation investments and carbon disclosure mandates under the EU Green Deal.
- Extract:Standardized polyphenol carriers for functional beverage applications.
- Residue:Fiber-enriched byproduct streams for animal feed and composting channels.
Puree retains volume leadership; extract holds the steepest expansion curve.
End User:
Cost tier differentiation separates commodity processors from premium formulation specialists.
- Food Processing:Sauce and infant food manufacturers requiring viscosity modification and natural sweetener carriers without added stabilizers. Indian exporters to European retail private labels face FSSAI labeling mandates on pulp percentages while competing with Southeast Asian suppliers on cost.
- Beverage Industry:Smoothie and juice formulators demanding cold-pressed pulp with preserved aromatic compounds. California manufacturers pilot pulsed electric field pasteurization to reduce thermal degradation, constrained by FDA pathogen log reduction requirements and capital equipment costs.
- Nutraceuticals:Polyphenol-standardized extracts for antioxidant positioning.
- Cosmetics:Fiber and enzyme carriers for natural skincare formulations.
Food processing commands procurement volume; nutraceuticals climb the fastest on specification premiums.
Distribution Channel:
Supply concentration favors direct relationships over intermediary-dependent channels.
- Direct Sales:Farm-to-processor contracts with harvest-lot traceability documentation. Indian mango and guava growers in Maharashtra bypass traditional brokers through digital procurement platforms, transferring quality assurance liability upstream while compressing intermediary margins.
- Wholesalers:Aggregated sourcing for mid-scale processors lacking dedicated procurement functions.
- Supermarkets:Private label puree and concentrate for retail-branded smoothie lines.
- Online Retail:Small-batch specialty pulp for artisanal food manufacturers.
Direct sales dominate volume flows; online retail gains share fastest among niche formulators.
Application:
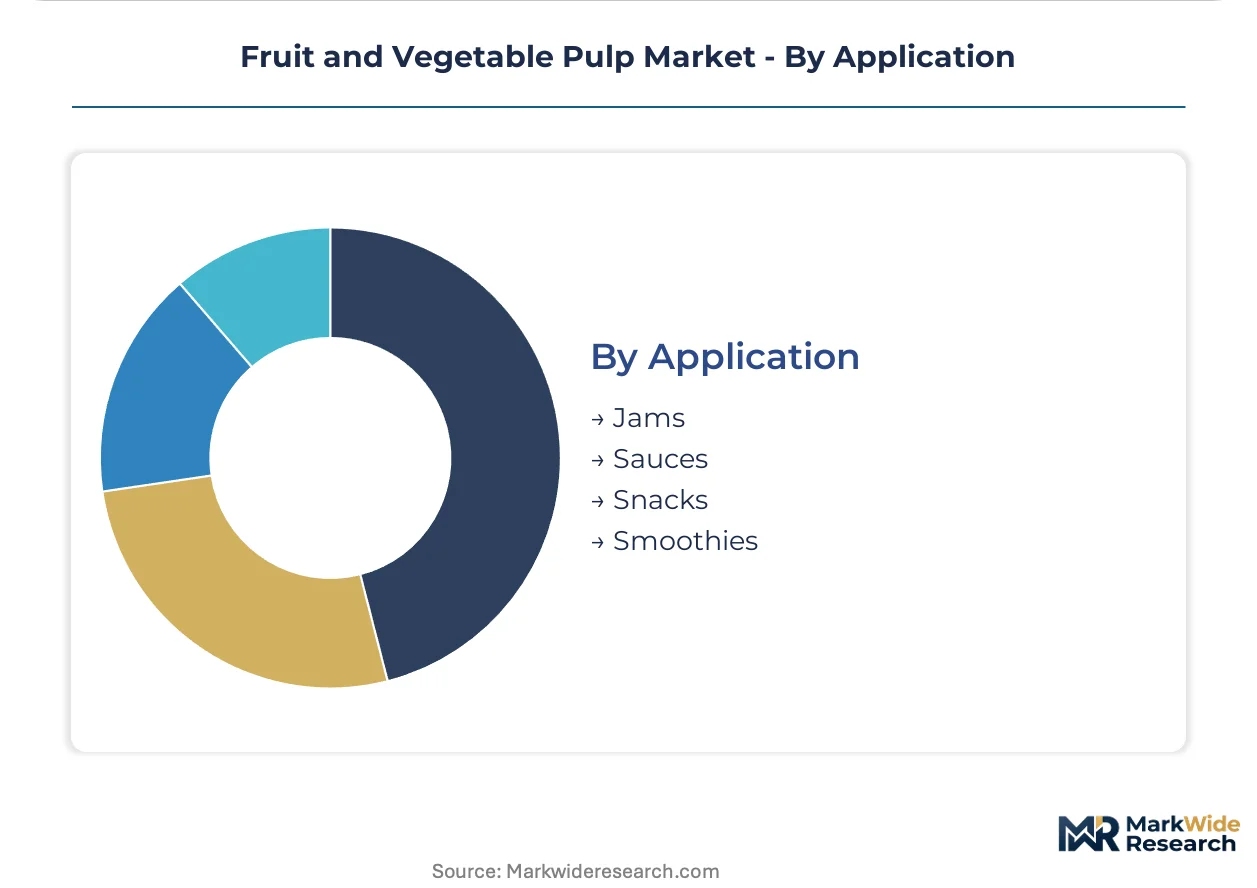
Customer type stratification separates industrial-scale buyers from specialty product developers.
- Smoothies:Cold-pressed pulp with preserved volatile aromatics for premium beverage positioning. Dutch and California manufacturers prioritize enzymatic liquefaction at reduced thermal loads, constrained by equipment supplier order backlogs and aseptic filling capacity bottlenecks from European machinery OEMs.
- Sauces:Viscosity-modifying puree for clean-label tomato and fruit-based formulations.
- Snacks:Fiber-enriched pulp for bakery and extruded product applications.
- Jams:High-pectin concentrate for gelation without commercial pectin additives.
Smoothies lead procurement expansion; snacks gain traction on EFSA dietary fiber guideline revisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. European buyers prioritize carbon-disclosed concentrate for beverage formulations, while Indian processors scale aseptic puree for export arbitrage. The United States concentrates procurement around cold-pressed pulp for premium smoothie channels.
United States
California smoothie manufacturers drive cold-pressed pulp procurement for premium beverage positioning. FDA's FSMA Section 204 traceability mandates accelerate digital lot-tracking infrastructure deployment. Los Angeles and San Diego processing clusters pilot pulsed electric field pasteurization to reduce thermal degradation while maintaining pathogen log reductions.
Germany
Infant food manufacturers in Bavaria concentrate puree procurement for clean-label sauce formulations. EFSA's revised dietary fiber guidelines reformulate bakery specifications toward pulp-enriched carriers. Hamburg and Bremen aseptic filling corridors face carbon disclosure pressure under EU Green Deal Scope 3 mandates.
India
Maharashtra and Gujarat food processors scale mango and guava puree output for European retail private labels. FSSAI mandates incremental labeling disclosures on added pulp percentages, tightening domestic formulation transparency. Mumbai-Pune processing corridors draw multinational co-manufacturers through central PLI scheme incentives for aseptic capacity.
Netherlands
Beverage formulators in Rotterdam and Amsterdam prioritize enzymatic liquefaction for preserved aromatic compounds in smoothie bases. EFSA's evolving pesticide residue thresholds reshape sourcing toward controlled-agriculture suppliers. Dutch machinery OEMs cluster aseptic filling equipment capacity, creating procurement bottlenecks for mid-scale entrants.
Brazil
Citrus and tropical fruit harvest variability creates margin squeeze for non-integrated processors lacking forward-contract coverage. ANVISA enforcement of imported food safety protocols elevates documentation burdens for puree exporters. São Paulo state processing hubs concentrate evaporative concentrate capacity for reduced-logistics-cost beverage formulations.
Fruit and Vegetable Pulp Market Competitive Landscape
Capability concentration sits with flavor-system integrators; scale advantage sits with retail-shelf controllers. The vendor base stratifies across three tiers: European specialists with captive extraction technology, South Asian farm-integrated processors, and multinational beverage conglomerates with captive pulp absorption. Consolidation pressure intensifies as commodity grades compress margins and traceability investments favor integrated operators. Dominant competitive moves include backward integration into farm-origin contracts and digital procurement platform deployment to disintermediate traditional brokers.
Within the European specialist tier, Dohler GmbH and AGRANA Beteiligungs-AG exemplify flavor-system integrators sustaining premium positioning through beverage concentrate formulation. ABC Fruits anchors the South Asian farm-integrated archetype through direct grower partnerships in regional puree specialization. PepsiCo, Inc. occupies the scale-driven multinational position, controlling retail shelf space for smoothie and snack applications that absorb bulk pulp volumes.
| Leading Market Players |
|---|
| Keventer Agro Limited |
| Conagra Brands, Inc. |
| PepsiCo, Inc. |
| ABC Fruits |
| Dohler GmbH |
| AGRANA Beteiligungs-AG |
| Pursuit Industries Private Limited |
| Iprona AG |
| Kiril Mischeff Limited |
| Others |
Value Network & Pricing Analysis
Maharashtra and Gujarat processing corridors concentrate aseptic puree capacity for European retail private labels, translating harvest-lot traceability investments into pricing leverage over Southeast Asian competitors. The FDA's Foreign Supplier Verification Program and EFSA's pesticide residue thresholds elevate compliance costs that filter through to concentrate premiums, while India's PLI scheme incentives compress domestic production economics against export arbitrage.
Pricing Analysis
Long-term offtake contracts dominate procurement between multinational beverage manufacturers and integrated processors, insulating volume buyers from spot-market volatility in Brazilian citrus and tropical fruit inputs. Three-tier pricing structure across premium cold-pressed, standard aseptic puree, and economy-grade concentrate levels reflects differentiation by enzymatic processing intensity and carbon disclosure certification. Pricing pressure stems from commodity pulp commoditization as branded concentrate formulations capture upstream value. Mid-scale processors lacking forward-contract coverage exhibit highest price sensitivity; nutraceutical extract buyers demonstrate lowest sensitivity due to polyphenol standardization premiums.
Supply Chain Analysis
Export-control regimes on aseptic filling equipment from Dutch and German machinery OEMs constrain capacity expansion for mid-scale entrants in India and Brazil. Supply concentrates in India, Brazil, and the Netherlands, with Indian processors drawing from Maharashtra mango and guava growers while Dutch formulators rest on enzymatic liquefaction technology. Raw material dependencies include citrus fruit harvests, sterile bag packaging, and cold-press equipment components. Single-source vulnerability clusters with European machinery suppliers. Distribution runs through direct farm-to-processor contracts with digital lot-tracking documentation displacing traditional broker channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fruit and vegetable pulp markets recover cyclically from input cost volatility as beverage manufacturers restock smoothie and juice formulations following weather-driven harvest disruptions. Procurement patterns normalize toward premium cold-pressed specifications as retail private labels elevate clean-label requirements.
For Market Incumbents: Harden traceability infrastructure investments against FDA FSMA Section 204 documentation burdens while compressing intermediary margins through direct farm-origin contract expansion. Backward integration into controlled-agriculture suppliers in Maharashtra and Gujarat insulates against EFSA pesticide residue threshold revisions. Channel control through digital procurement platforms displaces traditional broker relationships.
For New Entrants and Emerging Players: Mid-scale nutraceutical extract production in Germany and Switzerland represents the most penetrable entry point, bypassing capital-intensive aseptic filling bottlenecks through third-party toll processing arrangements. India's emerging PLI scheme corridors offer white-space capacity for European retail private label co-manufacturing. Go-to-market execution through verified polyphenol standardization commands specification premiums from functional beverage formulators.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors farm-integrated processors with captive cold-press and enzymatic liquefaction capabilities over commodity-grade operators. Long-term viability across the analysis window rests on carbon-disclosed concentrate capacity securing EU Green Deal preferred supplier status. Acquisition target archetype: South Asian puree specialists with direct grower partnerships and aseptic certification. Signal to watch: FDA enforcement intensity on Foreign Supplier Verification Program documentation as inflection indicator for import-dependent processor valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Capacity Expansion | PLI scheme incentives in Maharashtra draw multinational co-manufacturers into export-oriented puree production. |
| Backward Integration into Farm Contracts | Direct grower partnerships in Gujarat transfer quality assurance liability upstream while compressing broker margins. |
| Digital Traceability Platform Deployment | FDA FSMA Section 204 mandates accelerate lot-tracking infrastructure investments across North American processing facilities. |
| Cold-Press Technology Licensing | Enzymatic liquefaction equipment suppliers hybridize toward integrated process-intelligence platforms in California pilot programs. |
| Carbon Certification Program | EU Green Deal Scope 3 disclosure requirements secure preferred supplier status with sustainability-scored retail private labels. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade databases, regulatory filings, and industry association reports to validate procurement pattern shifts and capacity expansion timelines. Primary interviews engaged processing plant managers, beverage manufacturer procurement leads, aseptic equipment suppliers, and food safety compliance officers across India, Germany, the Netherlands, and the United States. Secondary sources included FDA FSMA guidance documents, EFSA dietary fiber guideline revisions, FSSAI labeling mandates, EU Green Deal technical standards, and customs trade flow records. Bottom-up capacity assessments triangulated against top-down demand projections from beverage formulation trends.
Forecast inputs incorporate product type segmentation across puree, concentrate, and extract categories; end-use differentiation between food processing, beverage, and nutraceutical channels; and application-specific viscosity and shelf-stability requirements. CAGRs derived from historical volume trajectories adjusted for PLI scheme capacity additions, cold-press technology adoption curves, and regulatory compliance cost escalations. Industry-specific inputs include enzymatic liquefaction equipment order backlogs, aseptic filling capacity utilization rates, and harvest variability indices for Brazilian citrus and Southeast Asian tropical fruits.
Practitioners should monitor FDA enforcement intensity on Foreign Supplier Verification Programs, EFSA pesticide residue threshold revisions, and weather-driven harvest disruptions in major producing regions for early signals of forecast deviation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Celery Juice Market
Fruits and Vegetables
Rubus Idaeus (Raspberry) Seed Oil Market
Fruits and Vegetables
Boysenberry Market
Fruits and Vegetables
Dragon Fruit Powder Market
Fruits and Vegetables
Global Bean Sprouts Market
Fruits and Vegetables
Kuwait Vegetables and Fruits Market
Fruits and Vegetables
Mexico Lime Market
Fruits and Vegetables
Ackee Market
Fruits and Vegetables
Dried Fruits Market
Fruits and Vegetables
Dried Apple Peel Market
Fruits and Vegetables
Spring Market
Fruits and Vegetables
Water Chestnut Market
Fruits and Vegetables
Peach Extract Market
Fruits and Vegetables
Brown Shimeji Mushroom Market
Fruits and Vegetables
Camellia Oil Market
Fruits and Vegetables
Mexico Fruits & Vegetables Market