
 Brined Vegetable Market | 2026-2036
Brined Vegetable Market Size, Share, and Industry Trends Forecast 2026-2036
Brined Vegetable Market Outlook
Clean-label fermentation is fragmenting traditional preservative-dependent supply chains. Kraft Heinz leverages its retail distribution scale to dominate shelf-stable pickled cucumbers across North American supermarkets. Mt. Olive Pickle Company anchors regional production gravity in North Carolina with specialized glass-jar packaging lines. China Minzhong Food competes on cost-optimized brine processing for industrial snack manufacturers.
Brined vegetables are plant products preserved in acidified salt solutions, typically containing 2-6% acetic acid and 5-10% sodium chloride, manufactured through controlled fermentation or direct acidification to inhibit spoilage organisms and extend shelf stability for commercial food manufacturing. The product type dimension shows pickled cucumbers sustaining the largest volume pool while fermented carrots represent the fastest-growing sub-category driven by functional food positioning. Distribution through online retail channels is accelerating as direct-to-consumer subscription models capture margin pools previously held by supermarket intermediaries.
FDA food safety regulations and EFSA additive authorization frameworks govern permissible preservative thresholds and labeling declarations for acidified foods sold across the United States and European Union. BIS certification requirements in India and GB standards in China impose additional compositional testing for imported brined vegetable shipments. Stakeholders must monitor evolving sodium reduction mandates and fermentation process validation standards to maintain cross-border market access.
Market Dynamics
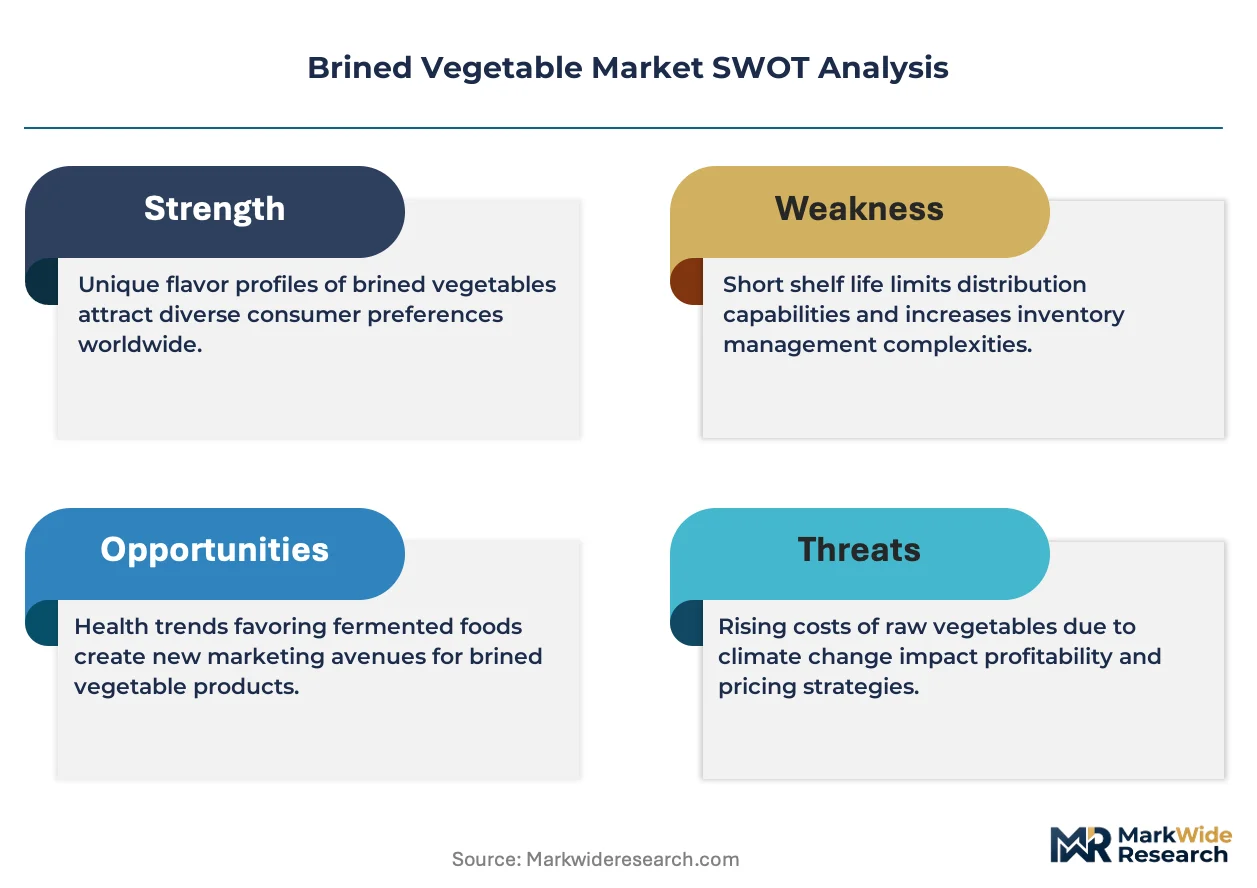
Sodium reduction mandates from FDA and EFSA are forcing reformulation of traditional brine recipes, compressing shelf-life performance while clean-label fermentation protocols fragment established preservative-dependent supply chains.
Growth Catalysts
- EFSA additive authorization frameworks:Accelerated approval pathways for natural fermentation starters enable faster product launches across European Union retail channels.
- Food service menu expansion:Restaurant operators in the United States are integrating fermented vegetables into bowl concepts and sandwich builds, pulling volume from industrial processors.
- China's GB standards harmonization:Streamlined import testing protocols reduce clearance delays for acidified vegetable shipments entering domestic distribution networks.
Market Restraints
- Glass packaging cost volatility:Energy-intensive manufacturing of specialized jars creates margin pressure for regional producers dependent on North Carolina production clusters.
- Supply concentration in Heilongjiang:China's snow vegetable processing belt dominates industrial-grade brined cabbage, creating single-source vulnerability for snack manufacturers.
- Acetic acid substitution threat:Vinegar-based rapid acidification methods displace slower fermentation protocols, eroding premium positioning of traditional barrel-aged products.
Strategic Opportunities
- Direct-to-consumer subscription channels:Online retail platforms capture margin pools previously held by supermarket intermediaries through recurring delivery models.
- Fermented carrot functional positioning:Probiotic content claims unlock pharmacy and wellness retail placements beyond conventional grocery aisles.
- India PLI scheme for food processing:Production-linked incentives reduce capital barriers for cold-chain infrastructure supporting regional brined vegetable manufacturing.
Industry Challenges
- Microbiologist talent scarcity:Fermentation process validation requires specialized food safety expertise that outpaces vocational training program output.
- Legacy ERP integration:Batch-tracking systems for acidified foods demand retrofitting of manufacturing execution software to meet FDA traceability mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brined Vegetable Market |
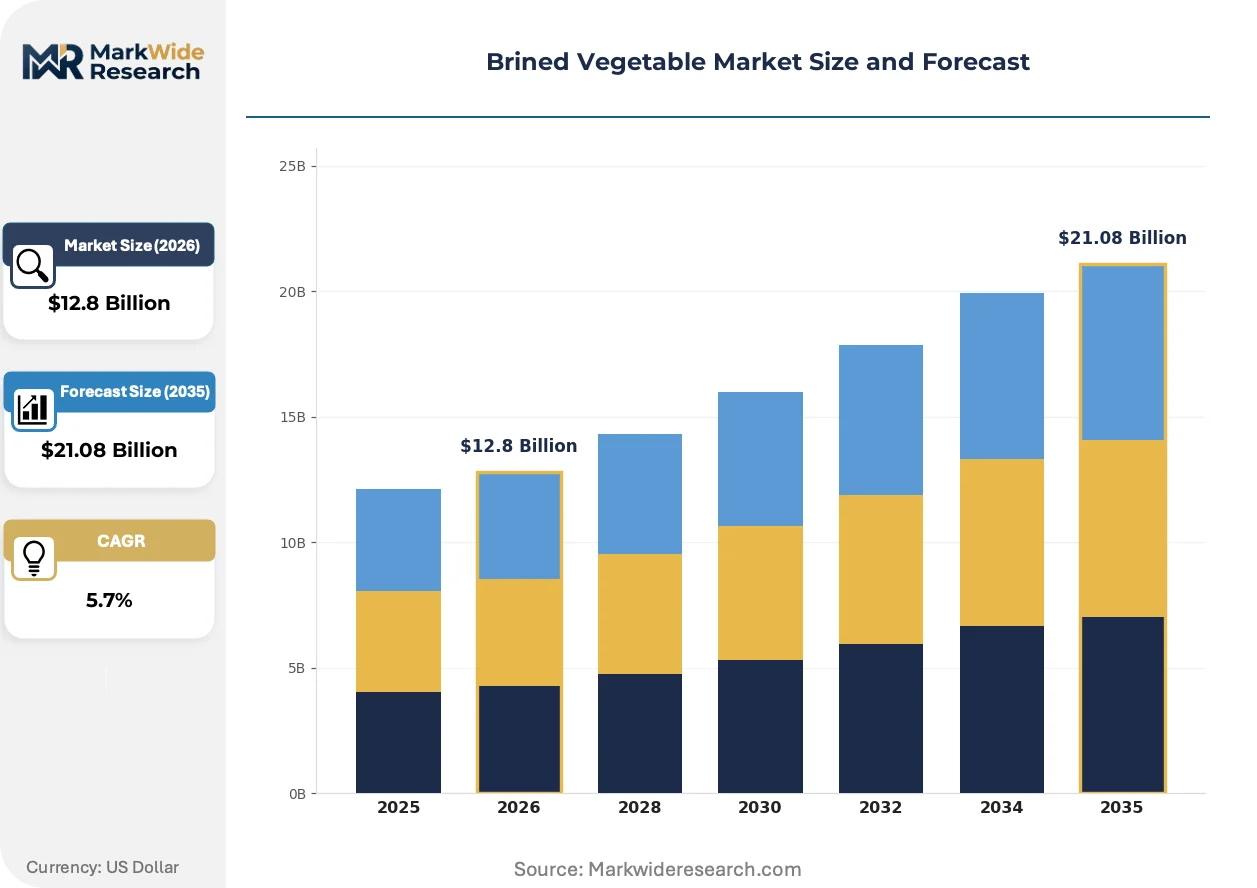
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pickled Cucumbers, Pickled Peppers, Fermented Carrots, Olives End User: Food Service, Retail Consumers, Industrial Users, Snack Manufacturers Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesalers Packaging Type: Glass Jars, Plastic Containers, Cans, Pouches |
| Companies Covered | Conagra Brands, Kraft Heinz, Mt. Olive Pickle Company, Ripon Pickle, PentaPure Foods, AlfaFrost, HAMPTONS BRINE, China Minzhong Food, JINAN A-FOOD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brined Vegetable Market Strategic Shifts
Controlled atmosphere fermentation and precision acidification technologies are compressing production cycles while regulatory sodium thresholds and direct-to-consumer channels reshape competitive positioning across established supply networks.
Precision-controlled fermentation systems using sensor-monitored pH and temperature profiles enable consistent probiotic counts without batch-to-batch variation. Mid-sized processors in Germany and the United States are retrofitting existing tank infrastructure with these monitoring suites. Real-time quality data is rendering obsolete the laboratory-dependent release protocols that previously added days to production timelines.
EU Green Deal farm-to-fork sustainability targets impose binding sodium reduction pathways for processed foods sold across member states. Brined vegetable manufacturers must reformulate recipes to maintain shelf stability at lower salt concentrations without synthetic preservative additions. Acidified cucumber and cabbage categories face the steepest compliance curves as EFSA reviews challenge historical GRAS determinations for traditional brine concentrations.
Direct-to-consumer subscription models bypass conventional wholesale distribution tiers, capturing consumer margin through recurring delivery commitments. Fermented vegetable specialists in California and Bavaria are building dedicated fulfillment infrastructure for temperature-controlled last-mile logistics. United States urban markets show the fastest channel rotation as meal-kit bundling and wellness-focused curation replace supermarket center-store placement as the primary discovery mechanism.
Brined Vegetable Market Segmentation
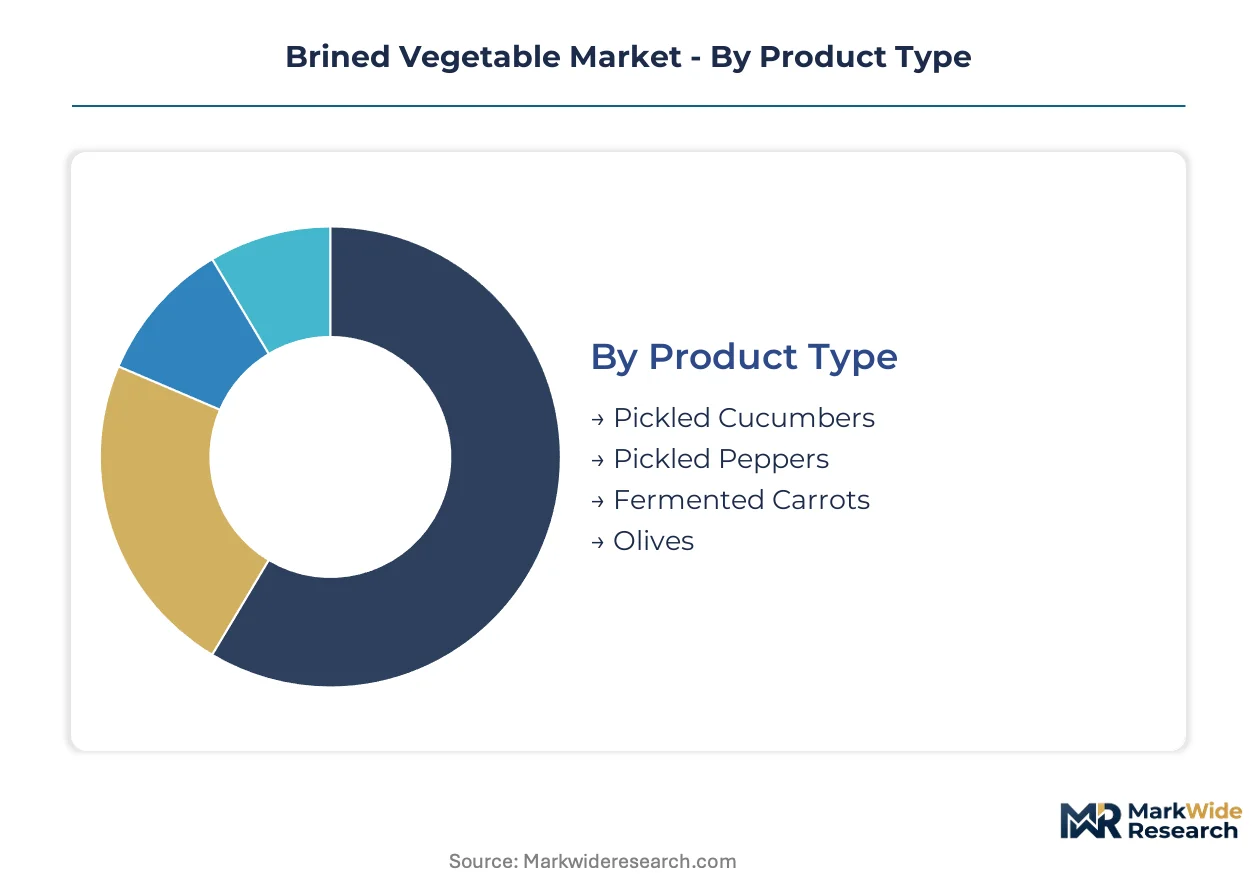
Brined vegetable manufacturers configure production assets around four intersecting dimensions that determine margin capture. Product type dictates fermentation infrastructure investment. End-user concentration shapes brine formulation and shelf-life engineering.
Product Type:
Mature segments dominate volume throughput while emerging categories reshape growth trajectories across fermentation capacity planning.
- Pickled Cucumbers:Acidified salt solutions containing 2-6% acetic acid and 5-10% sodium chloride preserve cucumber tissue through controlled fermentation or direct acidification. United States supermarket channels absorb the largest volume concentration, though FDA sodium reduction mandates compress traditional brine concentration tolerances.
- Fermented Carrots:Lacto-fermented carrot strips deliver elevated probiotic counts compared to vinegar-acidified alternatives, positioning the segment for pharmacy and wellness retail expansion. Germany shows the steepest demand acceleration as EFSA additive authorization frameworks validate natural fermentation starter claims.
- Pickled Peppers:Capsicum varieties in acidified brine serve industrial sauce manufacturers and food service operators requiring consistent heat profiles.
- Olives:Mediterranean-origin fruit processed in lye-cured or brine-cured methods targets premium retail placement with extended aging protocols.
Pickled cucumbers handle the majority of throughput; fermented carrots are climbing the fastest on share.
End User:
Cost tier stratification separates commodity-scale industrial buyers from premium-positioned retail and food service accounts.
- Food Service:Restaurant operators integrate fermented vegetables into bowl concepts and sandwich builds, pulling volume from industrial processors as menu applications expand.
- Retail Consumers:Direct-to-consumer subscription models capture margin pools previously held by supermarket intermediaries through recurring delivery commitments.
- Industrial Users:Bulk brined vegetable inputs supply condiment manufacturers and ready-meal producers with standardized acidification parameters.
- Snack Manufacturers:China-based processors dominate industrial-grade brined cabbage supply for packaged snack flavoring, creating single-source vulnerability.
Industrial users move the highest absolute tonnage; food service is expanding most quickly as menu integration accelerates.
Distribution Channel:
Channel margin capture diverges sharply between legacy wholesale tiers and emerging direct-to-consumer infrastructure.
- Supermarkets:Center-store placement remains the primary discovery mechanism for mass-market pickled cucumber and olive categories.
- Online Retail:Temperature-controlled last-mile logistics enable fermented vegetable specialists in California and Bavaria to bypass conventional distribution. United States urban markets show the fastest rotation as meal-kit bundling replaces wholesale discovery.
- Convenience Stores:Single-serve pouch formats target immediate consumption occasions with reduced shelf-space requirements.
- Wholesalers:Food service redistribution networks consolidate fragmented regional production into national account servicing.
Supermarkets retain the dominant throughput position; online retail is gaining share fastest through subscription conversion.
Packaging Type:
Material cost volatility and sustainability positioning drive format selection across price tiers.
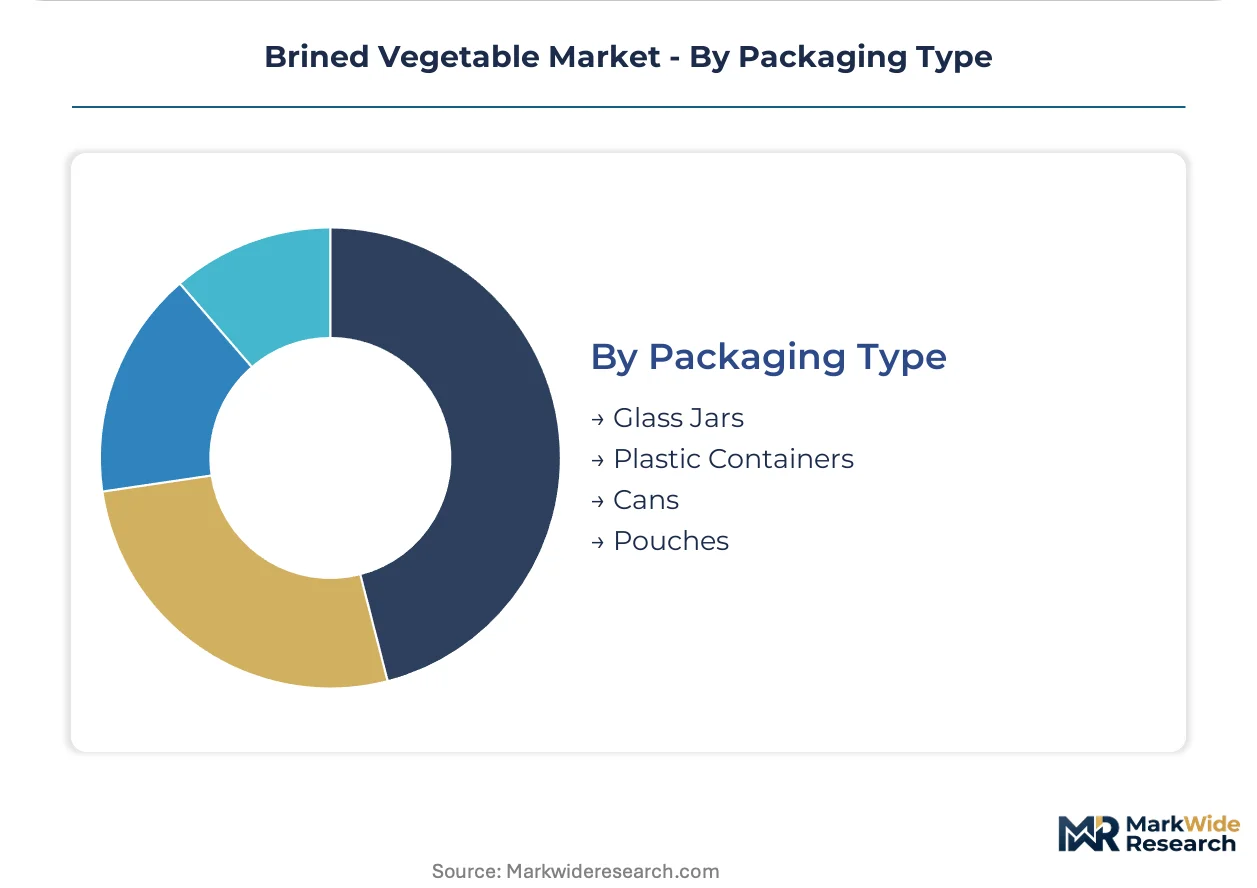
- Glass Jars:Specialized packaging lines in North Carolina production clusters serve premium retail positioning, though energy-intensive manufacturing creates margin pressure during fuel price spikes.
- Plastic Containers:Polymer-based formats reduce shipping weight for industrial bulk shipments and food service portion packs.
- Cans:Metal packaging extends shelf stability for export shipments facing extended transit timelines.
- Pouches:Flexible formats enable single-serve convenience store placement with reduced material cost per unit.
Glass jars command the premium tier volume; pouches are expanding fastest as convenience channel penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports industrial-grade brined cabbage to snack manufacturers across Asia and North America, while Germany and the United States dominate premium fermented vegetable trade flows into European and domestic retail channels respectively.
United States
Supermarket center-store placement drives pickled cucumber volume, though FDA sodium reduction mandates compress traditional brine concentration tolerances. Restaurant operators integrate fermented vegetables into bowl concepts and sandwich builds, pulling volume from industrial processors. North Carolina production clusters anchor regional manufacturing gravity with specialized glass-jar packaging lines.
Germany
EFSA additive authorization frameworks validate natural fermentation starter claims, accelerating pharmacy and wellness retail expansion for probiotic-positioned products. Bavaria-based specialists build dedicated fulfillment infrastructure for temperature-controlled last-mile logistics serving urban subscription markets. Precision-controlled fermentation monitoring suites retrofit existing tank infrastructure across mid-sized processors.
China
GB standards harmonization streamlines import testing protocols for acidified vegetable shipments entering domestic distribution networks. Heilongjiang's snow vegetable processing belt dominates industrial-grade brined cabbage supply, creating single-source vulnerability for snack manufacturers. Cost-optimized brine processing competes for industrial snack manufacturer contracts.
India
Production-linked incentive schemes reduce capital barriers for cold-chain infrastructure supporting regional brined vegetable manufacturing. BIS certification requirements impose additional compositional testing for imported shipments. Domestic processors target food service redistribution networks consolidating fragmented regional production.
Japan
Traditional fermentation protocols maintain premium positioning against vinegar-based rapid acidification substitutes. METI standards govern additive thresholds for acidified foods in retail channels. Regional processors balance heritage barrel-aging methods with sensor-monitored production cycle compression.
Brined Vegetable Market Competitive Environment
On the supply side, the industry is bifurcated between multinational packaged food conglomerates and specialized regional fermenters. Scale-driven players leverage retail distribution networks for shelf-stable volume, while craft-oriented specialists capture margin through direct-to-consumer channels. Three archetypes dominate: diversified food conglomerates with pickle portfolios, regional heritage specialists with localized production gravity, and cost-optimized industrial processors serving bulk ingredient buyers. Competitive moves center on backward integration into fermentation capacity and geographic expansion through distributor partnerships.
Among diversified packaged food conglomerates, Kraft Heinz and Conagra Brands exemplify scale-driven archetypes leveraging supermarket channel dominance. Kraft Heinz anchors North American shelf-stable pickled cucumber placement through retail distribution scale. Conagra Brands occupies a position within the diversified food manufacturer tier with broad preserved vegetable portfolios. Mt. Olive Pickle Company represents the regional heritage specialist archetype with concentrated production infrastructure.
| Leading Market Players |
|---|
| Conagra Brands |
| Kraft Heinz |
| Mt. Olive Pickle Company |
| Ripon Pickle |
| PentaPure Foods |
| AlfaFrost |
| HAMPTONS BRINE |
| China Minzhong Food |
| JINAN A-FOOD |
| Others |
Value Chain & Pricing Dynamics
The Qingdao–Los Angeles maritime corridor's freight volatility compresses margins for Heilongjiang-origin brined cabbage shipments while amplifying price spreads between barrel-aged premium positioning and rapid-acidification economy tiers across North American snack manufacturer procurement.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates traditional barrel-aged fermentation from vinegar-acidified rapid processing and industrial bulk brine supply. Price differentiation hinges on fermentation protocol certification and glass-jar packaging energy costs. Pricing pressure stems from FDA sodium reduction mandates forcing reformulation investment without corresponding shelf-life extension. Industrial snack manufacturers exhibit highest price sensitivity; wellness-positioned direct-to-consumer subscribers show lowest.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk assessment for industrial-grade brined cabbage flows. Geographic concentration centers on Heilongjiang, North Carolina, and Bavaria for distinct product tiers. Raw material dependencies encompass acetic acid supply, specialized glass packaging, and fermentation starter cultures. Single-source vulnerability characterizes China's snow vegetable processing belt. Distribution runs through supermarket center-store placement, temperature-controlled direct-to-consumer fulfillment, and food service redistribution networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The brined vegetable market sits in early-cycle expansion as fermented carrot functional positioning penetrates pharmacy and wellness retail channels beyond conventional grocery discovery.
For Market Incumbents: Harden fermentation capacity control through backward integration into Heilongjiang processing assets or North Carolina glass-jar packaging infrastructure. Accelerate EFSA-compliant natural starter certification investment to defend premium positioning against vinegar-acidification substitutes eroding traditional barrel-aged margins.
For New Entrants and Emerging Players: Build out temperature-controlled last-mile fulfillment infrastructure targeting United States urban subscription markets where meal-kit bundling replaces wholesale discovery. Capture pharmacy channel placement through probiotic content validation. Lead with functional wellness curation rather than center-store price competition.
For Investors and Strategic Acquirers: Regional heritage specialists with concentrated North Carolina or Bavaria production gravity present acquisition targets with embedded fermentation expertise and localized distribution relationships. Monitor EFSA sodium reduction enforcement intensity as inflection indicator for reformulation cost compression across premium tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captures margin pools previously allocated to Heilongjiang contract processors while securing supply continuity. |
| Direct-to-Consumer Subscription Launch | Bypasses supermarket intermediary margin extraction through recurring delivery commitments in United States urban markets. |
| EFSA Natural Starter Certification Investment | Validates probiotic content claims for pharmacy channel placement beyond conventional grocery aisle competition. |
| Temperature-Controlled Last-Mile Expansion | Enables California and Bavaria specialists to serve wellness-focused curation models replacing wholesale discovery. |
| Sodium-Reduced Reformulation Program | Anticipates FDA mandate compliance curves while maintaining shelf stability without synthetic preservative additions. |
Study Parameters
Operator-level perspectives from fermentation process engineers, food service procurement directors, retail category buyers, and cold-chain logistics specialists anchored the qualitative base. Primary interview data combined with secondary validation from FDA GRAS determinations, EFSA additive authorization frameworks, GB standards documentation, and customs trade records. Bottom-up volume modeling triangulated against top-down market sizing across producer-reported capacity and channel shipment data.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning product type, end-user concentration, distribution channel, and packaging format. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and channel migration patterns. Forecast inputs incorporated fermentation cycle compression technology adoption curves and sodium reduction mandate compliance timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified conglomerates acquiring regional heritage specialists would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Dragon Fruit Powder Market
Fruits and Vegetables
Mung Beans Market
Fruits and Vegetables
Gold Kiwifruit Market
Fruits and Vegetables
Farro Market
Fruits and Vegetables
Basil Leaves Market
Fruits and Vegetables
Cyanidin Market
Fruits and Vegetables
Edible Flowers Market
Fruits and Vegetables
Europe Kiwi Fruit Market
Fruits and Vegetables
South America Lime Market
Fruits and Vegetables
Fruit Punnet Market
Fruits and Vegetables
Kuwait Vegetables and Fruits Market
Fruits and Vegetables
Aubergine Market
Fruits and Vegetables
White Mushroom Market
Fruits and Vegetables
Global Fruit Pomace Market
Fruits and Vegetables
Clean Label Fruit and Vegetable Powder Market
Fruits and Vegetables
Turkish Figs Market