
 United States Archery Equipment Market | 2026-2036
United States Archery Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
United States Archery Equipment Market Intelligence
The capability gap between carbon fiber manufacturing scale and traditional bow assembly is collapsing as automated layup processes reduce entry barriers. Mathews Archery Inc. anchors its premium compound bow line through captive machining operations in Wisconsin. Bear Archery leverages legacy recurve expertise to dominate the youth and entry-level segments. Hoyt Archery sustains Olympic-grade reputation through precision riser forging and sponsorship of USA Archery competitive programs.
Archery equipment encompasses projectile-launching apparatus—principally recurve bows, compound bows, and crossbows—engineered with draw weights from 15 to 70 pounds and axle-to-axle lengths between 30 and 38 inches for target consistency and hunter maneuverability. The equipment serves recreational shooting, competitive tournament play, and regulated game harvesting. Bows command the dominant revenue share due to high replacement cycles and technology turnover in cam systems and limb materials. Carbon fiber arrows represent the fastest-expanding material segment as spine consistency tolerances tighten and bowhunters prioritize penetration performance. Accessories concentrate margin pools through high-frequency replacement of releases, sights, and stabilizers.
The National Field Archery Association establishes tournament equipment standards while state wildlife agencies mandate minimum draw weights and broadhead specifications for hunting licensure. OSHA workplace safety guidelines affect manufacturing facility compliance for domestic producers. ASTM F1443 testing protocols govern youth bow kinetic energy limits. Stakeholders must monitor evolving crossbow classification debates in state legislatures and the potential for federal excise tax restructuring under Pittman-Robertson reauthorization discussions.
Market Dynamics
Automated carbon fiber layup systems are collapsing the traditional capability gap between raw material production and bow assembly, compressing entry barriers for precision limb manufacturing while reshaping competitive positioning across the value chain.
Growth Catalysts
- ASTM F1443 youth safety protocols:Standardized kinetic energy limits for juvenile bows have streamlined school procurement processes, accelerating curriculum adoption in Texas and Florida public athletic programs.
- Carbon fiber spine consistency:Tighter manufacturing tolerances in arrow shaft production are driving replacement cycles among bowhunters prioritizing penetration reliability.
- Texas youth tournament infrastructure:Dedicated range construction and competitive league formation are concentrating equipment demand in the state's metropolitan corridors.
Market Restraints
- Prepreg carbon fiber supply concentration:Domestic bow manufacturers remain dependent on Toray and Hexcel fiber supplies, exposing margin pressure from aerospace contract prioritization.
- Crossbow classification friction:State wildlife agencies maintain inconsistent statutory definitions, complicating interstate commerce and inventory allocation for multi-state retailers.
- Aluminum riser machining capex:Precision forging equipment for Olympic-grade recurve production requires seven-figure capital commitments, limiting supplier diversification.
Strategic Opportunities
- 3D archery course expansion:Unpenetrated municipal park systems in the Mountain West present white space for equipment-lease programs tied to tourism infrastructure.
- Pittman-Robertson reauthorization:Potential federal excise tax restructuring could redirect conservation funding toward range development, stimulating equipment grant programs.
- Smart sight convergence:Integration of rangefinding optics with mobile ballistics applications is creating premium accessory attachment points for tech-forward hunters.
Industry Challenges
- Master bowyer skill scarcity:Traditional recurve limb lamination expertise is concentrating among retiring craftsmen, constraining handmade premium segment output.
- OSHA silica compliance:Carbon fiber cutting and finishing operations face respiratory protection mandates requiring facility reconfiguration and ongoing monitoring investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Archery Equipment Market |
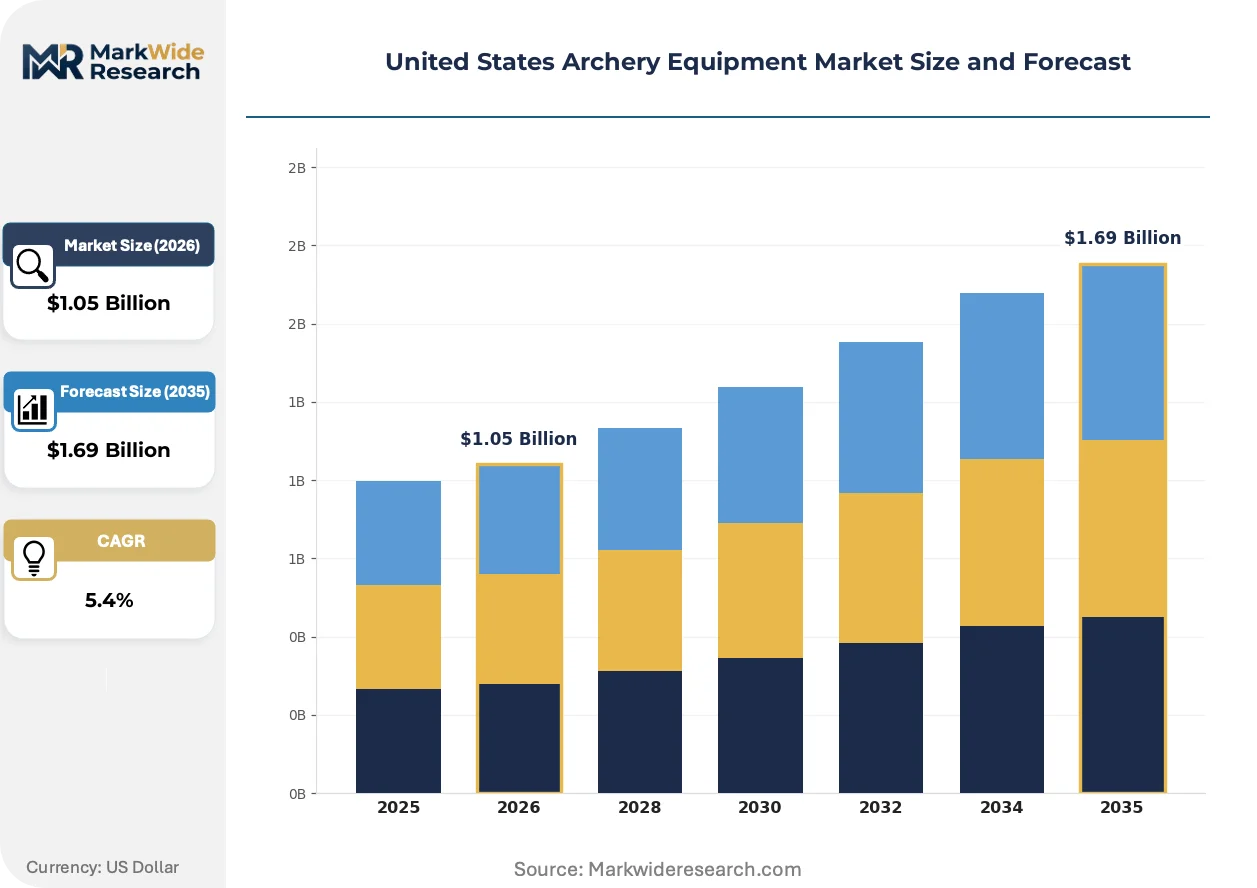
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.69 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bows, Arrows, Quivers, Accessories End User: Recreational Users, Professional Archers, Schools, Sports Teams Material: Wood, Carbon Fiber, Aluminum, Composite Distribution Channel: Online Retailers, Specialty Stores, Sporting Goods Stores, Trade Shows |
| Companies Covered | Bear Archery, PSE Archery LLC, Mathews Archery Inc., New Archery Products Inc., Escalade Inc., Hoyt Archery, Bowtech, Scott Archery, Easton Technical Products Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Archery Equipment Market Strategic Shifts & Innovations
Digital manufacturing workflows and materials science advances are compressing product development cycles while fragmenting traditional segment boundaries between recreational, competitive, and hunting equipment categories.
Carbon fiber arrow shafts with sub-0.001-inch spine deviation tolerances are supplanting aluminum and traditional carbon-aluminum hybrid constructions in the premium hunting segment. Bowhunters in the Midwest and Southeast are adopting these shafts at accelerating rates despite 40-60% price premiums. The shift is compressing margin pools for legacy arrow manufacturers while rewarding suppliers with captive prepreg consolidation capabilities.
OSHA workplace safety guidelines governing composite dust exposure are mandating upgraded ventilation and personal protective equipment standards across domestic bow manufacturing facilities. Wisconsin and Illinois machining operations face the most acute compliance timelines due to state-level plan adoption. Smaller assembly shops are responding through contract manufacturing arrangements with larger, compliant facilities rather than capital investment.
Direct-to-consumer sight and release customization platforms are fragmenting traditional pro-shop distribution for accessories. Archery retailers in Texas and California are unbundling fitting services from product sales, charging standalone consultation fees. The model is most visible in suburban markets where Amazon same-day delivery has eroded inventory carrying rationale for high-turn consumables.
United States Archery Equipment Market Segmentation
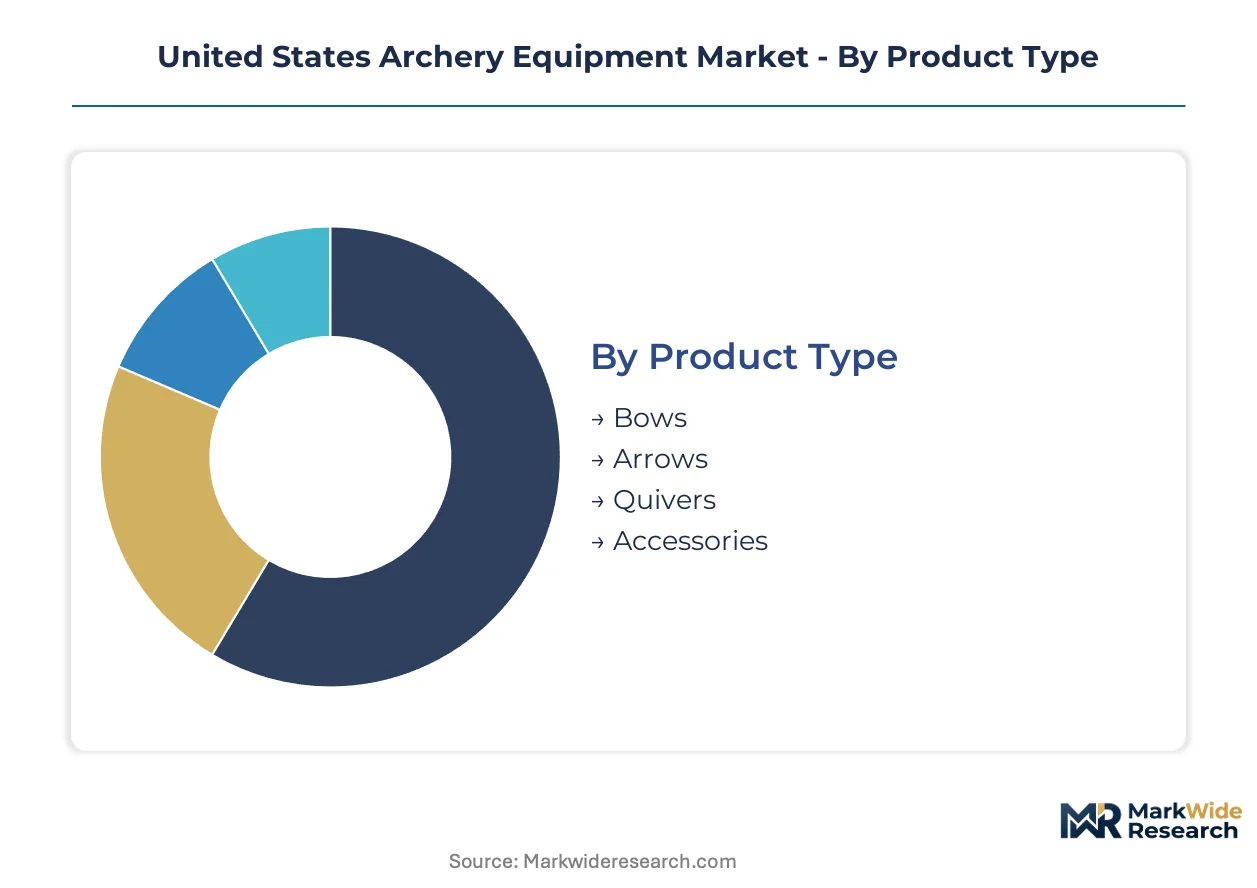
Equipment procurement across the United States archery market fragments along regulatory compliance lines, with ASTM F1443 youth safety mandates and state wildlife agency hunting specifications creating distinct purchasing workflows for institutional versus individual buyers.
Product Type:
ASTM International standards differentiate kinetic energy limits between youth bows and adult equipment, while state wildlife agencies mandate minimum draw weights for hunting licensure that reshape bow versus crossbow demand patterns.
- Bows:Compound and recurve configurations engineered with draw weights from 15 to 70 pounds and axle-to-axle lengths between 30 and 38 inches. Texas youth tournament infrastructure and dedicated range construction are concentrating replacement demand in metropolitan corridors where technology turnover in cam systems accelerates upgrade cycles.
- Arrows:Carbon fiber shafts with sub-0.001-inch spine deviation tolerances are supplanting aluminum constructions in the premium hunting segment. Bowhunters in the Midwest and Southeast are adopting these despite significant price premiums, compressing margin pools for legacy manufacturers lacking captive prepreg consolidation capabilities.
- Quivers:Hip-mounted and bow-mounted configurations designed for target consistency and hunter maneuverability, with high-frequency replacement driven by wear patterns in field conditions.
- Accessories:Releases, sights, and stabilizers concentrate margin pools through rapid replacement cycles and technology convergence with rangefinding optics.
Bows handle the majority of throughput; arrows are expanding most quickly on share as spine consistency tolerances tighten.
End User:
Procurement authority varies sharply across customer types, with school athletic programs subject to standardized district purchasing protocols while individual enthusiasts navigate direct-to-consumer platforms.
- Recreational Users:Weekend shooters and backyard hobbyists purchasing entry-level compound and recurve equipment through online retailers and sporting goods chains.
- Professional Archers:Tournament competitors requiring Olympic-grade recurve risers with precision forging tolerances, sourcing through specialty pro-shops with fitting services.
- Schools:Public and private athletic programs in Texas and Florida accelerating curriculum adoption under state physical education mandates, with ASTM F1443 compliance streamlining procurement processes.
- Sports Teams:Collegiate and club competitive programs investing in standardized equipment inventories for tournament travel and team training protocols.
Recreational users dominate absolute volume; schools are gaining share fastest as curriculum adoption spreads.
Material:
Supply concentration in aerospace-grade carbon fiber prepreg creates tiered access to performance materials, with Toray and Hexcel contract prioritization exposing domestic bow manufacturers to margin pressure.
- Wood:Traditional limb laminations for recurve bows requiring master craftsman expertise that is concentrating among retiring specialists, constraining handmade premium segment output.
- Carbon Fiber:Automated layup processes are collapsing the capability gap between raw material production and bow assembly, compressing entry barriers for precision limb manufacturing while reshaping competitive positioning.
- Aluminum:Riser forgings for Olympic-grade equipment requiring seven-figure capital commitments for precision machining equipment, limiting supplier diversification.
- Composite:Hybrid constructions blending fiberglass and carbon fiber for cost-optimized youth and entry-level segments.
Carbon fiber commands the steepest expansion trajectory; aluminum retains premium positioning in competitive equipment.
Distribution Channel:
Channel economics fragment along service intensity lines, with pro-shops unbundling fitting consultations from product sales in response to Amazon same-day delivery erosion.
- Online Retailers:Direct-to-consumer platforms capturing accessory sales through customization tools, with suburban markets showing highest penetration for high-turn consumables.
- Specialty Stores:Pro-shop operators in Texas and California charging standalone consultation fees as fitting services separate from equipment transactions.
- Sporting Goods Stores:Mass-market retailers carrying entry-level bows and arrows for casual recreational users with limited technical support.
- Trade Shows:Industry exhibitions serving product launch venues and bulk procurement events for institutional buyers and competitive team managers.
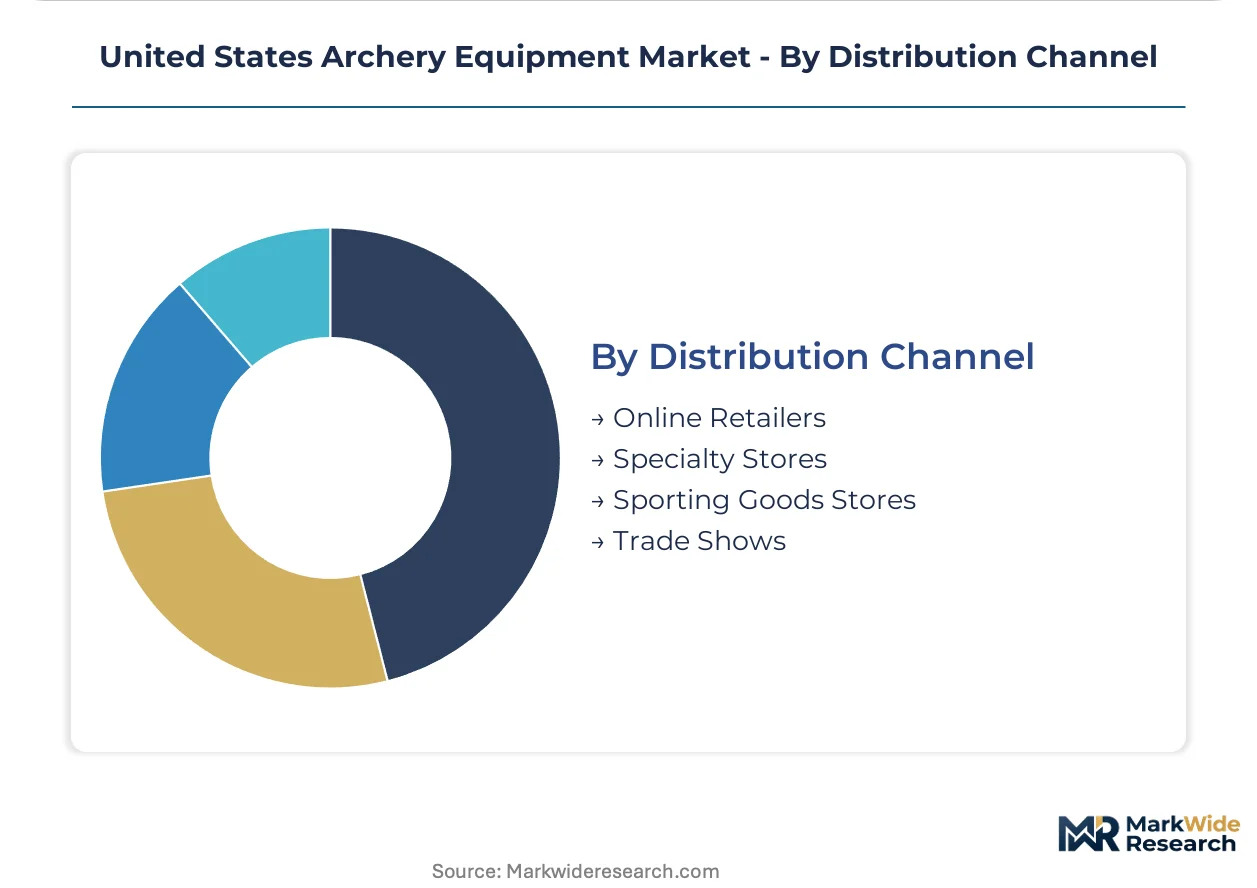
Specialty stores handle the majority of high-value transactions; online retailers are climbing the fastest on share for accessories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas buyers exhibit the lowest price elasticity in youth tournament equipment, while recreational shooters in the Mountain West and Midwest remain highly sensitive to entry-level compound bow pricing. School procurement in Florida and California operates on standardized district budgets that compress margin capture for institutional sales.
Texas
Metropolitan corridor demand concentrates in Houston, Dallas-Fort Worth, and Austin, where dedicated range construction and competitive league formation drive equipment turnover. State physical education mandates under Texas Education Agency guidelines accelerate curriculum adoption in public school athletic programs. Youth tournament infrastructure in the Dallas suburbs outpaces national participation rates, compressing replacement cycles for carbon fiber arrows and compound bows.
Florida
Recreational bowhunting participation in the Panhandle and Central Florida generates steady demand for crossbow and compound configurations. Florida Fish and Wildlife Conservation Commission regulations mandate minimum draw weights for deer and hog hunting licensure, reshaping equipment specifications for resident hunters. Orlando and Tampa metropolitan areas host expanding 3D archery course developments that stimulate accessory sales through tourism-linked lease programs.
California
Suburban pro-shop operators in Los Angeles and San Francisco Bay Area markets are unbundling fitting services from equipment transactions, charging standalone consultation fees. California Department of Education physical education standards incorporate archery curriculum options, though adoption lags Texas and Florida due to facility cost barriers. Precision machining operations in Southern California supply riser components to Olympic-grade recurve assemblers serving competitive programs.
Illinois
OSHA state-plan adoption in Illinois imposes accelerated compliance timelines for carbon fiber cutting and finishing operations, forcing facility reconfiguration among Chicago-area manufacturers. Recreational shooting clubs in the collar counties sustain steady demand for entry-level compound bows through indoor range memberships. The state's central location supports distribution hub operations serving Midwest retail chains.
Michigan
Bowhunting culture in the Upper Peninsula and northern Lower Peninsula sustains seasonal demand spikes for broadhead-tipped arrows and tree-stand compatible compound configurations. Michigan Department of Natural Resources crossbow classification debates create inventory allocation friction for retailers serving multi-state customers. Detroit metropolitan machine shops supply aluminum riser forgings to premium recurve assemblers on contract basis.
United States Archery Equipment Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with captive machining operations and automated carbon fiber layup capabilities separating premium compound and recurve producers from assembly-only competitors. The vendor base clusters around three strategic archetypes: Wisconsin-based precision manufacturers with captive riser forging, legacy recurve specialists leveraging traditional lamination expertise, and diversified sporting goods conglomerates with multi-brand portfolios. Competitive moves concentrate on backward integration into prepreg consolidation and geographic expansion through pro-shop network consolidation.
Among legacy recurve specialists, Bear Archery and Hoyt Archery exemplify archetype differentiation through youth segment focus versus Olympic-grade positioning. Mathews Archery Inc. anchors the integrated manufacturing tier with Wisconsin-based captive machining. These three companies represent distinct strategic postures: traditional craft expertise, precision competitive equipment, and vertically controlled premium compound production.
| Leading Market Players |
|---|
| Bear Archery |
| PSE Archery LLC |
| Mathews Archery Inc. |
| New Archery Products Inc. |
| Escalade Inc. |
| Hoyt Archery |
| Bowtech |
| Scott Archery |
| Easton Technical Products Inc. |
| Others |
Cost & Logistics Intelligence
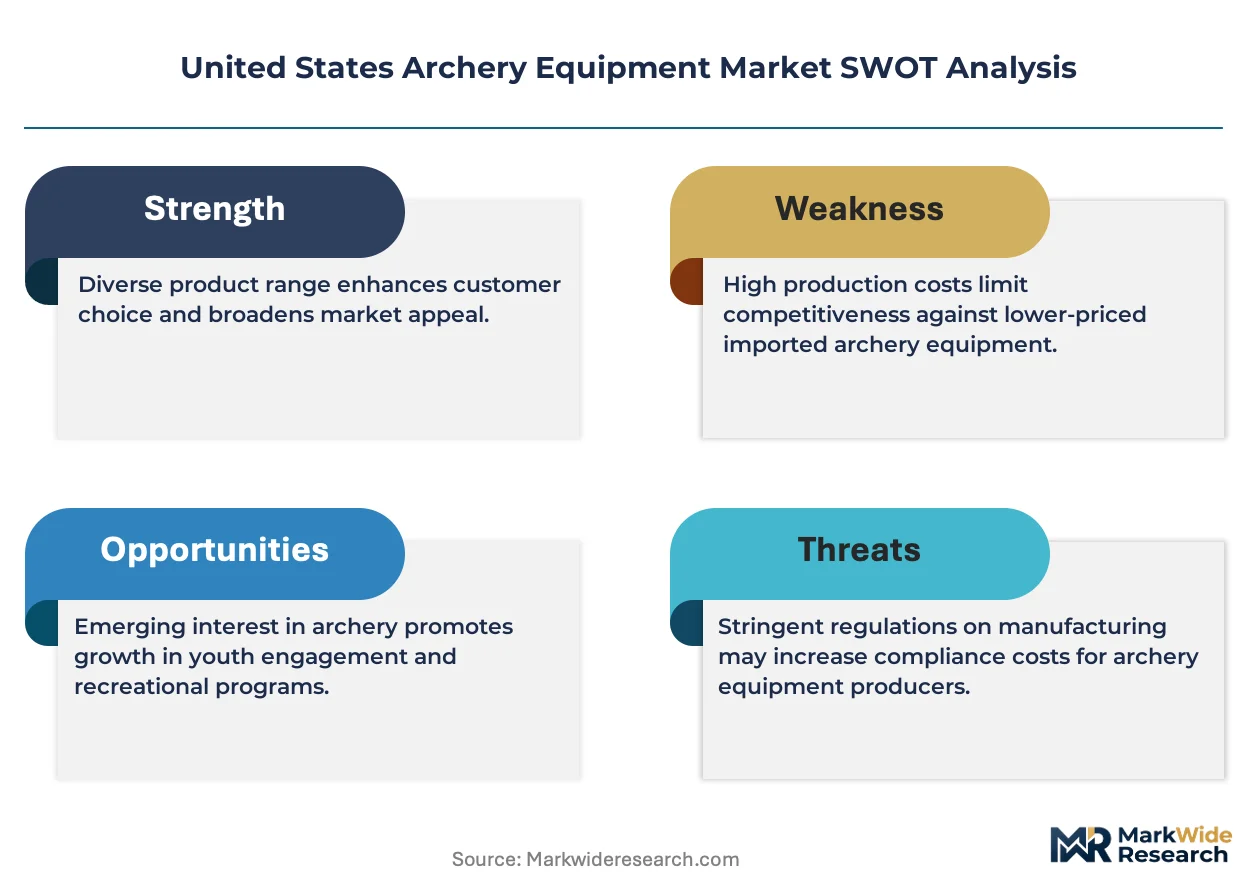
ASTM F1443 youth safety protocols gate both supplier qualification and price differentiation simultaneously, as certification compliance costs concentrate margin capture among prepreg-integrated manufacturers while school procurement budgets compress pricing flexibility for non-compliant assembly-only vendors.
Pricing Analysis
After-sales accessories and consumables drive lifetime value across equipment ownership cycles. Three-tier pricing structure across premium, standard, and economy levels stratifies by spine consistency tolerance and riser forging precision. Price differentiation rests on ISO-grade certification status and captive machining depth. Cost compression in entry-level compound bows is intensifying because Amazon same-day delivery erodes pro-shop inventory carrying rationale. Recreational shooters in the Mountain West exhibit highest price sensitivity; Texas youth tournament participants show lowest elasticity.
Supply Chain Analysis
Container availability constraints on transpacific trade lanes expose domestic bow manufacturers to aerospace contract prioritization at Toray and Hexcel fiber consolidation facilities. Geographic supply concentrates in Japan, the United States, and China for aerospace-grade carbon fiber prepreg. Raw material dependencies center on epoxy resin systems, aluminum billet stock, and precision machining consumables. Single-source vulnerability in prepreg supply creates inventory allocation friction during contract renewal windows. Distribution runs through specialty pro-shop networks in Texas and California, with online retailers capturing high-turn accessory sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart sight convergence with mobile ballistics applications signals a platform-economics inflection, as rangefinding optic interoperability reshapes accessory attachment standards and creates ecosystem lock-in opportunities for integrated hardware-software vendors.
For Market Incumbents: Secure captive prepreg consolidation capabilities to defend margin position against aerospace contract prioritization at Toray and Hexcel. Deepen backward integration into automated carbon fiber layup systems to compress entry barriers for precision limb manufacturing. Channel control through pro-shop network consolidation in Texas metropolitan corridors remains critical as Amazon same-day delivery fragments traditional distribution economics. For New Entrants and Emerging Players: Lead with 3D archery course lease programs in underpenetrated Mountain West municipal park systems, where tourism-linked infrastructure creates equipment-attachment white space. Target school athletic program procurement in Florida under state physical education mandates, where ASTM F1443 compliance streamlines district purchasing workflows. Direct-to-consumer sight customization platforms offer lowest-friction go-to-market angle for tech-forward hunters seeking rangefinding optic integration. For Investors and Strategic Acquirers: Pittman-Robertson reauthorization reshapes the acquisition landscape by redirecting conservation funding toward range development and equipment grant programs. Five-to-ten year viability favors vertically integrated manufacturers with Wisconsin-based captive machining and automated carbon fiber layup capabilities. Monitor crossbow classification debates in state legislatures as signal for interstate commerce friction and inventory allocation risk exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Prepreg Consolidation | Captive carbon fiber supply insulates margin pressure from aerospace contract prioritization at Toray. |
| Smart Sight Platform Integration | Rangefinding optic interoperability with mobile ballistics applications creates premium accessory attachment points. |
| 3D Archery Course Partnership | Tourism-linked municipal park infrastructure in Mountain West states stimulates equipment lease program demand. |
| Pro-Shop Network Consolidation | Channel control in Texas and California metros defends against Amazon same-day delivery erosion. |
| ASTM F1443 Certification Investment | Youth safety protocol compliance streamlines school procurement processes in Texas and Florida public athletic programs. |
Research Approach
Desk research of ASTM International standards documentation, state wildlife agency hunting regulations, and OSHA workplace safety guidelines preceded structured interviews with compound bow product managers, carbon fiber prepreg procurement leads, school athletic program directors, and specialty pro-shop operators across Texas and California. Secondary validation drew from National Field Archery Association tournament participation records, USA Archery competitive program disclosures, and Texas Education Agency physical education mandate filings. Bottom-up equipment shipment estimates and top-down market size triangulation anchored value projections.
Variance decomposition across product type, end user, material, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macroeconomic indicators and industry-specific demand drivers including youth tournament participation trends, school curriculum adoption rates, and bowhunter equipment replacement cycles.
Forecasts assume regulatory continuity in ASTM F1443 youth safety protocols and Pittman-Robertson conservation funding structures; material policy shifts would require re-modeling of school procurement demand and range development grant availability. Crossbow classification statutory changes, OSHA silica compliance timeline accelerations, and prepreg supply contract renegotiations represent specific risk factors that could revise trajectory assumptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
BMX Bikes Market
Sports Equipment
Starting Blocks Market
Sports Equipment
Bowling Lane Panels Market
Sports Equipment
Global Golf Accessories Market
Sports Equipment
Golf Shoes Market
Sports Equipment
UK Horse Riding Equipment Market
Sports Equipment
Alpine Ski Equipment Market
Sports Equipment
Ergonomic Strap Systems Market
Sports Equipment
Dirt Bike Market
Sports Equipment
Carbon-Fiber Badminton Racquet Market
Sports Equipment
Europe Running Gear Market
Sports Equipment
Waist Support Belt Market
Sports Equipment
Mini Balance Beam Market
Sports Equipment
Pickleball Pitching Machine Market
Sports Equipment
Ice Cleat Market
Sports Equipment
Football Equipment Market