
 Bowling Lane Panels Market | 2026-2036
Bowling Lane Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Bowling Lane Panels Market Analytics
USBC equipment certification is reorganizing competitive access for bowling lane panel suppliers, forcing manufacturers to maintain continuous testing compliance. Brunswick Bowling leverages captive lane installation networks to sustain replacement part demand across North American bowling centers. QubicaAMF anchors its position through integrated scoring-to-lane system bundling that locks in panel specification requirements.
Bowling lane panels are precision-engineered playing surfaces, traditionally fabricated from laminated maple and pine planks measuring approximately one inch in thickness and forty-one to forty-two inches in width, designed to withstand repeated ball impacts while maintaining consistent oil absorption and ball reaction characteristics. Synthetic panels now dominate new installations due to reduced maintenance requirements and extended service life compared to traditional wood substrates. The product type dimension shows lane panels capturing the core value pool while approach boards represent a faster-growing replacement segment driven by safety-focused renovation cycles. End-user concentration tilts toward bowling centers, though entertainment venues are expanding lane counts as experiential attractions diversify beyond traditional league play.
The United States Bowling Congress sets equipment standards that directly govern panel material tolerances, surface hardness, and lane geometry for sanctioned competition use. China's SAMR enforces national standards for recreational facility materials that affect import eligibility for foreign-manufactured panels. Stakeholders must monitor evolving certification timelines and regional standard harmonization to align production capacity with jurisdiction-specific compliance requirements.
Market Dynamics
USBC equipment certification mandates are compressing supplier margins while simultaneously locking out uncertified competitors, creating a bifurcated supply base where compliant manufacturers capture replacement cycles and non-compliant producers exit sanctioned competition channels entirely.
Growth Catalysts
- USBC specification compliance:Mandatory certification for sanctioned tournament play forces bowling centers to specify approved panels, creating captive demand streams for qualified suppliers.
- Entertainment venue lane expansion:Family entertainment centers in the United States are installing additional lanes as experiential attractions diversify beyond traditional league formats.
- Synthetic substrate durability:Advanced polymer formulations extend service intervals from 5-7 years to 15-20 years, reducing total cost of ownership and accelerating replacement of aging wood lanes.
Market Restraints
- Petrochemical input volatility:Synthetic panel production depends on polyurethane and epoxy resin feedstocks subject to crude oil price swings, compressing margin predictability for manufacturers.
- Chinese supply concentration:Raw material processing and intermediate chemical production clusters in Shandong and Jiangsu provinces, exposing downstream fabricators to single-region disruption risks.
- Wood lane artisan scarcity:Traditional maple and pine lane fabrication requires specialized carpentry skills that vocational programs no longer produce, constraining heritage restoration projects.
Strategic Opportunities
- German bowling center renovation wave:Aging facilities built during the 1980s bowling boom require full lane replacements, creating a concentrated demand window through 2030.
- Modular lane system integration:Prefabricated panel sections compatible with automated pinsetting machinery reduce installation labor and enable rapid venue reconfiguration.
- China SAMR recreational facility standards:Evolving national safety codes for public entertainment venues create compliance-driven replacement cycles for imported and domestic panel suppliers.
Industry Challenges
- USBC certification timeline compression:Accelerated testing protocols for new synthetic formulations extend product development cycles by 18-24 months, delaying revenue recognition.
- Legacy scoring system interfacing:New panel installations must maintain compatibility with existing Brunswick and QubicaAMF infrastructure, complicating specification engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bowling Lane Panels Market |
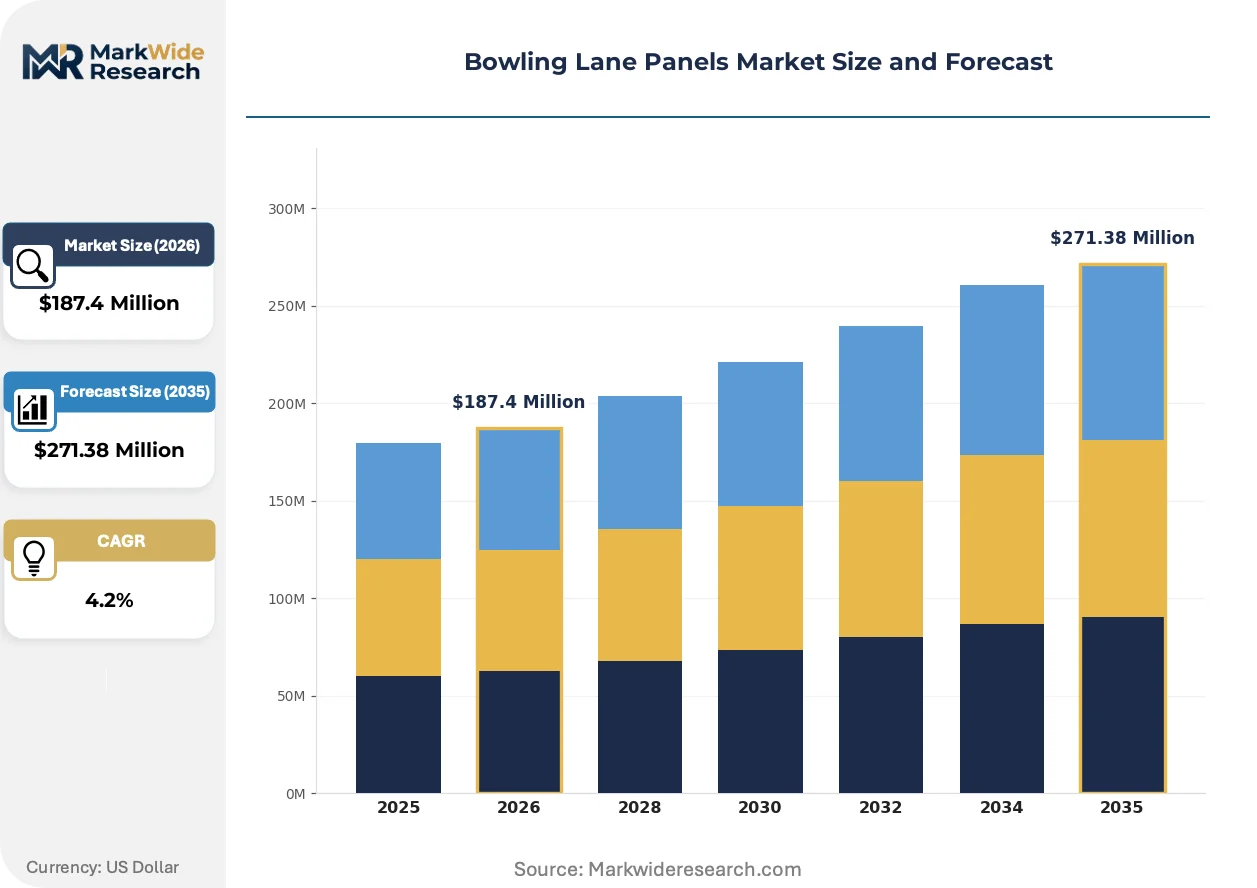
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $271.38 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Wood, Synthetic, Composite, Plastic Product Type: Lane Panels, Approach Boards, Backboards, Graphics End User: Bowling Centers, Entertainment Venues, Residential Users, Tournaments Installation Type: Permanent, Temporary, DIY, Professional |
| Companies Covered | Brunswick Bowling, QubicaAMF, AMF Bowling, Murrey International, US Bowling, Beijing Xushida, Guangzhou Jinchuang, Shenzhen Eternity, E. Parrella Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bowling Lane Panels Market Evolving Landscape
Material science advances and regulatory recalibration are fragmenting traditional supply relationships while enabling new entry points for specialized panel fabricators. Three developments warrant particular attention.
Multi-layer synthetic laminate construction is bifurcating the installed base between premium competition-grade surfaces and economy entertainment-tier alternatives. Tournament venues in the United States specify high-density fiberboard cores with specialized wear layers, while family entertainment centers adopt thinner, cost-optimized configurations. This technical divergence is compressing mid-tier suppliers unable to serve both performance segments profitably.
REACH chemical substance restrictions in Europe are forcing reformulation of polyurethane binding agents used in synthetic panel manufacturing. German and Dutch bowling center operators now demand full material disclosure documentation, shifting procurement evaluation criteria from price-per-lane to lifecycle environmental compliance. Panel suppliers with pre-certified green chemistry formulations capture specification advantages in North Rhine-Westphalia and Bavaria renovation tenders.
Lane-as-a-service leasing models are displacing capital purchase arrangements among independent bowling center operators in the United States. QubicaAMF and Brunswick now bundle panel replacement into multi-year equipment service contracts, transferring obsolescence risk from venue owners to manufacturers. This financialization trend concentrates purchasing authority with national account managers rather than individual center proprietors.
Bowling Lane Panels Market Segmentation
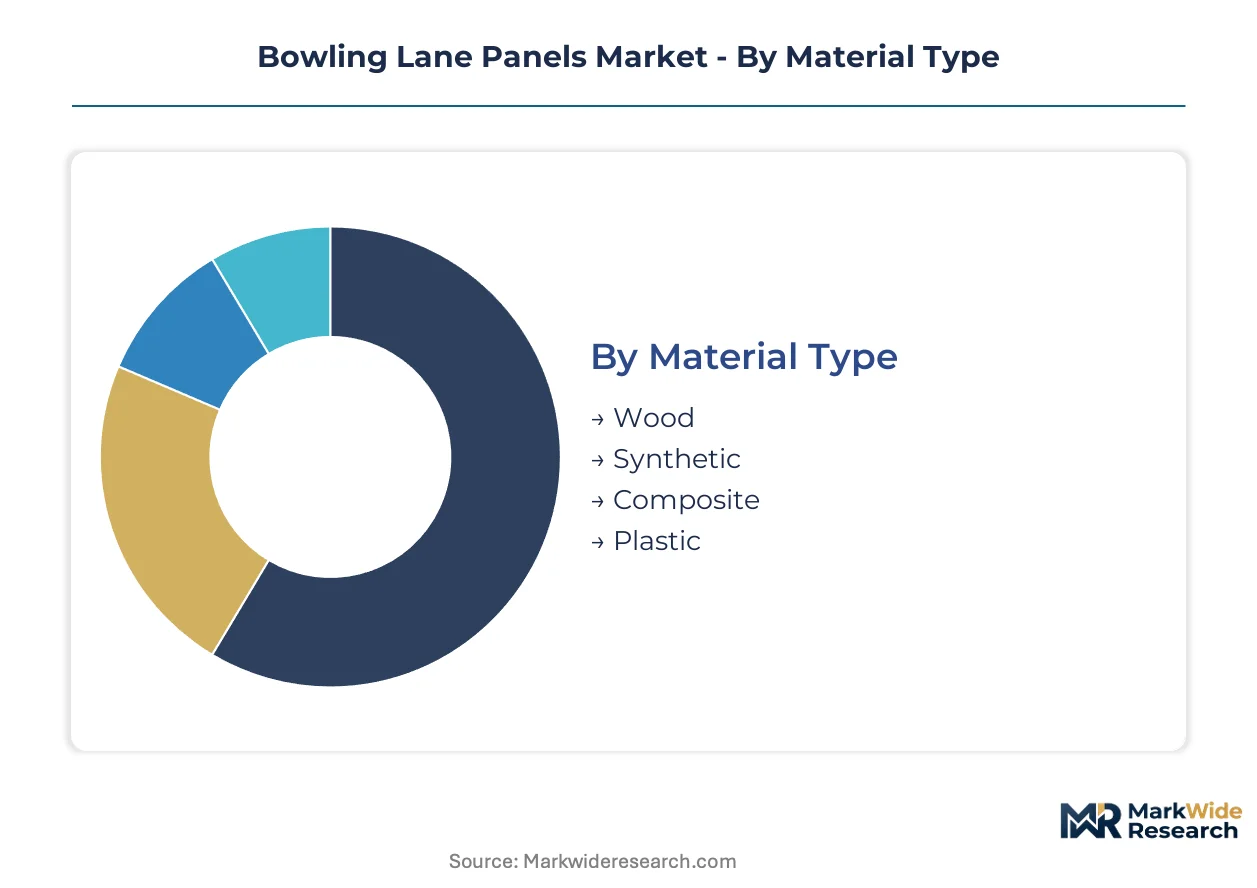
Bowling lane panel demand fragments across four distinct dimensions that govern procurement patterns and margin structures. Material composition determines certification eligibility and service life. Installation context shapes volume concentration and replacement frequency.
Material Type:
Domestic production clusters in North America and Europe for traditional substrates, while synthetic formulations flow from Asian chemical processing hubs to global assembly facilities.
- Wood:Traditional laminated maple and pine construction meets USBC hardness specifications for sanctioned tournament play. Demand concentrates in heritage renovation projects across the United States and Germany where bowling centers preserve authentic playing characteristics for league purists.
- Synthetic:Multi-layer polymer composites with specialized wear surfaces dominate new lane installations in family entertainment centers. Chinese and South Korean manufacturers supply the bulk of global synthetic substrate volume, though German fabricators capture premium competition-grade specifications.
- Composite:Hybrid wood-polymer constructions balance cost and performance for mid-tier bowling centers in secondary US markets.
- Plastic:Economy-grade extruded panels serve temporary installations and training facilities where capital constraints override longevity requirements.
Synthetic holds the largest share; momentum sits with composite formulations bridging performance and cost.
Product Type:
Cost tiers separate tournament-specification surfaces from entertainment-optimized alternatives, with approach boards commanding premium per-square-foot pricing due to safety-critical wear patterns.
- Lane Panels:Precision-engineered playing surfaces measuring 41-42 inches in width form the core revenue pool. Brunswick and QubicaAMF specify proprietary dimensions that lock in replacement demand across their installed base of automated pinsetters.
- Approach Boards:Safety-focused surfaces at the foul line experience accelerated wear from bowler foot traffic. German DIN standards and USBC regulations mandate specific friction coefficients, driving compliance-driven replacement cycles in aging European facilities.
- Backboards:Protective panels behind the pin deck absorb ball impact and reduce maintenance intervals for pinsetting machinery.
- Graphics:Branded lane markings and advertising overlays represent a discretionary spend category vulnerable to entertainment venue budget compression.
Lane panels anchor volume; approach boards are climbing the fastest on renovation-driven replacement schedules.
End User:
Customer type determines specification stringency, with tournament operators demanding certified surfaces while residential buyers prioritize installation simplicity over performance tolerances.
- Bowling Centers:Traditional league-based facilities in the United States and Germany drive the bulk of replacement demand through 15-20 year renovation cycles.
- Entertainment Venues:Family entertainment centers and experiential attractions in Texas, Florida, and California are expanding lane counts as bowling diversifies beyond league formats.
- Residential Users:Home bowling installations in affluent US suburbs represent a niche segment sensitive to DIY installation compatibility.
- Tournaments:Professional and collegiate competition organizers mandate USBC-certified panels, creating a specification gate that filters supplier eligibility.
Bowling centers retain the largest share; entertainment venues show the steepest expansion trajectory.
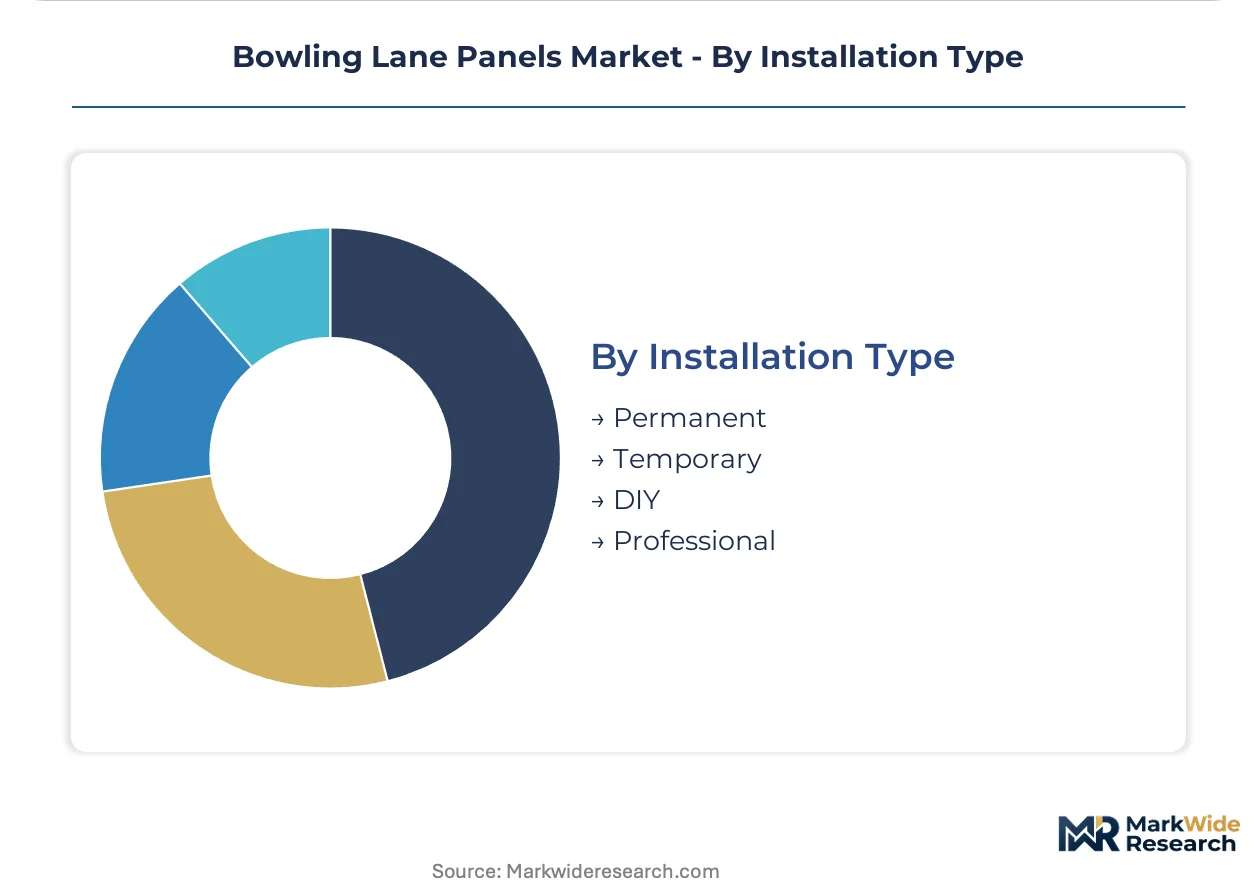
Installation Type:
Volume concentration tilts toward professional installation given the precision requirements for lane geometry and pinsetter alignment, though modular systems are eroding this dominance.
- Permanent:Fixed installations with concrete anchoring dominate commercial bowling centers where lane geometry must remain stable across decades of use.
- Temporary:Portable lane systems serve event operators and exhibition venues requiring rapid deployment and breakdown capabilities.
- DIY:Pre-cut panel kits with simplified fastening systems target residential buyers and small entertainment venues with limited contractor access.
- Professional:Certified installation crews from Brunswick and QubicaAMF ensure warranty compliance and scoring system integration.
Permanent installation holds the largest share; temporary systems are gaining share fastest in the event services segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach container throughput underwrites United States import capacity for synthetic polymer feedstocks, while Germany's Rhine River freight corridors sustain maple substrate distribution to European fabricators.
United States
Family entertainment centers in Texas and Florida are expanding lane installations as experiential attractions diversify beyond traditional league formats. USBC equipment certification mandates govern panel material tolerances and surface hardness specifications for sanctioned tournament play. Chicago and Milwaukee manufacturing clusters supply precision-engineered lane surfaces to domestic bowling center renovation cycles.
Germany
Aging facilities built during the 1980s bowling boom require full lane replacements through concentrated demand windows. REACH chemical substance restrictions force reformulation of polyurethane binding agents used in synthetic panel manufacturing. North Rhine-Westphalia and Bavaria renovation tenders now prioritize suppliers with pre-certified green chemistry formulations.
China
Shandong and Jiangsu province chemical processing hubs manufacture intermediate synthetic substrates for global assembly. SAMR enforces national standards for recreational facility materials that affect import eligibility for foreign-manufactured panels. Guangzhou and Shenzhen fabricators supply bulk synthetic volume to entertainment venue developers across Asia-Pacific.
Japan
Automated bowling installations in Tokyo and Osaka commercial complexes drive specification demand for precision-engineered surfaces. METI industrial standards govern recreational equipment material safety and durability testing protocols. Kanto region manufacturing clusters produce specialized wear layers for premium competition-grade panel exports.
Bowling Lane Panels Market Competitive Landscape
Listed leaders compete with private specialists across certification compliance and captive installation networks. The supplier base concentrates around equipment-integrated panel specifications that lock replacement demand to proprietary dimensions. Three archetypes dominate: full-system integrators bundling scoring-to-lane solutions, substrate specialists supplying certified surfaces to multiple equipment brands, and regional fabricators serving local renovation cycles. Competitive moves center on USBC certification timeline acceleration and modular lane system development for rapid venue reconfiguration.
Among United States-based full-system integrators, Brunswick Bowling and QubicaAMF occupy positions that exemplify equipment-captive demand capture through proprietary specification requirements. Chinese fabricators including Beijing Xushida represent the substrate-specialist archetype, supplying synthetic panel volume to global assembly facilities without direct scoring system integration.
| Leading Market Players |
|---|
| Brunswick Bowling |
| QubicaAMF |
| AMF Bowling |
| Murrey International |
| US Bowling |
| Beijing Xushida |
| Guangzhou Jinchuang |
| Shenzhen Eternity |
| E. Parrella Company |
| Others |
Value Network & Pricing Analysis
Capacity utilization at Shandong and Jiangsu chemical processing hubs shapes both supply concentration and price floors for synthetic bowling lane panels. USBC certification timelines compress margins for compliant manufacturers while creating captive demand streams that insulate approved suppliers from spot-market volatility.
Pricing Analysis
Certification level creates the primary spread between tournament-grade and entertainment-tier bowling lane panels. Three-tier pricing structure across premium, standard, and economy levels reflects USBC specification compliance, synthetic substrate durability ratings, and bundled installation services. Pricing pressure stems from petrochemical input volatility in polyurethane and epoxy resin feedstocks. Family entertainment centers exhibit the highest price sensitivity, while professional tournament operators prioritize certified surfaces over cost optimization.
Supply Chain Analysis
Port congestion at Long Beach and container availability constraints on trans-Pacific trade lanes elevate inbound logistics costs for North American bowling center operators. Raw material processing clusters in China, South Korea, and Germany supply intermediate synthetic substrates to global assembly facilities. Panel fabrication draws from maple and pine lumber, high-density fiberboard cores, and specialized polymer wear layers. Single-source vulnerability concentrates in Shandong province chemical processing. Distribution runs through Brunswick and QubicaAMF captive installation networks and independent certified contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bowling lane panels constitute a defensive-moat market where USBC regulatory entrenchment creates durable switching costs for certified suppliers. Network effects from proprietary scoring system integration lock replacement demand to incumbent specifications.
For Market Incumbents: Secure USBC certification timeline acceleration through pre-submission testing partnerships, reducing product development cycles by capturing early formulation feedback. Defend position by deepening backward integration into synthetic substrate production, mitigating petrochemical input volatility that threatens margin stability. Channel control through multi-year lane-as-a-service contracts transfers obsolescence risk to manufacturers while concentrating purchasing authority.
For New Entrants and Emerging Players: USBC certification fast-track programs represent the most viable entry pathway for synthetic panel specialists lacking established scoring system relationships. Target German bowling center renovation demand through REACH-compliant green chemistry formulations that satisfy North Rhine-Westphalia and Bavaria tender requirements. Pursue modular lane system partnerships with automated pinsetting machinery providers to bypass direct competition with full-system integrators.
For Investors and Strategic Acquirers: Substrate specialists with pre-certified synthetic formulations and established Asian chemical processing relationships offer compelling acquisition profiles. Long-term viability hinges on regulatory compliance durability rather than commodity pricing cycles. Monitor SAMR recreational facility standard evolution as an inflection indicator for China market access expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| USBC Certification Acceleration | Pre-submission testing partnerships compress product development cycles by capturing early formulation feedback from the governing body. |
| Backward Integration into Substrates | In-house production of synthetic polymer cores mitigates petrochemical input volatility threatening manufacturer margin stability. |
| Modular Lane System Development | Prefabricated panel sections compatible with automated pinsetting machinery reduce installation labor and enable rapid venue reconfiguration. |
| Green Chemistry Formulation Investment | REACH-compliant polyurethane binding agents capture specification advantages in German renovation tenders prioritizing lifecycle environmental compliance. |
| Lane-as-a-Service Contract Expansion | Multi-year equipment service bundles transfer obsolescence risk from venue owners to manufacturers while concentrating purchasing authority. |
Research Methodology
Cross-validation between primary interviews with bowling center operators and secondary validation from USBC equipment specifications anchors the qualitative findings. Bowling center proprietors, Brunswick and QubicaAMF national account managers, synthetic substrate chemical engineers, and certified installation contractors provided operational perspectives. Secondary sources encompass USBC technical bulletins, SAMR recreational facility standards, REACH chemical substance registrations, and customs trade data for maple lumber and polymer feedstocks. Bottom-up lane installation counts triangulate against top-down bowling center renovation cycle projections.
Sensitivity analysis around petrochemical price scenarios and certification timeline variations informs the analytical framework across the projection horizon. Segmentation dimensions encompass material composition, product type, end-user category, and installation context. CAGRs derive from installed base depreciation schedules and replacement frequency patterns. Synthetic substrate durability advances and entertainment venue lane expansion rates constitute industry-specific forecast inputs.
Underlying assumptions cover USBC specification stability, Chinese chemical processing capacity continuity, and German renovation cycle concentration, with deviation risk concentrated in regulatory harmonization delays and logistics chokepoint recurrence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Baseball Sliding Mitts Market
Sports Equipment
Speed Hurdle Market
Sports Equipment
Parallel Bars Market
Sports Equipment
UAE Horse Riding Equipment Market
Sports Equipment
Shuttlecock Market
Sports Equipment
One-Piece Carbon Fiber Badminton Racket Market
Sports Equipment
Shooting Ranges Market
Sports Equipment
Ice Hockey Equipment Market
Sports Equipment
Bicycle Pumps Market
Sports Equipment
Kickboxing Equipment Market
Sports Equipment
Europe Winter Sports Equipment Market
Sports Equipment
Sports Eyewear Market
Sports Equipment
Surfing Boards Market
Sports Equipment
Basketball Gear Market
Sports Equipment
Knee Pads Market
Sports Equipment
Cross Training Shoes Market