
 Carbon-Fiber Badminton Racquet Market | 2026-2036
Carbon-Fiber Badminton Racquet Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon-Fiber Badminton Racquet Market Insights
Pre-impregnated carbon-fiber layup is tilting racquet fabrication away from traditional aluminum and steel alloys toward woven graphite composites with tunable flex profiles. Yonex leverages in-house resin formulation to control shaft stiffness across its pro lineup. Li-Ning anchors its competitive position through vertical integration into carbon-fiber sourcing from domestic suppliers. Victor differentiates via aerodynamic frame geometries developed through wind-tunnel testing protocols.
A carbon-fiber badminton racquet consists of a hollow frame and shaft molded from polyacrylonitrile-derived graphite sheets, typically weighing between 70 and 100 grams, engineered to deliver high stiffness-to-weight ratios for rapid swing acceleration and precise shuttlecock placement. Professional-grade equipment commands the steepest price tiers due to tournament certification requirements and athlete endorsement economics. Recreational segments sustain volume throughput as casual players migrate from entry-level alloy racquets toward mid-range graphite alternatives. Ultra-light weight categories attract the fastest-growing demand among junior development programs and defensive specialists seeking maneuverability gains.
ISO 9001 quality management and Japan Industrial Standards certification govern structural integrity testing for competitive-grade racquets, while REACH compliance in Europe restricts certain epoxy resin formulations used in composite bonding. China's SAMR enforces product safety labeling that affects export eligibility for factory-direct brands. Stakeholders must monitor evolving carbon-fiber waste disposal regulations and raw material cost trajectories to calibrate production scale and geographic sourcing strategies.
Market Dynamics
Pre-impregnated carbon-fiber layup is consolidating manufacturing around Guangdong factory clusters while METI certification requirements in Japan fragment competitive tiers between certified tournament-grade and recreational equipment.
Growth Catalysts
- REACH compliance in Europe:Restrictions on legacy epoxy resin formulations are accelerating R&D investment into bio-based composite bonding agents that reduce environmental liability for exporters.
- Tournament participation rates:Competitive badminton clubs across East Asia are expanding equipment procurement budgets as regional championship circuits multiply fixture density.
- Junior development programs:Ultra-light weight racquet categories are capturing institutional demand from national sports academies prioritizing maneuverability training for defensive specialists.
Market Restraints
- Polyacrylonitrile price volatility:Precursor carbon-fiber feedstock costs fluctuate with acrylonitrile monomer supply tied to petrochemical refinery output cycles.
- Guangdong supply concentration:Factory cluster dependency creates single-region exposure to energy rationing policies and labor mobility constraints.
- Stiffness-to-weight ceiling:Current woven graphite composite architectures approach theoretical performance limits without graphene hybridization.
Strategic Opportunities
- India recreational migration:Casual players transitioning from aluminum entry-level racquets represent unconverted volume in badminton's fastest-growing participation market.
- SAMR export labeling alignment:China's product safety certification harmonization creates streamlined pathway for factory-direct brands entering European distribution channels.
- Wind-tunnel aerodynamics:Frame geometry optimization protocols from aerospace testing facilities are converging with racquet R&D to unlock drag reduction gains.
Industry Challenges
- Composite layup technician scarcity:Pre-preg manual placement and autoclave curing operations require skilled labor pools concentrated in aging Japanese and Taiwanese workforces.
- ISO 9001 certification timelines:Tournament-grade structural integrity testing protocols extend product development cycles by 8-14 months for new frame architectures.
- Carbon-fiber waste stream reconfiguration:Scrap graphite sheet disposal regulations are forcing fabrication facilities to retool cutting optimization software and invest in closed-loop recycling partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon-Fiber Badminton Racquet Market |
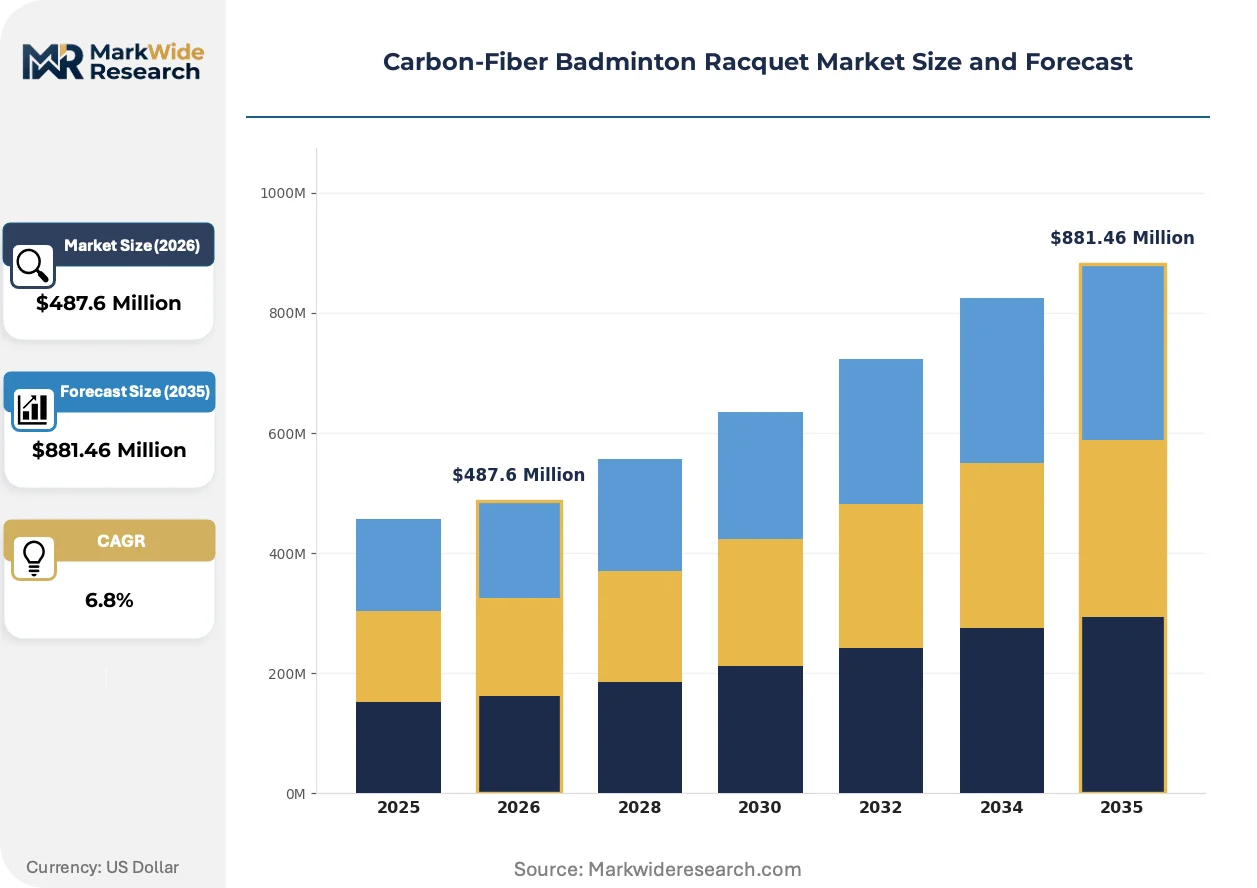
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Professional, Recreational, Junior, Advanced End User: Athletes, Coaches, Schools, Clubs Weight Category: Lightweight, Midweight, Heavyweight, Ultra-light Price Tier: Premium, Mid-range, Budget, Entry-level |
| Companies Covered | Yonex, Li-Ning, Victor, Babolat, Apacs Sports, Gosen, Carlton Sports, KAWASAKI, RSL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon-Fiber Badminton Racquet Market Trends and Innovations
Digital twin simulation is compressing prototype iteration cycles while regulatory divergence between Japanese industrial standards and European chemical restrictions is fragmenting resin formulation strategies across manufacturing footprints.
Computational fluid dynamics software is virtualizing frame geometry development by replacing physical wind-tunnel prototypes with high-fidelity aerodynamic modeling. Racquet manufacturers in Taiwan and South Korea are adopting these simulation suites to accelerate head shape optimization for drag reduction. This virtualization is compressing R&D timelines from 18-month physical test cycles to 6-month digital iteration windows while expanding the design space for non-traditional frame cross-sections.
Japan's METI enforcement of JIS carbon-fiber composite standards is elevating manufacturing cost structures for tournament-certified equipment. The industrial consequence is a widening certification gap between premium pro-grade racquets and recreational-tier products that bypass full structural testing protocols. Chinese factory clusters serving domestic brands are responding by bifurcating production lines: dedicated METI-compliant cells for Japanese export alongside standard-output lines for Southeast Asian and Indian markets.
Direct-to-academy procurement models are displacing traditional distributor networks for institutional volume orders. National sports federations in Indonesia and Malaysia are consolidating equipment tenders through centralized purchasing agreements that bypass regional sporting goods wholesalers. This channel compression is most visible in junior development program budgets, where procurement officers negotiate frame-shaft customization batches directly with factory technical teams rather than through brand marketing subsidiaries.
Carbon-Fiber Badminton Racquet Market Segmentation
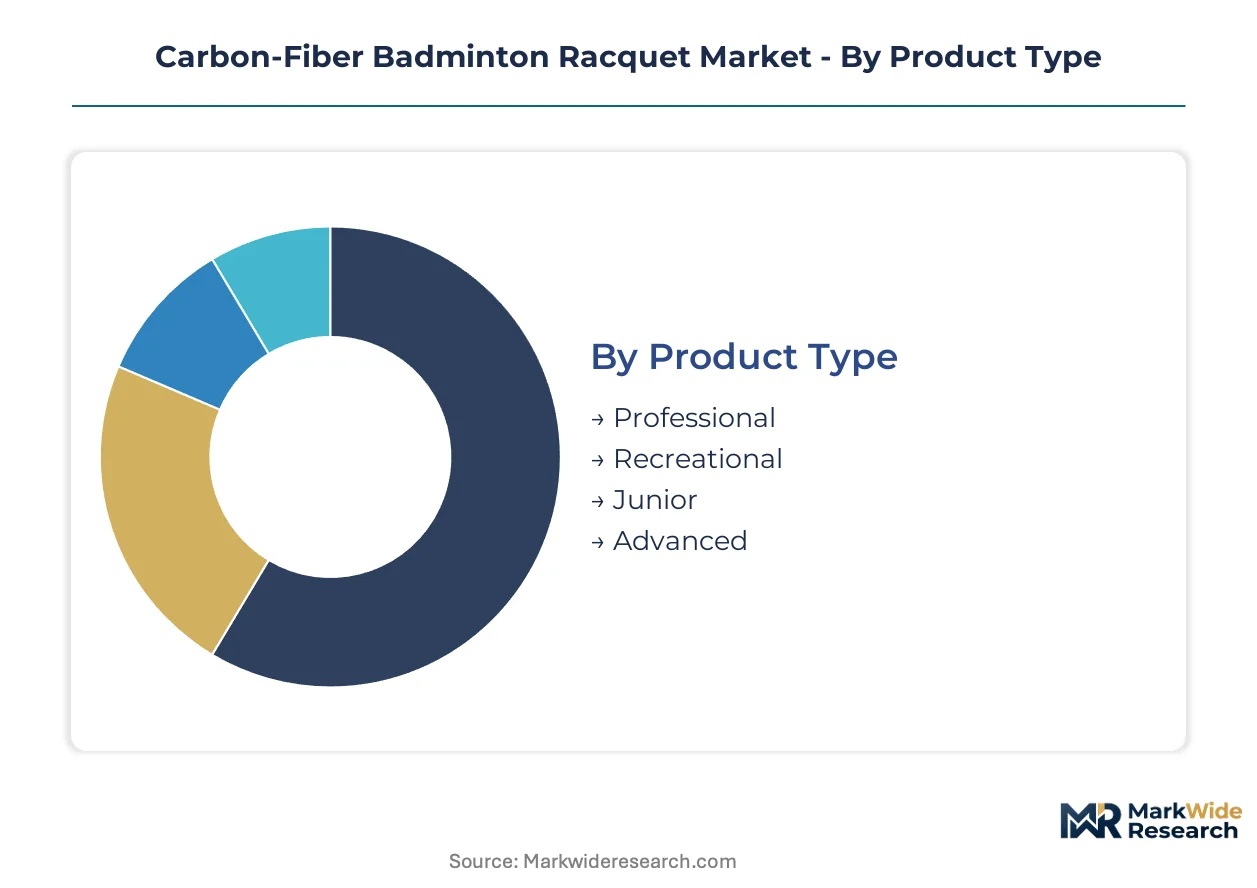
Carbon-fiber badminton racquet segmentation reveals how manufacturing complexity, certification requirements, and replacement cycles vary sharply across user tiers. Understanding these divides helps suppliers calibrate resin formulation investments, warranty terms, and distribution channel strategies for each profit pool.
Product Type:
After-sales service intensity escalates dramatically from recreational to professional tiers, with tournament-grade equipment demanding frame integrity monitoring and restringing protocols that junior lines rarely require.
- Professional:Full JIS-certified graphite layup with tunable flex profiles meets METI structural testing mandates. Demand concentrates in Japan's competitive club circuit, where athletes replace frames every 6-12 months under federation equipment allowances.
- Recreational:Standard-modulus carbon-fiber construction balances durability against cost for casual weekend players. Guangdong factory clusters supply this volume tier to Southeast Asian sporting goods retailers seeking 24-month warranty coverage.
- Junior:Scaled-down grip circumferences and reduced shaft lengths accommodate adolescent biomechanics. National sports academies in Indonesia procure these through direct factory negotiations rather than distributor networks.
- Advanced:Stiffness-tuned architectures bridge the performance gap between recreational and pro tiers. Club-level tournament participants in Malaysia drive replacement demand as skill progression outpaces equipment capabilities.
Professional holds the largest share; momentum sits with Junior as development program budgets expand across East Asia.
End User:
Procurement authority and technical specification knowledge diverge substantially across this dimension, with institutional buyers wielding volume leverage that individual consumers cannot match.
- Athletes:Individual competitors prioritize shaft stiffness calibration and grip customization for tournament certification. China's provincial team system generates concentrated demand for batch-customized frame geometries.
- Coaches:Equipment decisions for training squads balance durability against per-unit cost across roster sizes. Korean national team coaching staff negotiate annual frame procurement contracts directly with technical suppliers.
- Schools:Physical education departments favor midweight categories with reinforced frame heads for multi-year durability. India's government school sports initiatives are expanding institutional purchase orders for entry-level graphite alternatives.
- Clubs:Competitive badminton associations manage equipment pools for member access and tournament lending. Malaysian club federations consolidate tenders through centralized purchasing agreements that bypass traditional wholesalers.
Clubs hold the largest share; momentum sits with Schools as national physical education budgets prioritize racket sports infrastructure.
Weight Category:
Material cost and layup precision scale inversely with mass, as ultra-light architectures demand higher-grade carbon-fiber modulus and more stringent quality control.
- Ultra-light:Sub-75-gram constructions utilizing high-modulus graphite sheets with resin-rich toughening layers. Defensive specialists in Taiwan's professional circuit favor these for rapid net reaction times and sustained rally endurance.
- Lightweight:75-85-gram frames balancing maneuverability against stability for all-court playing styles. Junior development programs across Thailand specify this category for technical skill acquisition phases.
- Midweight:85-95-gram standard configurations dominating recreational and club-level participation. Guangdong export production lines optimize throughput around this mass specification for cost efficiency.
- Heavyweight:95-100-gram architectures preferred by power-oriented singles players seeking smash momentum. Aging club demographics in Japan sustain residual demand for head-heavy balance profiles.
Midweight holds the largest share; Ultra-light is climbing the fastest as junior academies prioritize defensive technique training.
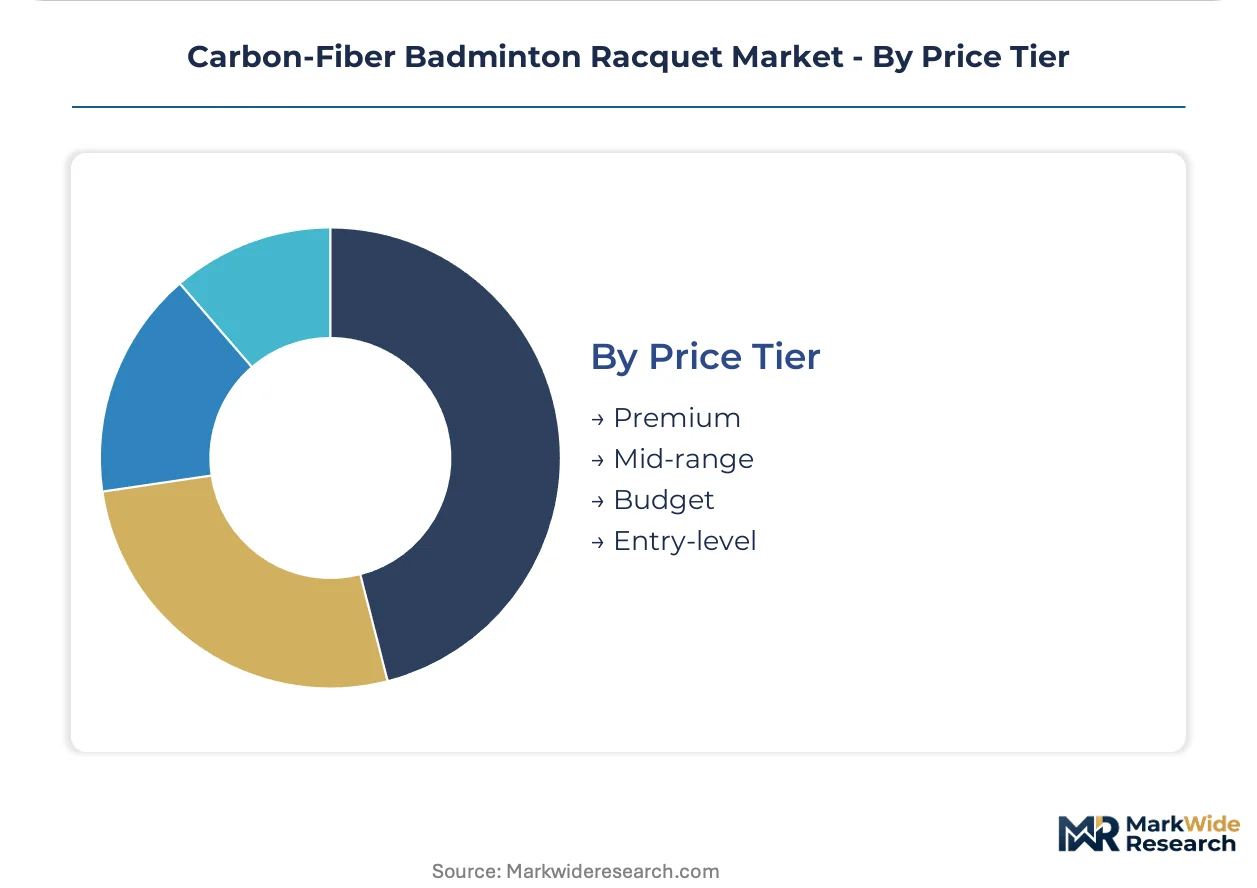
Price Tier:
Margin structures and channel economics stratify sharply across this dimension, with premium tiers absorbing certification and endorsement costs that budget lines eliminate entirely.
- Premium:Tournament-certified frames with METI-compliant testing documentation and athlete co-development programs. Japanese distribution channels capture these products through authorized dealer networks with technical service obligations.
- Mid-range:Performance-grade graphite construction without full JIS certification overhead for competitive club players. Chinese domestic brands dominate this tier through vertical control of carbon-fiber sourcing.
- Budget:Entry-modulus composites targeting casual players transitioning from aluminum equipment. Indian sporting goods retailers stock these for price-sensitive first-time graphite purchasers.
- Entry-level:Basic carbon-fiber reinforced polymer frames for institutional bulk procurement and school physical education programs. Southeast Asian ministry of education tenders specify this tier for mass distribution.
Premium holds the largest share; Budget is gaining share fastest as India's recreational participation base expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Competitive badminton clubs and institutional buyers cluster in East Asian manufacturing corridors and emerging South Asian participation markets. Equipment procurement authority concentrates with national sports federations, factory-direct academy contracts, and authorized dealer networks serving tournament-certified segments.
China
Guangdong province factory clusters supply carbon-fiber racquet output for domestic brands and export orders to Southeast Asian distributors. SAMR enforces product safety labeling requirements that affect export eligibility for factory-direct brands seeking European REACH compliance pathways. Shenzhen and Dongguan manufacturing hubs optimize throughput around midweight specifications while maintaining dedicated METI-compliant production cells for Japanese market access.
Japan
Competitive club circuits drive replacement demand every 6-12 months under federation equipment allowance programs. METI enforces strict JIS carbon-fiber composite standards that elevate manufacturing costs while ensuring performance consistency for tournament-certified equipment. Tokyo and Osaka metropolitan areas concentrate authorized dealer networks with technical service obligations for premium-tier distribution.
India
Casual players migrating from aluminum entry-level racquets represent unconverted volume in badminton's fastest-growing participation market. Government school sports initiatives are expanding institutional purchase orders for entry-level graphite alternatives under national physical education budget priorities. Maharashtra and Karnataka urban centers are emerging as retail distribution nodes for mid-range Chinese imports.
Indonesia
National sports federations consolidate equipment tenders through centralized purchasing agreements that bypass traditional sporting goods wholesalers. Junior development program budgets are capturing institutional demand for ultra-light weight categories prioritizing defensive technique training. Jakarta and Surabaya host direct-to-academy procurement negotiations with Guangdong factory technical teams.
Taiwan
Defensive specialists in the professional circuit favor sub-75-gram constructions for rapid net reaction times. Computational fluid dynamics software adoption is virtualizing frame geometry development among Taiwan-based manufacturers. Taipei and Taichung technical workforces concentrate pre-preg manual placement and autoclave curing operations requiring skilled labor pools.
Carbon-Fiber Badminton Racquet Market Competitive Landscape
Channel-controlling players compete with product-specialist players across bifurcated certification tiers separating tournament-grade from recreational equipment. Japanese and Chinese manufacturers anchor opposing ends of the premium-standard value spectrum. Three archetypes dominate: vertically integrated resin-formulators, factory-cluster assemblers with direct academy access, and aerodynamic-testing specialists. Competitive moves concentrate on production line bifurcation for METI compliance and wind-tunnel geometry licensing from aerospace facilities.
Among Japanese fabricators, Yonex occupies a position exemplifying in-house resin formulation control. Chinese manufacturers Li-Ning and Victor represent the factory-cluster and aerodynamic-specialist archetypes respectively. These three companies anchor the competitive structure without exhaustive market coverage claims.
| Leading Market Players |
|---|
| Yonex |
| Li-Ning |
| Victor |
| Babolat |
| Apacs Sports |
| Gosen |
| Carlton Sports |
| KAWASAKI |
| RSL |
| Others |
Pricing and Supply Chain Analysis
Polyacrylonitrile price volatility tied to petrochemical refinery output cycles compresses margin structures across all tiers while simultaneously forcing Guangdong factory clusters to index long-term supply contracts to acrylonitrile monomer benchmarks. This cost-plus contract pattern with feedstock indexation determines both the premium-to-budget tier spread and the geographic sourcing decisions that concentrate carbon-fiber sheet procurement around domestic Chinese suppliers.
Pricing Analysis
Cost-plus contract patterns with acrylonitrile monomer indexation dominate procurement between Guangdong factories and carbon-fiber sheet suppliers. Three-tier pricing structure across premium, standard, and economy levels separates METI-certified tournament frames from recreational graphite alternatives and entry-level institutional batches. Cost compression in the budget tier is intensifying because Indian retailers demand 24-month warranty coverage without absorbing certification overhead. Schools and government sports initiatives exhibit the highest price sensitivity, while Japanese competitive clubs under federation equipment allowances show minimal elasticity for JIS-certified pro-grade frames.
Supply Chain Analysis
Contract-manufacturing concentration sits with Shenzhen and Dongguan facilities serving as primary assembly hubs for both domestic Chinese brands and export orders to Southeast Asian distributors. Raw material sourcing draws from domestic polyacrylonitrile producers, Japanese resin formulation specialists, and Taiwanese pre-preg suppliers. Single-region vulnerability to Guangdong energy rationing policies and labor mobility constraints presents the dominant structural risk. Distribution runs through authorized dealer networks in Japan, direct-to-academy procurement channels in Indonesia and Malaysia, and mass-market sporting goods retailers in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as India's recreational participation base migrates from aluminum entry-level equipment toward graphite alternatives. Junior development program budget expansion across East Asian national sports academies provides additional penetration tailwind.
For Market Incumbents: Build certification moats through METI-compliant production cell investments that emerging entrants cannot replicate without 8-14 month ISO 9001 timeline penalties. Defensive moves should concentrate on backward integration into carbon-fiber sheet sourcing to buffer acrylonitrile volatility, alongside wind-tunnel geometry licensing from aerospace facilities to lock aerodynamic IP. Threat substitution from graphene hybridization architectures demands R&D allocation toward next-generation composite bonding.
For New Entrants and Emerging Players: Pursue white-space capture in India's recreational migration segment where price-sensitive first-time graphite purchasers lack brand loyalty. Target Maharashtra and Karnataka urban retail nodes for mid-range import distribution partnerships. Direct-to-academy procurement models in Indonesia and Malaysia offer bypass routes around entrenched wholesaler networks. Go-to-market angle should emphasize institutional volume tenders with customized frame-shaft specifications negotiated through Guangdong factory technical teams.
For Investors and Strategic Acquirers: The market sits at a capacity-constrained expansion phase that favors factory-cluster assemblers with direct academy access and resin-formulation control. Long-term viability over the next decade rests on regulatory compliance capabilities rather than pure manufacturing scale. Acquisition target archetype: vertically integrated mid-cap specialists with captive carbon-fiber sourcing and METI-certified production lines. Signal to watch: SAMR export labeling harmonization progress as indicator of streamlined European market entry for Chinese factory-direct brands.
| Strategic Initiative | Industry Significance |
|---|---|
| METI Certification Investment | JIS-compliant testing documentation unlocks Japanese tournament-grade pricing tiers and federation equipment allowance access. |
| Backward Integration into Carbon-Fiber Sourcing | Captive polyacrylonitrile supply agreements buffer margin compression from acrylonitrile monomer volatility cycles. |
| Wind-Tunnel Geometry Licensing | Aerospace testing facility partnerships enable drag reduction IP that differentiates frame architectures in competitive club segments. |
| Direct-to-Academy Procurement Channel | Bypassing traditional wholesalers captures institutional volume from Indonesian and Malaysian national sports federation tenders. |
| Closed-Loop Recycling Partnership | Scrap graphite sheet disposal compliance addresses tightening carbon-fiber waste regulations in Guangdong manufacturing zones. |
Research Methodology
A standing panel of racquet manufacturing plant managers, carbon-fiber procurement leads at composite suppliers, national sports federation equipment officers, and sporting goods retail category buyers provided ongoing calibration across the study period. Primary interview findings combined with secondary validation from SAMR product safety filings, Japan Industrial Standards certification databases, Guangdong customs export records, and BIS labeling requirements. Bottom-up demand modeling from institutional procurement tenders triangulated against top-down production capacity estimates from factory cluster surveys.
Scenario-bracketing framed the analytical approach across the analysis window, with segmentation dimensions spanning product type, end user, weight category, and price tier alongside regional regulatory cluster differentiation. CAGRs derived from production volume trajectories indexed to tournament participation rates and junior development program budget allocations. Industry-specific forecast inputs included polyacrylonitrile price band assumptions and METI certification timeline distributions for new frame architectures.
Macroeconomic conditions sit as an overlay; deviation in petrochemical feedstock costs, East Asian energy policy, or Indian physical education budget priorities would shift the trajectory. Forecasts reflect documented assumptions regarding acrylonitrile supply stability and certification harmonization progress. Quarterly review of SAMR labeling alignment indicators, METI enforcement intensity, and Guangdong factory utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Playground Sets and Equipment Market
Sports Equipment
Cricket Ball Market
Sports Equipment
Ice Hockey Equipment Market
Sports Equipment
Volleyball Shoes Market
Sports Equipment
Bike Saddles Market
Sports Equipment
Trampoline Market
Sports Equipment
Pitching Machine Market
Sports Equipment
Baseball Sliding Mitts Market
Sports Equipment
Europe Archery Equipment Market
Sports Equipment
Tetherball Market
Sports Equipment
Bicycle Pumps Market
Sports Equipment
Sports Fishing Equipment Market
Sports Equipment
Global Cycling Power Meters Market
Sports Equipment
Premium Bicycle Market
Sports Equipment
Dirt Bike Market
Sports Equipment
Surfing Equipment Market