
 Pickleball Pitching Machine Market | 2026-2036
Pickleball Pitching Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Pickleball Pitching Machine Market Insights
Aluminum alloy is hardening as the preferred frame material over steel in mid-tier pickleball pitching machines, cutting unit weight by nearly half without sacrificing ball-feed stability. Lobster Sports leverages its California manufacturing base to sustain rapid fulfillment cycles for domestic training centers. Spinshot differentiates through programmable spin-axis controls that occupy the premium tier of electronic machines. Sports Tutor anchors the institutional segment with fixed-court installations at high school athletic departments.
A pickleball pitching machine is an electromechanical or pneumatic device designed to propel polymer balls at controlled velocities, spin rates, and trajectories for repetitive stroke training; most units operate between 10 and 70 miles per hour with adjustable feed intervals of one to ten seconds. Portable electric machines lead unit shipments among product types, as lithium battery packs enable court-to-court mobility without dedicated power drops. Electronic technology commands the fastest expansion within the technology dimension, with automated ball-feed systems and smartphone app integration pulling replacement demand from mechanical legacy units. Fixed machines still dominate margin pools in the commercial end-user segment, where training centers amortize capital costs across high daily utilization rates.
The Consumer Product Safety Commission oversees electrical safety certification for powered sports equipment sold in the United States, while FCC regulations govern wireless connectivity modules in app-enabled machines. ISO 20957 standards for stationary training equipment provide voluntary design benchmarks that manufacturers increasingly adopt to access European and Asian-Pacific distribution channels. Stakeholders must monitor how state-level youth sports funding allocations and municipal court construction bonds reshape the addressable base of institutional buyers.
Market Dynamics
Lithium-ion battery density improvements are compressing the weight-to-runtime ratio for portable units, forcing fixed-installation vendors to defend their commercial stronghold through durability guarantees and multi-court networking capabilities.
Growth Catalysts
- Municipal Bond Programs:City infrastructure financing for public recreation facilities in the United States is expanding the installed base of institutional-grade machines at parks departments and community centers.
- Polymer Ball Consistency:Standardized USAPA-approved ball specifications are reducing calibration complexity for electronic feed systems, lowering the technical barrier for training center adoption.
- REACH Compliance Pathways:European manufacturers achieving full material disclosure certification are unlocking distribution access across EU member states previously blocked by chemical safety documentation gaps.
Market Restraints
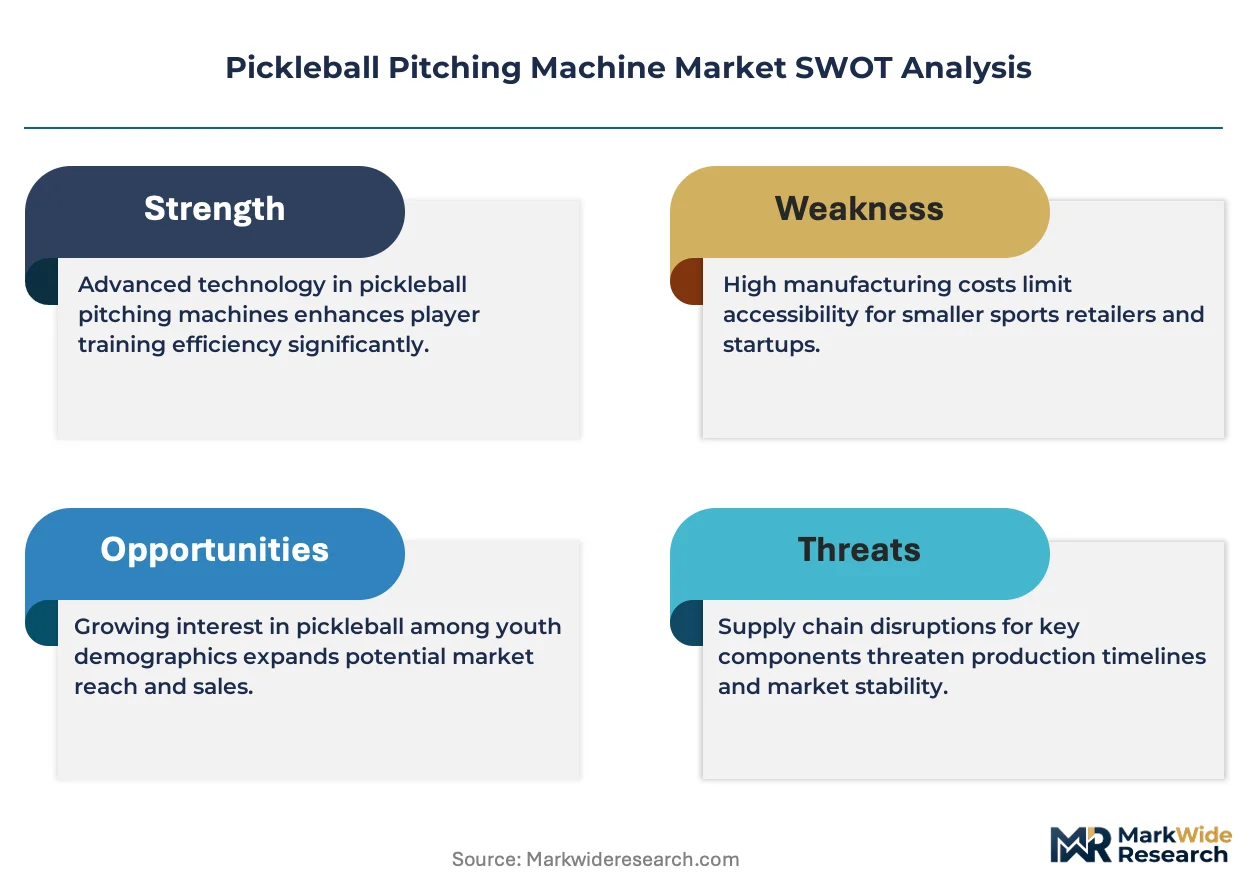
- Neodymium Magnet Supply:Brushless motor assemblies depend on rare earth elements concentrated in Chinese processing facilities, exposing production schedules to export quota volatility.
- Aluminum Alloy Price Swings:Mid-tier frame production faces margin compression when London Metal Exchange spot prices for 6061-grade aluminum spike above contract hedging levels.
- Ball Degradation Rates:High-velocity repetitive impact accelerates polymer fatigue, forcing training centers to maintain replacement inventories that inflate total cost of ownership calculations.
Strategic Opportunities
- India Recreation Infrastructure:The country's Smart Cities Mission allocations for public sports facilities remain largely untapped by automated training equipment suppliers, creating first-mover positioning for compliant entrants.
- CE Marking Acceleration:Voluntary ISO 20957 certification is hardening into a de facto import requirement across German and French distribution channels, rewarding early standardization investments with preferential shelf placement.
- App-Enabled Telemetry:Convergence of Bluetooth Low Energy modules with stroke-analytics software is opening subscription revenue streams that decouple vendor economics from unit sales cycles.
Industry Challenges
- Mechatronics Talent Scarcity:The intersection of pneumatic engineering and embedded firmware development commands salary premiums that strain R&D budgets at sub-scale manufacturers.
- UL Certification Timelines:Electrical safety validation for lithium-powered portable units averages fourteen months, compressing product launch windows against competitive pressure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pickleball Pitching Machine Market |
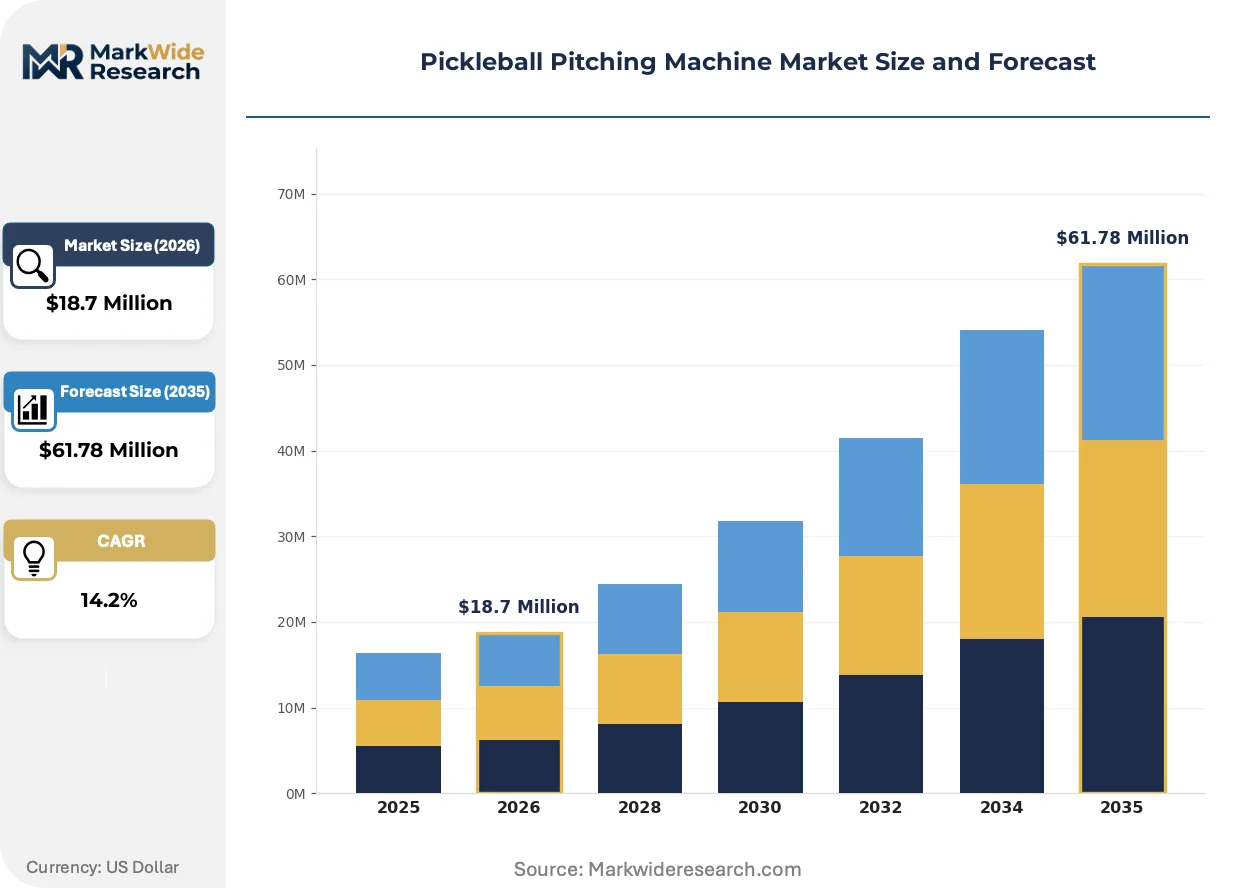
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $61.78 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Machines, Fixed Machines, Manual Machines, Electric Machines Technology: Mechanical, Pneumatic, Electronic, Automated End User: Schools, Training Centers, Gyms, Recreational Facilities Distribution Channel: Online Retail, Distributors, Specialty Stores, Direct Sales |
| Companies Covered | Lobster Sports, Pickleball Tutor, Erne Pickleball Machine, Titan Ball Machines, Sports Tutor, Snip Shot Sports, Metaltek, Spinshot, Slinger, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pickleball Pitching Machine Market Trends and Innovations
Electrification of mechanical subsystems is collapsing the traditional trade-off between portability and programmable control, while regulatory pressure on battery chemistry is reshaping supply chain qualification protocols.
Solid-state lithium-polymer packs are absorbing the runtime demands previously satisfied by lead-acid alternatives, extending cordless operation beyond six hours at full feed rates. Training centers in California and Florida are adopting these units for outdoor court rotation without generator dependency. The technology is absorbing market share from pneumatic legacy systems that require compressed air infrastructure.
The FCC's Part 15 rules for unlicensed radio frequency devices are tightening emission testing requirements for app-connected machines, adding third-party laboratory costs to product development cycles. Manufacturers targeting United States distribution are redesigning antenna architectures to ensure compliance ahead of enforcement phase-in. Electronic machine suppliers with existing wireless module certifications are capturing shelf space from competitors facing retesting delays.
Leasing arrangements are displacing outright purchase at municipal procurement departments, transferring maintenance liability to vendors and compressing upfront capital requirements. Sports equipment distributors in Texas and Arizona are building captive service fleets to support recurring revenue contracts. The model is most visible in school districts where bond-funded capital budgets face competing priorities from facility maintenance backlogs.
Pickleball Pitching Machine Market Segmentation
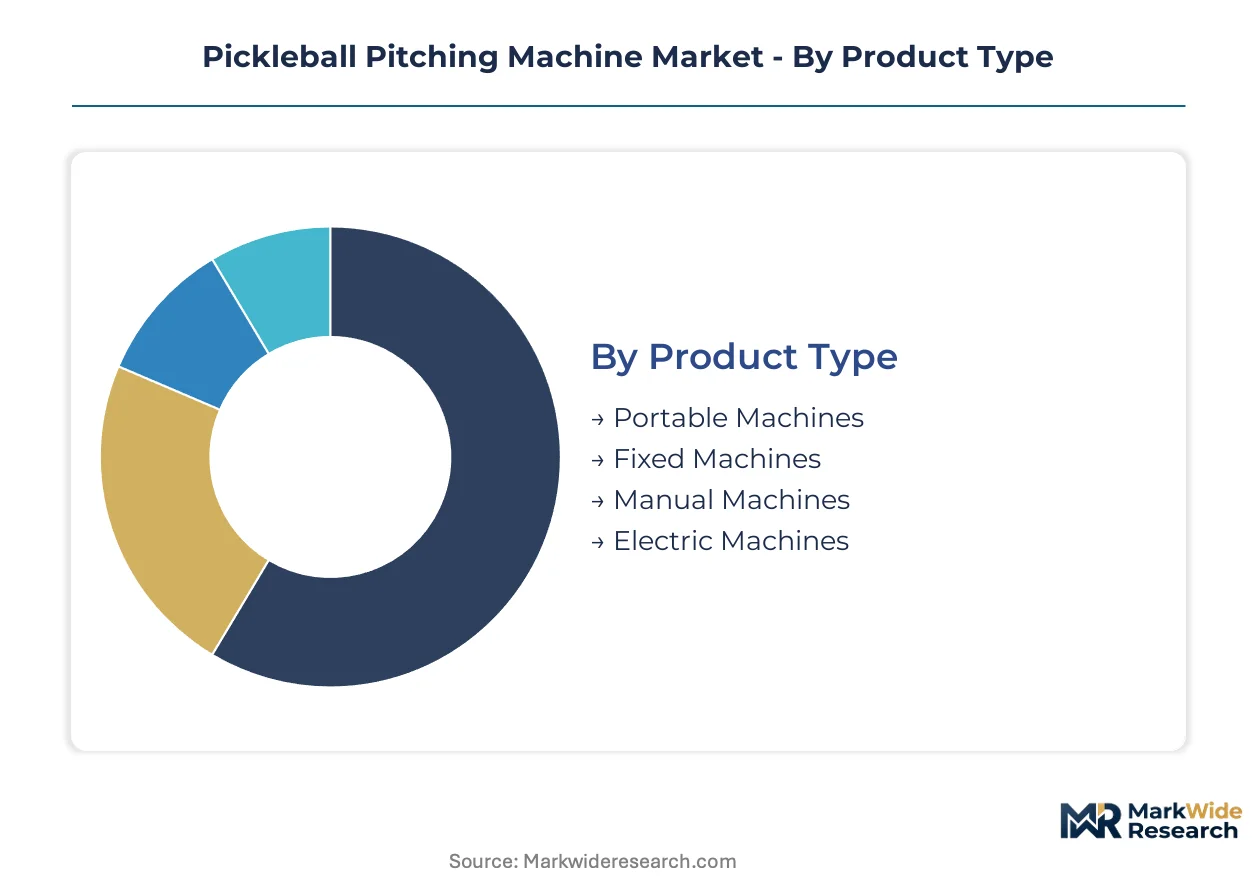
Segmentation in pickleball pitching machines reveals how certification burdens, mobility requirements, and procurement channels fragment vendor addressable markets. Each dimension carries distinct margin profiles and regulatory exposure that shape competitive positioning.
Product Type:
Portable electric machines require UL electrical safety validation and FCC emission testing for lithium-powered variants, while fixed installations face municipal building code inspections and OSHA workplace safety reviews.
- Portable Machines:Lithium-ion battery packs enable six-hour cordless operation at velocities up to 70 mph. Demand concentrates in California and Florida training centers seeking court-to-court rotation without generator dependency, though UL certification timelines averaging fourteen months compress product launch windows.
- Fixed Machines:Steel or aluminum alloy frames mount permanently to court surfaces with pneumatic or electric feed systems. High school athletic departments in Texas and Arizona amortize capital costs across high daily utilization rates, prioritizing durability guarantees over mobility features.
- Manual Machines:Spring-loaded or gravity-fed mechanisms require no electrical certification. Budget-constrained recreational facilities in municipal parks departments favor these units for basic stroke repetition without calibration complexity.
- Electric Machines:Brushless motor assemblies with programmable velocity controls. USAPA-approved ball standardization reduces feed system calibration requirements, lowering technical barriers for institutional adoption.
Portable Machines sit at the top of the volume ranking, with Electric Machines climbing the fastest.
Technology:
Cost tier stratification separates premium electronic systems from economy mechanical alternatives, with mid-tier pneumatic units defending position through compressed air infrastructure lock-in at existing training facilities.
- Mechanical:Spring-tension or counterweight propulsion without electrical components. Entry-level price points attract individual consumers through online retail channels, though limited velocity adjustment constrains advanced training applications.
- Pneumatic:Compressed air chambers deliver consistent ball velocity with lower maintenance than spring systems. Legacy installations at institutional facilities create switching costs that slow electronic replacement cycles.
- Electronic:Microprocessor-controlled motors with programmable spin-axis and trajectory adjustments. Smartphone app integration via Bluetooth Low Energy modules opens subscription revenue streams decoupled from unit sales.
- Automated:Ball-feed hoppers with randomized sequence programming and telemetry capture. FCC Part 15 compliance costs for wireless connectivity add third-party laboratory expenses that favor vendors with existing certifications.
Electronic technology commands the steepest expansion trajectory, while Mechanical systems retain residual share in price-sensitive consumer segments.
End User:
Application-specific durability requirements and procurement authority concentration determine sales cycle length, with institutional buyers demanding extended warranties and municipal vendors accepting leasing arrangements.
- Schools:Bond-funded capital budgets compete with facility maintenance backlogs, compressing upfront equipment allocations. Texas and Arizona districts increasingly favor recurring revenue contracts transferring maintenance liability to vendors.
- Training Centers:Professional coaching operations require programmable spin and velocity variability. California facilities lead fleet expansion as the sport professionalizes, absorbing premium electronic units with telemetry capabilities.
- Gyms:Multi-sport fitness centers prioritize compact footprint and rapid setup. Lease arrangements displace outright purchase as captive service fleets emerge among regional distributors.
- Recreational Facilities:Municipal parks departments depend on infrastructure financing for public court construction. United States city bond programs expand installed bases of institutional-grade machines at community centers.
Training Centers generate the highest revenue per account, with Recreational Facilities expanding most quickly through municipal infrastructure investment.
Distribution Channel:
Customer type and purchase urgency shape channel selection, with institutional procurement favoring relationship-based direct sales and individual consumers migrating to digital platforms.
- Online Retail:E-commerce platforms capture consumer segment volume with specification comparison tools and user review aggregation. Shipping constraints on machine weight limit penetration in portable electric categories.
- Distributors:Regional sports equipment networks provide installation support and maintenance services. Texas and Arizona distributors build captive service fleets to support recurring revenue contracts with school districts.
- Specialty Stores:Pro shop and tennis specialty retailers offer hands-on demonstration and immediate fulfillment. California manufacturing bases enable rapid fulfillment cycles for domestic training center demand.
- Direct Sales:Manufacturer field teams manage institutional procurement cycles with customized proposals. Extended payment terms and leasing documentation requirements favor established vendor relationships.
Distributors anchor institutional volume, with Online Retail gaining share fastest in consumer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California manufacturing clusters anchor global production capacity for pickleball pitching machines, with lithium-ion battery supply chains and precision machining capabilities concentrated in the western United States. Municipal bond programs and training center expansions are redrawing demand geography across four national markets.
United States
Training center fleet expansions in Florida and California absorb premium electronic units with programmable spin controls. FCC Part 15 regulations govern Bluetooth Low Energy modules in app-enabled machines, adding third-party laboratory costs to product development. Texas school districts favor leasing arrangements that transfer maintenance liability to regional distributors.
Canada
Municipal parks departments in Ontario and British Columbia leverage infrastructure financing for public court construction. Health Canada oversees electrical safety certification for powered sports equipment under CSA standards alignment. Vancouver training facilities adopt portable electric machines for indoor court rotation without ventilation requirements.
Germany
REACH compliance pathways unlock distribution access across EU member states previously blocked by chemical safety documentation gaps. CE marking hardens into de facto import requirements across German distribution channels. Bavarian sports equipment distributors prioritize ISO 20957-certified units for institutional procurement cycles.
United Kingdom
Specialty retailers in London and Southeast England offer hands-on demonstration for premium electronic machines. The country's national standards body aligns product safety benchmarks with ISO 20957 voluntary design specifications. Manchester training centers absorb fleet expansions as the sport professionalizes across northern England.
Australia
Recreational facilities in New South Wales and Victoria depend on municipal infrastructure investment for public court construction. The Therapeutic Goods Administration does not regulate sports equipment, leaving electrical safety to state-level consumer protection frameworks. Melbourne coaching operations require programmable velocity variability for competitive stroke training.
Pickleball Pitching Machine Market Competitive Landscape
Product portfolio diversification dominates the current landscape as vendors defend margin pools against lithium-ion battery commoditization. The vendor base organizes around three tiers: California-based manufacturers with rapid domestic fulfillment cycles, European specialists pursuing REACH compliance for EU market access, and Asian fabricators competing on portable unit cost structures. Strategic archetypes include premium-tier electronics specialists, mid-tier aluminum frame assemblers, and value-tier mechanical legacy defenders. Technology licensing agreements and captive service fleet construction represent the dominant competitive moves.
Among California-based manufacturers, Lobster Sports exemplifies rapid fulfillment positioning for domestic training center demand. Spinshot occupies a position within the premium-tier electronics segment through programmable control differentiation. Sports Tutor anchors the institutional fixed-installation segment where durability guarantees and multi-court networking capabilities defend commercial strongholds.
| Leading Market Players |
|---|
| Lobster Sports |
| Pickleball Tutor |
| Erne Pickleball Machine |
| Titan Ball Machines |
| Sports Tutor |
| Snip Shot Sports |
| Metaltek |
| Spinshot |
| Slinger |
| Others |
Pricing and Supply Chain Analysis
Municipal leasing preferences in Texas and Arizona school districts are compressing upfront capital outlays and forcing manufacturers to absorb lifecycle maintenance costs, which in turn tightens component sourcing standards and squeezes margin buffers across mid-tier frame assemblers.
Pricing Analysis
Aluminum alloy spot price volatility on the London Metal Exchange passes directly into portable machine frame costs, with 6061-grade swings compressing margins for mid-tier assemblers unable to hedge contract volumes. Three-tier pricing structure across premium, standard, and economy levels separates FCC-certified electronic units with Bluetooth telemetry from basic pneumatic systems and uncertified manual alternatives. Pricing pressure stems from lithium-ion battery commoditization as Chinese cell manufacturers flood export markets. Training centers in California demonstrate lowest price sensitivity while municipal parks departments in Florida face strict bond-funded budget caps.
Supply Chain Analysis
Neodymium magnet supply for brushless motor assemblies rests on Chinese rare earth processing facilities concentrated in Inner Mongolia and Jiangxi provinces, exposing production schedules to export quota volatility. Aluminum 6061 extrusions draw from domestic mills in Ohio and Pennsylvania, while lithium-ion cell supply sources from South Korean and Japanese producers. Tariff exposure on finished electronics from Asian fabricators threatens margin stability for value-tier entrants. Distribution runs through regional sports equipment networks in Texas and Arizona that provide installation support and captive service fleets for institutional leasing contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory layering, where FCC Part 15 certification timelines averaging fourteen months create defensive moats for early-compliant vendors against retesting delays.
For Market Incumbents: Acquire captive service fleet capabilities to capture recurring revenue from municipal leasing contracts displacing outright purchase. Secure multi-year aluminum supply agreements with Ohio and Pennsylvania mills before spot price spikes compress frame margins. Lobster Sports and Spinshot face emerging threat from Asian cost-optimized entrants in portable electric categories; certification investment in UL and FCC pre-approval buffers defends shelf space. For New Entrants and Emerging Players: The gap between premium electronic units with telemetry subscription potential and economy manual machines without certification requirements opens white-space positioning for mid-tier programmable pneumatic alternatives. Target underpenetrated municipal parks departments in Florida and Arizona where bond-funded court construction outpaces machine fleet deployment. Lead with leasing documentation expertise to bypass capital budget competition with facility maintenance backlogs. For Investors and Strategic Acquirers: Asymmetric upside sits with California-based manufacturers possessing rapid domestic fulfillment cycles and existing FCC wireless module certifications. Long-term viability favors vendors decoupling economics from unit sales through app-enabled telemetry subscription streams. Watch for inflection where REACH compliance acceleration in German distribution channels rewards early standardization investments with preferential procurement positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Cell Supply | Captive battery sourcing insulates runtime performance claims from Chinese export quota volatility. |
| FCC Pre-Certification Investment | Early Part 15 compliance locks in fourteen-month lead time advantage over retesting competitors. |
| Leasing Fleet Service Buildout | Recurring revenue contracts with Texas school districts transfer maintenance liability from municipal budgets. |
| REACH Compliance Acceleration | Full material disclosure certification unlocks German and French distribution channels blocked by documentation gaps. |
| Telemetry Platform Development | Bluetooth Low Energy stroke analytics open subscription economics decoupled from hardware replacement cycles. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with training center operators in California and Florida, municipal procurement officers in Texas and Arizona, and regional distributor service heads with secondary validation against FCC equipment authorization databases, UL certification registries, and municipal bond disclosure filings. Bottom-up unit shipment estimates triangulated against top-down addressable court construction projections.
Comparable historical utilization rates at high school athletic departments and training center fleet rotation patterns anchored the projection horizon across product type, technology tier, end-user category, and distribution channel dimensions. CAGRs derived from segment-level growth trajectory blending and cross-referenced against lithium-ion battery density improvement curves and aluminum price elasticity assumptions.
Caveats apply where neodymium export quota volatility or UL certification timeline extensions could materially shift the outlook for portable electric unit availability. A small set of named triggers—municipal bond program cancellations, REACH enforcement phase-in acceleration, and solid-state battery commercialization timelines—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Global Skateboard Market
Sports Equipment
Sponge Wrestling Mat Market
Sports Equipment
Parallel Bars Market
Sports Equipment
Global Golf Training Aids Market
Sports Equipment
Racket Sports Equipment Market
Sports Equipment
Table Tennis Equipment Market
Sports Equipment
Riding Gear Market
Sports Equipment
Baseball Sliding Mitts Market
Sports Equipment
Global Badminton Equipment Market
Sports Equipment
Synthetic Ice Skating Rink Market
Sports Equipment
Global Stand Up Paddle (SUP) Boards Market
Sports Equipment
Gymnastic Bars Market
Sports Equipment
Mouthguard Market
Sports Equipment
Skating Shoes Market
Sports Equipment
Sports Protection Equipment Market
Sports Equipment
Surfboard Market