
 Trans-Resveratrol Market | 2026-2036
Trans-Resveratrol Market Size, Share, and Industry Trends Forecast 2026-2036
Trans-Resveratrol Market Analytics
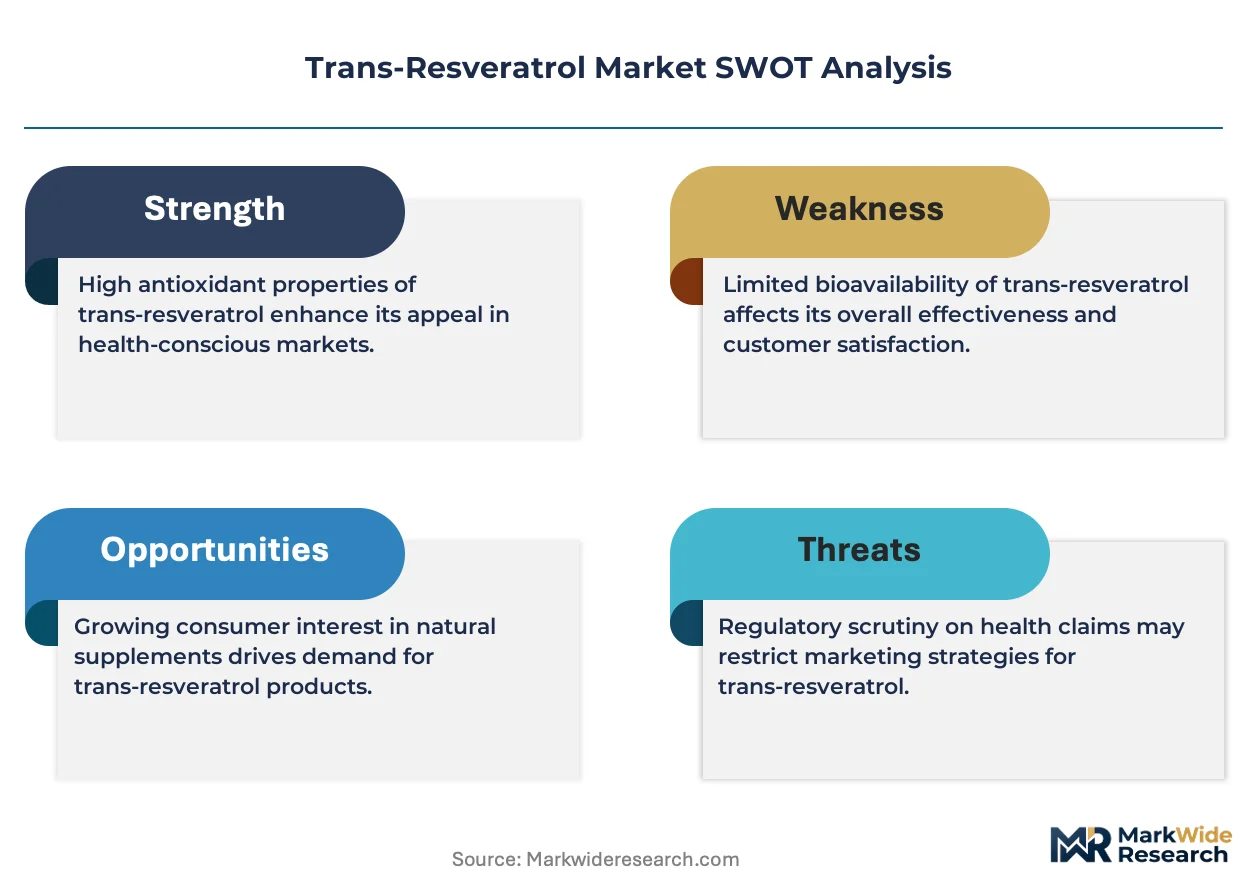
REACH is recalibrating the cost-of-entry calculus for European suppliers of trans-resveratrol by mandating exhaustive substance safety dossiers that smaller extractors cannot fund. DSM leverages its integrated biotechnology platform to sustain cost advantages across fermentation-derived resveratrol. Evolva anchors its position through synthetic biology expertise that controls yield consistency at industrial scale. Sabinsa Corporation differentiates via vertical integration into raw botanical sourcing and proprietary extraction protocols.
Trans-resveratrol is a stilbenoid polyphenol, specifically the trans-isomer of 3,5,4'-trihydroxystilbene, typically standardized to 98% purity for pharmaceutical applications and synthesized through either grape-skin extraction or microbial fermentation. Its primary commercial purpose centers on antioxidant, anti-inflammatory, and sirtuin-activating bioactivity that drives formulation in longevity-focused therapeutics and preventive health products. Among product types, capsules capture the dominant share of consumer-facing revenue while powders command premium pricing from nutraceutical firms integrating bulk active ingredients. Within applications, dietary supplements represent the established volume base, whereas functional foods are attracting accelerated R&D investment as delivery-format innovation broadens addressable consumption occasions.
The FDA's NDI notification process and the EFSA's novel food assessments jointly determine which trans-resveratrol sources achieve lawful market access in their respective jurisdictions, with fermentation-derived variants facing distinct toxicological scrutiny versus plant-extracted equivalents. China's NMPA and SAMR are converging on stricter purity and origin-labeling standards that reshape export competitiveness for domestic manufacturers. Stakeholders must monitor how regulatory divergence between biosynthetic and botanical qualification pathways reshapes supplier eligibility and procurement risk across major demand centers.
Market Dynamics
Fermentation-derived production is displacing botanical extraction as the dominant supply modality, compressing cost structures and recalibrating purity benchmarks across pharmaceutical and nutraceutical procurement channels.
Growth Catalysts
- Sirtuin-activating therapeutics:Cardiovascular drug pipelines at major pharmaceutical firms are expanding clinical programs targeting NAD+ pathways and mitochondrial health, pulling pharmaceutical-grade trans-resveratrol volumes upward.
- REACH substance registration:The European chemicals framework is consolidating supplier bases by mandating comprehensive safety dossiers that favor capitalized fermentation operators over small-batch extractors.
- China's dual carbon goals:Beijing's emissions reduction mandates are accelerating investment in microbial cell factories as lower-carbon alternatives to solvent-intensive grape-skin processing.
Market Restraints
- Picrotoxin contamination risk:Botanical sources from Polygonum cuspidatum carry trace alkaloid burdens that trigger FDA import alerts and destroy batch economics.
- Shaanxi Province concentration:Over 60% of global extraction capacity sits within a 200-kilometer radius, exposing buyers to single-point climate and logistics disruptions.
- Synthetic biology yield ceilings:Current Saccharomyces cerevisiae strains plateau at sub-10 g/L titers, constraining unit cost reductions against mature chemical synthesis.
Strategic Opportunities
- Functional food integration:Beverage and fortified dairy categories in Germany and Switzerland are piloting microencapsulated resveratrol for stability in aqueous matrices.
- Personalized longevity protocols:Direct-to-consumer biomarker testing platforms are creating subscription-based demand for precision-dosed polyphenol stacks.
- India's PLI scheme:Production-linked incentives for active pharmaceutical ingredients are drawing contract fermentation investment toward Gujarat and Telangana clusters.
Industry Challenges
- Metabolic engineering talent scarcity:Strain optimization requires rare hybrid skill sets spanning synthetic biology and industrial bioprocess engineering, with fewer than 200 qualified specialists globally.
- Novel food authorization timelines:EFSA's 18-24 month assessment windows for fermentation-derived ingredients freeze product launch schedules and tie up working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trans-Resveratrol Market |
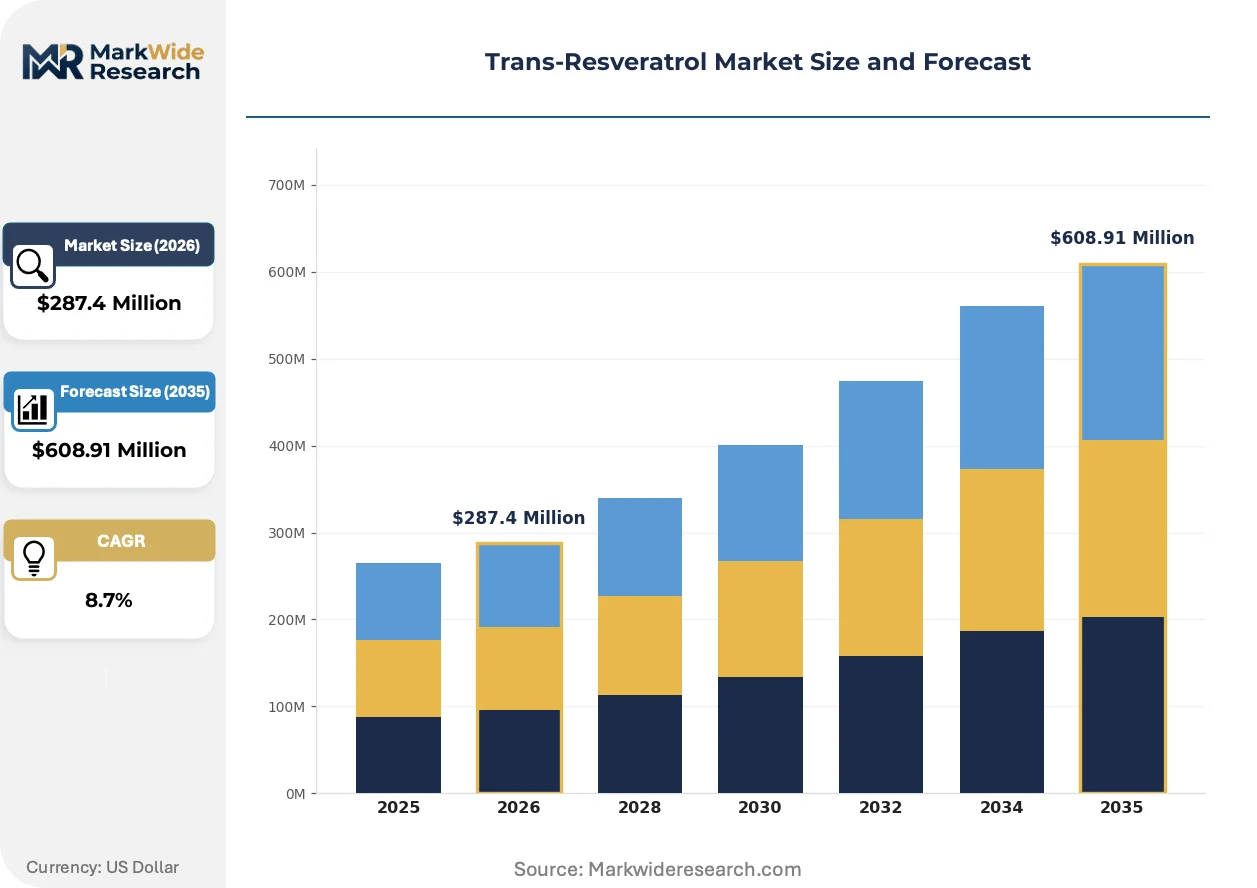
| Market Size in 2026 | $287.4 Million |
| Market Size in 2035 | $608.91 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Powders, Tablets, Liquids End User: Retail Consumers, Research Institutions, Pharmaceutical Companies, Nutraceutical Firms Distribution Channel: Online Retailers, Drugstores, Supermarkets, Specialty Stores Application: Dietary Supplements, Cosmetics, Pharmaceuticals, Functional Foods |
| Companies Covered | DSM, Evolva, Sabinsa Corporation, Maypro, Laurus Labs, Resveratrol Partners, Biotivia, RevGenetics, NutraBio Labs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trans-Resveratrol Market Evolving Landscape
Continuous bioprocessing and precision fermentation are collapsing the traditional batch-based manufacturing paradigm, while regulatory frameworks diverge on how biosynthetic botanicals qualify for market access.
Precision fermentation platforms using engineered Yarrowia lipolytica strains are decentralizing production geography by enabling distributed manufacturing at smaller scales with equivalent purity outputs. Pharmaceutical contract manufacturers in Denmark and Singapore are adopting these systems to reduce dependence on Chinese bulk supply. The technology is decentralizing procurement patterns as buyers establish dual-source strategies combining regional fermentation capacity with legacy extraction contracts.
EFSA's novel food assessment protocols are tightening toxicological requirements for microbially derived resveratrol compared to plant-extracted equivalents, creating a two-tier compliance burden. Fermentation operators must now submit extended 90-day rodent studies and metabolite profiling data that grape-skin extractors bypass. European nutraceutical formulators are responding by segregating supply chains and labeling provenance to maintain premium positioning.
Longevity clinics and concierge medicine practices are consolidating purchase volumes through group purchasing organizations that bypass traditional ingredient distributors. These direct contracts specify purity thresholds and certificate-of-analysis requirements that commodity traders cannot fulfill. The shift is most pronounced in Switzerland and the United Arab Emirates, where high-net-worth patient populations drive demand for pharmaceutical-grade polyphenol protocols.
Trans-Resveratrol Market Segmentation
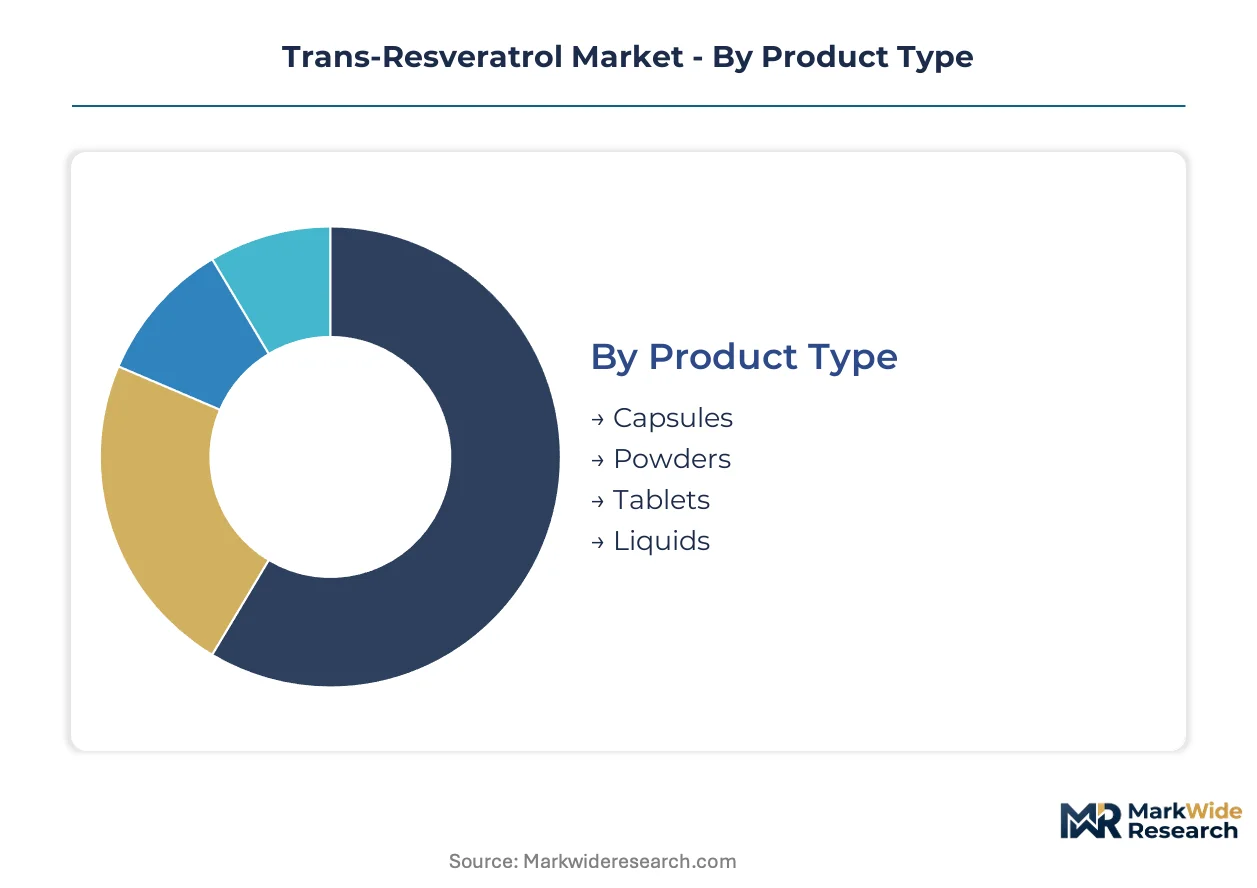
Trans-resveratrol procurement patterns diverge sharply across delivery formats and buyer categories, with fermentation-derived supply concentrating in pharmaceutical-grade channels while botanical extraction feeds commodity nutraceutical markets. Understanding these segment boundaries clarifies where purity premiums command pricing power versus where cost compression dominates.
Product Type:
Capsule and powder formats concentrate the highest-value procurement from pharmaceutical and nutraceutical manufacturers, with supply contracts specifying 98% purity thresholds and certificate-of-analysis documentation that liquid and tablet formats rarely match.
- Capsules:Gelatin and vegetable-shell delivery systems dominate consumer-facing revenue through standardized dosing convenience. Demand concentrates in direct-to-consumer longevity protocols across Switzerland and the United Arab Emirates, where concierge medicine practices specify pharmaceutical-grade polyphenol stacks with batch-traceable documentation.
- Powders:Bulk active ingredient format commands premium pricing from nutraceutical firms integrating trans-resveratrol into multi-ingredient formulations. Supply concentrates with DSM and Evolva's fermentation platforms, which guarantee yield consistency that grape-skin extraction cannot match for high-volume pharmaceutical contracts.
- Tablets:Compressed delivery format suits mass-market dietary supplement positioning with lower purity tolerances.
- Liquids:Aqueous suspensions serve functional food pilots in German and Swiss beverage categories requiring microencapsulation stability.
Today's leader: Powders. Tomorrow's challenger: Capsules.
End User:
Pharmaceutical companies and nutraceutical firms drive divergent purity requirements, with drug pipelines mandating fermentation-derived supply while supplement brands tolerate botanical extraction's trace alkaloid burdens.
- Pharmaceutical Companies:Cardiovascular and neuroprotective drug pipelines at major firms specify pharmaceutical-grade trans-resveratrol with exhaustive safety dossiers satisfying FDA New Dietary Ingredient notifications and EMA quality standards. Procurement concentrates through group purchasing organizations that bypass traditional distributors.
- Nutraceutical Firms:Formulation houses integrate bulk powders into multi-ingredient longevity stacks, prioritizing cost structures over single-batch purity documentation. Demand clusters in China's domestic market, where SAMR's tightening origin-labeling standards reshape export competitiveness.
- Retail Consumers:Individual purchasers through direct-to-consumer channels specify subscription-based precision dosing.
- Research Institutions:Academic and clinical trial sponsors require small-batch, high-characterization material for mechanistic studies.
Pharmaceutical companies anchor current volume. Nutraceutical firms are climbing the fastest as functional food R&D accelerates.
Distribution Channel:
Channel selection determines documentation depth, with specialty stores and online retailers capturing premium-positioned supply while supermarkets and drugstores move commodity-grade inventory.
- Online Retailers:E-commerce platforms consolidate subscription-based demand for precision-dosed polyphenol stacks, with biomarker testing platforms creating recurring revenue models. Longevity clinics in Switzerland leverage direct contracts specifying purity thresholds that commodity traders cannot fulfill.
- Specialty Stores:Premium health and wellness retailers curate pharmaceutical-grade capsules with provenance labeling that justifies price positioning against mass-market alternatives.
- Drugstores:Pharmacy chains stock standardized dietary supplement formats with lower documentation requirements.
- Supermarkets:Mass-market grocery channels prioritize cost-competitive tablets and liquids for casual wellness consumers.
Specialty stores defend margin position through curation. Online retailers are expanding most quickly via subscription models.
Application:
Dietary supplements and functional foods represent divergent growth trajectories, with established supplement volumes facing pressure from accelerated R&D investment in fortified food matrices.
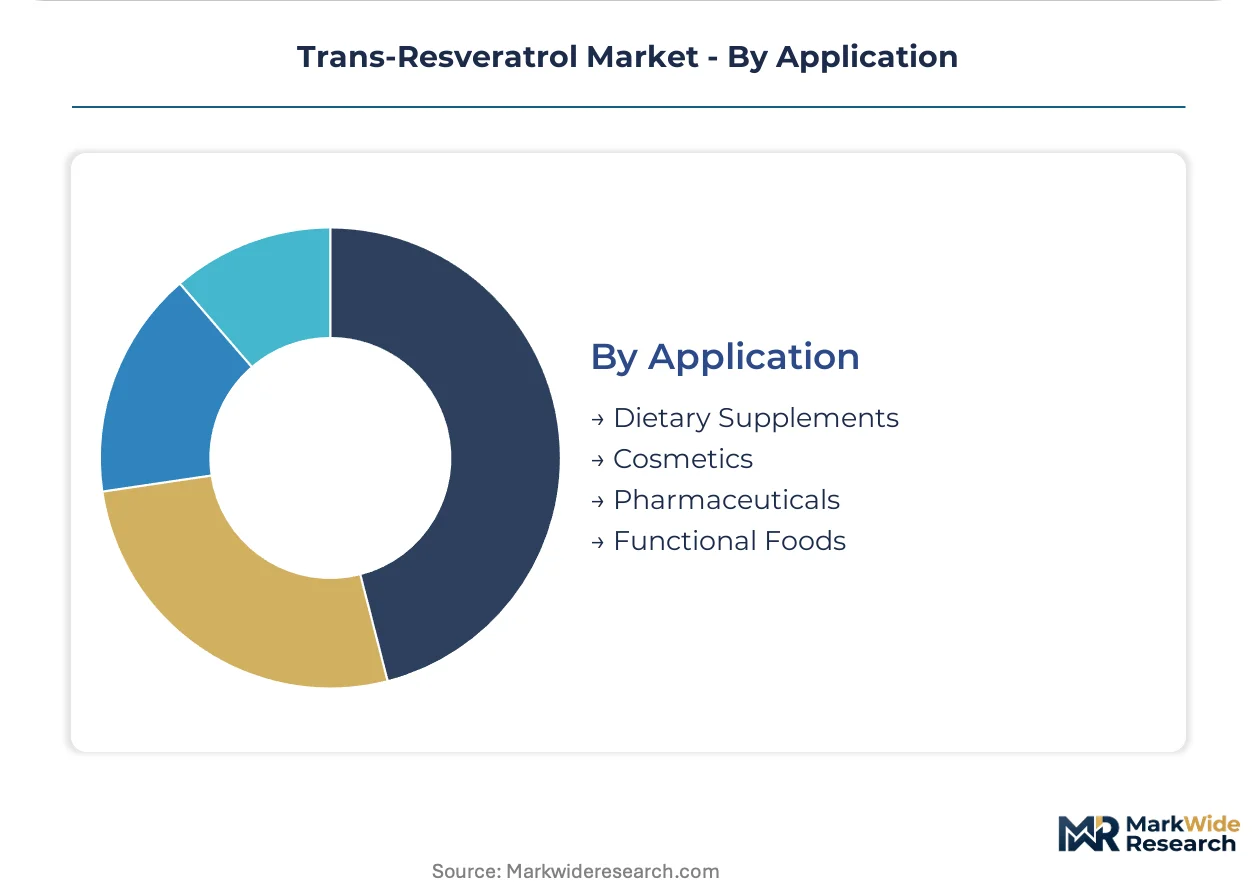
- Dietary Supplements:Capsule and tablet formats constitute the established volume base for preventive health positioning. Demand concentrates in North American and European markets where FDA and EFSA regulatory pathways are well-mapped for botanical extracts.
- Functional Foods:Beverage and fortified dairy categories in Germany and Switzerland pilot microencapsulated resveratrol for stability in aqueous matrices, broadening addressable consumption occasions beyond pill-fatigued demographics.
- Pharmaceuticals:Drug development pipelines target sirtuin-activating therapeutics with NAD+ pathway modulation.
- Cosmetics:Topical antioxidant formulations leverage trans-resveratrol's anti-inflammatory bioactivity for premium skincare positioning.
Dietary supplements maintain current dominance. Functional foods present the steepest expansion trajectory as delivery-format innovation matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Synthetic biology talent clusters in Basel, Boston, and Shanghai anchor the geographic distribution of trans-resveratrol innovation, with each hub feeding distinct regulatory and supply chain ecosystems.
United States
Cardiovascular drug pipelines at Boston and San Francisco biotech clusters pull pharmaceutical-grade volumes upward. FDA New Dietary Ingredient notification requirements tighten purity thresholds for botanical extracts entering US commerce. Greater Boston hosts contract fermentation operators adopting continuous bioprocessing to reduce dependence on Chinese bulk supply.
China
Domestic fermentation-based production capacity scales rapidly in Jiangsu and Shandong provinces to serve preventive health demand. SAMR and NMPA converge on stricter purity and origin-labeling standards that reshape export competitiveness. Shaanxi Province concentrates over sixty percent of global extraction capacity within a two-hundred-kilometer radius, exposing buyers to climate and logistics disruptions.
Switzerland
Longevity clinics and concierge medicine practices in Zurich and Geneva consolidate purchase volumes through group purchasing organizations. Swissmedic maintains exacting pharmaceutical-grade standards that commodity traders cannot fulfill. Basel anchors DSM's integrated biotechnology platform sustaining cost advantages across fermentation-derived supply.
Germany
Beverage and fortified dairy categories pilot microencapsulated resveratrol for stability in aqueous matrices. REACH mandates exhaustive substance safety dossiers that smaller extractors cannot fund, consolidating supplier bases toward capitalized fermentation operators. Bavaria and Baden-Württemberg house precision fermentation adopters establishing dual-source procurement strategies.
India
Production-linked incentives for active pharmaceutical ingredients draw contract fermentation investment toward Gujarat and Telangana clusters. CDSCO alignment with ICH guidelines accelerates novel ingredient approval pathways for export-oriented manufacturers. Hyderabad's biopharma corridor attracts strain optimization specialists commanding premium compensation.
Trans-Resveratrol Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a bifurcated supplier base. Fermentation-derived supply concentrates with biotechnology platforms commanding pharmaceutical-grade contracts, while botanical extraction feeds commodity nutraceutical markets. Three archetypes dominate: integrated life-science conglomerates with captive fermentation capacity, synthetic biology pure-plays controlling yield consistency, and vertically integrated botanical extractors with proprietary sourcing protocols. Capacity expansion and backward integration into raw material supply represent the dominant competitive moves reshaping procurement risk profiles.
Within the integrated biotechnology tier, DSM leverages its Basel-anchored platform to sustain cost advantages across fermentation-derived supply. Evolva exemplifies the synthetic biology pure-play archetype through industrial-scale yield consistency. Sabinsa Corporation anchors the botanical extraction vector with upstream control over raw material sourcing and proprietary extraction protocols.
| Leading Market Players |
|---|
| DSM |
| Evolva |
| Sabinsa Corporation |
| Maypro |
| Laurus Labs |
| Resveratrol Partners |
| Biotivia |
| RevGenetics |
| NutraBio Labs |
| Others |
Value Network & Pricing Analysis
Fermentation substrate costs cascade through pharmaceutical-grade purity premiums as buyers arbitrage between Chinese botanical extraction and European microbial cell factory output. REACH registration burdens and FDA NDI documentation requirements stratify procurement economics across buyer archetypes.
Pricing Analysis
Certificate-of-analysis bundling separates pharmaceutical contract manufacturers from commodity nutraceutical traders. Three-tier pricing structure across premium, standard, and economy levels reflects purity thresholds, with fermentation-derived 98% grades commanding substantial premiums over Polygonum cuspidatum extracts. Cost compression in botanical grades is intensifying because Shaanxi Province extraction capacity expansion outpaces quality differentiation. Nutraceutical formulators exhibit highest price sensitivity, while longevity clinics in Switzerland and the United Arab Emirates demonstrate inelastic demand for batch-traceable documentation.
Supply Chain Analysis
Freight cost volatility from Shaanxi Province to European pharmaceutical hubs is reshaping dual-source procurement strategies. Supply concentrates in China, Switzerland, and India, with Jiangsu fermentation platforms drawing investment from contract manufacturers seeking geographic diversification. Raw material dependencies span glucose feedstocks, engineered yeast strains, and grape-skin biomass from designated cultivation zones. Single-source vulnerability in Shaanxi's 200-kilometer extraction radius exposes buyers to climate disruption. Distribution runs through group purchasing organizations for pharmaceutical-grade volumes, while commodity nutraceutical channels rely on traditional ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Trans-resveratrol functions as a stable compounder anchored by irreversible pharmaceutical pipeline commitments to sirtuin-activating therapeutics and NAD+ pathway modulation.
For Market Incumbents: Deploy continuous bioprocessing technology to collapse batch manufacturing economics and defend against precision fermentation entrants. DSM and Evolva should accelerate backward integration into proprietary yeast strain libraries, while Sabinsa Corporation must tighten upstream control over Polygonum cuspidatum cultivation to mitigate picrotoxin contamination alerts from FDA. Capacity addition in Gujarat and Telangana clusters under India's PLI scheme threatens cost structures for European fermentation operators. For New Entrants and Emerging Players: Capture functional food integration opportunities in German beverage and Swiss fortified dairy categories before delivery-format innovation matures. Microencapsulation stability for aqueous matrices remains underpenetrated relative to established capsule and powder formats. Direct-to-consumer biomarker testing platforms offer a subscription-based go-to-market angle that bypasses traditional distributor relationships and commands recurring revenue premiums. For Investors and Strategic Acquirers: Consolidation pressure builds where metabolic engineering talent scarcity intersects with capital-intensive fermentation scale-up requirements. The 5-10 year viability window favors synthetic biology pure-plays with demonstrated industrial-scale yield consistency over botanical extraction operators facing regulatory headwinds. Acquire targets with captive strain optimization capabilities and existing EFSA novel food dossiers. Watch for EFSA toxicological assessment timeline compression as the inflection signal for fermentation-derived supply eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Engineered Yarrowia lipolytica platforms enable distributed manufacturing outside Shaanxi concentration. |
| Regulatory Dossier Investment | EFSA 90-day rodent studies and metabolite profiling secure novel food authorization for microbial supply. |
| Backward Integration into Strain Libraries | Proprietary Saccharomyces cerevisiae optimization protects yield consistency against talent scarcity. |
| Functional Food Formulation Partnerships | Microencapsulation R&D with German beverage pilots broadens addressable consumption occasions. |
| Group Purchasing Organization Contracts | Direct agreements with Swiss longevity clinics bypass commodity distributors and secure premium pricing. |
Research Methodology
Bottom-up pharmaceutical and nutraceutical procurement modeling reconciled against top-down fermentation capacity and extraction output tracking forms the analytical core of this study. Primary interviews with drug development executives at cardiovascular pipeline sponsors, regulatory affairs leads navigating FDA NDI pathways, procurement managers at group purchasing organizations, and strain optimization specialists at contract fermentation operators combined with secondary validation. Secondary sources include FDA New Dietary Ingredient notifications, EFSA novel food assessment registers, SAMR origin-labeling directives, customs trade data for resveratrol HS codes, and SEC filings from disclosed biotechnology platforms.
Historical trendline analysis of purity-grade pricing spreads and production modality shifts informed projection modeling across the analysis window. Segmentation dimensions encompass product type, end user category, application, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating sirtuin-activating therapeutic pipeline advancement rates and functional food R&D investment trajectories. Forecast inputs include strain titer improvement curves and EFSA assessment queue processing speeds.
Regulatory authorization delays, fermentation yield plateauing, and botanical contamination events are the dominant revision risks to modeled outputs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Australia Water Enhancer Market
Food Enhancers and Additives
Canada Food Flavor and Enhancer Market
Food Enhancers and Additives
Emulsifier Alternatives Market
Food Enhancers and Additives
Resveratrol Market
Food Enhancers and Additives
Flour Improvers Market
Food Enhancers and Additives
Liquid Smoke Market
Food Enhancers and Additives
South Korea Fat Replacers Market
Food Enhancers and Additives
Australia & New Zealand Food Flavors and Enhancers Market
Food Enhancers and Additives
United Kingdom Water Enhancer Market
Food Enhancers and Additives
Feed Palatability Enhancers and Modifiers Market
Food Enhancers and Additives
Mexico Food Flavor and Enhancer Market
Food Enhancers and Additives
Africa Food Flavor and Enhancer Market
Food Enhancers and Additives
Fortified Salts Market
Food Enhancers and Additives
Europe Food Flavor and Enhancer Market
Food Enhancers and Additives
North America Feed Palatability Enhancers Market
Food Enhancers and Additives
Crumb Softener Market