
 Raising Agents Market | 2026-2036
Raising Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Raising Agents Market Analysis
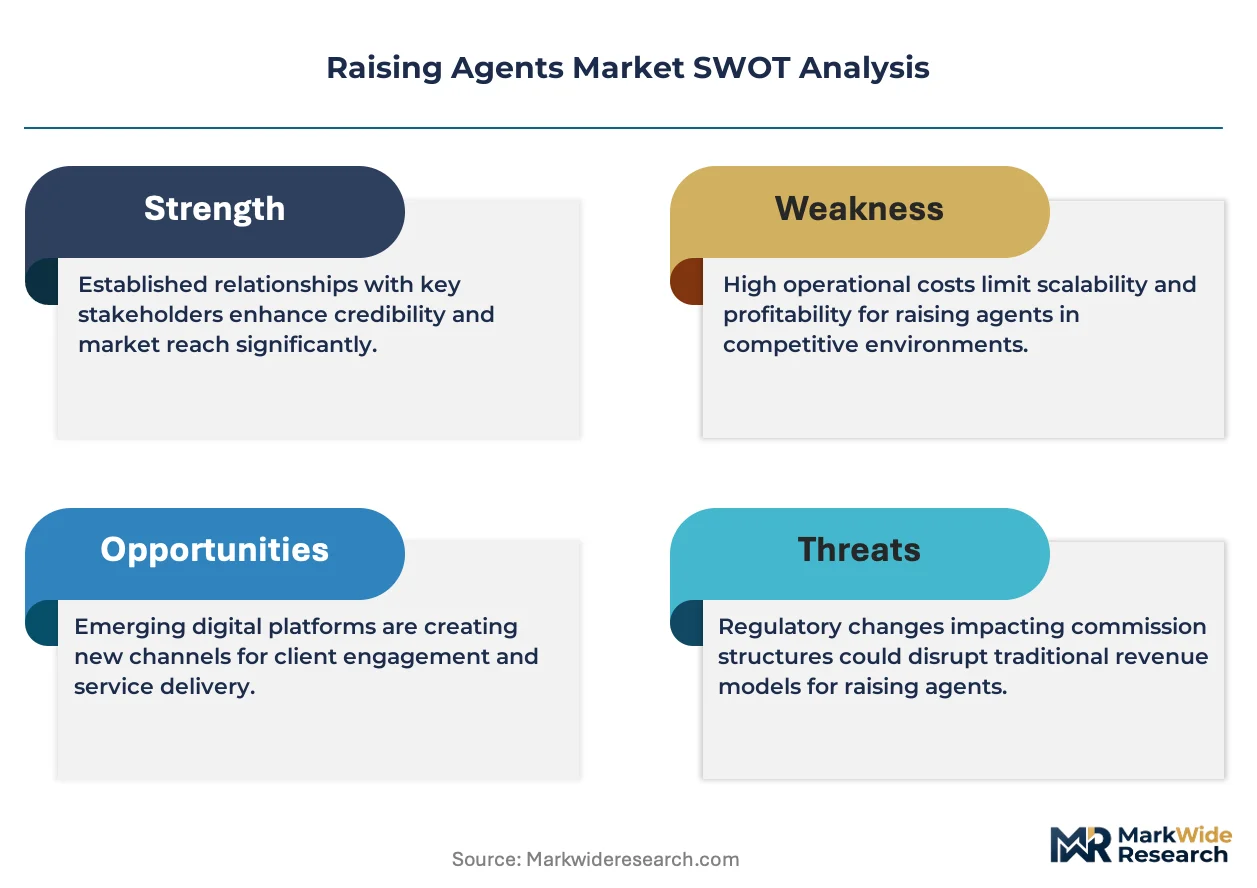
Asset-light leasing of fermentation capacity is narrowing the competitive field for mid-tier entrants. Lesaffre Group leverages its global yeast propagation infrastructure to sustain long-term supply contracts with industrial bakeries. Corbion N.V. specializes in emulsifier-raising agent blends that command premium positioning in European retail channels. Tata Chemicals Limited anchors its position through backward integration into soda ash production, insulating margins from raw material volatility.
Raising agents are functional additives that generate carbon dioxide gas through acid-base reactions or biological fermentation, typically operating within pH ranges of 6.5 to 7.5 and temperature thresholds between 35°C and 60°C to achieve optimal dough expansion in baked goods. Baking powder dominates commercial volume due to its standardized reactivity and extended shelf stability, though yeast captures expanding share in clean-label segments where biological leavening replaces chemical alternatives. Among applications, bread consumes the largest share of industrial-grade raising agents, while pastries represent the fastest-growing category as laminated dough production scales in foodservice channels.
EFSA purity standards and FDA GRAS notifications govern allowable acidulants and anti-caking agents in commercial baking powders, while EU organic certification requirements restrict synthetic phosphate sources in products labeled for natural retail channels. These frameworks elevate compliance costs for cross-border suppliers but simultaneously reward manufacturers with dual-certified production lines. Stakeholders must monitor evolving sodium reduction mandates, as regulators in multiple jurisdictions review maximum permissible levels in chemically leavened products.
Market Dynamics
Clean-label reformulations under EFSA and FDA phosphate reduction mandates are compressing demand for traditional aluminum phosphate baking powders while redirecting R&D investment toward organic acidulants and biological fermentation systems. This regulatory pivot is forcing simultaneous reformulation of shelf-stable and refrigerated product lines.
Growth Catalysts
- EU Organic Certification:Retailers in Germany and France now require phosphate-free leavening systems for private-label bread and pastry ranges, accelerating biological raising agent adoption in industrial bakeries serving these channels.
- Foodservice Laminated Dough Expansion:European café chains are scaling centralized production of croissants and Danish pastries, creating concentrated demand for high-activity yeast strains with precise temperature tolerance profiles.
- Sodium Reduction Mandates:Multiple national health authorities are reviewing maximum permissible sodium levels in chemically leavened baked goods, driving substitution toward potassium-based and yeast-leavened alternatives.
Market Restraints
- Soda Ash Price Volatility:Sodium carbonate feedstock costs fluctuate with energy-intensive Solvay process economics, compressing margins for synthetic baking powder manufacturers without backward integration into alkali production.
- Yeast Supply Concentration:Commercial yeast propagation capacity clusters in northern France and southern Germany, creating geographic single-point-of-failure exposure for industrial bakeries dependent on just-in-time liquid yeast delivery.
- Clean-Label Shelf Stability Trade-off:Phosphate-free and organic-certified raising agents exhibit reduced ambient storage life compared to conventional formulations, limiting distribution radius for reformulated products.
Strategic Opportunities
- Eastern European Industrial Bakery Modernization:Poland and Romania are consolidating fragmented artisanal baking sectors into centralized production facilities, opening greenfield demand for automated dosing systems and standardized raising agent supply contracts.
- Precision Fermentation Convergence:Integration of synthetic biology with traditional yeast propagation promises strain customization for specific dough rheology requirements, enabling premium positioning in specialty bread segments.
- Direct-to-Industrial Digital Platforms:Specialty ingredient distributors are launching e-procurement portals that bypass traditional foodservice wholesalers, reducing lead times for mid-tier bakeries seeking smaller batch raising agent formats.
Industry Challenges
- Dual-Certification Compliance Timeline:Simultaneous EFSA purity standard and EU organic certification audits require 18-24 month validation cycles, delaying product launches and freezing reformulation pipelines.
- Fermentation Process Control Expertise Gap:Industrial bakeries transitioning from chemical to biological leavening lack in-house microbiology capability, creating dependency on external technical service support from yeast suppliers.
- Legacy Equipment Retrofit Requirements:Existing continuous mixing lines designed for single-stage chemical leavening require temperature and humidity control upgrades to accommodate multi-stage yeast fermentation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Raising Agents Market |
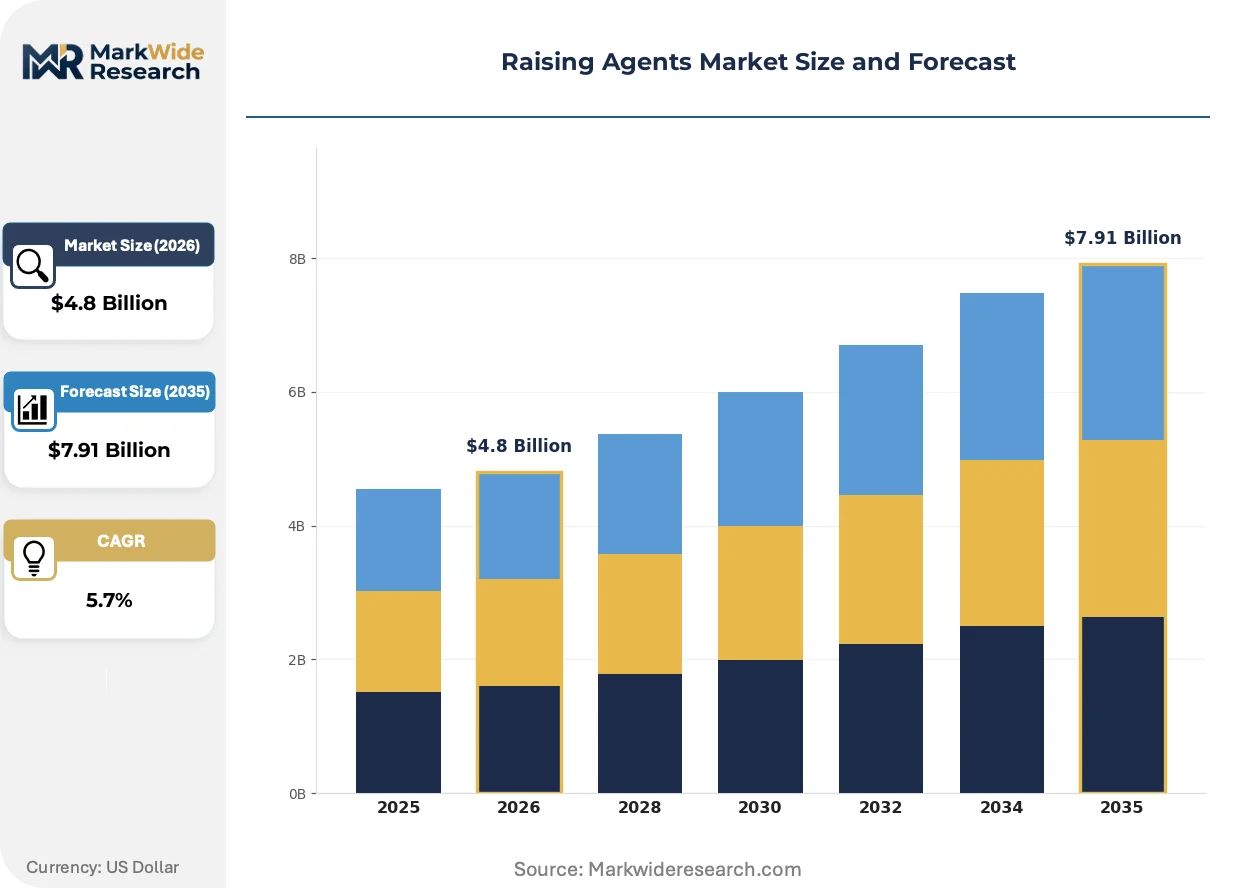
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Baking Powder, Yeast, Cream of Tartar, Baking Soda Application: Bread, Cakes, Cookies, Pastries End User: Food Manufacturers, Bakeries, Restaurants, Home Bakers Distribution Channel: Online Retail, Supermarkets, Wholesale Stores, Specialty Shops |
| Companies Covered | Lesaffre Group, AB Mauri, Solvay SA, Church & Dwight Co., Inc., Tata Chemicals Limited, Corbion N.V., Associated British Foods PLC, Arkema SA, Lallemand, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Raising Agents Market Emerging Trajectories
Active packaging technologies and biological process control systems are converging to extend the functional life of sensitive raising agents. These developments are compressing the traditional trade-off between clean-label positioning and supply chain reliability that has constrained reformulation timelines.
Encapsulated organic acidulants are migrating from niche gluten-free applications toward mainstream bread and cake formulations. Industrial bakeries in Italy and Spain are adopting these systems at pilot scale to maintain CO2 release kinetics without synthetic phosphate buffers. This technology is enabling phosphate-free claims in ambient-stable retail products previously deemed incompatible with clean-label leavening.
EFSA's 2023 updated guidance on food additive purity specifications is tightening residual heavy metal limits in commercial baking powders. Manufacturers serving cross-border EU distribution must now implement additional filtration and crystallization stages in acidulant production. The premium organic segment faces disproportionate compliance burden due to smaller batch sizes and limited process optimization economies.
Bakery procurement teams are consolidating supplier relationships from multi-source chemical portfolios toward single-source biological system partnerships. Foodservice channels across the Netherlands and Belgium are replacing spot-market baking powder purchases with multi-year yeast supply agreements incorporating technical service retainers. This concentration is most visible in industrial croissant production, where dough consistency requirements favor dedicated fermentation expertise over commodity ingredient sourcing.
Raising Agents Market Segmentation
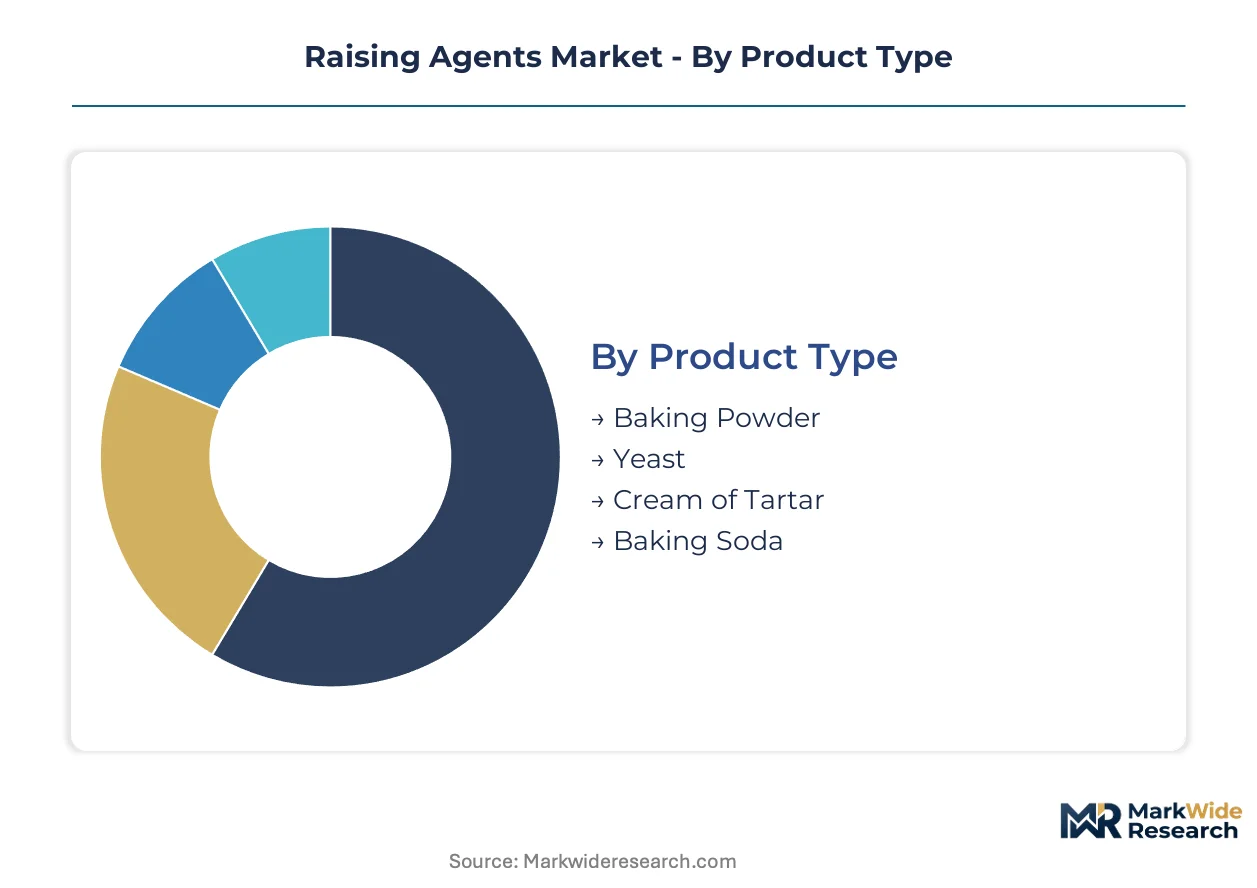
Raising agent procurement patterns diverge sharply across customer tiers, with industrial buyers demanding technical service retainers while retail channels prioritize shelf-stable formulations. Understanding these segment boundaries enables suppliers to align fermentation expertise, logistics infrastructure, and certification portfolios with specific buyer workflows.
Product Type:
After-sales technical intensity varies dramatically across product categories, with biological systems requiring ongoing microbiological support while chemical alternatives demand minimal post-sale intervention.
- Baking Powder:Double-acting formulations combine sodium bicarbonate with dual-stage acidulants to release CO2 during mixing and baking phases. Food manufacturers in Germany and France drive procurement of phosphate-free variants to meet EU organic certification requirements for private-label bread ranges.
- Yeast:Saccharomyces cerevisiae strains propagated under controlled fermentation conditions generate biological leavening through enzymatic sugar conversion. Centralized croissant production facilities across the Netherlands and Belgium are consolidating supply relationships with dedicated technical service partnerships for dough consistency management.
- Cream of Tartar:Potassium bitartrate precipitate from wine fermentation provides acidulant functionality in specialty cake formulations.
- Baking Soda:Sodium bicarbonate serves as the alkaline base component in custom acid-base leavening systems for industrial bakeries.
Baking powder holds the largest share; momentum sits with yeast as clean-label reformulations accelerate.
Application:
Volume concentration and margin structure diverge across baked goods categories, with high-throughput bread operations demanding commodity pricing while laminated dough applications support premium positioning.
- Bread:Industrial-scale loaf production consumes standardized chemical and biological leavening systems in continuous mixing environments. German industrial bakeries anchor procurement volume for both conventional and organic-certified raising agent supply contracts.
- Cakes:Aerated batter systems require precise control of CO2 release kinetics to maintain crumb structure during thermal expansion. Italian and Spanish manufacturers pilot encapsulated organic acidulants to achieve phosphate-free claims in ambient-stable retail products.
- Cookies:Chemically leavened drop and rolled varieties utilize sodium bicarbonate-based systems for controlled spread and texture development.
- Pastries:Laminated dough production depends on high-activity yeast strains with precise temperature tolerance for layered butter incorporation.
Bread captures the greatest volume; pastries are expanding most quickly through foodservice channel scaling.
End User:
Procurement sophistication and technical requirements stratify sharply across customer tiers, from automated dosing systems in food manufacturing to small-batch retail formats for home bakers.
- Food Manufacturers:Centralized production facilities operate automated continuous mixing lines requiring standardized raising agent specifications and just-in-time liquid yeast delivery. Polish and Romanian industrial bakery modernization programs are generating greenfield demand for automated dosing system integration.
- Bakeries:Mid-tier operations balance cost sensitivity with consistency requirements across diverse product portfolios.
- Restaurants:Foodservice channels prioritize reliable supply continuity over technical customization for laminated dough production.
- Home Bakers:Retail-packaged formats emphasize shelf stability and measurement convenience in consumer-oriented packaging.
Food manufacturers dominate procurement value; bakeries represent the steepest expansion trajectory as artisanal sectors consolidate.
Distribution Channel:
Channel selection directly determines service level requirements, with wholesale and specialty routes demanding technical consultation while online and supermarket channels prioritize logistics efficiency.
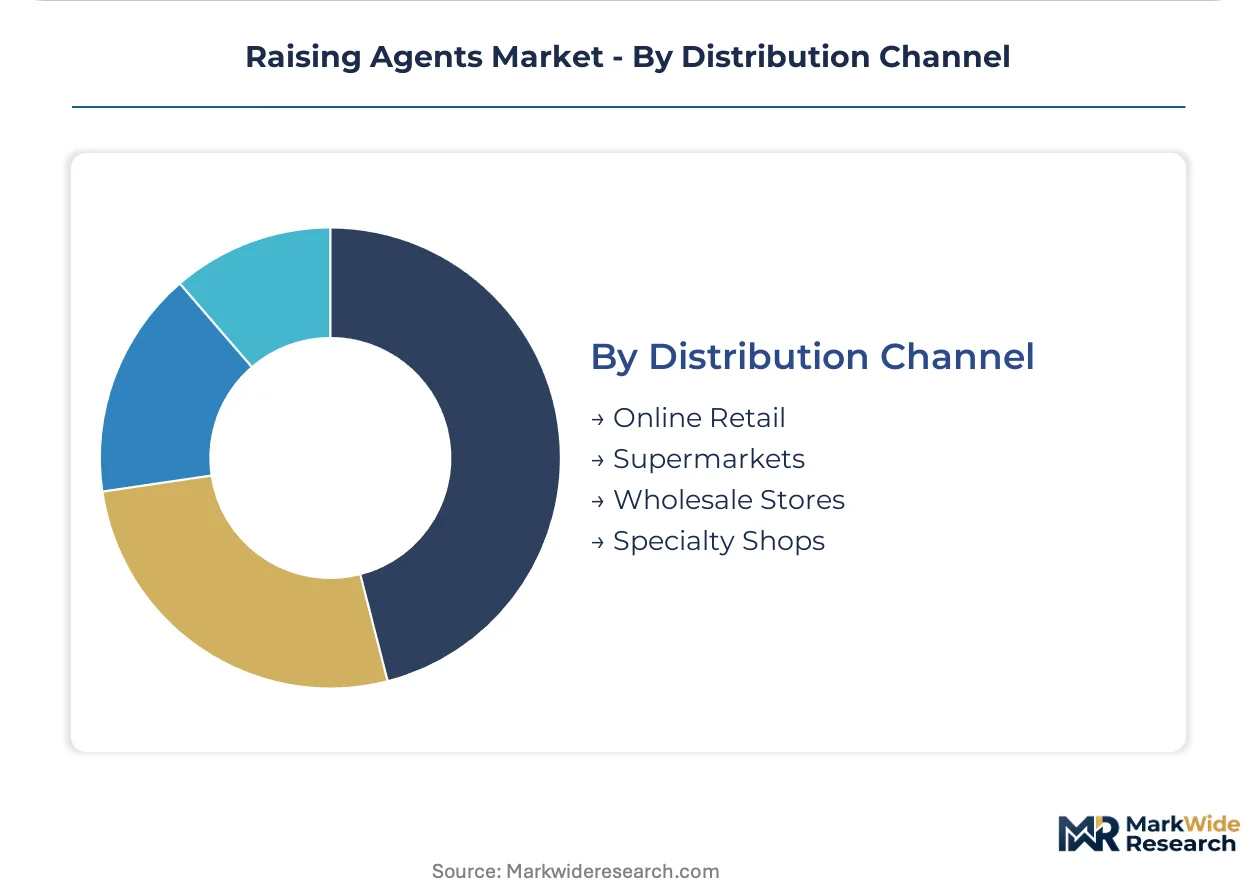
- Online Retail:E-procurement portals enable direct-to-industrial transactions that bypass traditional foodservice wholesalers, reducing lead times for mid-tier bakeries seeking smaller batch raising agent formats.
- Supermarkets:Mass retail channels concentrate consumer-oriented packaged formats with extended ambient shelf life.
- Wholesale Stores:Foodservice distribution networks supply bulk chemical leavening systems to high-volume bakery operations.
- Specialty Shops:Artisan ingredient suppliers curate organic-certified and heritage yeast strains for premium positioning.
Supermarkets move the greatest unit volume; online retail is gaining share fastest through procurement platform launches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA phosphate reduction mandates and EU organic certification requirements are redirecting procurement toward biological leavening systems across industrial baking clusters. National sodium reduction programs in multiple jurisdictions are accelerating substitution toward yeast-based alternatives.
Germany
Artisanal bread traditions merge with industrial-scale production in centralized facilities across Bavaria and North Rhine-Westphalia. The Federal Ministry of Food and Agriculture enforces strict phosphate limits in organic-certified products, compressing demand for conventional baking powders. Stuttgart and Munich host major industrial bakery modernization programs requiring automated yeast dosing systems.
France
Croissant and laminated dough production concentrates in the Paris Basin and northern Hauts-de-France region. ANSM and EFSA dual compliance requirements extend validation timelines for reformulated products. Lille and Roubaix industrial zones are consolidating fragmented artisanal sectors into centralized facilities with dedicated fermentation capacity.
Netherlands
Foodservice channel scaling drives demand for high-activity yeast strains in the Randstad corridor. The Dutch Food and Consumer Product Safety Authority enforces residual heavy metal limits under updated EFSA guidance. Rotterdam and Amsterdam distribution hubs are piloting direct-to-industrial e-procurement platforms for smaller batch formats.
Poland
Eastern European bakery modernization programs are generating greenfield demand for standardized raising agent supply contracts. EU structural funds support industrial consolidation in the Łódź and Poznań manufacturing belts. Warsaw industrial zones are retrofitting continuous mixing lines for multi-stage yeast fermentation protocols.
Italy
Encapsulated organic acidulant adoption is migrating from niche gluten-free applications toward mainstream bread and cake formulations. Ministry of Health sodium reduction mandates are driving substitution toward potassium-based alternatives. Milan and Bologna food manufacturing clusters are piloting phosphate-free ambient-stable retail products.
Raising Agents Market Vendor Landscape
On the supply side, the industry is consolidating around fermentation specialists and integrated chemical producers with captive alkali supply. Three strategic archetypes dominate: global yeast propagators with technical service infrastructure, soda ash-integrated baking powder manufacturers, and emulsifier-blend specialists serving premium retail channels. Capacity expansion and backward integration into raw material production represent the dominant competitive moves.
Within the biological leavening tier, Lesaffre Group and Lallemand exemplify the fermentation-focused archetype with established propagation infrastructure. Among chemically integrated producers, Solvay SA anchors the alkali-based segment through captive soda ash production. Tata Chemicals Limited occupies a position bridging commodity chemical supply with food-grade certification. Corbion N.V. sits within the specialty blend tier, combining emulsifier expertise with raising agent formulation.
| Leading Market Players |
|---|
| Lesaffre Group |
| AB Mauri |
| Solvay SA |
| Church & Dwight Co., Inc. |
| Tata Chemicals Limited |
| Corbion N.V. |
| Associated British Foods PLC |
| Arkema SA |
| Lallemand |
| Others |
Supply Flow & Price Mechanics
Undercapacity in northern France and southern Germany yeast propagation facilities is tightening supplier leverage and compressing procurement flexibility for industrial bakeries dependent on just-in-time liquid yeast delivery. This utilization squeeze simultaneously elevates biological leavening premiums while forcing chemical baking powder manufacturers to absorb soda ash volatility without passing through full cost recovery.
Pricing Analysis
Certification level creates the primary spread, with EU organic-certified and phosphate-free formulations commanding substantial premiums over conventional baking powders in German and French retail channels. Three-tier pricing structure separates technical-service-bundled yeast contracts from commodity baking powder spot purchases and economy-grade private-label formats. Cost compression in synthetic baking powders is intensifying because Solvay process energy economics tether sodium carbonate feedstock costs to natural gas benchmarks. Mid-tier industrial bakeries exhibit highest price sensitivity, while centralized food manufacturers prioritize consistency guarantees over unit cost minimization.
Supply Chain Analysis
Extended payment terms from 60 to 90 days characterize supplier relationships with consolidated European industrial bakeries, straining working capital for mid-tier acidulant producers lacking captive alkali supply. Geographic supply concentration clusters in France, Germany, and the Netherlands for commercial yeast propagation, while soda ash production anchors in Belgium and Poland through Solvay and Tata Chemicals operations. Raw material dependencies rest on sodium carbonate from the Solvay process, potassium bitartrate from wine fermentation, and specialized yeast strains from controlled propagation facilities. Single-source vulnerability pervades liquid yeast logistics given the geographic concentration of propagation capacity. Distribution runs through foodservice wholesalers in Belgium and the Netherlands, direct-to-industrial platforms in Poland, and specialty ingredient distributors for organic-certified formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity permeates this market as clean-label reformulations splinter procurement relationships and create white-space for specialized suppliers. The shift from commodity chemical sourcing toward biological system partnerships with embedded technical service generates niche entry points.
For Market Incumbents: Build technical service moats through dedicated fermentation expertise and on-site microbiology support that locks in multi-year supply agreements. Incumbents should deepen backward integration into soda ash production to insulate margins from energy price volatility, while simultaneously investing in dual-certification production lines to capture phosphate-free premium positioning as EFSA mandates tighten. The threat of precision fermentation startups displacing conventional yeast suppliers necessitates early-stage synthetic biology partnerships. For New Entrants and Emerging Players: Encapsulated organic acidulant production for Italian and Spanish ambient-stable retail applications represents the most penetrable entry point, given incumbent hesitation to retrofit legacy continuous mixing lines. Eastern European industrial bakery modernization in Poland and Romania offers second-tier opportunity through automated dosing system integration contracts. A go-to-market angle anchored in direct-to-industrial digital procurement platforms bypasses entrenched foodservice wholesaler relationships and captures mid-tier bakeries seeking smaller batch flexibility. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among yeast propagators with embedded technical service retainers and multi-year supply agreements, offering superior cash flow predictability over commodity chemical producers. Acquisition targets should exhibit dual EFSA and EU organic certification capabilities, captive fermentation infrastructure, and established relationships with consolidating industrial bakery clusters. The signal to watch is sodium reduction mandate acceleration across national health authorities, which would inflect substitution demand toward potassium-based and biological alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Soda Ash | Tata Chemicals and Solvay anchor margins through captive alkali supply insulating against Solvay process energy volatility. |
| Dual-Certification Production Investment | Simultaneous EFSA purity and EU organic certification unlocks premium positioning in German and French private-label channels. |
| Precision Fermentation Partnership | Synthetic biology integration enables strain customization for specific dough rheology requirements in specialty bread segments. |
| Direct-to-Industrial Platform Launch | E-procurement portals reduce lead times for Polish and Romanian mid-tier bakeries seeking smaller batch raising agent formats. |
| Technical Service Retainer Expansion | Embedded microbiology support locks in multi-year yeast supply agreements with Netherlands and Belgium foodservice chains. |
Methodological Framework
A spread of perspectives from industrial bakery procurement directors, yeast propagation facility managers, acidulant production engineers, and EFSA regulatory affairs specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with technical R&D directors at fermentation specialists and procurement leads at centralized baking facilities across Germany, France, and Poland. Secondary validation drew from EFSA additive purity guidance documents, EU organic certification registry data, customs trade flows for sodium carbonate, and SEC filings from integrated chemical producers. Bottom-up volume estimates from individual facility capacity and top-down market sizing from trade association data were triangulated to establish working ranges.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation modeling across product type, application, end-user tier, and distribution channel. The forecast incorporated biological versus chemical leavening substitution rates, sodium reduction mandate implementation timelines, and industrial bakery consolidation patterns in Eastern Europe. CAGRs were derived from slope analysis of segment-level growth trajectories rather than single-point extrapolation. Industry-specific inputs included Solvay process capacity utilization rates, yeast propagation facility expansion pipelines, and encapsulated acidulant pilot adoption data from Italian manufacturers.
Macroeconomic conditions sit as an overlay; deviation in natural gas pricing, EU carbon border adjustment implementation, or eurozone industrial production indices would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency, clean-label consumer preference persistence, and fermentation technology advancement rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Vegetable Shortening Market
Food Enhancers and Additives
Isoprenol Market
Food Enhancers and Additives
France Water Enhancer Market
Food Enhancers and Additives
Trans-Resveratrol Market
Food Enhancers and Additives
Isomalt Market
Food Enhancers and Additives
Dysphagia Diet Thickening Agents Market
Food Enhancers and Additives
Brazzein Market
Food Enhancers and Additives
Instant Whipping Agents Market
Food Enhancers and Additives
Charcoal-Infused Food Market
Food Enhancers and Additives
Enriched Yeast Extract Market
Food Enhancers and Additives
Asia-Pacific Food Stabilizers Market
Food Enhancers and Additives
Canada Food Flavor and Enhancer Market
Food Enhancers and Additives
Europe Water Enhancer Market
Food Enhancers and Additives
Resveratrol Market
Food Enhancers and Additives
North America Food Flavor and Enhancer Market
Food Enhancers and Additives
Food Raising Agents Market