
 Cephalometric X-Ray System Market | 2026-2036
Cephalometric X-Ray System Market Size, Share, and Industry Trends Forecast 2026-2036
Cephalometric X-Ray System Market Analytics
Orthodontic clinics is hardening as the dominant end-use vertical, displacing general dentistry as the primary procurement channel for cephalometric systems. Planmeca Oy leverages its Nordic manufacturing base to sustain leadership in digital panoramic-cephalometric combinations across European markets. Dentsply Sirona anchors its position through extensive direct sales networks in North American dental group practices. Carestream Dental competes aggressively on service contracts and software integration for orthodontic workflow management.
A cephalometric X-ray system captures standardized lateral skull radiographs using fixed distance between X-ray source, patient head positioner, and film or digital sensor, typically operating at 60-90 kVp with exposure times under one second to produce diagnostic images of craniofacial structures. These systems serve orthodontists and maxillofacial surgeons in treatment planning, growth prediction, and post-operative assessment through precise cephalometric landmark analysis. Digital radiography segments now command the strongest margin pools as practices abandon film processing chemicals and darkroom infrastructure. Cone beam computed tomography represents the fastest-expanding technology dimension, though 2D systems retain volume dominance in cost-sensitive clinics and emerging markets. Orthodontic applications lead absolute demand while maxillofacial surgery commands premium pricing for integrated 3D planning workflows.
FDA 510(k) clearance requirements and EU MDR technical documentation obligations are extending product development timelines and raising compliance costs for manufacturers seeking market access in the United States and European Union. The EPA regulates dental office radiation safety through state-level agreement programs, while ISO 9001 and ISO 13485 certifications function as baseline qualifiers for institutional procurement tenders. Stakeholders must monitor evolving AI-enabled automated landmark detection algorithms and their regulatory classification pathways as these tools reshape clinical workflow economics and hardware purchasing decisions.
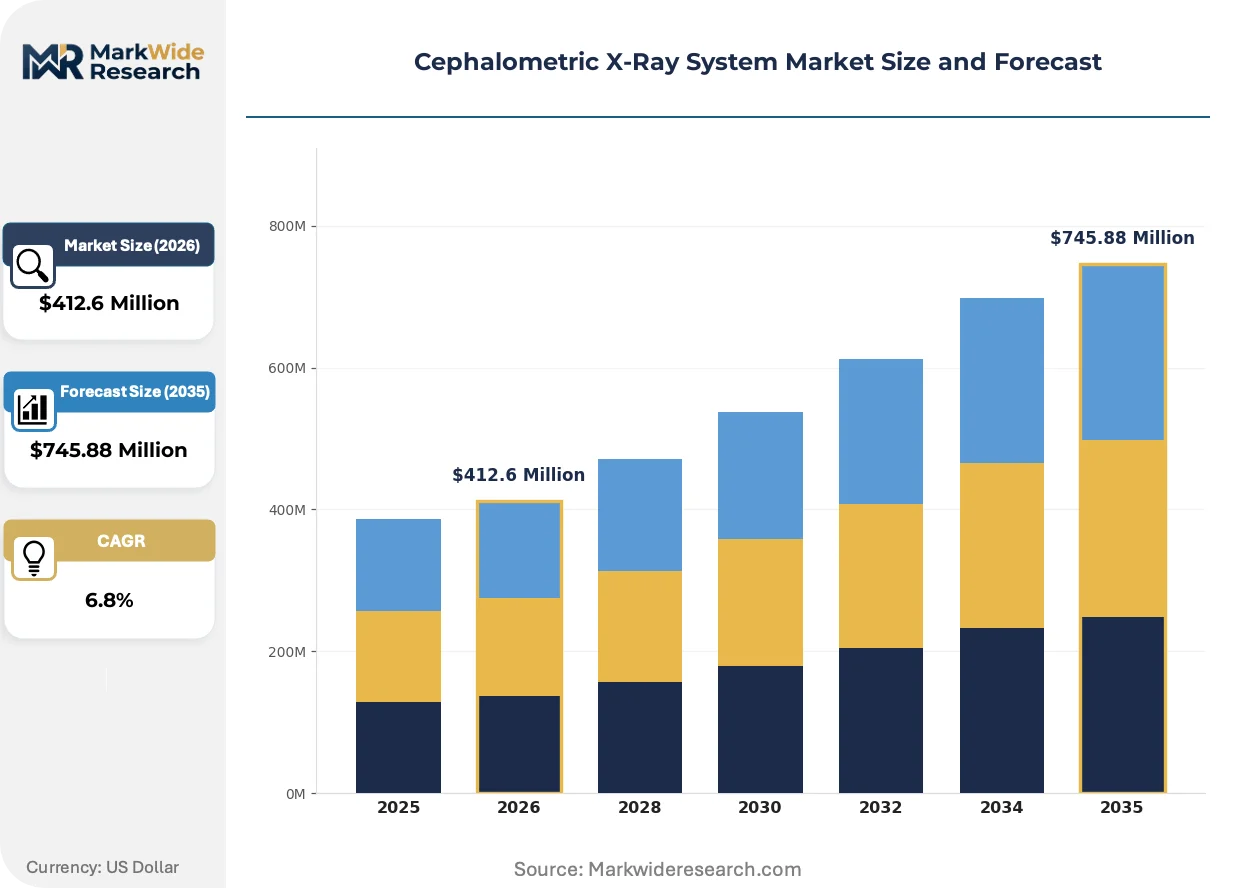
Market Dynamics
Orthodontic clinics are consolidating imaging procurement around digital panoramic-cephalometric combinations, compressing standalone system demand while elevating software-integrated bundles as the default purchasing format across developed dental markets.
Growth Catalysts
- Cone Beam CT Integration:Hybrid 2D-3D systems enable single-scan diagnostic workflows for orthodontic treatment planning. Practices in South Korea and Germany are prioritizing these configurations for patient throughput gains.
- EPA Radiation Safety Programs:State-level agreement programs mandate equipment upgrades to reduce operator exposure. Dental groups across the United States are replacing aging analog units to maintain compliance.
- Orthodontic Clinic Expansion:Specialized practices are hardening their imaging capabilities to support precision treatment planning. This vertical now displaces general dentistry as the dominant procurement channel.
Market Restraints
- EU MDR Technical Documentation:Extended product development timelines and elevated compliance costs are delaying market access for manufacturers seeking CE marking under tightened quality benchmarks.
- Digital Sensor Supply Concentration:Critical imaging components concentrate among a limited supplier base in East Asia. Disruptions to CMOS sensor availability compress manufacturing schedules.
- Film Processing Infrastructure Stranded Costs:Practices with recent investments in analog darkroom equipment face write-down pressure when migrating to digital radiography platforms.
Strategic Opportunities
- AI-Enabled Landmark Detection:Automated cephalometric analysis algorithms are reshaping clinical workflow economics. Regulatory classification pathways for these tools remain undefined, creating first-mover positioning potential.
- Service Contract Unbundling:Independent service organizations are capturing maintenance revenue previously held by original equipment manufacturers. This channel innovation opens margin recapture strategies for mid-scale practices.
- Maxillofacial Surgery Integration:Premium 3D planning workflows for surgical applications command pricing multiples above standard orthodontic configurations. This emerging application segment offers white space expansion.
Industry Challenges
- Radiation Physicist Staffing Constraints:Qualified professionals for equipment calibration and shielding verification are scarce in secondary dental markets. This talent gap extends deployment timelines.
- Legacy PACS Integration Complexity:New digital systems must interface with practice management software and hospital information systems. Compatibility testing consumes implementation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cephalometric X-Ray System Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D, 3D, Digital, Analog End User: Hospitals, Orthodontic Clinics, Diagnostic Centers, Research Institutions Technology: Film-based, Digital Radiography, Cone Beam Computed Tomography, Hybrid Systems Application: Orthodontics, Maxillofacial Surgery, General Dentistry, Oral Health Assessment |
| Companies Covered | Planmeca Oy, ACTEON, Carestream Dental, Air Techniques, KaVo, D�rr Dental, 3Shape, VATECH, Dentsply Sirona, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cephalometric X-Ray System Market Evolving Landscape
Three intersecting developments are compressing product lifecycles and elevating software-dependent value capture in cephalometric imaging. Hardware commoditization is accelerating while diagnostic algorithm differentiation hardens competitive positioning.
Cone beam computed tomography is expanding into orthodontic practices as the default imaging modality for complex malocclusion cases. Mid-scale clinics in Germany and South Korea are adopting compact CBCT units with integrated cephalometric functionality. This convergence is compressing demand for standalone 2D systems while elevating bundled service contracts as the primary vendor relationship format.
The EU Medical Device Regulation is extending conformity assessment timelines for digital radiography equipment. Manufacturers must submit enhanced clinical evidence and post-market surveillance protocols to notified bodies. Smaller equipment producers are withdrawing from European markets rather than absorbing compliance costs, concentrating supply among established players with dedicated regulatory affairs functions.
Orthodontic group practices are consolidating equipment procurement through centralized purchasing organizations. Independent clinics are losing access to volume discounts previously negotiated individually. This buyer concentration is most visible in the United States, where dental service organizations now control imaging standardization across multi-site networks.
Cephalometric X-Ray System Market Segmentation
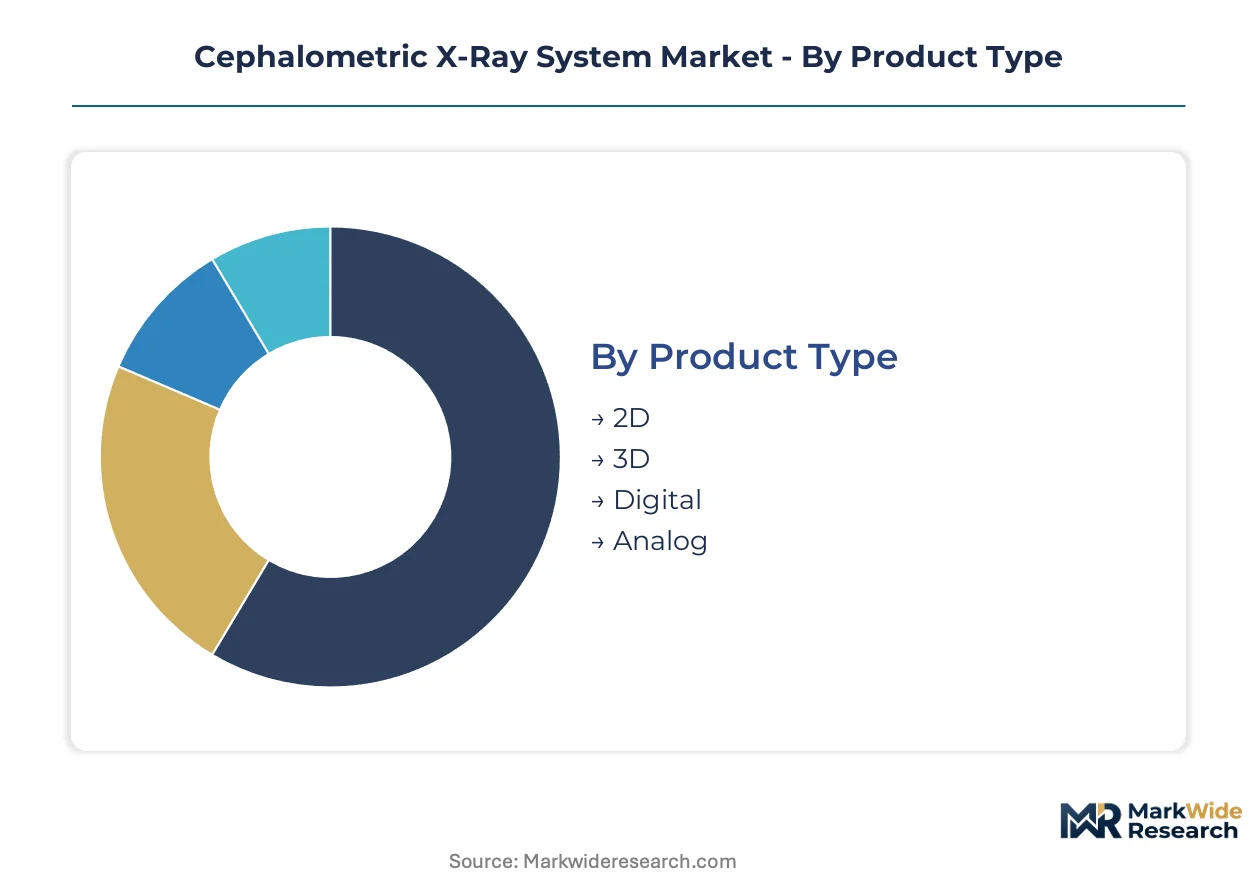
Cephalometric X-ray system procurement patterns diverge sharply across product configurations, end-user verticals, and imaging technologies. FDA 510(k) clearance and EU MDR conformity assessment requirements impose distinct compliance burdens on each segment, reshaping vendor participation and pricing structures.
Product Type:
Digital systems face the heaviest regulatory documentation loads under FDA quality system regulations and EU MDR technical file requirements, while analog equipment encounters phased-out approval pathways in developed markets.
- 2D:Conventional lateral cephalometric units operate at fixed 60-90 kVp with sub-second exposure times, producing standardized skull radiographs for orthodontic landmark analysis. Demand concentrates in cost-sensitive clinics across India and Southeast Asia where capital constraints delay digital migration. These systems require simplified FDA 510(k) submissions compared to 3D configurations.
- 3D:Cone beam and volumetric reconstruction systems generate multi-planar craniofacial datasets for complex surgical planning. Orthodontic group practices in Germany and South Korea prioritize these units for patient throughput optimization. EU MDR clinical evaluation requirements extend development timelines by 12-18 months for new 3D platform introductions.
- Digital:CMOS and CCD sensor-based systems eliminate chemical processing infrastructure. Mid-scale practices across the United States favor these configurations for workflow integration with practice management software.
- Analog:Film-cassette systems with darkroom processing retain residual demand in emerging markets with unreliable electrical infrastructure. Regulatory pressure is accelerating phase-out timelines.
2D systems sit at the top of the volume ranking, with 3D configurations climbing the fastest.
End User:
Procurement authority concentrates differently across institutional settings, with hospitals leveraging centralized purchasing power while specialized clinics prioritize workflow-specific feature bundles.
- Hospitals:Academic medical centers and maxillofacial surgery departments require multi-modality imaging suites with PACS integration. These buyers mandate ISO 13485 certification and extensive service network coverage. Capital budgeting cycles extend 24-36 months for major radiology infrastructure commitments.
- Orthodontic Clinics:Specialized practices now displace general dentistry as the dominant procurement channel. These end-users prioritize software-integrated bundles with automated cephalometric analysis. Group purchasing organizations in the United States are consolidating buying power across multi-site networks.
- Diagnostic Centers:Independent imaging facilities seek high-throughput configurations with rapid patient positioning systems. Reimbursement rate pressure drives demand for refurbished digital units.
- Research Institutions:Universities and craniofacial research centers require specialized protocols for longitudinal growth studies. Custom software development and data export capabilities command premium pricing.
Orthodontic clinics capture the highest absolute unit demand, with diagnostic centers expanding most quickly in secondary markets.
Technology:
Technology selection determines radiation dose profiles, spatial resolution capabilities, and total cost of ownership across deployment scenarios.
- Film-based:Silver halide emulsion systems with manual processing retain niche applications in regions with intermittent power supply. Environmental regulations on chemical waste disposal are constraining residual demand.
- Digital Radiography:Direct and indirect digital sensors now command the strongest margin pools as practices abandon darkroom infrastructure. CMOS sensor supply concentration in East Asia creates manufacturing vulnerability.
- Cone Beam Computed Tomography:Volumetric imaging with sub-millimeter isotropic resolution enables 3D treatment planning for complex malocclusions. Compact CBCT units with integrated cephalometric functionality are displacing standalone 2D systems in German and South Korean orthodontic markets.
- Hybrid Systems:Dual-modality platforms combining panoramic, cephalometric, and limited CBCT functionality reduce capital footprint for space-constrained practices. These configurations require extended FDA review for multi-purpose indications.
Digital radiography maintains volume leadership, with cone beam computed tomography gaining share fastest among premium-tier buyers.
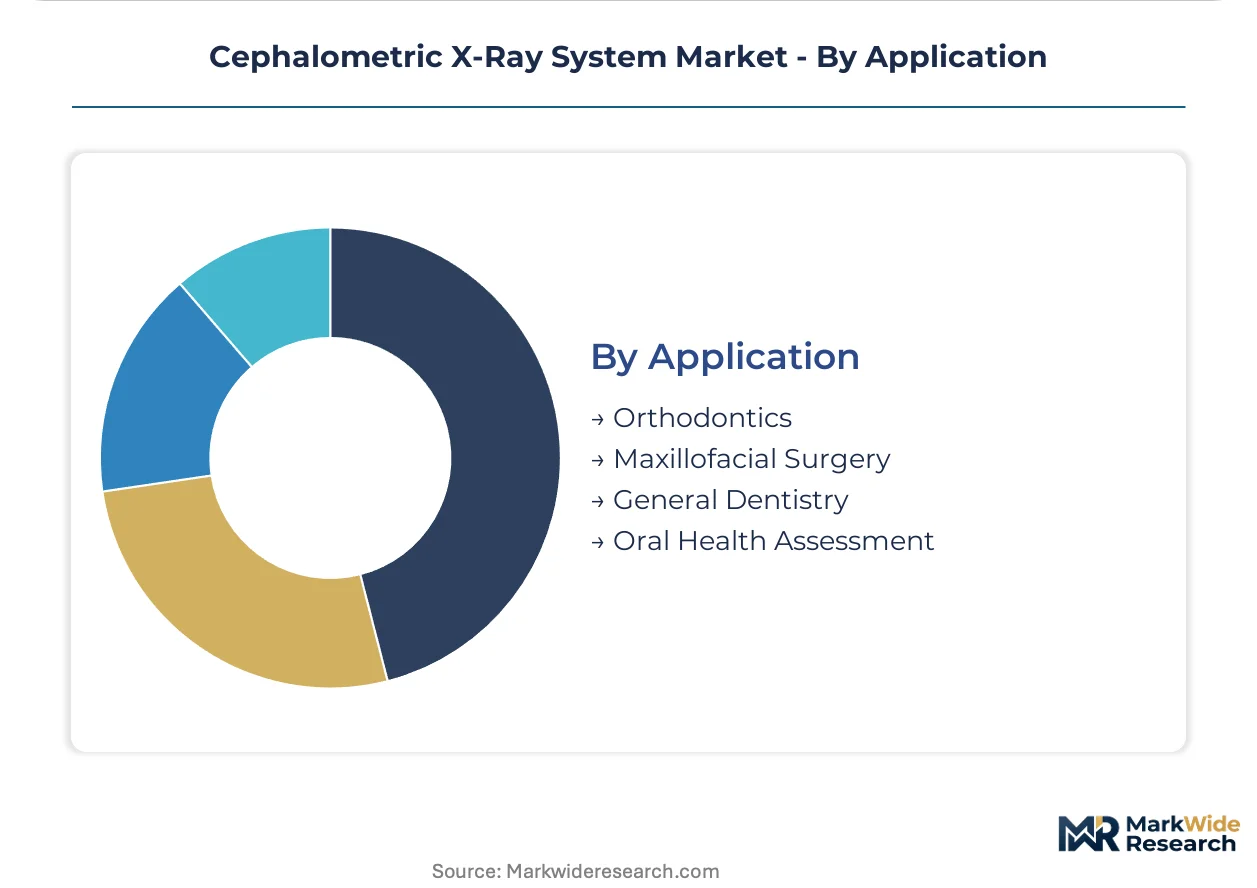
Application:
Clinical use case determines hardware specifications, software feature requirements, and service contract structures.
- Orthodontics:Treatment planning, growth prediction, and post-treatment assessment drive standardized lateral cephalogram acquisition. Automated landmark detection algorithms are reshaping workflow economics for high-volume practices.
- Maxillofacial Surgery:Orthognathic surgical planning and trauma reconstruction require 3D volumetric datasets with integrated virtual surgical simulation. These applications command pricing multiples above standard orthodontic configurations.
- General Dentistry:Routine diagnostic imaging and treatment monitoring represent declining demand as specialized orthodontic practices internalize cephalometric capabilities.
- Oral Health Assessment:Preventive screening and pediatric growth monitoring create episodic demand patterns with lower utilization rates.
Orthodontics anchors absolute demand volume, with maxillofacial surgery representing the steepest expansion trajectory for integrated 3D planning workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting cephalometric system production toward jurisdictions with streamlined medical device approval pathways, while demand concentrates in markets upgrading aging analog infrastructure to digital and cone beam configurations.
United States
Dental service organizations are consolidating imaging procurement across multi-site orthodontic networks, compressing vendor negotiation leverage for independent practices. FDA 510(k) clearance requirements and EPA state-level radiation safety agreement programs mandate equipment upgrades, accelerating analog replacement cycles. The Dallas-Fort Worth metroplex anchors concentration of orthodontic group practice headquarters driving standardization demand.
Germany
Mid-scale orthodontic clinics in Bavaria and North Rhine-Westphalia prioritize compact CBCT units with integrated cephalometric functionality for patient throughput optimization. EU MDR technical documentation obligations extend conformity assessment timelines, elevating compliance costs that favor established manufacturers with dedicated regulatory affairs functions. The Stuttgart industrial corridor concentrates precision mechanical component suppliers serving digital radiography OEMs.
South Korea
Seoul Capital Area orthodontic practices are adopting hybrid 2D-3D systems as default configurations for complex malocclusion treatment planning. MFDS medical device licensing requirements enforce quality benchmarks for digital sensor integration, while government healthcare digitization incentives subsidize practice technology upgrades. The Pangyo Techno Valley cluster houses CMOS sensor development facilities critical to regional manufacturing supply.
India
Cost-sensitive clinics in Maharashtra and Karnataka retain demand for conventional 2D systems where capital constraints delay digital migration, though CDSCO medical device registration requirements are tightening import pathways for foreign manufacturers. BIS certification mandates for electrical safety create compliance layering for equipment deployment. Mumbai's dental equipment distribution hubs channel refurbished digital units to secondary tier-two cities.
Brazil
Orthodontic group practices in São Paulo and Rio de Janeiro are consolidating procurement through centralized purchasing organizations, mirroring US buyer concentration trends. ANVISA medical device registration timelines create market access friction for new market entrants. The Campinas technology corridor hosts regional service and calibration facilities supporting imported digital radiography platforms.
Cephalometric X-Ray System Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated equipment-and-software bundles commanding premium positioning against standalone hardware vendors. The vendor base organizes around three tiers: full-stack imaging platform providers, component-specialist OEMs, and regional assembly operations serving price-sensitive markets. Consolidation pressure operates through orthodontic group purchasing organization concentration in North America and dental service organization standardization mandates. Strategic moves center on regulatory affairs capacity expansion for EU MDR compliance and AI-enabled diagnostic algorithm integration to differentiate software-dependent value capture.
Within the Nordic-origin equipment tier, Planmeca Oy occupies a position exemplifying integrated panoramic-cephalometric platform specialization. Dentsply Sirona and Carestream Dental represent the North American direct-sales archetype, anchoring service network coverage and orthodontic workflow software integration as competitive differentiators. These three entities illustrate divergent geographic manufacturing and distribution strategies across the Atlantic basin.
| Leading Market Players |
|---|
| Planmeca Oy |
| ACTEON |
| Carestream Dental |
| Air Techniques |
| KaVo |
| Dürr Dental |
| 3Shape |
| VATECH |
| Dentsply Sirona |
| Others |
Value Network & Pricing Analysis
Orthodontic group purchasing organization consolidation across United States multi-site networks is forcing original equipment manufacturers toward direct service contract bundling and compressing distributor margin layers, which elevates pricing power for vendors with captive maintenance capabilities while squeezing standalone hardware margins.
Pricing Analysis
Distributor markup layers in the 15-25% range for independent dental equipment resellers are compressing as dental service organizations negotiate direct manufacturer relationships. Three-tier pricing structure across premium, standard, and economy levels tracks FDA 510(k) clearance tier and ISO 13485 certification status. Pricing pressure stems from refurbished digital unit availability in secondary markets. Cost-sensitive clinics in India and Southeast Asia exhibit highest price sensitivity, while German maxillofacial surgery departments prioritize performance specifications over acquisition cost.
Supply Chain Analysis
Radiation physicist and biomedical engineer shortages in the Stuttgart industrial corridor and Dallas-Fort Worth metroplex are extending equipment calibration and deployment timelines. CMOS sensor fabrication concentrates in South Korea and Japan, while precision mechanical components for patient positioning systems source from Germany. Single-source vulnerability in East Asian digital sensor supply creates manufacturing schedule compression risk. Distribution runs through authorized dealer networks for capital equipment, with independent service organizations capturing aftermarket maintenance revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cephalometric X-ray system procurement is hardening around late-cycle quality specifications as orthodontic clinics prioritize AI-enabled automated landmark detection and integrated 3D planning workflows over base hardware functionality.
For Market Incumbents: Cement regulatory affairs capacity expansion in Brussels and Washington to absorb EU MDR technical documentation burdens and FDA 510(k) quality system regulation compliance costs. Defend against independent service organization encroachment by unbundling maintenance contracts for mid-scale practices. Prioritize backward integration into CMOS sensor supply relationships to reduce East Asian manufacturing vulnerability.
For New Entrants and Emerging Players: Begin with maxillofacial surgery 3D planning workflow integration as the most penetrable premium segment, where pricing multiples exceed standard orthodontic configurations. Target diagnostic centers in Brazilian and Indian secondary cities with refurbished digital unit remarketing programs. Pursue white-label manufacturing partnerships with established Nordic or North American platform providers to bypass direct regulatory clearance timelines.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale orthodontic software developers possessing FDA-cleared automated cephalometric analysis algorithms. Long-term viability hinges on regulatory classification pathway resolution for AI-enabled diagnostic tools. Watch for MFDS or FDA guidance document releases on machine learning-based radiological device review as the critical inflection signal for hardware-software bundle valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Extended conformity assessment timelines favor established manufacturers with dedicated regulatory affairs functions in Brussels. |
| AI-Enabled Landmark Detection Development | Automated cephalometric analysis algorithms reshape clinical workflow economics for high-volume orthodontic practices. |
| CMOS Sensor Supply Partnership | East Asian sensor concentration creates manufacturing vulnerability requiring captive supply relationships or alternative sourcing. |
| Service Contract Unbundling | Independent service organizations capture maintenance revenue previously held by original equipment manufacturers. |
| Hybrid 2D-3D Platform Launch | Cone beam CT integration enables single-scan diagnostic workflows for orthodontic treatment planning in South Korea and Germany. |
Research Methodology
Bottom-up orthodontic clinic procurement modeling reconciled against top-down digital radiography equipment production tracking forms the analytical core of this study. Primary interviews with orthodontic practice administrators, hospital biomedical engineers, GPO contracts managers, and dental equipment distributors combined with secondary validation from FDA 510(k) clearance databases, EU MDR notified body documentation, and hospital procurement system records. Triangulation across supply-side manufacturing capacity and demand-side installation data ensures cross-verification.
Historical trendline analysis of digital migration patterns from analog film systems establishes baseline trajectory assumptions across the projection horizon. Segmentation modeling covers product configuration, end-user vertical, imaging technology, and application use case dimensions. CAGR derivation incorporates orthodontic clinic expansion rates, EPA radiation safety program compliance upgrade cycles, and CBCT adoption curve parameters specific to German and South Korean markets.
Several conditions sit outside the modeled scope, including sovereign tariff regime changes, raw material commodity price spikes, and pandemic-related healthcare capital expenditure freezes. Forecasts reflect documented assumptions regarding regulatory clearance timeline stability and CMOS sensor supply continuity. Material deviation in FDA AI-enabled device classification guidance or EU MDR notified body capacity constraints warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global 3D Ultrasound Market
Medical Imaging
Medical Image Analysis Software Market
Medical Imaging
Ga 68 DOTATOC Market
Medical Imaging
Teleradiology Services Market
Medical Imaging
Diagnostic Imaging Markers Market
Medical Imaging
Radiology Services Market
Medical Imaging
Spain Magnetic Resonance Imaging Market
Medical Imaging
Mexico Nuclear Imaging Market
Medical Imaging
Fluoroscopy C-Arms Market
Medical Imaging
Asia-Pacific Digital Pathology Market
Medical Imaging
Non-Invasive & Minimally Invasive Medical Imaging and Visualization Systems Market
Medical Imaging
Pre-Clinical Imaging System Market
Medical Imaging
Veterinary CT Imaging Market
Medical Imaging
Radiographic Film Processor Market
Medical Imaging
Republic of Ireland (ROI) and Northern Ireland MRI and CT Scan Radiology Services Market
Medical Imaging
Global Mammography Systems Market