
 Europe Compound Feed Market | 2026-2036
Europe Compound Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Compound Feed Market Foresight
Spain is reshaping compound feed production capacity through major investments in Mediterranean aquafeed and poultry feed complexes. Nutreco N.V. anchors its European position through advanced nutritional solutions for monogastric species. ForFarmers N.V. dominates the Benelux and northwestern European market through dense distribution networks serving dairy and pig producers. Cargill, Incorporated leverages its grain origination infrastructure to control input costs across Iberian and Italian feed operations.
Compound feed refers to industrially manufactured mixtures of grains, protein meals, additives, and vitamins formulated to deliver precise nutritional profiles for livestock and aquaculture species, typically produced through pelleting or extrusion processes to ensure feed conversion efficiency and digestive consistency. Poultry feed leads volume consumption across Europe due to the region's integrated broiler and layer operations, while aquafeed represents the fastest-expanding product type as salmon and seabass farming intensifies in Norway and Greece. Protein meals command the largest share of composition value, though additives and vitamins concentrate margin pools as producers seek antibiotic-free growth promotion and precision nutrition.
The EU Green Deal and Farm to Fork Strategy are restricting imported deforestation-linked soy and tightening maximum residue limits for feed additives, compelling manufacturers to reformulate around alternative proteins and locally sourced oilseeds. EFSA evaluates novel feed ingredients including insect meal and single-cell proteins, while national regulators in Germany and France enforce stricter manure-nutrient regulations that cascade back into feed phosphorus and nitrogen specifications. Stakeholders must monitor how the EU Deforestation Regulation reshapes soy supply chains and whether insect protein achieves cost parity with conventional meals before scaling capital commitments.
Market Dynamics
The EU Green Deal and Farm to Fork Strategy are compressing protein sourcing options while accelerating capital flows toward alternative ingredient processing infrastructure across the continent.
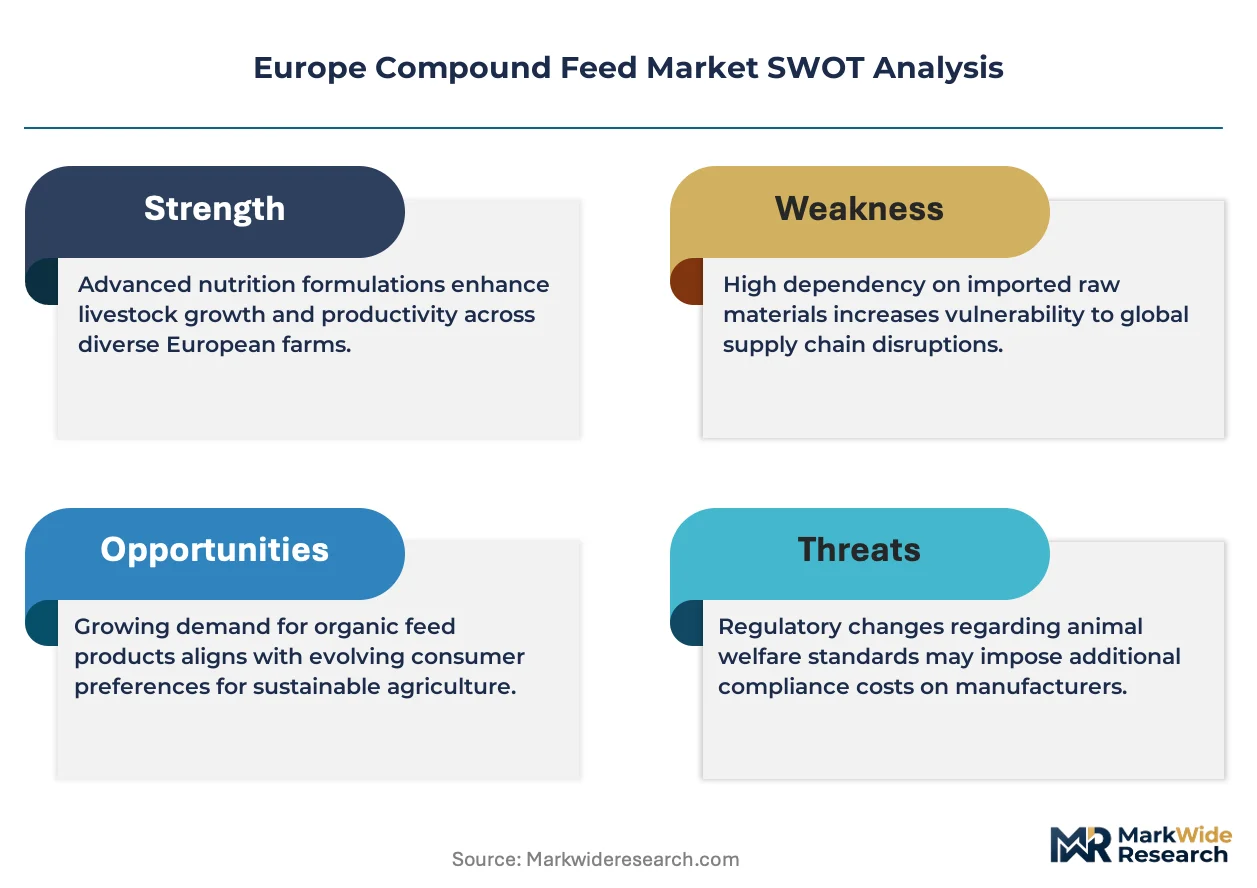
Growth Catalysts
- EFSA novel ingredient approvals:Regulatory clearance pathways for insect meal and single-cell proteins are unlocking domestic protein production capacity that reduces import dependency on South American soy.
- Denmark pig sector consolidation:Large integrated operations are standardizing precision nutrition protocols that demand compound feed with additive-optimized formulations.
- Salmon farming intensification:Norwegian aquaculture expansion is pulling high-performance aquafeed volumes that command premium formulation margins.
Market Restraints
- Soy supply chain reconcentration:The EU Deforestation Regulation is forcing feed manufacturers to sever ties with traditional Brazilian suppliers lacking traceability certification.
- Phosphorus specification tightening:German and French manure-nutrient regulations are cascading into feed formulation constraints that limit mineral additive flexibility.
- Protein meal cost volatility:Sunflower and rapeseed meal prices fluctuate with Black Sea export disruptions, compressing margin predictability for compounders.
Strategic Opportunities
- Greek seabass farming expansion:Mediterranean aquaculture growth is creating demand for specialized marine protein formulations that local compounders can capture.
- CSRD disclosure mandates:Corporate sustainability reporting requirements are incentivizing feed buyers to source from suppliers with verified Scope 3 emission reductions.
- Precision fermentation scale-up:Convergence of biotechnology and feed processing is enabling industrial production of tailored amino acid profiles that displace fishmeal inclusion rates.
Industry Challenges
- Novel protein processing capex:Insect farming and single-cell protein facilities require nine-figure capital commitments with unproven offtake volumes at scale.
- Multinational formulation talent scarcity:Compounders struggle to recruit nutritionists capable of balancing EFSA additive limits with livestock performance targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Compound Feed Market |
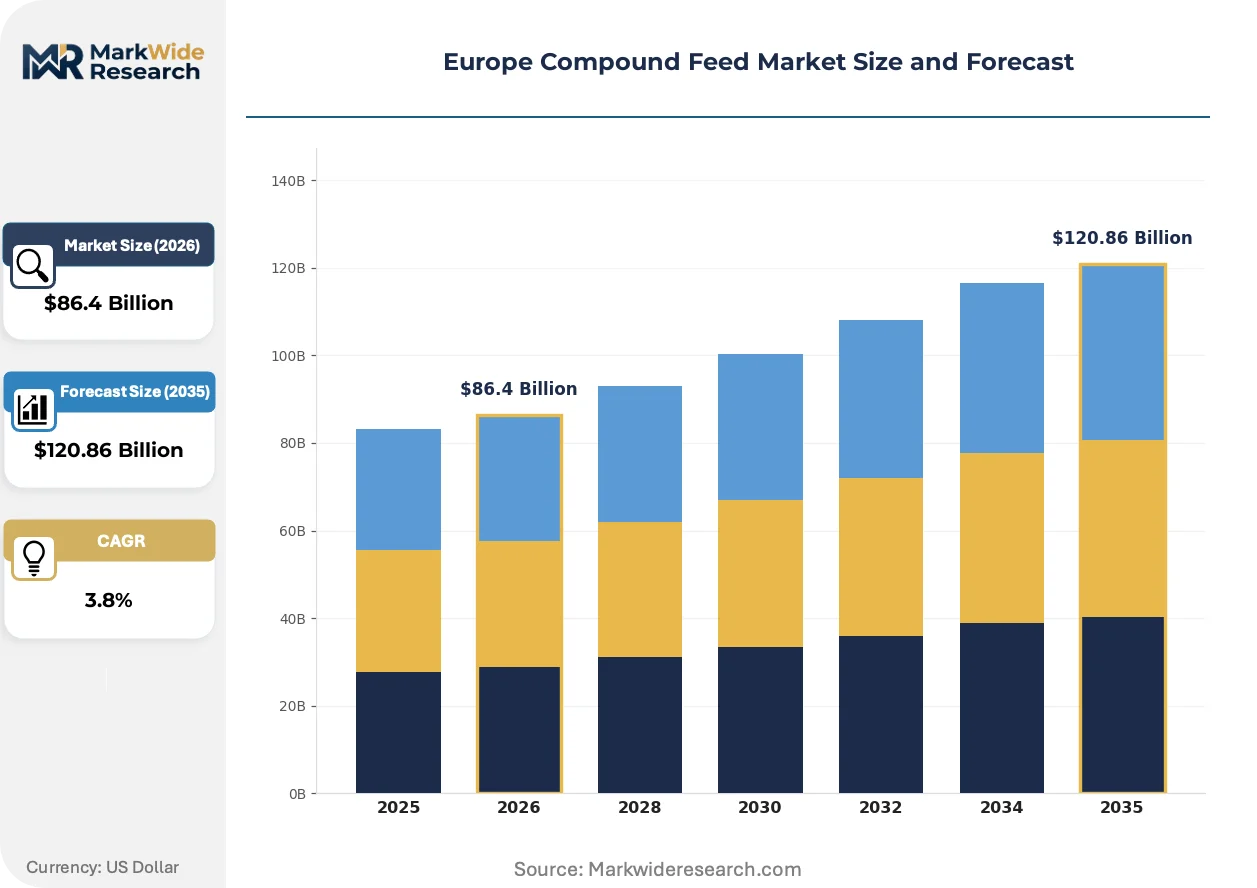
| Market Size in 2026 | $86.4 Billion |
| Market Size in 2035 | $120.86 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Poultry Feed, Cattle Feed, Swine Feed, Aquafeed Composition: Grains, Protein Meals, Additives, Vitamins Distribution Channel: Direct Sales, Retail Stores, Online Platforms, Wholesalers End User: Farmers, Feed Manufacturers, Livestock Producers, Aquaculture Operators |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Company, Nutreco N.V., Alltech, Kemin Industries, Inc., ForFarmers N.V., BASF SE, Charoen Pokphand Foods, Yara International ASA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Compound Feed Market Shifts & Advancements
Feed manufacturing is pivoting from commodity blending toward biotech-integrated precision nutrition systems that synchronize animal health, environmental compliance, and processor economics.
Enzyme-coated microencapsulation is hybridizing conventional pelleting with pharmaceutical-grade delivery systems. Pig and poultry integrators in Spain and Poland are adopting these technologies to protect acid-sensitive additives through gastric passage. The structural consequence is compressing the performance gap between premium and standard feed tiers as bioavailability improvements democratize precision nutrition.
REACH and the EU Deforestation Regulation are jointly constraining imported soy and synthetic additive portfolios. Feed manufacturers must now maintain dual traceability systems for agricultural inputs and chemical substances simultaneously. The poultry sector faces the steepest compliance burden due to its reliance on soy protein concentrates and coccidiostat programs.
Integrated farming operations are consolidating procurement authority into centralized nutrition teams that negotiate multi-year compound supply agreements. Traditional distributor networks serving smaller Dutch and Belgian livestock farms are losing volume to direct manufacturer relationships. This concentration is most visible in Germany's northwestern pig belt, where three processor cooperatives now control over half of regional feed purchasing decisions.
Europe Compound Feed Market Segmentation
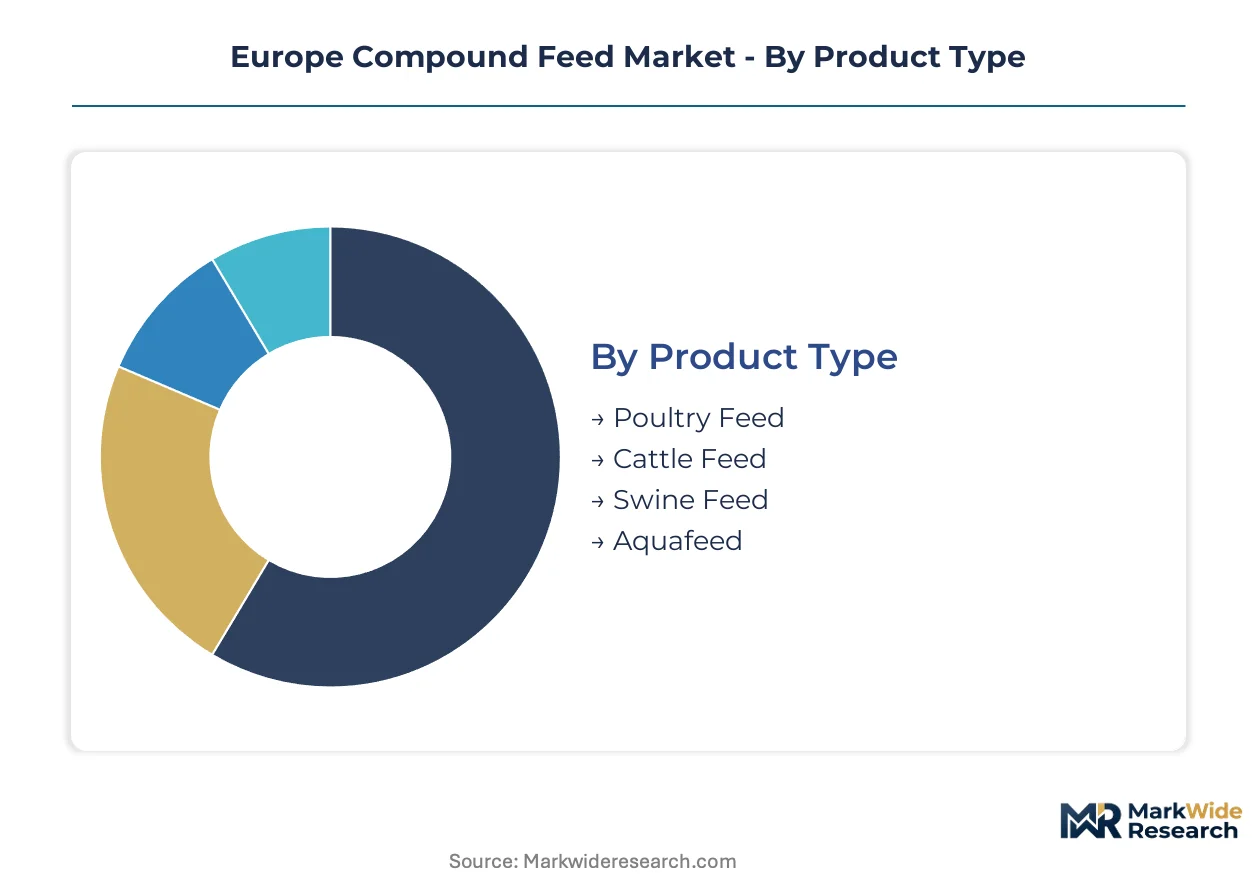
Compound feed segmentation in Europe reflects divergent biological requirements across livestock species and the regulatory pressure to reformulate around traceable, low-carbon ingredients. Understanding where formulation complexity concentrates versus where volume flows through commodity channels determines capital allocation across manufacturing assets.
Product Type:
Poultry feed turns inventory fastest due to short broiler grow-out cycles, while aquafeed sits longest in production pipelines given marine ingredient sourcing lead times.
- Poultry Feed:Formulated for high-energy conversion in integrated broiler and layer operations, typically incorporating soybean meal, corn, and phytase enzymes. Demand clusters in northeastern Spain and western France where vertically integrated poultry processors operate megafarms. EFSA restrictions on antibiotic growth promoters are accelerating enzyme and organic acid inclusion rates.
- Aquafeed:Extruded high-protein formulations for salmonids and Mediterranean species, requiring fishmeal, fish oil, and increasingly insect meal or single-cell proteins. Norwegian fjord operations and Greek seabass farms are pulling specialized marine formulations that command formulation premiums over terrestrial feeds.
- Cattle Feed:Ruminant-optimized blends balancing fiber, starch, and bypass proteins for dairy and beef operations. German and Dutch dairy cooperatives dominate procurement through centralized nutrition teams negotiating multi-year supply agreements.
- Swine Feed:Precision-formulated for monogastric digestibility, with phase-feeding protocols matching amino acid profiles to growth stages. Danish pig sector consolidation is standardizing additive-optimized formulations across fewer, larger operations.
Poultry feed dominates installed base. Aquafeed is where expansion concentrates.
Composition:
Cost tiers separate commodity carbohydrates from high-margin functional ingredients, with protein meals occupying the middle ground where price volatility most compresses compounding margins.
- Protein Meals:Soybean, rapeseed, and sunflower meals delivering essential amino acids for muscle development and milk production. EU Deforestation Regulation traceability requirements are forcing manufacturers to sever ties with uncertified Brazilian suppliers and pivot to European oilseed processing.
- Additives:Enzymes, organic acids, and gut health modifiers enabling antibiotic-free growth promotion and feed conversion efficiency. Spanish and Polish integrators are adopting enzyme-coated microencapsulation to protect acid-sensitive additives through gastric passage.
- Grains:Corn, wheat, and barley providing metabolizable energy foundations, sourced through Cargill and Bunge origination networks across Iberian and Black Sea corridors. Black Sea export disruptions continue injecting price unpredictability into European compounder cost structures.
- Vitamins:Fat-soluble and water-soluble micronutrients preventing deficiency diseases and optimizing metabolic function. EFSA maximum residue limit tightening is constraining synthetic vitamin premix formulations and accelerating natural source substitution.
Protein meals anchor volume throughput. Additives capture margin expansion.
Distribution Channel:
Customer scale determines channel economics, with direct manufacturer relationships displacing traditional distributor networks as livestock operations consolidate.
- Direct Sales:Manufacturer-to-producer contracts serving integrated poultry, pig, and dairy operations with customized formulation and technical support. Germany's northwestern pig belt exemplifies this shift, where three processor cooperatives now control over half of regional feed purchasing decisions.
- Wholesalers:Regional aggregators blending manufacturer volumes for delivery to mid-scale livestock farms. Benelux agricultural cooperatives maintain dense distribution networks serving dairy and pig producers outside integrated procurement systems.
- Retail Stores:Bagged feed sales to smallholder and hobby farmers through agricultural supply merchants. French and Italian rural retail networks persist despite volume erosion toward direct channels.
- Online Platforms:Digital procurement portals emerging for specialty additives and smaller-volume orders. CSRD disclosure mandates are incentivizing platform development that verifies supplier Scope 3 emission reductions.
Direct sales capture volume concentration. Online platforms are gaining share fastest among emerging channels.
End User:
Application maturity separates commodity livestock production from technology-intensive aquaculture, with feed manufacturers serving fundamentally different customer capability profiles.
- Livestock Producers:Integrated poultry, pig, and cattle operations with in-house nutritionists specifying precision formulations. Danish and Dutch large-scale operations are standardizing additive-optimized protocols that demand compound feed with pharmaceutical-grade delivery systems.
- Aquaculture Operators:Salmon and seabass farming enterprises requiring high-performance marine formulations with documented ingredient provenance. Norwegian and Greek expansion is pulling specialized aquafeed volumes that command premium formulation margins.
- Farmers:Independent crop-livestock operations purchasing standard rations through cooperative or retail channels. French and Polish small-to-mid-scale farms remain significant volume contributors despite consolidation pressures.
- Feed Manufacturers:Secondary compounders blending base mixes and concentrates for regional distribution. Iberian and Italian operations leverage Cargill grain origination infrastructure to control input costs.
Livestock producers dominate procurement scale. Aquaculture operators drive formulation innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Compound feed manufacturing clusters in northwestern Europe where grain handling infrastructure, livestock density, and port access converge. Germany, the Netherlands, and Denmark anchor production capacity, while Spain and France concentrate species-specific formulation expertise.
Germany
North Rhine-Westphalia and Lower Saxony host Europe's densest concentration of pig and dairy feed operations. EFSA maximum residue limit tightening constrains mineral additive formulations. Three processor cooperatives in the northwestern pig belt now control over half of regional feed purchasing decisions.
Netherlands
Benelux distribution networks serve dairy and pig producers through dense cooperative infrastructure. The EU Deforestation Regulation forces manufacturers to sever ties with uncertified Brazilian soy suppliers. ForFarmers N.V. anchors market presence through northwestern European distribution density.
Spain
Catalonia and Andalusia concentrate Mediterranean aquafeed and poultry feed manufacturing investments. REACH compliance constrains synthetic additive portfolios alongside deforestation-linked ingredient restrictions. Nutreco N.V. positions advanced nutritional solutions for monogastric species from Iberian production bases.
France
Western France clusters dairy feed formulation around cooperative nutrition teams negotiating multi-year supply agreements. National manure-nutrient regulations cascade into feed phosphorus and nitrogen specifications. Brittany and Pays de la Loire concentrate integrated poultry operations demanding precision-formulated rations.
Denmark
Jutland peninsula operations standardize additive-optimized formulations across consolidated pig production. EFSA novel ingredient approval pathways unlock domestic protein alternatives to South American soy imports. Large integrated operations drive procurement centralization into direct manufacturer relationships.
Europe Compound Feed Market Competitive Landscape
Integrated nutrition conglomerates and regional formulation specialists split the market along scale-versus-service lines. The vendor base concentrates around grain origination infrastructure, biotechnology integration, and distribution network density. Three strategic archetypes dominate: multinational agribusinesses controlling input costs through captive supply chains, regional cooperatives leveraging farmer ownership structures, and biotechnology specialists commercializing novel protein and enzyme platforms. Competitive moves center on M&A to secure alternative protein processing capacity and strategic partnerships to lock in traceable soy sourcing.
Among North American agribusiness anchors, Cargill, Incorporated exemplifies the grain-origination archetype through Iberian and Italian feed operations. Archer Daniels Midland Company occupies a comparable position in oilseed processing and commodity flow management. Within the European specialist tier, Nutreco N.V. represents biotechnology-integrated precision nutrition, while ForFarmers N.V. anchors cooperative-structured distribution density across Benelux and northwestern European dairy and pig markets. These three players collectively illustrate how competitive positioning diverges between input-cost control, formulation innovation, and farmer-proximate service models.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Nutreco N.V. |
| Alltech |
| Kemin Industries, Inc. |
| ForFarmers N.V. |
| BASF SE |
| Charoen Pokphand Foods |
| Yara International ASA |
| Others |
Supply & Pricing Matrix
Black Sea grain corridor disruptions determine both pricing tier spreads and supply chain shape across European compound feed manufacturing, compressing margin predictability for compounders while accelerating sourcing diversification into Iberian and Baltic grain origination networks.
Pricing Analysis
The EU Deforestation Regulation dictates the pricing tier structure by forcing traceability premiums on certified Brazilian soy versus discounted uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels separates ESG-verified formulations with full supply chain documentation from commodity blends with limited provenance. Cost compression in standard-tier poultry feed is intensifying because sunflower and rapeseed meal prices fluctuate with Ukrainian export availability. Smallholder farmers purchasing through retail channels exhibit highest price sensitivity, while integrated Norwegian salmon operations demonstrate lowest sensitivity due to formulation performance premiums.
Supply Chain Analysis
Ukrainian corn and wheat, Brazilian soy, and Norwegian fishmeal anchor raw material procurement for European compounders. Formulation draws from vegetable proteins, marine ingredients, and novel alternatives including insect meal and single-cell proteins. Single-source vulnerability concentrates in Brazilian soy traceability certification gaps under EUDR enforcement. Distribution runs through manufacturer-direct relationships with integrated livestock operations, displacing traditional cooperative networks in Germany and the Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation biochemistry expertise scarcity constrains European compound feed expansion, with qualified nutritionists capable of balancing EFSA additive limits against livestock performance targets commanding premium compensation packages.
For Market Incumbents: Pre-empt margin erosion by securing backward integration into insect protein processing capacity before cost parity with conventional meals achieves scale. Anchor position through multi-year direct supply agreements with Danish and Dutch integrated pig operations that are consolidating procurement authority. Certification investment in EUDR-compliant soy traceability systems represents essential defensive infrastructure against supply disqualification. For New Entrants and Emerging Players: Pursue Greek seabass farming expansion as the most penetrable aquafeed segment, where Mediterranean marine protein formulation demand outpaces local compounding capacity. Capture share through precision fermentation partnerships delivering tailored amino acid profiles that displace fishmeal inclusion rates. Digital procurement platforms verifying Scope 3 emission reductions offer viable go-to-market positioning against incumbent distributor networks. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors biotechnology-integrated precision nutrition specialists over commodity blending operations. Long-term viability over the coming decade hinges on alternative protein processing infrastructure ownership rather than grain origination scale. Acquisition target archetype: European insect farming or single-cell protein facilities with pilot-scale offtake agreements. The signal to watch is EFSA novel ingredient approval velocity for domestic protein alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Alternative Protein Processing Capacity | Reduces EUDR-linked soy dependency while capturing premium formulation margins in aquafeed. |
| Direct Manufacturer Relationships | Locks in volume commitments from German and Dutch integrated livestock cooperatives consolidating procurement. |
| Enzyme-Coated Microencapsulation Adoption | Protects acid-sensitive additives through gastric passage, democratizing precision nutrition across tiered feed products. |
| EFSA Novel Ingredient Approval Pathway | Unlocks regulatory clearance for insect meal and single-cell proteins displacing South American soy imports. |
| CSRD-Aligned Scope 3 Verification Systems | Enables platform-based procurement that meets corporate sustainability disclosure mandates for feed buyers. |
Research Methodology
A standing panel of feed formulation directors, procurement leads at integrated livestock cooperatives, EFSA regulatory affairs specialists, and aquaculture nutrition managers provided ongoing calibration across the study period. Primary interviews with compounder operations executives and distributor network managers combined with secondary validation against EFSA novel ingredient approval databases, EU customs trade statistics, and national agricultural ministry production reports. Bottom-up volume modeling across species-specific feed demand triangulated with top-down macroeconomic indicators.
Scenario-bracketing anchored the analytical framework, with projections developed across the analysis window through sensitivity testing of Black Sea export disruption severity and EUDR enforcement timelines. Segmentation dimensions modeled include livestock species, ingredient composition tier, distribution channel structure, and end-user operational scale. CAGRs derived from historical volume trajectories adjusted for regulatory intervention effects and protein substitution elasticity curves. Feed conversion efficiency improvements and antibiotic-free growth promotion adoption rates served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in energy costs, currency exchange rates, or Baltic grain export volumes would shift the trajectory. Forecasts reflect documented assumptions regarding EFSA approval timelines and EUDR certification penetration rates. Cross-checking against FEFAC compound feed production statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Australia Animal Protein Market
Agriculture and Agri Products
Marine Algae Market
Agriculture and Agri Products
Brazil Compound Feed Market
Agriculture and Agri Products
Malaysia Floriculture Market
Agriculture and Agri Products
United Kingdom Compound Feed Market
Agriculture and Agri Products
Argentina Compound Feed Market
Agriculture and Agri Products
US Residential Organic Compost Market
Agriculture and Agri Products
Rape Seed Meal Market
Agriculture and Agri Products
Flower and Ornamental Plants Market
Agriculture and Agri Products
Global Medicated Feed Market
Agriculture and Agri Products
Primary Feed Materials Market
Agriculture and Agri Products
Centella Asiatica Market
Agriculture and Agri Products
Live Goods Market
Agriculture and Agri Products
Greenhouse Horticulture Market
Agriculture and Agri Products
Angola Agriculture Market
Agriculture and Agri Products
Sweet Potato Flour Market