
 K-Beauty Products Market | 2026-2036
K-Beauty Products Market Size, Share, and Industry Trends Forecast 2026-2036
K-Beauty Products Market Foresight
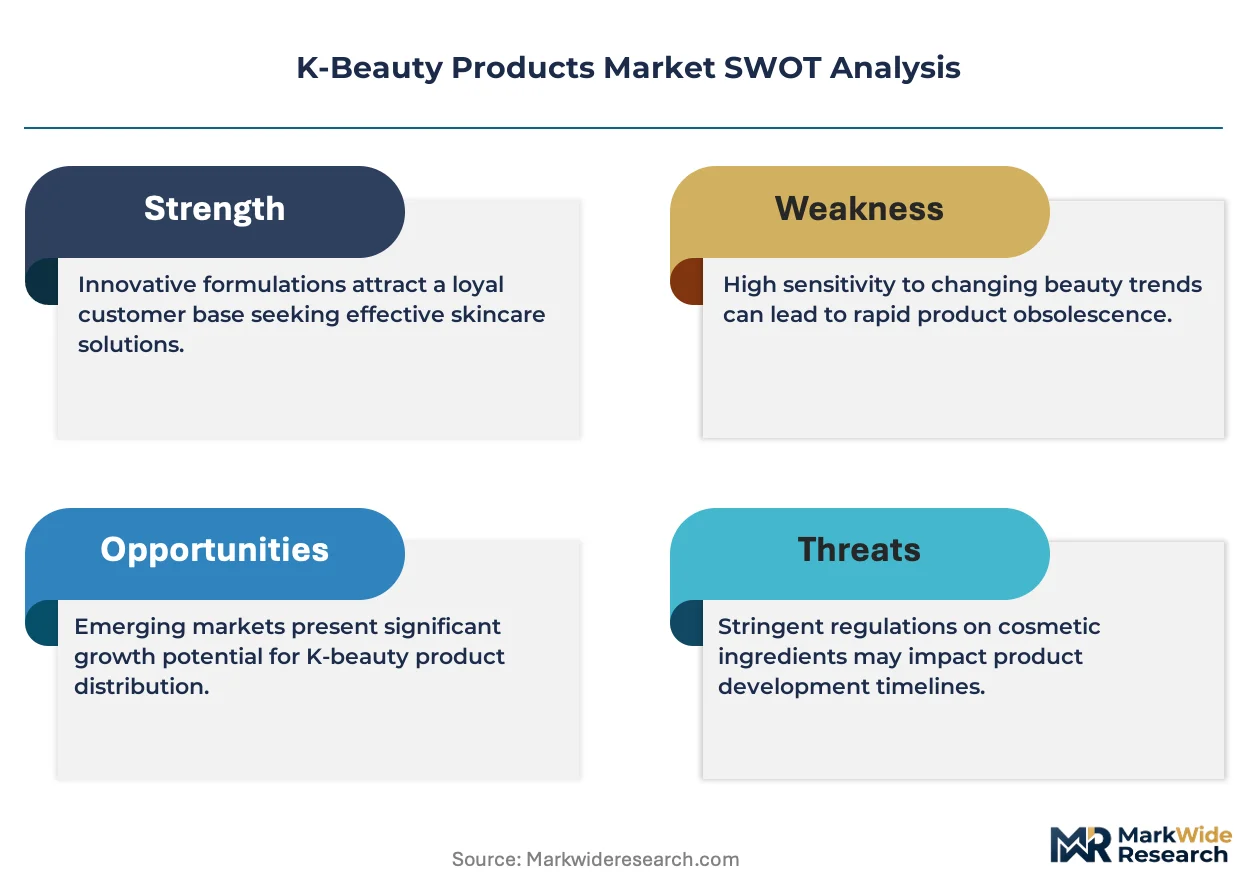
REACH compliance is expanding the cost-of-entry calculus for K-Beauty exporters seeking European market access. Amorepacific Corporation leverages integrated R&D labs to sustain formulation leadership across premium skincare tiers. LG Household & Health Care anchors its position through controlled distribution in domestic duty-free channels and selective overseas expansion. COSRX differentiates via ingredient transparency and minimalist positioning that navigates tightening regulatory scrutiny in multiple jurisdictions.
K-Beauty products encompass skincare, color cosmetics, haircare, and body care formulations distinguished by multi-step routines, fermented ingredients, and lightweight textures engineered for layering. Manufacturing emphasizes clean-room fermentation, low-pH stabilization, and airless packaging to preserve bioactive integrity across extended shelf lives. Skincare dominates value contribution due to higher per-unit pricing and repeat purchase frequency, while snail mucin and ginseng ingredient segments command premium positioning among Western consumers seeking provenance-driven efficacy. Daily routine applications lead volume throughput, though anti-aging treatments capture disproportionate margin pools through concentrated serum formats and clinical positioning.
MFDS cosmetic safety standards, EU REACH chemical registration, and FDA cosmetic labeling requirements collectively shape formulation constraints, import documentation burdens, and marketing claim boundaries for K-Beauty manufacturers. South Korean regulators now mandate expanded allergen disclosure, while European authorities scrutinize preservative systems under ongoing REACH evaluation cycles. Stakeholders must monitor evolving ingredient blacklists and preemptively reformulate legacy products to avoid market exclusion as regulatory harmonization pressures intensify across major export destinations.
Market Dynamics
Regulatory fragmentation across export destinations is forcing K-Beauty manufacturers to maintain parallel formulation portfolios, driving up compliance costs while compressing time-to-market for new product launches. MFDS allergen disclosure expansions and REACH preservative evaluations are creating divergent technical specifications that resist harmonization.
Growth Catalysts
- Gen Z Routine Adoption:North American consumers aged 18-27 are embracing 10-step skincare sequences, creating sustained demand for essences, ampoules, and layering-compatible textures that Western incumbents struggle to replicate.
- REACH-Compliant Formulation Services:European chemical registration requirements are spawning specialized Korean contract manufacturers who pre-certify ingredient decks, lowering market access barriers for mid-tier brands seeking EU distribution.
- Fermentation Biotechnology:Advances in controlled-environment bioactive cultivation are yielding stabilized galactomyces and bifida lysate variants with extended shelf integrity, enabling premium positioning in temperature-variable supply chains.
Market Restraints
- Snail Mucin Supply Concentration:Over 70% of cosmetic-grade snail secretion filtrate originates from Jeju Island and Gyeonggi-do farming collectives, exposing formulators to climate disruption and animal welfare scrutiny risks.
- Dual Certification Burden:Simultaneous MFDS safety dossiers and ECHA REACH registrations require redundant toxicological testing, adding 14-22 months to product development cycles for exporters targeting both domestic and European markets.
- Clean Beauty Substitution:Western "waterless" solid skincare formats and probiotic-forward indie brands are capturing ingredient-conscious consumers who perceive K-Beauty preservatives as excessive despite proven safety profiles.
Strategic Opportunities
- Men's Grooming White Space:Underpenetrated male skincare segments in Germany and the United Kingdom present first-mover potential for gender-neutral packaging and simplified 3-step routines that reduce purchase friction.
- Direct-to-Consumer Platform Expansion:TikTok Shop and Instagram Checkout are enabling Korean indie brands to bypass Sephora and Ulta margin structures, capturing full retail markup while building first-party customer data assets.
- Post-Consumer Recycled Packaging Mandates:EU Packaging and Packaging Waste Regulation requirements for 2030 recycled content thresholds are advantaging Korean suppliers with existing airless pump and mono-material tube capabilities.
Industry Challenges
- Cosmetic Chemist Talent Scarcity:Formulation expertise bridging traditional hanbang botanical knowledge and modern biotech stabilization is concentrated among a small cohort of MFDS-certified professionals in Seoul and Incheon.
- Legacy ERP Integration Friction:Mid-sized manufacturers are struggling to retrofit SAP and Oracle systems for real-time ingredient traceability required by expanding allergen disclosure mandates across multiple jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | K-Beauty Products Market |
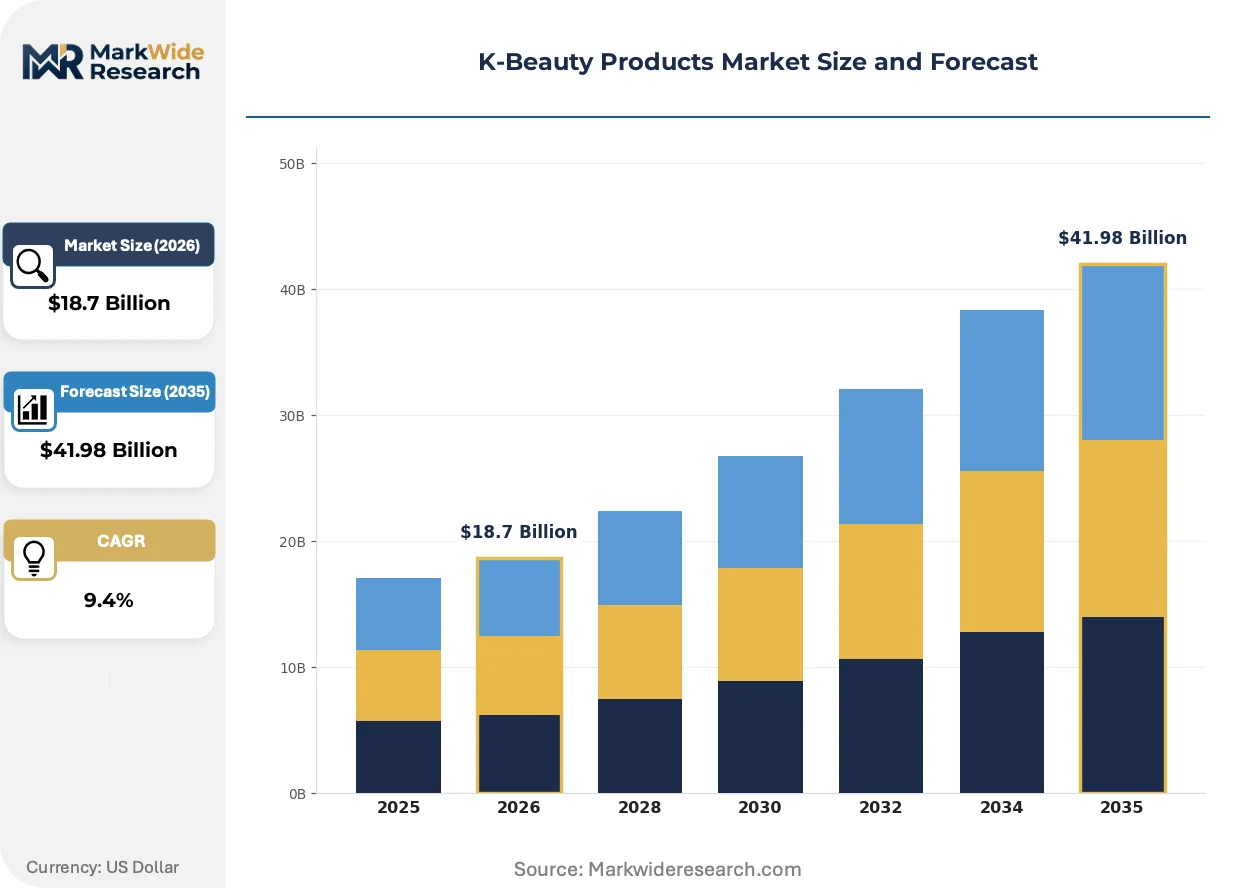
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Makeup, Haircare, Body Care Ingredient: Green Tea, Hyaluronic Acid, Snail Mucin, Ginseng Application: Daily Routine, Special Treatments, Anti-Aging, Hydration Packaging Type: Tubes, Jars, Pump Bottles, Sachets |
| Companies Covered | Amorepacific Corporation, LG Household & Health Care, COSRX, BANILA CO, The Face Shop, Clio Cosmetics, Able C&C, Nature Republic, Innisfree, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
K-Beauty Products Market Shifts & Advancements
Biotechnology convergence with traditional Korean botanical sourcing is compressing development timelines while raising efficacy substantiation standards. Formulators now face pressure to demonstrate clinical outcomes that satisfy both Western dermatological review boards and domestic hanbang authenticity claims.
Microbiome-targeted ingredient delivery is unifying fermentation-derived postbiotics with encapsulation technologies that protect bioactive integrity through acidic pH environments. Premium serum and ampoule lines from Seoul-based R&D clusters are adopting these systems at accelerating rates. The technology is unifying previously separate product categories—essences and treatments—into single-step formats that reduce routine complexity without sacrificing positioning.
EU REACH evaluation cycles are scrutinizing isothiazolinone preservative systems and certain ethanolamine compounds, forcing preemptive reformulation of legacy cleansing balms and sunscreens. Korean exporters are responding by accelerating phenoxyethanol-free and ethylhexylglycerin-stabilized alternatives through MFDS pre-approval channels. Color cosmetics with extended wear claims face the most intensive substitution pressure as European authorities tighten cumulative exposure assessments.
Social commerce discovery is displacing traditional retail browsing for K-Beauty acquisition, with algorithm-driven personalization replacing counter-based skin consultations. Younger consumers in the United States and Southeast Asia now encounter products through creator tutorials rather than brand-owned channels, fragmenting marketing spend across micro-influencer networks. This behavioral shift is most visible in TikTok-driven viral cycles that compress product lifecycles from 18-month trends to 90-day spikes requiring rapid inventory repositioning.
K-Beauty Products Market Segmentation
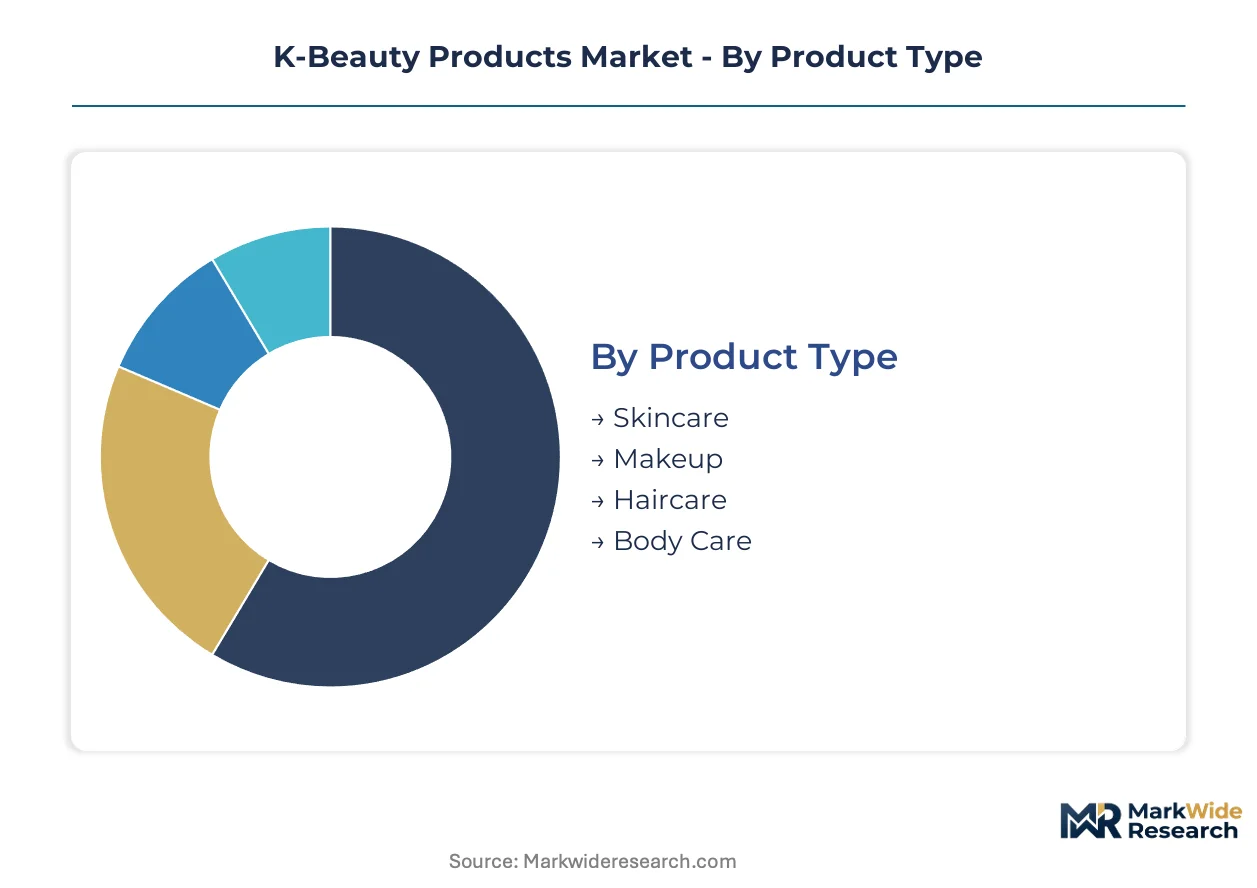
Segmentation reveals how K-Beauty manufacturers allocate R&D resources across divergent formulation requirements and channel specifications. Each dimension carries distinct margin profiles and regulatory exposure that shape portfolio construction for exporters navigating multiple jurisdictions.
Product Type:
Supply concentration tilts toward fermentation-capable facilities in Gyeonggi-do and Incheon, where clean-room infrastructure supports the most technically demanding categories.
- Skincare:Multi-step essences, serums, and ampoules dominate value capture through higher per-unit pricing and repeat purchase frequency. Demand concentrates in the United States among consumers aged 18-35 seeking clinical-grade outcomes without dermatologist intermediation. MFDS allergen disclosure mandates are forcing reformulation of legacy preservative systems in this category.
- Makeup:Lightweight cushion foundations and lip tints engineered for layering compatibility with skincare bases. Southeast Asian markets absorb the highest volumes due to humidity-responsive texture preferences and UV-protection integration. REACH evaluation cycles are scrutinizing colorant safety dossiers, compressing time-to-market for new shade launches.
- Haircare:Scalp-focused treatments leveraging fermented rice water and low-pH cleansing formulations. Korean domestic duty-free channels move significant volume of premium hair masks.
- Body Care:Extended hydration creams and exfoliating scrubs with lightweight, fast-absorbing textures adapted from facial skincare R&D. Sachet sampling formats drive trial conversion in emerging markets.
Skincare absorbs the bulk of installed capacity; makeup is expanding most quickly.
Ingredient:
Raw material sourcing geography determines cost volatility and provenance marketing authenticity for Western consumers.
- Snail Mucin:Cosmetic-grade filtrate harvested from controlled-environment heliciculture farms on Jeju Island. Over 70% of global supply originates from Gyeonggi-do and Jeju collectives, exposing formulators to climate disruption risks and animal welfare audit pressures. German and UK consumers drive premium positioning for ethically certified variants.
- Hyaluronic Acid:Biotech-derived multi-molecular weight hydrators stabilized through low-pH fermentation processes. Demand concentrates in daily routine applications across North American direct-to-consumer platforms where layering education reduces purchase friction. ECHA REACH registrations for sodium hyaluronate variants are accelerating among Korean contract manufacturers.
- Ginseng:Red ginseng root extracts processed through traditional hanbang methods combined with modern encapsulation. Domestic Korean consumers sustain the core market for anti-aging positioning.
- Green Tea:Camellia sinensis leaf extracts standardized for EGCG content, sourced primarily from Boseong tea-growing regions. Soothing claims for sensitive skin applications are gaining traction in EU markets.
Snail mucin commands the highest ingredient premiums; hyaluronic acid is climbing the fastest.
Application:
Usage occasion segmentation separates volume-driven replenishment purchases from margin-rich treatment positioning.
- Daily Routine:Core cleansing, toning, and moisturizing sequences forming the foundation of multi-step regimens. United States Gen Z consumers aged 18-27 sustain demand for essences and ampoules through TikTok-driven discovery and creator tutorial education. Social commerce fragmentation is compressing product lifecycles from 18-month trends to 90-day spikes.
- Anti-Aging:Concentrated retinol, peptide, and fermented extract treatments with clinical substantiation requirements. Premium serum formats capture disproportionate margin pools among Southeast Asian consumers seeking provenance-driven efficacy. Biotechnology convergence with traditional botanical sourcing is raising substantiation standards for both Western dermatological review and domestic hanbang authenticity claims.
- Special Treatments:Weekly exfoliating peels, sheet masks, and overnight sleeping packs with intensive active delivery. Korean domestic market penetration remains highest for this occasion.
- Hydration:Layering-focused products emphasizing moisture barrier repair and transepidermal water loss reduction. Simplified 3-step routine formats are penetrating male grooming white space in Germany and the United Kingdom.
Daily routine absorbs the bulk of volume throughput; anti-aging captures the steepest expansion trajectory.
Packaging Type:
Format engineering determines shelf stability, dispensing precision, and compliance with evolving recycled content mandates.
- Pump Bottles:Airless dispensing systems preserving bioactive integrity of fermentation-derived actives through oxygen exclusion. Premium skincare lines from Seoul-based R&D clusters are adopting these at accelerating rates. EU Packaging and Packaging Waste Regulation thresholds for 2030 recycled content are advantaging Korean suppliers with existing mono-material pump capabilities.
- Tubes:Laminated and mono-material squeeze formats for cleansers, sunscreens, and body care with extended shelf life requirements. Mid-tier brands targeting EU distribution favor tubes for REACH-compliant labeling surface area and logistics efficiency.
- Jars:Wide-mouth containers for balms, sleeping masks, and rich creams requiring finger application. Domestic Korean consumers associate jar formats with luxury hanbang positioning.
- Sachets:Single-use foil and biodegradable film packets for sampling, travel, and emerging market trial conversion. TikTok Shop and Instagram Checkout fulfillment models favor sachets for lightweight shipping economics.
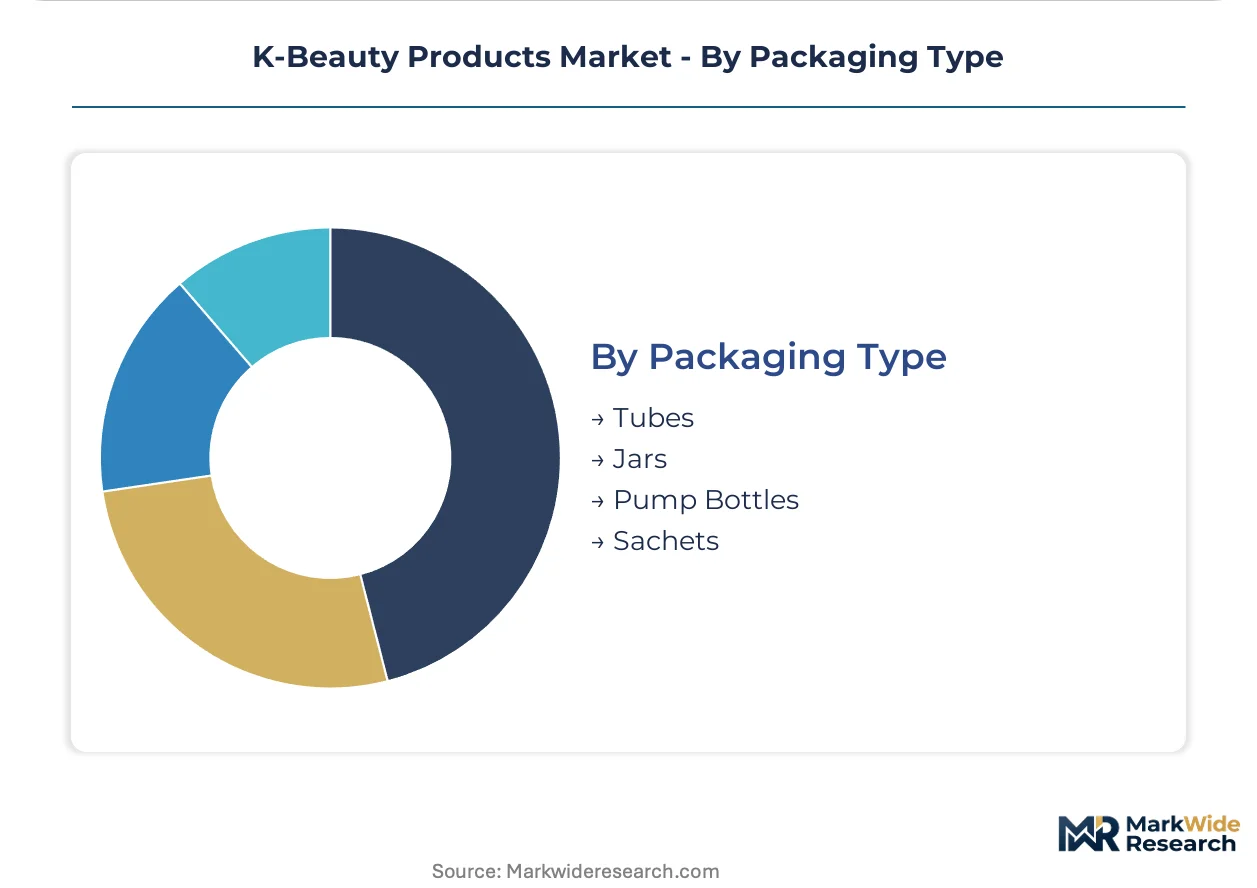
Pump bottles absorb the bulk of premium positioning investment; tubes are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's Free Economic Zones in Incheon and Gyeonggi-do concentrate K-Beauty manufacturing infrastructure, attracting foreign direct investment through tax holidays and streamlined MFDS pre-approval pathways for export-oriented facilities.
United States
Gen Z consumers aged 18-27 in California and New York Metro drive essence and ampoule demand through TikTok Shop discovery and creator tutorial education. FDA cosmetic labeling requirements mandate expanded ingredient disclosure for fermented actives, compressing time-to-market for new serum launches. Seoul-based brands establish fulfillment centers in New Jersey and Texas to bypass Sephora margin structures and capture direct-to-consumer retail markup.
Germany
Ingredient-conscious consumers in Bavaria and North Rhine-Westphalia seek REACH-compliant snail mucin variants with ethical certification documentation. ECHA preservative evaluation cycles scrutinize isothiazolinone systems in cleansing balms, forcing preemptive reformulation of legacy K-Beauty exports. Korean contract manufacturers in Gyeonggi-do now pre-certify phenoxyethanol-free alternatives specifically for German distribution.
United Kingdom
London and Southeast England absorb premium anti-aging serums with clinical substantiation positioning among millennial professionals. The UK's departure from EU REACH creates parallel registration requirements, adding documentation burden for exporters maintaining both ECHA and UK REACH dossiers. Korean indie brands leverage Instagram Checkout to build first-party customer data assets in Greater Manchester and Birmingham.
Japan
Tokyo and Osaka sustain demand for hanbang-authentic ginseng and green tea formulations through domestic duty-free channels and selective department store placement. METI cosmetic safety guidelines align closely with MFDS standards, reducing technical adaptation costs for Korean exporters. Seoul-based R&D clusters prioritize Japan-bound SKU development for shared fermentation biotechnology specifications.
Singapore
Southeast Asian humidity-responsive texture preferences concentrate cushion foundation and lip tint demand in this logistics hub serving Indonesia, Thailand, and Vietnam. The Health Sciences Authority's cosmetic regulatory framework accepts MFDS safety dossiers through mutual recognition pathways, accelerating market access. Korean manufacturers establish regional distribution centers in Jurong to serve ASEAN temperature-variable supply chains.
K-Beauty Products Market Competitive Landscape
South Korean producers anchor the premium tier through integrated R&D and controlled domestic duty-free channels; mid-sized specialists hold position via ingredient transparency and minimalist positioning that navigates tightening regulatory scrutiny. The vendor base stratifies across conglomerate-affiliated houses with captive fermentation facilities, contract manufacturing platforms serving EU REACH pre-certification demand, and direct-to-consumer indie brands exploiting social commerce fragmentation. Three archetypes dominate: biotechnology-integrated formulators, regulatory-compliance service providers, and algorithm-native digital natives. Competitive intensity concentrates on preemptive reformulation cycles and first-party customer data asset accumulation.
Within the biotechnology-integrated tier, Amorepacific Corporation exemplifies formulation leadership across premium skincare tiers through integrated R&D lab infrastructure. LG Household & Health Care anchors its competitive position through controlled distribution in domestic duty-free channels and selective overseas expansion into Japan and Southeast Asia. COSRX occupies a distinct archetype as a regulatory-navigation specialist, representing ingredient transparency and minimalist positioning that satisfies divergent MFDS and REACH disclosure mandates without legacy portfolio drag.
| Leading Market Players |
|---|
| Amorepacific Corporation |
| LG Household & Health Care |
| COSRX |
| BANILA CO |
| The Face Shop |
| Clio Cosmetics |
| Able C&C |
| Nature Republic |
| Innisfree |
| Others |
Supply & Pricing Matrix
Jeju Island snail mucin spot price volatility cascades through formulation cost structures, compressing margins for mid-tier exporters while amplifying premium positioning power for integrated houses with captive heliciculture operations and MFDS-certified fermentation facilities.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent above contract pricing reward brands with domestic Gyeonggi-do manufacturing and airless pump filling capabilities, while spot inventory liquidation through TikTok Shop channels erodes standard-tier positioning. Three-tier pricing structure across premium, standard, and economy levels separates Amorepacific's clinical-grade serums from COSRX's minimalist essences and sachet-format trial packs. Pricing pressure stems from REACH-compliant reformulation costs and redundant toxicological testing for dual MFDS-ECHA certification. Indie direct-to-consumer brands exhibit highest price sensitivity due to margin compression from platform fees and influencer commission structures.
Supply Chain Analysis
EU Packaging and Packaging Waste Regulation recycled content mandates for 2030 are reshaping sourcing toward Korean mono-material tube and airless pump suppliers with existing post-consumer recycled capabilities. Raw material dependencies center on Jeju Island and Gyeonggi-do snail farming collectives, Incheon biotech-derived hyaluronate facilities, and Boseong green tea extraction sites. Single-source vulnerability concentrates in cosmetic-grade snail secretion filtrate where climate disruption and animal welfare audit failures threaten seventy percent of global supply. Distribution runs through Seoul-based R&D clusters feeding New Jersey and Texas fulfillment centers for United States direct-to-consumer bypass, with Jurong regional hubs serving ASEAN humidity-responsive markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH registration burdens and MFDS allergen disclosure expansions erect capital-intensive compliance moats that protect incumbent market positions while screening out undercapitalized challengers lacking dedicated regulatory affairs infrastructure.
For Market Incumbents: Anticipate preemptive reformulation cycles for isothiazolinone-stabilized legacy cleansers and sunscreens as ECHA evaluation cycles tighten, while deepening backward integration into captive Jeju heliciculture and Incheon fermentation biotechnology to secure snail mucin and galactomyces supply against climate disruption. Channel control through domestic duty-free placement and selective Sephora exclusivity defends premium positioning from algorithm-native indie competitors. For New Entrants and Emerging Players: Male grooming professionals in Germany and the United Kingdom represent an underserved buyer archetype with minimal incumbent saturation and simplified three-step routine acceptance. Simplified hanbang-authentic formats with phenoxyethanol-free positioning penetrate this white space through Instagram Checkout first-party data accumulation, bypassing traditional retail margin structures entirely. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-sized contract manufacturers with pre-certified REACH ingredient decks and Gyeonggi-do clean-room infrastructure in South Korea, where regulatory compliance capabilities compound valuation resilience. Long-term viability hinges on biotechnology-integrated formulation expertise bridging traditional hanbang knowledge and modern encapsulation stabilization. The inflection signal to monitor is accelerated phenoxyethanol-free alternative adoption through MFDS pre-approval channels.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Formulation Pre-Certification | ECHA registration-ready ingredient decks lower European market access barriers for mid-tier brands. |
| Direct-to-Consumer Platform Expansion | TikTok Shop and Instagram Checkout bypass Sephora margin capture while building first-party data assets. |
| Men's Grooming Line Introduction | Gender-neutral packaging and simplified routines penetrate underpenetrated German and UK male segments. |
| Post-Consumer Recycled Packaging Transition | EU Packaging and Packaging Waste Regulation 2030 thresholds advantage existing mono-material capabilities. |
| Backward Integration into Helliciculture | Captive Jeju snail farming secures mucin supply against climate disruption and animal welfare audit risks. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, with MFDS cosmetic safety dossiers and ECHA REACH registration databases providing formulation constraint benchmarks. Primary interviews with brand managers at Seoul-based R&D clusters, category buyers at United States specialty retailers, contract manufacturing procurement leads in Gyeonggi-do, and regulatory affairs specialists navigating dual certification requirements validated demand assumptions and compliance cost structures. Bottom-up volume modeling across product type, ingredient, application, and packaging dimensions triangulated against top-down market sizing from import-export statistics.
Granularity-level modeling operated at SKU-country-channel intersection for skincare, makeup, haircare, and body care categories, with separate treatment of fermentation-derived and botanical-extract ingredient cost structures. CAGRs across the analysis window derived from segment-level volume projections adjusted for regulatory delay impacts and social commerce velocity shifts. Forecast inputs incorporated TikTok Shop fulfillment economics, EU recycled packaging mandate compliance curves, and male grooming penetration assumptions for Germany and the United Kingdom.
Revisions become necessary when ECHA preservative evaluation cycles accelerate beyond current timelines, MFDS expands allergen disclosure mandates to additional compound classes, or climate disruption materially impacts Jeju heliciculture yields. Forecasts reflect documented assumptions regarding social commerce platform fee structures and REACH registration cost trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Organic Makeup Remover Market
Cosmetics & Skincare
Organic Soaps Market
Cosmetics & Skincare
Temporary Tattoo Market
Cosmetics & Skincare
Period Balm Market
Cosmetics & Skincare
Camellia Skincare and Cosmetics Market
Cosmetics & Skincare
Beauty Facial Mask Market
Cosmetics & Skincare
Mascara Applicators Market
Cosmetics & Skincare
Natural Cosmetic Color Market
Cosmetics & Skincare
Eyeliner Market
Cosmetics & Skincare
Lip Oil Market
Cosmetics & Skincare
Glow in the Dark Cosmetics Market
Cosmetics & Skincare
Myanmar Skin Care Products Market
Cosmetics & Skincare
China Cosmetic Products Market
Cosmetics & Skincare
E Commerce Cosmetic and Fragrance Market
Cosmetics & Skincare
Face Wash Market
Cosmetics & Skincare
Pillow Spray Market