
 Israel Cosmetics Market | 2026-2036
Israel Cosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
Israel Cosmetics Market Insights
Multi-source ingredient procurement is expanding across Israeli cosmetics manufacturers as supply chain resilience replaces cost minimization. L'Oréal S.A. leverages its global R&D network to introduce advanced dermatological formulations tailored to regional skin profiles. FARAN Cosmetics anchors its position through Dead Sea mineral extraction and local botanical sourcing. Olea Essence differentiates via olive oil-based organic skincare manufactured in the Galilee region.
Israel cosmetics encompass topical preparations formulated with active ingredients for skin conditioning, color enhancement, and fragrance delivery, typically manufactured through emulsification, extraction, or fermentation processes meeting Ministry of Health purity thresholds. Skincare commands the largest revenue pool due to high consumer willingness to pay for anti-aging and sun protection formulations in Israel's intense UV climate. Online distribution channels represent the fastest-growing segment, driven by direct-to-consumer subscription models and social commerce penetration among younger demographics. Organic ingredient formulations attract premium pricing, though synthetic bases still dominate volume production for mass-market haircare and color cosmetics.
The Ministry of Health regulates cosmetic safety through pre-market notification requirements and ingredient disclosure mandates aligned with evolving EU REACH standards. BIS certification influences import acceptance for packaging materials and raw material traceability. ISO 22716 Good Manufacturing Practices shape production facility audits across domestic manufacturers and contract laboratories. Stakeholders must monitor regulatory divergence between Israeli national standards and harmonized European frameworks when planning export expansion or import substitution strategies.
Market Dynamics
Israel's Ministry of Health tightened cosmetic safety standards in alignment with evolving EU REACH thresholds, forcing domestic manufacturers into accelerated reformulation cycles and supply chain requalification. This regulatory compression is restructuring competitive positioning around compliance infrastructure rather than brand heritage alone.
Growth Catalysts
- Regulatory Harmonization:EU REACH alignment by Israel's Ministry of Health creates export pathway clarity for Dead Sea mineral extractors seeking European market access without dual certification burdens.
- UV-Driven Formulation Demand:Israel's intense solar exposure sustains premium willingness-to-pay for anti-aging and photoprotection skincare across Tel Aviv's affluent consumer base.
- Direct-to-Consumer Infrastructure:Social commerce penetration among millennial women is compressing traditional pharmacy and salon channel dominance in Jerusalem and Haifa.
Market Restraints
- Dead Sea Mineral Concentration Risk:Extraction rights and processing capacity concentrate in southern Israel, creating single-source dependency for mineral-based active ingredients.
- Import Packaging Certification Friction:BIS certification requirements for raw material traceability extend procurement timelines for international suppliers serving Israeli contract manufacturers.
- Synthetic Base Cost Volatility:Petrochemical-derived emulsifiers and surfactants face input cost fluctuation tied to global energy markets, pressuring mass-market haircare margins.
Strategic Opportunities
- Galilee Olive Oil Vertical:Underexploited organic olive cultivation in northern Israel offers traceable botanical sourcing for clean-label positioning in premium skincare.
- Subscription Model Penetration:Direct-to-consumer replenishment platforms remain underdeveloped outside Tel Aviv metro, presenting white space in Haifa and peripheral cities.
- Ministry of Health Export Facilitation:Streamlined pre-market notification pathways for EU-aligned formulations reduce regulatory friction for Israeli brands entering European pharmacy channels.
Industry Challenges
- ISO 22716 Audit Capacity:Limited domestic GMP-certified contract laboratories create bottlenecks for mid-tier manufacturers seeking facility qualification.
- Formulation Talent Scarcity:Shortage of cosmetic chemists with dual competency in Dead Sea mineral stabilization and clean-label organic chemistry constrains R&D throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Israel Cosmetics Market |
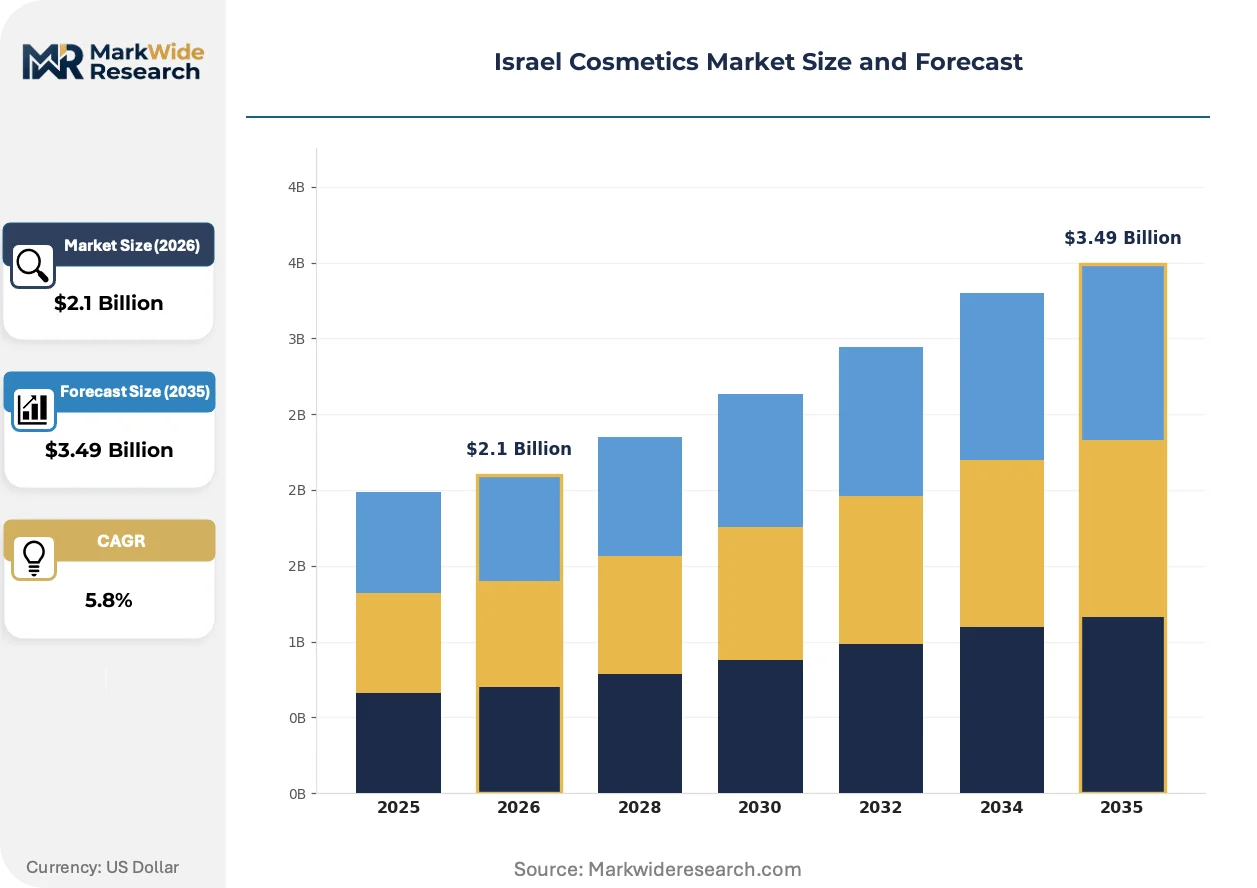
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Makeup, Fragrance, Haircare End User: Women, Men, Teens, Seniors Distribution Channel: Online, Retail Stores, Salons, Pharmacies Ingredient Type: Organic, Natural, Synthetic, Biodegradable |
| Companies Covered | L'Oréal S.A., Estee Lauder Companies Inc, FARAN Cosmetics, Olea Essence, Danya Cosmetics Ltd, Cosmopharm Ltd, Lilit Cosmetics Ltd, Revlon, Castro Model Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Israel Cosmetics Market Trends and Innovations
Biotechnology is displacing conventional extraction methods across Israeli cosmetic manufacturing, with fermentation-derived actives and cell-culture botanicals compressing traditional supply chains. This shift is restructuring competitive advantage around bioprocess capability rather than agricultural land access.
Fermentation-based active production is modularizing ingredient supply for Israeli skincare formulators. Domestic manufacturers are adopting microbial synthesis platforms to replicate Dead Sea mineral bioactivity without extraction dependency. This technology is modularizing supply chain geography, enabling production relocation from mineral-constrained southern regions to centralized industrial zones.
Israel's Ministry of Health is tightening pre-market notification requirements for novel biotechnology-derived ingredients. Manufacturers must now submit extended safety dossiers for fermentation actives previously grandfathered under traditional extraction classifications. Clean-label startups in Tel Aviv are responding by segregating R&D pipelines into EU-exportable and domestic-only formulation tracks.
Millennial women are compressing brand loyalty cycles through social commerce discovery mechanisms. Instagram and TikTok commerce are displacing pharmacy consultation as the primary purchase trigger for skincare in Jerusalem and Haifa. This behavioral shift is most visible among 25-34 demographic cohorts prioritizing ingredient transparency over heritage brand recognition.
Israel Cosmetics Market Segmentation
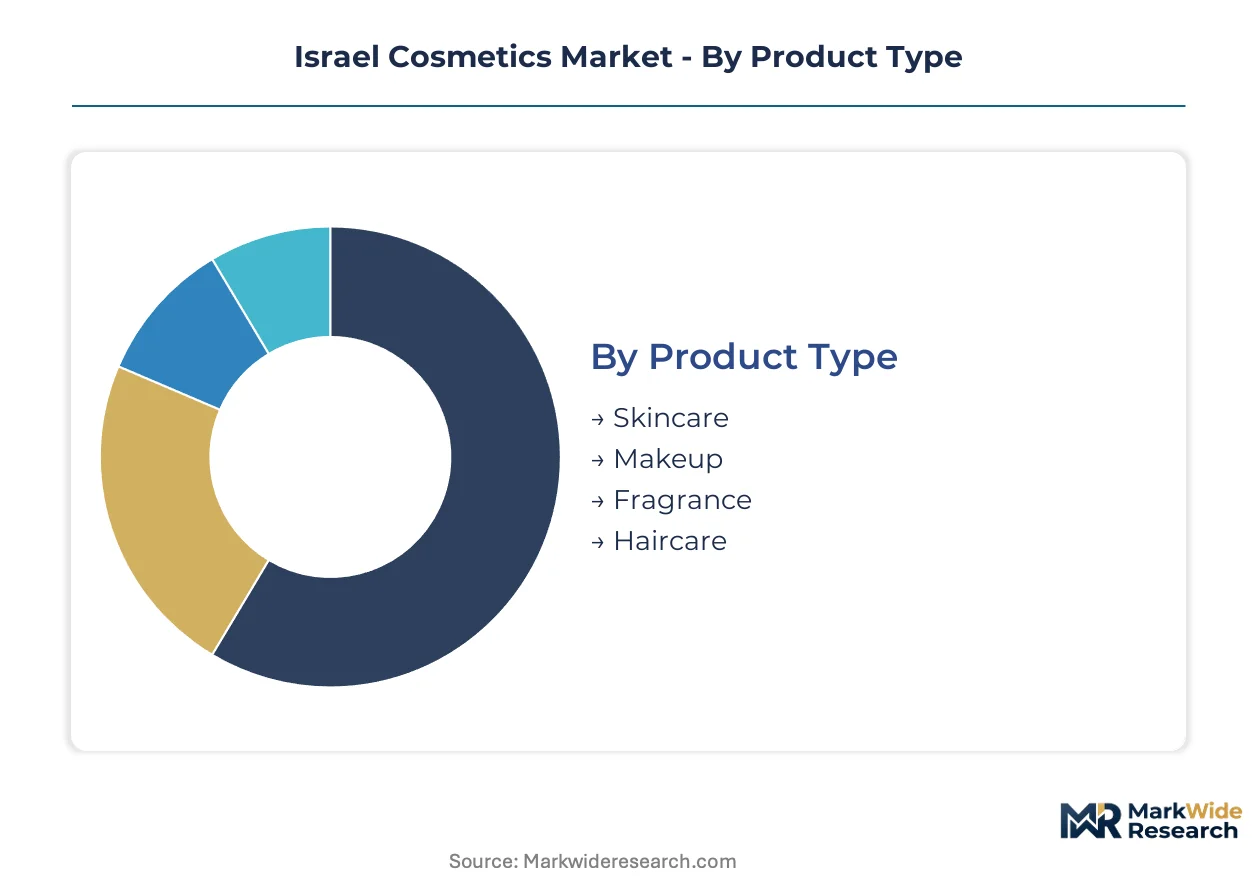
Israel's cosmetics market fragments across formulation chemistry, demographic targeting, and channel access. Each segmentation axis reveals distinct margin structures and regulatory exposure profiles that shape competitive strategy.
Product Type:
Formulation complexity and UV-adaptation requirements define the technology axis across Israel's climate-stressed consumer base.
- Skincare:Anti-aging serums and photoprotection creams command premium pricing through Dead Sea mineral complexes and high-SPF organic filters. Tel Aviv's affluent households sustain willingness-to-pay for dermatologist-backed formulations addressing intense solar exposure damage.
- Makeup:Color cosmetics incorporating skincare-actives—hybrid BB creams, mineral foundations with niacinamide—are displacing pure decorative products. Jerusalem's younger demographics prioritize Instagram-optimized textures over traditional pharmacy brands.
- Fragrance:Niche perfumery leveraging regional botanicals (citrus, jasmine, desert herbs) differentiates from mass-market imports.
- Haircare:Sulfate-free and keratin-repair segments dominate, with Dead Sea salt scalp treatments gaining traction in salon channels.
Skincare leads on scale; makeup leads on momentum.
End User:
Demographic targeting in Israel reflects divergent channel preferences and ingredient transparency expectations.
- Women:Millennial women aged 25-34 drive subscription commerce adoption and clean-label purchasing, particularly for Galilee-sourced olive oil formulations. Social commerce discovery has displaced pharmacy consultation as the primary purchase trigger.
- Men:Male grooming expansion concentrates in Tel Aviv metro, with beard oils and anti-aging moisturizers gaining pharmacy shelf space previously allocated to unisex products.
- Teens:Acne-focused, fragrance-free formulations with Ministry of Health pediatric safety clearance dominate this price-sensitive cohort.
- Seniors:Anti-aging clinical dermatology partnerships and pharmacy consultation dependency characterize mature-skin purchasing patterns.
Women anchor volume concentration; men exhibit the steepest expansion trajectory.
Distribution Channel:
Channel selection determines margin capture and regulatory compliance burden for Israeli cosmetics manufacturers.
- Online:Direct-to-consumer subscription models and TikTok commerce are compressing traditional retail dominance. Social proof mechanisms and ingredient transparency disclosure drive conversion among digitally native demographics.
- Retail Stores:Mass-market volume flows through supermarket and department store cosmetics counters, with private-label expansion pressuring branded margin structures.
- Salons:Professional-only treatments and back-bar products sustain higher service-attachment pricing, particularly for Dead Sea mineral-based therapies.
- Pharmacies:Regulatory credibility and pharmacist consultation remain decisive for sensitive-skin and post-procedure formulations.
Pharmacies retain trust leadership; online channels are climbing the fastest.
Ingredient Type:
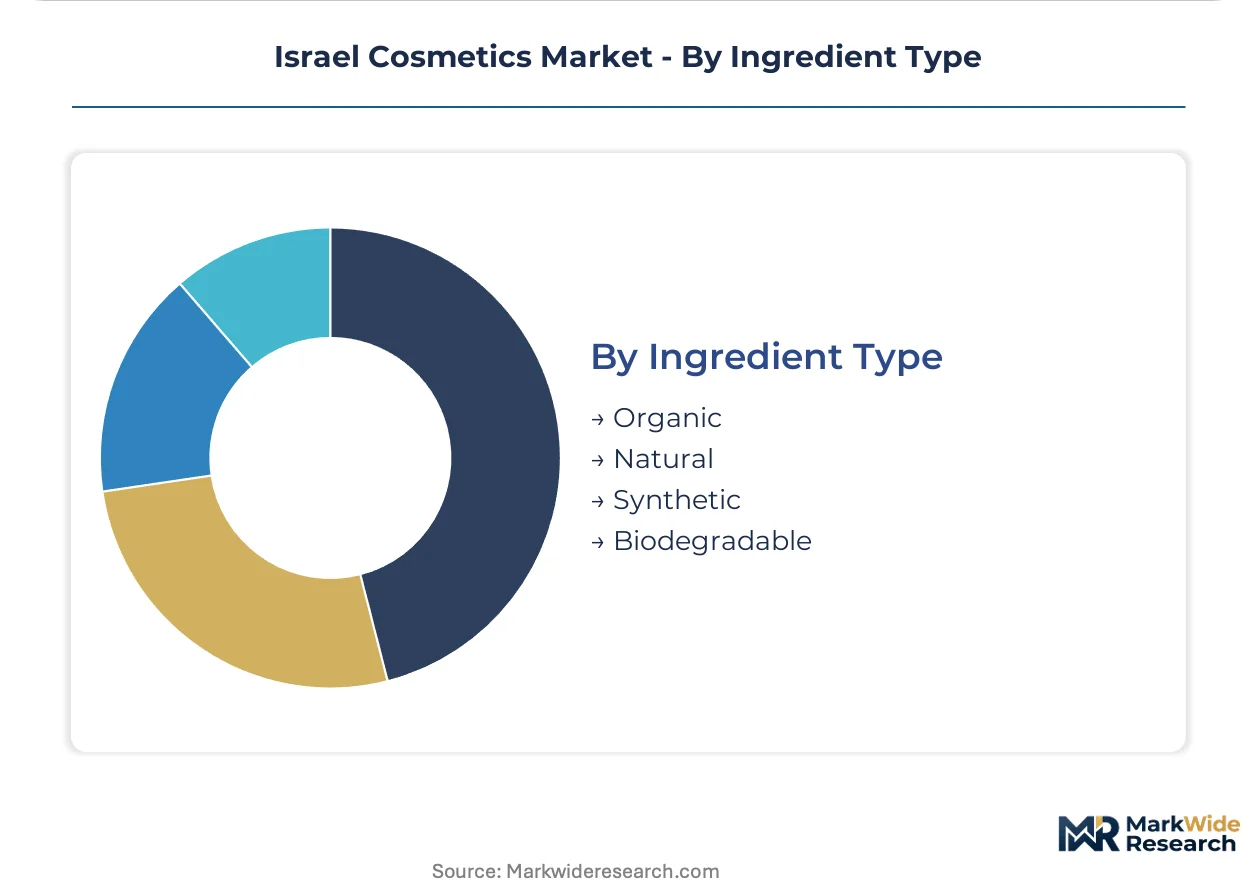
Raw material sourcing strategy separates premium positioning from mass-market cost engineering in Israel's supply-constrained environment.
- Organic:Certified organic olive oil from Galilee cultivation and Dead Sea salt extracts command 40-60% price premiums. Ministry of Health alignment with EU organic certification standards facilitates export pathway development.
- Natural:Botanically derived actives without full organic certification occupy the mid-tier, balancing consumer preference for "clean" positioning against cost constraints.
- Synthetic:Petrochemical-derived emulsifiers and surfactants dominate haircare and color cosmetics volume production, exposed to global energy market input volatility.
- Biodegradable:Emerging fermentation-derived and biosynthetic alternatives are displacing conventional synthetics in Tel Aviv clean-label startup formulations.
Synthetics dominate volume scale; biodegradable alternatives lead on innovation momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tel Aviv anchors Israel's cosmetics production gravity through its concentration of R&D laboratories, formulation startups, and direct-to-consumer distribution infrastructure. The country's market dynamics fragment across distinct metropolitan demand centers and specialized extraction zones.
Tel Aviv Metro
Affluent millennial households in Tel Aviv sustain premium pricing for anti-aging serums and photoprotection formulations adapted to intense UV exposure. The Ministry of Health maintains its primary cosmetics safety oversight office here, streamlining pre-market notification for EU-aligned export formulations. Ramat Gan hosts biotechnology startups developing fermentation-derived actives as alternatives to Dead Sea mineral extraction.
Jerusalem
Pharmacy channel dominance persists in Jerusalem through pharmacist consultation dependency for sensitive-skin and pediatric formulations. The city's national health infrastructure shapes demand for Ministry of Health-cleared therapeutic cosmetics. Industrial zones on the city's periphery concentrate contract manufacturing for mass-market haircare distributed through supermarket retail.
Haifa
Haifa's port infrastructure positions the metro as the primary import gateway for raw materials serving northern Israeli manufacturers. BIS certification processing for packaging materials concentrates here, extending procurement timelines for international suppliers. The city's younger demographic profile accelerates social commerce adoption, compressing traditional salon channel relevance.
Dead Sea Basin
Southern Israel's Dead Sea extraction rights concentrate mineral-based active ingredient supply for premium skincare brands. Water level decline and processing capacity constraints create single-source dependency risks for formulators dependent on salt and mud complexes. The region's industrial zones host the country's largest mineral processing facilities, with limited alternative sourcing for Dead Sea-derived actives.
Galilee Region
Organic olive cultivation in northern Israel supplies traceable botanical feedstock for clean-label skincare positioning. Olea Essence anchors regional production through olive oil-based formulation manufacturing. The area's agricultural cooperatives are expanding certified organic acreage to meet export demand for EU-organic-compliant raw materials.
Israel Cosmetics Market Competitive Landscape
Global majors compete with regional champions across formulation technology and channel access dimensions. L'Oréal S.A. and Estee Lauder Companies Inc anchor the multinational tier through dermatological R&D networks and pharmacy channel penetration, while domestic specialists concentrate around Dead Sea mineral extraction and Galilee botanical sourcing. Three archetypes define competitive positioning: biotechnology-driven formulators, mineral-extraction verticals, and direct-to-consumer clean-label startups. M&A activity concentrates on fermentation technology acquisitions, while capacity expansion targets EU-export-qualified manufacturing facilities.
Within the mineral-extraction vertical, FARAN Cosmetics exemplifies Dead Sea-based supply chain anchoring, while Olea Essence represents Galilee olive oil specialization. L'Oréal S.A. occupies the multinational technology leader position, leveraging global R&D infrastructure for regional skin-profile adaptation. These three entities illustrate the competitive tension between geographic resource control and global formulation capability.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| Estee Lauder Companies Inc |
| FARAN Cosmetics |
| Olea Essence |
| Danya Cosmetics Ltd |
| Cosmopharm Ltd |
| Lilit Cosmetics Ltd |
| Revlon |
| Castro Model Ltd |
| Others |
Pricing and Supply Chain Analysis
Pharmacy procurement managers in Jerusalem and Haifa anchor volume concentration for mass-market haircare and color cosmetics, locking in contract-based long-term offtake pricing that buffers domestic manufacturers against petrochemical input volatility. This buyer concentration forces tiered margin compression across synthetic-base formulations while enabling premium subscription pricing for Dead Sea mineral complexes sold through direct-to-consumer channels in Tel Aviv.
Pricing Analysis
Input-cost pass-through from Dead Sea mineral extraction rights and Galilee olive oil cultivation shapes pricing stratification across premium, standard, and economy tiers. Certification level—specifically Ministry of Health EU-alignment and ISO 22716 GMP compliance—drives 40-60% price premiums for organic formulations. Cost compression in mass-market synthetics is intensifying because global energy market volatility feeds directly into petrochemical-derived emulsifier costs. Teens and price-sensitive supermarket buyers exhibit highest price sensitivity; affluent Tel Aviv millennials purchasing anti-aging serums show least sensitivity.
Supply Chain Analysis
Certification and qualification gating through BIS packaging standards and Ministry of Health pre-market notification requirements extends procurement timelines for international raw material suppliers. Geographic supply concentration centers on Israel's Dead Sea Basin for mineral actives, Italy and Spain for organic olive oil feedstock alternatives, and China and India for synthetic base chemicals. Raw material dependencies include Dead Sea salt and mud complexes, Galilee-sourced olive oil, and petrochemical-derived surfactants. Single-source vulnerability for Dead Sea mineral extraction creates structural supply chain risk. Distribution runs through pharmacy and salon channels for therapeutic formulations, with online direct-to-consumer platforms capturing fastest-growing replenishment volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Israel's cosmetics market operates as a regulatory compounder where Ministry of Health alignment with EU REACH thresholds accelerates reformulation demand and creates compliance-based competitive moats for prepared manufacturers.
For Market Incumbents: Deploy fermentation technology acquisition as the priority lever to reduce Dead Sea mineral extraction dependency while securing biotechnology-derived active pipelines. Incorporate backward integration into Galilee olive cultivation to lock in certified organic feedstock traceability against emerging clean-label competitors. Counter social commerce entrants by capturing pharmacist consultation relationships in Jerusalem before digital channels displace pharmacy trust authority. For New Entrants and Emerging Players: TikTok commerce and Instagram shop integration offer the lowest barrier route to bypass entrenched pharmacy distribution in Haifa and peripheral cities. Target subscription replenishment models for millennial women aged 25-34 in underpenetrated northern metros outside Tel Aviv. Pursue Ministry of Health export facilitation pathways for EU-aligned formulations to access European pharmacy margins above domestic mass-market ceilings. For Investors and Strategic Acquirers: Multinational dermatological majors are the most active acquirer in this space, seeking biotechnology capability and Dead Sea mineral extraction rights to complete regional skin-profile adaptation portfolios. Long-term viability hinges on fermentation-platform R&D throughput rather than agricultural land access. Watch for Ministry of Health pre-market notification backlog clearance as inflection signal for export-ready formulation capacity scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Technology Acquisition | Microbial synthesis platforms reduce Dead Sea mineral dependency while enabling EU-exportable active production. |
| Galilee Olive Oil Backward Integration | Captive organic cultivation secures traceable feedstock for clean-label premium positioning against synthetic competitors. |
| Direct-to-Consumer Subscription Launch | Social commerce penetration in Haifa and peripheral cities bypasses pharmacy channel concentration in Jerusalem. |
| ISO 22716 GMP Certification Investment | Facility qualification unlocks contract manufacturing demand from mid-tier brands facing audit capacity bottlenecks. |
| EU REACH Alignment Completion | Regulatory harmonization enables streamlined export pathways into European pharmacy channels without dual certification burden. |
Research Methodology
Bottom-up pharmacy and salon channel modeling reconciled against top-down Dead Sea mineral extraction and Galilee olive oil cultivation tracking forms the analytical core of this study. Primary interviews with formulation chemists, Ministry of Health regulatory affairs officers, pharmacy procurement managers, salon channel distributors, and direct-to-consumer brand founders combined with secondary validation from customs import records, Ministry of Health pre-market notification filings, ISO certification databases, and EU REACH registration data. Triangulation between supply-side production capacity and demand-side channel flow ensures cross-verified volume and value estimates.
Historical trendline analysis across skincare, makeup, fragrance, and haircare segments established baseline growth patterns extended through the projection horizon. Segmentation dimensions modeled include formulation chemistry, demographic targeting, distribution channel, and ingredient sourcing strategy. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion constraints. Forecast inputs incorporated UV-driven photoprotection demand intensity, social commerce penetration curves, and regulatory harmonization implementation timelines.
The model assumes a particular technology adoption path; alternative pathways for fermentation-derived actives displacing traditional Dead Sea mineral extraction would alter the outlook. Forecasts reflect assumptions regarding Ministry of Health enforcement consistency, Dead Sea water level stabilization, and EU organic certification mutual recognition durability. A model refresh is warranted upon material change in biotechnology-derived ingredient safety dossier approval velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Matte Lipstick Market
Cosmetics & Skincare
GCC Bath Soap Market
Cosmetics & Skincare
Beauty Facial Mask Market
Cosmetics & Skincare
Waterproof Temporary Tattoo Sticker Market
Cosmetics & Skincare
Snail Beauty Products Market
Cosmetics & Skincare
Detox Face Oil Market
Cosmetics & Skincare
Anti-Pollution Skin Care Products Market
Cosmetics & Skincare
Organic Soaps Market
Cosmetics & Skincare
UK Lip Care Products Market
Cosmetics & Skincare
Face Bronzer Market
Cosmetics & Skincare
Nail Polish Market
Cosmetics & Skincare
J-Beauty Products Market
Cosmetics & Skincare
Tinted Cosmetics Market
Cosmetics & Skincare
Private Label Cosmetics Manufacturing Service Market
Cosmetics & Skincare
Italy Lip Care Products Market
Cosmetics & Skincare
Makeup Remover Pen Market