
 E Commerce Cosmetic and Fragrance Market | 2026-2036
E Commerce Cosmetic and Fragrance Market Size, Share, and Industry Trends Forecast 2026-2036
E Commerce Cosmetic and Fragrance Market Intelligence
ISO 22716 compliance for Good Manufacturing Practices in cosmetics is reorganizing the supply chain for online brands, setting new benchmarks for quality and safety. L'Oréal leverages its extensive portfolio of established brands to dominate multiple online marketplaces. Estée Lauder differentiates through its focus on luxury skincare and fragrance, targeting high-value customer segments on its direct-to-consumer websites. Sephora operates as a key multi-brand retail channel, curating both established and indie brands for a wide consumer base.
E-commerce for cosmetic and fragrance products involves the digital retail of skincare, makeup, scents, and haircare through online platforms. This channel relies on high-resolution product imaging, detailed ingredient lists, and customer review data to replicate the in-store discovery process. The Skincare product type continues to command the largest share, driven by a focus on wellness and preventative care. Within brand equity, Indie Brands are growing rapidly, utilizing social media channels to build direct relationships with eco-conscious consumers.
Regulatory frameworks such as the US FDA's guidelines on cosmetic labeling and the EU's Cosmetics Regulation (EC 1223/2009) dictate ingredient safety and marketing claims. In China, the NMPA's stringent registration requirements for imported cosmetics shape market access for international brands. Navigating divergent data privacy laws, like GDPR in Europe, while delivering hyper-personalized customer experiences remains the central challenge for online retailers.
Market Dynamics
The central tension shaping the market is the dual demand for hyper-personalized digital experiences and stringent data privacy. This conflict forces brands to navigate complex regulations like GDPR while leveraging AI and customer data to replicate in-store discovery online.
Growth Catalysts
- AI-Powered Personalization:The integration of artificial intelligence for virtual try-on applications and personalized skincare recommendations enhances user engagement and conversion rates, directly addressing a key barrier to online cosmetic sales.
- Sustainable and Clean Beauty:Demand from eco-conscious consumers for products with transparent, ethically sourced ingredients and sustainable packaging is a major growth vector, with digital channels being an effective medium for communicating this value.
- Social Commerce Expansion:The rapid adoption of social media and influencer-led commerce platforms, particularly in high-growth markets like India and China, creates new, direct-to-consumer sales channels that bypass traditional retail infrastructure.
Market Restraints
- Sensory Experience Gap:E-commerce platforms cannot replicate the tactile and olfactory experience of testing fragrances and cosmetics, which can lead to consumer hesitation, purchase friction, and higher product return rates.
- Regulatory Fragmentation:Divergent and stringent regulatory frameworks, such as China's NMPA registration for imported cosmetics, create significant compliance costs and market access delays for brands operating across multiple geographies.
- Counterfeit Product Proliferation:The prevalence of counterfeit goods on major third-party online marketplaces erodes brand equity, poses safety risks to consumers, and requires constant investment in brand protection and legal action.
Strategic Opportunities
- Subscription Box Models:Curated subscription services offer a channel for discovery and recurring revenue, allowing brands to gather valuable consumer preference data for future product development and hyper-personalization efforts.
- Men's Grooming Segment:The male skincare and fragrance category remains relatively underpenetrated in many markets, presenting a significant opportunity for brands to develop targeted digital marketing campaigns and product lines.
- Niche Marketplace Development:Creating or partnering with specialized online platforms focused on specific consumer values, such as vegan, cruelty-free, or halal-certified products, allows brands to target high-intent customer segments effectively.
Industry Challenges
- Data Privacy Compliance:Managing customer data for personalization across jurisdictions with conflicting privacy laws, such as Europe's GDPR and various US state-level regulations, presents a significant legal and operational challenge.
- Reverse Logistics Management:Handling returns for cosmetic and fragrance products is complex and costly due to hygiene regulations that often prevent resale, leading to increased waste and financial losses for online retailers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E Commerce Cosmetic and Fragrance Market |
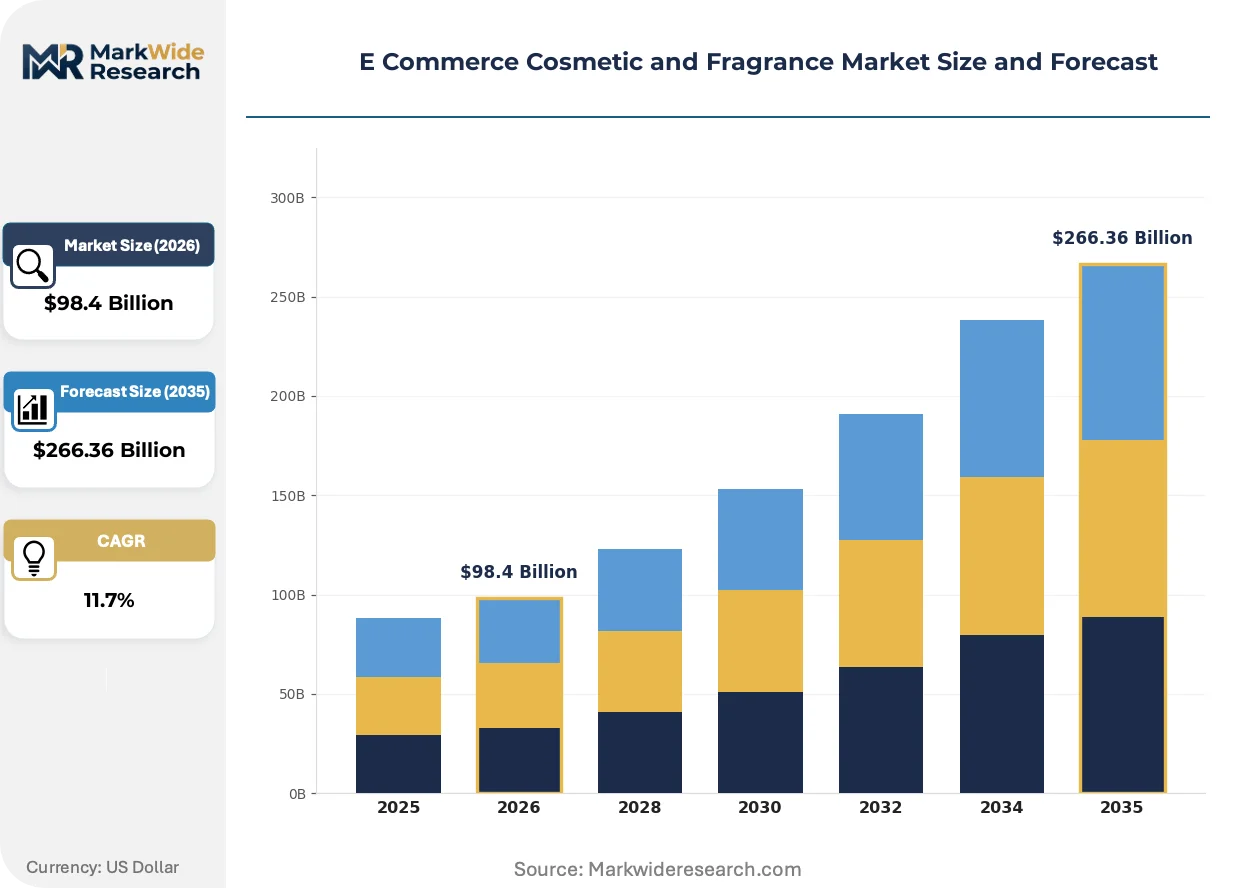
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $266.36 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Makeup, Fragrance, Haircare Distribution Channel: Online Marketplace, Brand Website, Social Media, Affiliate Sites Customer Type: Luxury Buyers, Budget Shoppers, Eco-conscious Consumers, Occasion-based Buyers Brand Equity: Established Brands, Indie Brands, Celebrity Brands, Private Labels |
| Companies Covered | L'Oréal, Estée Lauder, Procter & Gamble, Unilever, Coty, Shiseido, Revlon, Avon, Sephora, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E Commerce Cosmetic and Fragrance Market Strategic Shifts & Innovations
The market's evolution is defined by the convergence of technology-driven personalization and consumer demands for ethical transparency. Innovations focus on building digital trust and replicating the sensory aspects of physical retail, while regulatory pressures enforce higher standards for safety and marketing claims.
AI-driven skin diagnostic tools use smartphone cameras and proprietary algorithms to provide personalized skincare analysis. These tools are being rapidly adopted by direct-to-consumer brands and integrated into their mobile applications to guide purchasing decisions. This technology is miniaturizing the role of in-person consultations, embedding dermatological-style recommendations directly into the digital point of sale.
The EU's Cosmetics Regulation (EC 1223/2009) establishes strict requirements for product safety assessments and the substantiation of marketing claims. This framework forces brands to invest heavily in R&D and documentation, influencing product formulation and marketing strategies globally. Skincare brands making performance or "free-from" claims are most affected, using digital channels to provide the required ingredient transparency.
A significant behavioral shift is the rise of "dupe culture," where consumers use social media to find and share lower-cost alternatives to luxury products. This trend disrupts traditional brand loyalty, with platforms like TikTok serving as primary discovery channels that bypass brand-controlled marketing. The phenomenon is most visible among younger consumers in North America and Europe, pressuring premium brands to justify their value proposition.
E Commerce Cosmetic and Fragrance Market Segmentation
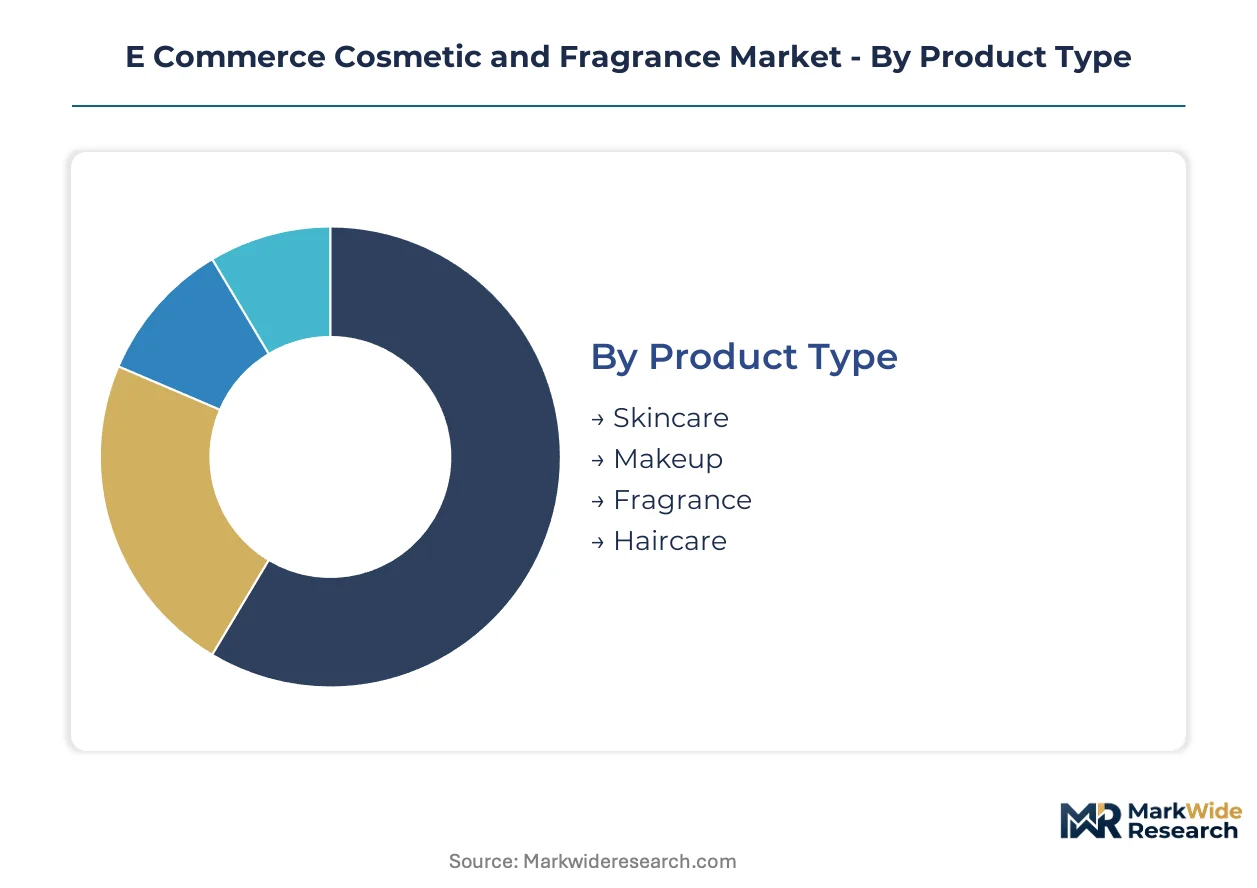
Segmentation within the e-commerce cosmetic and fragrance market illuminates critical distinctions in product appeal, distribution efficacy, customer behavior, and brand influence. Understanding these divisions helps brands tailor digital strategies, optimize inventory, and engage specific consumer cohorts effectively.
Product Type:
The diverse product types within the e-commerce cosmetic and fragrance market exhibit varied channel dependencies, with some categories thriving on multi-brand platforms while others leverage direct-to-consumer websites for niche appeal.
- Skincare:This category encompasses a wide array of products including cleansers, moisturizers, serums, and sunscreens, designed for facial and body care. Demand for skincare products is concentrating in Asian markets like China and India, driven by wellness trends and preventative care focus.
- Makeup:Makeup products include foundations, concealers, mascaras, lipsticks, and eyeshadows, used to enhance or alter facial appearance. Online demand for makeup products is strong in North America, with virtual try-on technology boosting conversion rates.
- Fragrance:This segment comprises perfumes, colognes, and body mists, offering distinct scents for personal use. Fragrance brands often leverage immersive digital content and subscription models to overcome the sensory experience gap.
- Haircare:Haircare products include shampoos, conditioners, treatments, and styling aids, addressing various hair concerns. Digital platforms provide detailed ingredient lists and customer reviews for informed haircare purchases.
Skincare products dominate the installed base. Fragrance is where expansion concentrates.
Distribution Channel:
Different distribution channels cater to distinct customer types, influencing purchasing behavior and brand interaction across the digital landscape.
- Online Marketplace:These are multi-brand platforms like Amazon and Sephora, offering a vast selection from various brands. Online marketplaces capture broad consumer segments, with extensive product reviews influencing purchase decisions.
- Brand Website:Direct-to-consumer (DTC) websites are owned and operated by individual cosmetic and fragrance brands. Brand websites enable direct customer relationships and offer exclusive products, particularly for luxury segments.
- Social Media:Platforms such as Instagram and TikTok facilitate social commerce, allowing users to discover and purchase products directly through influencer content. Social media channels are particularly effective for reaching younger, eco-conscious consumers.
- Affiliate Sites:These platforms drive traffic to e-commerce stores through product reviews, recommendations, and sponsored content. Affiliate sites generate significant leads for niche and emerging brands by building trust through third-party endorsements.
Online Marketplaces capture the largest transaction volume. Brand Websites demonstrate the highest average order value.
Customer Type:
Customer segmentation directly correlates with varying margin profiles, as specific buyer groups prioritize either premium experiences or cost-efficiency in their online cosmetic purchases.
- Eco-conscious Consumers:These buyers prioritize products with sustainable packaging, ethically sourced ingredients, and cruelty-free certifications. Eco-conscious consumers actively seek transparency and align with brands demonstrating strong environmental and social governance.
- Luxury Buyers:This segment seeks high-end, premium cosmetic and fragrance products, often from established brands, valuing exclusivity and sophisticated formulations. Luxury buyers are increasingly engaging with direct-to-consumer platforms for personalized experiences and bespoke offerings.
- Budget Shoppers:Price-sensitive consumers who seek affordable cosmetic and fragrance options, often comparing prices across various online retailers. Budget shoppers frequently utilize online marketplaces and look for promotions or private label alternatives.
- Occasion-based Buyers:Consumers who purchase specific cosmetic or fragrance items for particular events, such as weddings, holidays, or gifts. Occasion-based buyers often respond to targeted seasonal campaigns and curated product sets.
Luxury Buyers command premium pricing. Eco-conscious Consumers represent the fastest-growing trajectory.
Brand Equity:
Brand equity categories reveal distinct supply concentration patterns, with established players leveraging extensive manufacturing networks while indie brands rely on agile, often outsourced, production.
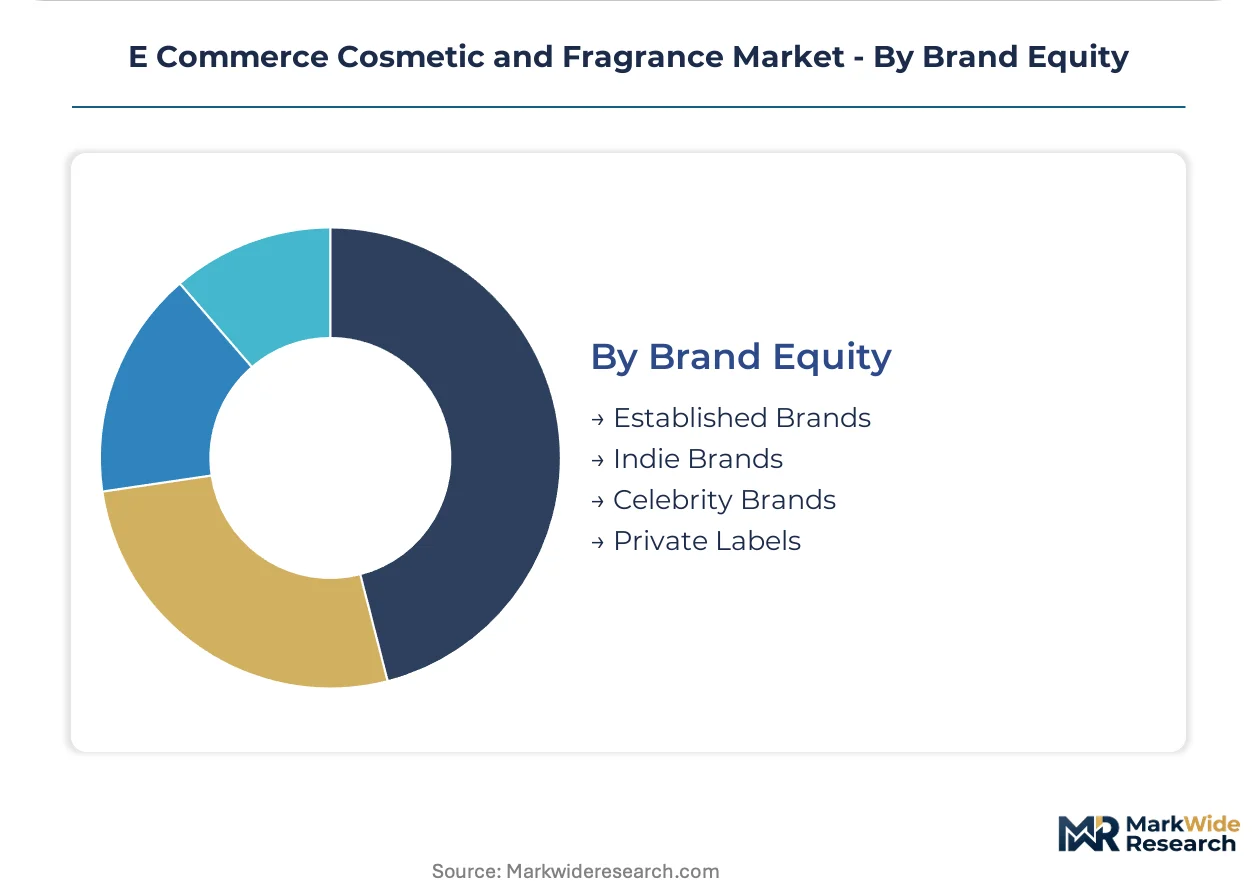
- Indie Brands:These are independent, often smaller brands known for unique formulations, ethical sourcing, and strong community engagement. Indie brands leverage social media extensively to build direct relationships with consumers and bypass traditional advertising costs.
- Established Brands:Large, well-known brands with a long history and significant market presence, often part of major beauty conglomerates. Established brands dominate online marketplaces and invest heavily in AI-powered personalization tools to maintain customer loyalty.
- Celebrity Brands:Brands launched or endorsed by public figures, leveraging their personal brand and social media reach to drive sales. Celebrity brands often achieve rapid market entry and significant initial sales volumes due to their founder's influence.
- Private Labels:Products manufactured by a third party but sold under a retailer's own brand name, typically offering a more cost-effective alternative. Private labels provide retailers with higher margins and control over product specifications and branding.
Established Brands maintain significant market share. Indie Brands are rapidly gaining traction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU's Cosmetics Regulation (EC 1223/2009) establishes a high bar for product safety and marketing claims, influencing product formulation and digital communication strategies across Europe. This regulatory environment fosters trust, encouraging consumer engagement with online cosmetic and fragrance purchases. Digital channels provide the necessary transparency for ingredient lists and ethical sourcing, aligning with consumer values.
China
Demand from digitally native consumers for personalized skincare solutions and luxury fragrances drives e-commerce growth in China. The NMPA's stringent registration requirements for imported cosmetics shape market access for international brands. Shanghai and Guangzhou host significant digital innovation hubs, where brands develop AI-powered virtual try-on applications for the local market.
India
Government initiatives promoting digital payments and internet penetration support the expansion of online cosmetic and fragrance sales in India. The Bureau of Indian Standards (BIS) formulates guidelines for cosmetic product quality and safety, impacting local manufacturing and import standards. Bengaluru and Mumbai are emerging as key centers for e-commerce logistics and digital marketing for beauty brands.
United States
Consumer demand for clean beauty products and direct-to-consumer experiences fuels the online cosmetic and fragrance market in the United States. The US FDA's guidelines on cosmetic labeling and ingredient safety provide a framework for product transparency. New York City and Los Angeles remain hubs for brand innovation and digital marketing strategies, catering to diverse consumer preferences.
France
Luxury buyers seeking exclusive fragrance and skincare products drive premium online sales in France. The Agence Nationale de Sécurité du Médicament et des produits de santé (ANSM) enforces strict regulations on cosmetic product composition and claims. Paris, as a global fashion and beauty capital, concentrates e-commerce platforms specializing in high-end beauty offerings.
Germany
Eco-conscious consumers in Germany prioritize sustainable packaging and ethically sourced ingredients, boosting demand for transparent online brands. The German Federal Office of Consumer Protection and Food Safety (BVL) oversees cosmetic product safety and compliance with EU regulations. Berlin and Hamburg are developing as centers for indie beauty brands, leveraging digital channels to reach their target audience.
E Commerce Cosmetic and Fragrance Market Key Industry Players
Player mix skews toward established brands leveraging extensive portfolios, complemented by a growing cohort of agile indie brands. The market structure is moderately concentrated at the top, with a fragmented base of specialized niche players. Strategic archetypes include global conglomerates, direct-to-consumer specialists, and multi-brand retailers. Dominant competitive moves include strategic partnerships for technology integration and portfolio diversification into high-growth segments.
Established market leaders, such as L'Oréal and Estée Lauder, exemplify the power of brand equity and extensive distribution networks. These companies leverage their global reach and invest in AI-powered personalization tools to maintain customer loyalty across online marketplaces. Sephora, acting as a key multi-brand retail channel, occupies a position that curates both established and indie brands, catering to a wide consumer base seeking discovery and variety.
| Leading Market Players |
|---|
| L'Oréal |
| Estée Lauder |
| Procter & Gamble |
| Unilever |
| Coty |
| Shiseido |
| Revlon |
| Avon |
| Sephora |
| Others |
Cost & Logistics Intelligence
Large-scale formulation and packaging operations drive cost efficiencies, influencing supply concentration among established brands. These efficiencies subsequently set competitive price floors for mass-market product categories.
Pricing Analysis
ISO 22716 compliance for Good Manufacturing Practices creates the primary price spread across cosmetic product lines. Pricing stratifies across premium, standard, and economy tiers, driven by brand equity and specialized ingredient sourcing, alongside advanced formulation R&D. Pricing pressure stems from the proliferation of private labels and "dupe culture" on social media platforms. Budget shoppers exhibit the highest price sensitivity, while luxury buyers prioritize product efficacy and brand prestige.
Supply Chain Analysis
Stringent NMPA registration processes in China underwrite market access for imported cosmetic ingredients and finished goods. Supply concentration for active ingredients draws from specialized chemical manufacturers in Europe and East Asia. Key dependencies include high-grade botanical extracts and synthetic compounds, alongside sustainable packaging materials. Regulatory fragmentation across global markets represents a structural risk, while distribution runs through a mix of online marketplaces and brand websites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The e-commerce cosmetic and fragrance market presents a defensive moat, underpinned by significant regulatory entrenchment for product safety. This structural advantage creates high barriers to entry for new formulations and imported goods.
For Market Incumbents: Shield core brand equity by investing in AI-powered personalization tools to enhance customer loyalty. Pursue strategic partnerships for technology integration, particularly in virtual try-on and skin diagnostics, to counter the sensory experience gap. This defends against indie brand disruption and maintains premium pricing power. Channel control through direct-to-consumer websites remains a critical lever.
For New Entrants and Emerging Players: Lead with niche marketplace development, targeting specific consumer values such as vegan or halal-certified products. Leverage social commerce expansion, particularly on platforms like TikTok, to build direct relationships with eco-conscious consumers. The men's grooming segment remains a highly penetrable category in many markets. An effective go-to-market angle involves influencer-led content demonstrating product transparency and ethical sourcing.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among subscription box models and luxury direct-to-consumer brands with strong customer retention. The market offers long-term viability, driven by sustained demand for wellness and preventative care products. Target acquisition archetypes include agile indie brands with strong social media presence and proprietary clean beauty formulations. The signal to watch is the continued growth in AI-powered diagnostic tool adoption rates, indicating deeper digital integration.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch (AI-powered skin diagnostic tools) | Integrates technology for personalized recommendations, enhancing online discovery for skincare. |
| Direct-to-Consumer Launch (Luxury fragrance line) | Captures high-value customer segments through exclusive online experiences and bespoke offerings. |
| Strategic Partnership (Social commerce platform) | Expands reach into high-growth markets like India and China via influencer-led sales channels. |
| Sustainability Repositioning (Packaging/Ingredients) | Addresses eco-conscious consumer demand for transparent, ethically sourced beauty products. |
| Portfolio Diversification (Men's Grooming) | Taps into an underpenetrated market segment with targeted digital marketing campaigns and product lines. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, company reports, and academic literature. Interviews engaged brand managers, e-commerce platform executives, supply chain specialists, and digital marketing leads. Data collection utilized both bottom-up market sizing and top-down validation. Secondary sources included industry association publications, trade journals, and customs import/export data.
Product type, distribution channel, customer type, and brand equity formed the core segmentation dimensions modeled across the analysis window. Compound annual growth rates were derived from historical data analysis and projected future demand trends. Key forecast inputs included internet penetration rates and consumer disposable income growth in emerging markets, alongside regulatory shifts.
Forecasts assume regulatory continuity in EU and NMPA regimes; material policy shifts would require re-modeling. Projections reflect current market dynamics; supply chain disruptions or privacy law changes could alter outcomes. Practitioners should keep alternative scenarios live as data privacy regulations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Global Cosmetic Jar Market
Cosmetics & Skincare
Facial Serum Market
Cosmetics & Skincare
Asia-Pacific Cosmetics Market
Cosmetics & Skincare
Lipstick Market
Cosmetics & Skincare
Organic Soaps Market
Cosmetics & Skincare
Europe Bath Soap Market
Cosmetics & Skincare
Eye Cream Market
Cosmetics & Skincare
South America Cosmetics Products Market
Cosmetics & Skincare
Moisturizing Spray Market
Cosmetics & Skincare
Chile Cosmetics Products Market
Cosmetics & Skincare
Japan Bath Soap Market
Cosmetics & Skincare
Microbiome Cosmetic Products Market
Cosmetics & Skincare
Scalp Scrub Market
Cosmetics & Skincare
Bangladesh Face Wash Market
Cosmetics & Skincare
Eye Makeup Market
Cosmetics & Skincare
Bath Soap Market