
 Cosmetics Private Label and Contract Manufacturing Market | 2026-2036
Cosmetics Private Label and Contract Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmetics Private Label and Contract Manufacturing Market Insights
The gap between premium formulation complexity and commodity cost engineering is restructuring procurement strategies across the sector. Kolmar Laboratories leverages advanced emulsion technology to anchor high-margin skincare partnerships with prestige brands. SBLC Cosmetics sustains its position through specialized haircare manufacturing for European retailers. Cosmetic Solutions differentiates via turnkey branding services that compress time-to-market for emerging labels.
Cosmetics private label and contract manufacturing encompasses third-party production of finished beauty products where the contracting brand owns the marketing identity while the manufacturer controls formulation chemistry, stability testing, and filling operations. Processes span cold-process emulsification for sensitive actives to hot-melt compounding for color cosmetics, with batch sizes ranging from pilot-scale 50-liter runs to industrial 10,000-liter tanks. Skincare commands the largest formulation service margin pool due to complex active ingredient sourcing and stability validation requirements. Haircare represents the fastest-growing product type as scalp-health positioning drives novel surfactant chemistry. Packaging services concentrate value in airless pump and sustainable mono-material formats where equipment amortization creates barriers.
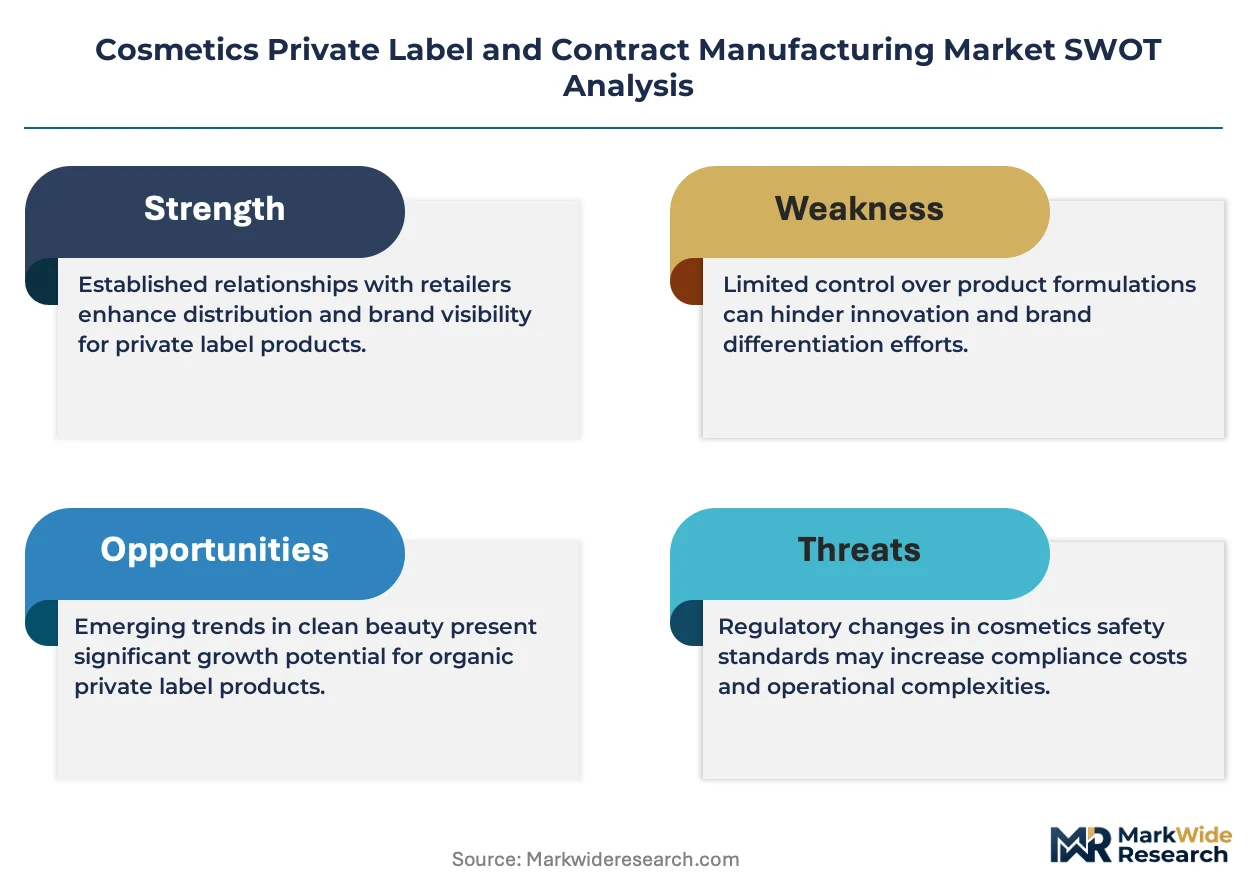
The U.S. FDA enforces MoCRA facility registration and serious adverse event reporting, while the EU enforces REACH chemical safety and animal testing prohibitions through ECHA. These frameworks elevate compliance costs that favor contract manufacturers with dedicated regulatory affairs teams over in-house brand laboratories. Stakeholders must monitor emerging state-level ingredient bans in California and New York that fragment formulation standardization.
Market Dynamics
Clean beauty startups are accelerating outsourcing partnerships as MoCRA facility registration and EU ingredient disclosure mandates compress in-house laboratory viability. This regulatory compression is restructuring procurement strategies across the sector.
Growth Catalysts
- MoCRA Facility Registration:The U.S. FDA mandate elevates compliance costs that favor contract manufacturers with dedicated regulatory affairs teams over brand laboratories.
- Cold-Process Emulsification:Advanced stabilization technology for sensitive actives enables premium skincare partnerships with higher formulation service margins.
- Seoul-Incheon Corridor:South Korea's manufacturing cluster concentrates K-beauty export capacity and novel surfactant chemistry for scalp-health positioning.
Market Restraints
- Active Ingredient Volatility:Peptide and botanical extract sourcing costs fluctuate with climate-driven agricultural yields and biotech fermentation capacity constraints.
- Equipment Amortization Barriers:Airless pump and mono-material packaging lines require capital deployment that locks out mid-scale entrants.
- REACH Compliance Friction:ECHA chemical safety documentation creates formulation standardization delays for brands seeking EU market access.
Strategic Opportunities
- Turnkey Branding Services:Compressed time-to-market offerings for emerging labels capture value from digital-native brand proliferation.
- Scalp-Health Positioning:Novel surfactant chemistry in haircare represents the fastest-growing product type by formulation service demand.
- California Ingredient Bans:State-level prohibitions on PFAS and formaldehyde-releasing preservatives create premium reformulation service demand.
Industry Challenges
- Regulatory Affairs Talent Scarcity:MoCRA adverse event reporting and REACH dossier preparation require specialized expertise in short supply.
- Pilot-to-Industrial Scale Transfer:Stability validation failures between 50-liter pilot runs and 10,000-liter commercial batches destroy batch economics.
- Cross-Border Formulation Fragmentation:Diverging state-level ingredient bans in New York and California complicate SKU rationalization for national brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmetics Private Label and Contract Manufacturing Market |
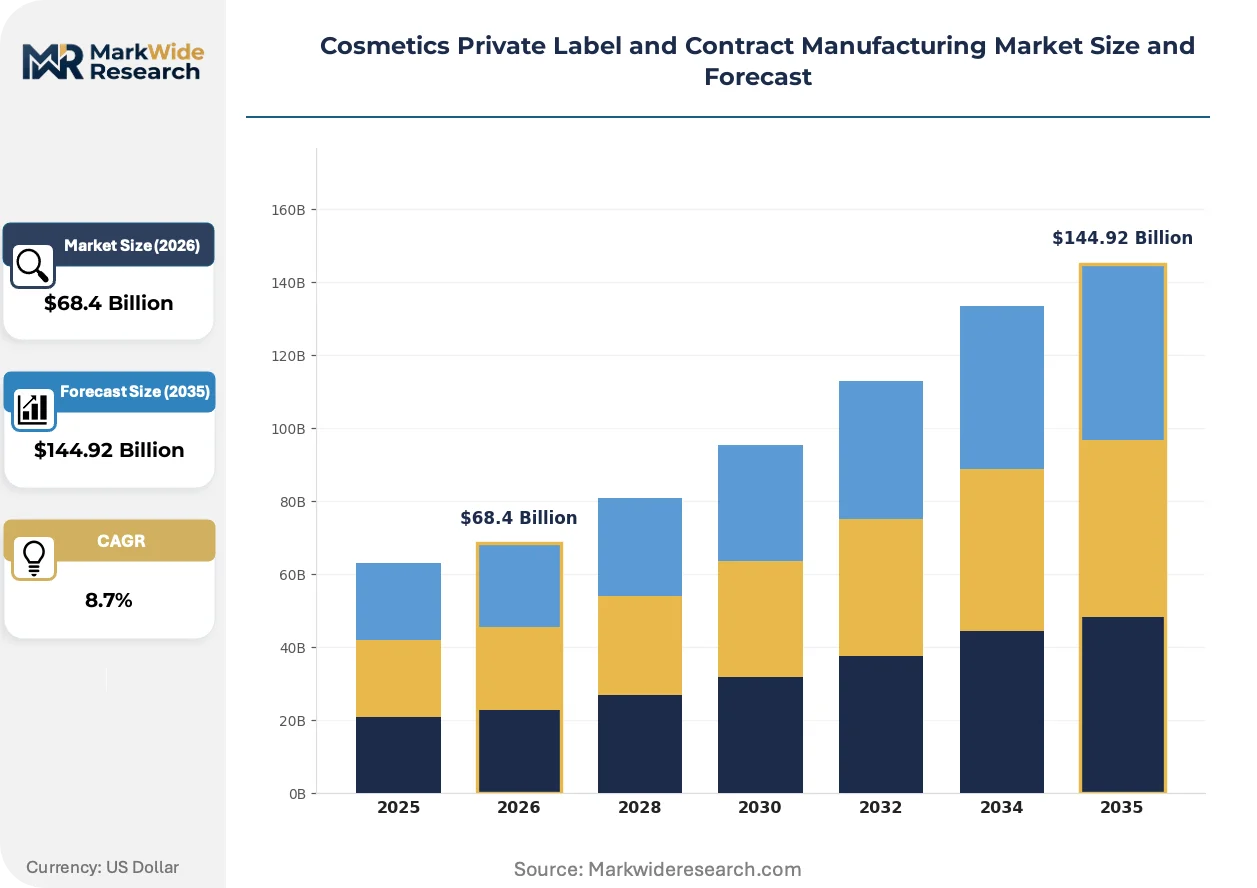
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Makeup, Haircare, Fragrance Service Type: Formulation, Packaging, Branding, Quality Control Distribution Channel: Online Retail, Brick-and-Mortar, Wholesalers, Direct Sales Customer Type: Small Businesses, Large Enterprises, Startups, E-commerce |
| Companies Covered | NOESIS, COSMECO, SBLC Cosmetics, Cosmetic Solutions, SystemKosmetik, Cosmewax, CarasaLab, Kolmar Laboratories, Elchemy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmetics Private Label and Contract Manufacturing Market Trends and Innovations
Biotechnology-derived actives and sustainable packaging formats are compressing traditional chemical synthesis and multi-component packaging. These shifts are restructuring manufacturer capability requirements and capital allocation priorities.
Biotechnology platforms including precision fermentation and enzymatic synthesis are absorbing demand from conventional petrochemical-derived emollients and preservatives. Prestige skincare brands are adopting these inputs at accelerated pace to meet clean beauty positioning requirements. This absorption is compressing margins for commodity chemical suppliers while elevating formulation complexity premiums for contract manufacturers with bioprocessing partnerships.
REACH chemical safety expansion through ECHA is tightening documentation requirements for fragrance allergens and endocrine-disrupting compounds. Manufacturers must now submit extended safety dossiers for existing formulations, extending product development timelines. European prestige brands are responding by consolidating supplier bases to reduce compliance fragmentation.
Direct-to-consumer brand incubators are compressing traditional wholesale distribution cycles for contract manufacturing clients. Small-batch digital-native labels now demand 50-liter pilot runs with 4-week turnaround, displacing the 12-week norms of retail-centric production. This compression is most visible in South Korea's Seoul-Incheon corridor, where K-beauty export manufacturers have reconfigured filling lines for micro-batch flexibility.
Cosmetics Private Label and Contract Manufacturing Market Segmentation
Procurement patterns in cosmetics contract manufacturing diverge sharply across formulation complexity, regulatory burden, and batch scale requirements. Buyers select manufacturing partners based on whether they prioritize speed-to-shelf, premium positioning, or compliance-heavy export markets.
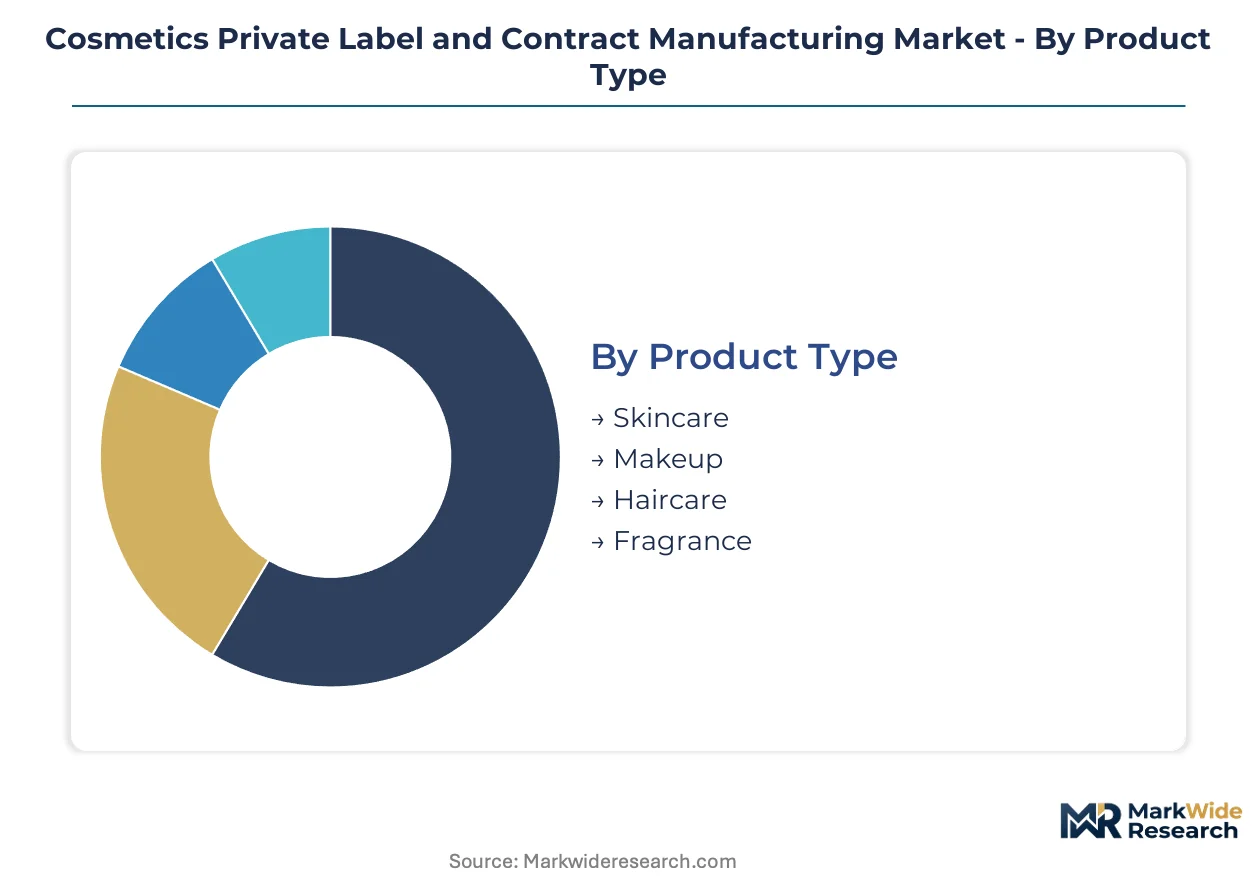
Product Type:
Margin capture and technical barrier intensity separate buyers across these four categories, with formulation sophistication driving partnership selection criteria.
- Skincare:Cold-process emulsification and active ingredient stabilization command the highest formulation service premiums. Demand concentrates with prestige brands in South Korea's Seoul-Incheon corridor, where biotech-derived peptide sourcing and stability validation create partnership stickiness.
- Haircare:Novel surfactant chemistry for scalp-health positioning absorbs the fastest-expanding R&D investment from contract manufacturers. European retailers are consolidating supplier relationships around specialized haircare manufacturers who can document REACH-compliant preservative systems.
- Makeup:Hot-melt compounding for color cosmetics requires pigment dispersion expertise and filling line flexibility for seasonal SKU proliferation.
- Fragrance:ECHA fragrance allergen documentation and IFRA compliance create regulatory friction that favors manufacturers with dedicated toxicology dossier teams.
Volume sits with skincare; growth tilts toward haircare.
Service Type:
Capital deployment intensity and talent scarcity define competitive differentiation among service providers, with regulatory capabilities becoming the scarcest resource.
- Formulation:Biotechnology platform partnerships for precision fermentation-derived actives separate premium manufacturers from commodity compounders. MoCRA adverse event reporting requirements and REACH dossier preparation demand specialized regulatory affairs talent that concentrates in established manufacturing clusters.
- Packaging:Airless pump and mono-material sustainable format lines require equipment amortization that locks out mid-scale entrants. South Korean manufacturers lead in micro-batch flexibility reconfiguration for direct-to-consumer brand incubators.
- Branding:Turnkey services compress time-to-market for digital-native labels through compressed 4-week turnaround norms versus traditional 12-week retail cycles.
- Quality Control:Stability validation between pilot-scale and industrial batches represents the critical failure point where batch economics collapse.
Revenue concentrates in formulation; capability gaps widen fastest in quality control.
Distribution Channel:
Order frequency and batch size economics restructure manufacturer line configurations, with channel selection determining capital recovery timelines.
- Online Retail:Direct-to-consumer velocity demands 50-liter pilot runs with rapid formulation iteration. K-beauty export manufacturers have reconfigured filling lines specifically for micro-batch flexibility to serve this channel.
- Brick-and-Mortar:Traditional retail-centric production maintains 12-week norms and 10,000-liter tank economies, favoring manufacturers with stable long-term brand partnerships.
- Wholesalers:Volume aggregation enables standard formulation runs with lower per-unit service premiums but requires inventory financing capabilities.
- Direct Sales:Relationship-driven channel with customized formulation exclusivity and white-label confidentiality agreements.
Capacity utilization peaks with brick-and-mortar; reconfiguration investment flows toward online retail.
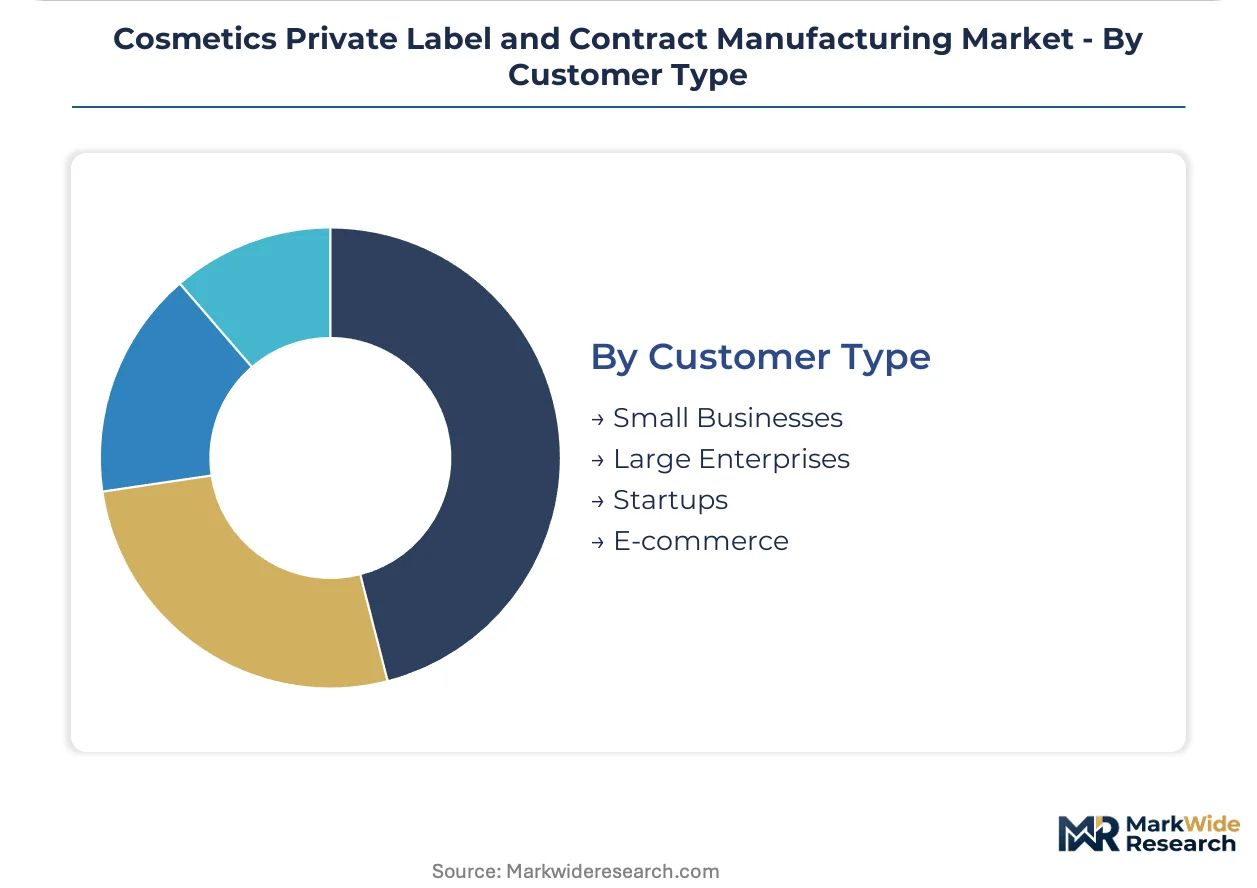
Customer Type:
Regulatory sophistication and capital access determine service tier matching, with compliance burden creating natural segmentation between self-serve and white-glove onboarding.
- Startups:Clean beauty entrants accelerating outsourcing partnerships as MoCRA facility registration compresses in-house laboratory viability. California and New York state-level ingredient bans fragment their formulation standardization needs.
- Small Businesses:Limited regulatory affairs capacity drives preference for manufacturers with bundled compliance services and turnkey documentation packages.
- Large Enterprises:Consolidated supplier bases reduce REACH compliance fragmentation through preferred partnership structures with dedicated account toxicologists.
- E-commerce:Digital-native labels demanding compressed turnaround with minimal order minimums, prioritizing flexibility over unit cost optimization.
Transaction volume clusters with large enterprises; expansion rates are steepest among startups.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Seoul-Incheon manufacturing corridor anchors formulation capacity for K-beauty export growth. Regulatory divergence between the US FDA's MoCRA framework and the EU's REACH expansion is fragmenting production strategies across major manufacturing clusters.
United States
MoCRA facility registration mandates compress in-house laboratory viability for clean beauty startups. The FDA's adverse event reporting requirements elevate compliance costs that favor contract manufacturers with dedicated regulatory affairs teams. New Jersey and California concentrate formulation capacity, with Los Angeles-based manufacturers specializing in turnkey branding services for digital-native labels.
South Korea
K-beauty export demand drives novel surfactant chemistry investment for scalp-health positioning. The MFDS maintains stringent cosmetic safety standards that validate stability testing capabilities. Seoul-Incheon corridor manufacturers have reconfigured filling lines for micro-batch flexibility to serve direct-to-consumer brand incubators.
Germany
European prestige brands consolidate supplier bases to reduce REACH compliance fragmentation. ECHA's fragrance allergen documentation requirements favor manufacturers with dedicated toxicology dossier teams. North Rhine-Westphalia hosts specialized haircare manufacturers serving retailer private label programs.
France
ANSM enforces cosmetic product safety reporting alongside EU-wide ECHA chemical safety obligations. The country's fragrance heritage concentrates expertise in allergen documentation and IFRA compliance. Île-de-France manufacturers capture premium formulation service margins through biotechnology-derived active partnerships.
India
CDSCO cosmetic registration requirements create entry barriers that favor established contract manufacturers with regulatory affairs capacity. Mumbai and Gujarat industrial corridors absorb demand from domestic brand proliferation and export-oriented production. BIS standards alignment enables formulation standardization for brands seeking multi-market access.
Cosmetics Private Label and Contract Manufacturing Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and regulatory capability tiers. The sector exhibits tiered concentration where established clusters absorb compliance-heavy contracts while mid-scale entrants compete on turnaround speed. Three archetypes dominate: biotechnology-integrated formulators, regulatory-specialized full-service manufacturers, and micro-batch flexible producers. Capacity expansion and strategic partnerships with bioprocessing platforms represent the dominant competitive moves.
Within the biotechnology-integrated tier, Kolmar Laboratories exemplifies premium positioning through advanced emulsion technology partnerships. SBLC Cosmetics and Cosmetic Solutions occupy distinct specialization positions, with the former representing European haircare manufacturing concentration and the latter exemplifying turnkey branding service compression of time-to-market cycles. These three anchors illustrate how geographic clustering and service tier differentiation structure procurement decisions for brand clients.
| Leading Market Players |
|---|
| NOESIS |
| COSMECO |
| SBLC Cosmetics |
| Cosmetic Solutions |
| SystemKosmetik |
| Cosmewax |
| CarasaLab |
| Kolmar Laboratories |
| Elchemy |
| Others |
Pricing and Supply Chain Analysis
Biotechnology-derived peptide sourcing costs cascade through formulation service tiers, with cold-process emulsification capabilities commanding premium pricing from prestige skincare brands while commodity compounders absorb margin compression from climate-driven agricultural yield volatility.
Pricing Analysis
Formulation complexity premiums anchor value-based pricing, with cold-process emulsification and active ingredient stabilization separating premium manufacturers from commodity operators. Price differentiation hinges on REACH dossier preparation capabilities and MoCRA adverse event reporting infrastructure, with regulatory-specialized manufacturers capturing margin premiums. Pricing pressure stems from equipment amortization barriers for airless pump and mono-material packaging lines, squeezing mid-scale entrants. Startup buyers exhibit highest price sensitivity, prioritizing turnkey speed over unit cost, while large enterprises accept premium pricing for consolidated compliance services.
Supply Chain Analysis
Regional distribution centers in South Korea's Seoul-Incheon corridor, Germany's North Rhine-Westphalia, and New Jersey-California clusters orchestrate hub-and-spoke patterns for formulation inputs and finished goods. Supply concentration draws from biotech fermentation capacity in South Korea, surfactant chemistry expertise in Germany, and turnkey branding infrastructure in California. Raw material dependencies center on peptide extracts, botanical actives, and sustainable mono-material packaging substrates. Single-source vulnerability in precision fermentation capacity creates supply chain risk. Distribution runs through direct-to-consumer micro-batch channels and traditional retail wholesale networks in parallel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where MoCRA facility registration and REACH dossier requirements erect barrier-to-entry moats favoring established manufacturers with dedicated regulatory affairs teams.
For Market Incumbents: Hedge against startup-driven margin compression by deepening biotechnology platform partnerships for precision fermentation-derived actives. Consolidate supplier relationships around Seoul-Incheon and North Rhine-Westphalia clusters to reduce REACH compliance fragmentation. Invest in micro-batch filling line reconfiguration to capture direct-to-consumer velocity without sacrificing brick-and-mortar economies.
For New Entrants and Emerging Players: Capture white-space in California and New York state-level ingredient ban compliance services, where fragmented formulation standardization creates premium reformulation demand. Target scalp-health positioning in haircare, the fastest-growing product type by formulation service demand. Pursue turnkey branding partnerships with digital-native labels seeking compressed 4-week turnaround cycles.
For Investors and Strategic Acquirers: Distressed-cycle entries favor regulatory-specialized full-service manufacturers with dedicated toxicology dossier teams in European manufacturing clusters. Long-term viability across the projection horizon rests on biotechnology-integrated formulators with stable prestige brand partnerships. Watch for inflection signals in MFDS enforcement tightening and ECHA fragrance allergen documentation expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Biotechnology Platform Partnership | Precision fermentation capacity anchors premium skincare formulation margins for prestige brand partnerships. |
| Micro-Batch Line Reconfiguration | Seoul-Incheon manufacturers capture direct-to-consumer velocity through 50-liter pilot run flexibility. |
| Regulatory Affairs Talent Acquisition | MoCRA adverse event reporting and REACH dossier expertise concentrates in established manufacturing clusters. |
| Turnkey Branding Service Expansion | Compressed time-to-market offerings capture value from digital-native clean beauty label proliferation. |
| Sustainable Packaging Format Investment | Airless pump and mono-material lines create equipment amortization barriers locking out mid-scale entrants. |
Research Methodology
Multi-period observation of formulation service margins, batch scale economics, and regulatory compliance cost trajectories anchored the trend analysis, supplemented by interviews with contract manufacturing executives, regulatory affairs directors, prestige brand procurement leads, and clean beauty startup founders. Secondary validation drew from FDA MoCRA facility registration databases, ECHA REACH dossier filings, MFDS cosmetic safety standards, and customs trade data for biotechnology-derived active ingredient flows. Bottom-up triangulation across manufacturer capacity disclosures and top-down reconciliation against segment revenue pools structured the analytical framework.
Segment-weighting approaches distributed value estimates across skincare, haircare, makeup, and fragrance product types, with further disaggregation by formulation, packaging, branding, and quality control service tiers. Distribution channel splits between online retail, brick-and-mortar, wholesale, and direct sales informed batch size and turnaround assumptions throughout the modeling period. CAGRs derived from regression analysis of historical procurement patterns and forward-looking regulatory cost imposition curves, with biotechnology adoption rates and state-level ingredient ban proliferation as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA chemical safety expansion timing, climate-driven agricultural yield volatility for botanical extracts, and fragmentation of state-level ingredient bans beyond California and New York. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
South America Cosmetics Products Market
Cosmetics & Skincare
Face Cream Market
Cosmetics & Skincare
GCC Bath Soap Market
Cosmetics & Skincare
Cosmetic Pencil and Pen Market
Cosmetics & Skincare
Cosmetic Mirror Market
Cosmetics & Skincare
Botanical Skin Care Ingredients Market
Cosmetics & Skincare
Cosmetics OEM and ODM Services Market
Cosmetics & Skincare
Eye Shadow Market
Cosmetics & Skincare
Natural Cosmetic Color Market
Cosmetics & Skincare
Magnetic Fake Eyelashes Market
Cosmetics & Skincare
Organic Bar Soap Market
Cosmetics & Skincare
Probiotic Skin Care Cosmetic Product Market
Cosmetics & Skincare
Herbal Soap Market
Cosmetics & Skincare
Global Cosmetic Applicator Foam Market
Cosmetics & Skincare
Tea Based Face Masks Market
Cosmetics & Skincare
Asia-Pacific Halal Cosmetics Market