
 Lip Products Pigment Market | 2026-2036
Lip Products Pigment Market Size, Share, and Industry Trends Forecast 2026-2036
Lip Products Pigment Market Insights
Aftermarket service revenue from color-matching and formulation consulting is narrowing as raw material suppliers build direct technical support capabilities. Sun Chemical Corporation leverages its integrated pigment and dispersion portfolio to capture formulation partnerships with cosmetic manufacturers. Sensient Cosmetic Technologies sustains competitive positioning through specialized effect pigments for metallic and iridescent lip finishes. Merck KGaA anchors premium segment supply with pearlescent pigment technology developed for high-end cosmetic brands.
Lip products pigment comprises colorants, pearlescent agents, and functional fillers engineered for adherence to mucosal tissue, lightfastness exceeding 4 on the Blue Wool Scale, and particle sizes typically between 5 and 25 microns for smooth application. These materials serve the primary commercial purpose of delivering stable, safe coloration across varying pH environments in cosmetic formulations. Liquid lipstick and lip gloss applications command the dominant volume share as consumers prioritize transfer-resistant wear and dimensional shine effects. Synthetic and mineral ingredient sources retain structural importance due to batch-to-batch consistency and cost scalability, though natural and organic alternatives attract margin premiums in clean beauty positioning. Matte texture formulations lead volume demand while satin and glossy finishes capture faster growth in Asian markets.
REACH registration requirements in Europe and FDA color additive regulations in the United States enforce heavy metal limits and purity certifications that shape supplier qualification processes and testing expenditure. ECHA substance evaluations and EPA chemical data reporting obligations further constrain formulation flexibility for imported pigment blends. BIS certification requirements in India and China's GB standards for cosmetic raw materials add national compliance layers that fragment market access protocols. Stakeholders must monitor evolving regulatory convergence between EU and Asian cosmetic ingredient standards to anticipate reformulation costs and qualification timelines.
Market Dynamics
Prestige cosmetic brands are consolidating pigment sourcing around vertically integrated suppliers capable of delivering REACH-compliant, batch-consistent colorants for long-wear lip formulations.
Growth Catalysts
- Liquid lipstick demand:Transfer-resistant formulations now dominate premium cosmetic portfolios, pulling specialized pigment dispersions with enhanced mucosal adherence properties.
- REACH enforcement:ECHA substance evaluations are disqualifying non-compliant suppliers, concentrating qualified vendor pools and locking in technical partnerships for compliant manufacturers.
- China beauty consumption:Premium lip color adoption in tier-one cities is accelerating demand for pearlescent and metallic effect pigments engineered for dimensional shine.
Market Restraints
- Titanium dioxide volatility:Mineral-based white pigment input costs fluctuate with ore concentrate availability, compressing margin predictability for matte formulation suppliers.
- Supplier concentration:Effect pigment synthesis capabilities cluster among German and Japanese specialty chemical houses, creating single-source vulnerability for iridescent finish lines.
- Heavy metal testing burden:FDA color additive certification requires extensive lot-level arsenic and lead screening, adding fixed compliance overhead that disadvantages smaller pigment blenders.
Strategic Opportunities
- Clean beauty positioning:Organic-certified colorant demand in North American prestige retail channels creates pricing power for natural-extraction pigment portfolios.
- South Korea K-beauty export:Gradient lip tint formulations are driving specialized microsphere encapsulation technology for controlled color release.
- GB standards alignment:China's cosmetic raw material regulations are converging with EU purity benchmarks, enabling unified formulation platforms across both markets.
Industry Challenges
- Color chemist scarcity:Formulation expertise spanning pigment dispersion rheology and regulatory toxicology remains concentrated among veteran specialists with limited training pipeline throughput.
- Dual certification timelines:Parallel FDA and ECHA qualification processes for new color additives extend commercialization cycles by eighteen to twenty-four months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lip Products Pigment Market |
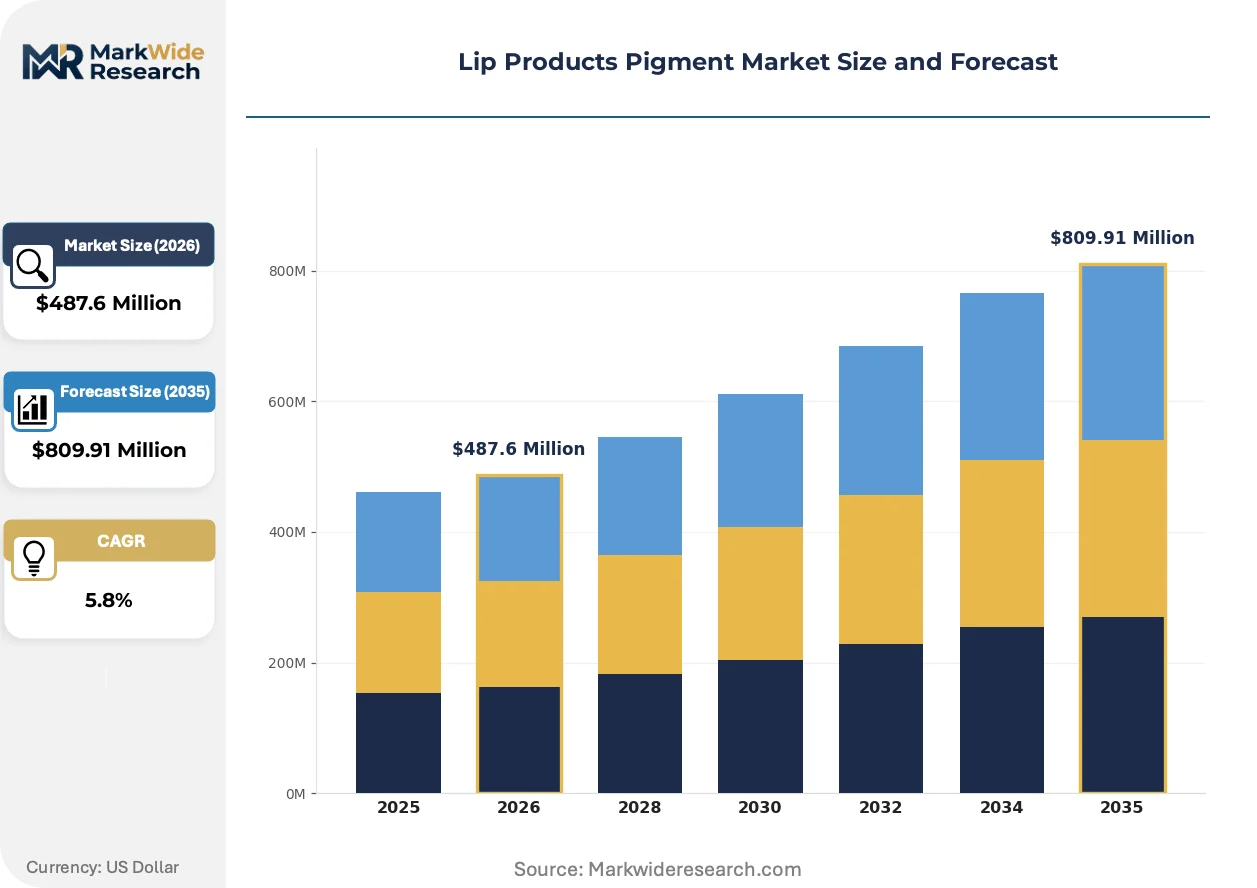
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Lipstick, Lip Gloss, Lip Balm, Lip Liner Application: Cosmetic Use, Medical Treatment, Skin Care, Personal Care Texture: Matte, Glossy, Satin, Sheer Ingredient Source: Natural, Synthetic, Organic, Mineral |
| Companies Covered | Sun Chemical Corporation, Sensient Cosmetic Technologies, Merck KGaA, BASF SE, ECKART GmbH, Sudarshan Chemical Industries Limited, Kobo Products Inc., Clariant AG, LANXESS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lip Products Pigment Market Trends and Innovations
Formulation science is converging with digital color-matching platforms to compress development cycles for seasonal lip color collections while tightening purity specifications.
Encapsulated pigment technology is hybridizing mineral core particles with organic polymer shells to achieve time-released color deposition in long-wear liquid lipsticks. Prestige cosmetic laboratories in South Korea and the United States are adopting these systems at accelerated pilot scales. This architecture is hybridizing traditional pigmentation with skincare-active delivery mechanisms, opening adjacent revenue streams in treatment-color hybrid products.
REACH authorization requirements for synthetic organic pigments are tightening impurity thresholds and mandating extended environmental fate studies. ECHA substance evaluations now demand full analytical profiles for trace contaminants previously exempt from disclosure. Color additive suppliers serving European cosmetic manufacturers are responding by consolidating production in ISO-certified facilities with captive analytical capabilities.
Direct-to-brand technical service models are displacing traditional distributor-mediated pigment procurement in mid-tier cosmetic houses. Raw material suppliers now embed formulation chemists within customer R&D teams, collapsing development iteration cycles. This pattern is most visible in California and Shenzhen, where speed-to-market for influencer-collaboration lip collections dictates sourcing relationships.
Lip Products Pigment Market Segmentation
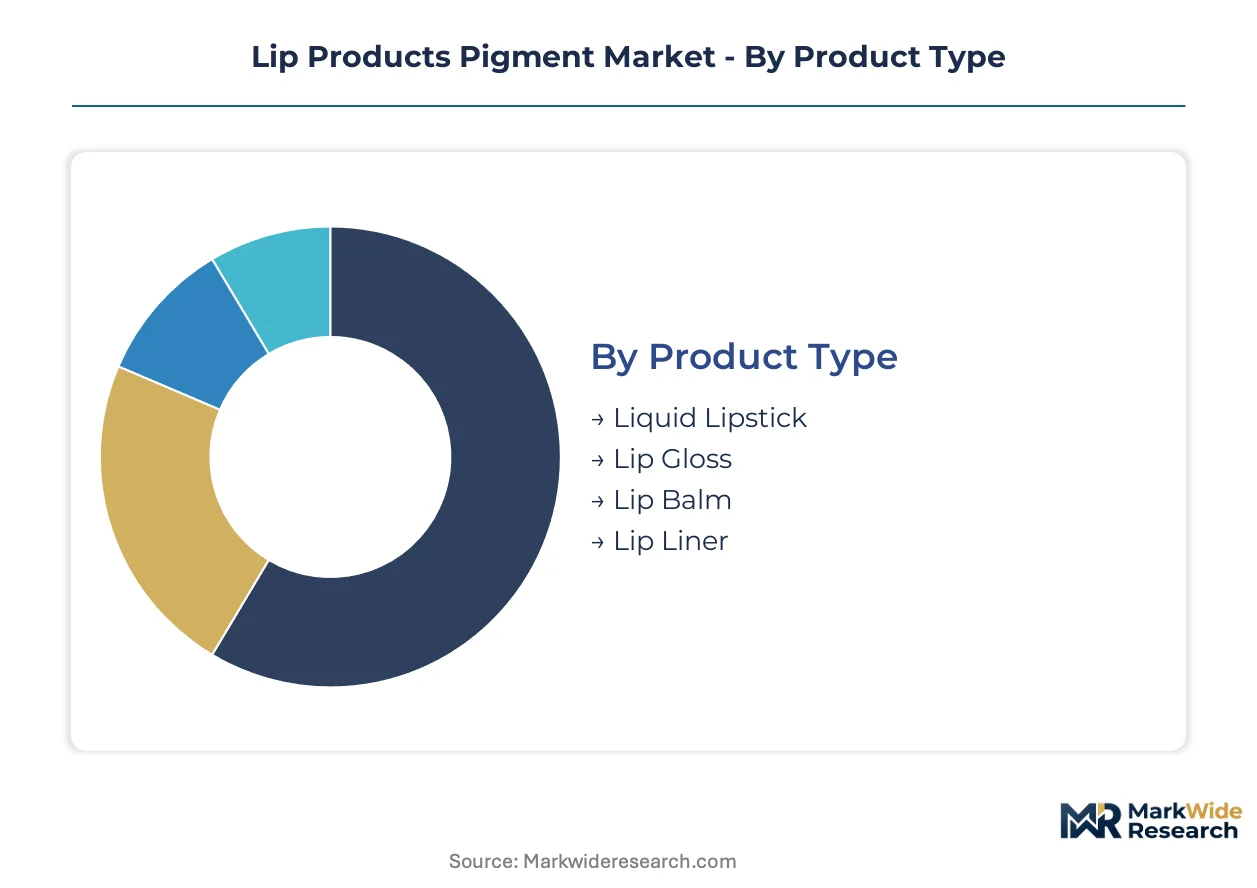
Pigment specification varies sharply across lip product formats, with transfer-resistance demands in liquid formulations driving specialized dispersion chemistry distinct from the emollient-compatible colorants required in balms. Texture and ingredient positioning further bifurcate supplier portfolios between performance-engineered synthetics and certification-dependent naturals.
Product Type:
Application format dictates pigment loading levels, dispersion rheology, and adherence chemistry required for mucosal tissue compatibility.
- Liquid Lipstick:High-pigment dispersions with film-forming polymers dominate this segment, engineered for transfer-resistant wear exceeding eight hours. Demand concentrates in United States prestige channels and South Korea's K-beauty export market, driven by influencer-collaboration collection velocity requiring rapid color-matching turnaround.
- Lip Gloss:Lower pigment concentrations combined with pearlescent and iridescent effect agents create dimensional shine. China tier-one cities anchor volume demand as consumers prioritize glossy finishes compatible with gradient lip tint techniques.
- Lip Balm:Emollient-compatible mineral pigments with reduced tinting strength serve functional moisturization positioning. Natural and organic certification requirements in North American clean beauty retail constrain supplier pools.
- Lip Liner:Precision application demands higher wax-compatible pigment loadings with enhanced edge definition. Long-wear formulation partnerships between pigment suppliers and pencil manufacturers concentrate technical service resources.
Liquid lipstick commands the established base. The steepest expansion runs through lip gloss as Asian markets elevate shine-focused aesthetics.
Application:
End-use context shapes regulatory burden, performance specification, and pricing architecture across pigment procurement decisions.
- Cosmetic Use:FDA color additive certification and REACH registration requirements enforce heavy metal screening protocols. Volume concentrates in prestige brand portfolios where batch-to-batch color consistency justifies premium pigment sourcing.
- Medical Treatment:Post-procedural camouflage and therapeutic coloration require hypoallergenic pigment grades with documented biocompatibility. United States dermatology channel demand is expanding for scar-concealment lip formulations.
- Skin Care:Treatment-color hybrids incorporate encapsulated pigments with active ingredient compatibility. South Korean laboratories lead pilot-scale adoption of time-release color deposition systems.
- Personal Care:Mass-market tinting applications prioritize cost-scalable synthetic colorants with basic lightfastness properties. Private-label manufacturing concentration in Shenzhen and Los Angeles drives procurement consolidation.
Cosmetic use retains the dominant revenue position. Medical treatment applications are gaining share fastest as post-aesthetic procedure protocols expand.
Texture:
Surface finish determines pigment particle size distribution, filler loading, and optical modifier requirements.
- Matte:Titanium dioxide and silica-loaded formulations achieve flat light absorption with enhanced oil-absorption capacity. United States prestige retail channels anchor demand as consumers prioritize non-transferring, mask-compatible wear.
- Glossy:Pearlescent mica substrates and synthetic fluorphlogopite create reflective dimension. China and South Korea dominate consumption as glossy finishes align with regional aesthetic preferences for hydrated lip appearance.
- Satin:Balanced pigment-filler ratios deliver moderate light reflection with comfortable wear. European formulation houses favor this texture for age-inclusive product positioning.
- Sheer:Reduced pigment loading with enhanced transparency enables natural lip tone enhancement. Clean beauty positioning in California and New York drives natural-origin colorant demand.
Matte texture holds the volume base. Glossy finishes are climbing the fastest as Asian consumption patterns influence global formulation trends.
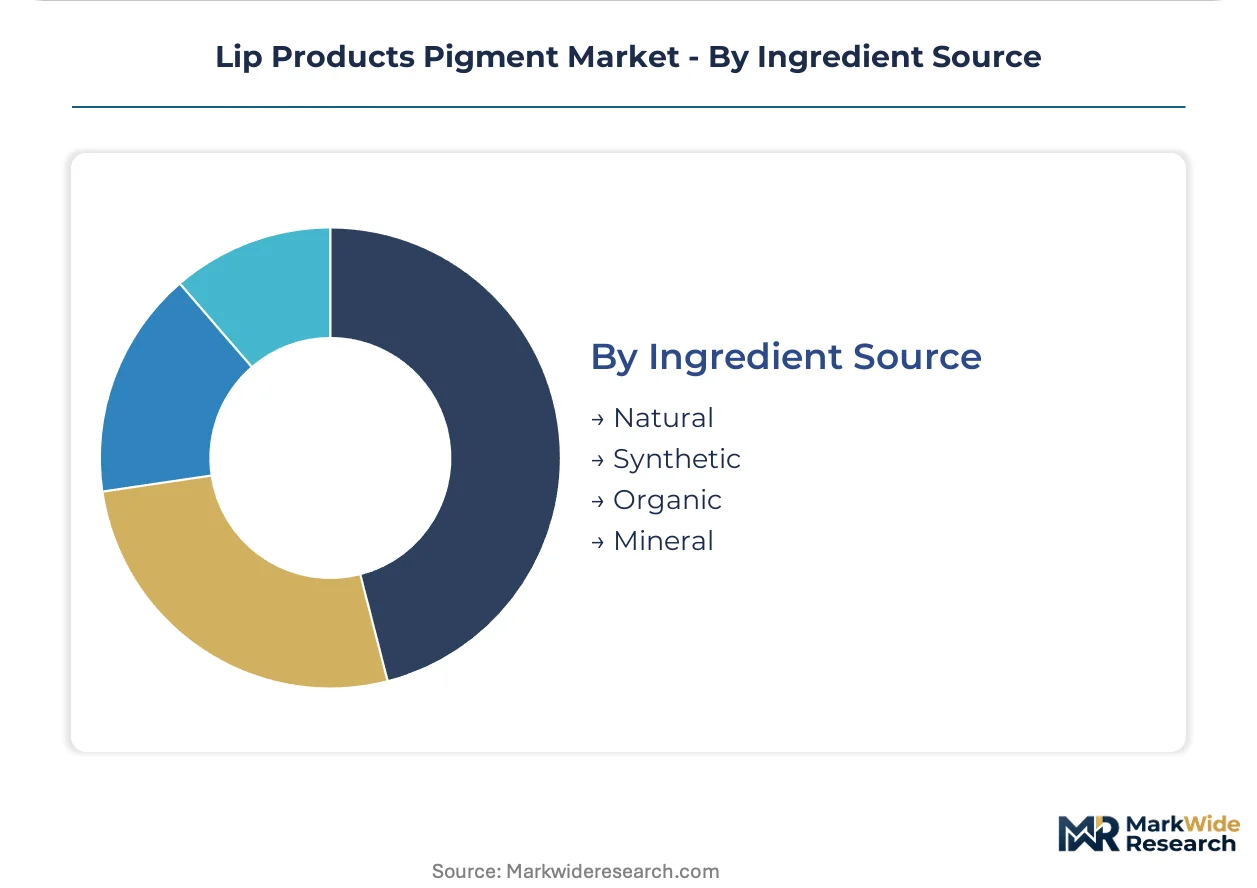
Ingredient Source:
Raw material provenance determines certification pathways, supply security, and margin architecture for pigment portfolios.
- Synthetic:Batch-consistent organic pigments including D&C and FD&C colorants deliver predictable performance at scale. REACH authorization tightening is extending environmental fate study requirements for new molecular introductions.
- Mineral:Iron oxides, titanium dioxide, and mica-based substrates provide lightfastness exceeding Blue Wool Scale 4. Ore concentrate availability fluctuations compress margin predictability for white pigment-dependent formulations.
- Natural:Plant-derived and mineral-extracted colorants with organic certification attract premium positioning. FDA certification bottlenecks and batch variability constrain commercial scalability.
- Organic:Certified-organic agricultural sourcing meets North American clean beauty retail requirements. Supply concentration among limited qualified extraction facilities creates procurement competition.
Synthetic and mineral sources command the established base. Organic-certified alternatives are expanding most quickly as prestige retail channels elevate clean formulation positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across consumption centers. Prestige buyers in tier-one Chinese cities absorb premium pearlescent formulations, while mass-market procurement in India prioritizes cost-scalable mineral pigments.
United States
FDA color additive certification demands drive supplier consolidation around REACH-compliant manufacturers. California's clean beauty retail channels anchor organic-certified pigment demand. Los Angeles-based formulation houses embed supplier chemists directly into R&D teams, compressing development cycles for influencer-collaboration collections.
China
GB standards for cosmetic raw materials are converging with EU purity benchmarks, enabling unified formulation platforms. Shanghai and Shenzhen clusters concentrate private-label manufacturing for both domestic prestige brands and export-oriented K-beauty suppliers. SAMR enforcement of heavy metal limits is disqualifying regional pigment blenders without captive analytical capabilities.
South Korea
Gradient lip tint formulations from Seoul-based laboratories are pulling specialized microsphere encapsulation technology for controlled color release. MFDS cosmetic ingredient regulations enforce batch-level documentation that favors vertically integrated suppliers. Busan-Ulsan chemical complexes house effect pigment synthesis operations serving K-beauty export markets.
Germany
ECHA substance evaluations under REACH authorization are extending environmental fate study requirements for new organic pigment introductions. Specialty chemical houses in Ludwigshafen and Frankfurt clusters concentrate pearlescent and iridescent effect pigment capabilities. German suppliers leverage ISO-certified facilities with captive analytical capabilities to lock in technical partnerships with cosmetic manufacturers.
India
BIS certification requirements for cosmetic raw materials add national compliance layers that fragment market access protocols. Maharashtra and Gujarat industrial corridors concentrate synthetic organic pigment production for domestic mass-market lip color manufacturers. Cost-sensitive procurement patterns favor mineral-based colorants with basic lightfastness properties over premium effect pigments.
Lip Products Pigment Market Competitive Landscape
Integrated pigment-dispersion suppliers and specialized effect pigment houses split the market between scale-driven commoditized colorants and premium iridescent formulations. Three strategic archetypes dominate: multinational chemical conglomerates with captive cosmetic divisions, mid-cap specialty pigment houses with regional regulatory expertise, and natural-extraction specialists serving clean beauty certification requirements. Competitive positioning hardens around backward integration into mineral ore processing and direct-to-brand technical service models that displace traditional distributor channels.
Among the integrated multinational tier, Sun Chemical Corporation and BASF SE occupy positions anchored by broad pigment and dispersion portfolios. Sensient Cosmetic Technologies and Merck KGaA exemplify the specialized effect pigment archetype, with the latter representing premium pearlescent technology positioning. Kobo Products Inc. sits within the mid-cap specialty segment focused on cosmetic-grade mineral substrates. These named entities illustrate how supplier qualification around REACH and FDA compliance is concentrating procurement relationships among qualified vendor pools.
| Leading Market Players |
|---|
| Sun Chemical Corporation |
| Sensient Cosmetic Technologies |
| Merck KGaA |
| BASF SE |
| ECKART GmbH |
| Sudarshan Chemical Industries Limited |
| Kobo Products Inc. |
| Clariant AG |
| LANXESS |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese titanium dioxide processing facilities is compressing white pigment margins and forcing suppliers toward specialty effect pigment portfolios to defend pricing power. This utilization imbalance concentrates bargaining leverage among German and Japanese pearlescent pigment houses while pushing mineral-based suppliers into cost-absorption strategies.
Pricing Analysis
Aftermarket technical service revenue from color-matching and formulation consulting is narrowing as raw material suppliers build direct technical support capabilities. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified pearlescent pigments from FDA-registered synthetics and uncertified mineral blends. Cost compression in standard-grade mineral pigments is intensifying because ore concentrate availability fluctuates with mining output cycles. Mass-market private-label manufacturers in Shenzhen and Los Angeles exhibit highest price sensitivity, while prestige cosmetic houses in Seoul and New York absorb premiums for encapsulated microsphere technology.
Supply Chain Analysis
Contract manufacturing concentration among Busan-Ulsan chemical complexes and Ludwigshafen specialty pigment houses anchors effect pigment synthesis capacity. Geographic supply concentrates in Germany, South Korea, and China for pearlescent substrates, synthetic organic pigments, and mineral ore processing respectively. Raw material dependencies draw from titanium dioxide ore concentrates, mica substrates, and petroleum-derived organic intermediates. Single-source vulnerability for iridescent fluorphlogopite synthesis creates supply chain risk. Distribution runs through direct-to-brand technical service models that displace traditional distributor channels in California and Shenzhen formulation clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Natural-extraction colorants and organic-certified alternatives present a substitution threat that synthetic pigment incumbents must navigate through certification investment and clean beauty portfolio expansion.
For Market Incumbents: Insulate formulation partnerships by embedding technical chemists within customer R&D teams, collapsing development cycles for influencer-collaboration collections. Captive analytical capabilities in ISO-certified facilities defend against ECHA substance evaluation disqualification. Backward integration into mineral ore processing secures titanium dioxide supply against concentrate availability volatility. For New Entrants and Emerging Players: Pursue organic-certified pigment extraction partnerships with limited qualified agricultural sourcing facilities in North America. Gradient lip tint microsphere encapsulation for K-beauty export markets represents the most penetrable technical white space. Direct technical service models bypassing traditional distribution offer the strongest go-to-market angle for mid-tier cosmetic houses. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated suppliers with captive REACH-compliant manufacturing and embedded formulation support teams. Long-term viability rests on regulatory qualification moats that extend commercialization cycles for new color additives. Acquisition targets should demonstrate ISO-certified facilities with heavy metal screening capabilities. Watch ECHA authorization timelines for synthetic organic pigments as inflection indicators for supplier consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mineral Ore Processing | Captive titanium dioxide supply defends margin predictability against concentrate price volatility. |
| Direct-to-Brand Technical Service Deployment | Embedded formulation chemists in Los Angeles and Shenzhen compress seasonal collection development cycles. |
| Organic Certification Investment | Clean beauty positioning in California and New York retail channels commands premium pricing power. |
| Encapsulated Microsphere Capacity Expansion | Time-release color deposition technology opens adjacent revenue in treatment-color hybrid products. |
| REACH-Compliant Analytical Capability Buildout | Captive heavy metal screening locks in technical partnerships with European cosmetic manufacturers. |
Research Methodology
A standing panel of cosmetic formulation chemists, regulatory affairs specialists at pigment suppliers, prestige brand procurement directors, and contract manufacturing plant managers provided ongoing calibration across the study period. Primary interviews combined with secondary validation from FDA color additive certification databases, ECHA REACH registration filings, SAMR cosmetic raw material standards, and SEC 10-K disclosures from listed chemical suppliers. Bottom-up segment sizing triangulated against top-down industry value estimates.
Scenario-bracketing around regulatory authorization timelines and ore concentrate price cycles shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, texture finish, ingredient source certification tier, and regional regulatory cluster. CAGRs derived from volume trajectory analysis incorporating K-beauty export velocity, clean beauty retail channel expansion, and REACH compliance cost absorption. Forecast inputs encompassed batch-to-batch consistency requirements and pearlescent effect pigment adoption curves.
Macroeconomic conditions sit as an overlay; deviation in titanium dioxide ore pricing, Chinese industrial policy, or EU-Asia regulatory convergence velocity would shift the trajectory. Forecasts reflect documented assumptions around supplier qualification timelines and certification bottleneck resolution. Quarterly review of ECHA substance evaluation announcements, SAMR enforcement actions, and K-beauty export licensing data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Cosmetic Mirror Market
Cosmetics & Skincare
Temporary Tattoo Market
Cosmetics & Skincare
Organic Color Cosmetics Products Market
Cosmetics & Skincare
Reusable Makeup Remover Pad Market
Cosmetics & Skincare
Japan Organic Cosmetics Market
Cosmetics & Skincare
Eyeliner Market
Cosmetics & Skincare
Silicone Makeup Sponge Market
Cosmetics & Skincare
Snail Beauty Products Market
Cosmetics & Skincare
Myanmar Skin Care Products Market
Cosmetics & Skincare
Eye Makeup Market
Cosmetics & Skincare
Cosmetics OEM and ODM Services Market
Cosmetics & Skincare
Herbal Soap Market
Cosmetics & Skincare
Sweden Cosmetics Products Market
Cosmetics & Skincare
Cosmetics ODM Market
Cosmetics & Skincare
Cosmetic Pencil and Pen Market
Cosmetics & Skincare
Waterproof Eyebrow Liner Market