
 UK Lip Care Products Market | 2026-2036
UK Lip Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
UK Lip Care Products Market Intelligence
UK contract manufacturers is broadening production capacity for petroleum-free and beeswax-based formulations. Burt's Bees leverages its heritage in natural ingredient sourcing to anchor premium positioning across British health and beauty retailers. L'Oreal SA competes through sustained R&D investment in barrier-repair lip technologies. Unilever PLC differentiates via mass-market distribution control through its Boots and Superdrug partnerships.
Lip care products comprise topical preparations designed to protect, moisturize, or color the labial skin, typically formulated with occlusive agents such as petrolatum, plant-derived waxes, or ceramides at concentrations between 15% and 40% to prevent transepidermal water loss. These products serve both therapeutic and cosmetic functions across consumer and professional channels. Lip balm occupies the mature volume base, while lip scrub generates faster growth as exfoliating routines expand beyond facial skincare. Stick packaging dominates impulse and travel segments, whereas jar formats command higher margins in gifting and premium positioning.
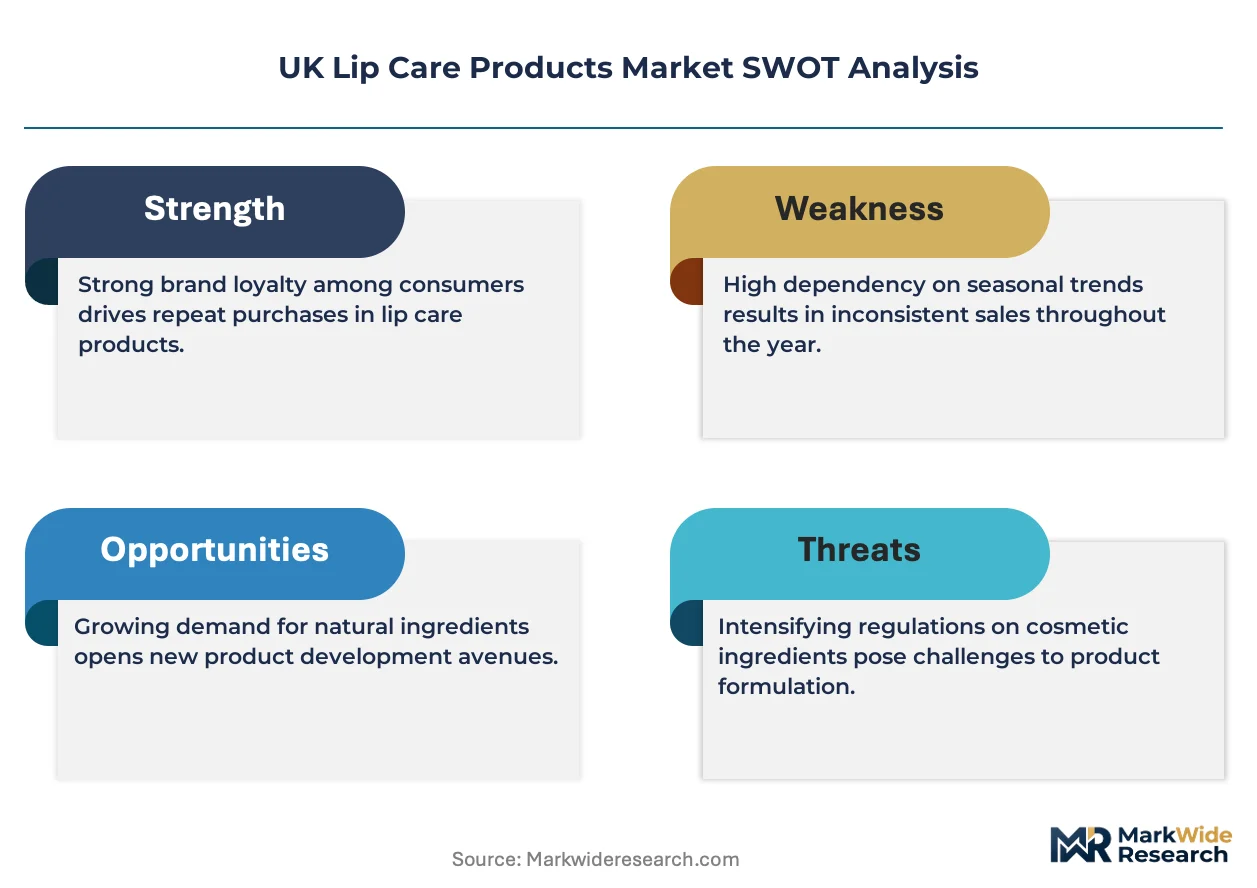
The UK Cosmetic, Toiletry and Perfumery Association guides industry compliance with the EU-derived Cosmetic Products Regulation, while Trading Standards enforces labeling accuracy and prohibited substance controls. The Office for Product Safety and Standards monitors emerging chemical concerns including fragrance allergens and persistent organic pollutants. Stakeholders must track evolving post-Brexit divergence from REACH chemical restrictions and anticipate stricter national standards on biodegradability.
Market Dynamics
The UK Environmental Protection Act's microbead prohibition has forced reformulation cycles across petroleum-based lip care portfolios, compressing supplier timelines while accelerating natural wax substitution. This regulatory pressure sits at the center of competitive repositioning among British contract manufacturers and retail buyers.
Growth Catalysts
- REACH-derived chemical restrictions:Post-Brexit divergence from EU chemical standards is creating first-mover advantages for UK brands with pre-positioned natural ingredient supply chains.
- South East England retail density:Urban pharmacy expansion in Greater London and surrounding counties concentrates premium product uptake through Boots and Superdrug flagship locations.
- Ceramide barrier-repair technologies:Clinical positioning of lip treatments is attracting dermatology channel placement and professional recommendation networks.
Market Restraints
- Beeswax supply volatility:UK apiary output fluctuations and import dependency on European wax suppliers create input cost instability for natural-formulation specialists.
- Single-use plastic packaging directives:Extended producer responsibility schemes under UK Environment Act obligations are raising compliance overhead for stick-format dominant portfolios.
- Petrolatum substitution complexity:Occlusive performance gaps in plant-derived alternatives limit full reformulation of therapeutic lip balm lines without sensory trade-offs.
Strategic Opportunities
- Scotland and Wales pharmacy penetration:Independent chemist networks outside England's South East present underdeveloped distribution for premium tinted formulations.
- Biodegradability certification pathways:Anticipated UK national standards on aquatic toxicity are creating positioning space for early-certified entrants.
- Exfoliating routine expansion:Lip scrub adoption is crossing over from facial skincare enthusiasts into mainstream beauty regimens through jar-format gifting positioning.
Industry Challenges
- Fragrance allergen labeling compliance:Trading Standards enforcement of EU-derived allergen disclosure rules requires reformulation documentation and packaging redesign cycles.
- Natural preservative system validation:Replacement of parabens with plant-derived antimicrobials demands extended stability testing timelines for shelf-life claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Lip Care Products Market |
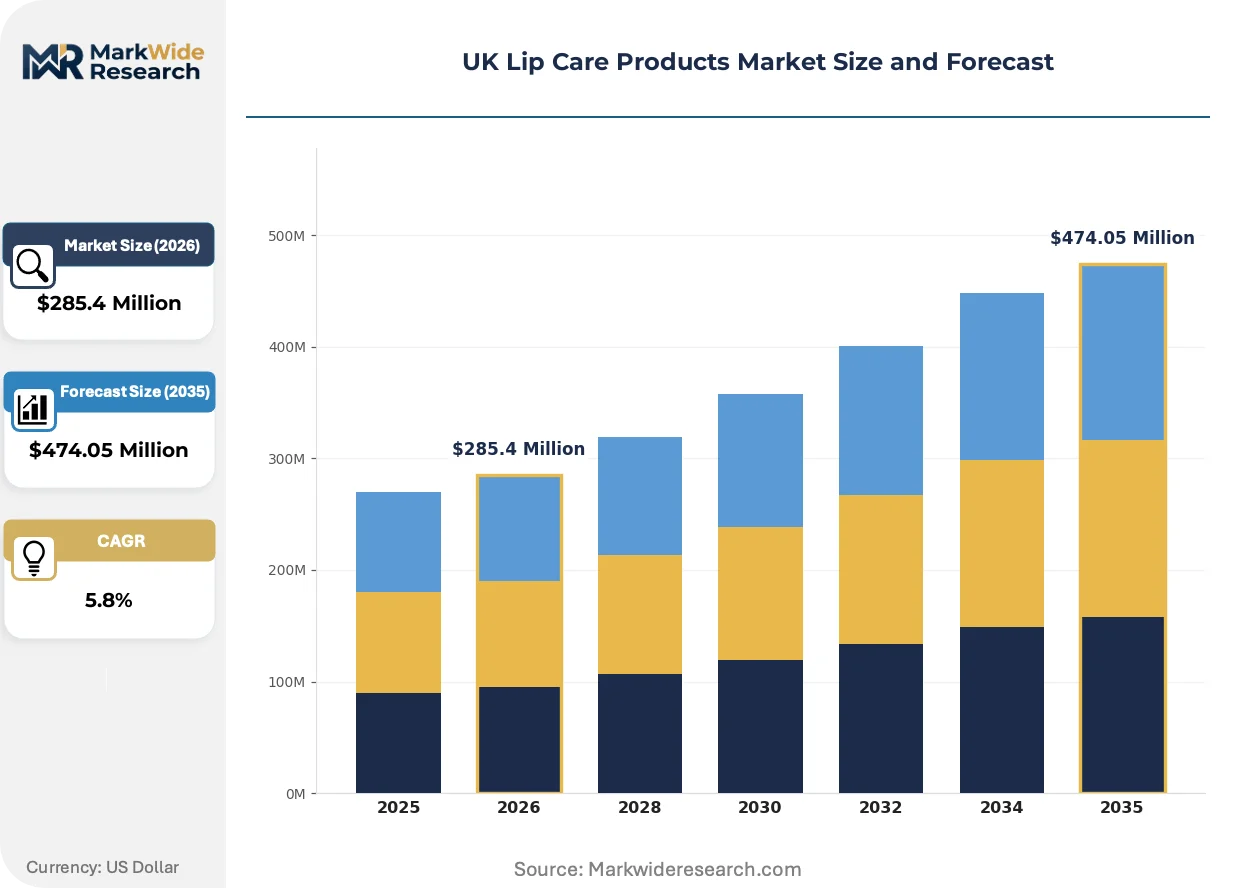
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $474.05 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lip Balm, Lip Scrub, Lip Gloss, Lipstick Application: Moisturizing, Exfoliating, Coloring, Protection End User: Women, Men, Teens, Children Packaging Type: Tub, Tube, Stick, Jar |
| Companies Covered | Colgate-Palmolive Co, Johnson & Johnson, L'Oreal SA, Revlon, Procter & Gamble Co, Unilever PLC, The Estee Lauder Companies Inc, Burt's Bees, Beiersdorf AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Lip Care Products Market Strategic Shifts & Innovations
Reformulation pressure from the UK microbead ban is cascading through ingredient sourcing, packaging design, and clinical positioning strategies. Three distinct vectors are reshaping how lip care products reach British consumers.
Plant-derived wax blends incorporating rice bran, candelilla, and sunflower seed derivatives are modularizing base formulation architectures. Mid-tier British brands are adopting these systems to bridge petroleum-free positioning with cost structures competitive against legacy petrolatum lines. This modularity is enabling rapid SKU expansion across tinted, medicated, and SPF-variant lines without full supply chain reconstruction.
The Office for Product Safety and Standards is intensifying scrutiny of persistent organic pollutants and fragrance allergens in cosmetic formulations. This monitoring activity is compressing product development timelines as manufacturers pre-emptively reformulate to avoid enforcement actions. Professional and pharmacy channels are responding by demanding batch-level traceability documentation from contract manufacturers.
Scottish and Welsh independent chemists are consolidating purchasing through regional wholesale cooperatives to match England's retail density advantages. This buyer concentration is shifting negotiation leverage toward distributors with private-label manufacturing capabilities. The pattern is most visible in Edinburgh, Glasgow, and Cardiff where pharmacy group procurement now represents a meaningful share of regional volume.
UK Lip Care Products Market Segmentation
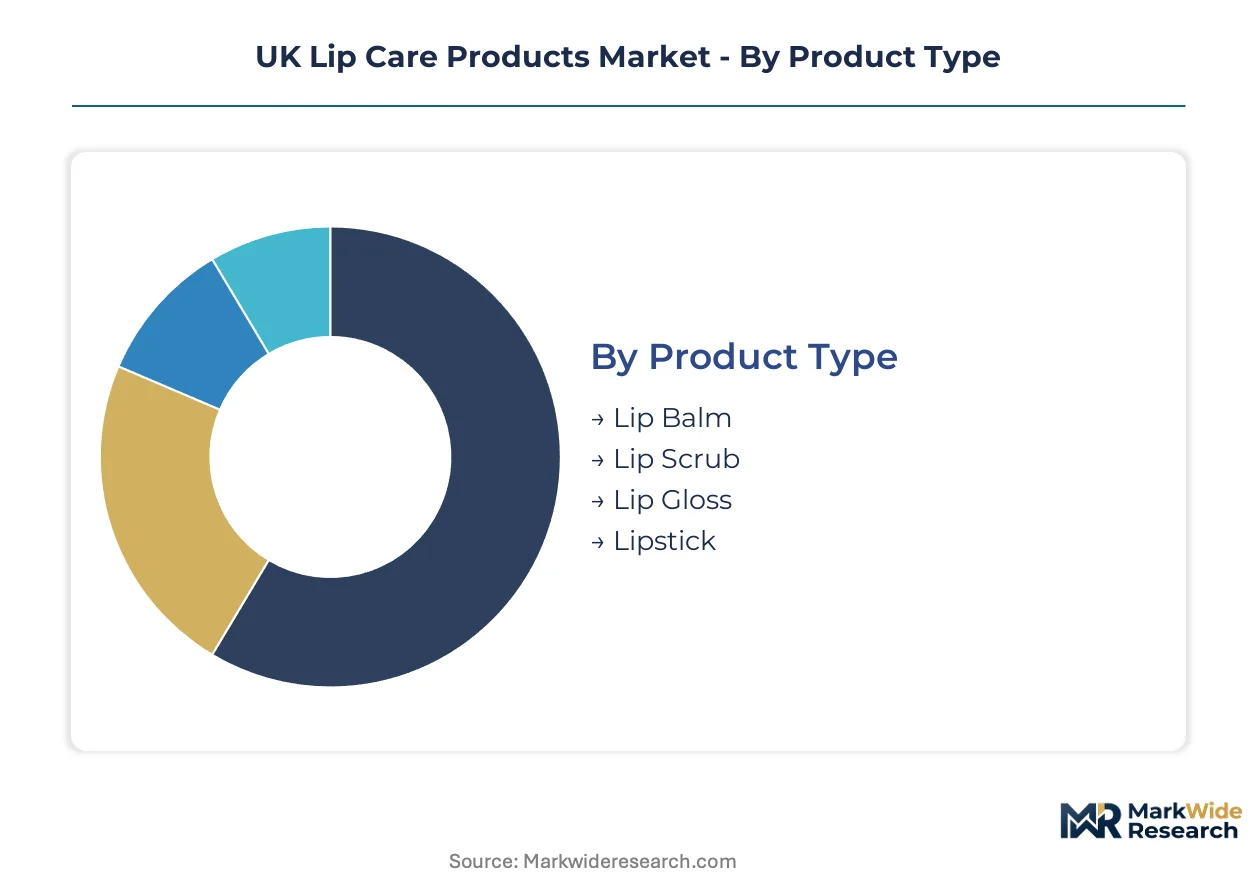
UK lip care segmentation reveals how formulation chemistry, application intent, and retail format intersect to determine margin structure and channel placement. Understanding these divides exposes where petroleum-free repositioning and pharmacy expansion will concentrate competitive investment.
Product Type:
Buyers differentiate primarily by routine integration depth—daily maintenance versus occasional treatment versus color cosmetics substitution.
- Lip Balm:Occlusive formulations with 15-40% petrolatum or plant-derived wax concentrations dominate unit volumes through impulse checkout placement. Greater London pharmacy chains and Boots flagship locations drive premium SPF and medicated variant uptake among commuters seeking barrier repair.
- Lip Scrub:Sugar and ground seed powder exfoliants are displacing banned microbead formulations under Environmental Protection Act compliance deadlines. Edinburgh and Glasgow independent chemists report accelerating jar-format gifting demand as facial skincare routines extend to lip care.
- Lip Gloss:High-shine emollient systems with lower occlusive load target color cosmetics crossover occasions. South East England urban density supports premium positioning through Superdrug and department store beauty halls.
- Lipstick:Pigmented wax-oil matrices with secondary moisturizing claims capture color cosmetics substitution demand. Wales pharmacy networks show underpenetration relative to English retail density for tinted therapeutic positioning.
Lip Balm leads volumes today; Lip Scrub is gaining share fastest.
Application:
Functional positioning determines whether products command pharmacy professional recommendation or mass self-selection.
- Moisturizing:Barrier-repair formulations with ceramide and hyaluronic acid technologies are securing dermatology channel placement. Trading Standards enforcement of EU-derived allergen disclosure rules is compressing development timelines for preservative system validation.
- Exfoliating:Physical and enzymatic lip surface renewal treatments are crossing from facial skincare enthusiasts into mainstream regimens. Scottish wholesale cooperative purchasing is concentrating negotiation leverage toward private-label capable manufacturers.
- Coloring:Tinted balms and hybrid color-care products bridge cosmetic and therapeutic positioning. Cardiff pharmacy group procurement represents emerging volume concentration outside England's South East dominance.
- Protection:SPF and environmental shield formulations command seasonal demand spikes and outdoor activity association. Office for Product Safety and Standards monitoring of persistent organic pollutants is forcing pre-emptive reformulation cycles.
Moisturizing anchors revenue today; Exfoliating shows steepest expansion trajectory.
End User:
Demographic targeting shapes distribution channel selection and price architecture.
- Women:Core volume base spanning therapeutic maintenance through color cosmetic substitution. South East England disposable income concentration supports premium SKU proliferation across all product types.
- Men:Simplified positioning emphasizing utility and neutral aesthetics. Independent chemist networks in Wales and Scotland report underdeveloped male-specific shelf space relative to English retail.
- Teens:Flavor-forward and socially shareable formats drive trial and frequency. Extended producer responsibility schemes under UK Environment Act obligations are raising compliance overhead for single-use stick formats favored by this segment.
- Children:Hypoallergenic and ingestible-safe formulations command parental trust premiums. Natural preservative system validation demands extended stability testing timelines for this safety-critical positioning.
Women retain volume leadership; Teens are expanding most quickly.
Packaging Type:
Format selection directly determines margin capture, sustainability compliance burden, and occasion targeting.
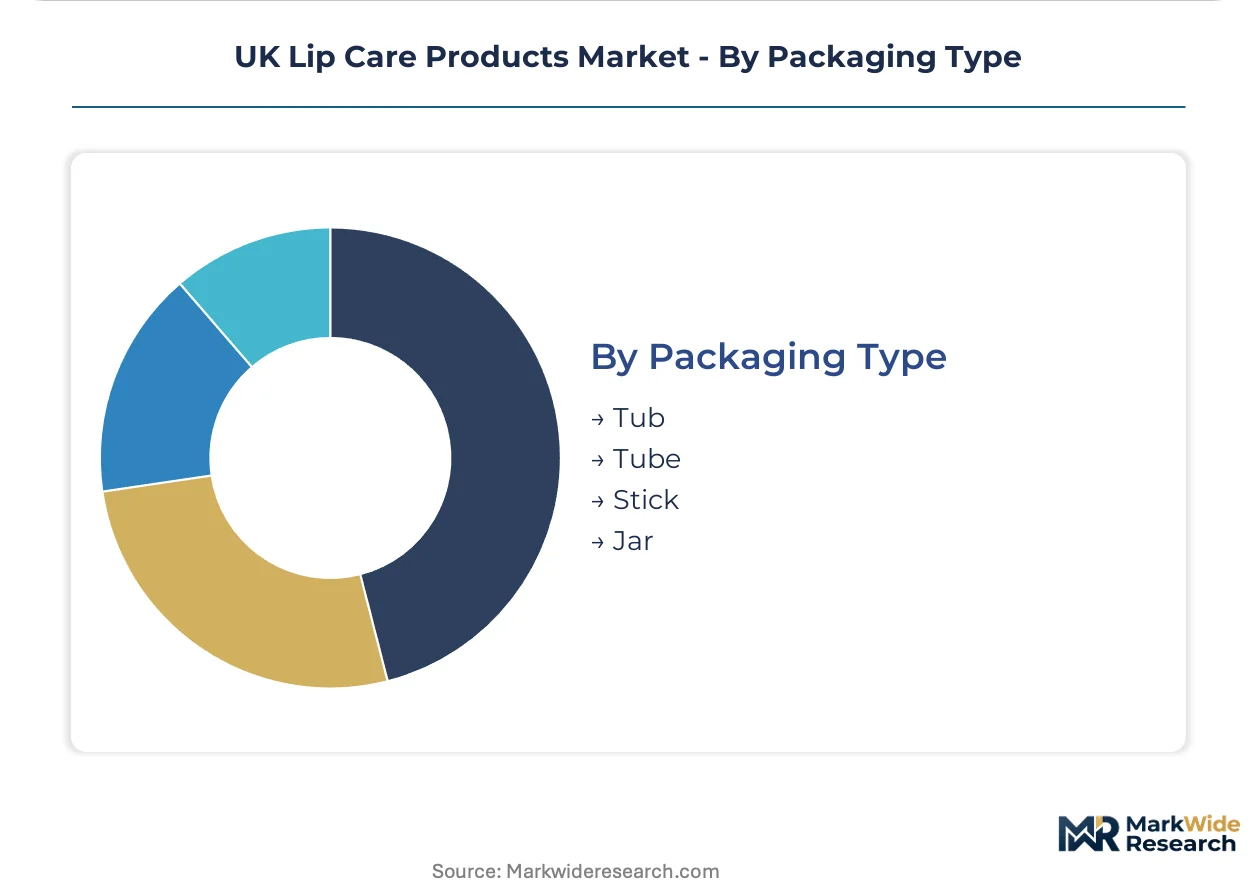
- Stick:Dominant impulse and travel format with established manufacturing infrastructure. Single-use plastic packaging directives are forcing material transition investments across petroleum-based and natural-formulation portfolios alike.
- Jar:Premium positioning and gifting occasion format with higher margin capture. Exfoliating routine expansion is driving sugar and seed powder scrub adoption through this tactile, shareable presentation.
- Tube:Squeezable format enabling varied viscosity formulations and controlled dispensing. Contract manufacturers are modularizing base architectures to serve tube-compatible plant-derived wax systems.
- Tub:Compact portable format with heritage association in UK pharmacy channels. Boots and Superdrug partnerships concentrate tub-format distribution control for mass-market lines.
Stick leads volumes today; Jar is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scotland's independent chemist networks are consolidating faster than Wales, though both trail England's retail density. The South East concentration of disposable income creates a bifurcated national map where regional penetration strategies diverge sharply.
London and South East England
Greater London pharmacy chains and Boots flagship locations drive premium SPF and medicated variant uptake among commuters. The UK Environmental Protection Act's microbead prohibition has accelerated natural wax reformulation among contract manufacturers concentrated in this region. Oxford and Cambridge retail clusters report the highest per-capita spending on barrier-repair ceramide technologies.
Midlands
Birmingham and Leicester manufacturing hubs supply petroleum-free base formulations to national distributors. Trading Standards enforcement of EU-derived allergen disclosure rules compresses development timelines for preservative system validation in this production corridor. Coventry-based contract manufacturers are modularizing plant-derived wax architectures to serve tube-compatible systems.
North England
Manchester and Leeds independent chemists are consolidating purchasing through regional wholesale cooperatives. Extended producer responsibility schemes under UK Environment Act obligations are raising compliance overhead for stick-format dominant portfolios distributed through these channels. Sheffield manufacturing retains heritage petroleum-based capacity serving mass-market price points.
Scotland
Edinburgh and Glasgow pharmacy group procurement now represents meaningful volume concentration outside England's dominance. Sugar and ground seed powder exfoliants are displacing banned microbead formulations through jar-format gifting demand. Scottish wholesale cooperative purchasing is shifting negotiation leverage toward private-label capable manufacturers.
Wales
Cardiff pharmacy networks show underpenetration relative to English retail density for tinted therapeutic positioning. The Office for Product Safety and Standards monitoring of persistent organic pollutants is forcing pre-emptive reformulation cycles among Welsh distributors. Swansea and Newport independent chemists report accelerating demand for natural preservative systems in children's hypoallergenic segments.
UK Lip Care Products Market Key Industry Players
US-based consumer goods conglomerates anchor the mass-market tier; UK and European specialists hold premium natural positioning. The vendor base separates into three distinct layers: multinational FMCG portfolios with pharmacy chain control, mid-tier British brands with petroleum-free modular architectures, and artisanal producers serving independent chemist cooperatives. Dominant competitive moves include strategic partnerships with Boots and Superdrug for distribution density, and backward integration into beeswax sourcing to mitigate supply volatility.
Within the multinational FMCG tier, L'Oreal SA and Unilever PLC exemplify divergent strategic archetypes. L'Oreal occupies a position representing sustained R&D investment in barrier-repair lip technologies, while Unilever anchors mass-market distribution control through established pharmacy partnerships. Burt's Bees sits within the natural heritage specialist category, leveraging ingredient sourcing credibility to command premium shelf space across British health and beauty retailers.
| Leading Market Players |
|---|
| Colgate-Palmolive Co |
| Johnson & Johnson |
| L'Oreal SA |
| Revlon |
| Procter & Gamble Co |
| Unilever PLC |
| The Estee Lauder Companies Inc |
| Burt's Bees |
| Beiersdorf AG |
| Others |
Cost & Logistics Intelligence
Boots and Superdrug pharmacy chain procurement consolidation is forcing contract manufacturers toward modular plant-derived wax architectures, compressing margins on legacy petrolatum lines while rewarding petroleum-free specialists with shelf-space premiums. This buyer concentration reshapes supplier investment priorities across English, Scottish, and Welsh distribution networks.
Pricing Analysis
Retailer markup layers stratify across premium, standard, and economy tiers, with South East England Boots flagship locations commanding 15-20 point spreads over Midlands manufacturing hubs. Price differentiation rests on natural certification grade and SPF variant complexity, with ceramide barrier-repair technologies anchoring premium positioning. Cost compression in mass-market petrolatum segments is intensifying because of beeswax import dependency and extended producer responsibility compliance overhead. Teen-oriented stick formats show highest price sensitivity; dermatology-channel therapeutic lines show lowest.
Supply Chain Analysis
Regional distribution centers in Birmingham and Coventry operate hub-and-spoke patterns feeding independent chemist cooperatives in Scotland and Wales. Manufacturing concentrates in England's Midlands corridor, with beeswax sourcing drawing from European apiary networks and candelilla wax imports from Mexico. Single-source vulnerability sits with UK domestic apiary output fluctuations, which ripple through natural-formulation specialist cost structures. Distribution runs through Boots and Superdrug-controlled wholesale networks for mass-market tiers, while artisanal producers bypass centralized hubs for direct independent chemist relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK Environmental Protection Act's microbead prohibition compounds competitive advantage for pre-positioned natural ingredient supply chains, transforming regulatory compliance into demand generation.
For Market Incumbents: Anticipate Trading Standards enforcement acceleration by pre-emptively reformulating fragrance allergen disclosures and natural preservative systems. Defensive consolidation moves should capture Edinburgh and Glasgow wholesale cooperative procurement leverage through private-label manufacturing capabilities, while backward integration into Spanish and Polish beeswax sourcing mitigates supply volatility threatening margin stability. For New Entrants and Emerging Players: Modular plant-derived wax blending technology offers entry wedge against petroleum-dependent incumbents constrained by sensory trade-offs in full reformulation. White-space targets concentrate in Wales tinted therapeutic positioning and Scottish male-specific shelf space, with jar-format lip scrub gifting positioning as the most penetrable application. Go-to-market angle should exploit biodegradable certification anticipation for early aquatic toxicity standard compliance. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier British brands possessing petroleum-free modular architectures and established Boots/Superdrug shelf placement. Long-term viability across the projection horizon favors specialists with captive natural wax supply relationships and regional chemist cooperative distribution penetration. Signal to watch: Office for Product Safety and Standards enforcement actions triggering accelerated reformulation cycles and distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Petroleum-Free Formulation Transition | Environmental Protection Act compliance creates first-mover shelf space advantages at Boots. |
| Scottish Wholesale Cooperative Penetration | Edinburgh and Glasgow pharmacy group procurement concentrates negotiation leverage for private-label entrants. |
| Beeswax Supply Backward Integration | Captive European apiary sourcing mitigates input cost instability for natural-formulation specialists. |
| Biodegradability Certification Investment | Anticipated UK national aquatic toxicity standards create positioning space for early-certified entrants. |
| Ceramide Barrier-Repair R&D Expansion | Dermatology channel placement secures professional recommendation networks against mass-market commoditization. |
Research Approach
Coverage spans England, Scotland, and Wales, with primary inputs from each region's pharmacy chain category buyers, independent chemist proprietors, contract manufacturing operations directors, and Trading Standards enforcement officers. Secondary validation draws from UK Cosmetic, Toiletry and Perfumery Association guidance documents, Office for Product Safety and Standards monitoring reports, Environment Act regulatory filings, and Nielsen retail audit data. Bottom-up SKU-level volume builds triangulate against top-down category spend estimates from wholesale cooperative purchasing disclosures.
Rate-of-change decomposition separates volume trajectory from price-mix effects across product type, application intent, end-user demographic, and packaging format dimensions. CAGRs derive from segment-level growth rate reconciliation with aggregate category expansion. Forecast inputs incorporate beeswax supply volatility scenarios, post-Brexit REACH divergence timelines, and extended producer responsibility scheme implementation phases.
The model holds under stable regulatory enforcement intensity and continued pharmacy chain consolidation; deviation in Trading Standards allergen disclosure stringency or Scottish wholesale cooperative merger activity would shift volume concentration patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Color Cosmetics OEM and ODM Market
Cosmetics & Skincare
Setting Spray Market
Cosmetics & Skincare
Eyeliner Pen Market
Cosmetics & Skincare
Mascara Applicators Market
Cosmetics & Skincare
Loose Setting Powder Market
Cosmetics & Skincare
North America Deodorants Market
Cosmetics & Skincare
Face Bronzer Market
Cosmetics & Skincare
Asia-Pacific Halal Cosmetics Market
Cosmetics & Skincare
Beauty Facial Mask Market
Cosmetics & Skincare
Israel Cosmetics Market
Cosmetics & Skincare
Night Cream Market
Cosmetics & Skincare
Cosmetic Pencil and Pen Market
Cosmetics & Skincare
Lip Oil Market
Cosmetics & Skincare
Body Cream Jars Market
Cosmetics & Skincare
Caffeine Eye Creams Market
Cosmetics & Skincare
Makeup Remover Pen Market