
 Europe Dark Chocolate Market | 2026-2036
Europe Dark Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Dark Chocolate Market Intelligence
Multi-source cocoa procurement is shifting toward vertically integrated supply chains across the European dark chocolate sector. Barry Callebaut AG anchors large-scale grinding and couverture supply to industrial buyers across the continent. Lindt & Sprüngli AG leverages its Swiss manufacturing heritage and premium retail positioning to sustain margin-rich direct-to-consumer channels. Mondelēz International competes through mass-market distribution density and brand portfolio breadth in supermarkets and convenience formats.
Dark chocolate denotes confectionery containing cocoa solids, cocoa butter, and sugar with minimal or no milk solids, typically manufactured through conching, tempering, and molding processes to achieve specific particle size below 30 microns and stable polymorphic crystal structures for snap and gloss. The product serves premium indulgence, functional food, and ingredient applications across retail and foodservice channels. Bittersweet varieties lead value contribution due to elevated cocoa content and artisanal positioning, while semi-sweet formulations dominate volume through bakery and food manufacturing offtake. Specialty stores and online channels capture the fastest expansion as consumers seek origin-specific, high-cocoa-percentage products with transparent provenance credentials.
The EU Deforestation Regulation and EFSA food labeling standards shape cocoa sourcing transparency and nutritional claim substantiation across member states. REACH compliance for processing aids and packaging materials further constrains formulation and material choices for manufacturers operating in the European Economic Area. Stakeholders must monitor evolving EUDR traceability deadlines and origin verification requirements to secure supply continuity and market access.
Market Dynamics
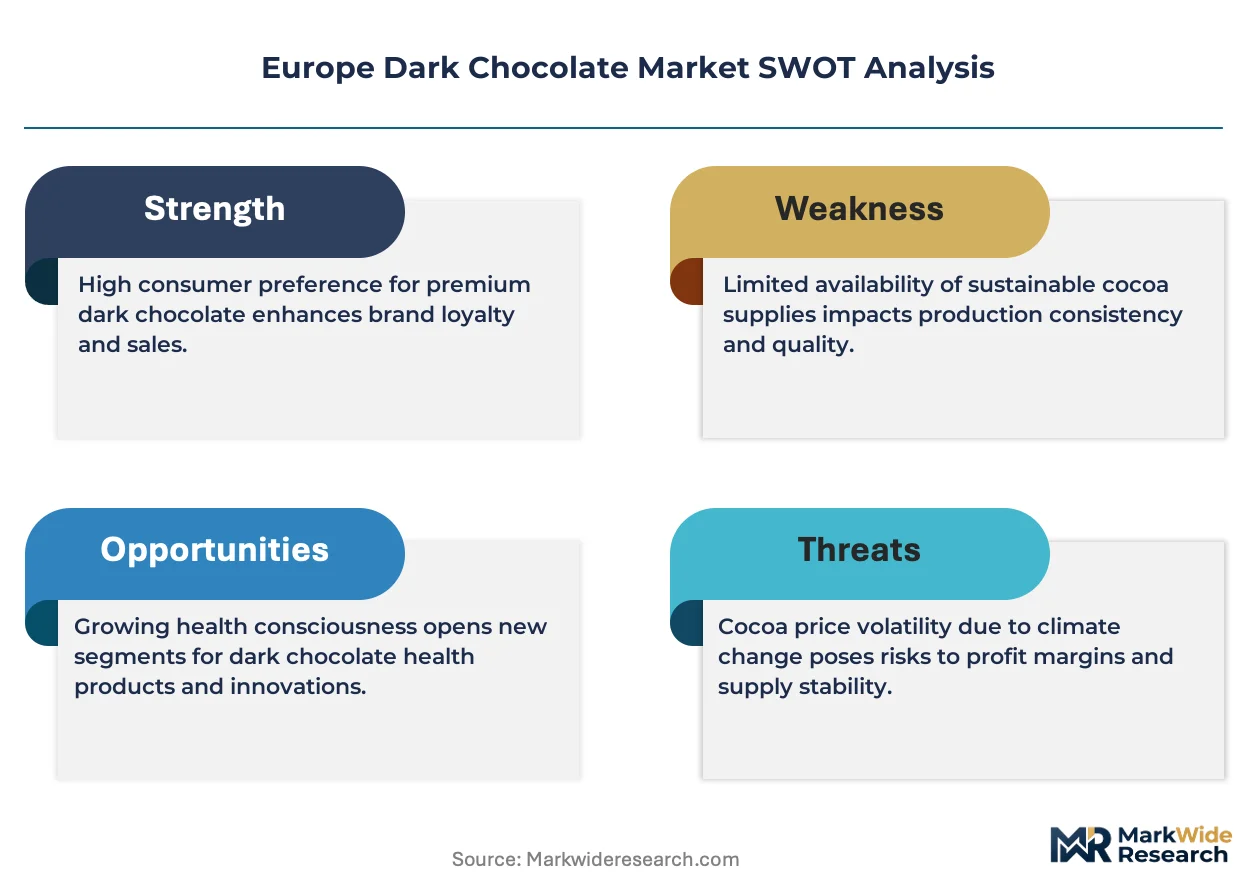
EU Deforestation Regulation traceability mandates are forcing European dark chocolate manufacturers to rebuild supply chains around verified origin documentation and geolocation data for every cocoa batch entering the continent.
Growth Catalysts
- EFSA nutritional claim substantiation:Manufacturers leveraging approved health claims around cocoa flavanols gain shelf positioning advantages in German and Swiss pharmacy retail channels.
- Bean-to-bar craftsmanship revival:Small-batch producers in Belgium and France attract premium pricing through direct farmer relationships and transparent provenance storytelling.
- Germany:Europe's largest chocolate consumption market drives volume demand for high-cocoa-percentage bars through specialist retailers and online subscription models.
Market Restraints
- Cocoa butter price volatility:Butter futures on European commodity exchanges swing with West African harvest cycles, compressing margins for couverture-dependent industrial users.
- West African supply concentration:Over seventy percent of European grinding capacity depends on Côte d'Ivoire and Ghana origin beans, creating geopolitical and climate exposure.
- EUDR compliance timeline friction:The December 2025 full implementation deadline demands satellite-based farm boundary verification that many smallholder cooperatives cannot yet provide.
Strategic Opportunities
- Eastern European underpenetration:Poland and Romania show per-capita dark chocolate consumption gaps of forty-plus percent versus Western European averages, inviting brand establishment.
- Functional food convergence:Dark chocolate fortified with probiotics or adaptogens accesses pharmacy and wellness retail channels previously closed to conventional confectionery.
- Direct-to-consumer subscription channels:Monthly origin-specific tasting boxes bypass supermarket slotting fees while capturing lifetime value through recurring revenue.
Industry Challenges
- Conching technician scarcity:Master chocolate makers with particle-size optimization expertise command premium wages in Switzerland and Belgium, constraining artisanal scale-up.
- Legacy ERP integration with traceability platforms:Mid-sized manufacturers struggle to map batch-level cocoa movement onto decades-old inventory systems without seven-figure replacement costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Dark Chocolate Market |
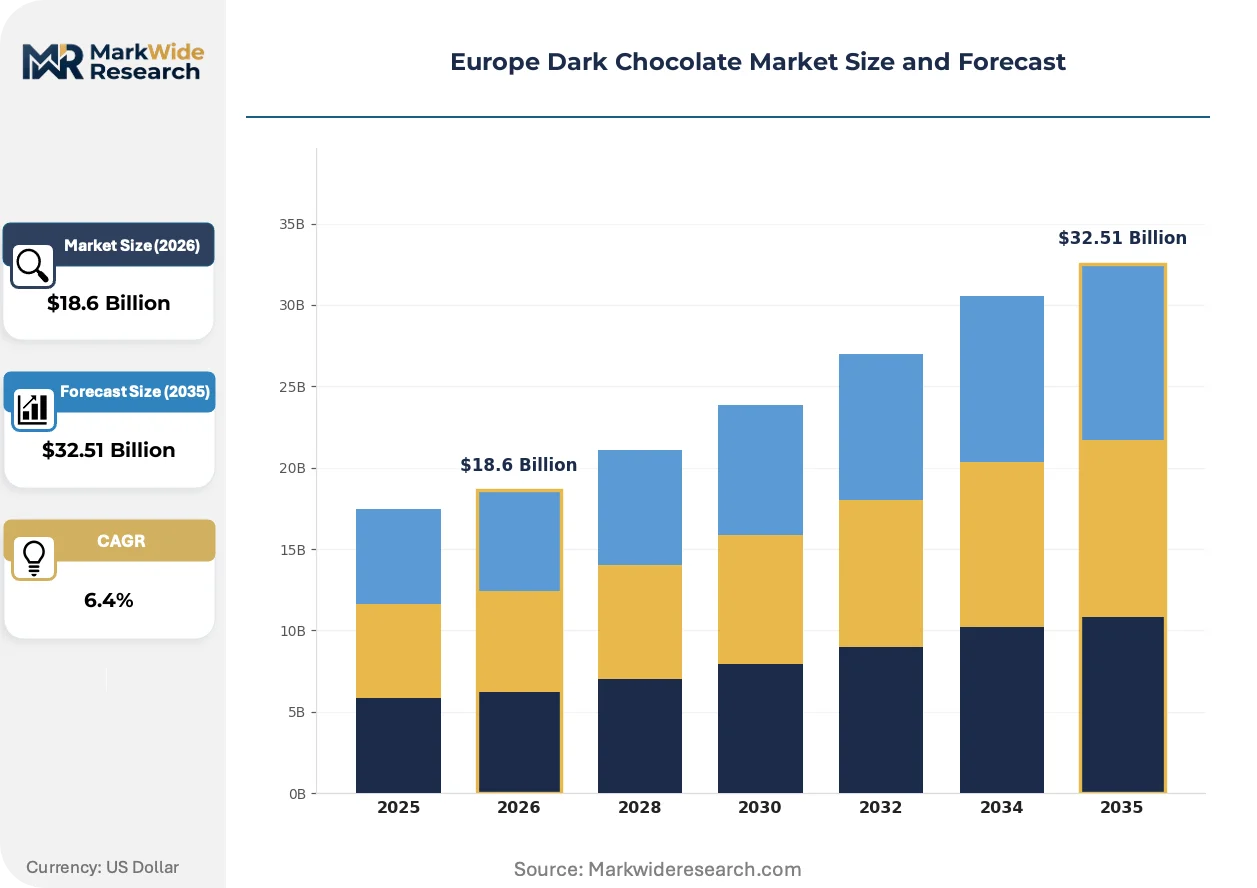
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $32.51 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bittersweet, Semi-Sweet, Unsweetened, Raw End User: Retail Consumers, Food Manufacturers, Bakeries, Cafés Packaging Type: Bars, Chips, Bulk, Bites Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | Lindt & Sprüngli AG, The Hershey Company, Barry Callebaut AG, Godiva Chocolatier, Ritter Sport, Ferrero International S.A., Mondelēz International, Amul, Nestlé S.A., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Dark Chocolate Market Strategic Shifts & Innovations
Precision fermentation-derived cocoa butter alternatives and blockchain-enabled provenance verification are compressing traditional supply chain structures while opening new formulation possibilities for European manufacturers.
Cell-cultured cocoa butter from precision fermentation bioreactors is electrifying R&D pipelines across Swiss and Belgian innovation centers. Industrial chocolate divisions at major grinders pilot these fats for stability-controlled applications where tropical climate resistance matters. The technology is electrifying cost structures for heat-stressed markets by reducing dependence on agricultural commodity cycles.
REACH compliance for novel processing aids tightens formulation freedom for manufacturers seeking clean-label positioning. ECHA substance evaluation workflows now demand extended toxicity datasets for enzymes used in cocoa alkalization. Belgian compound chocolate producers face reformulation costs or restricted substance lists that favor traditional conching methods.
Specialty retailers and direct subscription channels displace supermarket dominance for origin-transparent, high-percentage dark chocolate. German consumers increasingly verify bean-to-bar claims through QR-linked harvest documentation before purchase. This verification-driven preference shift concentrates volume growth in Zurich, Brussels, and Berlin metropolitan clusters where transparency premiums sustain fifty-plus percent price multiples over mass-market alternatives.
Europe Dark Chocolate Market Segmentation
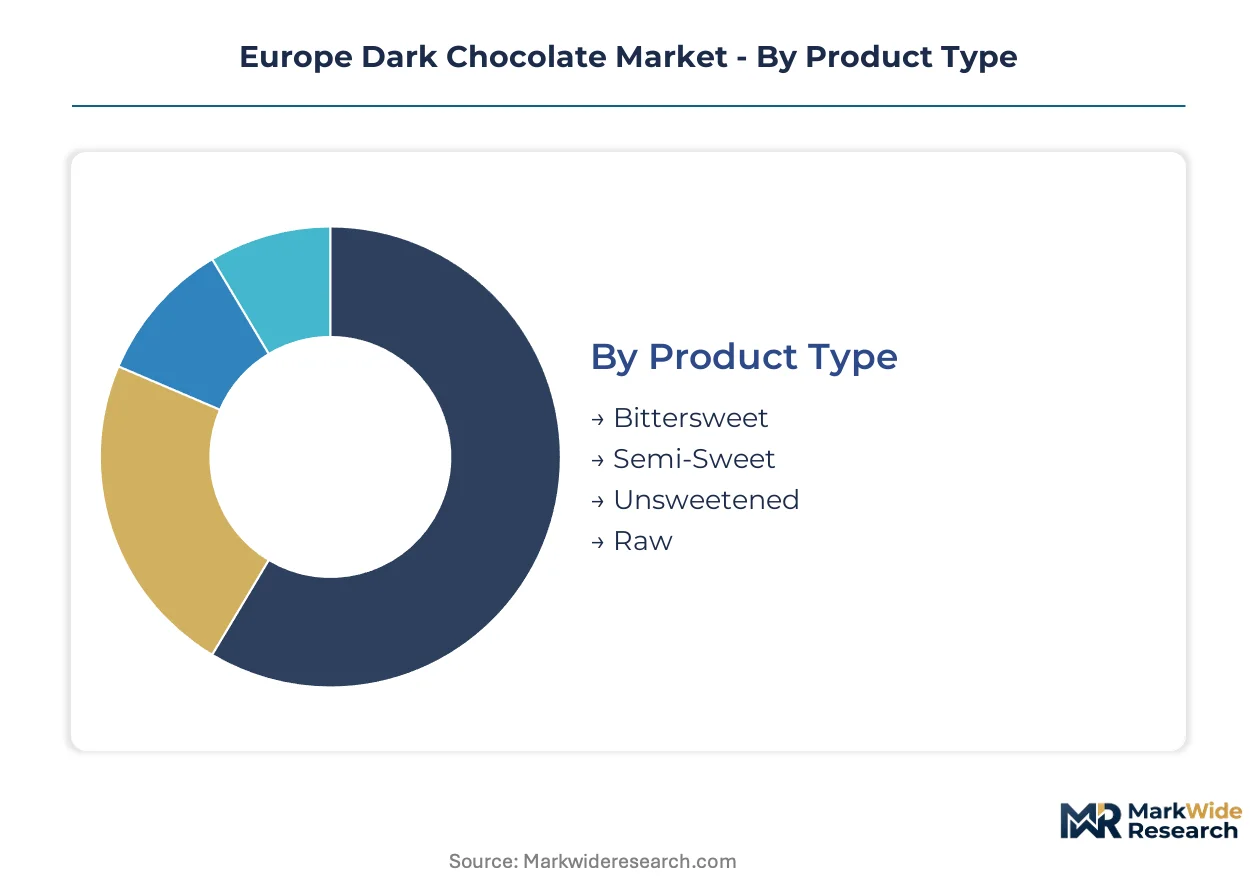
Dark chocolate segmentation in Europe tracks how cocoa percentage thresholds and provenance credentials command divergent price premiums across retail and industrial channels. Manufacturers align formulation portfolios to specific end-use viscosity requirements and tempering protocols that vary by customer type.
Product Type:
Upgrade cycles in European dark chocolate reflect shifting consumer sophistication from mass-market sweetness tolerance to high-percentage cocoa appreciation, with reformulation investments concentrating in German and Swiss innovation pipelines.
- Bittersweet:Contains elevated cocoa solids above seventy percent with minimal sugar, delivering intense flavor profiles through extended conching. German specialist retailers and Zurich bean-to-bar boutiques drive premium positioning for single-origin variants with EUDR-verified farm documentation.
- Semi-Sweet:Balances cocoa intensity with broader palatability through moderate sugar content, typically fifty to seventy percent cocoa. Belgian industrial chocolate houses supply this grade to European bakery chains and confectionery manufacturers seeking couverture with predictable tempering behavior.
- Unsweetened:Pure cocoa mass and butter without added sugars, serving ingredient applications in French pâtisserie and Scandinavian health-food formulations.
- Raw:Unroasted cocoa preserves heat-sensitive flavanol compounds, attracting wellness-positioned brands in Austrian and Dutch organic retail channels.
Semi-sweet sits at the top of the volume ranking, with bittersweet climbing the fastest.
End User:
Cost tier stratification separates commodity-scale industrial buyers from artisanal micro-batch producers, with procurement volumes spanning three orders of magnitude across the customer base.
- Retail Consumers:Individual purchasers seeking premium indulgence or functional food benefits through high-percentage bars and origin-specific offerings. Swiss and Belgian direct-to-consumer subscription channels capture recurring revenue from provenance-verified monthly selections.
- Food Manufacturers:Industrial chocolate users requiring couverture with precise viscosity, snap, and bloom resistance for mass-produced confectionery. German and Italian processing facilities demand EUDR-compliant documentation for every cocoa batch entering their grinding lines.
- Bakeries:Artisan and chain operations sourcing chips and callets for pastry applications where moisture tolerance and melt stability matter.
- Cafés:Specialty coffee houses incorporating drinking chocolate and mousse applications with single-origin storytelling for menu differentiation.
Food manufacturers represent the largest volume tier, with retail consumers gaining share fastest through premium subscription expansion.
Packaging Type:
Application-specific formats align with processing equipment requirements and shelf-life demands across European manufacturing and foodservice operations.
- Bars:Standard retail format ranging from single-serve to family-size tablets, with German supermarkets and French hypermarkets dominating volume throughput.
- Chips:Small, uniform drops engineered for baking applications requiring controlled melt distribution and moisture resistance.
- Bulk:Industrial totes and tanker deliveries serving large-scale confectionery and bakery operations in Belgium and the Netherlands.
- Bites:Portion-controlled pieces targeting on-the-go consumption and foodservice garnish applications.
Bars command the volume lead, with bites expanding most quickly through convenience and foodservice channels.
Distribution Channel:
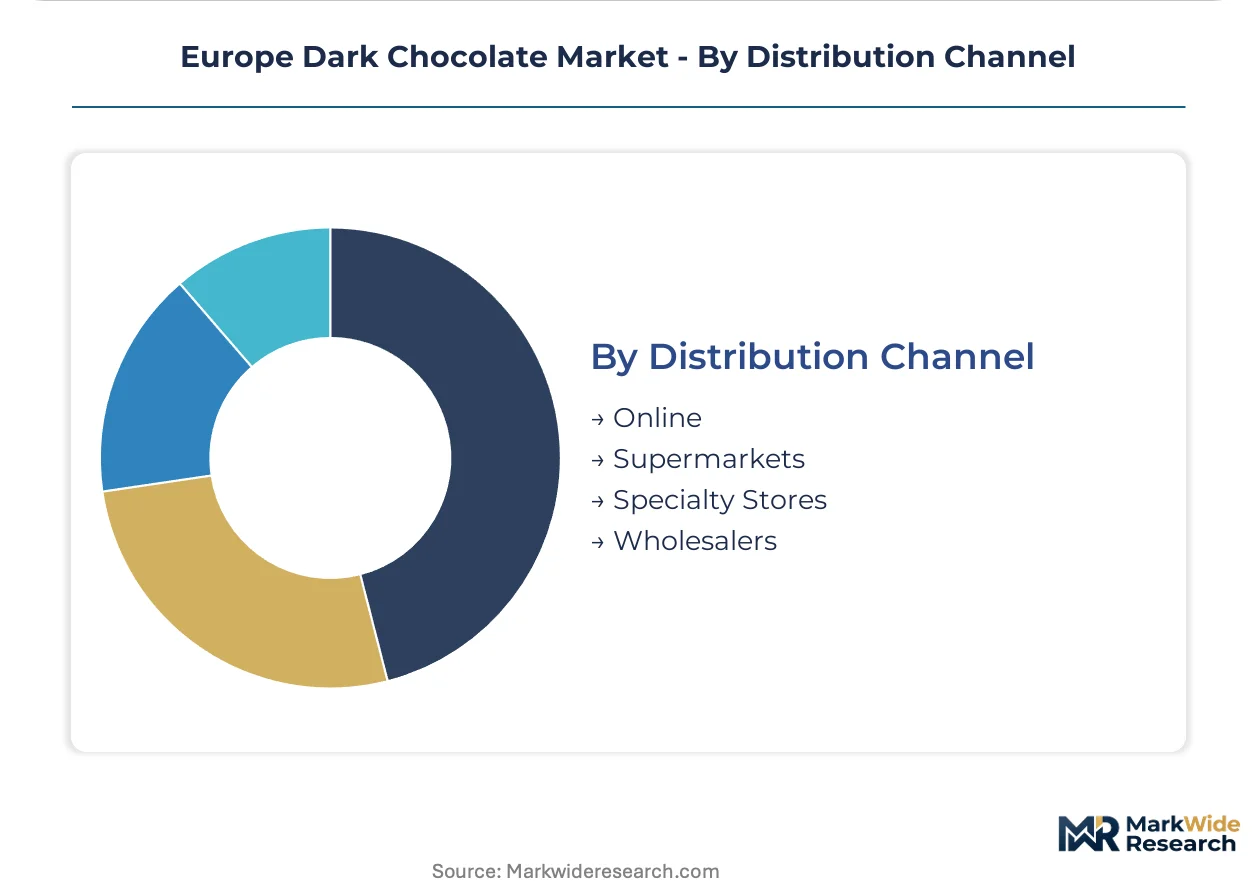
Geography-driven channel selection reflects urban density, retail infrastructure maturity, and regulatory compliance capabilities across European markets.
- Online:Direct-to-consumer platforms and marketplace aggregators enabling origin transparency through QR-linked documentation. German consumers verify bean-to-bar claims via harvest traceability portals before purchase.
- Supermarkets:Mass-market retail chains in France, Germany, and the UK driving volume for standard-percentage bars through promotional pricing and private-label expansion.
- Specialty Stores:Independent chocolatiers and gourmet retailers in Brussels, Zurich, and Berlin metropolitan clusters where transparency premiums sustain significant price multiples.
- Wholesalers:Foodservice distributors and industrial ingredient suppliers serving bakery and confectionery manufacturing across the continent.
Supermarkets retain the volume ranking, with online channels climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Brussels-Antwerp corridor anchors European dark chocolate manufacturing through concentrated grinding capacity and artisanal atelier density. This Benelux cluster interfaces with German industrial demand and Swiss premium positioning to shape continental supply patterns. National markets diverge sharply in regulatory exposure and consumption sophistication.
Germany
Pharmacy retail channels drive functional dark chocolate demand through EFSA-approved flavanol health claims. The country's national food regulator enforces strict nutritional substantiation requirements for cocoa polyphenol marketing. Berlin and Hamburg metropolitan clusters host subscription-based bean-to-bar platforms that verify EUDR compliance through QR-linked harvest documentation.
Switzerland
Swissmedic-aligned quality standards sustain premium export positioning for high-percentage couverture. The federal food safety authority mandates traceability protocols that exceed baseline EU requirements for cocoa origin verification. Zurich and Geneva house master chocolate makers whose particle-size optimization expertise commands wage premiums that constrain artisanal scale-up.
Belgium
Industrial chocolate houses in Flanders supply semi-sweet couverture to European bakery chains requiring predictable tempering behavior. ECHA substance evaluation workflows demand extended toxicity datasets for cocoa alkalization enzymes used in processing. Brussels anchors EU regulatory lobbying while Antwerp grinders pilot precision fermentation-derived cocoa butter alternatives for tropical climate applications.
France
French pâtisserie demand concentrates in unsweetened dark chocolate for ganache and mousse applications. The national food safety agency enforces EUDR-aligned deforestation-free supply chain documentation through its customs and fraud control directorate. Parisian specialty retailers and Lyon-based artisan chocolatiers leverage origin-transparent storytelling to sustain fifty-plus percent price multiples over mass-market alternatives.
United Kingdom
Supermarket private-label expansion drives volume for standard-percentage dark chocolate bars through promotional pricing cycles. The Food Standards Agency coordinates EUDR implementation timelines with trader readiness assessments for cocoa import documentation. London specialty retailers and Edinburgh bean-to-bar producers attract premium positioning through direct farmer relationship narratives.
Europe Dark Chocolate Market Key Industry Players
Global majors compete with regional champions across grinding capacity and premium retail positioning. The vendor base stratifies between industrial-scale couverture suppliers and artisanal micro-batch producers with divergent margin structures and capital intensity requirements. Three archetypes dominate: Swiss-heritage premium brands, Belgian-Dutch industrial grinders, and American mass-market portfolio owners. Competitive moves concentrate on EUDR-compliant supply chain reconstruction and direct-to-consumer subscription channel establishment.
Within the premium-heritage tier, Lindt & Sprüngli AG and Barry Callebaut AG exemplify divergent scale positioning. Lindt & Sprüngli AG occupies a position anchored in Swiss manufacturing heritage and margin-rich retail channels. Barry Callebaut AG represents industrial-scale grinding and couverture supply archetype serving food manufacturers across the continent. Mondelēz International sits within the mass-market portfolio owner category competing through distribution density in supermarkets and convenience formats.
| Leading Market Players |
|---|
| Lindt & Sprüngli AG |
| The Hershey Company |
| Barry Callebaut AG |
| Godiva Chocolatier |
| Ritter Sport |
| Ferrero International S.A. |
| Mondelēz International |
| Amul |
| Nestlé S.A. |
| Others |
Cost & Logistics Intelligence
Bean-to-bar certification gaps create a three-tier pricing structure across premium, standard, and economy levels that simultaneously rewards EUDR-verified provenance and punishes opaque sourcing. This stratification channels margin toward Swiss and Belgian ateliers with direct farmer relationships while compressing returns for commodity couverture suppliers dependent on spot cocoa butter markets.
Pricing Analysis
Input-cost pass-through from cocoa butter futures on European commodity exchanges intensifies margin volatility for industrial chocolate houses without long-term offtake agreements. Three-tier pricing structure across premium, standard, and economy levels separates Zurich bean-to-bar boutiques from Belgian compound producers and German private-label suppliers. Price differentiation hinges on EUDR compliance documentation and single-origin storytelling credentials. Food manufacturers exhibit highest price sensitivity due to volume procurement and substitutable couverture specifications, while German pharmacy retail channels absorb premium markups for EFSA-substantiated flavanol claims.
Supply Chain Analysis
Master chocolate maker scarcity in Switzerland and Belgium constrains artisanal scale-up as conching technicians command wage premiums that deter capacity expansion. Supply concentrates in Côte d'Ivoire and Ghana for raw bean inputs, with Belgian and Dutch grinders anchoring European processing capacity. Raw material dependencies span West African cocoa, Malaysian cocoa butter, and Madagascan vanilla for high-end formulations. Single-source vulnerability from West African harvest cycles creates commodity price volatility that ripples through couverture pricing. Distribution runs through Antwerp bulk terminals for industrial buyers and direct subscription platforms for premium retail consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in European dark chocolate rests on EUDR compliance cost absorption by premium tiers and precision fermentation scale-down of cocoa butter input volatility.
For Market Incumbents: Deploy backward integration into EUDR-verified farm networks to lock supply continuity ahead of full regulatory implementation. Lindt & Sprüngli AG and Barry Callebaut AG should accelerate satellite-based geolocation data collection from Ivorian and Ghanaian cooperatives. Master chocolate maker wage inflation in Zurich and Brussels threatens artisanal output scaling; automated conching systems warrant R&D investment. Certification investment in Swissmedic-aligned traceability protocols sustains export premium positioning against mass-market competitors. For New Entrants and Emerging Players: Begin with Eastern European underpenetration in Poland and Romania where per-capita consumption gaps invite brand establishment before incumbent shelf saturation. Direct-to-consumer subscription channels bypass supermarket slotting fees and capture lifetime value through recurring revenue. Functional food convergence offers the most penetrable white-space: probiotic-fortified dark chocolate accesses German pharmacy retail channels previously closed to conventional confectionery. QR-linked harvest documentation serves as the primary go-to-market angle for transparency-native consumer segments. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-sized manufacturers face seven-figure ERP replacement costs to integrate EUDR traceability platforms with legacy inventory systems. Long-term viability over the next decade favors vertically integrated supply chains with captive farm relationships and direct subscription revenue streams. Acquisition targets should display EUDR-ready documentation infrastructure and proven bean-to-bar brand equity in German or Swiss metropolitan clusters. Watch for EUDR implementation deadline friction as the inflection indicator: smallholder cooperative compliance failures will force distressed asset sales among non-compliant grinders.| Strategic Initiative | Industry Significance |
|---|---|
| EUDR Compliance Infrastructure | Satellite-based farm boundary verification secures market access for European grinders. |
| Precision Fermentation Scale-Up | Cell-cultured cocoa butter alternatives reduce tropical climate supply chain exposure. |
| Direct-to-Consumer Subscription Launch | Monthly origin-specific tasting boxes bypass supermarket slotting fee structures. |
| Functional Food Certification | EFSA-approved flavanol claims unlock German pharmacy retail channel placement. |
| Master Chocolate Maker Training Programs | Swiss and Belgian conching technician pipelines constrain artisanal capacity expansion. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to capture both volume trajectories and supply chain transformation narratives. Primary interviews engaged cocoa procurement directors at Belgian and Dutch grinders, Swiss bean-to-bar founders, German pharmacy retail category managers, and EUDR compliance officers at major confectionery houses. Secondary validation drew from EU customs cocoa import records, EFSA health claim substantiation filings, ECHA substance evaluation workflows, and Swissmedic traceability protocol documentation. Bottom-up demand modeling from retail channel audits triangulated against top-down grinder capacity assessments across the analysis window.
Comparable-period anchoring tied projection assumptions to verified historical consumption patterns and regulatory implementation timelines. Segmentation dimensions spanned cocoa percentage tiers, end-user viscosity requirements, packaging format specifications, and distribution channel compliance capabilities. CAGRs derived from weighted average growth trajectories across German, Swiss, and Belgian national markets with Eastern European expansion scenarios. Forecast inputs incorporated EUDR traceability cost curves, cocoa butter futures volatility bands, and precision fermentation technology adoption S-curves.
Several conditions sit outside the modeled scope, including geopolitical disruption in West African supply corridors and EUDR deadline extensions or enforcement dilution. Forecasts reflect assumptions about smallholder cooperative geolocation data readiness and consumer willingness to absorb transparency premiums. Material deviation in cocoa butter commodity cycles or EUDR implementation friction warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Global Candy Market
Confectionery
Sugar-Free Gummy Market
Confectionery
US Dark Chocolate Market
Confectionery
UK Confectionery Market
Confectionery
South America Compound Chocolate Market
Confectionery
Cocoa and Chocolate Market
Confectionery
Bangladesh Candy Market
Confectionery
Salted Caramel Products Market
Confectionery
North America Chocolate Market
Confectionery
Jellies and Gummies Market
Confectionery
Brain Mint Market
Confectionery
North America Gummy Market
Confectionery
Chocolate, Cocoa Beans, Lecithin, Sugar and Vanilla Market
Confectionery
Sugar Free Mints Market
Confectionery
Global Non-Cocoa Confectionery Market
Confectionery
US Confectionery Market