
 Europe Compound Chocolate Market | 2026-2036
Europe Compound Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Compound Chocolate Market Foresight
Belgium's compound chocolate processing corridor is fragmenting as new capacity additions in Poland and Romania redraw production maps. Barry Callebaut leverages its Belgian R&D infrastructure to sustain premium coating formulations. Puratos Group anchors artisan bakery channels with specialized compound chocolate drops. Cargill competes through integrated vegetable fat supply chains serving industrial confectionery accounts.
Compound chocolate replaces cocoa butter with vegetable fats such as palm, shea, or coconut oil, achieving melting profiles between 32°C and 36°C for coating applications where fat bloom resistance and snap stability matter. Milk compound chocolate dominates volume flows across European industrial bakeries due to cost positioning and flavor neutrality in laminated doughs. Dark compound variants occupy faster-growing niches as EFSA-labeled clean-label formulations gain traction among specialty confectioners. The coating application segment leads margin capture, since enrobing demands precise viscosity control and temper-free processing that compound formulations uniquely deliver.
EFSA purity criteria govern vegetable fat substitutions and labeling distinctions from chocolate proper, while the EU F-Gas Regulation indirectly pressures processing energy choices. REACH compliance shapes emulsifier and additive selections across Belgian and German manufacturing plants. Stakeholders must monitor regulatory divergence between EU-wide frameworks and emerging national clean-label standards in France and Italy.
Market Dynamics
Vegetable fat substitution protocols under tightening EFSA purity criteria are forcing compound chocolate manufacturers to revalidate coating formulations and relabel product portfolios across European processing plants.
Growth Catalysts
- EFSA Purity Criteria Expansion:Stricter vegetable fat labeling distinctions from chocolate proper are accelerating clean-label R&D investments among Belgian and Italian compound specialists.
- Industrial Bakery Scaling:German laminated dough manufacturers are expanding enrobed pastry lines that demand temper-free compound coatings with precise viscosity control.
- Polish Capacity Additions:New processing plants in Lower Silesia and Greater Poland are capturing contract manufacturing flows from Western European confectionery brands seeking cost-optimized supply.
Market Restraints
- Palm Oil Price Volatility:Crude palm oil futures fluctuations in Rotterdam and Hamburg trading hubs compress margin predictability for vegetable fat-dependent formulations.
- Belgian Processing Concentration:Overreliance on Flanders corridor infrastructure creates single-point vulnerability for European coating supply during energy rationing events.
- Cocoa Butter Equivalent Substitution Limits:Technical ceiling on CBE incorporation rates restricts premium positioning against bean-to-bar chocolate in gift confectionery channels.
Strategic Opportunities
- Romanian Greenfield Sites:Underdeveloped compound chocolate capacity in Transylvania and Moldova regions offers first-mover positioning for industrial bakery contract supply.
- EU F-Gas Regulation Tailwind:Refrigeration equipment replacement mandates are creating demand for compound coatings with enhanced thermal stability in ambient storage applications.
- Shea Butter Convergence:Hybrid shea-coconut fat blends are opening premium positioning in French artisan channels seeking differentiated melting profiles.
Industry Challenges
- REACH Compliance Timeline:Extended authorization periods for emulsifier additives are delaying new product launches at German manufacturing facilities.
- Temper-Free Process Engineering:Shortage of coating line technicians capable of calibrating viscosity parameters without traditional tempering protocols constrains plant throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Compound Chocolate Market |
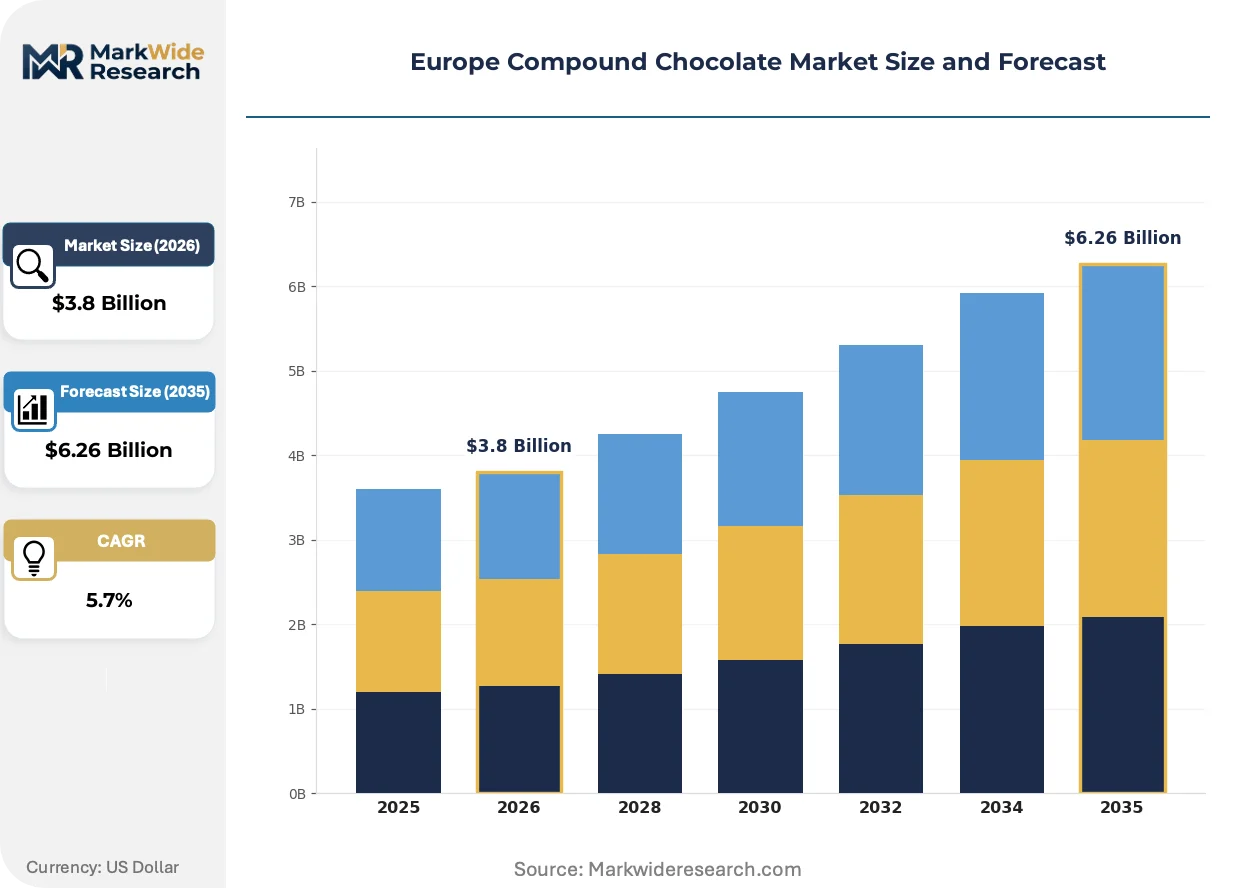
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark, Milk, White, Ruby Application: Baking, Confectionery, Coating, Fillings Distribution Channel: Online, Supermarkets, Convenience Stores, Specialty Stores Customer Type: Retail Consumers, Businesses, Bakeries, Food Service |
| Companies Covered | Nestlé S.A., Lindt & Sprüngli, Barry Callebaut, Puratos Group, Cargill, Mondelez International, Ferrero International, Fuji Oil Group, Mars Incorporated, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Compound Chocolate Market Shifts & Advancements
Formulation science and regulatory compliance are converging to redefine what compound chocolate can claim on European labels. Manufacturers are racing to patent next-generation fat systems before purity criteria harden further.
Shea stearin enrichment technology is hybridizing with traditional palm-based compound matrices to achieve cocoa butter equivalent functionality at lower saturated fat ratios. Italian industrial confectioners are piloting these blends in praline shell applications. The technology is hybridizing cost structures across premium and standard coating tiers, compressing historical price spreads between compound and chocolate proper.
REACH authorization requirements for food-contact emulsifiers are tightening additive approval pathways for Belgian and German manufacturing plants. Industrial consequence includes extended reformulation cycles and accelerated substitution toward naturally sourced lecithin alternatives. Dark compound variants targeting French specialty confectioners are most affected, with smaller producers delaying line extensions pending regulatory clarity.
Direct procurement relationships between industrial bakeries and compound chocolate manufacturers are displacing traditional ingredient distributor intermediaries in Northern European supply chains. Large-scale German frozen pastry operations are negotiating volume contracts with coating specialists for enrobed product lines. This disintermediation is most visible in the Rhine-Ruhr industrial corridor, where centralized bakery procurement functions are consolidating supplier panels.
Europe Compound Chocolate Market Segmentation
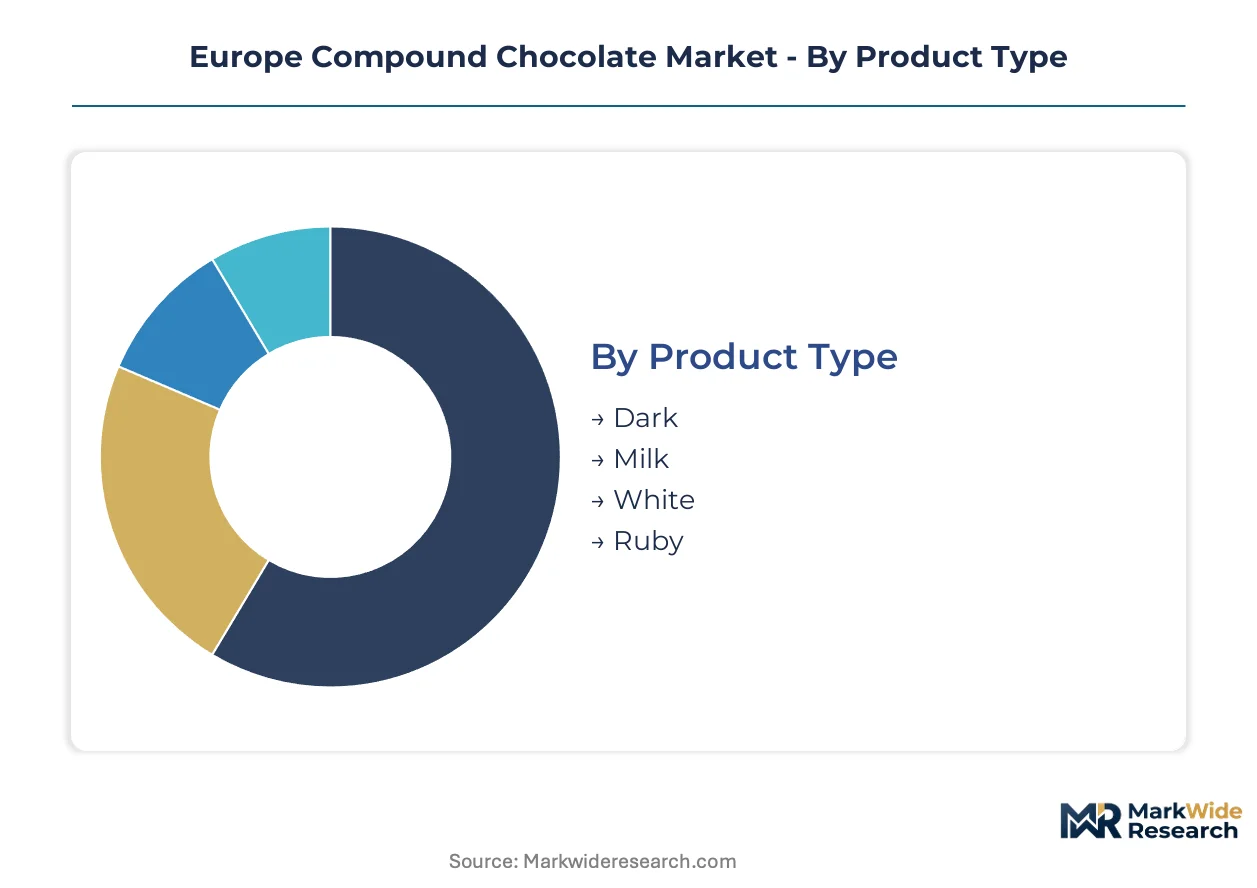
Compound chocolate formulations diverge sharply across European processing clusters based on fat system composition and end-use thermal requirements. Segment boundaries harden as EFSA labeling criteria force clearer distinctions between coating-grade and confectionery-grade specifications.
Product Type:
Cost tier differentiation separates commodity coatings from premium-positioned alternatives capable of cocoa butter equivalent claims.
- Milk:Palm-shea fat blends with 25-35% milk solids deliver the neutral flavor profile and snap stability that German laminated dough manufacturers demand for enrobed pastries. Industrial bakery procurement concentrates in the Rhine-Ruhr corridor, where temper-free processing compatibility drives volume contracts.
- Dark:Higher cocoa powder incorporation (15-25%) combined with reduced sugar ratios positions these formulations for clean-label confectionery channels in France and Belgium. EFSA-compliant vegetable fat labeling enables premium positioning against standard compound coatings in specialty praline applications.
- White:Cocoa butter-free matrices rely entirely on deodorized vegetable fats and dairy solids for flavor delivery, serving decorative bakery applications where color neutrality matters.
- Ruby:Ruby cocoa bean extract formulations without cocoa butter achieve distinctive pink coloration for limited artisan confectionery niches in Italian and Spanish markets.
Milk compound commands the established base across industrial bakery supply chains. The steepest expansion trajectory runs through dark variants as French and Belgian specialty confectioners pursue EFSA-validated clean-label positioning.
Application:
Processing temperature requirements and viscosity control tolerances segment demand across manufacturing equipment types.
- Coating:Enrobing applications demand precise viscosity windows (15-25 Poise at 40°C) and fat bloom resistance that temper-free compound formulations uniquely satisfy. Belgian confectionery belt manufacturers prioritize these specifications for ambient-stable finished goods.
- Baking:Chip and chunk formats for industrial cookie and muffin production require thermal stability through 200°C oven cycles without excessive spread or fat weeping.
- Confectionery:Molding and shell-forming applications in Italian praline manufacturing need sharper melting profiles than coating grades provide.
- Fillings:Cream and ganache-style applications for layered pastries prioritize pumpability and freeze-thaw stability in Northern European frozen bakery operations.
Coating applications anchor volume demand through Belgian and German industrial infrastructure. Baking integration is climbing fastest as Polish and Romanian capacity additions capture frozen pastry contract manufacturing.
Distribution Channel:
Customer scale and procurement centralization determine channel economics across the value chain.
- Online:Direct-to-artisan platforms serving French and Italian specialty confectioners with small-batch coating formulations and technical documentation.
- Supermarkets:Packaged compound chocolate for home baking concentrates in German and UK retail with private-label penetration.
- Convenience Stores:Limited grab-and-go baking ingredient formats with minimal technical support requirements.
- Specialty Stores:Professional-grade products with viscosity specifications and tempering guidance for artisan bakery customers in Belgium and the Netherlands.
Supermarket channels dominate packaged consumer volumes. Online distribution is expanding most quickly as procurement disintermediation accelerates between coating specialists and mid-scale confectioners.
Customer Type:
Volume concentration and formulation complexity split the market between industrial scale and artisan flexibility requirements.
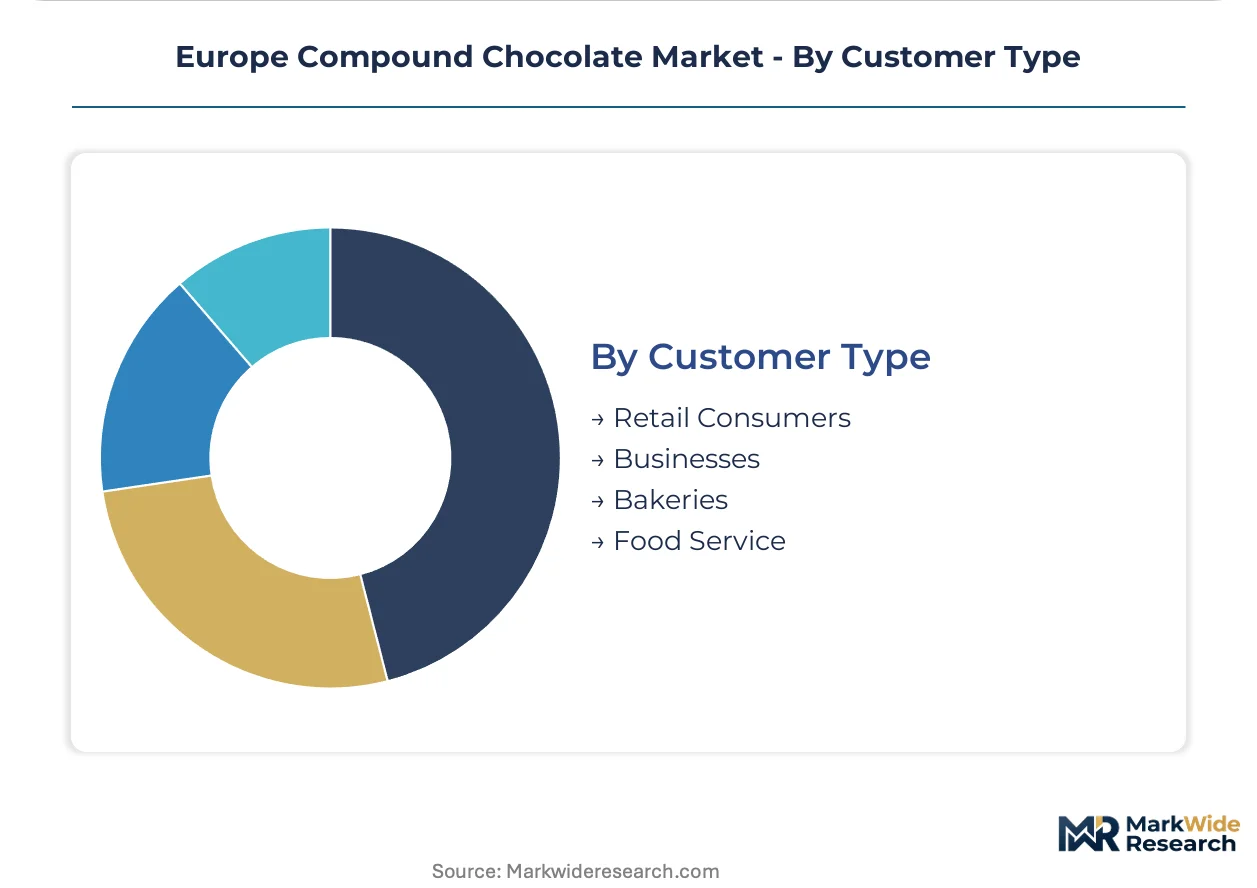
- Businesses:Industrial confectionery manufacturers in Belgium and northern Italy negotiate annual volume contracts with integrated vegetable fat supply guarantees.
- Bakeries:Mid-scale frozen and fresh pastry operations across Germany and Poland require consistent temper-free coating performance for enrobed product lines.
- Food Service:Hotel and restaurant dessert manufacturing in France demands smaller lot sizes with customized melting profiles for plated applications.
- Retail Consumers:Home baking segment with limited technical requirements and price-sensitive purchasing patterns.
Business customers command the volume base through centralized procurement functions. Bakery segment integration is gaining share fastest as Polish industrial capacity captures Western European contract flows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Compound chocolate manufacturing clusters across Western Europe concentrate coating production capacity while Eastern European greenfield investments redraw procurement maps for industrial bakery supply chains.
Belgium
Flanders hosts the densest concentration of compound chocolate processing infrastructure serving enrobing applications for ambient-stable confectionery. EFSA purity criteria enforcement from Brussels headquarters tightens vegetable fat labeling requirements for coating formulations exported across the single market. Antwerp-Ghent corridor manufacturers are expanding temper-free production lines to capture German frozen pastry contract flows.
Germany
Rhine-Ruhr industrial bakeries drive volume demand for milk compound coatings in laminated dough applications where snap stability and neutral flavor profiles matter. REACH compliance timelines at emulsifier authorization delay new product launches at North Rhine-Westphalia manufacturing facilities. Lower Saxony processing plants are retrofitting coating lines for enhanced thermal stability under EU F-Gas Regulation refrigeration mandates.
France
Specialty confectioners in Île-de-France and Auvergne-Rhône-Alpes pursue clean-label dark compound variants with elevated cocoa powder incorporation for praline applications. National clean-label standards emerging from ANSM consultations create regulatory divergence from EU-wide EFSA frameworks. Northern France frozen dessert manufacturers are consolidating procurement panels through direct coating specialist contracts.
Italy
Piedmont and Lombardy industrial confectioners pilot shea stearin enrichment technology in hybrid fat matrices for premium praline shell positioning. ECHA coordination on REACH food-contact additive approvals shapes emulsifier substitution patterns across Italian manufacturing plants. Turin-Milan ingredient corridor facilities are capturing artisan bakery channel demand for specialized compound chocolate drops.
Poland
Lower Silesia and Greater Poland capacity additions capture contract manufacturing flows from Western European brands seeking cost-optimized coating supply. EU F-Gas Regulation equipment replacement cycles create demand for ambient-storage-stable compound formulations at Polish processing plants. Warsaw industrial zone bakeries are scaling enrobed pastry lines with direct procurement from regional coating specialists.
Europe Compound Chocolate Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in fat supply and formulation technology. The European compound chocolate market structures around integrated confectionery conglomerates, independent coating specialists, and vegetable fat processors. Three archetypes dominate: Belgian R&D-anchored formulators, integrated agribusiness suppliers with captive fat streams, and Asian-origin oil processors with European tolling partnerships. Competitive moves concentrate on backward integration into shea and palm fractionation assets, plus geographic expansion into Romanian and Polish greenfield capacity.
Among the integrated processing tier, Barry Callebaut and Cargill exemplify divergent strategic positions. Barry Callebaut occupies the R&D-intensive formulator archetype through Belgian infrastructure. Cargill represents the agribusiness-integrated model with upstream vegetable fat supply chain control. Puratos Group sits within the artisan-channel specialist tier, anchoring mid-scale bakery applications with technical service differentiation.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Lindt & Sprüngli |
| Barry Callebaut |
| Puratos Group |
| Cargill |
| Mondelez International |
| Ferrero International |
| Fuji Oil Group |
| Mars Incorporated |
| Others |
Supply & Pricing Matrix
Rotterdam-Hamburg vegetable oil freight corridors transmit crude palm oil price volatility directly into Belgian coating formulation costs, compressing margin predictability for manufacturers while enabling downstream price stratification between commodity and EFSA-validated premium tiers.
Pricing Analysis
EFSA purity criteria dictate the pricing tier structure across European compound chocolate supply chains. Three-tier pricing structure across premium, standard, and economy levels separates clean-label dark formulations with elevated cocoa powder from commodity milk coatings and basic white matrices. Cost compression in economy tiers is intensifying because Rotterdam palm oil futures fluctuations transmit directly into vegetable fat-dependent formulations. Industrial bakery procurement teams in Germany demonstrate highest price sensitivity through centralized volume contracting, while French artisan confectioners accept premium positioning for EFSA-compliant labeling differentiation.
Supply Chain Analysis
Vegetable fat feedstock supply draws from Malaysian and Indonesian palm oil plantations, West African shea butter cooperatives, and Philippine coconut oil processors. Raw material dependencies center on crude palm oil futures, shea stearin fractionation outputs, and deodorized coconut oil shipments. Single-source vulnerability concentrates in Flanders corridor infrastructure where Belgian processing plants handle disproportionate European coating volume. Distribution runs through direct procurement relationships displacing traditional ingredient distributor intermediaries in Northern European supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA regulatory tightening is reshaping compound chocolate as a high-growth disruption where clean-label formulation patents determine competitive survival. The analysis window rewards early movers securing shea stearin enrichment technology and Romanian greenfield positioning.
For Market Incumbents: Pre-empt Polish and Romanian capacity additions by securing backward integration into shea fractionation assets before feedstock costs harden. Defend Belgian R&D infrastructure against emerging coating specialists through accelerated patent filings on hybrid fat matrices. Prioritize REACH-compliant emulsifier substitution pathways to outpace authorization delays affecting German manufacturing competitors.
For New Entrants and Emerging Players: Build out Transylvania and Moldova greenfield sites to capture industrial bakery contract manufacturing flows seeking cost-optimized supply outside Flanders concentration. Target Romanian frozen pastry channels with ambient-storage-stable formulations optimized for EU F-Gas Regulation equipment replacement cycles. Lead with direct technical service models that bypass established distributor relationships in Warsaw and Kraków industrial zones.
For Investors and Strategic Acquirers: Carve-out targets emerge from agribusiness conglomerates with captive vegetable fat streams but underdeveloped European coating formulation capabilities. Long-term viability hinges on regulatory compliance infrastructure rather than commodity scale alone. Watch for EFSA enforcement actions against non-compliant labeling as the inflection signal separating premium-positioned from distressed assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Shea Stearin Backward Integration | Captive supply of premium fat fractions secures EFSA-compliant clean-label positioning against palm-dependent competitors. |
| Romanian Greenfield Capacity | First-mover positioning in Transylvania captures industrial bakery contract flows seeking Flanders supply diversification. |
| REACH-Compliant Emulsifier Substitution | Natural lecithin alternatives accelerate product launch timelines where German competitors face authorization delays. |
| Direct Procurement Platform Launch | Bypassing distributor intermediaries in Rhine-Ruhr corridor captures margin from disintermediating industrial bakery accounts. |
| Hybrid Fat Matrix Patent Filing | Shea-coconut blend intellectual property creates defendable premium tier against commodity coating price erosion. |
Research Methodology
A standing panel of compound chocolate plant managers, industrial bakery procurement directors, vegetable fat supply specialists, and EFSA regulatory affairs consultants provided ongoing calibration against secondary validation. Primary fieldwork combined structured interviews with coating formulation R&D heads and distribution channel partners across Belgian, German, and Polish processing clusters. Secondary sources included EFSA purity criteria documentation, REACH authorization databases, EU F-Gas Regulation implementation guidance, and customs trade flows for vegetable oil feedstocks. Bottom-up volume modeling triangulated against top-down market sizing across product type, application, and customer segment dimensions.
Scenario-bracketing anchored projections across the analysis window with low, base, and high cases reflecting regulatory enforcement variance and feedstock price trajectory assumptions. Segmentation modeling captured product type splits, application thermal requirements, distribution channel economics, and customer scale procurement patterns. CAGRs derived from volume trajectory analysis incorporating industrial bakery capacity expansion pipelines and confectionery belt coating demand forecasts. Industry-specific inputs included shea stearin enrichment technology adoption curves and EU F-Gas Regulation equipment replacement cycle timing.
Practitioners should monitor EFSA enforcement intensity, palm oil futures volatility spikes, and Romanian capacity utilization rates for early signals requiring forecast revision. Cross-checking against European Cocoa Association production statistics and Cefic chemical industry output indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Asia Pacific and Latin America Sugar Confectionery Market
Confectionery
Gum Base Candy Market
Confectionery
Vegan Chocolate Confectionery Market
Confectionery
Chocolate Confectionery Market
Confectionery
Europe Chocolate Market
Confectionery
Organic Chocolate Confectionery Market
Confectionery
Europe Dark Chocolate Market
Confectionery
US Confectionery Market
Confectionery
Chocolate Couverture Market
Confectionery
United Arab Emirates Chocolate Market
Confectionery
North America Compound Chocolate Market
Confectionery
Liquorice Shellac Market
Confectionery
Green Tea Chocolate Market
Confectionery
North America Gummy Market
Confectionery
Low-Fat Dark Chocolate Market
Confectionery
Italy Chocolate Market