
 Underwater Robot Market | 2026-2036
Underwater Robot Market Size, Share, and Industry Trends Forecast 2026-2036
Underwater Robot Market Outlook
Market Context with Strategic Players
Norway is tilting the competitive map through concentrated subsea engineering capacity around Kongsberg and Stavanger. Kongsberg Maritime leverages decades of sonar and autonomous navigation heritage to dominate deep-water AUV contracts. Teledyne Marine anchors North American supply chains through its vertically integrated sensor-to-platform manufacturing footprint. ECA Group specializes in mine-countermeasure robotics, sustaining European defense procurement pipelines against Asian price competition.
Technical Definition and Structural Segments
Underwater robots are untethered or tethered electromechanical systems operating at depths from shallow coastal zones to full ocean trenches, typically incorporating pressure-resistant hulls, acoustic positioning arrays, and multi-beam sonar payloads for tasks beyond human diver endurance. ROV platforms retain the largest installed base across offshore energy, yet AUV segments capture disproportionate R&D allocation due to elimination of surface support vessels and umbilical costs. Within end-user demand, Oil and Gas procurement still occupies the dominant revenue share, though Environmental Monitoring applications are accelerating fastest as seabed carbon storage verification and marine protected area enforcement expand.
Regulatory Frame and Forward Outlook
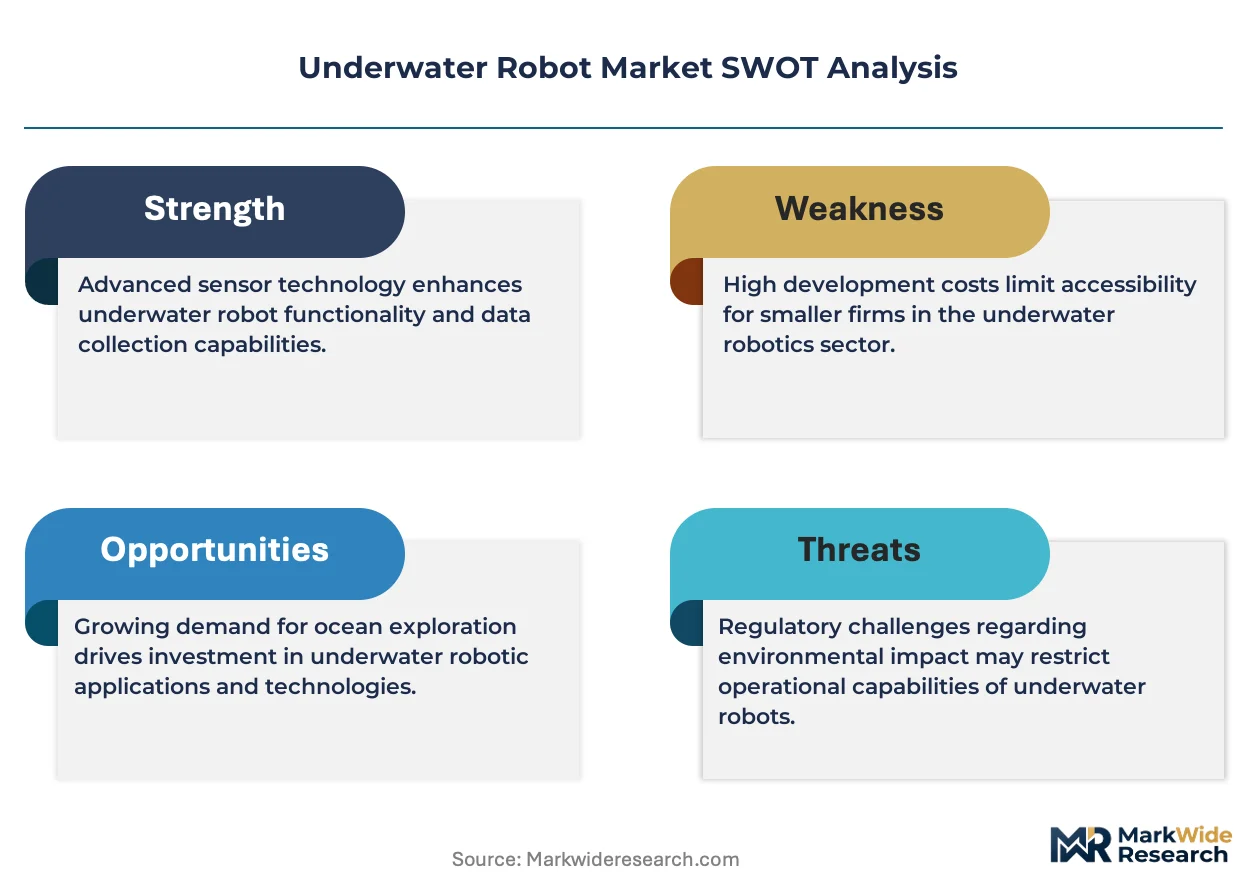
The International Maritime Organization's subsea cable protection guidelines, the U.S. FAA's overlapping jurisdiction on surface-launch drone vessels, and Norway's Petroleum Safety Authority well-intervention standards collectively shape platform certification requirements and operational liability frameworks. The EU's Marine Strategy Framework Directive is tightening seabed disturbance thresholds, pushing manufacturers toward lower-acoustic-signature propulsion and biodegradable lubricant systems. Stakeholders must weigh regulatory compliance costs against the operational savings of fully autonomous platforms when rebuilding fleet procurement models.
Market Dynamics
The International Seabed Authority's tightening extraction moratoriums are redirecting capital flows from mining robotics toward inspection and monitoring platforms, compressing development timelines for non-extractive applications.
Growth Catalysts
- Subsea Carbon Storage Verification:Norway's Petroleum Safety Authority mandates continuous seabed integrity monitoring for CO2 injection sites, forcing operators to deploy autonomous inspection fleets.
- REACH Biodegradable Lubricant Standards:The ECHA's environmental compliance deadlines are accelerating propulsion system redesigns across European manufacturers.
- Kongsberg-Horten Cluster Effect:Concentrated subsea engineering talent in Norway's technology corridor is shortening R&D iteration cycles for deep-water navigation systems.
Market Restraints
- Titanium Alloy Supply Concentration:Pressure hull fabrication depends on Russian and Chinese sponge titanium, exposing procurement to geopolitical disruption.
- Acoustic Positioning Infrastructure Gaps:Sparse seabed beacon networks beyond North Sea and Gulf of Mexico installations limit AUV operational range.
- FAA Surface-Launch Jurisdiction Overlap:US operators face dual certification requirements for drone vessels, extending deployment timelines.
Strategic Opportunities
- Marine Protected Area Enforcement:The EU Marine Strategy Framework Directive's disturbance thresholds create mandated demand for low-signature monitoring platforms.
- AI-Enhanced Sonar Fusion:Machine learning integration with multi-beam bathymetry is opening new contract categories for real-time seabed classification.
- India Port Infrastructure Modernization:The country's Sagarmala initiative is generating first-time demand for hull inspection robotics at minor ports.
Industry Challenges
- Subsea Software Engineering Talent Scarcity:Acoustic navigation algorithm development requires specialized skill sets concentrated in Norway and Scotland.
- ISO 13628-8 Certification Timelines:Subsea production control system qualification extends platform commercialization by 18-24 months.
- Legacy ROV Fleet Integration:Tethered platform operators resist full AUV adoption due to sunk capital in surface support vessels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Underwater Robot Market |
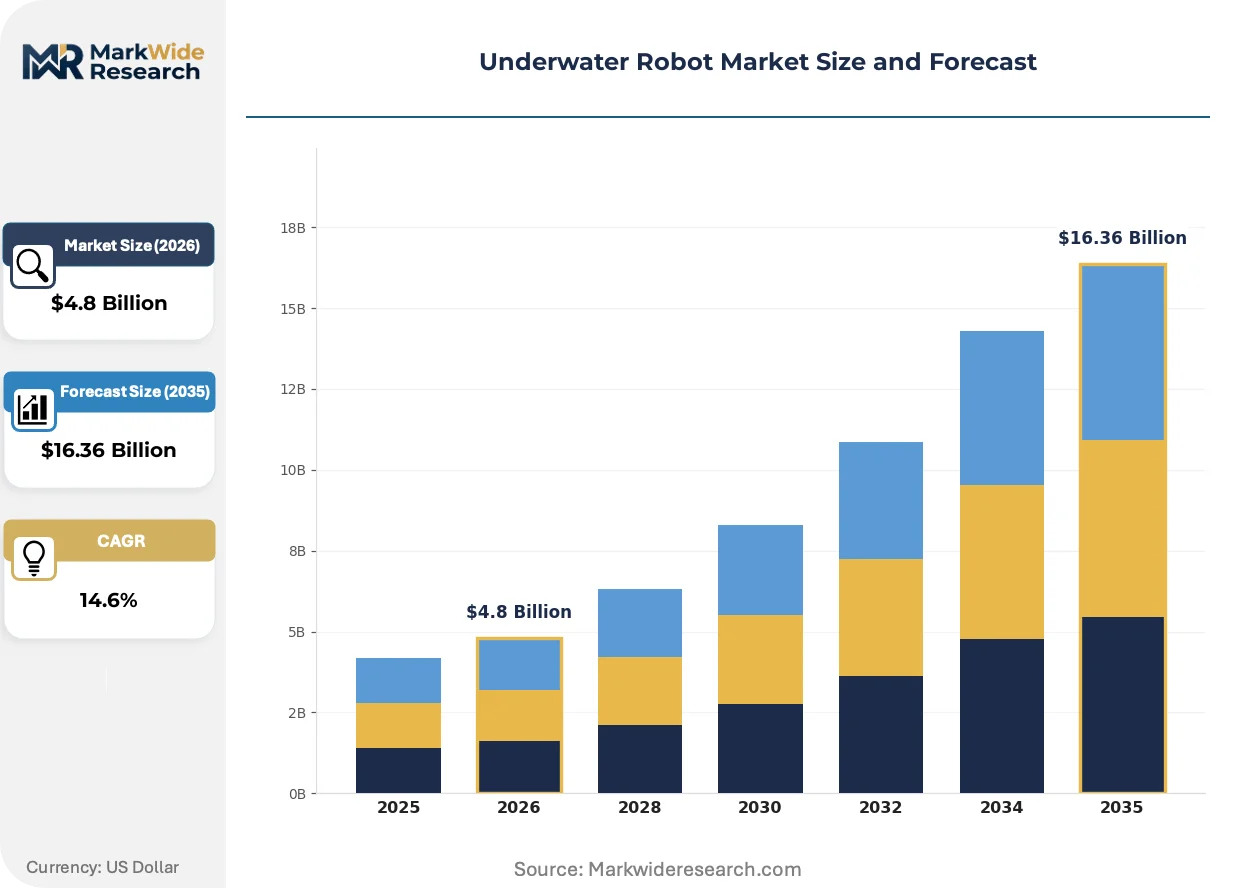
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AUV, ROV, Hybrid, UUV Application: Surveillance, Inspection, Research, Maintenance End User: Oil & Gas, Marine Research, Defense, Environmental Monitoring Technology: Navigation, Communication, Propulsion, Imaging |
| Companies Covered | Kongsberg Maritime, Blue Robotics, Teledyne Marine, Ocean Infinity, ECA Group, Oceaneering International, Fugro, Lockheed Martin Corporation, Saab, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Underwater Robot Market Strategic Shifts
Autonomous navigation architectures are compressing the operational cost gap between tethered and untethered platforms, forcing incumbents to accelerate software-centric differentiation.
Digital twin technology is digitizing subsea asset condition monitoring by creating persistent virtual replicas of pipeline and wellhead infrastructure. Offshore operators in Norway and the UK are deploying these systems for predictive maintenance scheduling. The technology is digitizing inspection workflows, reducing vessel-day requirements by eliminating redundant physical surveys.
The EU's CSRD sustainability disclosure rules are mandating granular seabed impact reporting for offshore energy operators. This regulatory pressure is accelerating sensor payload standardization across European AUV fleets. Environmental monitoring contracts now specify CSRD-aligned data formats, privileging manufacturers with integrated reporting software.
Leasing arrangements for inspection platforms are displacing traditional capital purchase models among mid-sized offshore contractors. Equipment providers in Aberdeen and Houston are restructuring offerings around vessel-day availability guarantees rather than unit sales. This shift is most pronounced in the North Sea decommissioning segment, where project-specific demand spikes favor operational flexibility over fleet ownership.
Underwater Robot Market Segmentation
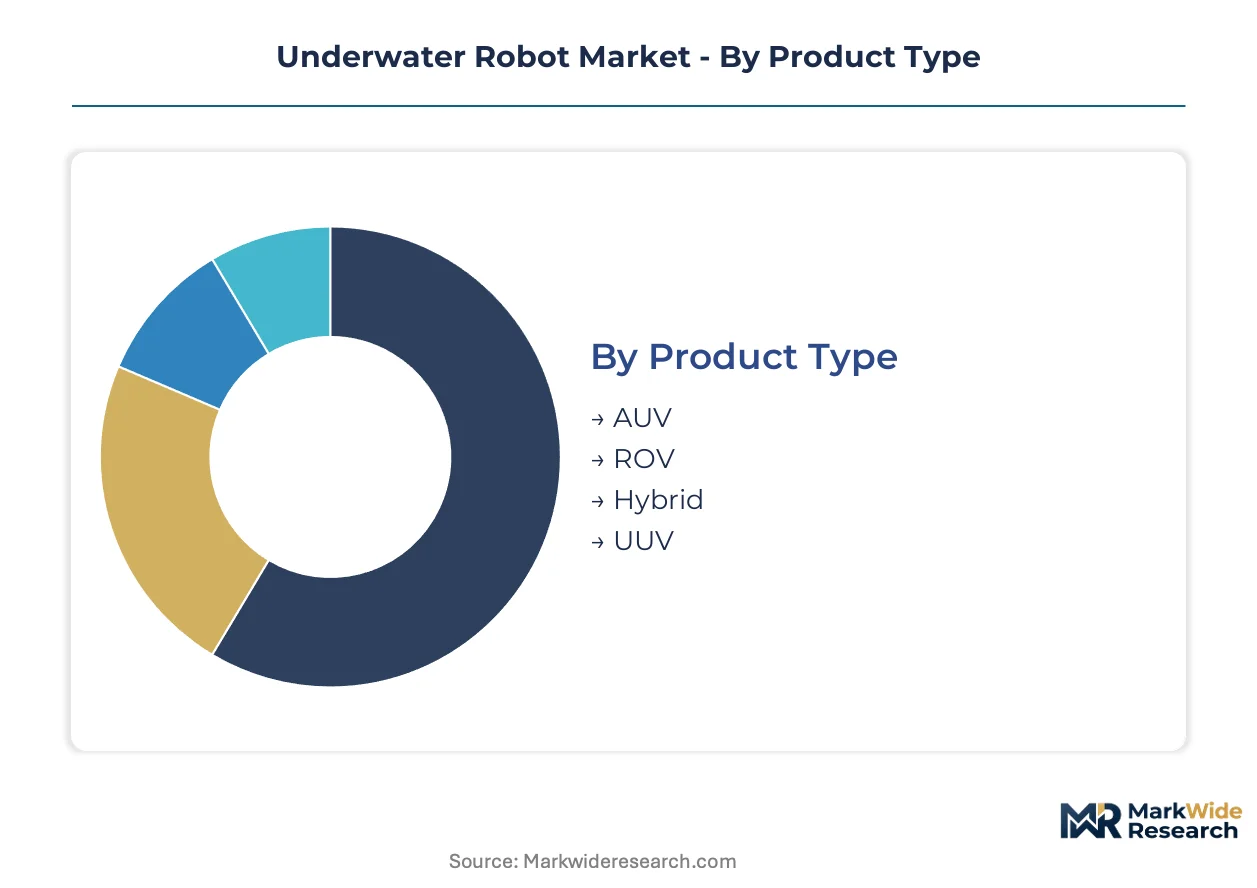
Segmentation reveals how underwater robot procurement splits across operational architectures, mission profiles, and institutional buyers. Each dimension carries distinct certification requirements, pricing logic, and vendor specialization that shape competitive positioning.
Product Type:
The use-case spectrum spans fully autonomous seabed surveys to human-piloted intervention tasks, with hybrid architectures emerging at the boundary.
- ROV:Tethered electromechanical platforms with real-time pilot control via umbilical cable, rated for depths exceeding 6,000 meters in work-class configurations. Demand concentrates in the Gulf of Mexico and Brazil's pre-salt basins where Petrobras and Shell deploy fleets for wellhead intervention and pipeline repair, constrained by surface vessel day-rate economics that compress contract margins.
- AUV:Untethered battery-powered vehicles executing pre-programmed mission profiles with acoustic navigation and onboard data storage. Norway's Equinor and the UK's BP are expanding AUV fleets for carbon storage site monitoring, eliminating umbilical costs and reducing vessel requirements by over 60% compared to ROV operations.
- Hybrid:Modular platforms switching between tethered precision work and autonomous transit modes through detachable fiber-optic tethers. Japan's JAMSTEC and Australia's CSIRO deploy these for deep-ocean research stations requiring both survey coverage and sample retrieval flexibility.
- UUV:Military-optimized variants with mine-countermeasure and intelligence-gathering payloads, subject to ITAR and national security classification restrictions that fragment supplier bases.
The dominant share belongs to ROV, while AUV is closing the gap fastest as autonomous navigation reliability improves.
Application:
Cost tier differentiation separates capital-intensive infrastructure work from recurring monitoring contracts and grant-funded science missions.
- Inspection:Systematic assessment of subsea pipelines, risers, and wellheads using multi-beam sonar and cathodic potential sensors, generating recurring revenue through annual integrity management contracts. Norway's Petroleum Safety Authority mandates continuous inspection for CO2 injection infrastructure, creating regulatory-locked demand streams.
- Surveillance:Persistent seabed monitoring for cable protection, marine protected area enforcement, and unauthorized activity detection, requiring low-acoustic-signature platforms to avoid disturbance violations under the EU Marine Strategy Framework Directive.
- Maintenance:Intervention tasks including valve operation, debris removal, and anode replacement, still dominated by ROV platforms due to manipulator precision requirements and real-time human decision loops.
- Research:Academic and governmental oceanographic data collection with extended endurance requirements, funded through national science budgets subject to multi-year appropriation cycles.
Inspection commands the largest revenue pool, though surveillance is expanding most quickly as marine spatial planning tightens.
End User:
Customer type determines procurement sophistication, with oil majors driving standardization and defense buyers prioritizing security over cost.
- Oil & Gas:Integrated supermajors and national oil companies operating fixed and floating production assets, specifying ISO 13628-8 compliant platforms with integrated digital twin data feeds. Norway's Equinor and the UK's Harbour Energy dominate fleet renewal cycles.
- Defense:Naval mine countermeasure programs and seabed warfare units in France, the UK, and Australia, procuring through defense acquisition frameworks with multi-year development timelines and classified performance specifications.
- Marine Research:Oceanographic institutes including WHOI, Scripps, and the UK's NOC, relying on grant funding with equipment depreciation schedules spanning 15-20 years.
- Environmental Monitoring:Carbon storage operators, offshore wind developers, and marine protected area managers, a segment accelerating as CSRD disclosure rules mandate granular seabed impact reporting.
Oil & Gas retains the dominant procurement volume, while Environmental Monitoring is climbing the fastest as regulatory disclosure requirements multiply.
Technology:
Supply concentration in acoustic and optical subsystems creates vendor lock-in effects that propagate through platform integration.
- Navigation:Inertial measurement units fused with Doppler velocity logs and long-baseline acoustic positioning, with Kongsberg Maritime and Teledyne Marine controlling core sensor supply through proprietary array geometries.
- Imaging:Multi-beam sonar, side-scan sonar, and sub-bottom profiler payloads generating bathymetric and sediment classification data, with resolution specifications driving 40% of platform cost at the high end.
- Communication:Acoustic modems and optical downlinks for tethered platforms, with bandwidth limitations constraining real-time video quality and AI processing offload.
- Propulsion:Brushless DC thrusters and biomimetic fin drives, with REACH biodegradable lubricant standards forcing European manufacturers into redesign cycles.
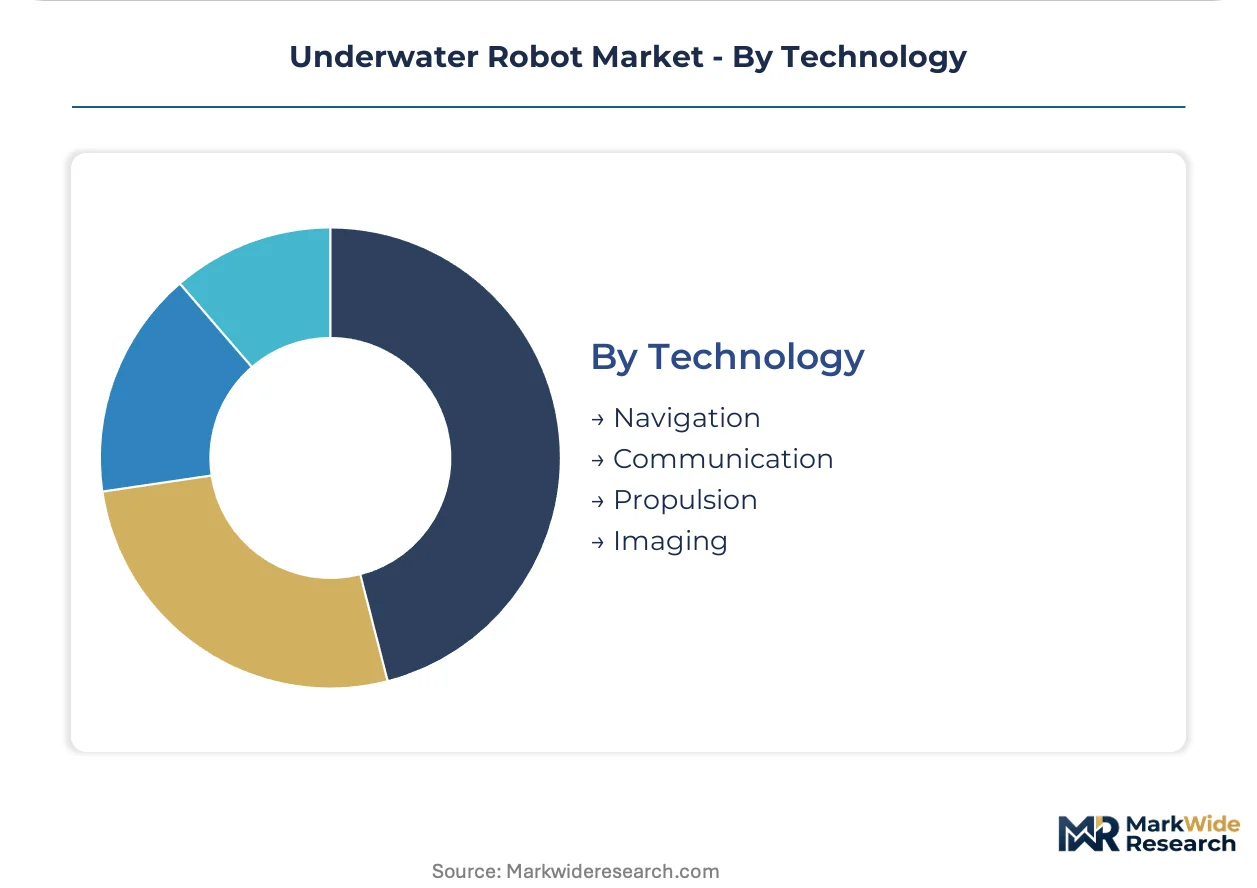
Navigation technology captures the largest subsystem value, though Imaging is gaining share fastest as seabed classification AI creates new performance tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform integrators cluster in Norway's deep-water technology corridor, while component manufacturing concentrates in North America and East Asia. This geographic split shapes procurement patterns and regulatory compliance pathways across major operational theaters.
Norway
Equinor's carbon storage mandates and North Sea decommissioning contracts drive AUV fleet expansion. The Petroleum Safety Authority enforces continuous seabed integrity monitoring for CO2 injection infrastructure. Kongsberg and Horten host concentrated subsea engineering talent pools that compress R&D iteration cycles for autonomous navigation systems.
United States
Deep-water operators in the Gulf of Mexico deploy work-class ROV fleets for wellhead intervention and pipeline repair. The FAA's overlapping jurisdiction on surface-launch drone vessels creates dual certification requirements that extend deployment timelines. Houston anchors North American supply chains through equipment leasing hubs serving mid-sized offshore contractors.
United Kingdom
BP and Harbour Energy accelerate AUV adoption for North Sea carbon storage site verification. The EU Marine Strategy Framework Directive's seabed disturbance thresholds push operators toward low-acoustic-signature platforms. Aberdeen's decommissioning specialists favor leasing arrangements over capital purchases due to project-specific demand spikes.
Japan
JAMSTEC deploys hybrid platforms for deep-ocean research stations requiring both survey coverage and sample retrieval flexibility. METI funding cycles support extended endurance requirements for academic and governmental oceanographic data collection. Tokyo-Yokohama corridors concentrate marine robotics component fabrication for regional export markets.
Australia
CSIRO utilizes hybrid architectures for persistent seabed monitoring across marine protected areas. The country's national environmental regulator enforces strict disturbance thresholds that privilege low-signature monitoring platforms. Perth anchors Indo-Pacific service operations for offshore energy contractors operating across Southeast Asian basins.
Underwater Robot Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream controlling sensor and navigation subsystem supply. Market structure tilts toward consolidation among full-stack providers while acoustic positioning and imaging module vendors retain concentrated supply positions. Three archetypes dominate: defense-anchored conglomerates with mine-countermeasure legacies, oilfield service spinoffs with vessel integration capabilities, and pure-play autonomy specialists with software-centric differentiation. Competitive moves center on strategic partnerships for seabed data analytics integration and capacity expansion in Norwegian deep-water engineering clusters.
Among Norway-based platform integrators, Kongsberg Maritime occupies a position exemplifying sonar heritage and autonomous navigation dominance. Teledyne Marine anchors North American supply chains through vertically integrated sensor-to-platform manufacturing. ECA Group represents the European defense procurement pipeline archetype, sustaining mine-countermeasure robotics against Asian price competition.
| Leading Market Players |
|---|
| Kongsberg Maritime |
| Blue Robotics |
| Teledyne Marine |
| Ocean Infinity |
| ECA Group |
| Oceaneering International |
| Fugro |
| Lockheed Martin Corporation |
| Saab |
| Others |
Value Chain & Pricing Dynamics
The North Sea offshore logistics corridor carries titanium alloy pressure hull components from Russian and Chinese sponge sources through Norwegian fabrication hubs, with freight cost volatility amplifying procurement spreads between ISO 13628-8 certified premium tiers and standard-grade platforms while compressing margins for mid-sized contractors lacking scale purchasing power.
Pricing Analysis
REACH biodegradable lubricant standards dictate the pricing tier structure across European procurement, separating REACH-compliant premium navigation systems from legacy standard tiers and economy-grade inspection rentals. Price differentiation rests on certification grade and acoustic sensor resolution, with CSRD-aligned environmental reporting bundles commanding premiums. Pricing pressure stems from leasing arrangements displacing capital purchases among Aberdeen and Houston contractors. Mid-sized offshore contractors exhibit highest price sensitivity, while Equinor and BP prioritize performance guarantees over unit cost.
Supply Chain Analysis
Teledyne Marine and Kongsberg Maritime control contract-manufacturing capacity for acoustic positioning arrays and multi-beam sonar modules, with final platform integration concentrating in Norway, the United States, and Japan. Raw material dependencies draw from Russian and Chinese titanium sponge, Japanese pressure vessel ceramics, and Norwegian composite hull fabrication. Single-source vulnerability in seabed beacon networks beyond North Sea and Gulf of Mexico installations constrains AUV operational range expansion. Distribution runs through equipment leasing hubs in Aberdeen and Houston serving project-specific offshore contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Underwater robotics is approaching a platform-economics inflection where autonomous navigation software stacks are decoupling from hardware hulls, with Kongsberg Maritime's open architecture APIs enabling third-party sensor fusion modules to interoperate across fleet operators.
For Market Incumbents: Harden defensive positions through captive control of acoustic positioning sensor supply and accelerated certification investment in Norway's Petroleum Safety Authority compliance frameworks. Vertical integration into titanium alloy pressure hull fabrication mitigates geopolitical disruption exposure from Russian and Chinese sponge concentration. Channel control through vessel-day availability guarantees locks in mid-sized contractor relationships against pure-play autonomy specialists.
For New Entrants and Emerging Players: Build out white-space presence in India's Sagarmala port infrastructure modernization, where first-time hull inspection robotics demand lacks established vendor relationships. Marine protected area enforcement across Australian and EU jurisdictions offers penetrable regulatory-mandated demand with lower incumbent saturation. A software-centric go-to-market angle targeting CSRD-aligned environmental reporting integration bypasses capital-intensive platform manufacturing barriers.
For Investors and Strategic Acquirers: Carve-out targets emerge from oilfield service conglomerates spinning off subsea robotics divisions amid fleet electrification pressures. Long-term viability over the next decade hinges on autonomous navigation reliability displacing tethered ROV economics. Watch for inflection signals in FAA surface-launch certification streamlining that would compress dual-jurisdiction deployment timelines for US operators.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enhanced Sonar Fusion Development | Machine learning integration with Kongsberg multi-beam systems opens real-time seabed classification contracts. |
| Biodegradable Lubricant System Redesign | REACH compliance deadlines force European propulsion manufacturers into 18-month redesign cycles. |
| Leasing Model Expansion | Vessel-day availability guarantees in Aberdeen displace capital purchases among decommissioning specialists. |
| Carbon Storage Verification Fleet Deployment | Norway's Petroleum Safety Authority mandates create regulatory-locked demand streams for AUV operators. |
| Acoustic Positioning Infrastructure Buildout | Sparse seabed beacon networks beyond North Sea and Gulf of Mexico constrain AUV operational range. |
Study Parameters
Desk research of SEC filings from offshore energy contractors, International Seabed Authority regulatory dockets, and EU Marine Strategy Framework Directive implementation guidelines preceded structured interviews with AUV fleet managers at Equinor and BP, subsea engineering directors at Kongsberg Maritime, and procurement leads at Aberdeen decommissioning specialists. Secondary validation drew from Norwegian Petroleum Safety Authority inspection records, Teledyne Marine product specification databases, and customs data on titanium alloy imports. Bottom-up platform deployment counts were triangulated against top-down offshore energy capital expenditure allocations.
Assumptions held fixed include continued REACH biodegradable lubricant enforcement timelines, FAA surface-launch jurisdiction overlap persistence, and titanium alloy supply concentration from Russian and Chinese sources. Variables stress-tested across the analysis window encompass International Seabed Authority extraction moratorium extensions, acoustic positioning infrastructure deployment rates, and AI-enhanced sonar fusion commercialization timelines. Segmentation dimensions modeled span product architecture, application mission profile, end-user procurement sophistication, and technology subsystem integration depth. CAGRs were derived from fleet replacement cycle analysis and regulatory mandate compliance deadlines.
Stress conditions across titanium supply disruption scenarios, FAA certification streamlining timelines, and seabed mining regulation redirection were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these bounded assumptions with revision triggers tied to geopolitical supply shocks or autonomous navigation reliability breakthroughs. Quarterly review of AUV fleet deployment announcements, REACH compliance certification timelines, and carbon storage site monitoring contract awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Asrs and Ruos Market
Robotics and Automation
Global Security Robots Market
Robotics and Automation
GCC AUV Market
Robotics and Automation
Robotic Lawn Mower Market
Robotics and Automation
Bot Services Market
Robotics and Automation
Cleaning Robot Market
Robotics and Automation
Inspection Robots Market
Robotics and Automation
Agricultural Robots Market
Robotics and Automation
Global Educational Robots Market
Robotics and Automation
Solar Panel Cleaning Robot Market
Robotics and Automation
Simultaneous Localization and Mapping (SLAM) Technology Market
Robotics and Automation
Global Underwater Robotics Market
Robotics and Automation
Africa Cloud Robotics Market
Robotics and Automation
Medical Robotics Market
Robotics and Automation
High-Precision Truss Robot Market
Robotics and Automation
North America Service Robotics Market