
 North America Service Robotics Market | 2026-2036
North America Service Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Service Robotics Market Analytics
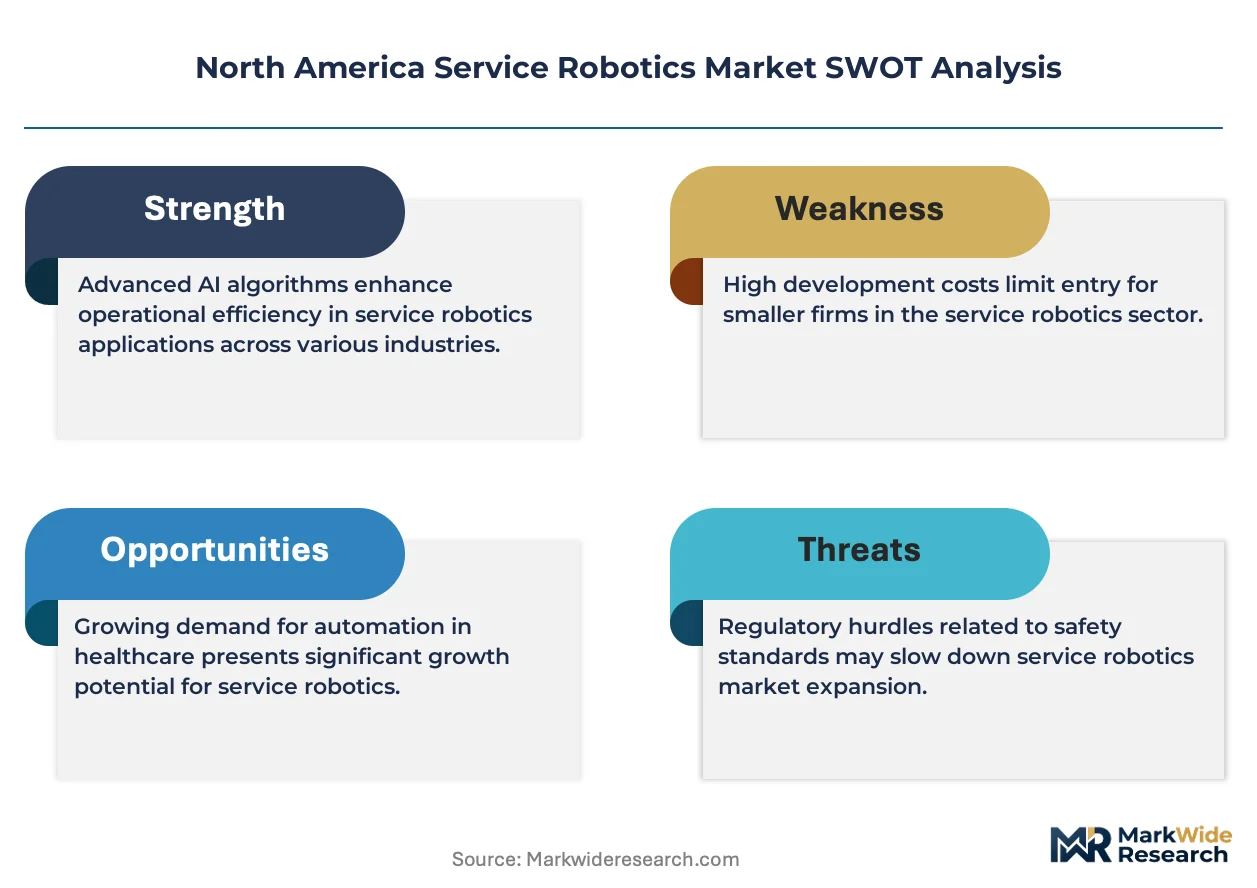
Aging maintenance technicians and scarce mechatronics graduates is reorganizing deployment timelines across North American manufacturing and logistics sectors. Intuitive Surgical sustains dominance in minimally invasive robotic platforms through captive training networks and hospital credentialing programs. Boston Dynamics differentiates with legged locomotion systems that navigate unstructured warehouse and construction terrain where wheeled platforms fail.
North America service robotics encompasses autonomous or semi-autonomous electromechanical systems operating outside traditional factory automation, typically integrating sensor fusion, real-time path planning, and human-robot interaction protocols to execute tasks in unstructured environments. Professional robots command the largest revenue share as hospitals and distribution centers replace legacy equipment with autonomous mobile platforms. Delivery services within the application dimension represent the fastest expansion vector, though security surveillance retains higher margin pools due to recurring software subscription structures and federal procurement premiums.
The U.S. Food and Drug Administration regulates surgical and therapeutic robots under Class II and Class III device pathways, while the Federal Aviation Administration governs aerial delivery platforms through Part 135 certification requirements. Health Canada's Medical Devices Directorate maintains parallel approval standards that Canadian vendors must satisfy for cross-border commercialization. Stakeholders must monitor how OSHA's emerging workplace robotics safety guidelines will reshape liability frameworks and insurance requirements for deployed fleets.
Market Dynamics
Workforce demographics and regulatory classification uncertainty are compressing deployment timelines across North American healthcare and logistics sectors. Hospitals and distribution centers face simultaneous pressure to automate aging infrastructure while navigating evolving FDA device pathways and OSHA safety protocols.
Growth Catalysts
- Healthcare labor shortages:Surgical and rehabilitation facilities are expanding robotic-assisted procedures to offset retiring specialized nursing staff and reduce procedure variability.
- FAA Part 135 certification expansion:Aerial delivery platforms are securing beyond-visual-line-of-sight waivers, enabling last-mile automation in suburban and rural corridors previously unreachable by ground fleets.
- California's robotics corridor concentration:Venture deployment and mechatronics talent clustering in the San Francisco-San Jose axis is accelerating commercialization timelines for humanoid and legged systems.
Market Restraints
- Lithium-ion battery supply concentration:Cell production for mobile robot powertrains depends heavily on Asian cathode supply chains, exposing fleet operators to input cost volatility and forced stockpiling.
- FDA Class III pathway duration:Autonomous surgical systems face 18-36 month premarket approval timelines that freeze R&D capital and delay revenue recognition for therapeutic robot developers.
- Legacy warehouse management system incompatibility:Proprietary WMS architectures in installed base facilities block seamless AMR integration without expensive middleware development.
Strategic Opportunities
- Mexican nearshoring corridors:Manufacturing automation demand in Monterrey and Tijuana is outpacing local integrator capacity, creating first-mover openings for U.S.-based service robot vendors with Spanish-language support infrastructure.
- OSHA workplace robotics guidelines:Anticipated federal safety standards will mandate fleet monitoring and collision-avoidance certification, advantaging vendors with pre-compliant sensor architectures.
- 5G edge computing convergence:Ultra-reliable low-latency connectivity is enabling cloud-offloaded path planning for construction and agricultural robots previously constrained by onboard processing limits.
Industry Challenges
- Mechatronics technician scarcity:Community college programs cannot graduate field service engineers fast enough to support deployed fleet maintenance across multi-state hospital networks.
- Cross-border Health Canada synchronization:Canadian commercialization requires parallel Medical Devices Directorate filings that duplicate FDA documentation without mutual recognition, stretching regulatory affairs teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Service Robotics Market |
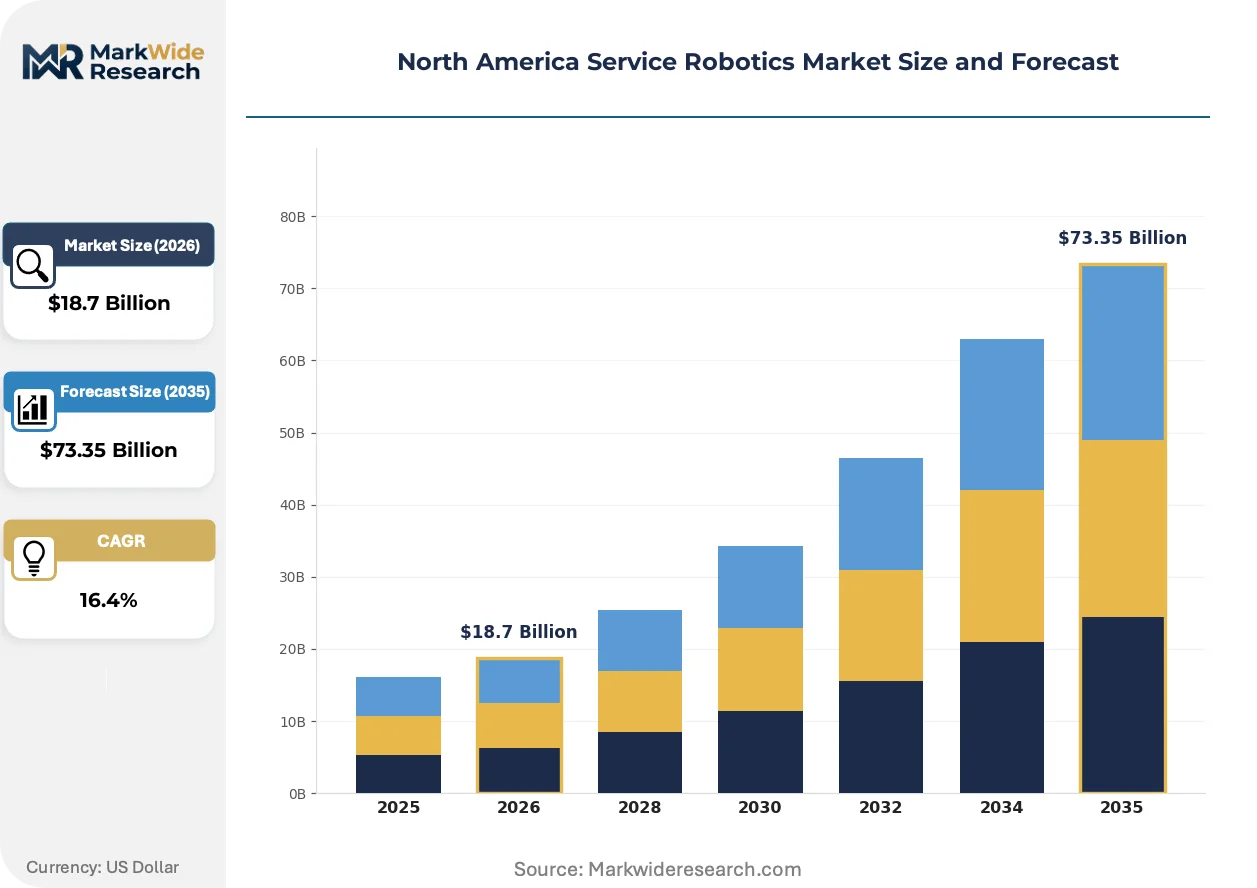
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Domestic Robots, Professional Robots, Commercial Robots, Industrial Robots End User: Healthcare Facilities, Retail Stores, Hospitality Industry, Educational Institutions Application: Telepresence, Delivery Services, Cleaning Services, Security Surveillance Technology: Artificial Intelligence, Machine Learning, Sensor Technology, Navigation Systems |
| Companies Covered | Northrop Grumman Corporation, Brain Corp, iRobot Corporation, Aethon Inc., Fetch Robotics, Intuitive Surgical, Inc., Stryker Corporation, GeckoSystems International Corporation, Boston Dynamics, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Service Robotics Market Evolving Landscape
Sensor fusion architectures and human-robot interaction protocols are redefining operational boundaries for systems deployed in unstructured environments. The competitive frontier is shifting from hardware specifications to software-defined adaptability and fleet orchestration capabilities.
Multimodal perception stacks combining LiDAR, depth cameras, and tactile arrays are fragmenting traditional single-sensor navigation approaches. Hospital surgical suites and warehouse fulfillment centers are adopting these layered sensing systems to handle dynamic obstacle environments. The technology is fragmenting vendor market positions by enabling smaller players to compete on scene understanding without proprietary hardware investments.
OSHA's emerging workplace robotics safety guidelines are forcing liability restructuring across deployed fleets. Insurance underwriters are demanding collision-avoidance certification and real-time telemetry logging as preconditions for commercial coverage. Logistics operators in California and Texas are piloting third-party safety auditing to preempt regulatory enforcement actions.
Hospital procurement committees are unbundling robot acquisition from captive training and maintenance contracts. IDN purchasing consortia are negotiating direct platform purchases while sourcing aftermarket support from independent clinical engineering firms. This pattern is most visible in the Midwest, where Catholic health systems and academic medical centers are leading contract restructuring.
North America Service Robotics Market Segmentation
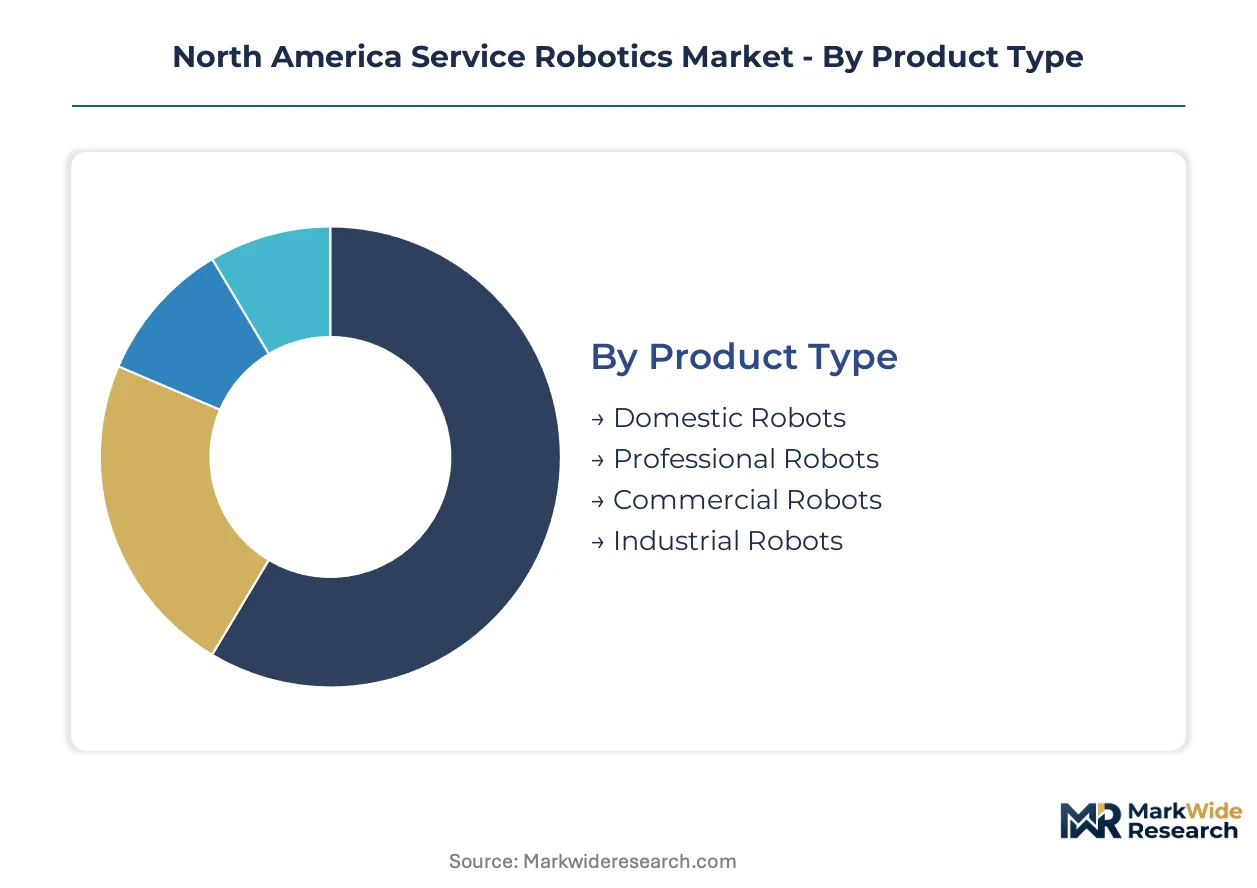
Segmentation reveals how margin pools concentrate across distinct technology architectures and deployment environments in North American service robotics. Product type and application dimensions expose where venture capital and hospital procurement committees direct capital allocation.
Product Type:
Professional robots capture the dominant margin pool through hospital credentialing programs and multi-year service contracts that lock in recurring revenue streams.
- Domestic Robots:Vacuum and lawn maintenance platforms integrate basic LiDAR and camera-based navigation for residential obstacle avoidance. California and Texas households drive replacement cycles as battery degradation accelerates hardware refresh timelines.
- Professional Robots:Surgical and rehabilitation systems incorporate haptic feedback and real-time tissue imaging for minimally invasive procedures. Academic medical centers in the Midwest and Northeast are expanding robotic-assisted surgery suites to offset specialized nursing shortages.
- Commercial Robots:Autonomous mobile platforms for inventory management and customer service deploy in retail and hospitality environments. Big-box distribution centers in the Great Lakes region are retrofitting legacy facilities with these systems.
- Industrial Robots:Ex-factory automation systems handle material transport and quality inspection in unstructured manufacturing settings. Nearshoring corridors in Monterrey and Tijuana are absorbing deployment capacity as U.S.-based vendors establish Spanish-language support infrastructure.
Professional robots hold installed capacity. Commercial robots are rotating up the share rankings.
End User:
Healthcare facilities concentrate procurement volume where FDA Class II and Class III pathways create regulatory moats that protect incumbent positions.
- Healthcare Facilities:Hospitals and ambulatory surgery centers deploy telepresence and surgical systems for remote consultation and precision intervention. Catholic health systems and IDN purchasing consortia in the Midwest are unbundling robot acquisition from captive training contracts.
- Retail Stores:Inventory scanning and customer assistance robots navigate aisle configurations using sensor fusion stacks. Big-box operators in Texas and California are piloting fleet deployments ahead of OSHA workplace robotics guideline finalization.
- Hospitality Industry:Concierge and delivery robots service guest requests in hotel and resort environments. Las Vegas and Orlando properties are deploying these systems to reduce front-desk staffing ratios.
- Educational Institutions:Research and teaching platforms support mechatronics curriculum and laboratory automation. Community colleges in the San Francisco-San Jose corridor are integrating these systems to address technician training gaps.
Healthcare facilities command procurement volume. Retail stores are climbing the fastest as warehouse automation extends into consumer-facing environments.
Application:
Security surveillance retains superior margin structure through recurring software subscriptions and federal procurement premiums that amortize hardware costs.
- Telepresence:Remote presence systems combine mobile bases with high-definition audiovisual links for distributed collaboration. Healthcare networks spanning rural corridors in the Mountain West are deploying these platforms to extend specialist reach.
- Delivery Services:Ground and aerial autonomous vehicles execute last-mile logistics in suburban and exurban environments. FAA Part 135 certification expansion is enabling beyond-visual-line-of-sight operations in previously unreachable territories.
- Cleaning Services:Floor scrubbing and disinfection robots operate in healthcare and commercial environments using UV-C and chemical modalities. Hospital infection control committees are standardizing these systems for terminal room decontamination.
- Security Surveillance:Patrol and monitoring platforms integrate thermal imaging and behavioral analytics for perimeter and facility protection. Federal installations and critical infrastructure operators are mandating collision-avoidance certification as insurance preconditions.
Security surveillance holds recurring revenue density. Delivery services are gaining share fastest as aerial certification pathways mature.
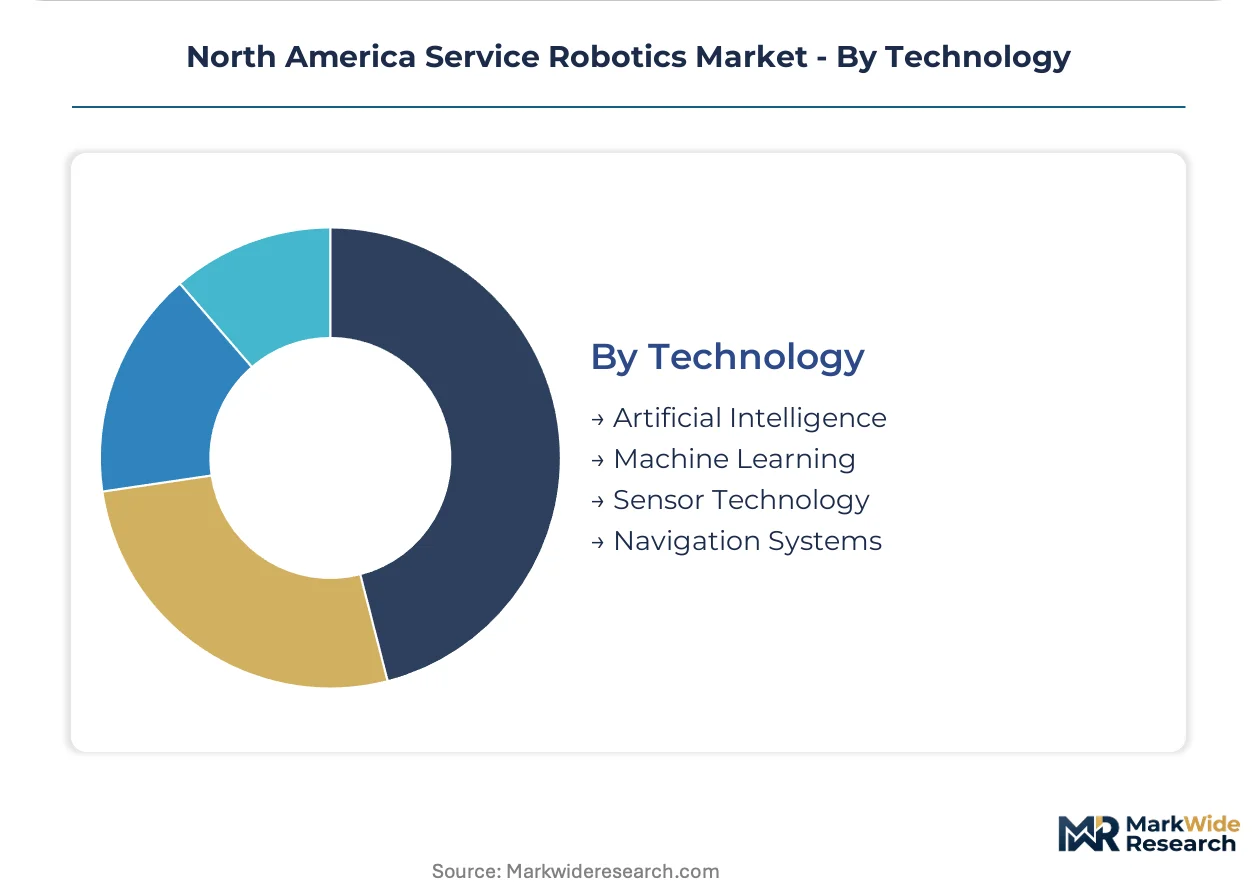
Technology:
Sensor technology and navigation systems concentrate hardware value capture, while artificial intelligence and machine learning enable software-defined differentiation that fragments vendor positioning.
- Artificial Intelligence:Deep learning models process multimodal sensor inputs for scene understanding and decision autonomy. Cloud-offloaded inference is expanding operational envelopes for construction and agricultural robots previously constrained by onboard processing.
- Machine Learning:Adaptive algorithms optimize path planning and task execution through fleet telemetry aggregation. Warehouse operators are deploying these capabilities to reduce AMR congestion in high-density fulfillment zones.
- Sensor Technology:LiDAR, depth cameras, and tactile arrays provide layered environmental perception for dynamic obstacle handling. Multimodal stacks are enabling smaller vendors to compete on scene understanding without proprietary hardware investments.
- Navigation Systems:Real-time localization and mapping architectures integrate GPS-denied positioning for indoor and outdoor operation. 5G edge computing convergence is reducing latency for construction site deployment where connectivity was previously unreliable.
Sensor technology anchors hardware margins. Artificial intelligence is rotating up the share rankings as software-defined adaptability becomes the competitive frontier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in California's robotics corridor while Mexican nearshoring corridors absorb cost-sensitive deployment volumes. The United States commands premium margins through FDA-cleared surgical platforms and venture-backed humanoid development. Canada and Mexico operate on compressed hardware economics shaped by cross-border regulatory duplication and integrator scarcity.
United States
Healthcare labor shortages and hospital consolidation are accelerating robotic-assisted surgery procurement across the Midwest and Northeast. FDA Class II and Class III device pathways create regulatory moats that protect incumbent surgical platform vendors. The San Francisco-San Jose corridor clusters venture deployment and mechatronics talent for legged locomotion and humanoid system commercialization.
Canada
Hospital networks in Ontario and Quebec are expanding telepresence systems to extend specialist reach into rural Prairie provinces. Health Canada's Medical Devices Directorate requires parallel filings that duplicate FDA documentation without mutual recognition, stretching regulatory affairs capacity. Toronto and Vancouver anchor deployment clusters where academic medical centers pilot multimodal perception stacks for surgical applications.
Mexico
Manufacturing automation demand in Nuevo León and Tijuana is outpacing local integrator capacity as nearshoring accelerates. Mexican federal procurement guidelines lack collision-avoidance certification mandates, creating coverage gaps for deployed industrial fleets. The Bajío Region and Northern Border States absorb U.S.-based vendor capacity as Spanish-language support infrastructure expands.
North America Service Robotics Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North American service robotics landscape. Surgical and rehabilitation systems concentrate around platform vendors with captive training networks, while logistics and warehouse automation fragments across sensor-agnostic AMR specialists. Three archetypes dominate: FDA-cleared surgical platform vendors with hospital credentialing programs, legged locomotion specialists with defense and construction applications, and sensor-fusion AMR vendors competing on fleet orchestration software. Competitive moves center on unbundling hardware from service contracts and establishing Spanish-language support infrastructure for Mexican nearshoring corridors.
Within the surgical platform tier, Intuitive Surgical and Stryker Corporation represent established archetypes with hospital credentialing dependencies. Boston Dynamics exemplifies the legged locomotion specialist archetype navigating unstructured terrain applications. Among warehouse automation vendors, Fetch Robotics and Brain Corp occupy positions emphasizing fleet orchestration over proprietary hardware differentiation.
| Leading Market Players |
|---|
| Northrop Grumman Corporation |
| Brain Corp |
| iRobot Corporation |
| Aethon Inc. |
| Fetch Robotics |
| Intuitive Surgical, Inc. |
| Stryker Corporation |
| GeckoSystems International Corporation |
| Boston Dynamics |
| Others |
Value Network & Pricing Analysis
FDA Class II and Class III device pathways simultaneously gate supplier qualification and stratify price tiers across surgical and therapeutic robot segments. Certification investment requirements create dual moats that protect premium pricing for cleared platforms while compressing margins for uncertified commercial systems competing on hardware specifications alone.
Pricing Analysis
Configured-to-order pricing for surgical platforms commands substantial premiums over standard AMR configurations, with hospital credentialing programs and captive training contracts amplifying the spread. Three-tier pricing structure across premium, standard, and economy levels segments the market: FDA-cleared surgical systems with haptic feedback anchor the premium tier, sensor-fusion warehouse robots occupy the standard band, and basic domestic cleaning platforms sit at the economy level. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in the commercial AMR tier is intensifying because sensor component commoditization erodes hardware margins. Hospital procurement committees exhibit lowest price sensitivity due to reimbursement pass-through structures, while retail distribution centers face acute budget constraints.
Supply Chain Analysis
Inventory buffers for LiDAR arrays and precision gearboxes have extended lead times for North American robot OEMs awaiting Asian component shipments. Lithium-ion cell production rests on cathode supply chains concentrated in China, South Korea, and Japan, with cylindrical and prismatic formats feeding mobile robot powertrains. Rare earth magnets for servo motors, high-resolution depth cameras, and FPGA processing modules constitute critical input dependencies. Single-source vulnerability around solid-state LiDAR emitters exposes fleet operators to allocation risk during demand surges. Distribution runs through authorized integrator networks for professional systems and direct e-commerce channels for domestic platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America service robotics market sits in early-cycle recovery, with healthcare labor shortages and nearshoring automation demand providing cyclical lift. Capital deployment should weight toward regulatory-cleared platforms and Mexican corridor infrastructure.
For Market Incumbents: Consolidate hospital credentialing networks and captive training infrastructure to defend against independent clinical engineering firms unbundling service contracts. Add Spanish-language support capacity in Monterrey and Tijuana to capture nearshoring automation demand outpacing local integrator supply. Vertical integration into sensor calibration and fleet telemetry software reinforces recurring revenue density. For New Entrants and Emerging Players: Aftermarket maintenance services for aging installed bases present immediate white-space where incumbents under-serve through bundled pricing. Target mid-tier Catholic health systems in the Midwest with unbundled platform-plus-support offerings. Construction and agricultural robotics in 5G-enabled edge computing corridors offer the most penetrable application layer. Go-to-market leverage should emphasize OSHA pre-compliance certification as insurance procurement accelerates. For Investors and Strategic Acquirers: Carve-out targets emerge from defense contractor robotics divisions seeking commercial revenue diversification. Five-to-ten year viability favors vendors with software-defined fleet orchestration capabilities over hardware-specification competitors. Acquisition archetypes include sensor-agnostic AMR specialists with proven warehouse deployments. Watch FAA Part 135 certification velocity as inflection signal for aerial delivery platform commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital Credentialing Program Expansion | Locks in multi-year service contracts with IDN purchasing consortia across the Midwest. |
| Mexican Nearshoring Support Infrastructure | Captures automation demand in Monterrey and Tijuana exceeding local integrator capacity. |
| OSHA Pre-Compliance Certification Investment | Positions vendors ahead of federal workplace robotics safety guideline finalization. |
| Sensor-Agnostic Fleet Orchestration Platform | Enables software differentiation without proprietary hardware development cycles. |
| 5G Edge Computing Partnership | Expands operational envelopes for construction robots previously constrained by latency. |
Research Methodology
A standing panel of hospital purchasing committee directors, AMR fleet operations managers, biomedical engineering leads, and Mexican manufacturing automation executives provided ongoing calibration against primary interview transcripts and secondary validation. FDA 510(k) and PMA filing databases, Health Canada Medical Devices Directorate records, FAA Part 135 certification dockets, and OSHA draft workplace robotics guidelines supplied regulatory trajectory inputs. Hospital procurement databases, GPO contract repositories, and venture capital deployment tracking across California's robotics corridor anchored demand-side quantification. Bottom-up installed base modeling and top-down healthcare expenditure allocation triangulated segment sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type, end user, application, and technology dimensions alongside regulatory pathway clustering and geographic adoption intensity. CAGRs were derived from segment-level unit economics and replacement cycle analysis. Forecast inputs incorporated healthcare labor shortage projections, FAA certification velocity assumptions, and lithium-ion battery cost curves.
Forecasts assume regulatory continuity in FDA device classification and FAA aerial delivery frameworks; material policy shifts would require re-modeling. Supply chain disruption scenarios, mechatronics technician graduation rates, and Health Canada-FDA mutual recognition developments constitute specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Clean Room Robot Market
Robotics and Automation
Agriculture Robotics Market
Robotics and Automation
Humanoids Market
Robotics and Automation
Smart Curtain Robot Market
Robotics and Automation
Cognitive Robotics Market
Robotics and Automation
Underwater Rescue Robot Market
Robotics and Automation
North America AUV and ROV Market
Robotics and Automation
Europe Underwater Robotics Market
Robotics and Automation
Europe Automated Liquid Handling Market
Robotics and Automation
Europe Data Center Robotics Market
Robotics and Automation
Asia Pacific Warehouse Robotics Market
Robotics and Automation
Food Robotics Market
Robotics and Automation
Asia-Pacific AUV Market
Robotics and Automation
Micro Robots Market
Robotics and Automation
APAC Robotic Process Automation (RPA) Market
Robotics and Automation
Industrial Control Robotics Market