
 North America Cloud Robotics Market | 2026-2036
North America Cloud Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Cloud Robotics Market Analytics
ISO 10218 robot safety certification is bifurcating the competitive landscape into qualified system integrators and peripheral software vendors. Microsoft Corporation leverages its Azure industrial IoT backbone to anchor cloud-native robot orchestration for automotive clients. Amazon Web Services, Inc. competes through AWS RoboMaker's simulation-to-deployment pipeline, sustaining developer ecosystem density across North American logistics hubs.
Cloud robotics denotes distributed robot architectures where computation, storage, and learning models reside on remote servers rather than onboard controllers, with sub-50ms latency thresholds defining real-time viability for collaborative tasks. The primary purpose is to offload cognitive workloads from edge hardware while enabling fleet-wide model updates and centralized operational intelligence. Public cloud deployments dominate pilot-phase adoption, though hybrid cloud configurations capture expanding margin pools as manufacturers demand data sovereignty over proprietary process telemetry. Machine learning segments lead technology investment, while computer vision applications mature fastest in quality-inspection workflows across the Great Lakes industrial belt.
FCC Part 15 rules govern unlicensed spectrum for robot-to-cloud communication, while NIST cybersecurity frameworks mandate encryption standards for connected industrial systems; both shape procurement specifications and vendor qualification cycles. OSHA directives on collaborative robot workplace safety further constrain deployment architectures, particularly in dense human-robot environments. Stakeholders must weigh cloud provider lock-in risks against the operational agility that centralized fleet management delivers.
Market Dynamics
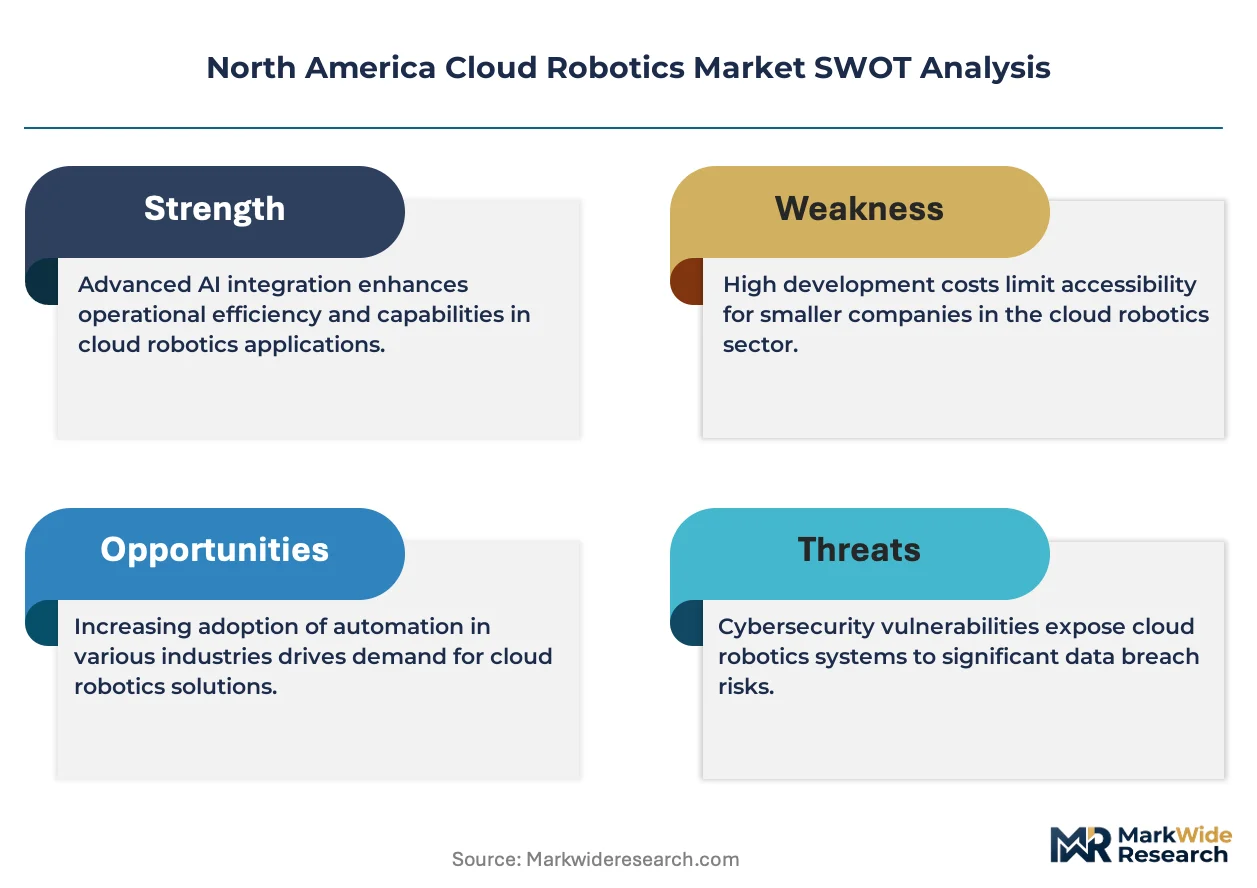
ISO 10218 robot safety certification is bifurcating the competitive landscape into qualified system integrators and peripheral software vendors, forcing procurement committees to weight vendor qualification timelines against deployment velocity in automotive and logistics corridors.
Growth Catalysts
- NIST Cybersecurity Framework:Tightening compliance thresholds for connected industrial systems are accelerating vendor consolidation toward certified cloud-native orchestration platforms in Michigan and Ohio manufacturing clusters.
- Warehouse fulfillment robotics:E-commerce operators across the Great Lakes corridor are scaling robotic fleet deployments, pulling demand for sub-50ms latency cloud architectures.
- Machine learning offloading:Distributed computation architectures are enabling real-time fleet-wide model updates without onboard hardware upgrades, compressing total cost of ownership for mid-tier manufacturers.
Market Restraints
- Cloud provider lock-in:Proprietary orchestration APIs create switching costs that constrain multi-cloud strategies for manufacturers demanding data sovereignty over process telemetry.
- Spectrum allocation uncertainty:FCC Part 15 unlicensed band congestion in dense industrial zones introduces latency variability that disqualifies real-time collaborative applications.
- Edge hardware dependency:Persistent requirements for local safety controllers under ISO 10218 limit full computation offloading, maintaining hybrid architecture complexity.
Strategic Opportunities
- Illinois-Indiana logistics corridor:Underpenetrated mid-market 3PL operators present whitespace for standardized cloud robotics-as-a-service offerings with reduced integration overhead.
- Computer vision quality inspection:Mature vision algorithms are displacing manual inspection in automotive stamping and welding workflows across Ohio supplier parks.
- OSHA collaborative robot directives:Clarified safety standards for dense human-robot environments are reducing deployment risk premiums and accelerating pilot-to-production transitions.
Industry Challenges
- ISO 10218-2 certification timelines:Extended vendor qualification cycles for system integrators are delaying fleet deployments and compressing implementation windows for seasonal demand peaks.
- Legacy MES integration:Proprietary manufacturing execution system protocols in established automotive plants require custom middleware development, inflating project costs and technical risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Cloud Robotics Market |
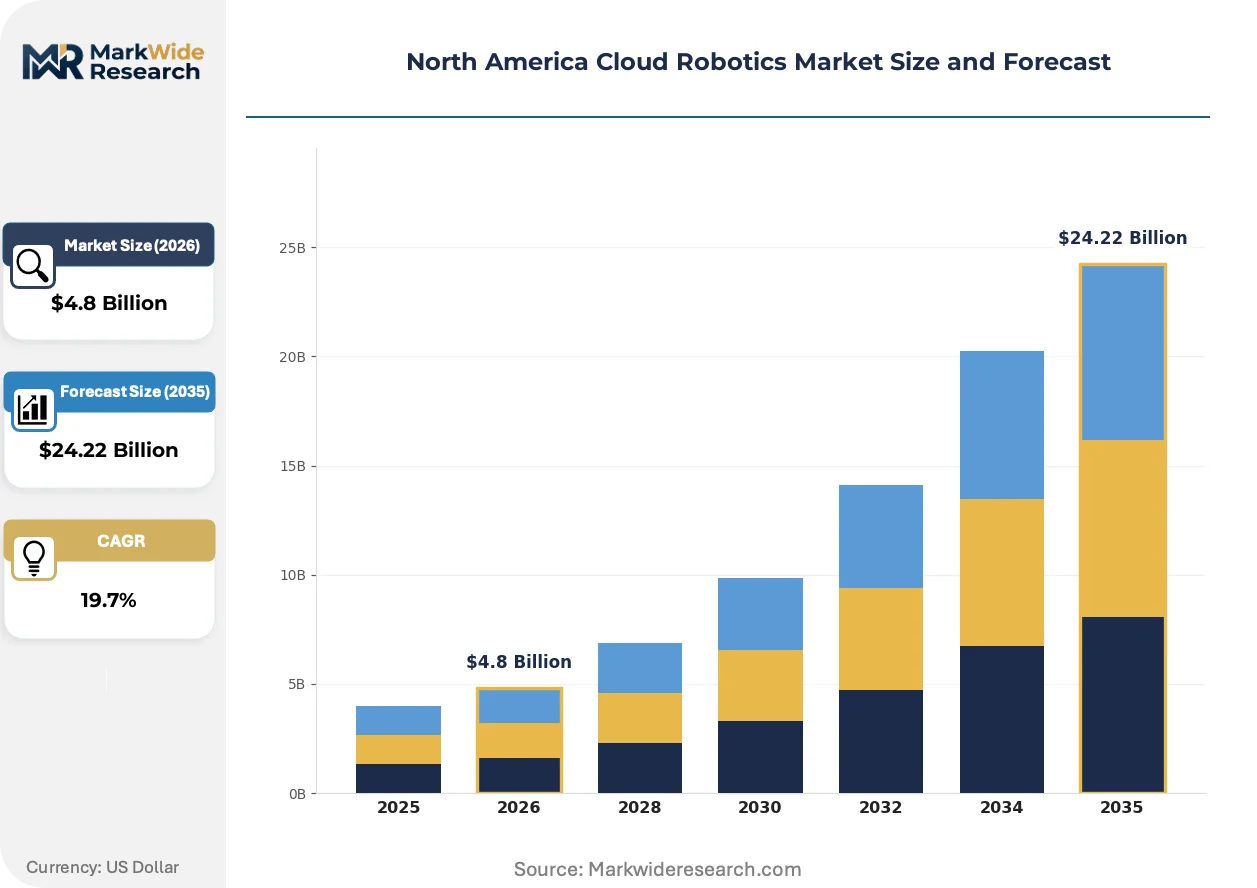
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $24.22 Billion |
| CAGR (2026 – 2036) | 19.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Edge Computing Application: Manufacturing, Agriculture, Healthcare, Logistics Technology: Machine Learning, IoT Integration, Computer Vision, Natural Language Processing End User: SMBs, Enterprises, OEMs, Research Institutions |
| Companies Covered | Amazon Web Services, Inc., Microsoft Corporation, IBM Corporation, ABB Group, Rockwell Automation Inc., Google LLC, CloudMinds Technology Inc., Kuka AG, SoftBank Robotics Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Cloud Robotics Market Evolving Landscape
Edge inference accelerators are compressing latency budgets for safety-critical robot motions, while regulatory pressure on data residency is fragmenting cloud architecture choices across jurisdictional boundaries.
Embedded GPU modules for onboard trajectory planning is miniaturizing the compute footprint required for millisecond-level collision avoidance, enabling automotive tier-one suppliers in Detroit and Windsor to deploy collaborative cells without dedicated server rooms. Tier-two stamping plants are adopting these modules fastest, driven by floor space constraints and HVAC retrofit costs. The technology is miniaturizing the physical infrastructure barrier that previously restricted cloud-connected robotics to greenfield facilities.
NIST's cybersecurity framework updates for operational technology systems are mandating encryption standards that exceed current industrial IoT gateway capabilities, forcing hardware refresh cycles across Canadian and US manufacturing networks. Automotive OEMs are responding by segmenting robot telemetry streams into sovereign and non-sovereign data classes. The Great Lakes supplier base faces the steepest compliance burden due to cross-border data flow complexity.
Subscription-based fleet management contracts are displacing perpetual licensing for robot orchestration software among mid-market logistics operators. Third-party logistics providers in Chicago and Toronto are piloting all-inclusive per-pick pricing models that bundle hardware, cloud compute, and maintenance. This restructuring is most visible in seasonal fulfillment operations where capital flexibility outweighs long-term ownership economics.
North America Cloud Robotics Market Segmentation
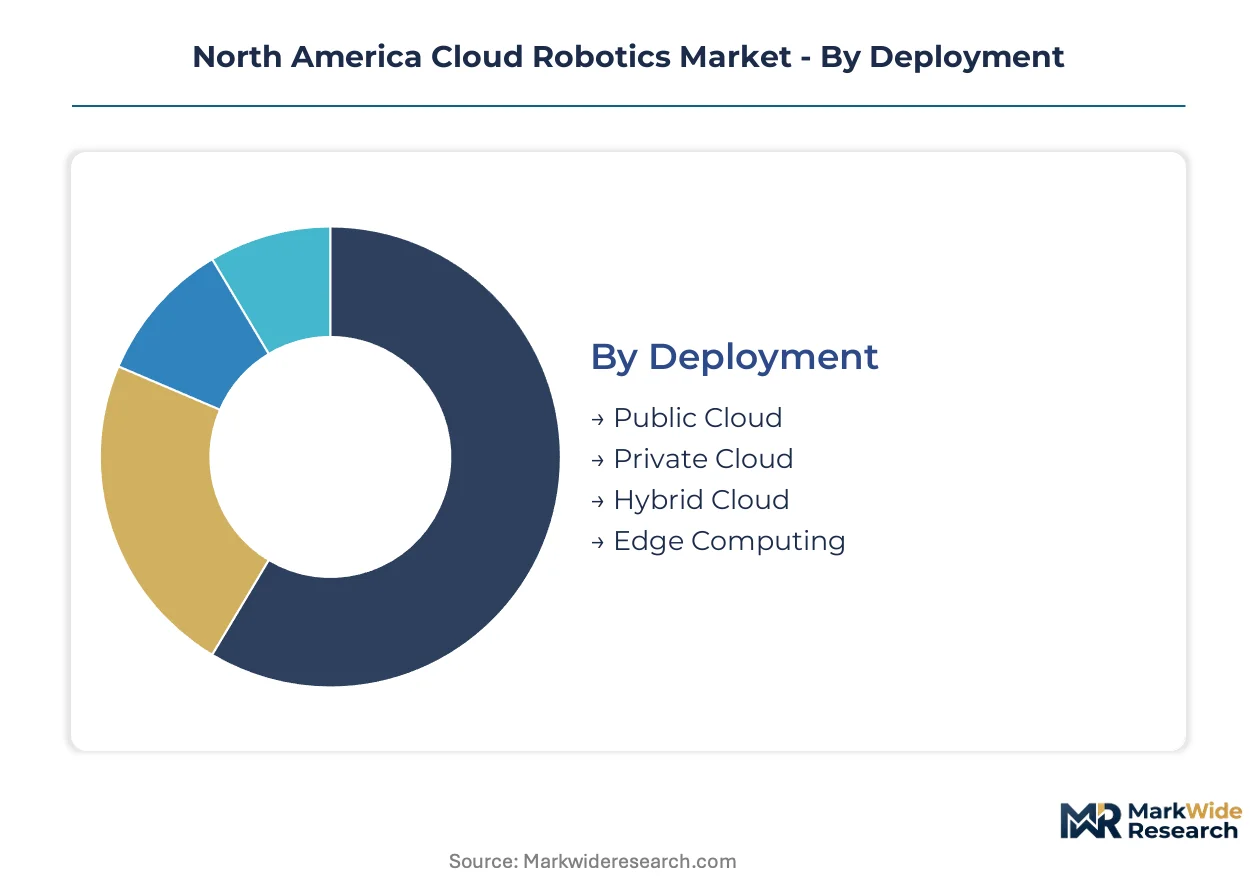
Cloud robotics architectures fragment across deployment topologies, application domains, and technology stacks. Each segmentation dimension carries distinct channel economics and vendor qualification requirements.
Deployment:
Public cloud deployments flow through hyperscaler marketplaces and system integrator channels, while private and hybrid configurations route through certified industrial automation distributors.
- Public Cloud:Centralized compute and storage resources hosted on third-party infrastructure. Demand concentrates among mid-market logistics operators in Chicago and Toronto seeking capital flexibility without on-premise hardware investments.
- Hybrid Cloud:Split architectures keeping sensitive process telemetry on-premise while offloading non-critical workloads to remote servers. Automotive OEMs in Michigan and Ohio manufacturing clusters favor this model for data sovereignty compliance.
- Private Cloud:Dedicated infrastructure deployed within facility boundaries. Defense contractors and aerospace suppliers in Southern California require this topology for ITAR-controlled data handling.
- Edge Computing:Distributed processing nodes positioned at the network periphery. Stamping plants across Ohio supplier parks adopt these modules to compress latency for millisecond-level collision avoidance.
By volume, public cloud leads. By growth pace, hybrid cloud is climbing the fastest.
Application:
Cost tier differentiation separates high-complexity manufacturing implementations from standardized logistics deployments.
- Logistics:Warehouse fulfillment robotics for order picking, sorting, and palletizing operations. Third-party logistics providers in the Illinois-Indiana corridor pilot subscription-based per-pick pricing models.
- Manufacturing:Collaborative robot cells for assembly, welding, and quality inspection workflows. Tier-one automotive suppliers in Detroit and Windsor deploy these systems under ISO 10218-2 certification requirements.
- Healthcare:Surgical assistance and sterilization logistics robots. Hospital systems in Texas and Florida evaluate cloud-connected platforms for centralized fleet management.
- Agriculture:Autonomous harvesting and crop monitoring systems. Large-scale operations in California's Central Valley test computer vision-enabled platforms for labor substitution.
Manufacturing captures the largest revenue pool. Logistics is expanding most quickly.
Technology:
Maturity curves diverge sharply, with computer vision reaching production stability while natural language processing remains experimental.
- Computer Vision:Camera-based object detection and quality inspection algorithms. Mature vision systems displace manual inspection in automotive stamping workflows across Ohio supplier parks.
- Machine Learning:Distributed model training and fleet-wide algorithm updates. Cloud-native orchestration enables real-time learning without onboard hardware refreshes for mid-tier manufacturers.
- IoT Integration:Sensor fusion and telemetry aggregation from distributed robot fleets. NIST cybersecurity frameworks mandate encryption standards that exceed current industrial gateway capabilities.
- Natural Language Processing:Voice-command interfaces for human-robot collaboration. Research institutions in Massachusetts and California pilot conversational control systems for non-technical operators.
Computer vision leads by deployment count. Machine learning shows the steepest investment trajectory.
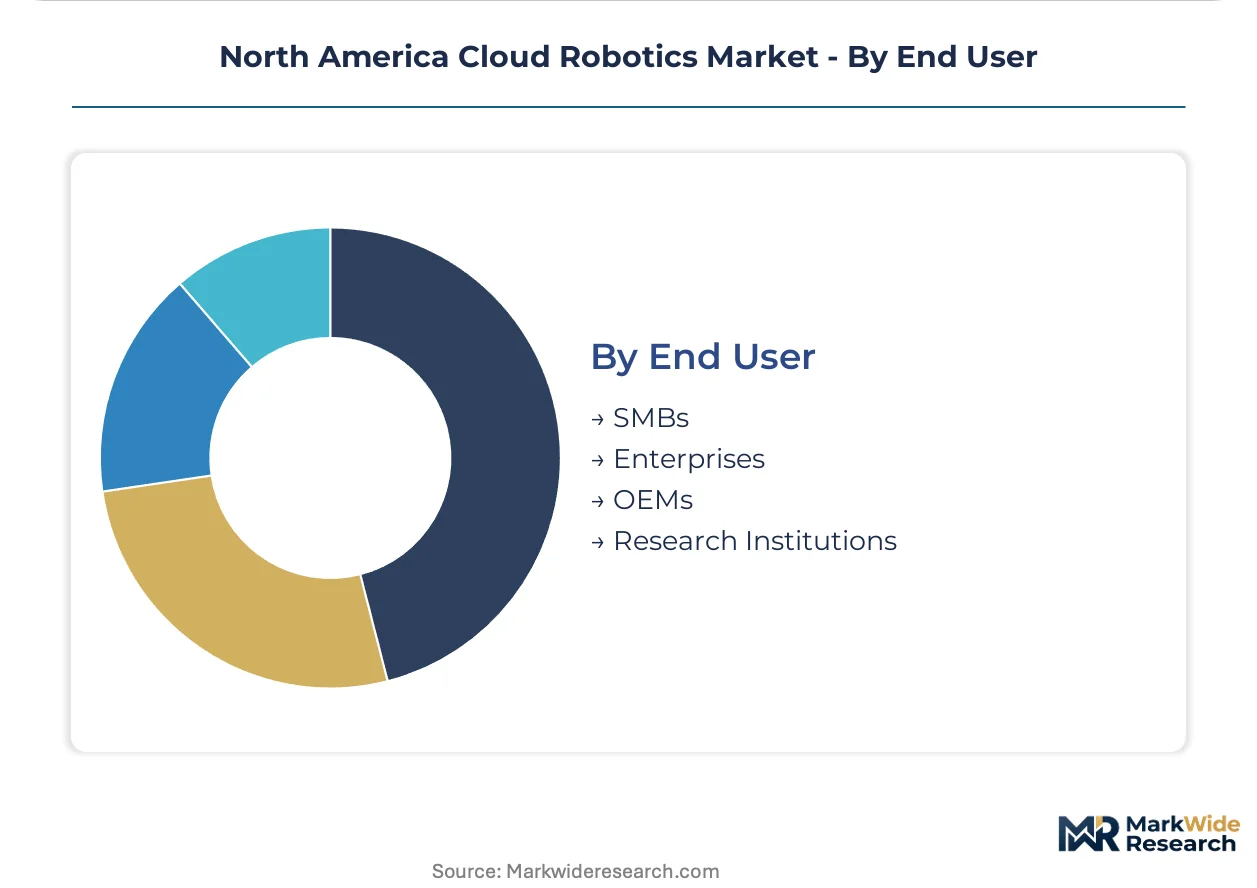
End User:
Customer type determines integration complexity, with OEMs demanding custom middleware while SMBs prioritize standardized offerings.
- Enterprises:Large manufacturers and logistics operators with dedicated automation engineering teams. These buyers negotiate direct vendor relationships and custom service-level agreements.
- SMBs:Mid-market manufacturers and regional 3PL operators lacking in-house integration expertise. Standardized robotics-as-a-service offerings with reduced deployment overhead address this segment.
- OEMs:Original equipment manufacturers embedding cloud robotics into product lines. These customers require extensive API access and white-label orchestration capabilities.
- Research Institutions:Universities and government laboratories advancing foundational robotics research. Federal funding through NSF and DARPA shapes procurement priorities in this channel.
Enterprises dominate current revenue. SMBs represent the largest addressable expansion opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC Part 15 spectrum rules and NIST cybersecurity mandates are accelerating compliance investments across North American manufacturing networks. Warehouse operators in the Great Lakes corridor are scaling robotic fleet deployments under tightened operational standards.
United States
Automotive OEMs in Michigan and Ohio manufacturing clusters are deploying hybrid cloud architectures to maintain data sovereignty over proprietary process telemetry. OSHA directives on collaborative robot workplace safety are constraining deployment architectures in dense human-robot environments. The Detroit-Windsor supplier corridor leads in embedded GPU module adoption for millisecond-level collision avoidance.
Canada
Cross-border data flow complexity is forcing Great Lakes supplier base investments in segmented robot telemetry streams. Health Canada and PMRA oversight of connected medical devices is extending to cloud-connected surgical assistance robots in Toronto and Vancouver hospital systems. Ontario-based tier-one suppliers are adopting subscription-based fleet management contracts for seasonal fulfillment flexibility.
Mexico
Bajío Region automotive plants are piloting cloud-native orchestration platforms under NIST-aligned cybersecurity frameworks demanded by US parent companies. Mexico's national telecommunications regulator IFT governs unlicensed spectrum allocation for robot-to-cloud communication in dense industrial zones near Mexico City. Nuevo León manufacturing clusters are adopting computer vision quality inspection systems for automotive stamping workflows.
North America Cloud Robotics Market Competitive Landscape
Listed leaders compete with private specialists across cloud infrastructure and industrial automation domains. Hyperscalers anchor public cloud deployments while diversified industrial conglomerates dominate hybrid configurations. Three archetypes define competitive positioning: cloud-native platform providers, certified system integrators, and robotics-as-a-service specialists. Strategic consolidation centers on API ecosystem expansion and vertical middleware development.
Within the hyperscaler tier, Amazon Web Services, Inc. and Microsoft Corporation exemplify divergent approaches to developer ecosystem density. AWS RoboMaker's simulation-to-deployment pipeline sustains logistics hub concentration, while Microsoft Corporation leverages Azure industrial IoT backbone for automotive client anchoring. Rockwell Automation Inc. occupies a position bridging operational technology heritage with cloud-native orchestration demands.
| Leading Market Players |
|---|
| Amazon Web Services, Inc. |
| Microsoft Corporation |
| IBM Corporation |
| ABB Group |
| Rockwell Automation Inc. |
| Google LLC |
| CloudMinds Technology Inc. |
| Kuka AG |
| SoftBank Robotics Group |
| Others |
Value Network & Pricing Analysis
Ninety-day lead times for embedded GPU modules from Taiwan semiconductor foundries concentrate pricing power with tier-one automotive suppliers in Detroit and Windsor, while mid-market logistics operators in Chicago face cost compression from inventory carrying charges and expedited freight premiums.
Pricing Analysis
Certification level creates the primary spread between ISO 10218-2 qualified system integrators and peripheral software vendors. Three-tier pricing structure across premium, standard, and economy levels separates certified fleet orchestration platforms from unvalidated middleware and open-source alternatives. Pricing pressure stems from subscription-based robotics-as-a-service models displacing perpetual licenses among seasonal 3PL operators. SMBs in the Illinois-Indiana corridor exhibit highest price sensitivity, while defense contractors accepting private cloud deployments show lowest elasticity due to ITAR compliance requirements.
Supply Chain Analysis
Sixty-day inventory cycles for industrial IoT gateways reflect dependency on Taiwanese and South Korean semiconductor packaging facilities. Component sourcing draws from German precision motion controllers, Japanese servo motors, and Chinese camera modules for computer vision systems. Single-source vulnerability concentrates in NIST-compliant encryption chipsets exceeding legacy gateway capabilities. Distribution runs through certified industrial automation distributors for hybrid cloud configurations and hyperscaler marketplaces for public cloud pilots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud robotics represents a service-attach opportunity where subscription-based fleet management contracts and per-pick pricing models expand faster than hardware unit sales among mid-market logistics operators.
For Market Incumbents: Fortify API ecosystem control by embedding orchestration layers deeper into automotive MES workflows, countering hyperscaler encroachment into operational technology domains. Pursue backward integration into edge inference accelerators to capture margin pools from embedded GPU module suppliers serving Detroit-Windsor stamping plants. ISO 10218-2 certification investment creates switching costs that delay competitive displacement. For New Entrants and Emerging Players: Mid-market 3PL operator under-service in the Illinois-Indiana logistics corridor offers whitespace for standardized robotics-as-a-service offerings with reduced integration overhead. Target computer vision quality inspection workflows across Ohio automotive supplier parks where incumbent system integrators lack vertical-specific algorithm libraries. Channel partnership with established industrial automation distributors accelerates qualification timelines. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core robotics software assets amid cloud-native platform consolidation. Long-term viability centers on recurring revenue attach rates rather than hardware shipment volumes. Monitor NIST cybersecurity framework enforcement intensity across Great Lakes manufacturing clusters as inflection indicator for compliance-driven vendor consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Azure industrial IoT backbone anchoring anchors automotive client retention against AWS RoboMaker logistics concentration. |
| Acquisition of Specialist Firm | Computer vision algorithm shops in Ohio supplier parks accelerate vertical middleware development for stamping quality inspection. |
| Strategic Partnership | System integrator alliances with NIST-certified cybersecurity vendors compress qualification timelines for Michigan OEMs. |
| Product Launch | Edge inference accelerator modules miniaturize compute footprints for tier-two plants facing HVAC retrofit constraints. |
| Geographic Expansion | Toronto and Vancouver hospital system penetration leverages Health Canada oversight alignment for surgical assistance robotics. |
Research Methodology
The analysis maps public cloud, hybrid cloud, private cloud, and edge computing deployment topologies, each validated through primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and integration specialists, combined with secondary sources including SEC 10-K filings, hyperscaler capex disclosures, and NIST cybersecurity framework documentation, employing bottom-up fleet deployment estimates and top-down industrial automation spending triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation modeling spanning deployment topology, application domain, technology stack, and end-user archetype, deriving CAGRs from installed base growth curves and average revenue per robot trajectories, incorporating automotive production schedules and e-commerce fulfillment center buildout pipelines as industry-specific demand drivers.
Material uncertainties — FCC Part 15 spectrum reallocation, NIST framework revision timing, ISO 10218-2 certification backlog resolution — sit outside the modeled envelope, with forecasts reflecting documented assumptions subject to revision from regulatory enforcement intensity or hyperscaler pricing strategy shifts. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Singapore Cloud Robotics Market
Robotics and Automation
Europe Agricultural Robots and Mechatronics Market
Robotics and Automation
Cordless Router Market
Robotics and Automation
South America Agricultural Robots and Mechatronics Market
Robotics and Automation
Top Robotics Market
Robotics and Automation
Global K-12 Robotic Toolkits Market
Robotics and Automation
Asia-Pacific AUV and ROV Market
Robotics and Automation
Pipetting Robots Market
Robotics and Automation
AI Powered Robot Market
Robotics and Automation
Robotics End of Arm Tooling Market
Robotics and Automation
Asia-Pacific Robotics and Automation Actuators Market
Robotics and Automation
Biaxial Mobile Phone Stabilizer Market
Robotics and Automation
Asia-Pacific Medical Robots Market
Robotics and Automation
LAMEA Demolition Robot Market
Robotics and Automation
Global Demolition Robots Market
Robotics and Automation
Robotics Actuators Market