
 Commercial Sink Market | 2026-2036
Commercial Sink Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Sink Market Outlook
China is tilting toward expanded stainless steel fabrication capacity for commercial kitchen fixtures. Franke Group leverages its European engineering heritage to sustain premium positioning across hotel and hospital channels. Elkay Manufacturing Company anchors North American distribution through deep contractor relationships and specification-grade product lines.
A commercial sink is a purpose-built wash station, typically fabricated from 16- to 18-gauge stainless steel or engineered polymer, designed for high-cycle food preparation, utensil sanitization, and hand-washing compliance in professional environments. Stainless steel dominates material selection for its corrosion resistance and weldability under NSF/ANSI standards, while polymer alternatives gain traction in corrosive chemical applications. Undermount configurations lead in new restaurant construction for seamless counter integration, whereas wall-mounted units command replacement demand where floor space is constrained and hygiene access matters most.
The EPA Safe Drinking Water Act and FDA Food Code shape fixture specifications for flow restriction and drainage containment across United States installations. NSF International certification operates as a de facto market gate for product placement in regulated foodservice and healthcare environments. Stakeholders must weigh material cost trajectories against evolving water-efficiency mandates when configuring product portfolios for institutional buyers.
Market Dynamics
Sanitation protocol tightening across foodservice and healthcare verticals is compressing replacement cycles and forcing specification upgrades that favor deeper basin configurations and sensor-activated fixtures over legacy manual models.
Growth Catalysts
- EPA Safe Drinking Water Act amendments:Flow restriction mandates in the United States are compelling operators to retrofit existing stations with water-efficient fixtures, creating replacement pull across institutional kitchens.
- Fast-casual expansion clusters:Chains in Texas, California, and Florida are expanding kitchen footprints and adding dedicated hand-washing stations to meet operational throughput targets.
- NSF/ANSI 2 certification requirements:Foodservice equipment standards are filtering non-compliant fabricators from specification lists, concentrating demand among certified producers.
Market Restraints
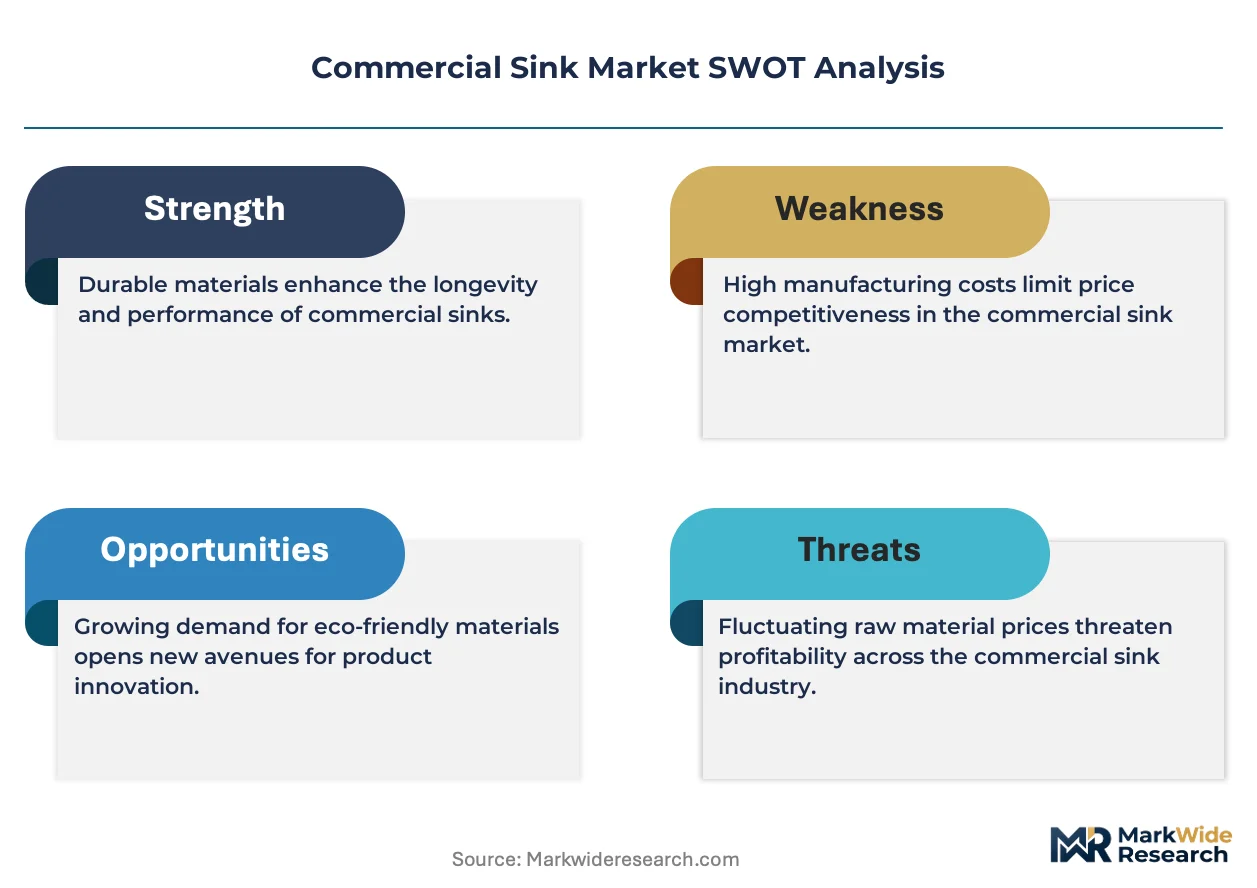
- Nickel and chromium price volatility:Stainless steel input costs fluctuate with commodity markets, squeezing fabrication margins and destabilizing project quoting.
- Regional fabrication concentration:Domestic capacity constraints in North America create lead time vulnerability during construction seasonality peaks.
- Polymer substitution ceiling:Engineered polymer alternatives face thermal durability limits that prevent penetration beyond corrosive chemical wash applications.
Strategic Opportunities
- Healthcare facility modernization wave:Hospital and long-term care construction in the southeastern United States is specifying antimicrobial copper-alloy fixtures for infection control.
- Sensor-activated retrofit kits:Battery-powered and hardwired touchless conversion modules allow operators to upgrade existing basins without full replacement.
- Remote monitoring integration:IoT-enabled flow sensors and temperature loggers are converging with facility management platforms to automate compliance documentation.
Industry Challenges
- Certification timeline compression:NSF International testing queues and documentation requirements are extending product launch cycles for new basin configurations.
- Skilled welder scarcity:TIG welding expertise for 16-gauge stainless fabrication is thinning across the contractor base, constraining quality throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Sink Market |
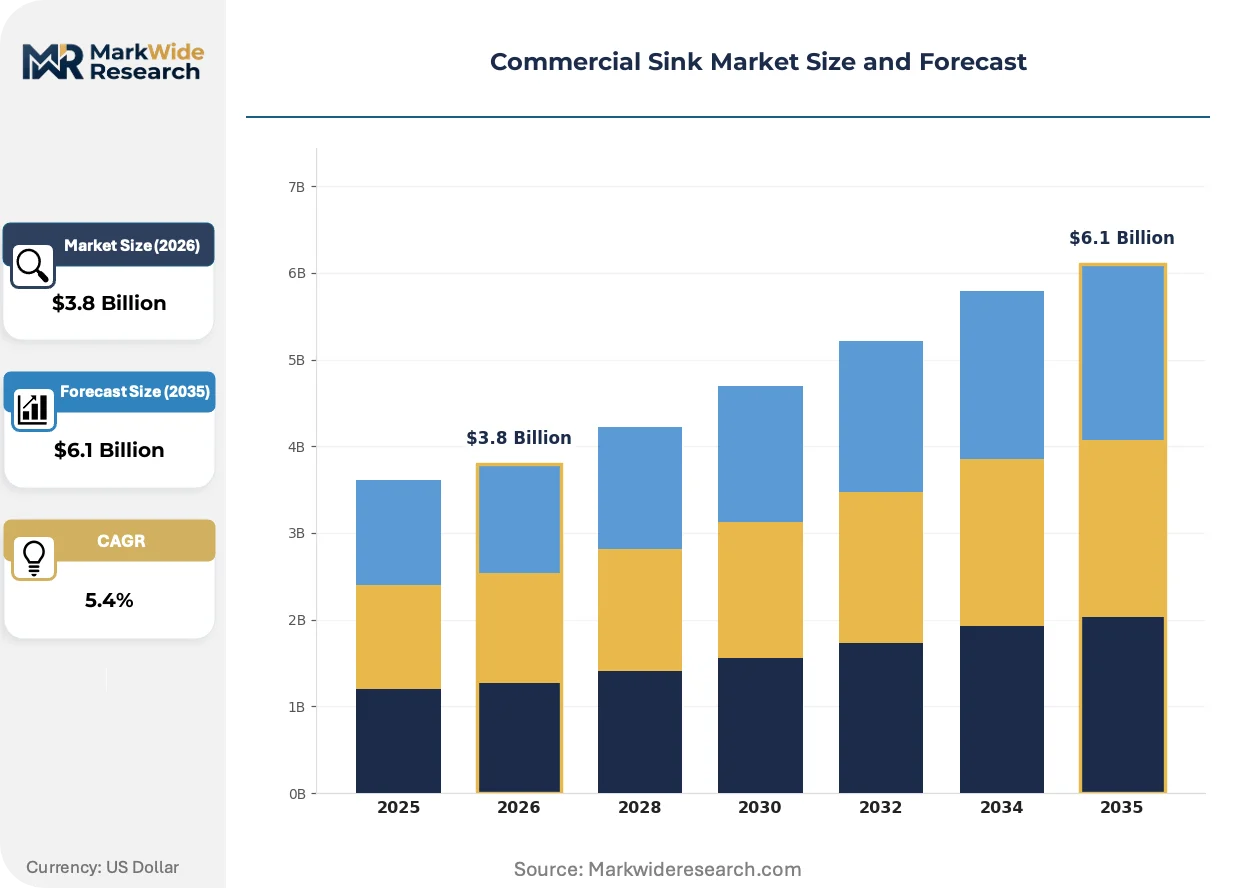
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Undermount, Drop-in, Wall-mounted, Single-basin Material: Stainless Steel, Polymer, Porcelain, Concrete End User: Restaurants, Hotels, Hospitals, Cafeterias Installation Type: Freestanding, Built-in, Corner, Mobile |
| Companies Covered | Elkay Manufacturing Company, Franke Group, Kohler Co., Blanco GmbH, American Standard Brands, TOTO Ltd., Duravit AG, Roca Sanitario, Teka Industrial, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Sink Market Strategic Shifts
Fabrication methods and fixture intelligence are converging to redefine wash station performance standards. Operators now prioritize seamless integration, automated compliance, and modular upgrade paths over static equipment specifications.
Touchless sensor activation systems using infrared proximity detection and capacitive sensing are eliminating cross-contamination vectors in high-throughput kitchen environments. Fast-casual chains and hospital foodservice departments are specifying these fixtures as standard in new construction. Traditional lever-handle and knee-valve mechanisms are rendering obsolete across segments where hand-washing frequency exceeds fifty cycles per hour.
FDA Food Code updates governing hand-washing station accessibility and water temperature maintenance are mandating specific basin depths and fixture placements in commercial kitchens. These provisions are forcing renovation budgets toward full-station replacement rather than component-level upgrades. Institutional operators in the United States are responding by consolidating procurement around specification-grade product lines that preempt future code revisions.
Specification decisions are migrating from facilities managers to infection control consultants and culinary operations directors with distinct performance criteria. Distributor showrooms and contractor relationships are losing influence to direct manufacturer engagement with multi-unit chain technical teams. This pattern is most pronounced in the United States, where fast-casual and institutional foodservice operators are centralizing equipment standards across regional portfolios.
Commercial Sink Market Segmentation
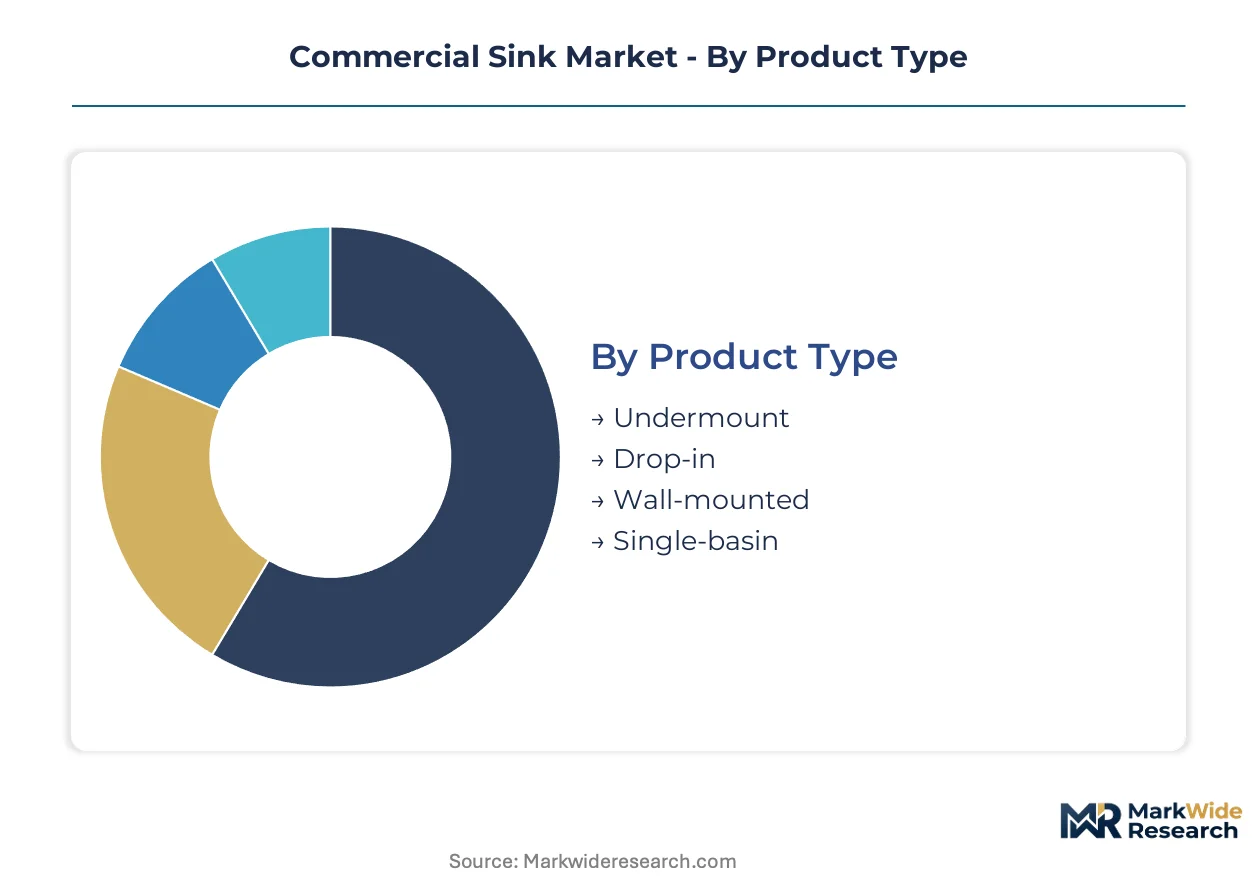
Commercial sink procurement decisions cascade from installation constraints, material durability requirements, and end-use hygiene protocols. Specification-grade buyers prioritize NSF certification compatibility and thermal performance over upfront cost, fragmenting demand across fabrication methods and mounting configurations.
Product Type:
Mature configurations dominate specification lists while emerging formats address renovation constraints and throughput demands.
- Undermount:Seamless counter integration eliminates bacterial harborage points at basin edges. Fast-casual chains in Texas and California specify these for new construction to satisfy FDA Food Code surface sanitation requirements.
- Wall-mounted:Floor clearance maximizes hygiene access and simplifies cleaning protocols in high-turnover environments. Hospital foodservice departments in Florida favor these for replacement projects where footprint compression matters.
- Drop-in:Rim-seated basins reduce installation labor for contractor-driven replacement cycles.
- Single-basin:Compact configurations serve food truck and mobile catering operators with space-constrained workflows.
Undermount retains volume leadership; wall-mounted holds the steepest expansion curve.
Material:
Cost tier stratification separates specification-grade stainless from economy alternatives with divergent certification trajectories.
- Stainless Steel:16- to 18-gauge 304 and 316 alloys deliver weldability and corrosion resistance under NSF/ANSI 2 standards. Institutional foodservice operators in the United States mandate this material for high-cycle sanitization environments.
- Polymer:Engineered thermoplastics resist aggressive chemical cleaners that degrade metal finishes. Healthcare facility maintenance teams specify these for corrosive wash applications where bleach protocols exceed stainless tolerance.
- Porcelain:Vitreous enamel coatings serve front-of-house hand-washing stations with aesthetic requirements.
- Concrete:Cast polymer-concrete composites gain traction in open-kitchen designs with visible wash stations.
Stainless steel commands procurement volume; polymer climbs fastest among healthcare verticals.
End User:
Application intensity varies dramatically across foodservice throughput and healthcare infection control mandates.
- Restaurants:Fast-casual chains drive specification for deeper basin configurations and sensor-activated fixtures. Operators in California and Texas are expanding dedicated hand-washing stations to meet operational throughput targets.
- Hospitals:Infection control consultants specify antimicrobial copper-alloy fixtures and touchless activation for foodservice and clinical wash stations. Southeastern United States facility construction is concentrating demand for these premium configurations.
- Hotels:Full-service properties balance back-of-house durability with front-of-house aesthetic integration.
- Cafeterias:Institutional operators centralize procurement around specification-grade lines that preempt future code revisions.
Restaurants anchor procurement volume; hospitals gain share fastest through modernization waves.
Installation Type:
Customer type and project phase dictate mobility requirements and spatial configuration constraints.
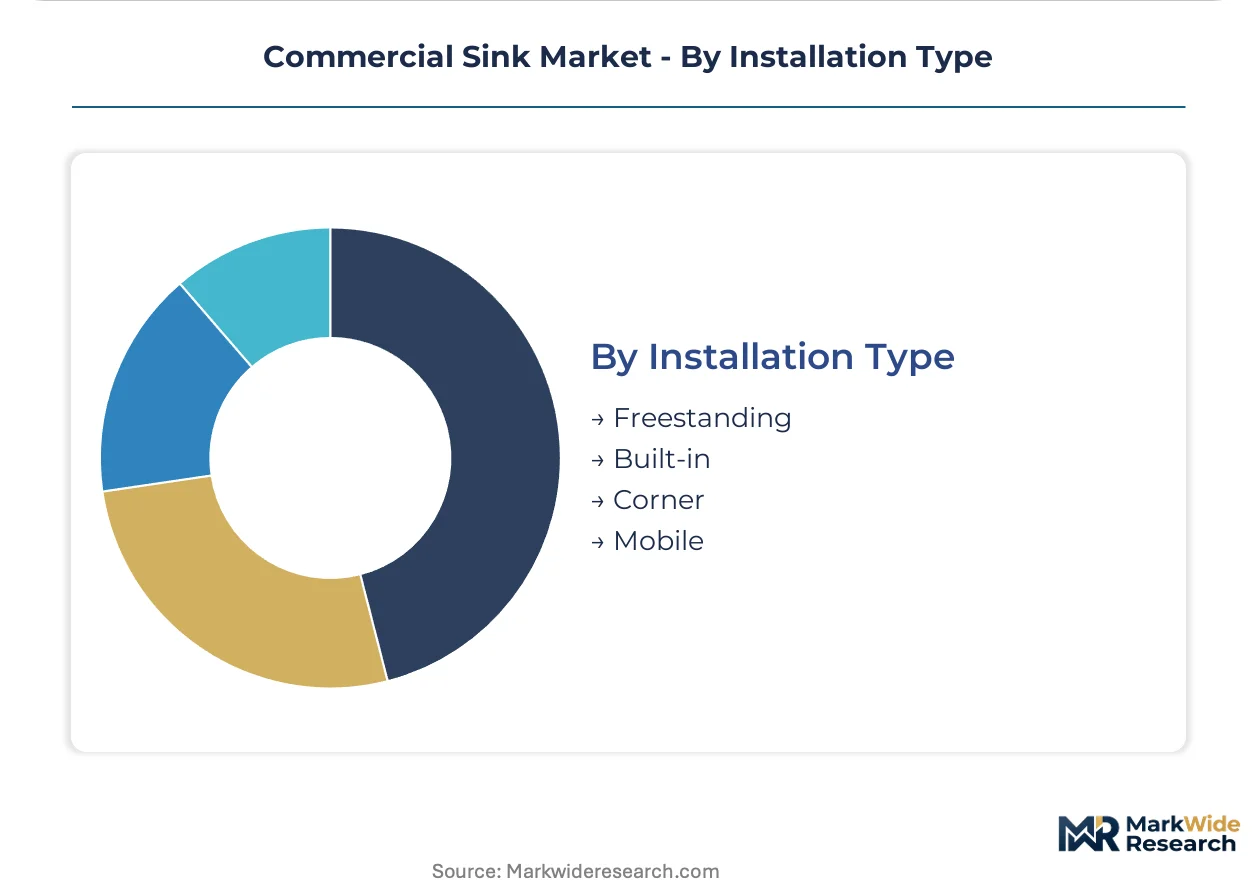
- Freestanding:Self-supporting frames with integrated legs serve temporary kitchen installations and catering operations. Event venues and disaster relief foodservice deploy these for rapid deployment without structural modification.
- Built-in:Cabinet-integrated basins dominate permanent commercial kitchen construction. General contractors in Florida specify these for fast-casual rollout programs requiring standardized station layouts.
- Corner:Triangular basin configurations maximize utility in spatially constrained prep areas.
- Mobile:Castor-mounted units enable reconfiguration for seasonal demand fluctuations and cleaning access.
Built-in retains specification dominance; mobile units expand most quickly in flexible-format foodservice.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach and Los Angeles rail intermodal complex underwrites North American distribution velocity for stainless steel sheet goods, while Rotterdam's Maasvlakte container terminals anchor European material flows for commercial kitchen fabricators.
United States
Fast-casual chains in Texas, California, and Florida are expanding kitchen footprints and adding dedicated hand-washing stations to meet operational throughput targets. The EPA Safe Drinking Water Act amendments mandate flow restriction compliance, compelling institutional operators toward water-efficient fixture retrofits. Southeastern hospital construction clusters in Georgia and North Carolina specify antimicrobial copper-alloy configurations for infection control.
Germany
Engineering heritage in commercial kitchen systems sustains premium export positioning across hotel and hospital channels. The EU F-Gas Regulation and ECHA REACH compliance frameworks shape material selection for basin fabrication and coating chemistry. Industrial fabricators in Baden-Württemberg concentrate precision welding capacity for specification-grade NSF-certified product lines.
China
Expanded stainless steel fabrication capacity in Guangdong and Zhejiang provinces tilts global supply toward cost-competitive basin production. The GB standards system and MIIT industrial policy directives govern product quality certification for domestic and export markets. Yangtze River Delta manufacturing clusters serve both domestic foodservice modernization and international contract fabrication demand.
Japan
Compact kitchen design traditions drive demand for space-optimized wall-mounted and corner basin configurations in urban restaurant environments. METI energy efficiency guidelines and JIS standards for sanitary fixtures influence product specification in commercial foodservice and hospitality sectors. Osaka-Kansai industrial districts maintain specialized fabrication capacity for high-precision institutional installations.
India
Quick-service restaurant expansion in Maharashtra and Karnataka states generates procurement volume for durable stainless steel wash stations. FSSAI food safety regulations and BIS certification requirements filter non-compliant equipment from institutional procurement lists. Gujarat-based metalworking clusters are scaling fabrication capacity to serve domestic hospitality and healthcare facility construction.
Commercial Sink Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with fabrication and certification expertise. The vendor base stratifies across three tiers: multinational fixture conglomerates with specification-grade portfolios, regional metalworking specialists with NSF-certified production lines, and value-oriented fabricators serving replacement cycles. Two archetypes dominate competitive positioning: European engineering-led premium specialists and North American distribution-anchored volume players. Capacity expansion and strategic specification partnerships with fast-casual chain technical teams represent the dominant competitive moves.
Among European engineering heritage groups, Franke Group and Blanco GmbH exemplify premium-tier positioning through specification-grade product architectures. Elkay Manufacturing Company anchors North American volume distribution through contractor relationship networks and institutional certification compliance. These three entities represent the competitive archetype spectrum: European premium engineering, German precision fabrication, and North American scale distribution.
| Leading Market Players |
|---|
| Elkay Manufacturing Company |
| Franke Group |
| Kohler Co. |
| Blanco GmbH |
| American Standard Brands |
| TOTO Ltd. |
| Duravit AG |
| Roca Sanitario |
| Teka Industrial |
| Others |
Value Chain & Pricing Dynamics
The Port of Long Beach and Los Angeles rail intermodal complex underwrites North American distribution velocity for stainless steel sheet goods, while Rotterdam's Maasvlakte container terminals anchor European material flows for commercial kitchen fabricators. Freight corridor cost dynamics concentrate supply power among NSF-certified fabricators with Guangdong and Zhejiang basin production, compressing margin capture for non-certified value-tier competitors serving replacement cycles in Texas and California.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates specification-grade NSF/ANSI 2-certified fabricators from uncertified regional metalworkers and import-dependent value suppliers. Price differentiation rests on certification grade and volume scale, with fast-casual chain procurement centralization extracting steepest discounts. Cost compression in the economy tier intensifies because nickel and chromium input volatility squeezes non-integrated fabricators. Institutional foodservice operators in the southeastern United States exhibit least price sensitivity, prioritating antimicrobial copper-alloy configurations for infection control compliance.
Supply Chain Analysis
Contract manufacturing concentration tilts toward Guangdong and Zhejiang province fabrication clusters serving both domestic Chinese foodservice modernization and international contract demand. Raw material dependencies center on 304 and 316 stainless steel sheet from Yangtze River Delta mills, nickel and chromium alloying elements, and polymer resin feedstocks for corrosive-wash alternatives. Single-source vulnerability concentrates in TIG welding expertise for 16-gauge precision fabrication, constraining quality throughput across North American contractor networks. Distribution runs through specification-grade distributor showrooms and direct manufacturer engagement with multi-unit chain technical teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
TIG welding expertise scarcity for 16-gauge stainless fabrication thins across the contractor base, constraining quality throughput and compressing replacement cycle timelines for institutional buyers demanding NSF-certified precision work.
For Market Incumbents: Harden specification-grade positioning by deepening captive supply of 304 and 316 stainless sheet through backward integration into Yangtze River Delta mill partnerships, insulating margin capture from nickel price volatility. Anchor channel control through exclusive distributor arrangements with fast-casual chain technical teams in Texas and California, preempting polymer substitution threats in corrosive wash applications. For New Entrants and Emerging Players: India's Maharashtra and Karnataka quick-service restaurant expansion offers white-space penetration for durable stainless wash stations with FSSAI-compliant certification pathways. Target healthcare facility maintenance teams in the southeastern United States with engineered polymer basin configurations for bleach-intensive protocols exceeding stainless tolerance, leveraging direct sales bypass of incumbent distributor networks. For Investors and Strategic Acquirers: Carve-out targets emerge from European engineering heritage groups with dormant North American distribution infrastructure and stranded specification-grade NSF portfolios. Five-to-ten-year viability favors mid-cap fabricators with integrated Guangdong production and captive TIG welding capacity. Watch for EPA Safe Drinking Water Act amendment enforcement intensity as inflection signal for water-efficient fixture retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| NSF/ANSI 2 Certification Investment | Filters non-compliant fabricators from fast-casual chain specification lists across Texas and California. |
| Backward Integration into Stainless Sheet Supply | Captures margin insulation from nickel and chromium commodity volatility affecting 304 and 316 alloys. |
| Sensor-Activated Retrofit Kit Development | Enables fast-casual operators to upgrade existing basins without full station replacement capital burden. |
| Antimicrobial Copper-Alloy Fixture Launch | Addresses southeastern United States hospital infection control mandates for foodservice and clinical wash stations. |
| Direct Engagement with Chain Technical Teams | Bypasses distributor showroom influence loss as specification decisions migrate to culinary operations directors. |
Study Parameters
The analysis maps undermount, wall-mounted, drop-in, and single-basin configurations, each validated through facilities managers, infection control consultants, culinary operations directors, and contractor procurement leads. Primary interviews with fast-casual chain technical teams, hospital foodservice departments, and institutional equipment buyers combined with secondary validation from NSF International certification databases, EPA Safe Drinking Water Act amendment filings, FDA Food Code update documentation, and stainless steel trade flow customs records. Bottom-up basin shipment aggregation and top-down foodservice construction spend triangulation anchored volume estimates.
Assumption sets held fixed regulatory enforcement trajectories for EPA and FDA provisions while varying nickel price volatility scenarios and fast-casual expansion cluster intensity across Texas, California, and Florida. The projection horizon modeled product type, material grade, end-user vertical, and installation format segmentation dimensions. CAGRs derived from basin replacement cycle compression analysis and institutional procurement centralization trends, with healthcare facility modernization waves and sensor-activation adoption curves as industry-specific forecast inputs.
Practitioners should monitor NSF International testing queue lengths, skilled welder labor availability indices, and EPA enforcement intensity for early signals of supply constraint or demand acceleration. Quarterly review of nickel and chromium commodity price movements, fast-casual chain capital expenditure disclosures, and hospital construction permit issuances in Georgia and North Carolina is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Brazil Foodservice Market
Food Service
Japan Foodservice Market
Food Service
Africa Foodservice Market
Food Service
United States Smokeless Indoor Grills Market
Food Service
Vietnam Online Food Delivery Market
Food Service
GCC Food Service Market
Food Service
Asia-Pacific Food Away from Home Market
Food Service
Global Dark Store Market
Food Service
Turkey Food Service Market
Food Service
Saudi Arabia Cloud Kitchen Market
Food Service
Light Meal Market
Food Service
United States Biodegradable Food Service Disposables Market
Food Service
India Online Grocery Market
Food Service
China Retail Bubble Tea Kits Market
Food Service
International Food Subscription Box Service Market
Food Service
United Arab Emirates Foodservice Market