
 Ultrasonic Wall Thickness Gauges Market | 2026-2036
Ultrasonic Wall Thickness Gauges Market Size, Share, and Industry Trends Forecast 2026-2036
Ultrasonic Wall Thickness Gauges Market Analysis
The oil and gas sector is realigning its non-destructive testing procurement toward handheld digital solutions for subsea and downstream assets. Olympus Corporation leverages its transducer miniaturization expertise to dominate offshore inspection contracts. Baker Hughes sustains its position through integrated asset integrity platforms that bundle ultrasonic thickness monitoring with predictive analytics.
Ultrasonic wall thickness gauges emit high-frequency sound pulses into metallic or composite substrates and measure return-time differentials to calculate remaining wall thickness, typically operating between 0.5 MHz and 15 MHz depending on material density and attenuation characteristics. These instruments serve critical safety functions in pressure vessel integrity programs, pipeline corrosion surveys, and structural fatigue assessments where material loss threatens catastrophic failure. Portable gauges lead unit shipments due to field deployment requirements in remote oilfields and elevated infrastructure, while guided wave ultrasonics captures premium pricing for long-range pipe screening applications where access points remain sparse. Digital gauges displace analog predecessors as operators demand Bluetooth-enabled data logging, cloud-connected reporting, and API-compliant documentation trails.
The US Department of Transportation's Pipeline and Hazardous Materials Safety Administration mandates periodic external corrosion direct assessment for interstate pipelines, compelling operators to maintain certified ultrasonic inspection fleets. In Europe, the Pressure Equipment Directive and REACH substance restrictions shape transducer gel formulations and calibration traceability requirements for cross-border equipment deployment. Stakeholders must monitor evolving hydrogen infrastructure codes, as repurposed natural gas pipelines demand modified ultrasonic calibration protocols for embrittlement-sensitive steel grades.
Market Dynamics
Pipeline operators are consolidating inspection workflows around single-vendor digital ecosystems that collapse data silos between field crews and integrity management systems.
Growth Catalysts
- PHMSA inspection mandates:The US Department of Transportation's tightened intervals for hazardous liquid line assessments force operators to expand certified ultrasonic fleets and accelerate replacement cycles for aging analog equipment.
- Subsea infrastructure expansion:Deepwater developments in the Gulf of Mexico and offshore Brazil drive demand for pressure-rated portable gauges with enhanced transducer durability in high-salinity environments.
- Hydrogen pipeline repurposing:European energy transition frameworks prioritize ultrasonic recalibration protocols for embrittlement-sensitive steel grades in converted natural gas networks.
Market Restraints
- Piezoelectric ceramic supply concentration:Specialty transducer materials depend on concentrated rare earth processing capabilities concentrated in East Asian supply chains, exposing gauge manufacturers to input volatility.
- Calibration traceability costs:ISO 17025-accredited laboratory services for thickness standard verification impose recurring operational burdens on mid-sized inspection contractors.
- Guided wave ultrasonic substitution:Long-range screening technologies capture screening applications where single-point thickness measurement previously dominated, compressing addressable volume for conventional gauges.
Strategic Opportunities
- India refinery modernization:The country's Petroleum and Natural Gas Regulatory Board mandates comprehensive integrity assessments for aging downstream assets, creating first-time gauge procurement demand among state-owned processors.
- Cloud-connected predictive maintenance:Convergence of Bluetooth-enabled field instruments with API-compliant data lakes enables subscription-based analytics revenue streams beyond hardware sales.
- Wind turbine tower inspection:Offshore wind installation growth in the North Sea and Baltic corridor generates new demand for composite-compatible thickness measurement in blade root and monopile structures.
Industry Challenges
- ASNT NDT Level II certification scarcity:Qualified ultrasonic technicians command premium wages, constraining inspection contractor capacity expansion and project throughput.
- Legacy system integration friction:Digital gauge deployments face data format incompatibilities with decades-old asset integrity databases maintained by major pipeline operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultrasonic Wall Thickness Gauges Market |
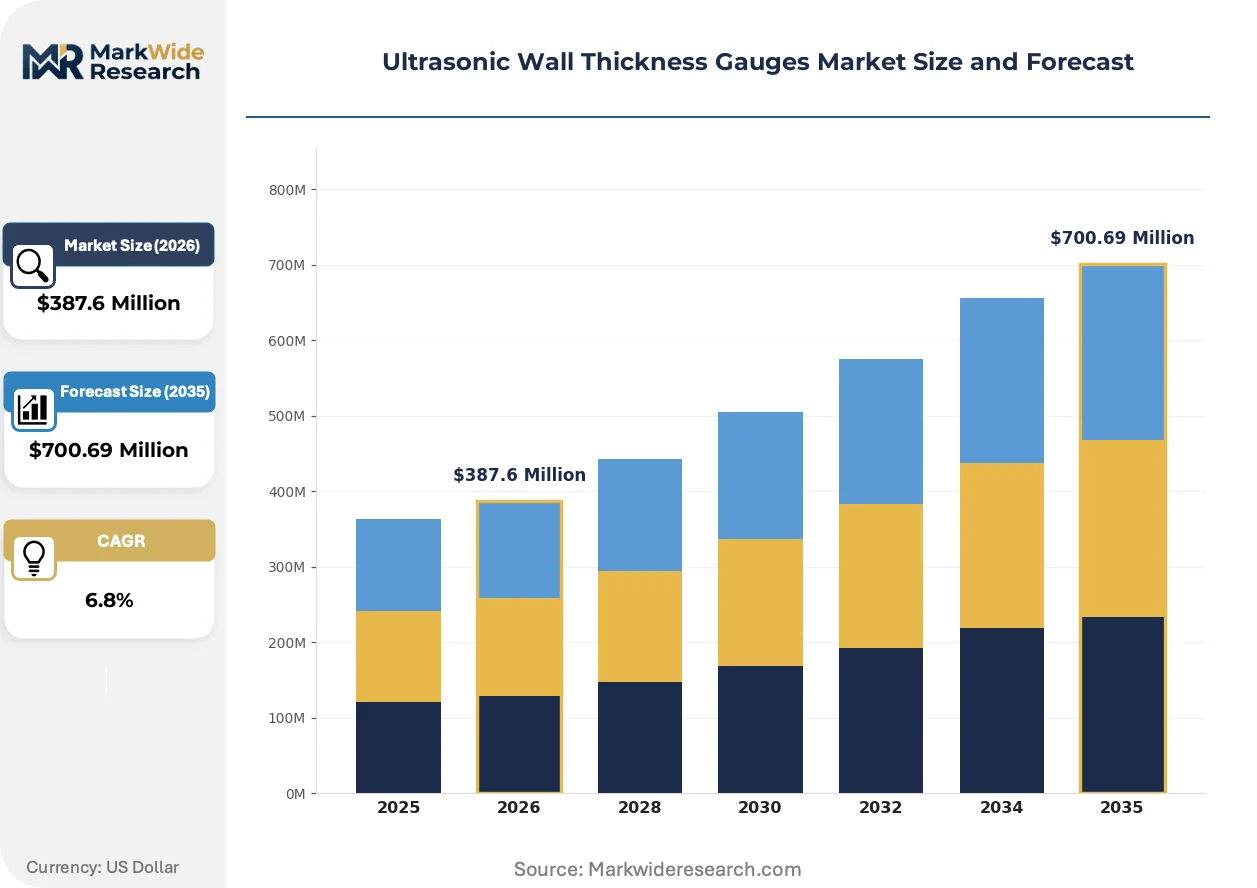
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Gauges, Desktop Gauges, Digital Gauges, Analog Gauges Technology: Ultrasonic Pulse Echo, Ultrasonic Time of Flight, Guided Wave Ultrasonics, Non-Destructive Testing End User: Oil & Gas, Aerospace, Manufacturing, Construction Application: Pipe Inspection, Tank Measurement, Safety Assessment, Structural Evaluation |
| Companies Covered | Olympus Corporation, Baker Hughes, Fischer Technology Inc, Sonotec Ultrasonic Solutions, Intertek Group plc, Cygnus Instruments Ltd, DeFelsko Corporation, Elcometer, Mitchell Instrument Company Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultrasonic Wall Thickness Gauges Market Emerging Trajectories
Digital instrumentation is collapsing the latency between field measurement and engineering decision-making, compressing inspection-to-remediation cycles from weeks to hours.
Phased-array ultrasonic technology is rewriting thickness mapping workflows by delivering volumetric scan data through electronically steerable beams without mechanical transducer movement. Offshore platform operators in the North Sea are adopting these systems for corrosion monitoring in splash zones where access remains hazardous. The technology is rewriting competitive positioning by favoring suppliers with embedded software competencies over traditional hardware-focused gauge manufacturers.
The European Union's CSRD disclosure requirements now mandate granular asset condition reporting for energy infrastructure operators, extending beyond financial metrics to physical integrity indicators. This regulatory architecture forces inspection data standardization across multinational asset portfolios. Midstream operators with cross-border pipelines face the steepest compliance burden, driving demand for gauges with automated ISO-compliant documentation generation.
Inspection contractors are unbundling hardware ownership from measurement services, deploying vendor-managed gauge fleets where clients pay per-test rather than capitalizing equipment. This model disrupts traditional distributor relationships and concentrates purchasing authority with national service providers. The shift is most visible in the United States Gulf Coast petrochemical corridor, where integrated maintenance contractors now specify gauge platforms based on API data interoperability rather than unit price.
Ultrasonic Wall Thickness Gauges Market Segmentation
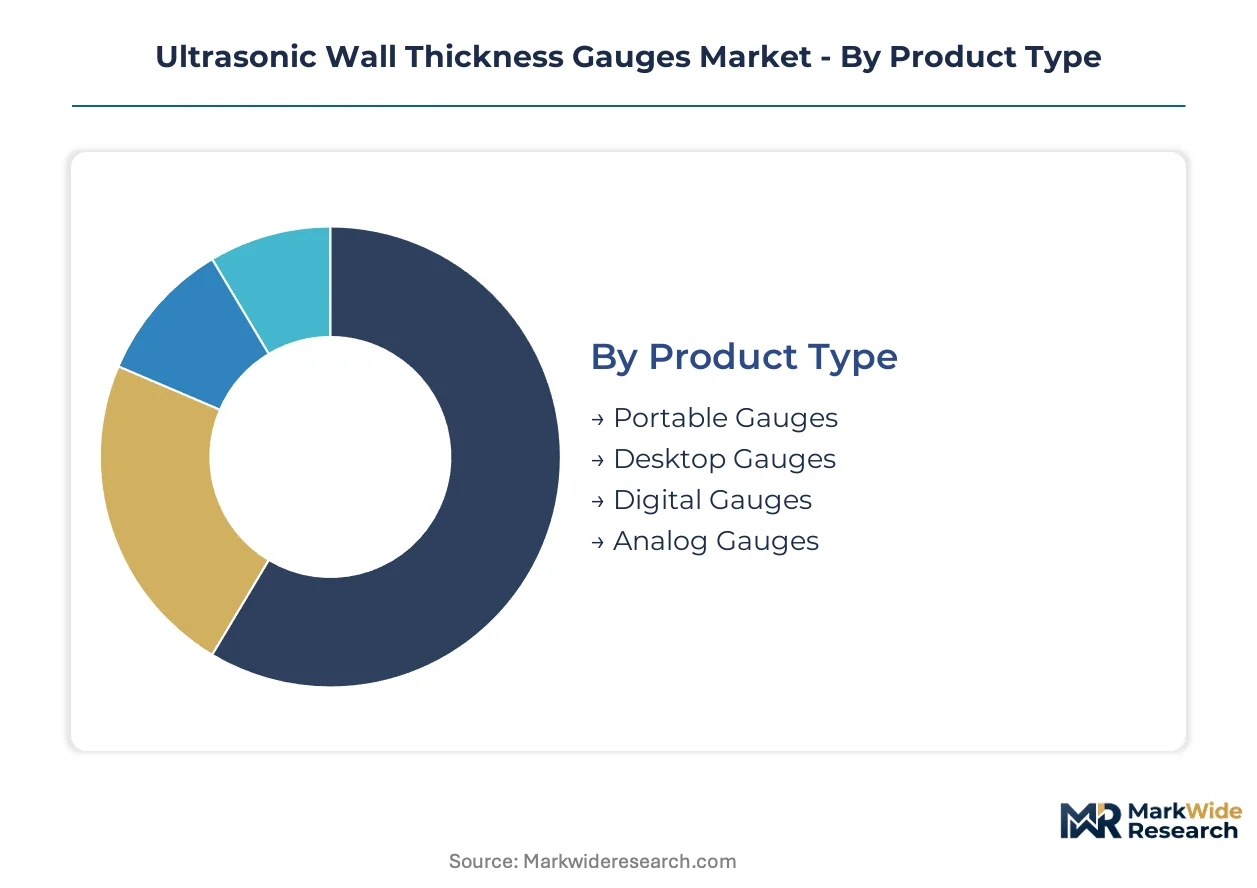
Ultrasonic wall thickness gauges serve divergent operational contexts—from handheld field units for pipeline crews to laboratory-grade desktop systems for metallurgical labs. Segmentation reveals where procurement budgets concentrate and which technologies command pricing premiums across inspection workflows.
Product Type:
Portable gauges dominate unit shipments while desktop systems capture margin concentration in calibration-intensive applications.
- Portable Gauges:Battery-powered handheld units with IP-rated enclosures withstand offshore platform conditions and elevated infrastructure access. Field crews in the United States Gulf Coast petrochemical corridor deploy these for corrosion monitoring campaigns where mobility outweighs laboratory precision.
- Digital Gauges:Bluetooth-enabled instruments with cloud-connected data logging displace analog predecessors as operators demand API-compliant documentation trails and real-time integrity system integration. PHMSA-mandated inspection intervals accelerate replacement cycles toward digital platforms.
- Desktop Gauges:Benchtop systems with automated scanning stages serve metallurgical laboratories and manufacturing quality control stations requiring traceable calibration chains.
- Analog Gauges:Legacy needle-display instruments persist in budget-constrained maintenance operations but face procurement freezes at major pipeline operators.
Today's leader: Portable Gauges. Tomorrow's challenger: Digital Gauges.
Technology:
Single-point measurement techniques anchor current procurement while long-range screening methods reshape competitive boundaries.
- Ultrasonic Pulse Echo:The foundational thickness measurement method emits high-frequency pulses into metallic substrates and calculates wall loss from return-time differentials. Standard equipment for pressure vessel integrity programs across downstream oil and gas assets.
- Guided Wave Ultrasonics:Low-frequency excitation propagates axially along pipe walls, enabling 50-meter screening coverage from single access points. Offshore platform operators in the North Sea adopt these systems for splash zone corrosion monitoring where physical access remains hazardous.
- Ultrasonic Time of Flight:Differential transit-time measurement eliminates couplant dependency for high-temperature surface applications in refinery furnace tube assessment.
- Non-Destructive Testing:Encompasses complementary modalities including eddy current and radiographic methods bundled in integrated inspection service contracts.
Pulse Echo maintains installed base dominance. Guided Wave Ultrasonics gains share fastest in subsea contract awards.
End User:
Asset-intensive process industries drive replacement demand while emerging verticals introduce composite material measurement requirements.
- Oil & Gas:Midstream pipeline operators and downstream refiners constitute the core procurement base. The US Department of Transportation's tightened hazardous liquid line inspection intervals force fleet expansion and equipment modernization across interstate systems.
- Aerospace:MRO facilities and airframe manufacturers deploy precision gauges for turbine blade wall thickness verification and fuselage fatigue assessment where material loss threatens catastrophic failure.
- Manufacturing:Pressure equipment fabricators require certified thickness documentation for ASME code compliance and customer acceptance testing.
- Construction:Structural steel contractors perform thickness verification on weathering steel bridge components and high-rise column sections.
Oil & Gas commands current procurement volume. Aerospace offers the steepest expansion trajectory as fleet renewal accelerates.
Application:
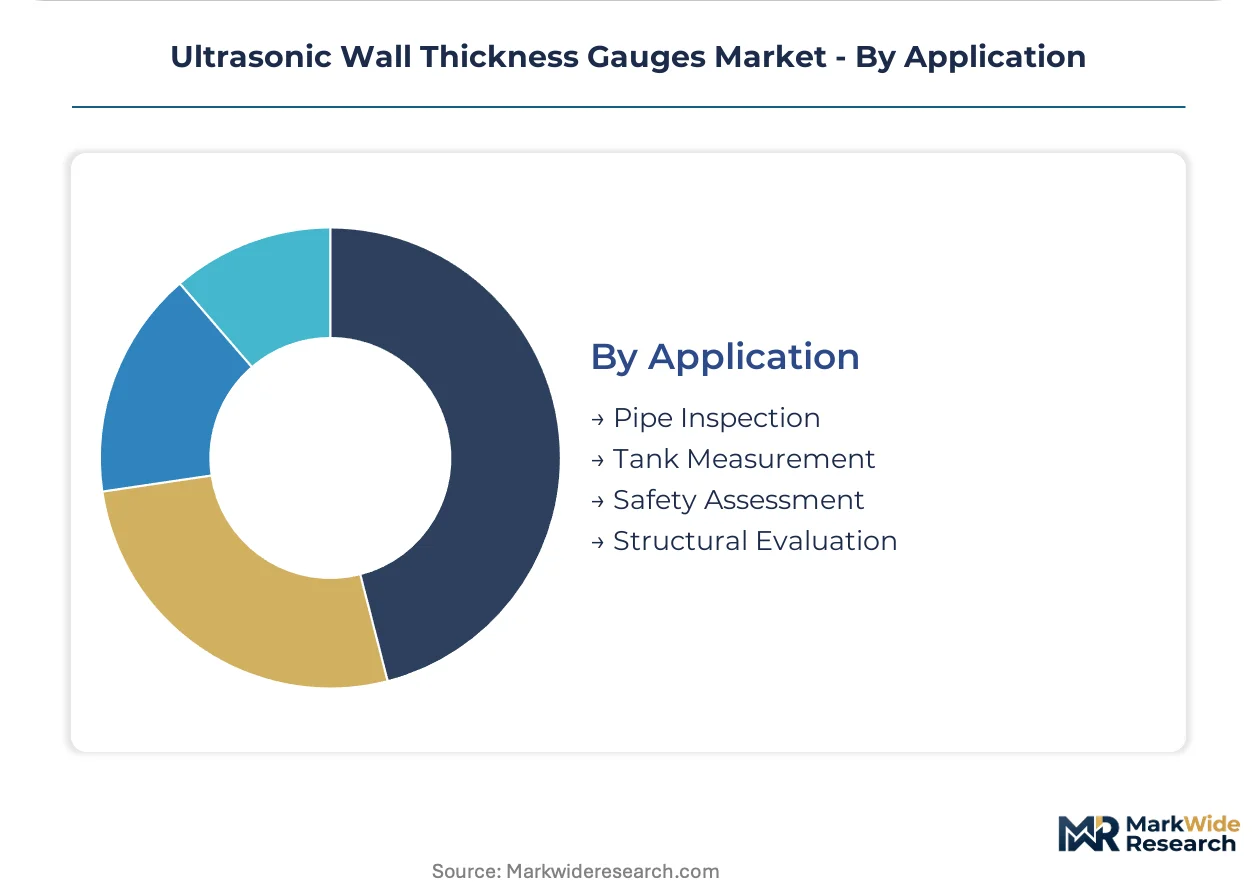
Corrosion monitoring applications concentrate demand while safety-critical assessments justify premium instrumentation.
- Pipe Inspection:External corrosion direct assessment for interstate pipelines under PHMSA jurisdiction constitutes the largest application segment. Operators maintain certified ultrasonic fleets with documented calibration traceability.
- Safety Assessment:Pressure vessel integrity programs for ammonia storage tanks and LPG spheres demand high-reliability measurement with automated documentation generation for regulatory submission.
- Tank Measurement:Aboveground storage tank floor and shell surveys for leak prevention compliance and remaining life estimation.
- Structural Evaluation:Bridge girder and offshore platform member thickness mapping for fatigue life assessment and load rating verification.
Pipe Inspection anchors procurement budgets. Safety Assessment climbs fastest as CSRD disclosure requirements extend to physical integrity indicators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between jurisdictions with stringent inspection mandates and those with emerging enforcement frameworks is redirecting procurement volumes toward markets where compliance costs are offset by asset density and infrastructure age.
United States
Gulf Coast petrochemical operators are expanding certified ultrasonic fleets to meet PHMSA's tightened hazardous liquid pipeline inspection intervals. The Department of Transportation mandates documented calibration traceability for interstate systems. Houston and Corpus Christi anchor procurement concentration as integrated maintenance contractors specify API-interoperable digital platforms.
Germany
Ruhr industrial corridor refineries and chemical complexes drive replacement demand for REACH-compliant transducer formulations. The Pressure Equipment Directive shapes cross-border equipment deployment standards for thickness measurement systems. Bavarian precision instrument manufacturers supply calibration-intensive desktop systems for metallurgical laboratories serving automotive and aerospace certification chains.
China
State-owned pipeline operators in Sichuan-Chongqing shale gas basins are procuring pressure-rated portable units for high-salinity environment deployment. GB standards for non-destructive testing equipment establish domestic certification requirements that foreign suppliers must navigate through joint ventures. Yangtze River Delta manufacturing clusters produce piezoelectric ceramic components concentrated in East Asian supply chains.
Brazil
Offshore pre-salt development operators in the Campos and Santos basins require subsea-rated gauges with enhanced transducer durability. ANVISA-equivalent industrial safety regulations for pressure vessel integrity programs are tightening inspection documentation requirements. Rio de Janeiro-based inspection contractors are consolidating around vendor-managed gauge fleets with per-test pricing models.
India
Petroleum and Natural Gas Regulatory Board mandates for aging refinery integrity assessments are creating first-time procurement demand among state-owned processors. BIS certification requirements for imported NDT equipment impose technical barriers that domestic assemblers are exploiting. Gujarat and Maharashtra downstream clusters are modernizing corrosion monitoring workflows with Bluetooth-enabled field instruments.
Ultrasonic Wall Thickness Gauges Market Vendor Landscape
Strategic partnerships dominate the current landscape as hardware specialists converge with predictive analytics platforms to collapse data silos between field measurement and engineering decision-making. The vendor base organizes around three tiers: diversified industrial conglomerates with integrated asset integrity platforms, precision instrument specialists with transducer miniaturization expertise, and regional service providers deploying vendor-managed gauge fleets. Two competitive moves define current positioning: technology licensing arrangements that embed software competencies into hardware portfolios, and geographic expansion through distributor consolidation in petrochemical corridors.
Among diversified industrial conglomerates, Olympus Corporation and Baker Hughes exemplify contrasting archetypes—one anchored in transducer engineering depth, the other in integrated platform bundling. Fischer Technology Inc represents the precision instrumentation specialist tier with calibration-traceable laboratory systems. Sonotec Ultrasonic Solutions occupies a position within the European specialist segment serving cross-border pipeline operators with CSRD-compliant documentation capabilities. Cygnus Instruments Ltd and DeFelsko Corporation anchor the mid-market portable gauge segment where field durability and unit economics drive procurement decisions.
| Leading Market Players |
|---|
| Olympus Corporation |
| Baker Hughes |
| Fischer Technology Inc |
| Sonotec Ultrasonic Solutions |
| Intertek Group plc |
| Cygnus Instruments Ltd |
| DeFelsko Corporation |
| Elcometer |
| Mitchell Instrument Company Inc |
| Others |
Supply Flow & Price Mechanics
Piezoelectric ceramic feedstock costs cascade through three distinct pricing tiers as raw material volatility from East Asian processing centers compresses margins at the gauge assembly level. PHMSA-mandated calibration traceability requirements force mid-tier inspection contractors toward premium digital platforms despite budget constraints.
Pricing Analysis
Distributor margins absorb the steepest compression as vendor-managed fleet models displace traditional equipment sales. Three-tier pricing structure across premium, standard, and economy levels separates API-compliant digital systems with cloud connectivity from analog legacy units facing procurement freezes. Price differentiation centers on ISO 17025 calibration certification and Bluetooth-enabled data logging capabilities. Pricing pressure stems from guided wave ultrasonic substitution in long-range screening applications where single-point measurement previously dominated. Mid-sized inspection contractors exhibit highest price sensitivity due to recurring laboratory verification burdens, while integrated maintenance contractors prioritize API interoperability over unit economics.
Supply Chain Analysis
Freight costs for pressure-rated portable units escalate disproportionately for subsea-rated enclosures requiring specialized corrosion-resistant alloys. Manufacturing concentrates in China, Germany, and the United States, with Yangtze River Delta clusters producing piezoelectric ceramic components and Bavarian precision houses supplying calibration-intensive desktop systems. Raw material dependencies include rare earth elements for transducer formulations, lithium batteries for field power, and specialty alloys for offshore-rated housings. Single-source vulnerability in East Asian rare earth processing exposes gauge manufacturers to input volatility. Distribution runs through national service providers consolidating purchasing authority in the Gulf Coast petrochemical corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as oil and gas operators abandon analog procurement in favor of API-compliant digital ecosystems with automated documentation generation.
For Market Incumbents: Hedge against guided wave ultrasonic substitution by embedding phased-array capabilities into portable gauge portfolios. Secure backward integration into transducer miniaturization to defend margin position against specialty ceramic supply volatility. Prioritize certification investment in hydrogen pipeline recalibration protocols before European infrastructure codes solidify. For New Entrants and Emerging Players: Begin with vendor-managed fleet deployment in India's state-owned refinery modernization wave, where first-time procurement demand outpaces established service relationships. Target wind turbine tower inspection as the most penetrable emerging vertical, leveraging composite-compatible measurement specifications absent from incumbent oil and gas portfolios. Pursue per-test pricing models to bypass capital-intensive distributor relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where cloud-connected predictive maintenance platforms require software competencies beyond traditional hardware manufacturers. Five-to-ten year viability favors acquirers of embedded analytics specialists over pure-play gauge assemblers. Target acquisition profile encompasses Bluetooth-enabled field instrument developers with API data lake integration capabilities. Signal to watch: ANVISA-equivalent tightening in Brazil forcing documentation standardization that favors integrated platform bundlers.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing Arrangement | Embeds phased-array software competencies into hardware portfolios of traditional gauge manufacturers. |
| Geographic Expansion Through Distributor Consolidation | Captures procurement concentration in United States Gulf Coast petrochemical corridor maintenance contracts. |
| Backward Integration Into Transducer Supply | Reduces exposure to East Asian rare earth processing volatility for critical ceramic components. |
| Cloud-Connected Predictive Maintenance Platform | Enables subscription-based analytics revenue streams beyond transactional hardware sales to inspection contractors. |
| Hydrogen Pipeline Recalibration Protocol Development | Positions suppliers ahead of European embrittlement-sensitive steel grade inspection code finalization. |
Methodological Framework
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with integrity management directors, NDT service company procurement leads, pipeline maintenance supervisors, and transducer manufacturing engineers were cross-validated against PHMSA regulatory filings, API standards documentation, SEC 10-K equipment disclosures, and customs trade data for ultrasonic instrument imports. This dual approach ensures demand-side fleet expansion signals align with supply-side capacity and component availability constraints.
Input-output matrices map unit shipment volumes across portable, digital, desktop, and analog product types against oil and gas, aerospace, manufacturing, and construction end-use segments. CAGRs derive from regression analysis of replacement cycle acceleration, regulatory mandate enforcement trajectories, and emerging application penetration rates. Forecast inputs include PHMSA inspection interval tightening schedules, European hydrogen infrastructure code development timelines, and India refinery modernization procurement waves.
Several conditions sit outside the modeled scope, including abrupt rare earth export restrictions, breakthrough alternative NDT modalities displacing ultrasonic methods, and pipeline operator insolvencies triggering fleet liquidation. Forecasts reflect documented assumptions about regulatory enforcement continuity and technology substitution rates. Stakeholders should weight assumptions against their own operating context and regional regulatory exposure profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Burn-In and System-Level Test (SLT) Platforms for AI Accelerators Market
Test and Measurement
Optical Wafer Inspection Systems Market
Test and Measurement
Noise Dosimeter Market
Test and Measurement
Heat Deformation Tester Market
Test and Measurement
Digital Inspection Tools Market
Test and Measurement
Global Platform Electronic Laboratory Balance Market
Test and Measurement
5G Testing Devices Market
Test and Measurement
AI Inference Hardware Performance Benchmarking Test Systems Market
Test and Measurement
Calibration Management Software Market
Test and Measurement
Continuous Methane Monitoring and Leak Detection Test Equipment Market
Test and Measurement
Ceramic Tester Market
Test and Measurement
LAMEA Semiconductor Metrology and Inspection Market
Test and Measurement
Continuous Friction Tester Market
Test and Measurement
Digital Inspection Market
Test and Measurement
AI-Enabled Testing Market
Test and Measurement
Data Acquisition Equipment Market