
 Burn-In and System-Level Test (SLT) Platforms for AI Accelerators Market | 2026-2036
Burn-In and System-Level Test (SLT) Platforms for AI Accelerators Market Size, Share, and Industry Trends Forecast 2026-2036
Burn-In and System-Level Test (SLT) Platforms for AI Accelerators Market Insights
Chiplet-based architecture is fragmenting the traditional monolithic test flow, forcing platform vendors to support heterogeneous integration protocols. Advantest Corporation leverages its installed base of high-pin-count testers to anchor the premium segment for multi-die AI accelerators. Teradyne competes through flexible instrumentation architectures that sustain R&D intensity across thermal and electrical stress domains. Cohu differentiates by occupying the mid-range modular burn-in niche where cost-per-device economics dominate purchasing decisions.
Burn-In and System-Level Test Platforms for AI Accelerators comprise electromechanical systems that subject semiconductor devices to accelerated thermal cycling between minus 40 and 150 degrees Celsius combined with voltage stress patterns to precipitate early-life failures before field deployment. Their primary purpose is to screen latent defects in high-complexity AI chips where functional yield loss carries catastrophic downstream costs. Integrated SLT Systems command the dominant revenue share because they unify functional pattern execution with environmental stress in a single footprint, while Modular Burn-In Units represent the fastest-expanding category as chip designers demand reconfigurable capacity for prototype-to-production transitions. Custom Test Platforms capture concentrated margin pools where proprietary interconnect topologies for neural network chips require application-specific hardware.
The U.S. Department of Commerce export control framework and the EPA energy efficiency directives are tightening compliance requirements for test equipment deployed in domestic semiconductor fabrication facilities, directly shaping platform specifications and procurement timelines. Japan's METI semiconductor revitalization subsidies and the EU Chips Act facility qualification standards are creating parallel certification pathways that vendors must navigate for market access. Stakeholders must monitor which regulatory jurisdictions achieve interoperability in test protocol standards before committing to platform architectures that risk stranded capacity.
Market Dynamics
Chiplet-based architectures are fragmenting monolithic test flows, forcing platform vendors to reconfigure electromechanical systems for heterogeneous die integration while hyperscale data center operators compress validation timelines for neural network accelerators.
Growth Catalysts
- Advanced packaging proliferation:Taiwan-based foundries cluster near chip fabrication sites, creating concentrated demand for multi-die validation protocols that stress-test interconnect integrity under thermal cycling.
- CHIPS and Science Act capital redirection:U.S. facility qualification standards mandate domestic test capacity expansion, accelerating procurement of integrated SLT systems for onshore AI accelerator production.
- Early-life failure economics:Hyperscale operators face catastrophic downstream costs from latent defects in deployed neural network chips, elevating burn-in screening to a non-negotiable procurement criterion.
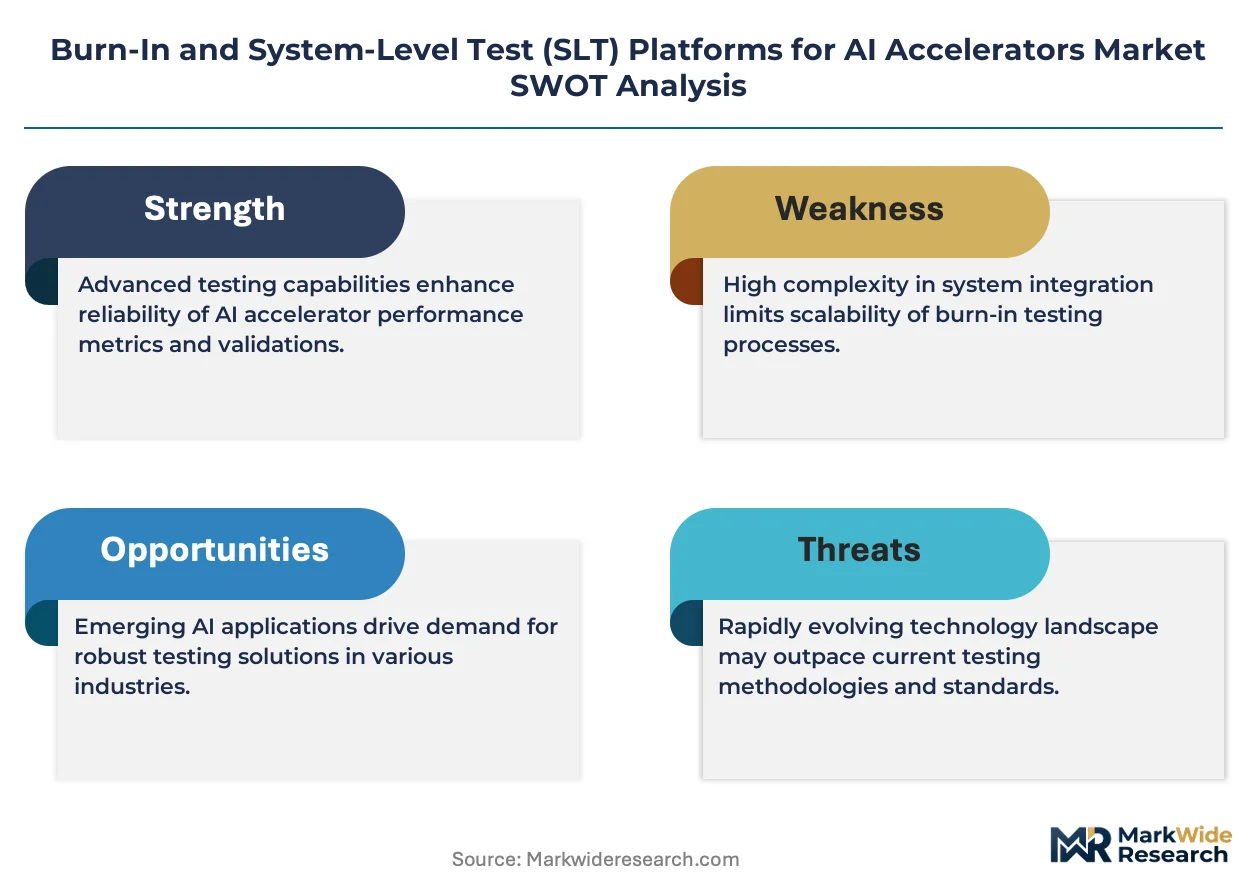
Market Restraints
- Input cost volatility:High-pin-count probe cards and thermal chuck materials experience supply constraints from precision machining capacity limitations in Japanese component suppliers.
- Geographic supply concentration:Advanced packaging test capacity clusters disproportionately in Taiwan, exposing procurement timelines to single-point-of-failure risks from regional infrastructure constraints.
- Technical limitation:Existing platforms struggle to simultaneously stress-test heterogeneous chiplets with divergent thermal profiles and voltage domains in unified test sequences.
Strategic Opportunities
- EU Chips Act facility buildout:European semiconductor fabrication subsidies create qualification pathways for modular burn-in units serving prototype-to-production transitions in Dresden and Leuven clusters.
- Regulatory tailwind:EPA energy efficiency directives for domestic semiconductor facilities shape platform specifications favoring integrated thermal-electric systems that reduce per-device power consumption.
- Technology convergence:Machine learning-based defect prediction algorithms fused with real-time thermal monitoring enable predictive burn-in termination, compressing test duration without yield sacrifice.
Industry Challenges
- Thermal engineering talent scarcity:Platform vendors compete for specialists capable of modeling multi-die junction temperature gradients under accelerated stress conditions.
- Certification timeline compression:METI semiconductor revitalization subsidies and parallel EU qualification standards force vendors to navigate divergent regulatory pathways without stranded capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Burn-In and System-Level Test (SLT) Platforms for AI Accelerators Market |
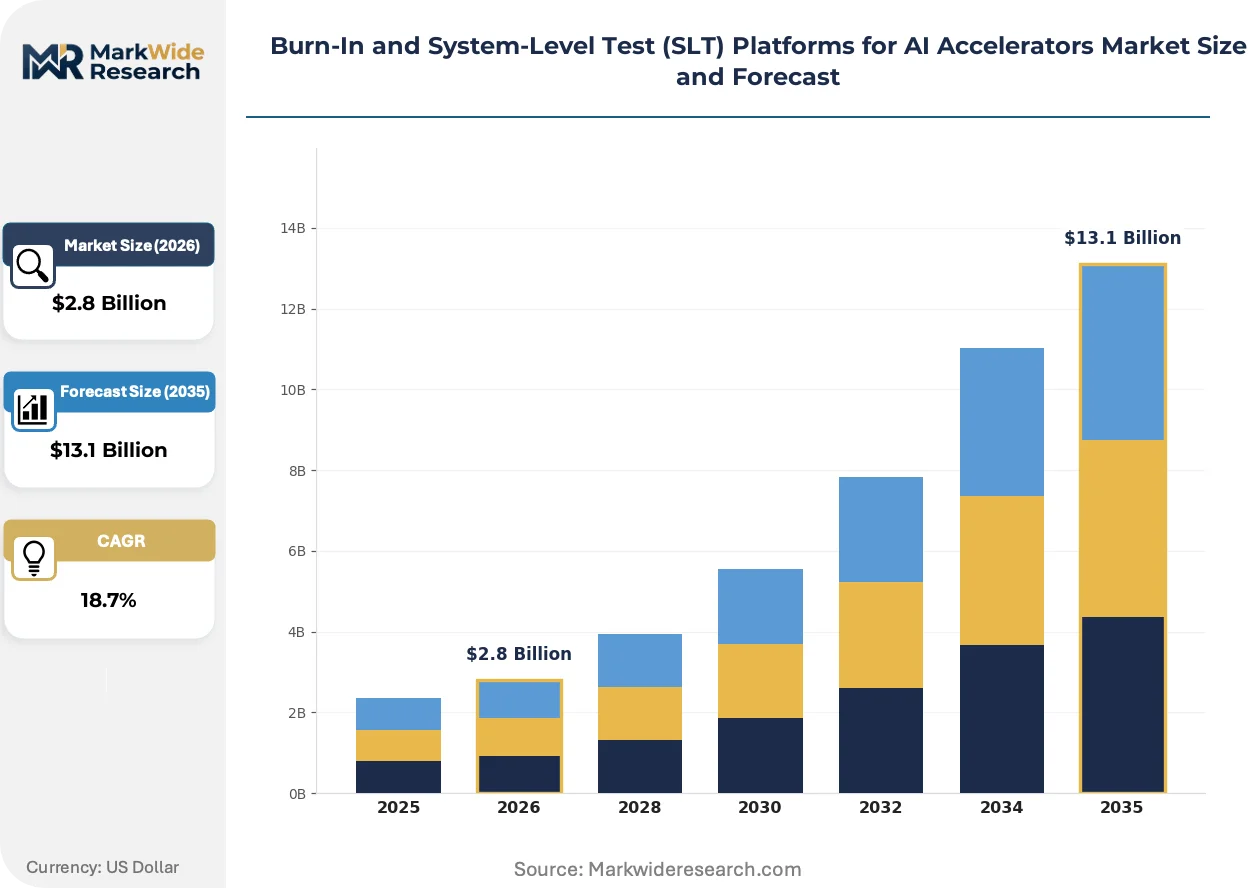
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13.1 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Burn-In System, Integrated SLT System, Custom Test Platforms, Modular Burn-In Units Technology: Temperature Cycling, Voltage Stress, Load Testing, Signal Integrity Analysis, Thermal Shock Application: Edge Computing Devices, Data Processing Units, Neural Network Chips, Autonomous Systems End User: Semiconductor Fabricators, Chip Designers, Test Service Providers, Electronics Manufacturers |
| Companies Covered | Advantest Corporation, Teradyne, Cohu, Chroma ATE, Aehr Test Systems, Hon Precision, Microtest, Keysight Technologies, National Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Burn-In and System-Level Test (SLT) Platforms for AI Accelerators Market Trends and Innovations
Test platform architectures are converging around software-defined instrumentation that decouples hardware footprints from evolving protocol requirements, enabling rapid reconfiguration as AI chip interconnect topologies fragment.
Adaptive thermal control systems utilizing multi-zone chuck architectures with independent temperature gradients are rendering obsolete single-zone burn-in ovens that cannot address heterogeneous chiplet thermal profiles. Hyperscale data center qualification teams are adopting these platforms for next-generation accelerator validation. The structural consequence compresses capital deployment timelines by eliminating redundant thermal cycling sequences for mixed-die devices.
EPA energy efficiency directives targeting domestic semiconductor fabrication facilities are mandating power consumption disclosures and thermal recovery systems for deployed test equipment. Platform vendors must now engineer heat recapture mechanisms and idle-state power management into base system specifications. Integrated SLT system manufacturers face the steepest compliance costs due to their larger thermal envelopes and continuous-duty operational profiles.
Hyperscale operators are consolidating validation procurement through direct platform-as-a-service arrangements that unbundle capital ownership from test capacity access. Traditional distributor and systems integrator channels face margin compression as NVIDIA, Google, and Microsoft negotiate captive test cell deployments at foundry-adjacent locations. Taiwan and Arizona fabrication clusters exhibit the most pronounced channel disintermediation, with data center operators contracting directly with Advantest and Teradyne for multi-year capacity reservations.
Burn-In and System-Level Test (SLT) Platforms for AI Accelerators Market Segmentation
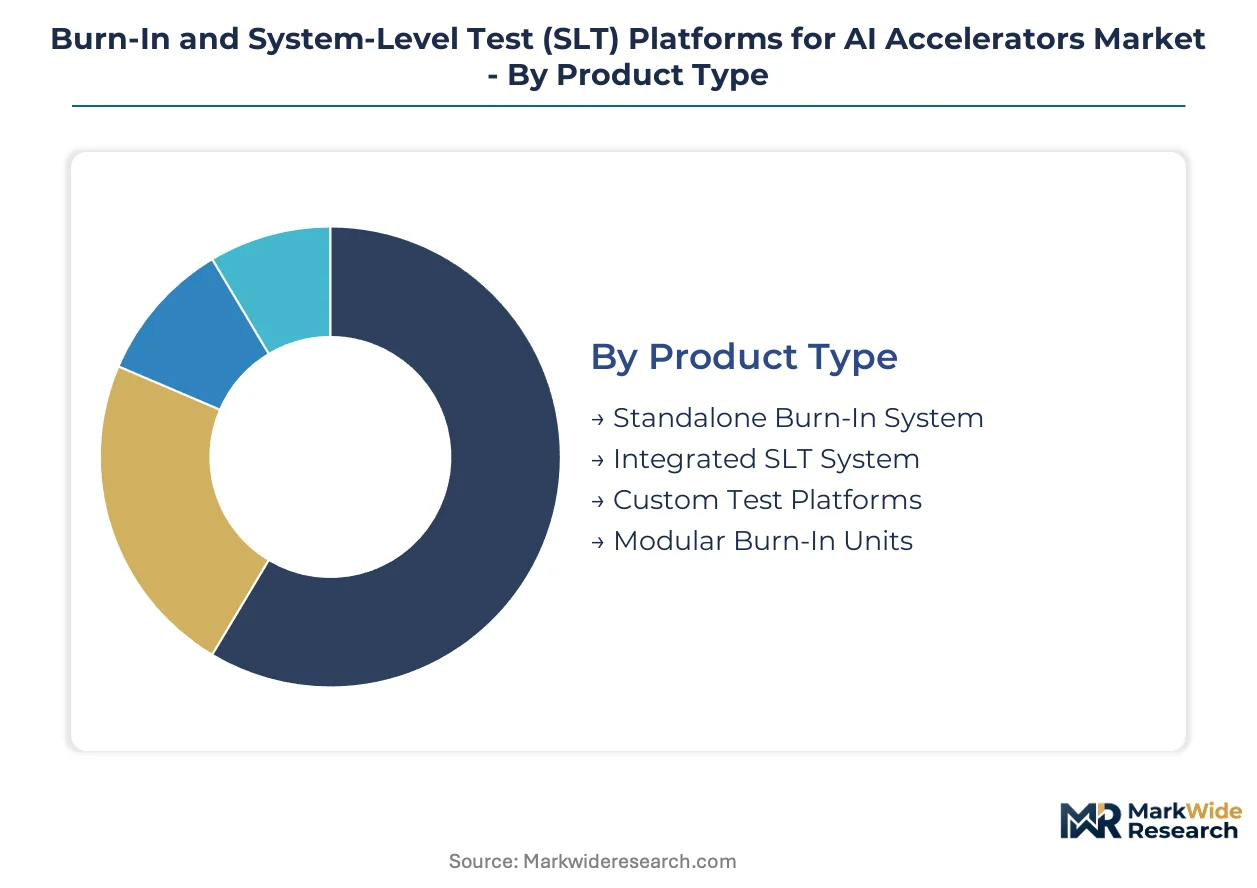
Test platform procurement diverges sharply across product architectures, stress methodologies, and customer sophistication levels. Each dimension carries distinct margin profiles and technical requirements that shape vendor positioning and capacity planning decisions.
Product Type:
Cost tier determines capital deployment patterns and customer retention economics across the platform landscape.
- Integrated SLT System:These systems unify functional pattern execution with environmental stress in a single footprint, eliminating redundant handling steps. Hyperscale data center operators in Taiwan and Arizona procurement clusters specify these platforms for high-volume neural network accelerator validation where downstream failure costs dominate economics.
- Modular Burn-In Units:Reconfigurable architectures support rapid retooling between prototype and production phases without full platform replacement. Dresden and Leuven semiconductor clusters exhibit concentrated demand as European facility buildouts prioritize flexible capacity for heterogeneous chiplet integration.
- Standalone Burn-In System:Discrete thermal cycling ovens serve legacy device portfolios and cost-sensitive volume screening.
- Custom Test Platforms:Application-specific hardware addresses proprietary interconnect topologies for neural network chips with concentrated margin capture.
Integrated SLT Systems command the established base. The steepest expansion runs through Modular Burn-In Units.
Technology:
Application specificity separates mature thermal methods from emerging electrical stress protocols required for advanced packaging validation.
- Temperature Cycling:Accelerated thermal cycling between minus 40 and 150 degrees Celsius precipitates thermomechanical defects in high-complexity AI chips. Taiwan-based advanced packaging foundries deploy these protocols most intensively where multi-die interconnect integrity determines field reliability.
- Voltage Stress:Patterned electrical overstress accelerates gate oxide degradation and electromigration failures. U.S. CHIPS Act facility qualifications mandate these capabilities for domestic AI accelerator production lines.
- Load Testing:Functional stress under operational power profiles validates thermal design power margins.
- Signal Integrity Analysis:High-speed interconnect characterization addresses chiplet-to-chiplet communication margins.
- Thermal Shock:Rapid temperature transition protocols screen for package delamination in automotive-qualified devices.
Temperature Cycling retains the largest installed base. Voltage Stress is climbing the fastest as voltage domain complexity multiplies in heterogeneous integration.
Application:
Compute location and workload intensity dictate thermal envelope requirements and test duration economics.
- Neural Network Chips:Massive tensor operation arrays generate concentrated heat flux requiring multi-zone thermal management. Hyperscale operators face catastrophic downstream costs from latent defects, elevating burn-in screening to non-negotiable procurement criteria for these devices.
- Data Processing Units:Memory-intensive architectures stress power delivery networks and thermal interfaces differently than compute-centric designs. Arizona fabrication clusters show accelerating procurement as domestic capacity expansion proceeds.
- Edge Computing Devices:Constrained thermal budgets and extended operational lifecycles drive extended stress duration requirements.
- Autonomous Systems:Functional safety certification mandates deterministic failure mode coverage beyond standard commercial screening.
Neural Network Chips anchor current revenue concentration. Data Processing Units are gaining share fastest from domestic supply chain investments.
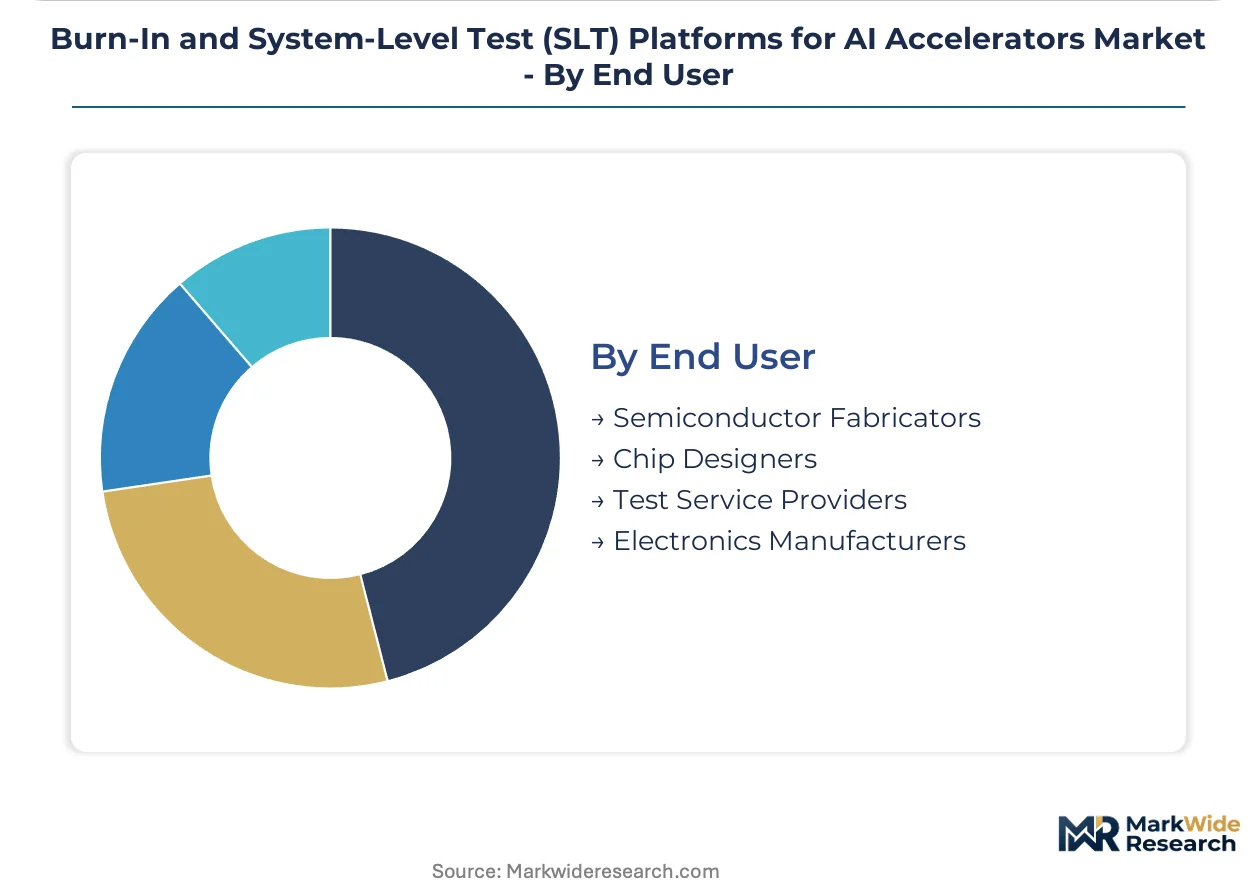
End User:
Customer technical sophistication and captive volume scale determine platform ownership versus outsourced service preferences.
- Semiconductor Fabricators:High-volume captive test cells at Taiwan and Arizona foundry sites require continuous-duty thermal systems with predictive maintenance integration. These operators negotiate direct platform-as-a-service arrangements that disintermediate traditional distribution channels.
- Test Service Providers:Multi-customer load consolidation demands rapid protocol reconfiguration and mixed-lot handling capabilities. Japanese precision machining supply constraints for high-pin-count probe cards compress these providers' capital deployment timelines.
- Chip Designers:Pre-silicon validation and early yield learning drive modular platform preferences for prototype-to-production transitions.
- Electronics Manufacturers:System-level integration testing of AI accelerator modules requires less specialized thermal stress capacity.
Semiconductor Fabricators represent the dominant ownership base. Test Service Providers show the steepest capacity expansion trajectory from channel disintermediation pressures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Test platform trade flows reflect concentrated import dependence in regions building domestic semiconductor capacity, while established fabrication clusters export validation services through integrated captive facilities.
United States
Arizona and Texas fabrication clusters are absorbing CHIPS Act capital for domestic AI accelerator production, triggering procurement of integrated SLT systems. EPA energy efficiency directives mandate thermal recovery systems in new test equipment installations. Phoenix-area foundry sites negotiate direct platform-as-a-service arrangements that bypass traditional distribution channels.
Taiwan
Advanced packaging foundries cluster near Hsinchu and Tainan chip fabrication sites, creating concentrated demand for multi-die validation protocols. The country's national semiconductor regulator coordinates test protocol standards with domestic equipment vendors. Taipei-based hyperscale operators contract directly with platform manufacturers for multi-year capacity reservations.
Japan
Precision machining capacity limitations constrain high-pin-count probe card supply for domestic test service providers. METI semiconductor revitalization subsidies create parallel certification pathways for platform vendors seeking market access. Kyushu fabrication facilities prioritize thermal chuck material sourcing from domestic component suppliers.
Germany
Dresden and Leuven-adjacent semiconductor clusters exhibit concentrated demand for modular burn-in units serving prototype-to-production transitions. EU Chips Act facility qualification standards shape procurement specifications for European fabrication buildouts. Saxony-based test service providers face compressed capital deployment timelines from supply constraints.
South Korea
Memory-intensive AI accelerator architectures drive differentiated thermal interface stress testing requirements in domestic fabrication facilities. The country's national industrial technology regulator coordinates standards alignment with Japanese and Taiwanese counterparts. Seoul Capital Area foundry sites prioritize voltage stress capabilities for heterogeneous chiplet integration.
Burn-In and System-Level Test (SLT) Platforms for AI Accelerators Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers, with premium-positioned vendors anchoring high-pin-count validation for multi-die accelerators while mid-range modular specialists capture flexible capacity demand. Strategic archetypes include integrated system manufacturers, modular platform specialists, and custom hardware fabricators serving proprietary interconnect topologies. Dominant competitive moves center on direct platform-as-a-service arrangements with hyperscale operators and predictive maintenance integration for continuous-duty captive test cells.
Among Japan-based test equipment manufacturers, Advantest Corporation occupies a position exemplifying the premium integrated system archetype for neural network chip validation. Teradyne represents the flexible instrumentation tier competing across thermal and electrical stress domains with reconfigurable architectures. Cohu sits within the mid-range modular segment where cost-per-device economics govern purchasing decisions for prototype-to-production transitions.
| Leading Market Players |
|---|
| Advantest Corporation |
| Teradyne |
| Cohu |
| Chroma ATE |
| Aehr Test Systems |
| Hon Precision |
| Microtest |
| Keysight Technologies |
| National Instruments |
| Others |
Pricing and Supply Chain Analysis
Trans-Pacific freight corridors linking Japanese precision machining hubs to Taiwan packaging foundries impose cost premiums that cascade through high-pin-count probe card supply chains, compressing margins for modular burn-in unit vendors while amplifying price premiums for integrated SLT systems with captive thermal chuck sourcing.
Pricing Analysis
Current-generation integrated SLT systems command substantial premiums over prior-generation standalone burn-in ovens, while next-generation adaptive thermal control platforms with multi-zone chuck architectures extract further markups from hyperscale operators facing catastrophic downstream failure costs. Three-tier pricing structure across premium, standard, and economy levels stratifies by thermal zone count and predictive maintenance integration, with certification-grade EPA compliance tiers adding differentiation. Cost compression in mid-range modular segments intensifies because Japanese precision machining constraints limit high-pin-count probe card availability. Test service providers exhibit highest price sensitivity due to multi-customer load consolidation pressures, whereas hyperscale data center operators prioritize yield protection over unit economics.
Supply Chain Analysis
U.S. Department of Commerce export control frameworks restricting advanced thermal chuck and precision probe card technologies limit component flows from Japanese suppliers to Chinese end-users, reshaping procurement patterns. Manufacturing concentration centers on Taiwan for advanced packaging test capacity, Japan for precision machining components, and the United States for integrated SLT system final assembly. Raw material dependencies span thermal chuck ceramics from Kyushu suppliers, high-pin-count probe card substrates from precision machining facilities in Aichi Prefecture, and software-defined instrumentation controllers from domestic U.S. vendors. Single-source vulnerability runs through Japanese precision machining capacity for critical thermal interface components. Distribution runs through direct platform-as-a-service arrangements that disintermediate traditional systems integrator channels at Taiwan and Arizona fabrication clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment around EPA energy efficiency directives and METI certification pathways erects formidable barriers against unqualified competitors, with switching costs amplified by hyperscale operators' multi-year capacity reservation commitments.
For Market Incumbents: Pre-empt emerging modular platform specialists by securing exclusive thermal chuck material offtake agreements with Japanese precision machining suppliers before capacity constraints worsen. Anchor defensive positioning through backward integration into predictive maintenance software stacks that deepen captive test cell relationships with hyperscale operators, neutralizing the threat of flexible instrumentation architectures from reconfigurable platform competitors. For New Entrants and Emerging Players: Arizona fabrication cluster underpenetration by modular burn-in specialists creates white-space opportunity for prototype-to-production transition capacity serving domestic CHIPS Act facility buildouts. European Dresden and Leuven semiconductor clusters offer secondary entry points where EU Chips Act qualification standards favor new vendors with adaptive thermal control expertise. Pursue channel partnerships with test service providers facing compressed capital deployment timelines from probe card supply constraints. For Investors and Strategic Acquirers: Mid-range modular platform vendors with reconfigurable architectures and established European regulatory certifications represent the most compelling acquisition target archetype for portfolio exposure to chiplet-driven test flow fragmentation. Long-term viability hinges on sustained capital redirection toward domestic semiconductor capacity across multiple regulatory jurisdictions. Monitor EPA thermal recovery system mandate enforcement intensity as the critical inflection signal for integrated SLT system manufacturer margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Platform-as-a-Service Capacity Reservation | Hyperscale operators in Taiwan and Arizona bypass distribution channels through multi-year direct contracts. |
| Adaptive Thermal Control System Launch | Multi-zone chuck architectures with independent temperature gradients address heterogeneous chiplet validation requirements. |
| Backward Integration into Thermal Chuck Supply | Captive ceramic sourcing from Kyushu suppliers mitigates Japanese precision machining capacity constraints. |
| Predictive Maintenance Software Development | Machine learning-based defect prediction algorithms enable burn-in termination optimization without yield sacrifice. |
| EU Chips Act Certification Investment | Dresden and Leuven facility qualification standards create parallel regulatory pathway for modular platform vendors. |
Research Methodology
A spread of perspectives from platform engineering directors at integrated system manufacturers, thermal chuck procurement leads at Taiwanese foundries, EPA compliance officers at Arizona fabrication facilities, and test service provider operations heads converged on the working assumptions underlying this analysis. Primary interview intelligence combined with secondary validation from SEC equipment vendor filings, Japanese METI semiconductor subsidy disclosures, EPA energy efficiency directive documentation, and EU Chips Act facility qualification standards. Bottom-up segmentation modeling and top-down market sizing triangulated across product type, technology protocol, application workload, and end-user sophistication dimensions.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with capacity installation rates at Taiwan and Arizona fabrication clusters weighted against Japanese precision machining output constraints. Segmentation dimensions modeled encompassed platform architecture tier, stress methodology protocol, AI accelerator compute location, and customer ownership structure. CAGRs derived from installed base evolution and replacement cycle compression patterns. Industry-specific forecast inputs included hyperscale data center capex disclosure trajectories and CHIPS Act facility qualification timeline acceleration.
Practitioners should monitor export control expansion scope, EPA thermal recovery mandate enforcement timing, and Japanese precision machining capacity utilization rates for early signals of forecast deviation. Forecasts reflect assumptions around sustained hyperscale operator procurement intensity and regulatory jurisdiction interoperability achievement. Material shifts in U.S.-China technology transfer restrictions or abrupt Japanese supplier consolidation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Noise Vibration Harshness (NVH) Testing Market
Test and Measurement
High Rate Discharge Test Machine Market
Test and Measurement
Volte Testing Market
Test and Measurement
Air Leak Testing Market
Test and Measurement
Permeability Testing Machine Market
Test and Measurement
Automated Ultrasonic Testing Market
Test and Measurement
Solid-State Battery Fast-Charge Degradation Test Systems Market
Test and Measurement
Burst Strength Tester Market
Test and Measurement
Wireless Network Test Equipment Market
Test and Measurement
Miniaturized Package Solder Joint Reliability Test Equipment Market
Test and Measurement
Battery Drop Tester Market
Test and Measurement
North America Electrical Testing Services Market
Test and Measurement
Satellite Communications and Direct-to-Device RF Test Platforms Market
Test and Measurement
Test Benches Market
Test and Measurement
Industrial Direct Radiography Market
Test and Measurement
Digital Oscilloscope Market