
 Continuous Friction Tester Market | 2026-2036
Continuous Friction Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Continuous Friction Tester Market Analysis
The gap between premium automated runway systems and basic portable units is expanding. Dynatest International leverages its installed base across Nordic airports to sustain service revenue through calibration contracts. SARSYS-ASFT AB anchors European market presence with ice-detection-integrated friction platforms. Neubert Aero Corp differentiates through FAA-certified continuous measurement systems for US military airfields.
A continuous friction tester measures the coefficient of friction between a standardized rubber tire and a test surface under controlled load and water-film conditions, typically generating data at intervals below one meter for highway or runway profiling. The device serves civil aviation authorities and road agencies seeking objective surface-condition documentation for safety compliance. Portable testers capture the fastest growth among product types as developing aviation markets prioritize capital-light deployment over fixed installations. Aerospace companies represent the deepest margin pool among end users due to stringent OEM certification requirements for brake-lining materials. ASTM-classified systems dominate North American procurement while ISO-standard equipment prevails across European tenders.
FAA Advisory Circular 150/5320-12C and ICAO Annex 14 Volume I establish minimum friction thresholds that directly shape equipment replacement cycles and sensor-upgrade demand. The US EPA and EU REACH framework both regulate tire-wear particulate composition, affecting the supply chain for standardized test tires that form consumable revenue streams for tester manufacturers. Stakeholders must weigh calibration-network density against sensor-modularity roadmaps when selecting platform partners for long-term fleet contracts.
Market Dynamics
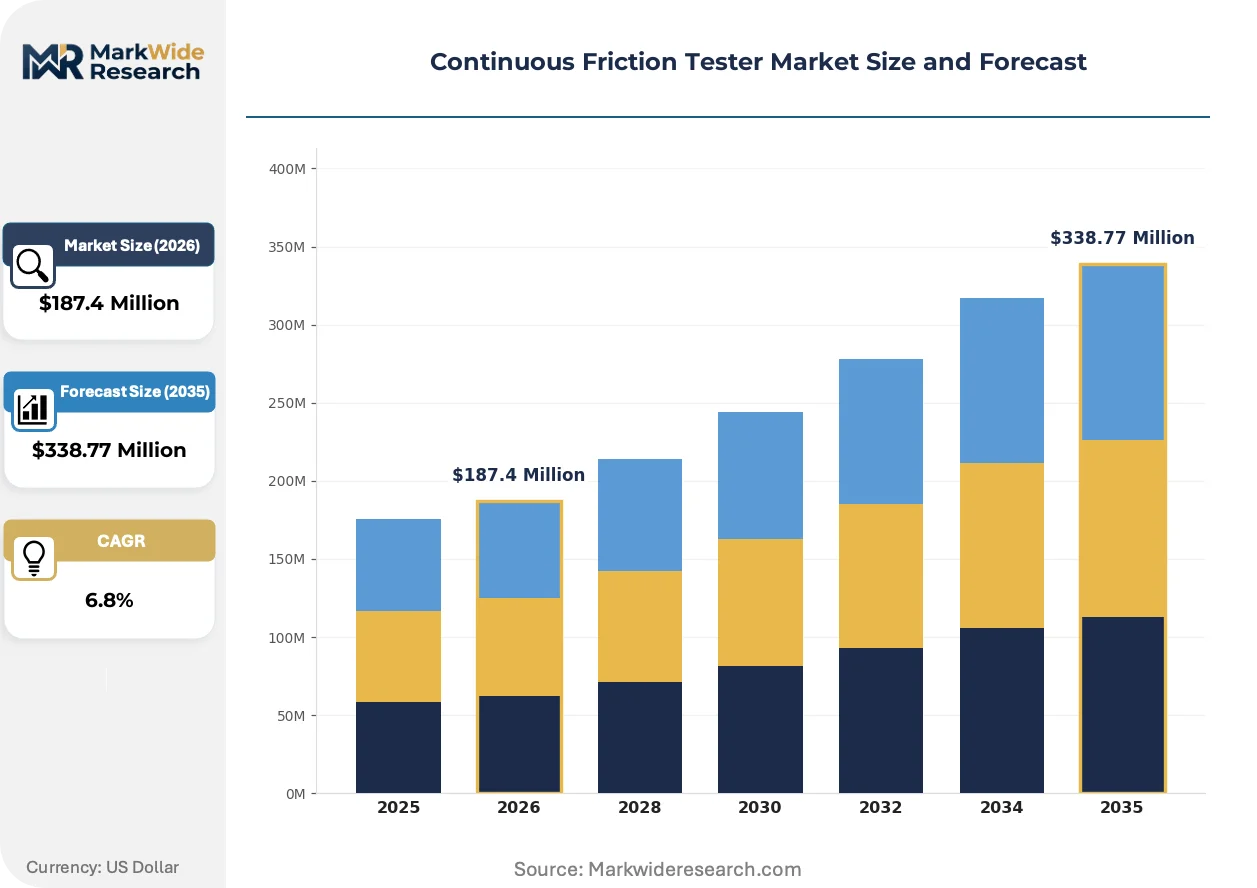
Regulatory tightening around runway friction measurement accuracy is compressing replacement cycles and forcing sensor upgrades across installed fleets. FAA Advisory Circular 150/5320-12C and ICAO Annex 14 Volume I now mandate documented friction thresholds that legacy analog systems cannot satisfy.
Growth Catalysts
- ICAO Annex 14 compliance mandates:National aviation authorities in Germany and France now require periodic friction coefficient verification on all commercial runways, directly stimulating equipment procurement.
- Winter operations safety programs:Airport authorities across Nordic markets are expanding continuous friction tester deployment to meet seasonal operational compliance standards.
- Portable unit prioritization:Developing aviation markets favor capital-light portable testers over fixed installations, accelerating volume demand in Southeast Asia and Latin America.
Market Restraints
- Standardized test tire supply concentration:US EPA and EU REACH regulations on tire-wear particulate composition limit qualified suppliers, creating consumable revenue bottlenecks for manufacturers.
- Calibration infrastructure gaps:Sparse third-party calibration networks in emerging aviation markets extend equipment downtime and raise total cost of ownership.
- Fixed installation capital intensity:Automated runway systems require substantial civil works and integration with airport data networks, constraining adoption at secondary airfields.
Strategic Opportunities
- Ice-detection integration:Convergence of friction measurement with meteorological sensors creates premium platform opportunities for Nordic and Alpine airport operators.
- US military airfield expansion:FAA-certified continuous measurement systems face mandated procurement across Department of Defense runway portfolios.
- Service revenue capture:Dense calibration contract networks defend incumbent positions and generate recurring revenue streams independent of hardware sales cycles.
Industry Challenges
- ASTM-ISO standard divergence:North American ASTM-classified systems and European ISO-standard equipment require separate certification pathways, fragmenting R&D and complicating global product strategies.
- Sensor-modularity roadmap execution:Buyers demand field-upgradeable sensor architectures, pressuring manufacturers to balance backward compatibility against next-generation performance gains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Continuous Friction Tester Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Tester, Bench-Top Tester, Portable Tester, Automated Tester End User: Automotive Manufacturers, Textile Industry, Electronics Sector, Aerospace Companies Test Standard: ASTM, ISO, TAPPI, DIN Material Type: Metals, Plastics, Composites, Coatings |
| Companies Covered | Dynatest International, SARSYS-ASFT AB, Neubert Aero Corp, GripTester, Findlay Irvine Ltd., Norsemeter AS, Moventor Ltd., Controls Group, Humboldt Mfg. Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Continuous Friction Tester Market Emerging Trajectories
Measurement technology is fragmenting across portable, vehicle-mounted, and fixed-installation architectures while regulatory precision demands intensify. Three developments are reshaping competitive positioning and buyer procurement patterns.
Wireless data transmission architectures are decentralizing friction data collection from centralized airport operations centers. Regional airport authorities in Canada and Australia are piloting cloud-connected portable units that stream real-time coefficient readings directly to ground crew tablets. This architecture compresses response times for surface treatment decisions and reduces dependency on fixed network infrastructure.
REACH framework amendments on rubber particulate emissions are tightening standardized test tire specifications across European tenders. Manufacturers must reformulate tire compounds or qualify alternative suppliers, extending new product validation timelines. German national aviation authority procurement cycles now explicitly reference ECHA substance restriction lists in technical specifications.
Buyer organizations are unbundling after-sales service from initial equipment contracts. Airport operators in France and the Netherlands now separately tender calibration and maintenance services, opening entry points for specialized service providers. This pattern is most visible among mid-sized regional airports seeking to reduce captive dependence on original equipment vendors.
Continuous Friction Tester Market Segmentation
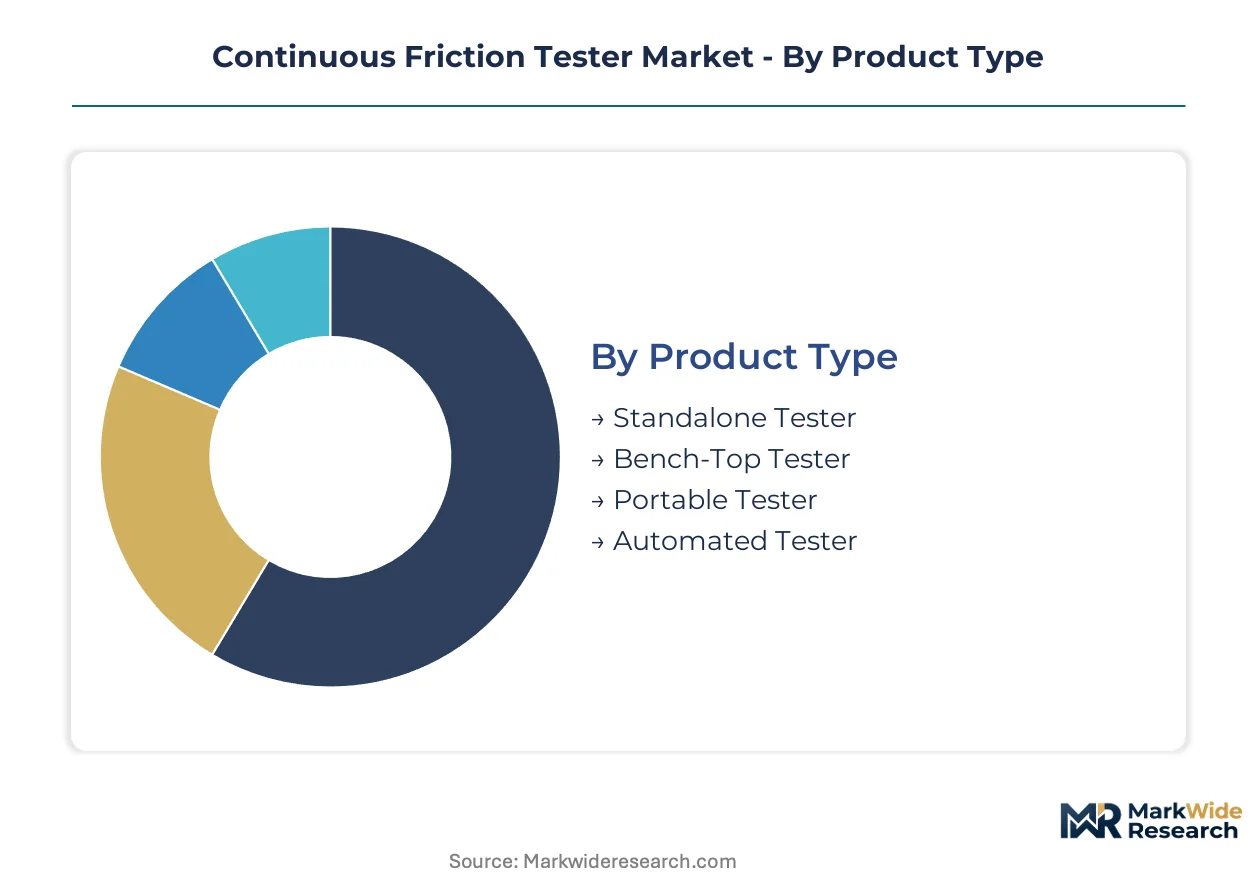
Segmentation in the continuous friction tester market reveals divergent upgrade cycles across equipment architectures and end-use certification requirements. Procurement patterns split sharply between capital-intensive fixed installations and rapidly deployable portable units, with regulatory standard alignment determining replacement urgency.
Product Type:
Replacement cycles compress fastest where regulatory precision demands intensify, forcing sensor obsolescence across legacy analog platforms.
- Portable Tester:Battery-powered units with wireless data transmission enable rapid deployment across multiple runway surfaces without fixed infrastructure. Developing aviation markets in Southeast Asia and Latin America prioritize these capital-light systems for seasonal compliance verification, accelerating procurement velocity.
- Automated Tester:Fixed-installation systems integrate directly with airport data networks for continuous coefficient monitoring under ICAO Annex 14 mandates. Nordic airport authorities deploy these for winter operations compliance, though civil works requirements constrain adoption at secondary airfields.
- Standalone Tester:Self-contained vehicle-mounted platforms deliver highway and runway profiling without permanent infrastructure.
- Bench-Top Tester:Laboratory-grade systems serve material validation workflows for brake-lining manufacturers.
Portable Tester sits at the top of the volume ranking, with Automated Tester climbing the fastest.
End User:
Margin concentration tracks certification stringency, with OEM validation requirements creating the deepest profit pools.
- Aerospace Companies:Brake-lining material certification demands continuous friction measurement under ASTM E1551 and ISO standards for airworthiness approval. FAA and EASA mandates for documented friction thresholds sustain replacement demand across military and commercial airfield portfolios.
- Automotive Manufacturers:Tire-road interaction testing for wet-grip ratings requires standardized coefficient measurement under UN ECE R117 protocols. European KBA and US NHTSA compliance programs drive periodic equipment refresh cycles.
- Textile Industry:Fabric-to-fabric friction testing supports quality control in technical textile production.
- Electronics Sector:Connector insertion force validation and membrane switch testing utilize bench-top friction platforms.
Aerospace Companies command the highest margin tier, with Automotive Manufacturers expanding most quickly.
Test Standard:
Standard divergence fragments procurement specifications across regional tender markets, complicating global product strategies.
- ASTM:North American aviation and highway agencies specify ASTM E1551 and ASTM E274 protocols for coefficient measurement accuracy. FAA Advisory Circular 150/5320-12C references these standards directly, shaping US military and commercial airport procurement.
- ISO:European tenders mandate ISO 8349 and ISO 23678 specifications for runway friction reporting. German national aviation authority and French DGAC procurement cycles explicitly require ISO-compliant equipment for periodic verification mandates.
- TAPPI:Pulp and paper industry applications specify coefficient measurement for sheet handling properties.
- DIN:German industrial standards govern material testing workflows in automotive and manufacturing sectors.
ASTM dominates North American procurement volume, with ISO gaining share fastest in European tenders.
Material Type:
Application breadth varies with surface complexity, from homogeneous metal substrates to multi-layer composite architectures.
- Metals:Steel and aluminum alloy friction characterization supports brake rotor development and industrial machinery design. Automotive OEMs and aerospace suppliers require high-frequency testing for wear-rate prediction under standardized load conditions.
- Composites:Carbon-fiber and ceramic-matrix materials demand specialized test protocols for anisotropic friction behavior. Aircraft brake manufacturers utilize continuous measurement for thermal degradation assessment in landing gear systems.
- Plastics:Polymer friction testing serves packaging machinery and consumer product development.
- Coatings:Surface treatment validation requires thin-film friction measurement for automotive and industrial applications.
Metals testing represents the largest installed base, with Composites expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States diverge sharply in procurement rhythm, with German authorities mandating periodic friction verification cycles that outpace FAA-driven replacement timelines in North America.
United States
FAA Advisory Circular 150/5320-12C drives equipment refresh demand across commercial and military airfield portfolios. The EPA regulates standardized test tire composition under tire-wear particulate frameworks, constraining consumable supplier pools. Chicago O'Hare and Dallas-Fort Worth anchor the densest installed bases of automated runway systems.
Germany
The national aviation authority mandates periodic friction coefficient verification on all commercial runways, compressing replacement cycles for legacy analog platforms. ECHA REACH amendments tighten rubber particulate specifications in European tenders. Frankfurt and Munich airport clusters concentrate procurement volume for ice-detection-integrated platforms.
France
DGAC procurement cycles explicitly require ISO-compliant equipment for runway friction reporting under ICAO Annex 14 alignment. ANSM and CNIL frameworks influence data transmission specifications for cloud-connected units. Paris Charles de Gaulle and Lyon-Saint Exupéry anchor the primary demand concentration for portable verification systems.
Sweden
Nordic winter operations compliance programs expand continuous friction tester deployment for seasonal runway safety management. The Swedish Transport Agency references ISO 23678 specifications directly in technical tender documents. Stockholm Arlanda and Gothenburg Landvetter drive regional demand for meteorological sensor convergence platforms.
Canada
Transport Canada aligns with FAA friction threshold documentation requirements while piloting wireless data transmission architectures for decentralized operations. Health Canada and PMRA frameworks govern material validation protocols for brake-lining suppliers. Toronto Pearson and Vancouver International anchor cloud-connected portable unit trials for ground crew tablet integration.
Continuous Friction Tester Market Vendor Landscape
Top-tier vendors anchor the premium automated runway tier, while mid-scale specialists occupy the portable and vehicle-mounted segments. The market structure consolidates around calibration-network density and sensor-modularity roadmaps rather than pure manufacturing scale. Two strategic archetypes dominate: Nordic-origin ice-detection integrators and FAA-certified military airfield specialists. Competitive moves concentrate on dense service contract capture and field-upgradeable sensor architectures.
Among Scandinavian-origin platform developers, SARSYS-ASFT AB and Norsemeter AS exemplify the ice-detection integration archetype, while Dynatest International occupies a position anchored in Nordic airport calibration networks. Neubert Aero Corp represents the FAA-certified military specialist tier. These three entities collectively illustrate how geographic regulatory alignment and installed base density determine sustainable revenue capture in long-term fleet contracts.
| Leading Market Players |
|---|
| Dynatest International |
| SARSYS-ASFT AB |
| Neubert Aero Corp |
| GripTester |
| Findlay Irvine Ltd. |
| Norsemeter AS |
| Moventor Ltd. |
| Controls Group |
| Humboldt Mfg. Co. |
| Others |
Supply Flow & Price Mechanics
The performance gap between FAA-certified automated runway systems and basic portable verification units manifests in divergent pricing architectures and supplier consolidation patterns. Premium platforms command substantial upfront capital commitments plus recurring calibration service contracts, while portable units compete on acquisition cost and deployment flexibility across developing aviation markets.
Pricing Analysis
Capacity additions in Southeast Asia are reshaping price floors for entry-level portable testers as regional manufacturers expand assembly operations. The dominant pricing model combines hardware acquisition with mandatory service contracts for calibration and tire consumables. Price differentiation hinges on certification tier—ASTM E1551 versus ISO 23678 compliance—and after-sales network density. Pricing pressure intensifies in the portable segment as capital-constrained airport authorities in Latin America prioritize lowest acquisition cost over sensor precision. Aerospace companies and military airfield operators demonstrate lowest price sensitivity, accepting substantial premiums for documented traceability and FAA certification.
Supply Chain Analysis
Refurbishment flows for legacy sensor modules and recalibrated test tires create secondary supply channels that extend equipment lifecycle value. Manufacturing concentrates in Germany, Sweden, and the United States, with specialized tire compound production anchored in EU REACH-compliant facilities. Raw material dependencies include precision load cells, standardized rubber formulations, and wireless transmission chipsets. Single-source vulnerability concentrates in qualified test tire suppliers, where EPA and ECHA particulate emission restrictions constrain qualified vendor pools. Distribution runs through direct OEM sales for automated systems and regional equipment distributors for portable units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as regulatory precision mandates displace legacy analog platforms. The demand shift toward ice-detection-integrated friction measurement systems favors suppliers with meteorological sensor convergence capabilities.
For Market Incumbents: Hedge against sensor-modularity disruption by accelerating field-upgradeable architecture roadmaps while locking in dense calibration contract networks. The threat of portable-first entrants with cloud-connected platforms demands defensive investment in wireless data transmission integration. Priority levers include backward integration into standardized test tire production and captive control over European calibration infrastructure. For New Entrants and Emerging Players: Begin with unbundled service provision in mid-sized regional airports across France and the Netherlands, where procurement patterns now separate calibration contracts from initial equipment tenders. The most penetrable white-space sits in Southeast Asian secondary airfields prioritizing capital-light portable deployment. A calibration-network-first go-to-market angle bypasses incumbent hardware lock-in. For Investors and Strategic Acquirers: Consolidation pressure builds where calibration network density intersects with sensor-modularity patent portfolios, creating scarce platform assets with recurring revenue defensibility. Long-term viability favors vendors with installed base scale across Nordic winter operations compliance programs. The acquisition target archetype combines FAA certification with ice-detection integration capabilities. Practitioners should monitor ECHA REACH amendment timelines for test tire supply disruption signals.| Strategic Initiative | Industry Significance |
|---|---|
| Ice-Detection Sensor Integration | Swedish Transport Agency mandates accelerate premium platform adoption across Nordic airports. |
| Calibration Network Expansion | Dense service infrastructure in Germany defends incumbent positions against portable entrants. |
| FAA Certification Investment | US military airfield portfolios require documented compliance with Advisory Circular 150/5320-12C. |
| Wireless Data Architecture Development | Transport Canada pilots enable decentralized ground crew tablet integration for runway operations. |
| REACH-Compliant Tire Reformulation | ECHA substance restrictions force compound validation extensions for European tender participation. |
Methodological Framework
Coverage spans North America, Western Europe, and Southeast Asia, with primary inputs from each regional cluster. The analysis combines structured interviews with airport operations directors, national aviation authority procurement leads, and aftermarket service managers with secondary validation against FAA Advisory Circulars, ECHA regulatory filings, and ICAO Annex 14 documentation. Bottom-up equipment deployment tallies triangulate against top-down aviation infrastructure spending estimates.
Granularity-level modeling distinguishes portable, automated, and vehicle-mounted architectures across each end-use segment. The analytical framework projects coefficient measurement device demand across the analysis window by equipment type, test standard alignment, and regional regulatory compliance tier. CAGRs derive from replacement cycle compression rates and new airfield construction pipelines. Forecast inputs include winter operations safety program expansion timelines and REACH framework amendment implementation schedules.
Several conditions sit outside the modeled scope, including force majeure disruptions to aviation traffic recovery and unilateral regulatory standard harmonization between ASTM and ISO protocols. Forecasts reflect documented assumptions regarding sensor-modularity adoption curves and calibration network buildout rates. Practitioners should monitor ECHA substance restriction list updates and FAA circular revision schedules for early signals of equipment specification shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
In-Line Overlay and Critical Dimension Metrology for Sub-3nm Nodes Market
Test and Measurement
AI Accelerator Thermal Management and Hot Spot Mapping Test Platforms Market
Test and Measurement
Battery Testing Market
Test and Measurement
North America Electrical Testing Services Market
Test and Measurement
Glow Wire Test Apparatus Market
Test and Measurement
Electrical Test Equipment Market
Test and Measurement
Structure Tester Market
Test and Measurement
Flying Probe Testing for PCB Assembly Market
Test and Measurement
Humidity Testers Market
Test and Measurement
Noise Vibration Harshness (NVH) Testing Market
Test and Measurement
Ethernet Test Equipment Market
Test and Measurement
Gloss Meters Market
Test and Measurement
Battery Capacity Testers Market
Test and Measurement
Voltage Tester Market
Test and Measurement
Hardness Testing Machine Market
Test and Measurement
AI Inference Hardware Performance Benchmarking Test Systems Market