
 LAMEA Semiconductor Metrology and Inspection Market | 2026-2036
LAMEA Semiconductor Metrology and Inspection Market Size, Share, and Industry Trends Forecast 2026-2036
LAMEA Semiconductor Metrology and Inspection Market Insights
EU Green Deal compliance requirements for semiconductor supply chain traceability is shifting procurement priorities across LAMEA-based foundries. KLA Corporation leverages its installed base of patterned wafer inspection systems to sustain service revenue across Israeli fabrication plants. Applied Materials, Inc. anchors its regional position through localized technical support centers in São Paulo. ASML Holding N.V. differentiates via extreme ultraviolet lithography metrology partnerships with advanced node developers.
Semiconductor metrology and inspection encompasses precision measurement systems that characterize wafer topography, detect atomic-scale defects, and verify critical dimensions at sub-nanometer resolution using electron beam, optical interferometry, and X-ray modalities. These systems enable yield management in semiconductor fabrication by identifying process deviations before they propagate through multi-layer device structures. Optical Metrology occupies the largest equipment spend share due to its throughput advantage in high-volume wafer fabrication. Scanning Electron Microscope adoption is accelerating among IDM Manufacturers pursuing sub-7nm process nodes where optical resolution limits constrain defect classification. Atomic Force Microscope deployment concentrates in Research Institutions developing novel materials for next-generation transistor architectures.
Israeli Ministry of Environmental Protection regulations on hazardous substance handling in cleanroom operations shape equipment qualification requirements for imported inspection tools. Brazil's national telecommunications regulator ANATEL mandates electromagnetic compatibility certification for semiconductor test equipment deployed in domestic fabs. South African Bureau of Standards (SBS) alignment with ISO 14644 cleanroom classification standards influences facility upgrade timelines. Stakeholders must monitor evolving national content requirements across LAMEA jurisdictions that could restrict equipment sourcing flexibility or mandate local technical partnership structures.
Market Dynamics
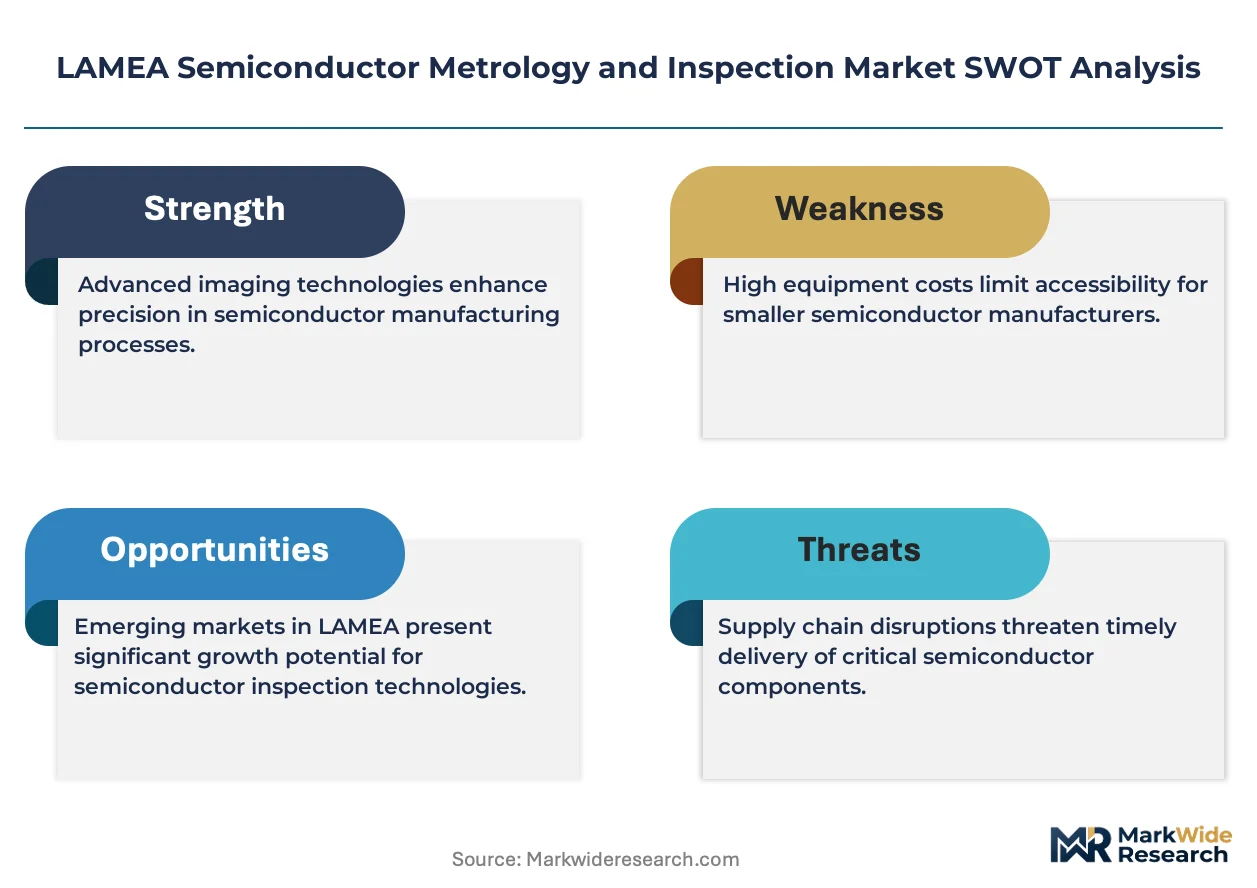
Sub-7nm node proliferation across Israeli foundries is compressing defect detection tolerances below optical limits, forcing wholesale metrology platform replacement cycles and reshaping equipment procurement specifications across LAMEA fabrication facilities.
Growth Catalysts
- EU Green Deal traceability mandates:Supply chain disclosure requirements for semiconductor inputs are compelling LAMEA foundries to deploy inspection systems with full wafer-level provenance tracking capabilities.
- Automotive chip manufacturing expansion:Brazil and South Africa-based vehicle electronics producers are scaling wafer starts for power management ICs, driving equipment orders for high-throughput optical metrology.
- Optical interferometry resolution advances:Next-generation multi-wavelength systems now achieve sub-nanometer critical dimension uniformity measurement, enabling yield recovery in advanced memory production.
Market Restraints
- Extreme ultraviolet lithography mask blank scarcity:Concentrated supply from single-source Japanese substrate producers creates inspection tool qualification bottlenecks for advanced node developers.
- Electron beam inspection throughput ceilings:Serial image acquisition fundamentally limits wafer-per-hour rates below optical alternatives, constraining deployment economics at mature nodes.
- Import licensing friction for X-ray metrology:Israeli and South African dual-use technology controls extend equipment procurement timelines by 8-14 months for certain inspection modalities.
Strategic Opportunities
- Brazilian domestic fab buildout:National semiconductor industrial policy targets are attracting foundry investment to São Paulo state, creating greenfield equipment specification windows.
- Atomic force microscope materials research convergence:2D material characterization for next-generation transistor channels is opening instrumentation demand from university and national laboratory facilities.
- Localized technical support center requirements:Equipment vendors establishing Brazilian and Israeli service hubs gain preferential access to national procurement frameworks mandating domestic technical partnership structures.
Industry Challenges
- Cleanroom-qualified metrology engineer scarcity:Specialized technician training programs in LAMEA markets lag equipment deployment rates, extending commissioning timelines.
- Multi-vendor platform integration complexity:Heterogeneous inspection data formats from electron beam, optical, and X-ray systems complicate unified yield management software deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAMEA Semiconductor Metrology and Inspection Market |
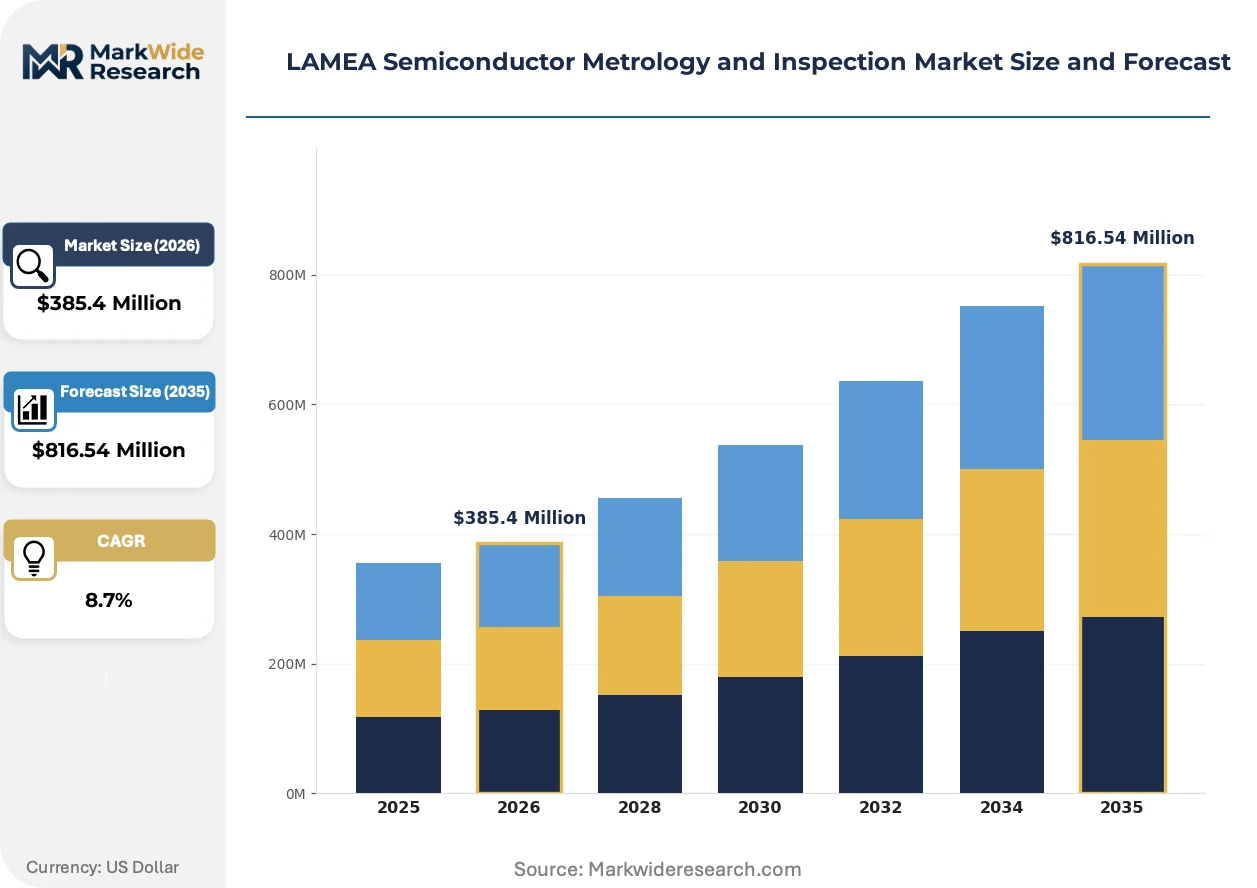
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Metrology, X-Ray Inspection, Scanning Electron Microscope, Atomic Force Microscope Technology: Patterned Wafer Inspection, 3D Metrology, Defect Detection, Critical Dimension Measurement End User: Foundries, IDM Manufacturers, Fabless Companies, Research Institutions Application: Wafer Fabrication, Device Characterization, Process Development, Quality Assurance |
| Companies Covered | KLA Corporation, Applied Materials, Inc., ASML Holding N.V., Onto Innovation, Inc., Thermo Fisher Scientific Inc., Hitachi High-Tech Corporation, Nova Ltd., Camtek Ltd., Lasertec Corporation, Others |
| Regions Covered | LAMEA: Brazil, Mexico, Argentina, Saudi Arabia, UAE, South Africa, Nigeria, Egypt, Rest of LAMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAMEA Semiconductor Metrology and Inspection Market Trends and Innovations
Computational metrology and machine learning-enabled defect classification are compressing feedback loops between measurement and process adjustment, reducing the latency that previously allowed defect propagation through multi-layer device stacks.
Hybrid optical-electron beam inspection architectures are rewriting yield management economics at the 5nm node. Memory manufacturers in Israeli fabrication plants are deploying these combined systems to maintain throughput while capturing resolution-limited defect populations. The technology is compressing the capital intensity gap between optical-only and full electron beam inspection deployments.
ANATEL electromagnetic compatibility certification requirements for semiconductor test equipment are mandating redesigned shielding specifications for metrology tools deployed in Brazilian domestic fabs. Industrial consequence includes extended type-approval timelines and modified power supply architectures. Memory and logic producers are responding by front-loading certification documentation in procurement negotiations.
Consolidated vendor relationships are displacing fragmented multi-source equipment strategies among LAMEA foundries. IDM manufacturers now prioritize single-vendor platform ecosystems that unify data formats and service contracts. Israeli advanced node developers exhibit the most concentrated procurement patterns, driven by integration complexity with existing patterned wafer inspection infrastructure.
LAMEA Semiconductor Metrology and Inspection Market Segmentation
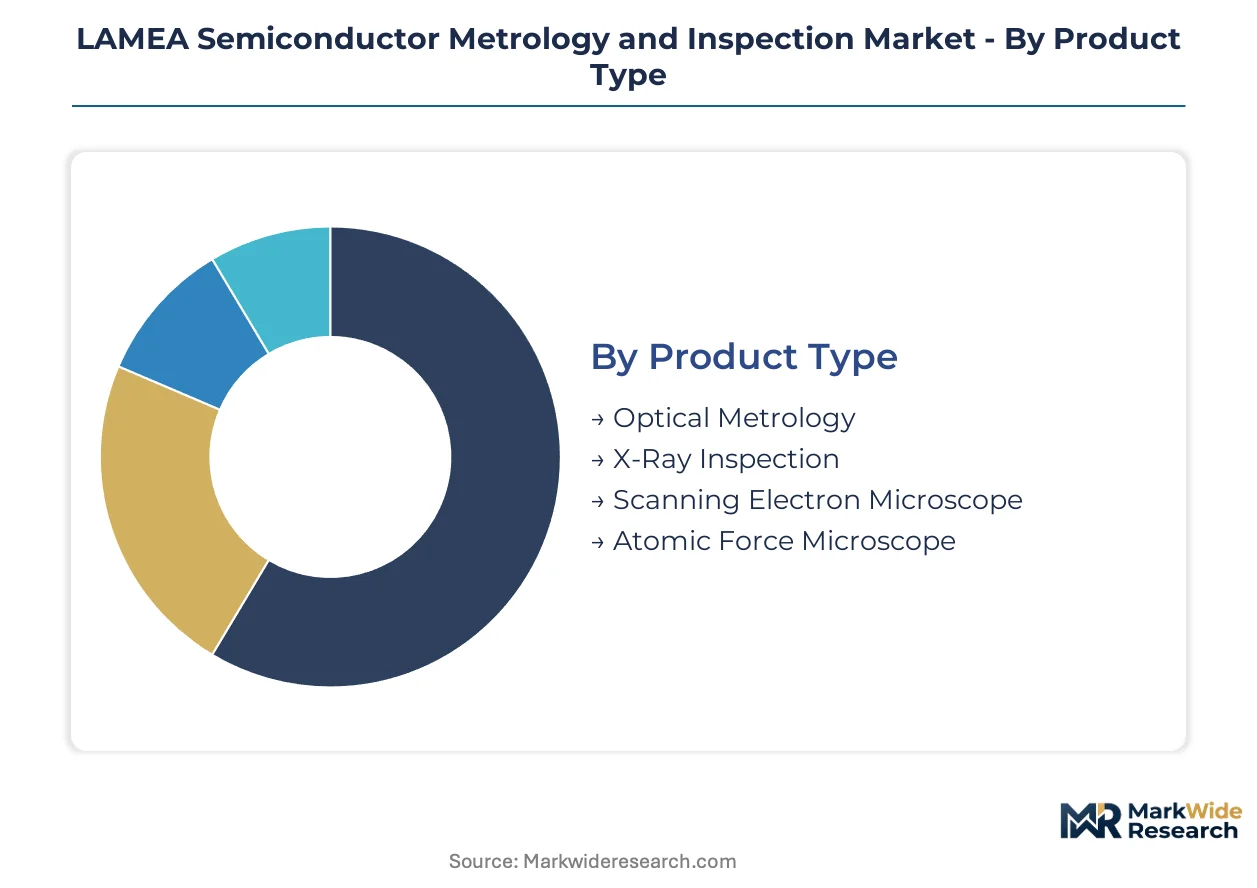
Segmentation in semiconductor metrology reveals how equipment specifications diverge across fabrication maturity levels. Procurement patterns in LAMEA fabrication facilities track directly against process node targets and local regulatory qualification requirements.
Product Type:
Customization intensity spans from standardized optical platforms to highly configured electron beam architectures tailored to specific cleanroom protocols.
- Optical Metrology:Multi-wavelength interferometry systems achieve sub-nanometer critical dimension uniformity at wafer-throughput rates unmatched by electron-based alternatives. Israeli foundries deploying these systems for high-volume memory production drive regional equipment spend concentration.
- Scanning Electron Microscope:Serial image acquisition enables atomic-scale defect classification below optical resolution limits, though wafer-per-hour rates constrain economics. IDM Manufacturers in Israel pursuing sub-7nm nodes represent the primary demand concentration for these platforms.
- X-Ray Inspection:Non-destructive subsurface characterization for advanced packaging interconnects.
- Atomic Force Microscope:University and national laboratory facilities in Israel and South Africa deploy these for 2D material characterization.
Leading the category by volume: Optical Metrology. Growing fastest: Scanning Electron Microscope.
Technology:
Application maturity separates proven patterned wafer systems from emerging 3D architectures still qualifying for production deployment.
- Patterned Wafer Inspection:Established optical and electron beam architectures for detecting defects on processed wafer surfaces. Foundries across Israel and Brazil prioritize these systems for yield management at mature nodes.
- 3D Metrology:Vertical device architectures in advanced memory stacks demand z-axis characterization capabilities. Israeli fabrication plants scaling 3D NAND production anchor regional adoption curves.
- Defect Detection:Process excursion identification before propagation through multi-layer structures.
- Critical Dimension Measurement:Line-width verification for lithography process control.
Patterned Wafer Inspection commands the largest installed base. 3D Metrology is expanding most quickly as memory manufacturers scale vertical architectures.
End User:
Capital intensity and technical specification authority vary sharply between integrated manufacturers and research-oriented procurement.
- Foundries:High-volume wafer processing demands inspection platforms optimized for throughput economics. Tower Semiconductor and other Israeli foundries drive regional procurement specifications for multi-node flexibility.
- IDM Manufacturers:Vertically integrated design-to-fabrication operations require metrology systems spanning R&D through production. Intel's Israeli operations anchor advanced node equipment qualification timelines.
- Fabless Companies:Reliance on external fabrication limits direct metrology ownership to design-for-manufacturing partnerships.
- Research Institutions:Weizmann Institute and similar facilities in Israel and South Africa prioritize resolution over throughput for materials science applications.
Foundries lead equipment volume. IDM Manufacturers are gaining share fastest as domestic fab investments accelerate.
Application:
Process stage determines metrology integration depth, from inline wafer monitoring to offline characterization protocols.
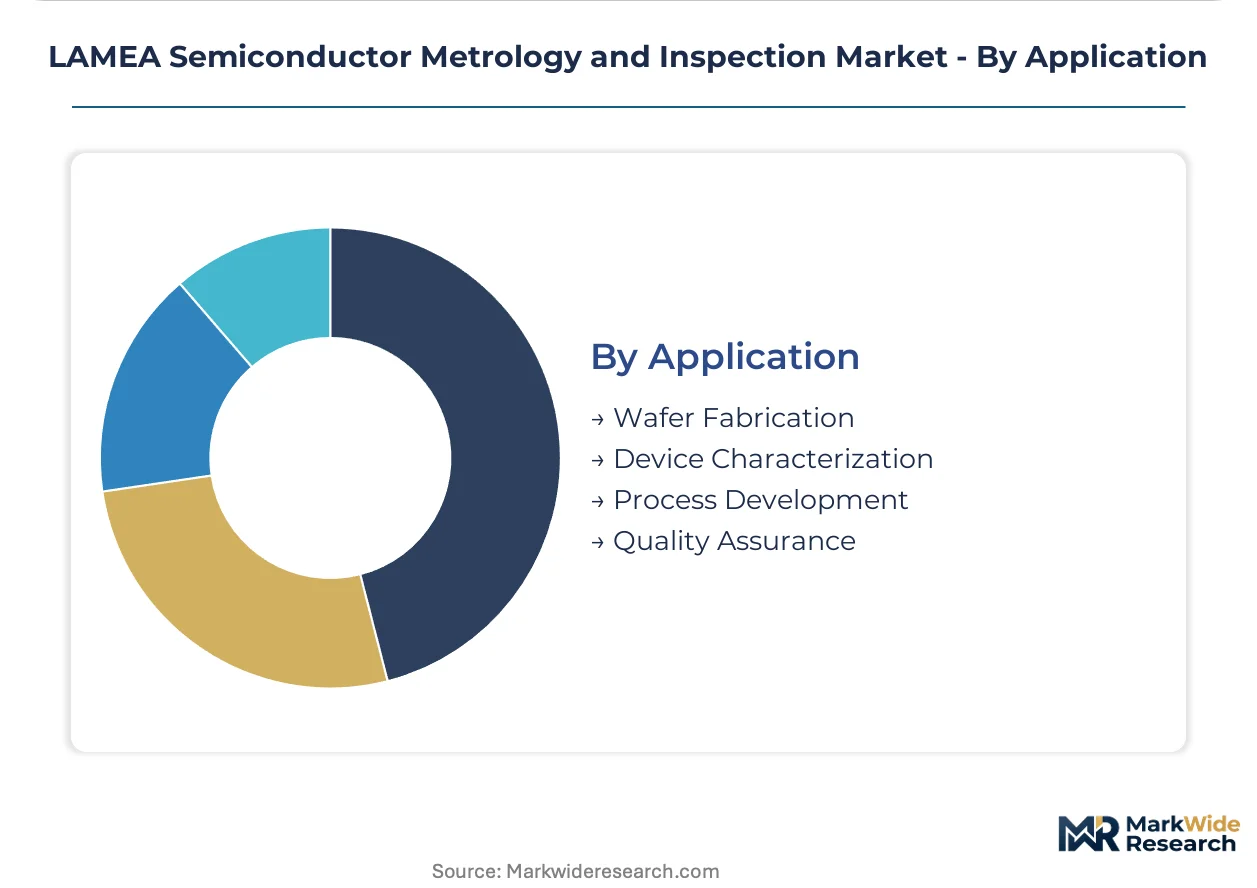
- Wafer Fabrication:Inline inspection at lithography, etch, and deposition steps enables real-time process adjustment. Brazilian and Israeli fabs expanding production capacity prioritize these systems for yield protection.
- Process Development:Engineering-focused metrology for new node qualification demands higher resolution than production tools. Israeli advanced node developers concentrate regional demand for electron beam and X-ray modalities.
- Device Characterization:Electrical and structural verification of completed device structures.
- Quality Assurance:Final outgoing inspection and reliability screening protocols.
Wafer Fabrication dominates equipment deployment. Process Development shows the steepest expansion trajectory as sub-7nm qualification cycles intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Israel's Yokneam industrial corridor anchors metrology equipment demand through Tower Semiconductor and Intel fabrication complexes. Brazilian São Paulo state and South African Gauteng province concentrate automotive chip packaging investments. National industrial policies across these jurisdictions are tightening semiconductor quality standards and mandating localized technical support infrastructure.
Israel
Advanced node foundries in Kiryat Gat and Yokneam drive electron beam inspection procurement for sub-7nm process qualification. The Israeli Ministry of Environmental Protection regulates hazardous substance handling in cleanroom operations, shaping equipment import specifications. Intel's Fab 28 and Tower Semiconductor facilities concentrate regional demand for patterned wafer inspection systems.
Brazil
São Paulo state foundry investments target power management IC production for domestic automotive electronics. ANATEL mandates electromagnetic compatibility certification for semiconductor test equipment, extending type-approval timelines for imported metrology tools. The Campinas technology corridor hosts emerging fab construction requiring greenfield optical metrology specification.
South Africa
Gauteng province automotive chip packaging facilities scale wafer starts for vehicle electronics supply chains. The South African Bureau of Standards alignment with ISO 14644 cleanroom classification standards influences facility upgrade timelines for inspection tool deployment. Tshwane-Pretoria industrial zones concentrate technical training programs addressing cleanroom-qualified engineer scarcity.
United Arab Emirates
Dubai and Abu Dhabi logistics hubs facilitate metrology equipment transshipment to Israeli and African markets. The country's national industrial regulator enforces import standards for precision instrumentation entering free zone facilities. Jebel Ali port concentration supports regional service center establishment for equipment vendors seeking Gulf market access.
Turkey
Istanbul and Ankara electronics manufacturing clusters generate secondary demand for mature node inspection equipment. The country's national standards body implements EU-aligned technical regulations for semiconductor production machinery. Gebze industrial zone packaging facilities require mid-tier optical metrology for quality assurance protocols.
LAMEA Semiconductor Metrology and Inspection Market Competitive Landscape
The competitive structure tilts toward integrated platform providers with established service infrastructure. Equipment vendors concentrate procurement influence through localized technical support centers and unified data format ecosystems. Three archetypes dominate: lithography-integrated metrology specialists, multi-modal inspection platform providers, and regional service-anchored distributors. Competitive positioning depends on qualification speed for national regulatory frameworks and cleanroom technician training program partnerships.
Among US-based platform providers, KLA Corporation and Applied Materials exemplify the integrated inspection ecosystem archetype, anchoring regional presence through Israeli and Brazilian service infrastructure. ASML Holding N.V. represents the lithography-metrology convergence tier, with Dutch incorporation and extreme ultraviolet equipment partnerships. Onto Innovation and Nova Ltd. occupy specialized optical critical dimension measurement positions, with the latter's Israeli incorporation reflecting regional R&D proximity advantages.
| Leading Market Players |
|---|
| KLA Corporation |
| Applied Materials, Inc. |
| ASML Holding N.V. |
| Onto Innovation, Inc. |
| Thermo Fisher Scientific Inc. |
| Hitachi High-Tech Corporation |
| Nova Ltd. |
| Camtek Ltd. |
| Lasertec Corporation |
| Others |
Pricing and Supply Chain Analysis
Resolution-tier divergence between sub-7nm electron beam platforms and mature-node optical systems manifests in both capital expenditure stratification and supply chain complexity. Premium-tier procurement concentrates in Israeli advanced node foundries where yield economics justify throughput-sacrificing serial inspection, while Brazilian automotive chip producers anchor standard-tier demand for high-wafer-per-hour optical alternatives.
Pricing Analysis
Yield-recovery value anchors pricing for metrology platforms serving sub-7nm process nodes, with Israeli IDM manufacturers accepting capital intensity premiums tied to defect prevention economics. Price differentiation rests on resolution certification tiers and cleanroom qualification protocols mandated by national regulators. Cost compression in optical metrology intensifies as multi-wavelength interferometry commoditizes at mature nodes. Fabless companies exhibit highest price sensitivity due to indirect procurement through foundry partnerships, while IDM manufacturers prioritize performance over unit cost.
Supply Chain Analysis
Freight logistics for precision instrumentation from Netherlands, Japan, and USA absorbs disproportionate cost share due to vibration-controlled transport requirements and customs brokerage complexity for dual-use technology classifications. Core component dependencies span extreme ultraviolet light sources, electron beam columns, and interferometric sensors. Single-source vulnerability concentrates in Japanese substrate producers for EUV mask blanks. Distribution runs through Dubai and São Paulo regional hubs serving Israeli and Brazilian fab clusters respectively.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment procurement queues extend 8-14 months for X-ray and electron beam modalities under Israeli and South African dual-use controls, propping pricing power for qualified vendors with established import pathways.
For Market Incumbents: Extend service revenue capture through localized technical support center buildout in São Paulo and Yokneam industrial corridors. Anchor platform stickiness via unified data format ecosystems that complicate multi-vendor substitution. Defend against emerging optical-electron beam hybrid architectures by accelerating computational metrology software roadmaps. Prioritize cleanroom technician training program partnerships with Tshwane-Pretoria technical institutes to compress commissioning timelines. For New Entrants and Emerging Players: Capture white-space in Brazilian greenfield fab specifications where national content requirements favor vendors with domestic technical partnership structures. Penetrate atomic force microscope demand from Weizmann Institute and South African national laboratory facilities pursuing 2D material characterization. Pursue ANATEL electromagnetic compatibility pre-certification to front-load procurement negotiations with São Paulo state foundry investors. For Investors and Strategic Acquirers: Re-rating potential sits with specialized optical critical dimension measurement providers given hybrid inspection architecture convergence at 5nm nodes. Long-term viability favors vendors with lithography-integrated metrology positioning and established Israeli R&D proximity. Monitor EU Green Deal traceability mandate implementation velocity as inflection indicator for wafer-level provenance tracking capability premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Localized Technical Support Center Establishment | São Paulo and Yokneam hubs satisfy Brazilian national content requirements and Israeli cleanroom qualification protocols. |
| Computational Metrology Platform Integration | Machine learning-enabled defect classification compresses feedback loops for Tower Semiconductor yield management. |
| Hybrid Optical-Electron Beam Architecture Deployment | Combined systems bridge throughput-resolution economics for Intel Fab 28 advanced memory production. |
| ANATEL Pre-Certification Investment | Front-loaded electromagnetic compatibility documentation accelerates Brazilian domestic fab equipment procurement. |
| Cleanroom Technician Training Partnership | Tshwane-Pretoria institute collaborations address Gauteng province qualified engineer scarcity. |
Research Methodology
Independent corroboration across semiconductor fabrication executives, metrology equipment procurement leads, and cleanroom operations directors underwrites the qualitative findings. Primary fieldwork encompassed foundry engineering managers at Israeli advanced node facilities, Brazilian automotive chip packaging specialists, and South African ISO 14644 compliance officers. Secondary validation drew from SEMI equipment market data, Israeli Ministry of Environmental Protection regulatory filings, ANATEL certification databases, and SEC 10-K disclosures from listed equipment vendors. Bottom-up equipment shipment tracking and top-down fabrication capacity modeling were reconciled through iterative triangulation.
Comparable-period anchoring to historical metrology equipment procurement cycles across Israeli, Brazilian, and South African fabrication facilities structured the forecast window. The analytical framework modeled segmentation across product type, technology maturity, end-user capital intensity, and application process stage. CAGRs were derived from equipment spend trajectories tied to foundry buildout announcements and national industrial policy targets. Forecast inputs incorporated EU Green Deal traceability mandate compliance timelines and sub-7nm node proliferation curves at Intel and Tower Semiconductor facilities.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to extreme ultraviolet lithography mask blank supply concentration and dual-use technology control enforcement shifts. Forecasts reflect assumptions regarding cleanroom-qualified engineer pipeline development and national content requirement evolution across LAMEA jurisdictions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
RFID Tester Market
Test and Measurement
Electromagnetic NDT Market
Test and Measurement
Moisture Analyzer Market
Test and Measurement
Fingertip Pulse Oximeter Electronic Testers Market
Test and Measurement
Hearing Aid and True Wireless Earbud Acoustic Performance Test Systems Market
Test and Measurement
Stress Test Chamber Market
Test and Measurement
Europe Signal Generator Market
Test and Measurement
Calorimeters Market
Test and Measurement
Global Platform Electronic Laboratory Balance Market
Test and Measurement
Additively Manufactured Lattice Structure Mechanical Test Systems Market
Test and Measurement
Bend Testing Machine Market
Test and Measurement
Failure Analysis Market
Test and Measurement
Global Micrometer Market
Test and Measurement
Global 5G Test Equipment Market
Test and Measurement
Solid-State Battery Fast-Charge Degradation Test Systems Market
Test and Measurement
5G Testing Equipment Market