
 Retardant Solvent Market | 2026-2036
Retardant Solvent Market Size, Share, and Industry Trends Forecast 2026-2036
Retardant Solvent Market Analytics
The retardant solvent market is pivoting on a widening gap between aerospace-grade halogenated formulations and commodity aliphatic alternatives used in construction coatings. BASF SE leverages its integrated aromatic supply chain to dominate premium specification tiers. Dow Inc. anchors North American production through backward integration into chlorinated intermediate feedstocks. Lanxess AG competes on phosphorus-based technology leadership for electronics-grade purity requirements.
Retardant solvents are formulated chemical carriers, typically halogenated or phosphorus-based compounds with flash points exceeding sixty degrees Celsius, engineered to suppress combustion propagation in coating and adhesive systems. Their primary industrial purpose centers on enabling fire-resistant material performance without compromising substrate adhesion or film formation in applied finishes. Aromatic solvents occupy the mature volume base in paints and coatings, while ketone formulations represent the fastest-expanding margin pool driven by electronics end-user specifications for low-residue precision cleaning. The aerospace segment commands premium pricing through certification-intensive qualification protocols that lock in multi-year supplier relationships.
EPA regulations under the Toxic Substances Control Act restrict perchloroethylene content in consumer-facing coatings, while REACH authorization requirements in the European Union limit brominated retardant concentrations in architectural applications. China's MEE enforces volatile organic compound emission caps that favor water-dispersible retardant solvent systems in Yangtze River Delta manufacturing zones. Stakeholders must monitor evolving flammability test standards from FAA and EASA as next-generation electric vehicle battery enclosures create novel fire-resistance specifications across automotive supply chains.
Market Dynamics
REACH authorization requirements in the European Union are tightening brominated retardant concentrations, forcing reformulation investments across coating supply chains while China's MEE emission caps accelerate water-dispersible system adoption in manufacturing clusters.
Growth Catalysts
- Electric vehicle battery enclosures:Automotive OEMs in Germany and France are mandating fire-resistant coating specifications for lithium-ion cell housings, creating specification pull through tier-one suppliers.
- FAA flammability protocols:Aerospace interior certification standards are expanding testing scope to include adhesive-bonded assemblies, locking in multi-year supplier qualification cycles.
- Phosphorus-based purity grades:Electronics-grade cleaning solvents with sub-ppm residue specifications are capturing margin expansion in semiconductor packaging operations across China's eastern corridor.
Market Restraints
- Chlorinated intermediate volatility:Feedstock cost swings in perchloroethylene and trichloroethylene are compressing formulation margins for commodity coating producers.
- REACH authorization bottlenecks:ECHA's phased restriction of hexabromocyclododecane is forcing architectural coating reformulations with 18-24 month compliance timelines.
- Waterborne substitution pressure:Low-VOC aqueous fire-retardant systems are displacing solvent-based formulations in interior architectural applications.
Strategic Opportunities
- India's PLI scheme for electronics:Domestic semiconductor packaging investments in Gujarat and Tamil Nadu are creating demand for electronics-grade phosphorus-based cleaning formulations.
- Aviation biofuel compatibility:Next-generation sustainable aviation fuel handling systems require revised fire-resistance specifications for sealant and coating interfaces.
- Marine LNG containment:Cryogenic insulation systems for liquefied natural gas carriers in South Korean shipyards are specifying halogenated retardant barriers with -160°C performance ratings.
Industry Challenges
- Cross-functional formulation chemistry:Retardant solvent developers must bridge fire-resistance performance with substrate adhesion science and volatile organic compound compliance simultaneously.
- Multi-jurisdiction certification stacking:Aerospace suppliers face overlapping FAA, EASA, and CAAC qualification protocols with non-harmonized test methods and documentation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retardant Solvent Market |
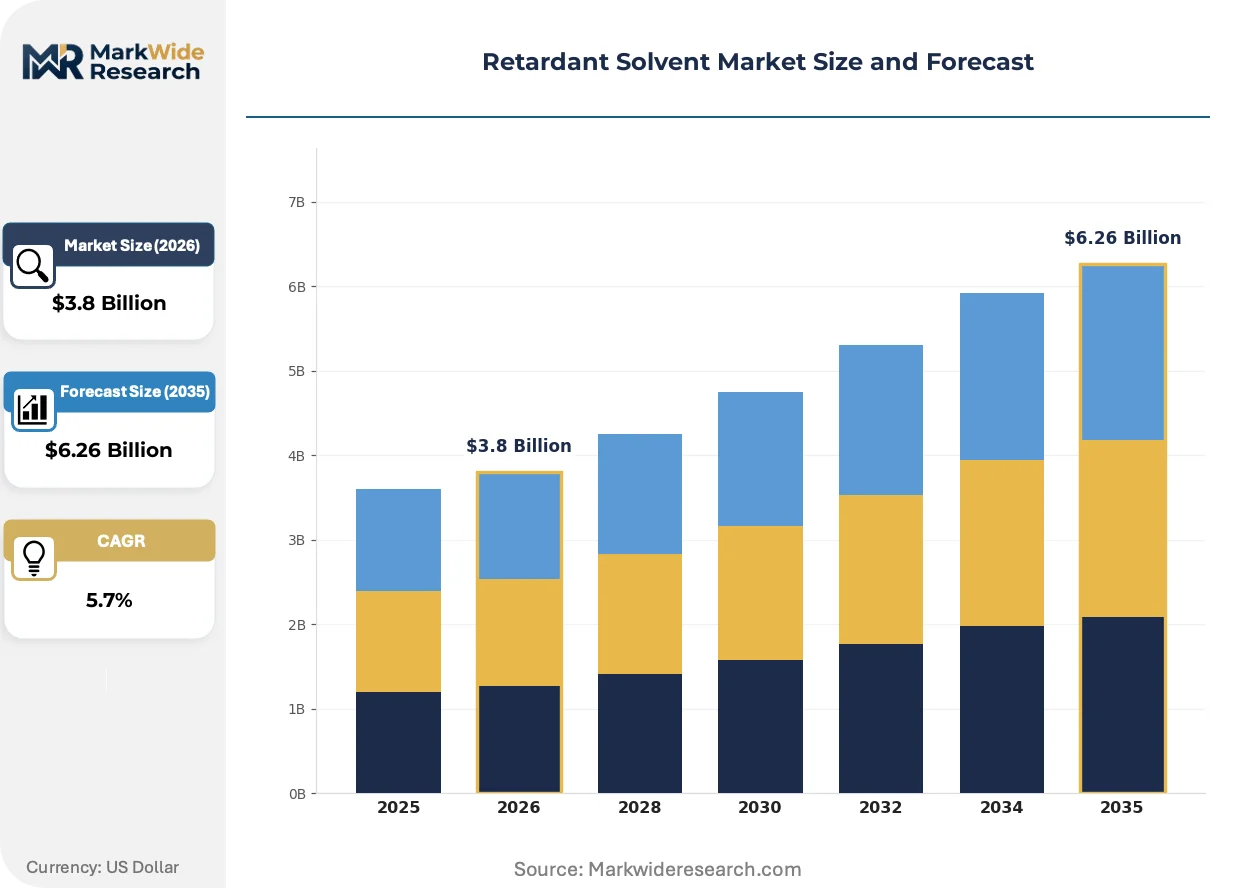
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aromatic Solvents, Aliphatic Solvents, Alcohols, Ketones Application: Paints & Coatings, Adhesives, Inks, Chemicals End User: Construction, Automotive, Aerospace, Electronics Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | BASF SE, Dow Inc., AkzoNobel N.V., Solvay S.A., Clariant AG, Lanxess AG, DuPont, Arkema S.A., Albemarle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retardant Solvent Market Evolving Landscape
Reformulation chemistry is pivoting toward reactive phosphorus oligomers that bond covalently into coating matrices, eliminating migration risks while maintaining process compatibility with existing application equipment.
Reactive phosphorus oligomer technology is integrating into high-solids polyurethane coating systems for transportation applications. Tier-one automotive suppliers in Germany are qualifying these formulations for electric vehicle battery tray assemblies. The technology is integrating fire-resistance directly into polymer backbones, reducing additive loading requirements and enabling thinner film builds without sacrificing protection ratings.
EPA restrictions under the Toxic Substances Control Act are narrowing perchloroethylene availability in consumer-facing coatings and dry-cleaning applications. Industrial formulators are accelerating migration to alternative chlorinated and fluorinated carriers with modified toxicological profiles. Metal finishing operations in the US Midwest are bearing the highest compliance costs as they retrofit vapor degreasing systems for reduced-emission solvent blends.
Specification-driven procurement is consolidating buyer power among aerospace OEMs and automotive battery system integrators. Long-term supply agreements with embedded volume commitments are displacing spot-market purchasing in premium formulation tiers. This concentration is most visible in France and Germany, where Airbus and automotive electrification programs are locking in three-to-five-year retardant solvent supply contracts with qualification-locked suppliers.
Retardant Solvent Market Segmentation
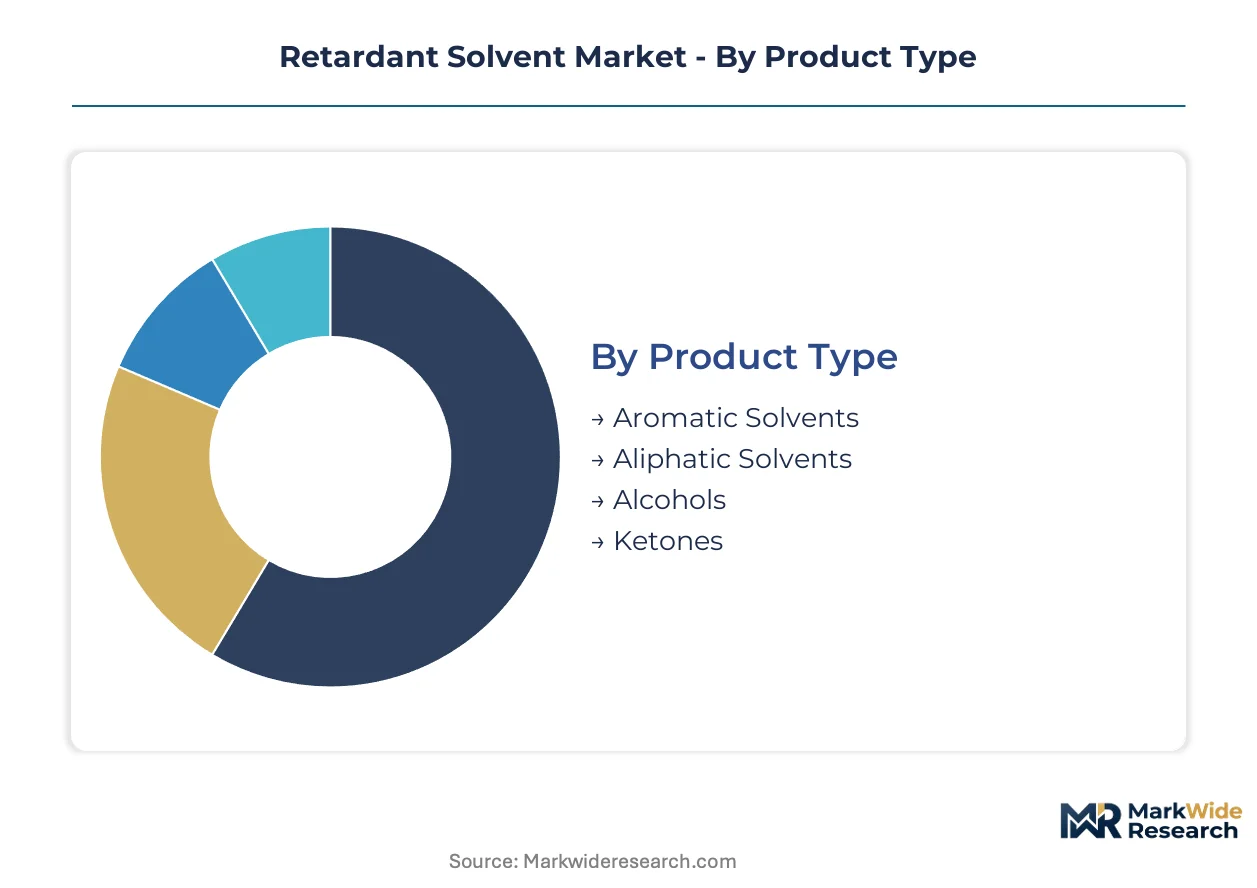
Retardant solvent procurement splits across technical specification tiers, application performance requirements, and channel economics. Understanding these divisions reveals where margin pools concentrate and which qualification barriers protect incumbent positions.
Product Type:
Halogenated versus phosphorus-based chemistry defines the specification axis, with flash point thresholds and residue limits determining end-use eligibility.
- Aromatic Solvents:Toluene and xylene-based formulations dominate architectural coatings through established supply chains and cost-efficient dilution properties. Mature volume in Germany and France serves automotive OEM refinishing operations, though REACH VOC restrictions are tightening permissible emission profiles.
- Ketones:Methyl ethyl ketone and acetone derivatives deliver sub-ppm residue specifications essential for semiconductor packaging cleaning. Electronics-grade demand in China's eastern corridor is climbing fastest as domestic chip assembly capacity expands.
- Aliphatic Solvents:Mineral spirits and hexane variants serve commodity construction sealants with lower thermal stability requirements.
- Alcohols:Isopropanol and butanol formulations provide intermediate flash points for adhesive thinning in industrial assembly.
Mature deployment sits with aromatic solvents. Newer deployment is concentrated in ketones.
Application:
Film formation demands and substrate compatibility requirements segment the market by performance tier and certification intensity.
- Paints & Coatings:Architectural, automotive, and aerospace finishes require tailored viscosity control and fire-resistance integration. China's Yangtze River Delta manufacturing clusters are absorbing water-dispersible formulations as MEE emission caps tighten.
- Adhesives:Bond-line fire protection in aerospace interior assemblies commands premium pricing through FAA and EASA qualification protocols. German tier-one suppliers are locking in multi-year supply agreements for electric vehicle battery tray bonding systems.
- Inks:Flexographic and gravure printing applications prioritize low-odor, fast-evaporating carriers for packaging substrates.
- Chemicals:Process solvents and extraction media serve pharmaceutical and agrochemical intermediate synthesis with varying purity grades.
Volume concentration rests in paints and coatings. Value expansion is sharpest in adhesives.
End User:
Specification stringency and procurement scale separate price-insensitive certification-driven buyers from cost-optimized commodity purchasers.
- Aerospace:Interior cabin materials and fuel system sealants demand halogenated formulations meeting FAA flammability protocols. French and German OEMs enforce three-to-five-year supplier lock-in through intensive qualification cycles.
- Electronics:Semiconductor packaging and printed circuit board cleaning require phosphorus-based purity grades with metallic impurity controls below part-per-billion thresholds. India's PLI scheme for Gujarat and Tamil Nadu semiconductor investments is generating new demand pull.
- Automotive:Electric vehicle battery enclosures are mandating fire-resistant coating specifications across German and French supply chains.
- Construction:Architectural coatings face waterborne substitution pressure as interior VOC regulations tighten.
Procurement sophistication peaks in aerospace. Fastest volume uptake is occurring in electronics.
Distribution Channel:
Relationship intensity and technical service requirements determine channel selection across specification tiers.
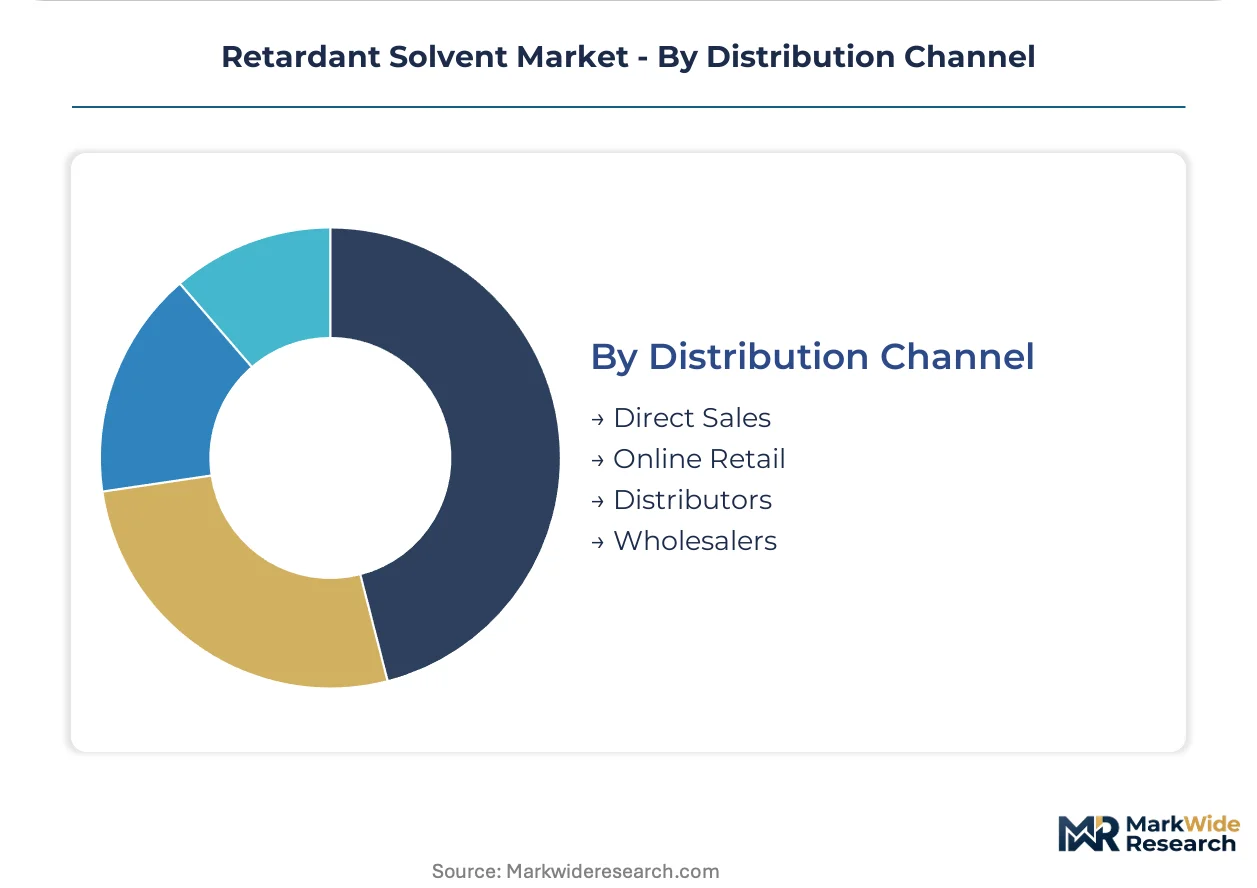
- Direct Sales:Aerospace and automotive OEMs negotiate long-term supply agreements with embedded volume commitments and joint formulation development. Specification-driven procurement in France and Germany consolidates buyer power among qualified suppliers.
- Distributors:Regional chemical distributors serve mid-tier coating producers with inventory management and technical support for reformulation transitions.
- Wholesalers:Bulk volume handlers supply commodity construction coating manufacturers with price-sensitive aliphatic solvent blends.
- Online Retail:E-commerce platforms capture small-laboratory and maintenance-repair-operations demand with limited technical service content.
Relationship depth concentrates in direct sales. Channel expansion is strongest in distributor networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta manufacturing corridor anchors retardant solvent consumption, absorbing water-dispersible formulations as coating producers serve automotive and electronics assembly lines. Germany's aerospace supply chain and France's automotive electrification programs drive premium specification demand. REACH restrictions and China's MEE emission caps are reshaping formulation standards across major industrial zones.
China
Electronics-grade cleaning solvents with sub-ppm residue specifications dominate demand in Shanghai and Suzhou semiconductor packaging operations. MEE volatile organic compound emission caps favor water-dispersible retardant solvent systems across Yangtze River Delta manufacturing zones. Domestic coating producers in Jiangsu and Zhejiang provinces are retrofitting solvent-based lines to meet tightening environmental thresholds.
Germany
Automotive OEMs in Stuttgart and Munich are mandating fire-resistant coating specifications for electric vehicle battery enclosures. ECHA's phased REACH authorization requirements restrict hexabromocyclododecane concentrations, forcing 18-24 month reformulation timelines. BASF SE leverages its integrated aromatic supply chain from Ludwigshafen to dominate premium aerospace and automotive specification tiers.
France
Airbus procurement in Toulouse locks in multi-year supplier qualification cycles for halogenated formulations meeting EASA flammability protocols. The country's national chemical regulator enforces REACH VOC restrictions that tighten permissible emission profiles in architectural coatings. Lyon-based adhesive producers serve tier-one automotive battery system integrators with specification-locked supply agreements.
United States
EPA restrictions under the Toxic Substances Control Act narrow perchloroethylene availability in consumer-facing coatings and dry-cleaning applications. Metal finishing operations in Michigan and Ohio bear the highest compliance costs as they retrofit vapor degreasing systems. Dow Inc. anchors North American production through backward integration into chlorinated intermediate feedstocks from Gulf Coast petrochemical complexes.
India
Domestic semiconductor packaging investments in Gujarat and Tamil Nadu are creating demand for electronics-grade phosphorus-based cleaning formulations. The PLI scheme for electronics manufacturing subsidizes capital equipment for Gujarat's Dholera and Tamil Nadu's Sriperumbudur clusters. Lanxess AG competes on technology leadership for purity requirements in these emerging fabrication facilities.
Retardant Solvent Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a tiered market structure. Integrated chemical majors with captive feedstock positions dominate volume tiers, while specialty formulators capture margin in certification-intensive aerospace and electronics segments. Three archetypes define competitive positioning: backward-integrated petrochemical giants, phosphorus-based technology specialists, and regional distributors serving commodity construction coatings. Dominant competitive moves include long-term supply agreements with embedded volume commitments and joint formulation development partnerships with automotive and aerospace OEMs.
Within the integrated petrochemical tier, BASF SE and Dow Inc. exemplify scale-driven positioning through aromatic and chlorinated intermediate supply chain control. Lanxess AG occupies the specialty technology vector, representing phosphorus-based purity leadership for electronics-grade applications. Among European-based formulators, Solvay S.A. and Arkema S.A. sit within the halogenated chemistry archetype serving aerospace certification protocols. These named entities anchor industry-level commentary without implying specific strategic actions or market share claims.
| Leading Market Players |
|---|
| BASF SE |
| Dow Inc. |
| AkzoNobel N.V. |
| Solvay S.A. |
| Clariant AG |
| Lanxess AG |
| DuPont |
| Arkema S.A. |
| Albemarle Corporation |
| Others |
Value Network & Pricing Analysis
Captive backward integration into chlorinated intermediate feedstocks anchors both supply security and pricing power for North American and European producers, insulating premium formulation tiers from volatile spot-market swings in perchloroethylene and trichloroethylene.
Pricing Analysis
Certification-grade pricing tied to FAA and EASA qualification outcomes stratifies across premium, standard, and economy tiers. Aerospace-grade halogenated formulations command the highest premiums through locked-in multi-year supply agreements, while commodity aliphatic alternatives for construction coatings face acute price compression. Feedstock cost volatility in chlorinated intermediates squeezes margins for non-integrated formulators. Electronics-grade phosphorus-based purity grades exhibit the lowest buyer price sensitivity due to sub-ppm residue specifications.
Supply Chain Analysis
India's PLI scheme domestic-content mandates for Gujarat and Tamil Nadu semiconductor packaging are reshaping sourcing patterns for electronics-grade phosphorus-based formulations. Raw material dependencies center on chlorinated intermediates from Gulf Coast petrochemical complexes, aromatic feedstocks from Ludwigshafen integrated sites, and phosphorus derivatives from Chinese phosphate processing hubs. Single-source vulnerability concentrates in brominated precursor supply from limited REACH-authorized producers. Distribution runs through specification-locked direct sales for aerospace and automotive OEMs, with regional chemical distributors serving mid-tier coating producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where upstream control over chlorinated and phosphorus intermediate feedstocks determines margin capture across certification-intensive tiers.
For Market Incumbents: Hedge against REACH authorization bottlenecks by accelerating phosphorus-based technology partnerships and securing alternative brominated precursor supply before ECHA phased restrictions tighten. BASF SE and Dow Inc. should deepen captive aromatic and chlorinated feedstock positions to defend formulation margin against commodity spot volatility. Certification investment in FAA-EASA harmonized qualification protocols locks out second-tier competitors. For New Entrants and Emerging Players: Reactive phosphorus oligomer technology for electric vehicle battery tray assemblies offers a technology-first wedge into automotive supply chains where German tier-one suppliers are actively qualifying new formulations. Target India's PLI-subsidized semiconductor packaging clusters in Gujarat and Tamil Nadu for electronics-grade cleaning solvent demand. A joint development partnership with domestic coating producers in China's Yangtze River Delta accelerates water-dispersible system adoption under MEE emission caps. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty technology acquisition by integrated petrochemical majors seeking phosphorus-based purity leadership. Long-term viability favors assets with locked-in aerospace qualification cycles and automotive battery enclosure specification wins. Watch for ECHA authorization timeline acceleration as the inflection signal for brominated formulation obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlorinated Intermediates | Dow Inc. secures feedstock cost control for North American formulation margins. |
| Phosphorus-Based Technology Partnership | Lanxess AG locks in electronics-grade purity specifications for semiconductor packaging. |
| Long-Term Supply Agreement with Aerospace OEM | Airbus procurement in Toulouse enforces three-to-five-year supplier lock-in cycles. |
| Joint Formulation Development with Automotive Tier-One | German battery tray suppliers qualify reactive phosphorus oligomer systems for EV enclosures. |
| Green Manufacturing Transition to Water-Dispersible Systems | China's MEE emission caps favor Yangtze River Delta retrofit investments. |
Research Methodology
Independent corroboration across plant managers at chlorinated intermediate facilities, procurement leads at German automotive OEMs, distribution channel partners in China's eastern corridor, and technical R&D directors at phosphorus-based formulators underwrites the qualitative findings. Secondary validation draws from customs and trade data, SEC 10-K filings, ECHA authorization databases, and ACC industry reports. Bottom-up demand modeling from end-use consumption patterns triangulates against top-down supply-side capacity assessments.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions include chemistry type (halogenated versus phosphorus-based), grade tier (electronics-grade purity versus commodity construction), end-use industry (aerospace, automotive, electronics, construction), and regional production hub (Yangtze River Delta, Ludwigshafen, Gulf Coast). CAGRs derive from regression analysis against industrial production indices and regulatory enforcement timelines. Forecast inputs incorporate REACH authorization phase-out schedules and FAA flammability protocol expansion scope.
Several conditions sit outside the modeled scope, including unannounced regulatory acceleration by EPA or ECHA, breakthrough non-halogenated fire-resistance technologies, and geopolitical disruption to Chinese phosphate supply chains. Forecasts reflect documented assumptions about qualification cycle durations and reformulation investment lag times. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Europe Hydrocarbon Solvents Market
Solvents
Methyl Diethanolamine Market
Solvents
Global Nitrochlorobenzene Market
Solvents
Alpha-Methylstyrene Market
Solvents
Meta-Xylene Market
Solvents
Xylene Market
Solvents
India High Purity Solvents Market
Solvents
Aliphatic Solvents Market
Solvents
Natural Distillates Market
Solvents
Methyl Ethyl Ketone (MEK) Market
Solvents
Dibutyl Ether Market
Solvents
Sugar Dissolvers Market
Solvents
Benzene-Toluene-Xylene (BTX) Market
Solvents
Aromatic Solvents Market
Solvents
Nitromethane Market
Solvents
Nitroglycerin Market