
 Reactive Diluents Market | 2026-2036
Reactive Diluents Market Size, Share, and Industry Trends Forecast 2026-2036
Reactive Diluents Market Outlook
Waterborne epoxy curing systems is reshaping how industrial coatings achieve low-emission performance without sacrificing crosslink density. BASF SE leverages its integrated Ludwigshafen complex to sustain captive supply of specialty glycidyl ethers for high-solids formulations. Evonik Industries AG anchors its position through amino-functional diluent technology leadership in wind turbine blade laminates. Huntsman Corporation competes via geographic dominance in Asian epoxy hardener markets, extending its Jeffreyamine product architecture into reactive diluent adjacencies.
Reactive diluents are low-viscosity epoxy-functional or co-reactive compounds incorporated into thermoset resin systems to reduce application viscosity while participating in the crosslinking reaction, typically containing one or more oxirane rings or amine-reactive termini that become chemically bound in the cured polymer network. Epoxy diluents dominate volume consumption in protective marine coatings where their dilution efficiency preserves chemical resistance at reduced film thickness. Amino diluents represent the fastest-expanding category in aerospace structural adhesives, as out-of-autoclave processing demands extended pot life with rapid elevated-temperature cure. Water-based formulation types command premium positioning in European architectural coatings, while solvent-based systems retain margin pools in industrial maintenance applications requiring extreme chemical exposure.
EPA regulations under TSCA Section 6 are restricting certain alkylphenol-based reactive diluents in consumer-facing coatings, redirecting formulation investment toward cardanol-derived bio-alternatives. REACH Annex XVII limitations on cycloaliphatic amine emissions are forcing European adhesive producers to qualify low-vapor-pressure diluent grades for indoor construction applications. China's MEE standards on industrial VOC discharge are accelerating substitution of traditional solvents with reactive diluents in Yangtze River Delta manufacturing zones. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory in cross-border coating supply chains.
Market Dynamics
REACH Annex XVII restrictions on cycloaliphatic amine emissions are forcing European adhesive producers to requalify entire product portfolios, while automotive OEM lightweighting programs pull epoxy-based coatings into structural applications previously served by metals.
Growth Catalysts
- Automotive lightweighting mandates:OEMs in Germany and Japan are specifying high-solids epoxy primers to replace metal substrates in closure panels, directly consuming glycidyl ether diluents for viscosity control without solvent loading.
- REACH low-VOC thresholds:ECHA enforcement of volatile organic compound limits in industrial maintenance coatings is mandating reformulation toward reactive diluents that chemically bind into cured films rather than evaporating.
- Wind blade manufacturing scale-up:Amino-functional diluent demand is accelerating in Denmark and Spain as turbine OEMs extend blade lengths beyond 100 meters, requiring extended pot life systems for vacuum infusion processing.
Market Restraints
- Epichlorohydrin feedstock volatility:Price swings in propylene-derived epichlorohydrin compress margins for glycidyl ether producers, particularly affecting small-batch specialty diluent manufacturers without backward integration into chlor-alkali operations.
- German supply concentration:Captive production at the Ludwigshafen chemical cluster controls approximately sixty percent of European specialty glycidyl ether capacity, creating single-source vulnerability for coating formulators elsewhere in the continent.
- Alkylphenol regulatory sunset:EPA TSCA Section 6 restrictions on nonylphenol-based diluents are forcing immediate reformulation in US architectural coatings, stranding existing inventory and accelerating substitution toward cardanol bio-alternatives with unproven long-term performance data.
Strategic Opportunities
- India industrial coating penetration:BIS adoption of ISO 12944 corrosion protection standards for infrastructure projects is opening specification pathways for high-performance epoxy systems in Mumbai and Chennai port facilities.
- Aerospace out-of-autoclave processing:Extended pot life amino diluents are capturing share in wing spar adhesives as Boeing and Airbus suppliers qualify room-temperature staging followed by rapid elevated-temperature cure cycles.
- China MEE VOC discharge standards:Yangtze River Delta manufacturing zones face mandatory solvent reduction timelines, creating pull for waterborne epoxy curing systems that incorporate reactive diluents as co-solvent replacements.
Industry Challenges
- Formulation chemist scarcity:Expertise in epoxy-amine stoichiometry and diluent reactivity profiling is concentrating at legacy German and Swiss coating houses, constraining new entrant product development timelines.
- Multi-jurisdiction certification lag:Qualifying a single reactive diluent grade for REACH, EPA TSCA, and China MEE registration simultaneously extends commercialization cycles by eighteen to thirty months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reactive Diluents Market |
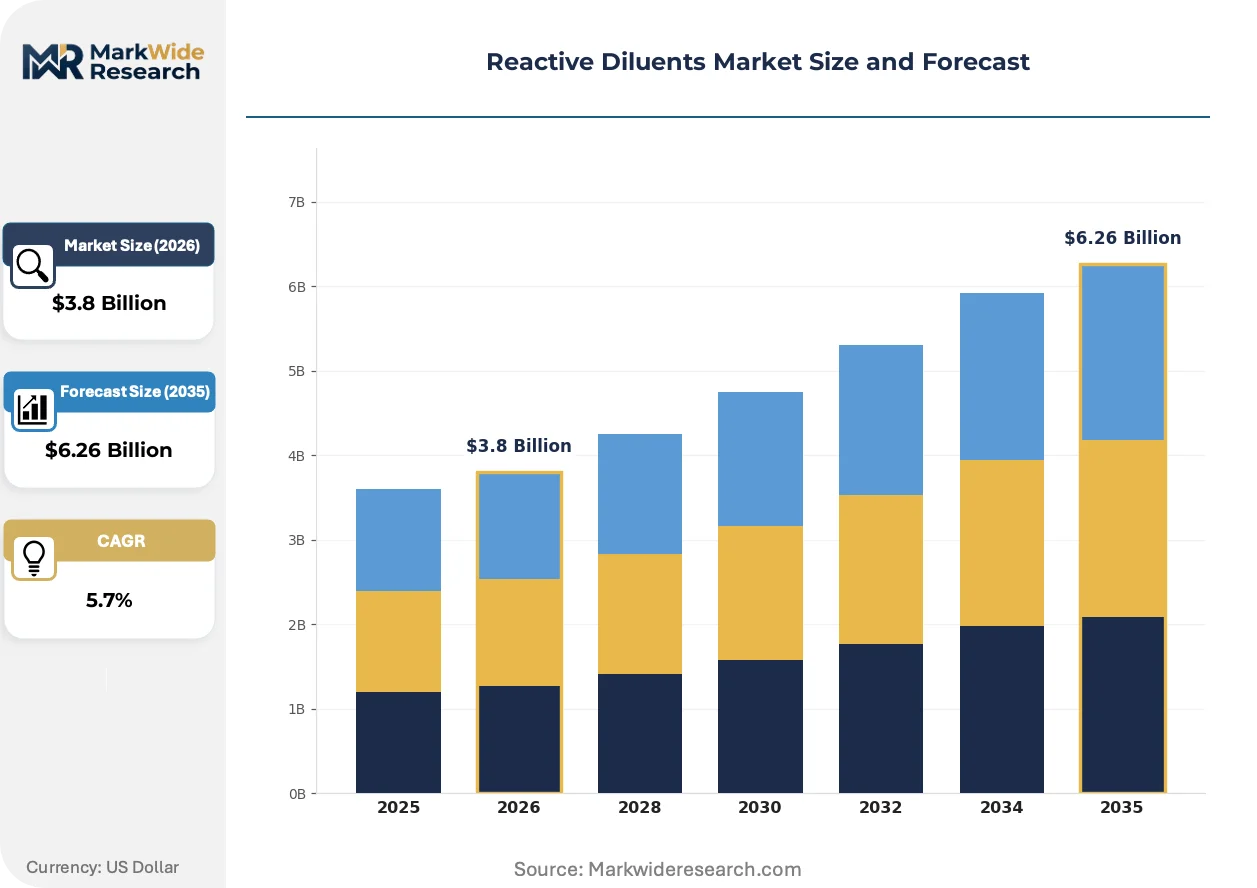
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy Diluent, Amino Diluent, Vinyl Ester Diluent, Polyester Diluent Application: Coatings, Adhesives, Composites, Sealants End User: Aerospace, Automotive, Construction, Marine Formulation Type: Water-based, Solvent-based, UV-curable, Powder Coating |
| Companies Covered | Evonik Industries AG, Cargill, Olin Corporation, Huntsman Corporation, BASF SE, Arkema, Mitsubishi Chemical Group Corporation, Kukdo Chemical, Hexion Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reactive Diluents Market Strategic Shifts
Bio-based feedstock substitution and waterborne curing chemistry are compressing the traditional solvent-borne formulation paradigm, while regulatory divergence between jurisdictions fragments standardization efforts.
Cardanol-derived reactive diluents from cashew nutshell liquid are collapsing the cost premium between bio-based and petroleum-based epoxy functional monomers. Marine coating formulators in Rotterdam and Singapore are qualifying these materials for tank lining applications at commercial scale. The technology is collapsing the historical performance gap that confined bio-alternatives to decorative or light-duty segments.
EPA TSCA Section 6 restrictions on alkylphenol ethoxylates are redirecting US architectural coating investment toward cardanol and lignin-derived diluent platforms. The rulemaking compresses formulation windows for exterior house paints and wood preservatives. Coating manufacturers in the Ohio River Valley are accelerating qualification programs to avoid inventory stranding ahead of enforcement deadlines.
Specification authority is consolidating at European automotive OEM engineering centers, compressing distributor influence in coating procurement decisions. Tier-one suppliers in Stuttgart and Munich now mandate approved diluent grades from qualified resin houses, bypassing traditional channel intermediaries. This concentration is most visible in Germany's industrial belt, where captive supply agreements between chemical producers and coating houses lock out independent distributors from premium formulation segments.
Reactive Diluents Market Segmentation
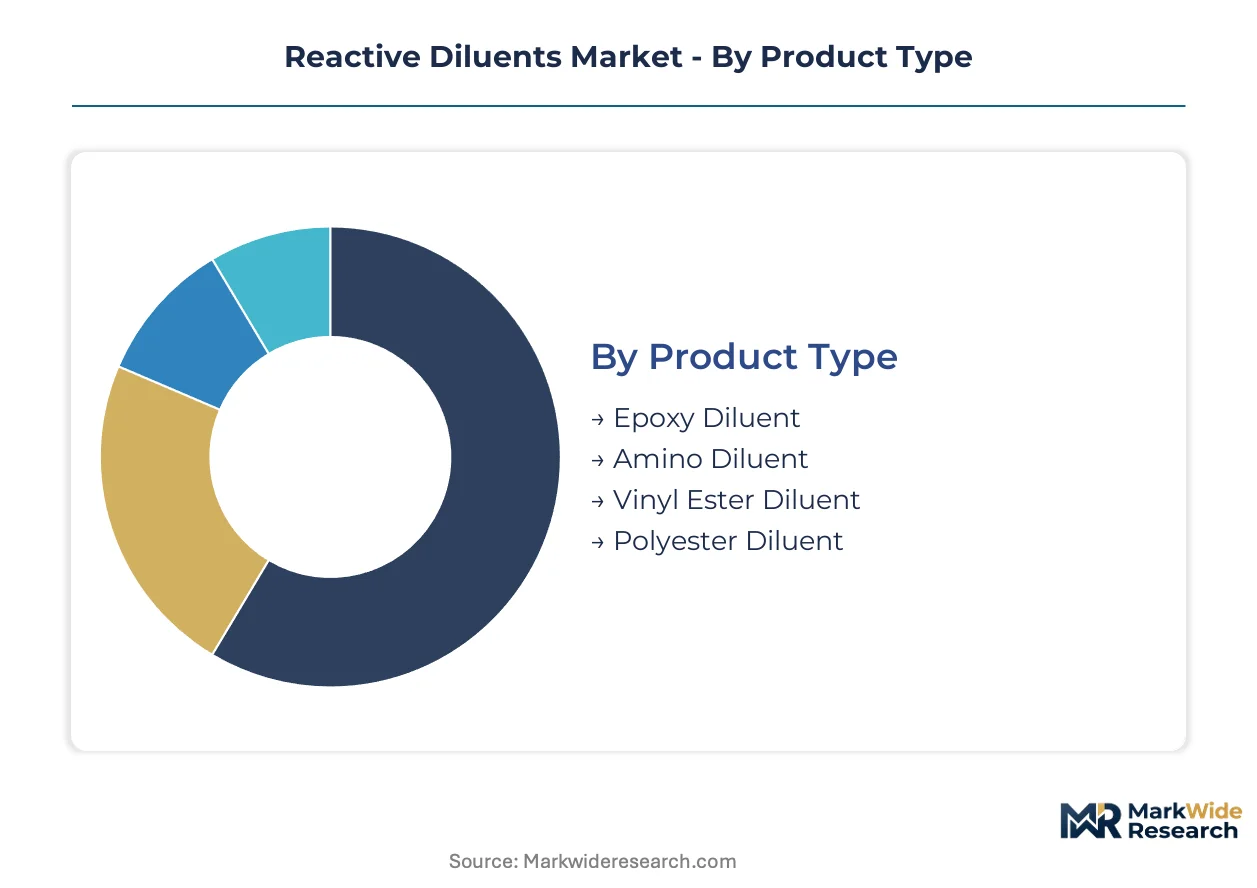
Reactive diluent selection determines formulation service requirements, inventory turns, and technical support intensity across coating and adhesive supply chains. Segmentation reveals how product architecture, application environment, and end-user certification demands create divergent margin pools and customer stickiness profiles.
Product Type:
After-sales service intensity escalates with product complexity, as epoxy and amino diluents demand formulation guidance, pot-life troubleshooting, and cure-profile optimization that simpler vinyl ester variants rarely require.
- Epoxy Diluent:Glycidyl ether compounds with one or more oxirane rings chemically bind into cured networks while reducing application viscosity. Demand concentrates in marine protective coatings serving Rotterdam and Singapore tank lining facilities, where dilution efficiency must preserve chemical resistance at reduced film thickness. REACH low-VOC enforcement is accelerating substitution of traditional solvents with these reactive alternatives.
- Amino Diluent:Amine-reactive termini provide extended pot life with rapid elevated-temperature cure capability. Wind turbine blade manufacturing in Denmark and Spain consumes growing volumes as blade lengths exceed 100 meters and vacuum infusion processing demands precise rheology control. Out-of-autoclave aerospace adhesive qualification is expanding addressable applications.
- Vinyl Ester Diluent:Styrene-based reactive monomers serve corrosion-resistant composites and chemical storage tank fabrication.
- Polyester Diluent:Unsaturated monomers reduce viscosity in gel coat and fiberglass reinforced plastic systems.
By volume, epoxy diluents lead across protective coatings. By growth pace, amino diluents are expanding most quickly in wind energy and aerospace structural applications.
Application:
Cost tier stratification separates specification-grade coatings from commodity adhesives, with composite applications commanding premium pricing for certified aerospace and automotive structural parts.
- Coatings:Industrial maintenance, marine protective, and automotive refinish formulations incorporate reactive diluents to achieve high-solids, low-VOC performance without sacrificing crosslink density. Germany's automotive OEM lightweighting programs are pulling epoxy-based coatings into closure panel applications previously served by metal substrates.
- Adhesives:Structural bonding systems for aerospace wing spars and wind blade laminates require precise pot-life extension with rapid cure activation. Boeing and Airbus suppliers in the US and France are qualifying room-temperature staging followed by elevated-temperature cure cycles.
- Composites:Vacuum infusion and resin transfer molding processes consume reactive diluents for viscosity reduction in fiber-reinforced polymer manufacturing.
- Sealants:Construction and transportation applications utilize reactive diluents for rheology modification and adhesion promotion.
Coatings generate the largest absolute volume consumption. Adhesives are climbing the fastest as out-of-autoclave processing displaces traditional autoclave curing in aerospace fabrication.
End User:
Customer type concentration varies sharply, with automotive and aerospace procurement consolidating at OEM engineering centers while construction remains fragmented across regional applicators.
- Aerospace:FAA and EASA certification requirements mandate extensive qualification protocols for structural adhesive diluents. Extended pot life amino systems are capturing share in wing spar bonding as suppliers seek process flexibility.
- Automotive:OEM specification authority in Stuttgart, Munich, and Toyota City is compressing distributor influence, with tier-one suppliers mandating approved diluent grades from qualified resin houses. High-solids epoxy primers for lightweight closure panels directly consume glycidyl ether diluents.
- Construction:BIS adoption of ISO 12944 corrosion protection standards in India is opening specification pathways for high-performance epoxy systems in Mumbai and Chennai port infrastructure.
- Marine:IMO environmental regulations and shipyard productivity demands drive tank lining and hull coating reformulation toward high-solids, low-VOC systems.
Automotive represents the largest volume end user. Aerospace exhibits the steepest expansion trajectory as commercial aircraft production rates recover and composite content increases.
Formulation Type:
Supply concentration in waterborne curing chemistry is reshaping competitive positioning, as integrated chemical producers with captive glycidyl ether supply capture share from independent formulators.
- Water-based:Epoxy curing systems achieve low-emission performance through reactive diluents that function as co-solvent replacements. European architectural coatings command premium positioning, while China MEE VOC discharge standards in the Yangtze River Delta are accelerating adoption.
- Solvent-based:Traditional systems retain margin pools in industrial maintenance applications requiring extreme chemical exposure and rapid dry-to-handle properties.
- UV-curable:Acrylate and epoxy-functional diluents enable instant cure for wood coatings, graphic arts, and electronics applications.
- Powder Coating:Reactive diluents in powder systems modify melt flow and cure kinetics for architectural and appliance finishes.
Solvent-based formulations retain volume leadership in industrial segments. Water-based systems are gaining share fastest as regulatory pressure intensifies across multiple jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial chemical corridor around Ludwigshafen and Leverkusen concentrates specification authority for European coating formulators. Japanese automotive OEMs in Toyota City and Yokohama anchor Asian demand for high-solids epoxy systems. Chinese manufacturers in the Yangtze River Delta face accelerating regulatory pressure to reformulate solvent-borne coatings.
Germany
Automotive OEM lightweighting programs in Stuttgart and Munich pull glycidyl ether diluents into closure panel applications previously served by metal substrates. ECHA enforcement of REACH Annex XVII cycloaliphatic amine emission limits forces adhesive producers to requalify entire product portfolios for indoor construction. The Ludwigshafen chemical cluster controls approximately sixty percent of European specialty glycidyl ether capacity, creating single-source vulnerability for coating formulators elsewhere on the continent.
China
Wind turbine blade manufacturing scale-up in Jiangsu and Zhejiang provinces accelerates amino-functional diluent consumption as blade lengths exceed 100 meters. MEE standards on industrial VOC discharge mandate solvent reduction timelines across Yangtze River Delta manufacturing zones. Shanghai and Ningbo coating producers are qualifying waterborne epoxy curing systems that incorporate reactive diluents as co-solvent replacements ahead of enforcement deadlines.
United States
EPA TSCA Section 6 restrictions on alkylphenol-based reactive diluents redirect formulation investment toward cardanol-derived bio-alternatives in architectural coatings. Ohio River Valley coating manufacturers accelerate qualification programs to avoid inventory stranding ahead of enforcement timelines. Boeing and Airbus suppliers in Washington State and Kansas qualify extended pot life amino diluents for out-of-autoclave wing spar adhesive applications.
India
BIS adoption of ISO 12944 corrosion protection standards for infrastructure projects opens specification pathways for high-performance epoxy systems in port facilities. Mumbai and Chennai industrial coating applicators transition from solvent-borne maintenance coatings toward high-solids formulations as public sector procurement rules tighten. Gujarat chemical producers expand glycidyl ether capacity to serve domestic marine and protective coating demand.
Japan
Automotive OEM engineering centers in Toyota City concentrate specification authority for high-solids epoxy primers used in lightweight vehicle architectures. METI industrial emissions guidelines push coating formulators toward reactive diluents that chemically bind into cured films. Osaka and Nagoya resin houses maintain captive supply relationships with glycidyl ether producers, compressing distributor influence in premium formulation segments.
Reactive Diluents Market Competitive Environment
Channel-controlling players compete with product-specialist players across distinct margin pools in the reactive diluents market. Integrated chemical producers with captive epichlorohydrin supply dominate European specialty glycidyl ether segments, while independent formulators concentrate in regional adhesive applications. Three archetypes define competitive positioning: backward-integrated resin houses controlling upstream feedstock, amino-functional technology specialists serving wind and aerospace verticals, and geographic-focused hardener suppliers extending into diluent adjacencies. Capacity expansion in Asia-Pacific and strategic partnerships for bio-based feedstock qualification represent the dominant competitive moves.
Within the integrated chemical producer tier, BASF SE and Evonik Industries AG exemplify divergent strategic positions. BASF's Ludwigshafen-based operations represent captive supply chain control over specialty glycidyl ethers for high-solids formulations. Evonik occupies a technology-leadership position in amino-functional diluents for wind turbine blade laminates. Huntsman Corporation anchors the geographic-expansion archetype through Asian epoxy hardener market presence. These three players illustrate how European chemical conglomerates leverage distinct capability bases—feedstock integration, functional technology, and regional distribution—to defend position in adjacent reactive diluent segments.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Cargill |
| Olin Corporation |
| Huntsman Corporation |
| BASF SE |
| Arkema |
| Mitsubishi Chemical Group Corporation |
| Kukdo Chemical |
| Hexion Inc. |
| Others |
Value Chain & Pricing Dynamics
Rhine-Alpine corridor freight rates compress margins for specialty glycidyl ether shipments from Ludwigshafen to Rotterdam coating houses, amplifying the price premium that captive BASF supply commands over independent distributors while forcing smaller formulators toward lower-grade amino diluent alternatives.
Pricing Analysis
Cost-plus contracts with epichlorohydrin indexation dominate glycidyl ether procurement between resin houses and chlor-alkali producers. Price differentiation stratifies across REACH-certified premium grades, standard industrial maintenance tiers, and economy construction adhesive levels. Cost compression in standard epoxy diluents is intensifying because propylene derivative volatility transfers directly to contract renegotiations. Mid-sized coating formulators exhibit highest price sensitivity, while aerospace adhesive suppliers accept premium amino-functional grades for certification compliance.
Supply Chain Analysis
Contract manufacturing concentrates at Hexion's Rotterdam blending facilities and Kukdo Chemical's Ulsan operations for bulk epoxy diluent formulation. Production gravity centers on Germany, China, and South Korea for glycidyl ether synthesis. Feedstock supply draws from propylene derivatives, cashew nutshell liquid for cardanol bio-alternatives, and cycloaliphatic amine intermediates. Single-source vulnerability pervades European specialty glycidyl ether access given Ludwigshafen cluster dominance. Distribution runs through qualified resin house direct sales for automotive OEMs, with independent distributors serving fragmented construction applicators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where REACH registration entrenchment creates switching costs that lock coating formulators into established supplier relationships for eighteen to thirty month qualification cycles.
For Market Incumbents: Harden regulatory moats by accelerating REACH Annex XVII pre-registration for low-vapor-pressure amino diluent grades ahead of ECHA enforcement timelines. Deepen backward integration into epichlorohydrin through chlor-alkali joint ventures in the Yangtze River Delta to offset German supply concentration risk. Prioritize certification investment for aerospace out-of-autoclave adhesive qualifications at Boeing and Airbus tier-one suppliers.
For New Entrants and Emerging Players: India's industrial coating penetration offers the most penetrable white-space target as BIS ISO 12944 adoption accelerates specification pathways for high-performance epoxy systems in Mumbai and Chennai port infrastructure. Qualify cardanol-derived bio-diluents for marine tank lining applications where EPA TSCA Section 6 is stranding alkylphenol inventory. Pursue toll-manufacturing partnerships with Gujarat chemical producers to bypass capital-intensive glycidyl ether synthesis.
For Investors and Strategic Acquirers: EPA TSCA Section 6 enforcement reshapes the acquisition landscape toward cardanol bio-alternative platforms with proven marine qualification data. Long-term viability favors amino-functional technology specialists serving wind energy and aerospace verticals over commodity epoxy diluent producers exposed to feedstock volatility. Monitor ECHA REACH Annex XVII implementation timelines as the critical inflection signal for European adhesive producer distress. Quarterly review of MEE VOC discharge standard enforcement in Jiangsu and Zhejiang provinces is advised to detect Chinese waterborne formulation inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epichlorohydrin | Captive chlor-alkali supply insulates BASF and Olin from propylene derivative volatility in Ludwigshafen and Texas. |
| Bio-Based Feedstock Qualification | Cardanol-derived diluents from Cargill collapse the performance gap for marine tank lining applications at Rotterdam. |
| REACH Pre-Registration Acceleration | Early ECHA compliance for low-vapor-pressure amino grades locks out competitors from indoor construction segments. |
| Aerospace Adhesive Certification | Extended pot life amino diluent qualification at Boeing and Airbus suppliers captures out-of-autoclave processing shift. |
| Waterborne Curing System Partnership | Joint development with Shanghai coating producers addresses China MEE VOC mandates in Yangtze River Delta zones. |
Study Parameters
Desk research of ECHA REACH registration databases, EPA TSCA Section 6 docket filings, and China MEE discharge standard notices preceded structured interviews with epoxy resin plant managers, coating procurement leads at automotive OEMs, wind blade manufacturing engineers, and marine protective coating formulators. Primary fieldwork combined with secondary validation from SEC 10-K chemical segment disclosures, Cefic trade flow data, and customs import records. Bottom-up volume modeling triangulated against top-down market sizing across product type, application, and formulation segments.
Assumptions held fixed include REACH Annex XVII enforcement timelines, EPA TSCA Section 6 alkylphenol sunset dates, and China MEE VOC reduction mandates across the analysis window. Variables modeled encompass automotive lightweighting penetration rates, wind turbine blade length trajectories, and aerospace out-of-autoclave adoption curves. Segmentation dimensions included epoxy versus amino versus vinyl ester diluent chemistry, coatings versus adhesives versus composites end-use, and water-based versus solvent-based versus UV-curable formulation platforms. CAGRs derived from regression analysis of historical volume trends against projected end-use demand elasticities.
Practitioners should monitor epichlorohydrin price volatility, ECHA enforcement intensity, and MEE inspection frequency for early signals of forecast revision. Forecasts reflect assumptions about regulatory implementation cadence, feedstock cost pass-through mechanisms, and qualification timeline stability. Quarterly review of REACH registration completion rates, wind turbine OEM production schedules, and aerospace tier-one supplier qualification announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Epoxy Thinner Market
Solvents
Xylene Market
Solvents
Methyl Acetate Market
Solvents
Decanol Market
Solvents
Methyl Diethanolamine Market
Solvents
Asia Pacific Industrial Solvents Market
Solvents
Aliphatic Solvents Market
Solvents
4-Dichlorobenzyl Alcohol (DCBA) Market
Solvents
3-Methyl-3-Penten-2-One (3M3P) Market
Solvents
Butane Market
Solvents
Nitroglycerin Market
Solvents
Mono Propylene Glycol Market
Solvents
Coating Solvents Market
Solvents
Hydrofluoroether Market
Solvents
6-Xylenol Market
Solvents
Electronic Cleaning Solvents Market