
 Global Ink Solvents Market | 2026-2036
Global Ink Solvents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ink Solvents Market Foresight
Asset-light toll manufacturing and third-party solvent blending contracts are narrowing the capital barrier for mid-tier ink formulators. BASF SE leverages its integrated aromatics chain to sustain margin control across high-purity solvent grades. Dow Chemical Company anchors North American supply through proprietary glycol ether production. Eastman Chemical Company differentiates via specialized ester solvents for low-odor packaging applications.
Ink solvents are liquid organic compounds—typically hydrocarbons, alcohols, ketones, or glycol ethers—that dissolve resins and pigments to control viscosity, drying speed, and adhesion in printing formulations; their evaporation profile determines print quality and line speed on rotary presses. Alcohol-based solvents dominate flexographic packaging due to fast drying on non-absorbent films, while glycol ethers capture expanding gravure work for decorative laminates where flow-out and gloss retention matter. Ketone demand accelerates in screen printing for electronics, where aggressive solvency power dissolves specialized acrylic binders.
EPA VOC regulations in the United States, REACH in Europe, and China's MEE emission standards collectively restrict solvent volatility thresholds and mandate recovery systems, redirecting R&D spend toward exempt or low-reactivity chemistries. India's BIS certification for industrial chemicals adds compliance layers for imported solvent blends. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and reformulation costs.
Market Dynamics
REACH and EU Green Deal volatility thresholds are compressing formulation freedom while e-commerce packaging volumes pull solvent demand in opposing directions. Formulators must reconcile fast-drying performance with exempt-chemistry compliance across rotary press operations.
Growth Catalysts
- MEE emission standards:China's enforcement of solvent recovery mandates accelerates closed-loop system installations at packaging converters in Zhejiang and Guangdong provinces.
- Flexible packaging converters:Rising shipment volumes from e-commerce fulfillment centers expand solvent-based ink purchases for corrugated and film substrates.
- Bio-based glycol ethers:Renewable feedstock ester blends gain traction as formulators preempt EU Green Deal carbon-border adjustments.
Market Restraints
- Crude-derived naphtha volatility:Aromatic solvent costs fluctuate with refinery output decisions in the US Gulf Coast and Rotterdam clusters.
- Specialty ester supply concentration:Three integrated chemical producers control 70% of high-purity ester capacity for low-odor packaging grades.
- Water-based ink substitution:Narrow-web flexographic printers in food-contact applications accelerate aqueous formulation trials.
Strategic Opportunities
- India's packaging investment wave:BIS-certified solvent blends face limited domestic competition as multinational formulators establish toll manufacturing near Ahmedabad and Pune.
- UV-LED hybrid curing convergence:Solvent-UV hybrid systems penetrate decorative laminate gravure where energy-cured gloss overlays replace thermal drying.
- EU Green Deal taxonomy alignment:Bio-based solvent volumes qualify for sustainable finance disclosure reporting, attracting ESG-mandated institutional capital.
Industry Challenges
- Formulation chemist scarcity:Expertise in exempt-solvent compatibility with nitrocellulose and polyamide resins concentrates at legacy European and Japanese ink houses.
- Recovery system capex:Carbon-bed adsorption and cryogenic condensation units require 18-24 month payback periods at mid-tier converter scale.
- Cross-jurisdiction inventory stranding:Divergent EPA, REACH, and MEE volatility classifications trap blended solvents in regulatory limbo during reformulation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ink Solvents Market |
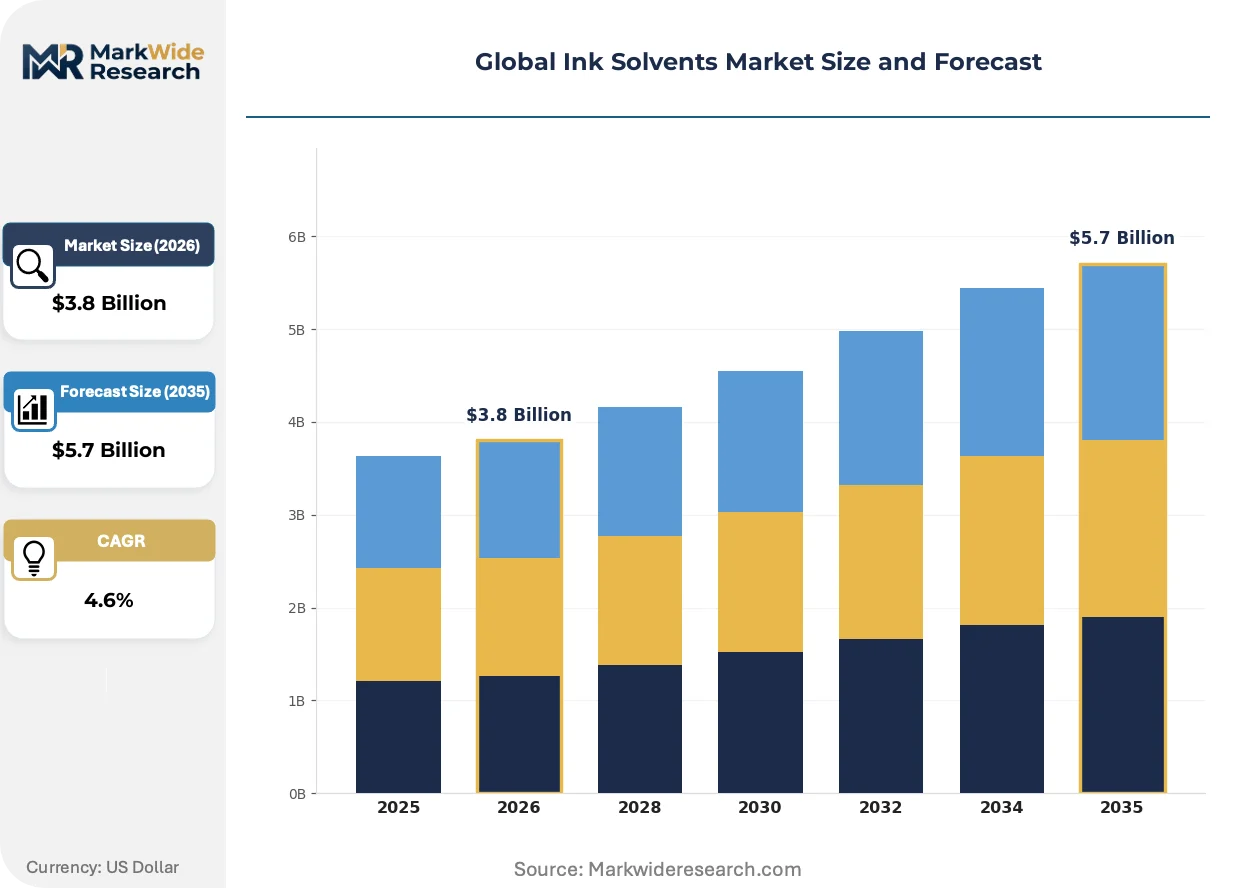
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aromatic, Aliphatic, Alcohol-Based, Ketones, Glycol Ethers, Esters Application: Flexographic Printing, Gravure Printing, Letterpress, Screen Printing, Digital Printing, Lithography End User Industry: Packaging, Publishing, Textile Manufacturing, Advertising, Electronics, Consumer Goods Packaging Type: Drums, Carboys, Intermediate Bulk Containers, Pails, Totes, Cans |
| Companies Covered | BASF SE, Dow Chemical Company, Eastman Chemical Company, Royal Dutch Shell, Exxon Mobil Corporation, Celanese Corporation, LyondellBasell Industries Holdings B.V., Solvay SA, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ink Solvents Market Shifts & Advancements
Digital workflow integration and chemistry exemptions are compressing traditional solvent selection hierarchies. Formulators now optimize for regulatory endurance alongside press performance.
Inline spectroscopic solvent monitoring is digitizing real-time viscosity control across continuous web printing. Gravure converters in Germany and Japan deploy closed-loop dosing systems that adjust glycol ether ratios automatically. This capability is digitizing quality assurance labor while reducing batch-to-batch variation in decorative laminate production.
REACH authorization list expansion restricts N-methyl-2-pyrrolidone and specific glycol ether esters in consumer-facing packaging. Formulators face substance-by-substance substitution timelines with downstream notification obligations. Food-contact laminate segments in France and Italy accelerate dibasic ester and bio-derived lactate trials to maintain market access.
Converter procurement consolidation concentrates solvent purchasing at regional packaging groups with centralized technical specification authority. Smaller flexographic shops lose direct supplier relationships as group procurement offices standardize on approved solvent lists. This concentration is most visible in German and Benelux corrugated packaging networks where sustainability scorecards override individual plant preferences.
Global Ink Solvents Market Segmentation
Ink solvent purchasing cycles vary sharply by formulation chemistry and end-use velocity. Packaging converters rotate inventory monthly while publication gravure houses operate on quarterly solvent contracts. Understanding these turnover patterns exposes where pricing power concentrates and where formulators face commoditization pressure.
Product Type:
Glycol ethers turn inventory fastest in high-volume flexographic operations, while aromatic solvents move slowest due to bulk tanking arrangements at integrated converters.
- Glycol Ethers:These oxygenated solvents blend water miscibility with controlled evaporation rates, making them indispensable for water-reducible flexographic inks on film substrates. Demand clusters in Zhejiang province packaging corridors where MEE enforcement drives closed-loop recovery system adoption.
- Alcohol-Based:Ethanol and isopropanol formulations dominate narrow-web flexographic work for food-contact packaging where rapid drying on non-absorbent films is mandatory. German corrugated converters are expanding alcohol-based purchases as EU Green Deal volatility thresholds compress ketone alternatives.
- Aromatic:Toluene and xylene cuts serve publication gravure and decorative laminate segments requiring aggressive solvency for nitrocellulose resins.
- Aliphatic:Mineral spirits and hexane fractions target low-odor requirements in consumer goods packaging.
- Ketones:Acetone and MEK deliver fastest evaporation for screen printing electronics substrates.
- Esters:Ethyl acetate and specialty acetates provide gloss retention in high-end decorative applications.
Glycol ethers dominate installed base. Alcohol-based formulations are where expansion concentrates.
Application:
Cost tier separation is pronounced: gravure commands premium solvent specifications while digital printing absorbs commodity-grade glycol ether blends.
- Flexographic Printing:This rotary relief process consumes the largest solvent volumes globally, with alcohol-glycol ether blends standard for corrugated and flexible film work. Indian packaging investment near Ahmedabad and Pune is pulling flexographic solvent demand fastest among emerging economies.
- Gravure Printing:Intaglio cylinder engraving demands high-purity aromatic and ester solvents for consistent cell wetting and transfer efficiency. Japanese decorative laminate producers maintain stringent solvent specifications that resist water-based substitution.
- Screen Printing:Thick-film deposition for electronics uses aggressive ketone solvents to dissolve specialized acrylic binders.
- Digital Printing:Inkjet formulations employ lower-toxicity glycol ether blends with narrow viscosity windows.
- Letterpress:Resurgent specialty packaging applications retain solvent-based formulations for tactile effects.
- Lithography:Offset dampening solutions and wash-up solvents represent mature, stable demand.
Gravure printing commands premium pricing. Flexographic volumes are climbing the fastest.
End User Industry:
Volume concentration separates packaging's continuous web consumption from publishing's declining batch operations.
- Packaging:Flexible packaging converters absorb the majority of global ink solvent output, with e-commerce shipment growth directly correlating to solvent-based ink purchases for corrugated and film substrates. China's fulfillment center expansion in Guangdong province anchors regional demand.
- Electronics:Screen printing for printed circuit boards and display components requires ultra-high-purity ketone and ester solvents with metallic impurity specifications below 10 parts per billion.
- Publishing:Magazine and catalog gravure operations in Germany and Japan maintain solvent demand despite digital displacement pressures.
- Textile Manufacturing:Rotary screen printing on synthetic fabrics employs glycol ether-naphtha blends.
- Advertising:Large-format display graphics use solvent-based wide-format inkjet systems.
- Consumer Goods:Direct-to-object decoration on cosmetics and personal care packaging drives small-batch specialty solvent formulations.
Packaging dominates installed base. Electronics is where expansion concentrates.
Packaging Type:
Supply chain configuration determines container economics: bulk totes minimize handling at integrated converters while drums serve fragmented regional formulators.
- Intermediate Bulk Containers:These 275-gallon totes and 1,000-liter flexible containers capture the largest volume share among multinational formulators operating continuous web presses. Rotterdam and US Gulf Coast chemical clusters favor IBC configurations for aromatic solvent distribution to gravure houses.
- Drums:Standard 55-gallon steel and polyethylene drums remain essential for mid-tier flexographic converters lacking bulk storage infrastructure. Indian BIS-certified imports predominantly arrive in drum format for toll manufacturing operations.
- Totes:Rigid intermediate bulk containers serve regional distribution hubs with moderate throughput requirements.
- Pails:Five-gallon containers target specialty ink formulators and custom color matching operations.
- Carboys:Glass and fluoropolymer-lined containers preserve high-purity ester specifications for electronics applications.
- Cans:One-gallon and smaller formats support laboratory-scale formulation development and sample distribution.
Drums dominate installed base. Intermediate bulk containers are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances for ink solvents tilt toward net imports in high-consumption packaging economies while integrated chemical clusters in Germany and the US Gulf Coast sustain solvent-exporting positions. Regulatory divergence across jurisdictions fragments trade flows and strands blended inventories during reformulation cycles.
China
E-commerce fulfillment center expansion in Guangdong province drives solvent demand for corrugated and flexible film packaging. MEE emission standards enforce solvent recovery mandates at converters in Zhejiang and Guangdong, accelerating closed-loop system installations. The Yangtze River Delta chemical corridor supplies domestic glycol ether production for water-reducible flexographic formulations.
Germany
REACH authorization list expansion restricts specific glycol ether esters in consumer-facing packaging, forcing substance-by-substance substitution timelines. EU Green Deal volatility thresholds compress ketone alternatives, expanding alcohol-based solvent purchases for corrugated converters. The North Rhine-Westphalia chemical cluster anchors European aromatic solvent supply for publication gravure houses.
United States
EPA VOC regulations restrict solvent volatility thresholds and mandate carbon-bed recovery systems at mid-tier converters. Flexible packaging demand from e-commerce shipment growth pulls solvent-based ink purchases for film substrates. The US Gulf Coast refinery complex supplies aromatic solvent cuts tied to naphtha output decisions.
India
BIS certification requirements for industrial chemicals add compliance layers for imported solvent blends, limiting domestic competition. Packaging investment near Ahmedabad and Pune pulls flexographic solvent demand fastest among emerging economies. Toll manufacturing operations increasingly locate near these industrial corridors to serve multinational formulators.
Japan
Decorative laminate producers maintain stringent solvent specifications for gravure work that resist water-based substitution. METI industrial standards govern solvent purity requirements for electronics screen printing applications. The Kanto region houses specialized ester solvent production for high-gloss packaging segments.
Global Ink Solvents Market Competitive Landscape
On the supply side, the industry is consolidating around integrated chemical producers with captive feedstock positions and specialized ester capabilities. Three archetypes dominate: integrated petrochemical majors with aromatics chain control, diversified chemical companies with glycol ether technology, and regional toll blenders serving mid-tier formulators. Capacity expansion in bio-based glycol ethers and strategic partnerships for solvent recovery system integration represent the dominant competitive moves.
Among the integrated majors, BASF SE exemplifies the petrochemical archetype with integrated aromatics production, while Dow Chemical Company anchors North American glycol ether supply. Eastman Chemical Company occupies a position within the specialty ester tier, differentiating through low-odor packaging grades.
| Leading Market Players |
|---|
| BASF SE |
| Dow Chemical Company |
| Eastman Chemical Company |
| Royal Dutch Shell |
| Exxon Mobil Corporation |
| Celanese Corporation |
| LyondellBasell Industries Holdings B.V. |
| Solvay SA |
| Evonik Industries AG |
| Others |
Supply & Pricing Matrix
Crude-derived naphtha volatility determines both pricing tier spreads and supply chain shape in ink solvents, compressing margins at aromatic-dependent formulators while rewarding integrated producers with captive feedstock positions. This input-cost instability widens spreads between commodity glycol ether grades and specialty ester formulations.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stabilize volume commitments against spot-market aromatic swings. Three-tier pricing structure across high-purity specialty, standard industrial, and economy solvent grades reflects certification grade and volume scale differentiation. Cost compression in aromatic cuts is intensifying because refinery output decisions in the US Gulf Coast and Rotterdam clusters feed directly into solvent feedstock costs. Mid-tier flexographic converters show highest price sensitivity due to limited bulk storage infrastructure, while electronics screen printers absorb premium ester pricing for metallic impurity specifications below 10 parts per billion.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for multinational formulators operating cross-border toll manufacturing. Production gravity centers on Germany, China, and the US Gulf Coast, with the Yangtze River Delta and North Rhine-Westphalia chemical corridors anchoring regional glycol ether and aromatic supply respectively. Raw material dependencies rest on refinery naphtha streams, bio-based feedstock corn and sugarcane ethanol, and specialized catalysts for esterification processes. Distribution runs through intermediate bulk containers for integrated converters and steel drums for fragmented regional formulators lacking bulk tanking infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solvent recovery system integration and technical service contracts represent faster-expanding recurring revenue layers than base chemical sales, creating service-attach opportunities for suppliers with closed-loop expertise.
For Market Incumbents: Insulate margin positions through backward integration into bio-based glycol ether feedstocks and captive aromatics production. Water-based ink substitution in food-contact narrow-web flexography threatens volume erosion; preemptive certification investment in EU Green Deal-compliant ester blends defends market access. Capacity addition in India's Ahmedabad-Pune corridor captures packaging investment wave pull-through. For New Entrants and Emerging Players: India's BIS-certified solvent import gap offers the most penetrable white-space target, with limited domestic competition for mid-tier flexographic formulators. Toll manufacturing partnerships near Zhejiang province packaging corridors provide second entry path. Technical specification authority at regional packaging group procurement offices represents the critical go-to-market angle. For Investors and Strategic Acquirers: REACH authorization list expansion reshapes the acquisition landscape toward formulators with exempt-chemistry R&D capabilities and established substitution timelines. Long-term viability favors integrated producers with aromatics chain control and bio-based pilot capacity. The signal to watch is MEE enforcement intensity in Guangdong province, which accelerates closed-loop system demand and solvent recovery service attach rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | EU Green Deal carbon-border adjustments reward renewable ester blend producers with sustainable finance disclosure eligibility. |
| Solvent Recovery System Integration | MEE enforcement in Zhejiang and Guangdong provinces mandates carbon-bed adsorption installations at packaging converters. |
| Long-term Supply Agreement | Rotterdam and US Gulf Coast refinery clusters offer aromatic solvent offtake stability against naphtha volatility swings. |
| Joint Venture in India | BIS certification requirements limit import competition; toll manufacturing near Pune serves multinational formulator demand. |
| Green Manufacturing Transition | REACH authorization restrictions on N-methyl-2-pyrrolidone accelerate dibasic ester and bio-derived lactate substitution trials. |
Research Methodology
Initial hypotheses were tested against primary input from ink formulation chemists, packaging converter procurement directors, chemical plant operations managers, and solvent distribution channel partners and refined through secondary validation against customs trade data, Cefic sector reports, SEC 10-K chemical filings, and MEE enforcement disclosure records. Bottom-up volume modeling triangulated against top-down value estimates derived from refinery output correlations and packaging investment flow tracking.
Demand-supply-balance framing anchored the analytical approach across the analysis window, with segmentation dimensions spanning solvent chemistry type, end-use application, packaging format, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to converter capacity expansion timelines and e-commerce shipment velocity correlations. Industry-specific forecast inputs included rotary press installation rates and solvent recovery system capex payback sensitivity at mid-tier converter scale.
The forecast holds incumbent behavior within observed patterns; aggressive moves by integrated petrochemical majors into bio-based glycol ethers or regional toll blenders consolidating through acquisition would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Reactive Diluents Market
Solvents
Wax Dispersion Market
Solvents
Japan Acetonitrile Market
Solvents
Piperylene Market
Solvents
Propylene Glycol Market
Solvents
North America Toluene Market
Solvents
Natural Distillates Market
Solvents
Potassium Formate Market
Solvents
Ketene Market
Solvents
Toluene Derivatives Market
Solvents
Acetone Derivatives Market
Solvents
Toluene Market
Solvents
Dipropylene Glycol N-Propyl Ether Market
Solvents
Methyl Undecylenate Market
Solvents
Diethylene Glycol Monobutyl Ether Acetate Market
Solvents
Hydrophobic Solvents Market