
 Global High Purity AHCL Market | 2026-2036
Global High Purity AHCL Market Size, Share, and Industry Trends Forecast 2026-2036
Global High Purity AHCL Market Foresight
Chinese specialty gas producers is expanding high-purity anhydrous hydrogen chloride capacity to serve domestic semiconductor self-sufficiency targets. Linde plc leverages its global helium and electronic gas network to anchor AHCL supply for advanced lithography customers in Taiwan and Germany. Air Liquide S.A. sustains leadership through on-site purification systems at major European chip foundries. BASF SE differentiates via backward integration into chlor-alkali feedstocks, securing raw material stability for reagent-grade output.
High purity AHCL denotes anhydrous hydrogen chloride refined to sub-ppm metallic and moisture specifications, typically achieved through fractional distillation and adsorptive drying to achieve total impurity levels below one part per million. The compound functions as a critical etchant and dopant carrier in semiconductor manufacturing, particularly for silicon wafer surface preparation and compound semiconductor epitaxy. Semiconductor grade product commands the dominant value share due to fabs' zero-tolerance for particulate contamination at nodes below seven nanometers. Electronic grade output represents the fastest-expanding category as photovoltaic cell manufacturers adopt n-type TOPCon architectures requiring cleaner process chemistry. Reagent grade supply remains mature, with margin pools compressing as laboratory procurement consolidates through distributor networks.
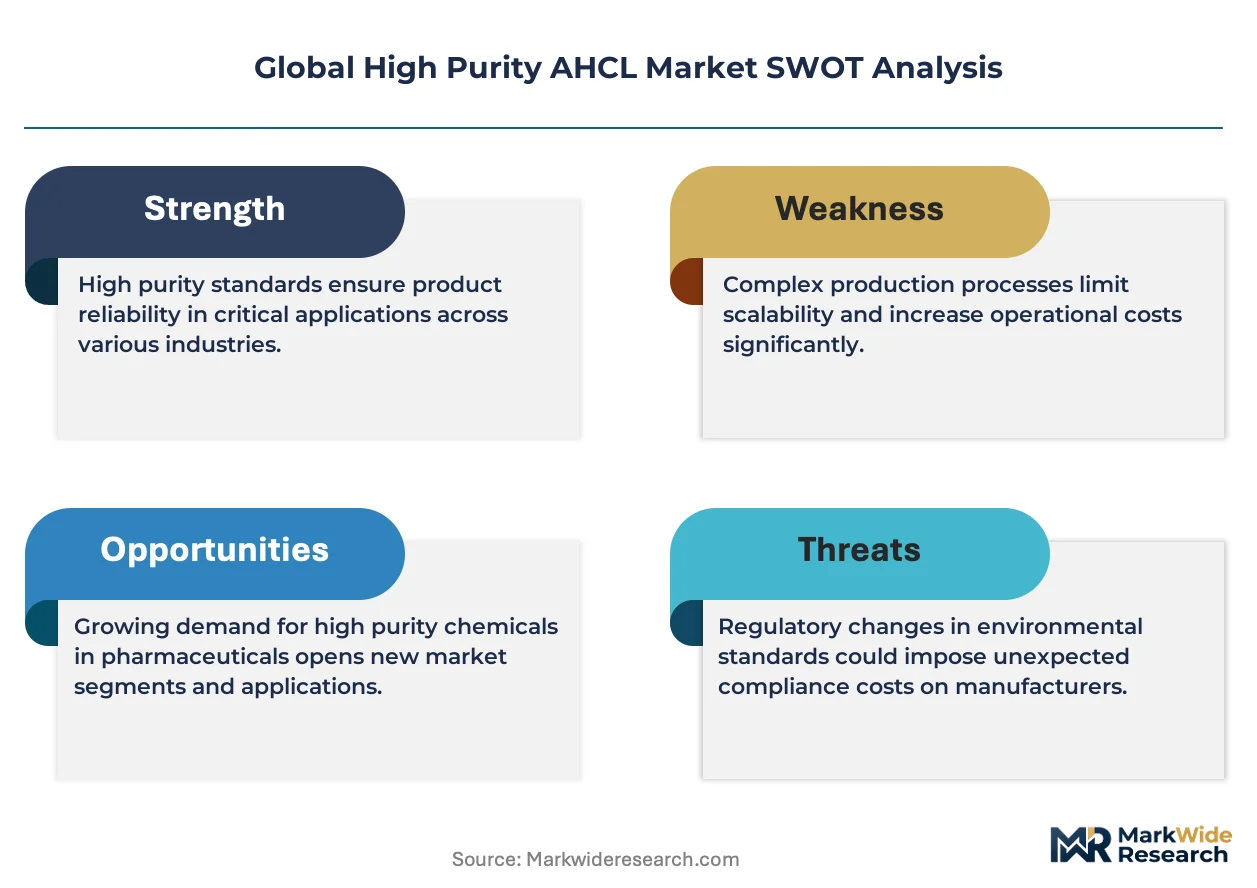
EPA hazardous air pollutant standards and REACH Annex XVII restrictions on chlorinated substance emissions shape product formulation and packaging requirements across US and European supply chains. Japan's METI enforces JIS K 8180 purity benchmarks that effectively block uncertified imports from serving its domestic electronics base. Semiconductor manufacturers must monitor regulatory divergence between EPA risk management rules and EU F-Gas Regulation amendments, as divergent compliance costs will reshape supplier qualification timelines and capital allocation priorities.
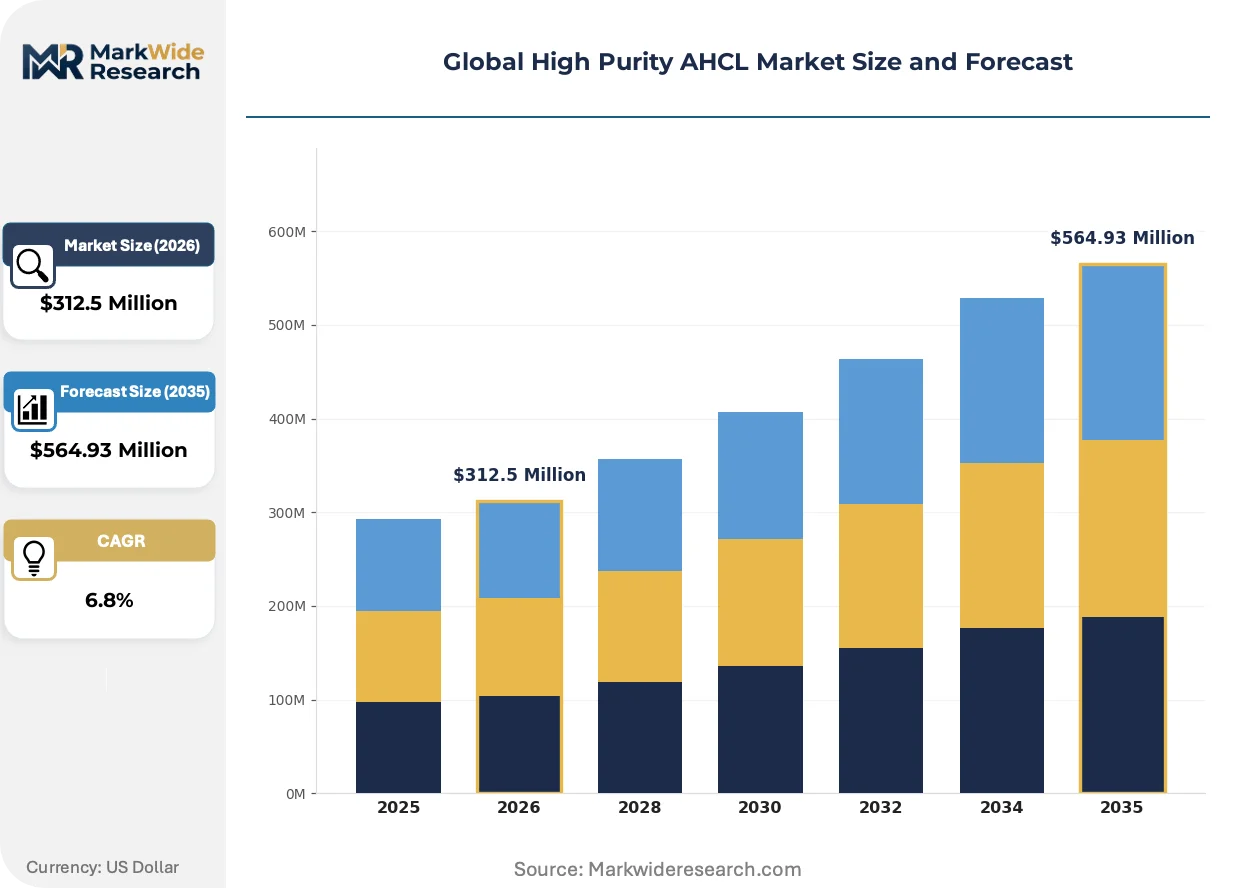
Market Dynamics
Advanced node migration below three nanometers is intensifying purity requirements for etchant gases, forcing suppliers to deploy multi-stage cryogenic distillation and point-of-use purification systems at fab sites.
Growth Catalysts
- EUV Lithography Expansion:Semiconductor manufacturers in South Korea's Gyeonggi cluster now require ultra-high-purity AHCL for photoresist development and wafer conditioning at sub-7nm nodes.
- REACH Annex XVII Tightening:Stricter chlorinated substance emission thresholds across European supply chains are accelerating replacement of lower-purity alternatives with certified electronic-grade reagents.
- TOPCon Cell Architecture:Photovoltaic producers adopting n-type tunnel oxide passivated contact designs demand cleaner process chemistry for boron diffusion and surface passivation steps.
Market Restraints
- Feedstock Concentration:Chlor-alkali capacity for hydrogen chloride precursors clusters in coastal China and the US Gulf Coast, exposing buyers to shipping disruption and tariff exposure.
- Moisture Specification Limits:Current adsorptive drying technologies face fundamental thermodynamic constraints preventing sub-ppb moisture achievement without prohibitively expensive cryogenic trapping stages.
- F-Gas Regulation Friction:EU amendments restricting fluorinated greenhouse gases create compliance complexity for AHCL suppliers using fluoropolymer-lined transport containers and process equipment.
Strategic Opportunities
- India Semiconductor Mission:Domestic fab construction under the country's PLI scheme creates first-mover advantage for suppliers establishing local purification and on-site generation capability.
- Compound Semiconductor Epitaxy:Gallium nitride and silicon carbide device manufacturing for power electronics requires specialized dopant carrier chemistries with distinct impurity profiles from silicon processing.
- Closed-Loop Recycling:On-site recovery and re-purification systems at large fabs reduce virgin material consumption while locking in long-term service contracts with integrated gas suppliers.
Industry Challenges
- Metrology Talent Scarcity:Operation of inductively coupled plasma mass spectrometry and atmospheric pressure ionization systems for sub-ppb impurity detection requires specialized analytical chemists in short supply across manufacturing regions.
- Qualification Timeline Compression:Semiconductor customers now demand six-month supplier validation cycles for new purification sources, down from historical eighteen-month windows, straining documentation and audit resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global High Purity AHCL Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analytical Grade, Reagent Grade, Electronic Grade, Semiconductor Grade, Optics Grade Application: Pharmaceuticals, Electronics Manufacturing, Water Treatment, Food Processing, Laboratory Research End User: Semiconductor Manufacturers, Research Institutions, Pharmaceutical Producers, Chemical Synthesizers, Water Treatment Facilities Packaging Type: Plastic Drum, Glass Bottle, HDPE Container, Metal Canister, Composite Packaging |
| Companies Covered | Linde plc, Air Liquide S.A., Air Products and Chemicals, Inc., Matheson Tri-Gas, Inc., BASF SE, Gas Innovations, Messer Group GmbH, Showa Denko K.K., Central Glass Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global High Purity AHCL Market Shifts & Advancements
Process control digitization and predictive quality analytics are redefining how purity specifications are guaranteed, shifting competitive advantage from static certification to dynamic, lot-level traceability systems.
Membrane-based gas separation is automating impurity removal in secondary purification stages. Foundries in Taiwan and Germany are piloting polymeric and ceramic membrane systems for moisture and metal contaminant reduction downstream of conventional distillation. This technology is automating quality assurance by enabling real-time permeate monitoring and autonomous process adjustment without batch-wise laboratory verification.
EPA hazardous air pollutant standards are tightening monitoring and reporting obligations for hydrogen chloride storage and handling facilities. The agency's revised Risk Management Plan requirements now mandate third-party audits and enhanced leak detection for quantities above threshold levels. Bulk chemical terminals and on-site generation facilities across Texas and Arizona are retrofitting containment systems and sensor networks to maintain operating permits.
Specification-driven supplier consolidation is concentrating procurement authority at the corporate level rather than individual fab sites. Semiconductor manufacturers are centralizing AHCL sourcing decisions through global category management functions, displacing regional purchasing autonomy. This pattern is most pronounced among memory producers with multi-site manufacturing footprints in South Korea and China, where enterprise-wide master service agreements now govern volume allocation and price benchmarking.
Global High Purity AHCL Market Segmentation
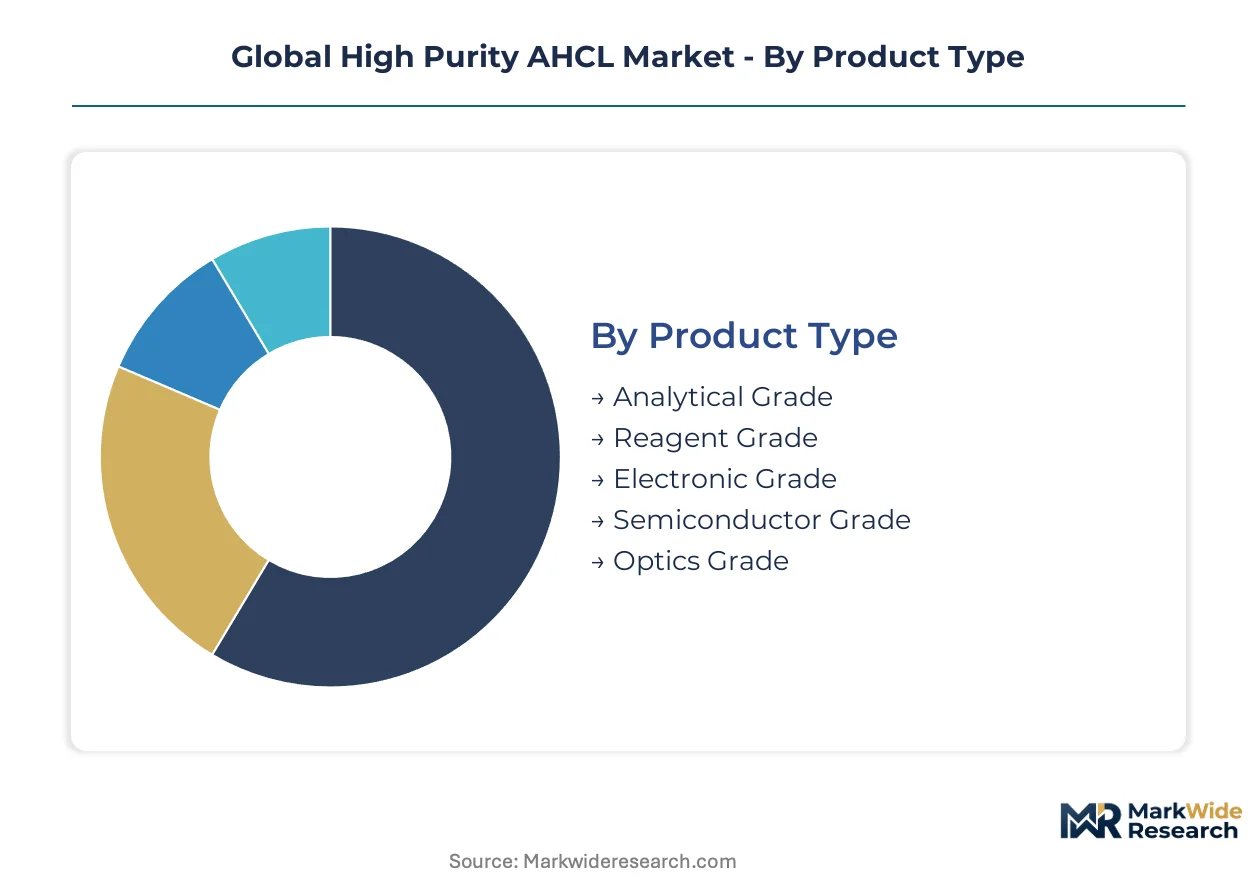
High purity AHCL supply chains fragment across five distinct purity tiers and packaging configurations, each commanding separate qualification protocols and margin structures. Semiconductor fabs source at sub-ppm specifications while analytical laboratories tolerate wider impurity bands, creating tiered procurement patterns that reshape supplier investment priorities.
Product Type:
Supply concentration for ultra-high-purity output clusters among fractional distillation specialists with captive chlor-alkali feedstock access.
- Semiconductor Grade:Refined to sub-ppm metallic and moisture specifications through multi-stage cryogenic distillation and adsorptive drying. South Korea's Gyeonggi cluster now requires this tier for EUV lithography processes at nodes below seven nanometers, with qualification timelines compressing to six-month validation cycles.
- Electronic Grade:Achieves total impurity levels below one part per million for photovoltaic cell manufacturing. N-type TOPCon architecture adoption in China and Taiwan is accelerating consumption for boron diffusion and surface passivation steps.
- Reagent Grade:Serves laboratory and industrial synthesis applications with established JIS K 8180 benchmarks in Japan blocking uncertified imports.
- Analytical Grade:Targets trace analysis and reference standard preparation with documented batch certification.
- Optics Grade:Supports fiber optic preform and specialty glass manufacturing with controlled hydroxyl content.
Semiconductor grade absorbs the bulk of installed capacity; electronic grade is expanding most quickly.
Application:
Cost tier differentiation separates mission-critical fab chemistry from commodity industrial treatment uses.
- Electronics Manufacturing:Wafer etching, epitaxial growth, and photoresist development demand point-of-use purification systems. Taiwan and Germany foundries are piloting membrane-based secondary purification for real-time quality assurance.
- Pharmaceuticals:Active pharmaceutical ingredient synthesis and pH adjustment require documented impurity profiles meeting FDA and EMA guidelines.
- Laboratory Research:Analytical method development and reference material preparation consume certified lots through distributor consolidation.
- Water Treatment:pH control and disinfection byproduct management in municipal systems operates at lower purity thresholds.
- Food Processing:Acidulation and processing aid applications face FSSAI and FDA food-grade compliance requirements.
Electronics manufacturing commands premium pricing; pharmaceuticals is climbing the fastest as biologics manufacturing expands.
End User:
Customer type determines contract structure, with integrated gas suppliers locking in long-term service agreements against spot market laboratory procurement.
- Semiconductor Manufacturers:Foundries in South Korea, Taiwan, and Germany centralize global category management for AHCL sourcing, displacing regional purchasing autonomy. Enterprise-wide master service agreements now govern volume allocation.
- Pharmaceutical Producers:Multi-site manufacturing footprints in India and Switzerland require harmonized impurity documentation across regulatory jurisdictions.
- Research Institutions:University and government laboratory procurement consolidates through distributor networks with compressed margin pools.
- Chemical Synthesizers:Specialty and fine chemical producers source reagent grade material for intermediate manufacturing.
- Water Treatment Facilities:Municipal and industrial utilities purchase bulk quantities with less stringent certification requirements.
Semiconductor manufacturers anchor volume commitments; pharmaceutical producers are gaining share fastest through biologics capacity expansion.
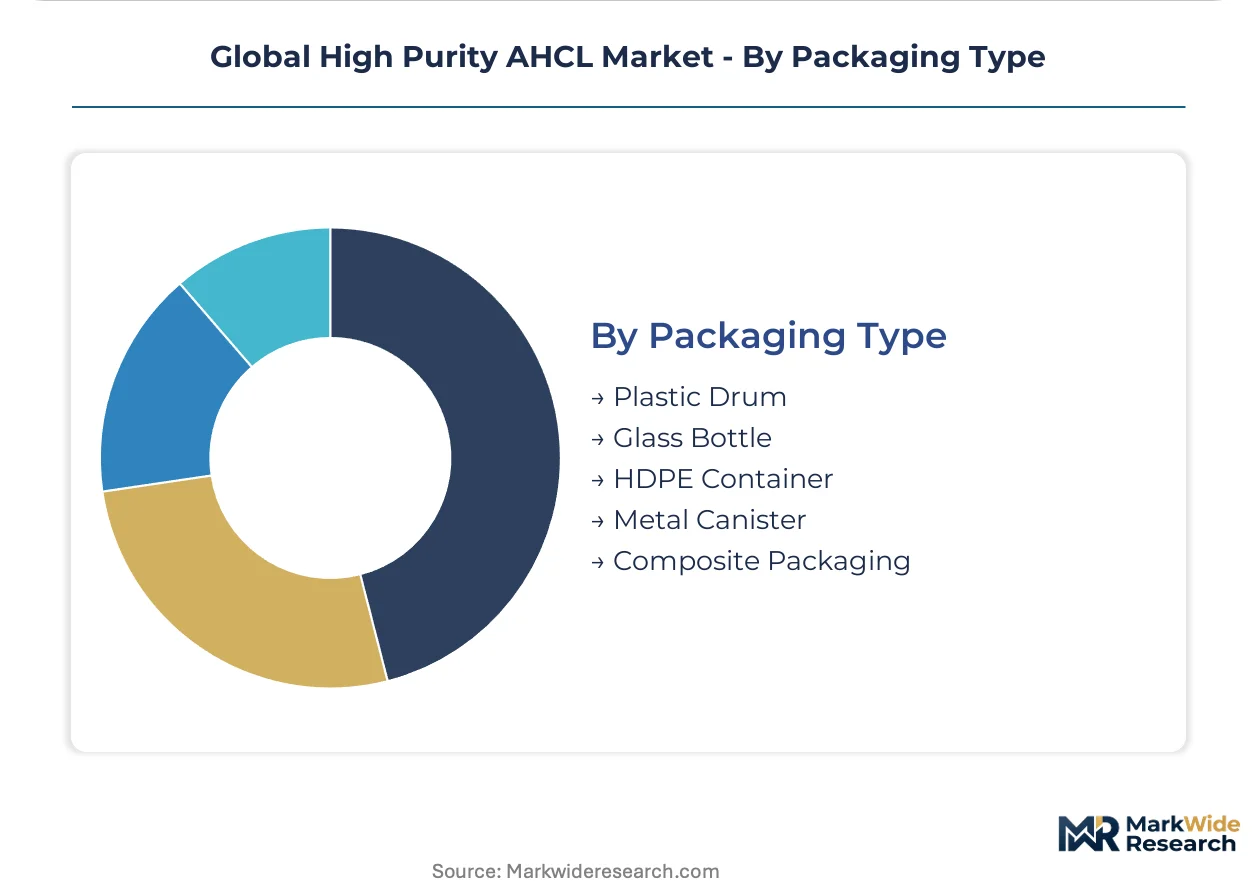
Packaging Type:
Volume scale and contamination risk dictate container selection, with EU F-Gas Regulation amendments complicating fluoropolymer-lined transport equipment.
- Metal Canister:High-pressure steel cylinders with specialized valve configurations serve semiconductor fabs requiring ultra-high-purity gas delivery. Linde plc and Air Liquide S.A. deploy global cylinder fleets with tracked chain-of-custody documentation.
- Composite Packaging:Multi-layer barrier systems combine polymer liners with structural reinforcement for electronic grade liquid shipment. REACH Annex XVII compliance on chlorinated substance emissions shapes material selection.
- Plastic Drum:HDPE and fluoropolymer-lined drums serve bulk chemical terminals across Texas and Arizona with EPA Risk Management Plan audit requirements.
- Glass Bottle:Amber and clear borosilicate containers protect light-sensitive analytical grade reagents.
- HDPE Container:Cost-effective packaging for reagent grade and water treatment applications with lower purity thresholds.
Metal canister absorbs the bulk of high-value shipments; composite packaging is expanding most quickly as membrane purification enables longer transport distances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chlor-alkali feedstock concentration along the US Gulf Coast and coastal China anchors global supply geography for hydrogen chloride precursors. Semiconductor fab clusters in East Asia and Europe drive demand localization for ultra-high-purity reagent delivery.
United States
Texas and Arizona host bulk chemical terminals retrofitting containment systems under EPA Risk Management Plan audit requirements. The EPA mandates third-party audits and enhanced leak detection for hydrogen chloride storage above threshold quantities. Phoenix-area fabs source metal canister deliveries through tracked chain-of-custody documentation.
China
Domestic specialty gas producers expand high-purity anhydrous hydrogen chloride capacity to serve semiconductor self-sufficiency targets under MIIT industrial policy. The country's national environmental regulator enforces dual carbon goals that shape chlor-alkali facility emissions profiles. Yangtze River Delta foundries pilot membrane-based secondary purification systems for real-time quality assurance.
South Korea
Gyeonggi cluster foundries now require ultra-high-purity AHCL for EUV lithography processes at nodes below seven nanometers. MFDS-aligned purity benchmarks govern import certification for electronic-grade reagents. Seoul Capital Area memory producers centralize global category management through enterprise-wide master service agreements.
Germany
Air Liquide S.A. sustains on-site purification systems at major European chip foundries serving automotive and industrial semiconductor demand. REACH Annex XVII restrictions on chlorinated substance emissions accelerate replacement of lower-purity alternatives with certified electronic-grade reagents. Dresden and Munich fabs anchor continental demand for sub-ppm specification material.
Japan
METI enforces JIS K 8180 purity benchmarks that effectively block uncertified imports from serving the domestic electronics base. Showa Denko K.K. and Central Glass Co., Ltd. occupy positions within the certified supplier tier for domestic fab procurement. Kyushu and Kanto region semiconductor manufacturers demand six-month supplier validation cycles for new purification sources.
Global High Purity AHCL Market Competitive Landscape
Global majors compete with regional champions across purification technology and on-site service capability. The vendor base clusters around integrated gas suppliers with captive chlor-alkali feedstock access and fractional distillation specialists. Three archetypes dominate: multinational industrial gas conglomerates with global cylinder fleets, regional chemical producers with backward integration into chlor-alkali operations, and specialized electronic material suppliers with fab-proximate purification infrastructure. Competitive moves concentrate on M&A for regional capacity absorption and strategic partnerships for closed-loop recycling systems at large fabs.
Within the integrated gas supplier tier, Linde plc and Air Liquide S.A. exemplify global network leverage for electronic-grade reagent delivery. BASF SE represents the backward-integrated chemical conglomerate archetype with captive chlor-alkali feedstock stability. Matheson Tri-Gas, Inc. occupies a position among North American specialists with fab-proximate service capability.
| Leading Market Players |
|---|
| Linde plc |
| Air Liquide S.A. |
| Air Products and Chemicals, Inc. |
| Matheson Tri-Gas, Inc. |
| BASF SE |
| Gas Innovations |
| Messer Group GmbH |
| Showa Denko K.K. |
| Central Glass Co., Ltd. |
| Others |
Supply & Pricing Matrix
Analytical chemist concentration in Germany's Ruhr Valley and Japan's Kansai corridor creates labor-cost differentials that widen pricing spreads between semiconductor-grade and reagent-grade tiers. European purification specialists command premium service-bundling rates that Asian contract manufacturers cannot match without cryogenic distillation capability investments.
Pricing Analysis
On-site generation service contracts bundle point-of-use purification hardware with per-kilogram chemical consumption fees, while spot-market cylinder deliveries remain unbundled and exposed to freight volatility. Three-tier pricing structure across semiconductor, electronic, and reagent grades separates fabs with six-month qualification timelines from laboratories with distributor-consolidated procurement. Cost compression in electronic-grade supply runs through Chinese TOPCon cell manufacturers demanding volume discounts for boron diffusion chemistry. Pharmaceutical producers show least price sensitivity due to FDA batch certification requirements that block uncertified substitutes.
Supply Chain Analysis
Regional distribution centers in Texas, Shanghai, and Antwerp maintain hub-and-spoke patterns for metal canister fleets with tracked chain-of-custody documentation. Hydrogen chloride precursor supply anchors in coastal China and the US Gulf Coast, drawing from chlor-alkali capacity clusters exposed to tariff friction and shipping disruption. Feedstock dependence on electrolytic chlorine and metallurgical-grade hydrogen creates single-source vulnerability when coastal logistics chokepoints congest. Distribution runs through integrated gas supplier networks with captive cylinder fleets rather than third-party chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualification timeline compression to six-month validation cycles is forcing sub-scale purification specialists into distressed asset sales, consolidating procurement authority at integrated gas conglomerates with documentation resources.
For Market Incumbents: Deploy closed-loop recycling systems at large fabs to lock in decade-long service contracts and displace virgin material competitors. BASF SE and Linde plc should extend backward integration into chlor-alkali feedstocks to neutralize coastal China supply disruption threats. Memory producers with multi-site footprints in South Korea and China are centralizing global category management, squeezing regional distributors without enterprise-wide master service agreements. For New Entrants and Emerging Players: Membrane-based secondary purification technology offers entry into Taiwan and Germany foundry pilot programs seeking real-time quality assurance without batch-wise laboratory verification. India's Semiconductor Mission under PLI scheme creates first-mover advantage for domestic purification infrastructure before volume commitments harden. Target compound semiconductor epitaxy applications for gallium nitride power electronics, where distinct dopant carrier impurity profiles reward specialist chemistry over commoditized silicon-grade supply. For Investors and Strategic Acquirers: Re-rating potential sits with fractional distillation specialists holding JIS K 8180 certification given Japan's METI import barriers that block uncertified competitors. Five-to-ten year viability favors assets with on-site generation capability at fab-proximate locations rather than centralized bulk terminals exposed to EPA Risk Management Plan audit burdens. Watch EU F-Gas Regulation amendment implementation as inflection indicator for fluoropolymer-lined transport equipment replacement costs that reshape supplier economics.| Strategic Initiative | Industry Significance |
|---|---|
| On-Site Purification Deployment | Air Liquide S.A. sustains European fab relationships through point-of-use systems at Dresden and Munich facilities. |
| Backward Integration into Chlor-Alkali | BASF SE secures raw material stability for reagent-grade output via captive electrolytic chlorine supply. |
| Membrane Technology Pilot Programs | Taiwan and Germany foundries test polymeric separation systems for autonomous moisture reduction downstream of distillation. |
| Closed-Loop Recycling Systems | Integrated gas suppliers reduce virgin material consumption while locking long-term service contracts at large fabs. |
| India Local Capacity Buildout | Domestic purification infrastructure under PLI scheme captures first-mover advantage before procurement commitments solidify. |
Research Methodology
Document review covered EPA Risk Management Plan filings, REACH Annex XVII regulatory updates, JIS K 8180 certification databases, and SEC 10-K disclosures from integrated gas suppliers, complemented by interviews with plant managers at chlor-alkali facilities, procurement leads at South Korean foundries, distribution channel partners in European electronic gas markets, and technical R&D directors at membrane separation technology developers. Bottom-up triangulation across cylinder fleet tracking data and top-down validation against customs trade statistics anchored volume estimates. Secondary sources included customs/trade data, Cefic chemical industry reports, and MFDS import certification records.
Historical capacity utilization rates were cross-referenced against expert panel input on qualification timeline compression and EUV lithography purity requirement escalation. The analytical framework modeled grade tier, end-use industry, packaging format, and regional production hub segmentation across the projection horizon. CAGRs were derived from installed capacity expansion announcements, fab construction pipelines, and substitution elasticity between purification technologies. Forecast inputs incorporated TOPCon cell architecture adoption curves and semiconductor node migration below three nanometers.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EPA hazardous air pollutant standard revisions or chlor-alkali feedstock disruption from coastal logistics congestion. Outputs reflect assumptions around membrane technology adoption rates and REACH enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
High-Value Chemicals
Ultra-High Purity Materials Market
High-Value Chemicals
High Molecular Ammonium Polyphosphate Market
High-Value Chemicals
Ultra-High Purity Hydrofluoric Acid Market
High-Value Chemicals
Phenanthroline Monohydrate Market
High-Value Chemicals
Ultra-High-Purity Anhydrous Hydrogen Chloride (Hcl) Gas Market
High-Value Chemicals
High Temperature Plastic Market
High-Value Chemicals
Global Hyaluronidase Market
High-Value Chemicals
Global High Purity Oxygen Market
High-Value Chemicals
Global High Temperature Thermoplastics (Htts) Market
High-Value Chemicals
High Friction Films Market
High-Value Chemicals
Hydroxyethyl Urea Market
High-Value Chemicals
Hydrogen Isotope Market
High-Value Chemicals
High Purity Aluminum Hydroxide Market
High-Value Chemicals
Diethylhydroxylamine (DEHA) Market
High-Value Chemicals
High Purity Silica Market
High-Value Chemicals
High-Nickel NCM Cathode Binder Latex Market