
 Battery Grade High Purity Lithium Fluoride Market | 2026-2036
Battery Grade High Purity Lithium Fluoride Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Grade High Purity Lithium Fluoride Market Insights
Aftermarket electrolyte formulation services is narrowing as cell manufacturers bring lithium fluoride blending in-house. Ganfeng Lithium Group leverages captive brine-to-fluoride refining to dominate upstream supply. American Elements anchors its position through rare earth co-production economics that lower lithium fluoride marginal costs. Crystran Ltd specializes in optical-grade fluoride crystal know-how that extends into battery-grade purification protocols.
Battery grade high purity lithium fluoride denotes lithium fluoride refined to impurity levels below 50 ppm total metallic content, typically produced via aqueous precipitation followed by multiple recrystallization stages under inert atmosphere; the material functions primarily as an electrolyte additive and solid-state electrolyte precursor in next-generation lithium-metal batteries. Powder formulations currently occupy the largest volume share among product types due to ease of dispersion in slurry-based cathode coating, while granule demand is accelerating for dry electrode manufacturing lines that eliminate solvent recovery steps. Energy storage applications lead absolute consumption among end-use segments, though electric vehicle qualification timelines are compressing as cell makers validate fluoride-enhanced electrolytes for silicon-anode cells.
FDA guidelines on battery materials for medical device power sources, China's GB standards for lithium salt purity, and the EU Battery Regulation's recycled content mandates collectively elevate testing burdens and certification costs for market entry. The analysis indicates that stakeholders must track evolving solid-state battery pilot timelines and corresponding fluoride purity specifications to align capacity investments with commercial offtake commitments.
Market Dynamics
Solid-state battery commercialization timelines are compressing qualification windows for ultra-high purity lithium fluoride, forcing upstream refiners to align capacity expansion with cell manufacturer pilot-to-scale transitions rather than spot market demand.
Growth Catalysts
- EU Battery Regulation recycled content mandates:Purity thresholds for imported cathode materials are tightening, elevating demand for certified high-purity lithium fluoride as electrolyte additive in silicon-anode formulations.
- China's dual carbon goals:Provincial governments in Jiangsu and Sichuan are incentivizing integrated lithium salt-to-battery cell corridors that internalize fluoride refining capacity.
- Dry electrode manufacturing:Elimination of solvent recovery steps in next-generation cell production lines is accelerating granule-form lithium fluoride qualification for direct powder coating.
Market Restraints
- Spodumene concentrate supply concentration:Hard rock lithium feedstock dependency on Australian and Canadian mining operations creates input cost volatility for fluoride refiners without captive brine assets.
- Technical limitation in moisture sensitivity:Lithium fluoride's hygroscopic properties necessitate inert-atmosphere handling infrastructure that elevates capital intensity for new market entrants.
- Substitution threat from lithium bis(fluorosulfonyl)imide:Advanced lithium salts for liquid electrolyte formulations are displacing fluoride additives in certain high-voltage cathode systems.
Strategic Opportunities
- Medical device power sources:FDA guidelines on implantable battery materials are creating premium certification tiers for ultra-high purity fluoride that command price differentiation.
- Solid-state electrolyte precursor convergence:Integration of lithium fluoride with argyrodite and garnet ceramic electrolyte chemistries is opening technical partnerships with solid-state cell developers.
- Aftermarket service unbundling:Independent electrolyte formulation laboratories in South Korea and Japan are emerging as alternative channels for specialty fluoride procurement outside integrated cell manufacturers.
Industry Challenges
- Recrystallization expertise scarcity:Battery-grade purification protocols require optical-grade crystal growth know-how concentrated in legacy optical materials specialists, constraining talent availability for capacity expansion.
- Multi-jurisdiction certification timelines:Concurrent GB standard testing in China, REACH registration in Europe, and EPA hazard classification in the US extend market entry cycles by 18-24 months for new suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Grade High Purity Lithium Fluoride Market |
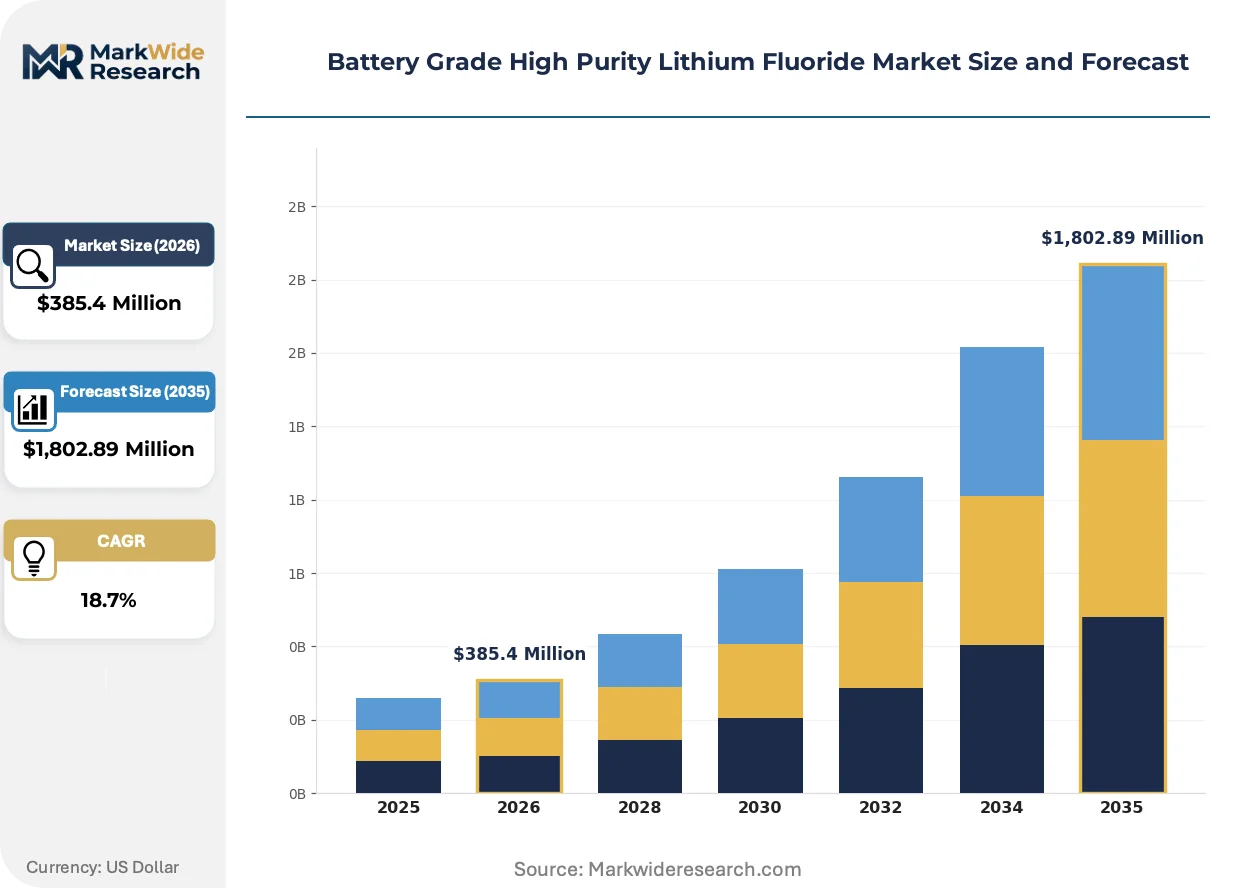
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,802.89 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Blends, Crystals End User: Battery Manufacturers, Electronics, Aerospace, Automotive Application: Energy Storage, Electric Vehicles, Consumer Electronics, Industrial Uses Delivery Mode: Direct Supply, Distributor Supply, Online Sales, Retail |
| Companies Covered | Ganfeng Lithium Group, Leverton, Axiom Chemicals, American Elements, Crystran Ltd, FMC, Huizhi Lithium Energy, Baiyin Zhongtian Co Ltd, Tinci Materials Technology Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Grade High Purity Lithium Fluoride Market Trends and Innovations
Synthetic route innovation and process analytical technology adoption are compressing impurity detection limits while expanding the addressable purity grades for next-generation battery chemistries beyond current specifications.
Computational materials screening for solid-state electrolyte formulations is virtualizing traditional Edisonian experimentation cycles. Cell manufacturers at the pilot scale are adopting machine-learning-guided compositional mapping to identify optimal lithium fluoride loading in composite electrolytes. This approach is virtualizing the historical dependency on physical sample iteration, compressing qualification timelines from years to months for novel fluoride-enhanced chemistries.
China's GB standards for lithium salt purity are harmonizing with EU Battery Regulation testing protocols through mutual recognition agreements under WTO technical barriers frameworks. This regulatory convergence reduces redundant certification burdens for multi-market suppliers. Battery-grade fluoride exporters to both jurisdictions are consolidating testing laboratories to capture efficiency gains from unified analytical methods.
Cell manufacturers are internalizing electrolyte additive blending operations that were historically outsourced to specialty chemical distributors. This backward integration trend concentrates procurement leverage among tier-one battery producers with sufficient volume to justify captive formulation capacity. The shift is most visible in China's Yangtze River Delta manufacturing clusters where integrated cathode-electrolyte production lines are eliminating intermediate handling steps.
Battery Grade High Purity Lithium Fluoride Market Segmentation
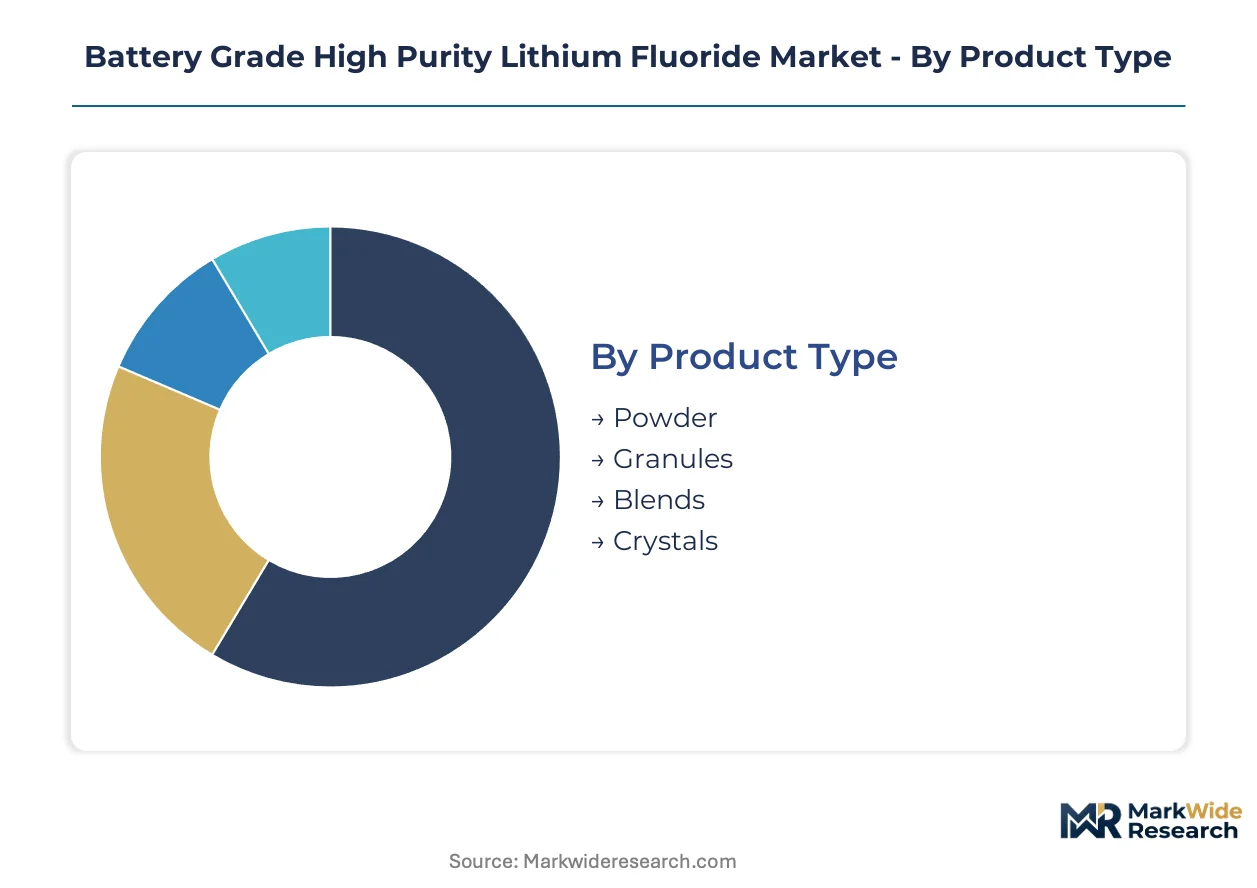
Segmentation in battery-grade lithium fluoride tracks how physical form factors, customer integration depth, and application-specific purity thresholds create divergent procurement patterns across the value chain. Each dimension carries distinct handling protocols and certification requirements that shape supplier-customer relationships.
Product Type:
Powder formulations command established positions in cathode coating workflows, while granule formats are accelerating for solvent-free electrode manufacturing.
- Powder:Fine particulate lithium fluoride below 10 microns enables uniform dispersion in slurry-based cathode coating processes. Jiangsu province battery cell corridors are standardizing powder specifications for silicon-anode electrolyte enhancement, with dry-room handling infrastructure now mandatory for qualification.
- Granules:Spherical agglomerated particles between 100-500 microns eliminate dust exposure and enable direct dry powder coating without solvent recovery systems. Sichuan province integrated production lines are validating granule feedstock for next-generation solid-state cell manufacturing, compressing processing steps and capital intensity.
- Blends:Pre-mixed lithium fluoride compositions with lithium bis(fluorosulfonyl)imide or other salts reduce formulation variability for mid-tier battery producers lacking captive blending capacity.
- Crystals:Optical-grade crystal growth protocols extend into battery-grade purification, serving ultra-high purity requirements for medical device power sources under FDA guidelines.
Powder retains volume leadership; granules hold the steepest expansion curve.
End User:
Customer integration depth spans from fully captive refining operations to specialized component procurement, with regulatory proximity determining certification tier requirements.
- Battery Manufacturers:Tier-one cell producers in China's Yangtze River Delta are internalizing lithium fluoride blending operations that specialty chemical distributors historically managed. This backward integration concentrates procurement leverage among volume-scale producers with sufficient throughput to justify captive formulation infrastructure and inert-atmosphere handling systems.
- Electronics:Consumer device battery suppliers prioritize consistent impurity profiles below 50 ppm total metallic content for compact cell geometries where electrolyte stability directly impacts cycle life.
- Aerospace:Satellite and aviation power systems demand extended thermal cycling performance, driving qualification of ultra-high purity fluoride grades with specialized moisture sensitivity protocols.
- Automotive:Electric vehicle battery producers are compressing qualification timelines for fluoride-enhanced electrolytes as silicon-anode cell designs advance toward commercial scale.
Battery manufacturers dominate procurement volume; aerospace commands the highest purity premiums.
Application:
End-use performance requirements stratify across grid-scale durability demands, vehicle qualification timelines, and portable device miniaturization pressures.
- Energy Storage:Grid-scale battery installations prioritize cost-optimized purity grades with proven 20-year degradation profiles, with procurement concentrating among utility-scale project developers in China and the US.
- Electric Vehicles:Silicon-anode cell validation is accelerating fluoride loading optimization through machine-learning-guided compositional mapping, compressing traditional Edisonian experimentation from years to months.
- Consumer Electronics:Smartphone and laptop battery suppliers balance energy density targets against thermal runaway prevention, specifying mid-tier purity grades with established supply continuity.
- Industrial Uses:Specialty chemical and metallurgical applications outside battery markets absorb lower-purity fluoride production, providing demand floor stability during battery-grade capacity ramp cycles.
Energy storage leads absolute consumption; electric vehicles are climbing the fastest.
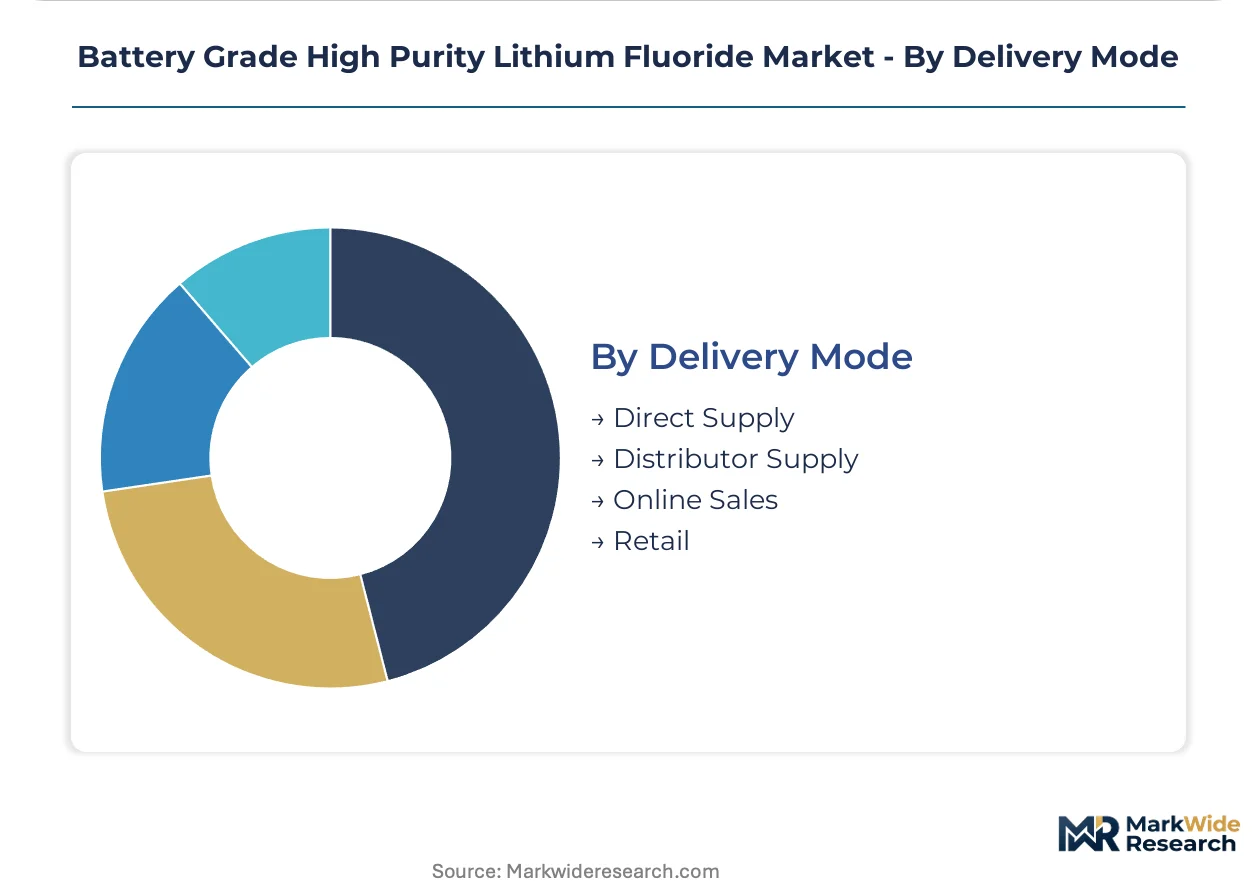
Delivery Mode:
Channel structure reflects customer scale concentration, with direct relationships dominating volume flows and distributor networks serving fragmented specialty demand.
- Direct Supply:Long-term offtake agreements link Ganfeng Lithium Group and similar integrated refiners directly with tier-one battery producers, aligning capacity expansion with pilot-to-scale transition timelines rather than spot market volatility.
- Distributor Supply:Regional chemical distributors maintain inventory positions for mid-tier battery manufacturers and electronics suppliers lacking volume scale for direct refiner relationships.
- Online Sales:E-commerce platforms serve research institutions and pilot-scale cell developers requiring rapid procurement of small-batch specialty grades without contractual overhead.
- Retail:Limited to laboratory supply houses and educational institutions, representing minimal commercial significance for battery-grade material flows.
Direct supply captures the dominant share; online sales are expanding most quickly for specialty batch procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China's integrated battery corridors exhibit the lowest price elasticity due to captive refining economics, while European importers face steep certification premiums that compress margin tolerance for spot procurement.
China
Jiangsu and Sichuan provinces anchor domestic consumption through lithium salt-to-cell corridors that internalize fluoride refining capacity. GB standards for lithium salt purity are tightening under dual carbon goals, elevating testing burdens for imported materials. Ganfeng Lithium Group leverages captive brine assets in these corridors to dominate upstream supply.
United States
Silicon-anode cell developers in the Midwest and Southeast are compressing qualification timelines for fluoride-enhanced electrolytes. EPA hazard classification requirements extend market entry cycles for new suppliers by 18-24 months. American Elements anchors its position through rare earth co-production economics that lower marginal costs.
Germany
Automotive cell producers in Bavaria and Baden-Württemberg are validating solid-state electrolyte precursors under EU Battery Regulation recycled content mandates. REACH registration requirements create certification tiers that favor established suppliers with multi-jurisdiction testing infrastructure. Industrial clusters around Stuttgart and Munich concentrate pilot-to-scale transition timelines.
Japan
Machine-learning-guided compositional mapping in Kansai and Chubu regions is virtualizing traditional Edisonian experimentation for fluoride loading optimization. METI standards for next-generation battery materials are harmonizing with EU testing protocols through mutual recognition agreements. Osaka-based independent electrolyte formulation laboratories are emerging as alternative procurement channels.
South Korea
Battery manufacturers in the Seoul Capital Area are internalizing additive blending operations that specialty chemical distributors historically managed. MFDS guidelines on implantable battery materials are creating premium certification tiers for ultra-high purity fluoride. Busan-Ulsan industrial complexes concentrate backward integration into captive formulation capacity.
Battery Grade High Purity Lithium Fluoride Market Competitive Landscape
Capability concentration sits with optical-grade crystal specialists; scale advantage sits with integrated lithium majors with captive brine assets. The vendor base stratifies across three tiers: upstream refiners with feedstock control, midstream blenders serving fragmented specialty demand, and downstream cell manufacturers internalizing formulation. Dominant competitive moves include backward integration into captive refining capacity and strategic partnerships with solid-state cell developers for electrolyte precursor convergence.
Among integrated lithium majors, Ganfeng Lithium Group and Huizhi Lithium Energy exemplify the upstream tier with brine-to-fluoride refining economics. Crystran Ltd occupies a position within the capability-concentrated specialist tier, representing optical-grade crystal know-how that extends into battery-grade purification protocols.
| Leading Market Players |
|---|
| Ganfeng Lithium Group |
| Leverton |
| Axiom Chemicals |
| American Elements |
| Crystran Ltd |
| FMC |
| Huizhi Lithium Energy |
| Baiyin Zhongtian Co Ltd |
| Tinci Materials Technology Co., Ltd |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Sichuan province's integrated lithium salt-to-cell corridors is compressing spot availability and amplifying pricing leverage for captive refiners with brine assets. This utilization squeeze forces non-integrated buyers toward long-term offtake commitments or premium-certified imports, reshaping procurement economics across battery-grade fluoride tiers.
Pricing Analysis
Long-term offtake agreements dominate volume flows between integrated refiners and tier-one battery producers, while spot procurement serves only fragmented specialty demand. Three-tier pricing structure across premium, standard, and economy levels separates FDA-certified medical-grade fluoride from automotive-qualified and industrial-absorption tiers. Cost compression in standard-grade powder is intensifying because Jiangsu corridor manufacturers are internalizing blending operations. Research institutions and pilot-scale developers exhibit highest price sensitivity; aerospace satellite power systems show lowest elasticity due to qualification rigidity.
Supply Chain Analysis
Upstream spodumene concentrate dependency centers on Australian and Canadian hard rock mining operations, with Chilean and Argentine brine assets providing alternative lithium carbonate feedstock. Battery-grade fluoride production draws from lithium salt precursors, hydrofluoric acid, and inert-atmosphere handling infrastructure. Single-source vulnerability in optical-grade crystal growth expertise—concentrated among legacy materials specialists—constrains capacity expansion timelines. Distribution runs through direct refiner-to-manufacturer channels for volume buyers, with regional chemical distributors serving mid-tier electronics and research accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting around solid-state electrolyte precursor convergence, where interoperability between lithium fluoride and argyrodite or garnet ceramic chemistries is consolidating technical partnership structures.
For Market Incumbents: Harden captive brine-to-fluoride refining positions through capacity additions in Jiangsu and Sichuan corridors before EU Battery Regulation recycled content mandates tighten import competition. Invest in optical-grade crystal growth talent acquisition to defend against recrystallization expertise scarcity that threatens expansion timelines. Secure multi-jurisdiction certification infrastructure across GB standards, REACH, and EPA classifications to extend qualification lead times for challengers.
For New Entrants and Emerging Players: Pursue aftermarket service unbundling in South Korea and Japan, where independent electrolyte formulation laboratories are emerging as alternative procurement channels outside integrated cell manufacturers. Target medical device power source certification tiers under FDA guidelines, where ultra-high purity fluoride commands sustainable price premiums and incumbent concentration remains lowest. Establish rapid small-batch supply relationships through e-commerce platforms serving research institutions before scaling to direct manufacturer offtake negotiations.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across solid-state electrolyte precursor manufacturing, where inert-atmosphere infrastructure requirements and multi-jurisdiction certification burdens favor scaled incumbents with existing compliance architectures. Acquisition targets should emphasize optical-grade crystal specialists with extensible battery-grade purification protocols and established rare earth co-production economics. Watch solid-state battery pilot-to-scale transition timelines as the critical signal for fluoride purity specification inflection and corresponding capacity investment windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brine Assets | Ganfeng Lithium Group leverages captive feedstock to dominate upstream fluoride supply economics. |
| Multi-Jurisdiction Certification Infrastructure | Consolidated testing across GB standards, REACH, and EPA protocols reduces market entry cycles for exporters. |
| Optical-Grade Crystal Growth Capability Acquisition | Crystran Ltd's legacy expertise extends into battery-grade purification protocols for ultra-high purity tiers. |
| Solid-State Electrolyte Precursor Partnerships | Technical collaboration with argyrodite and garnet ceramic developers locks in future offtake commitments. |
| Dry Electrode Manufacturing Line Qualification | Granule-form lithium fluoride validation eliminates solvent recovery steps in Sichuan province production corridors. |
Research Methodology
Cross-validation between primary interviews with lithium refinery plant managers, battery cell procurement leads, solid-state electrolyte R&D directors, and medical device power source engineers anchors the qualitative findings. Secondary validation draws from customs and trade data, SEC filings of integrated lithium majors, GB standard documentation, and EU Battery Regulation impact assessments. Bottom-up triangulation across product-grade volume flows and top-down calibration against end-use consumption patterns ensures segmentation integrity.
Calibration against pilot-to-scale transition timelines and solid-state battery commercialization roadmaps shapes the analytical framework across the analysis window. Segmentation dimensions span physical form factor, end-user integration depth, application-specific purity threshold, and regional regulatory cluster. CAGRs derive from capacity expansion announcements correlated with qualification timeline compression signals. Forecast inputs include silicon-anode cell validation progress and dry electrode manufacturing adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by mid-tier battery manufacturers or accelerated solid-state commercialization by automotive OEMs would shift outcomes. Cross-checking against solid-state battery pilot production announcements and corresponding fluoride purity specification disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
High-Value Chemicals
Sodium Hexametaphosphate Market
High-Value Chemicals
Global High Temperature Thermoplastics (Htts) Market
High-Value Chemicals
High Performance Fluoropolymers Market
High-Value Chemicals
Ultra-High Purity Hydrofluoric Acid Market
High-Value Chemicals
High Purity Silica Market
High-Value Chemicals
High-Nickel NCM Cathode Binder Latex Market
High-Value Chemicals
High-Purity Boehmite Market
High-Value Chemicals
Diethylhydroxylamine (DEHA) Market
High-Value Chemicals
Hydroxyethyl Urea Market
High-Value Chemicals
High Molecular Ammonium Polyphosphate Market
High-Value Chemicals
High Purity Lignin Market
High-Value Chemicals
High-K Dielectric Material Market
High-Value Chemicals
Potassium Hydroxide Market
High-Value Chemicals
Global High Purity Oxygen Market
High-Value Chemicals
Global Hydrofluoric Acid Market
High-Value Chemicals
Hydroxocobalamin Chloride Market