
 Mono Methyl Ether of Hydroquinone (MEHQ) Market | 2026-2036
Mono Methyl Ether of Hydroquinone (MEHQ) Market Size, Share, and Industry Trends Forecast 2026-2036
Mono Methyl Ether of Hydroquinone (MEHQ) Market Analytics
Buyer concentration among monomer producers is shifting as acrylic acid and methacrylate manufacturers consolidate procurement around fewer, larger MEHQ suppliers. Eastman Chemical Company leverages its integrated phenol derivative chain to sustain cost-competitive industrial-grade supply. Mitsubishi Gas Chemical Company anchors Northeast Asian availability through captive hydroquinone feedstock. Solvay S.A. differentiates via pharmaceutical-grade certification and European regulatory compliance depth.
Mono methyl ether of hydroquinone (MEHQ) is an organic compound with the formula C7H8O2, synthesized through methylation of hydroquinone using dimethyl sulfate or methyl halides, and functions primarily as a polymerization inhibitor and antioxidant in unsaturated monomers. Industrial-grade MEHQ dominates volume flows into plastics and coatings applications where cost efficiency outweighs purity premiums. Pharmaceutical-grade material commands tighter margin pools despite smaller tonnage, driven by API stabilization and antioxidant demand from drug manufacturers. Research-grade supply remains fragmented across specialty distributors serving academic and contract research institutions.
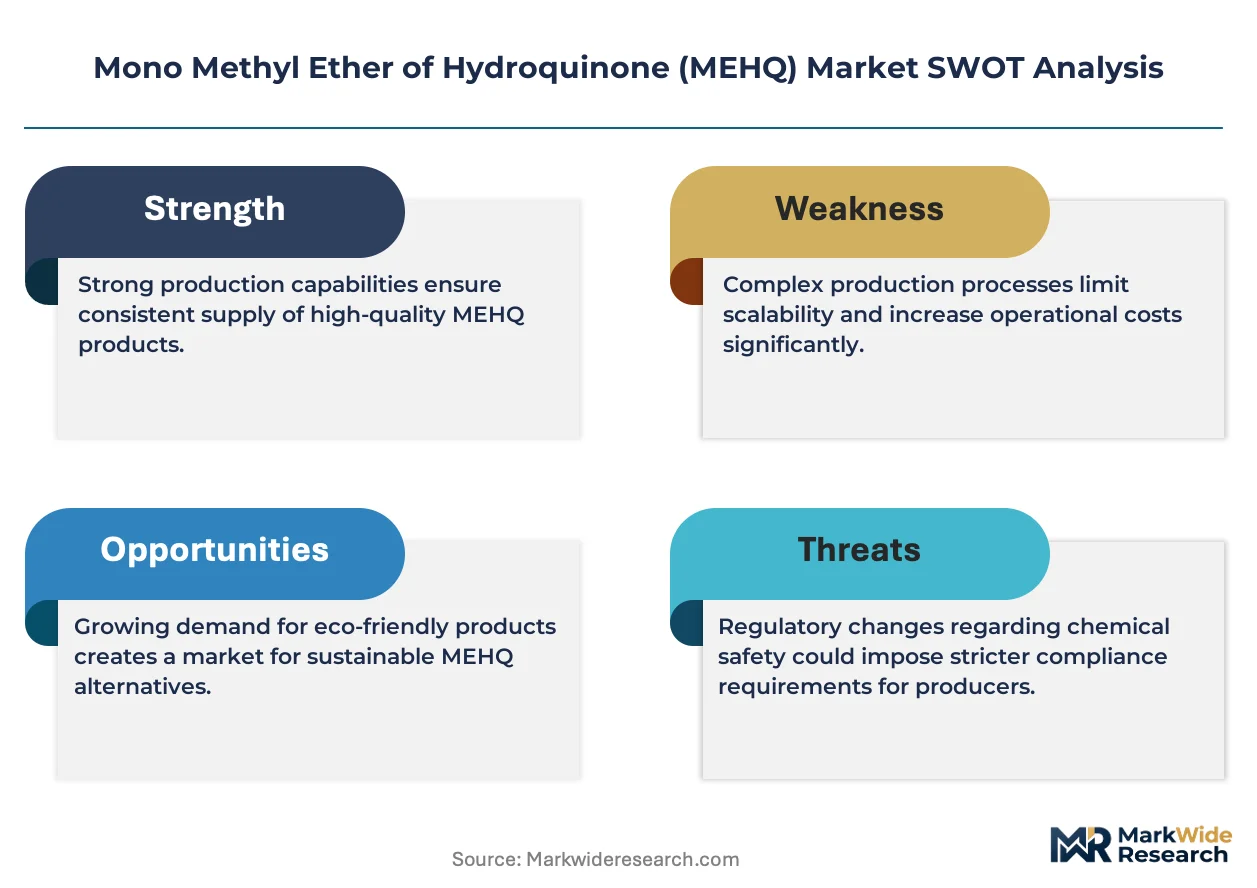
EPA oversight under the Toxic Substances Control Act shapes US market access requirements for industrial-grade importers, while REACH registration mandates in Europe enforce full supply-chain substance documentation. China's MEE enforces emission controls on methylation processes that affect Jiangsu province production economics. Stakeholders must monitor evolving pharmaceutical-grade pharmacopeia standards and regional carbon-intensity regulations that could reroute manufacturing investment toward lower-emission process technologies.
Market Dynamics
Acrylic acid and methacrylate monomer producers are consolidating procurement around fewer MEHQ suppliers, compressing vendor margins while rewarding integrated phenol derivative chains with captive hydroquinone feedstock.
Growth Catalysts
- REACH registration mandates:European chemical compliance documentation requirements are filtering out non-compliant traders and directing volume toward certified manufacturers with full substance dossiers.
- Jiangsu province chemical clusters:China's concentrated acrylic acid production base generates localized MEHQ demand that reduces logistics costs for regional suppliers.
- Dual carbon goals:China's emission intensity targets are accelerating methylation process upgrades that lower unit carbon footprints for compliant producers.
Market Restraints
- Hydroquinone feedstock volatility:Phenol derivative pricing fluctuations transmit directly to MEHQ production economics, squeezing margin buffers for non-integrated manufacturers.
- East Asian supply concentration:Captive production by Japanese and Korean chemical conglomerates limits third-party spot availability during demand spikes.
- Substitution by phenothiazine:Alternative polymerization inhibitors are capturing share in specific vinyl monomer applications where color stability requirements are less stringent.
Strategic Opportunities
- Pharmaceutical-grade pharmacopeia expansion:API stabilization applications in oncology and biologic drug manufacturing offer margin premiums above industrial-grade commoditization.
- EPA toxic substance control alignment:US importers with pre-manufacture notification compliance can capture volume from suppliers lacking TSCA Section 5 certification.
- Carbon-intensity labeling:Low-emission methylation process certification is creating product differentiation for European buyers under EU Green Deal procurement guidelines.
Industry Challenges
- Process safety engineering talent:Dimethyl sulfate handling expertise is scarce in emerging production locations, extending commissioning timelines for new methylation capacity.
- Pharmaceutical-grade validation cycles:ICH Q7 compliance documentation for API-grade material requires 18-24 month qualification periods that delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mono Methyl Ether of Hydroquinone (MEHQ) Market |
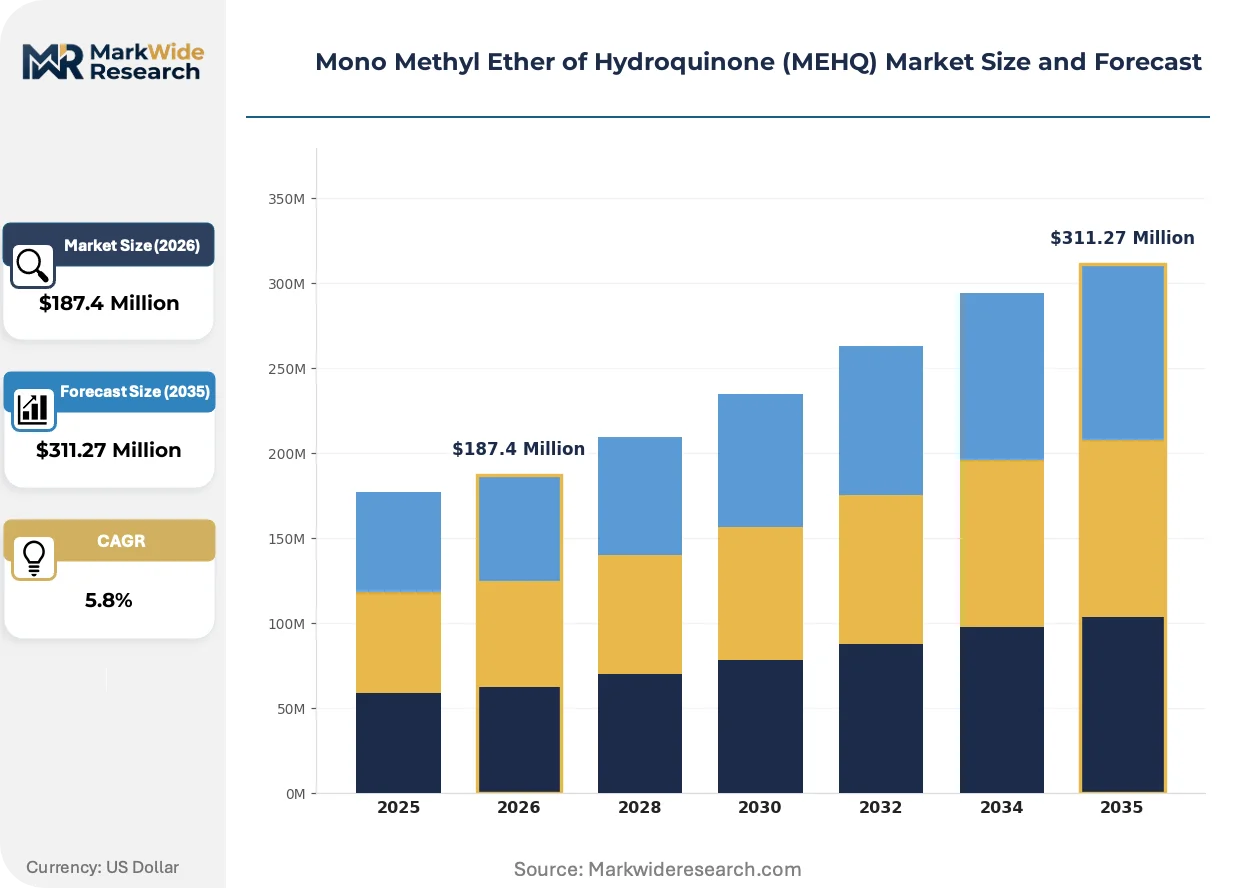
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Cosmetic Grade, Pharmaceutical Grade, Research Grade Application: Plastics, Paints, Coatings, Inks End User: Pharmaceuticals, Cosmetics, Chemical Manufacturing, Research Laboratories Packaging Type: Drums, Bottles, Cans, Bulk Containers |
| Companies Covered | Tokyo Chemical Industry Co., Ltd., Mitsubishi Gas Chemical Company, Eastman Chemical Company, Xiangshui Henryda Tech Chemical Co., Ltd., Jiangsu Evergreen Chemical Industry Co., Ltd., Solvay S.A., Camlin Fine Sciences, Arkema S.A., TCI Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mono Methyl Ether of Hydroquinone (MEHQ) Market Evolving Landscape
Continuous flow methylation reactor designs are displacing batch processes, unifying reaction efficiency with emission control compliance across Asian and European production bases.
Membrane separation technology for MEHQ purification is unifying pharmaceutical-grade yield improvements with reduced solvent waste generation. Acrylic acid producers in China's Shandong province are adopting these systems fastest, compressing the cost gap between industrial and pharmaceutical grades. The structural consequence is tier compression in pricing, as purification economics improve for mid-scale manufacturers.
REACH authorization list expansion for hydroquinone derivatives is tightening substance volume tracking requirements across European coatings supply chains. Downstream formulators must now document MEHQ incorporation rates in UV-curable resin systems. German and French automotive coatings producers are responding by pre-qualifying suppliers with complete SCIP database entries.
Long-term offtake contracting is displacing spot purchasing among vinyl ester resin manufacturers, compressing price volatility exposure for buyers while locking in volume commitments for suppliers. North American wind blade composite producers are driving this shift, seeking supply security for multi-year turbine installation projects. The pattern is most visible in US Gulf Coast procurement offices, where three-year contracts now dominate annual negotiations.
Mono Methyl Ether of Hydroquinone (MEHQ) Market Segmentation
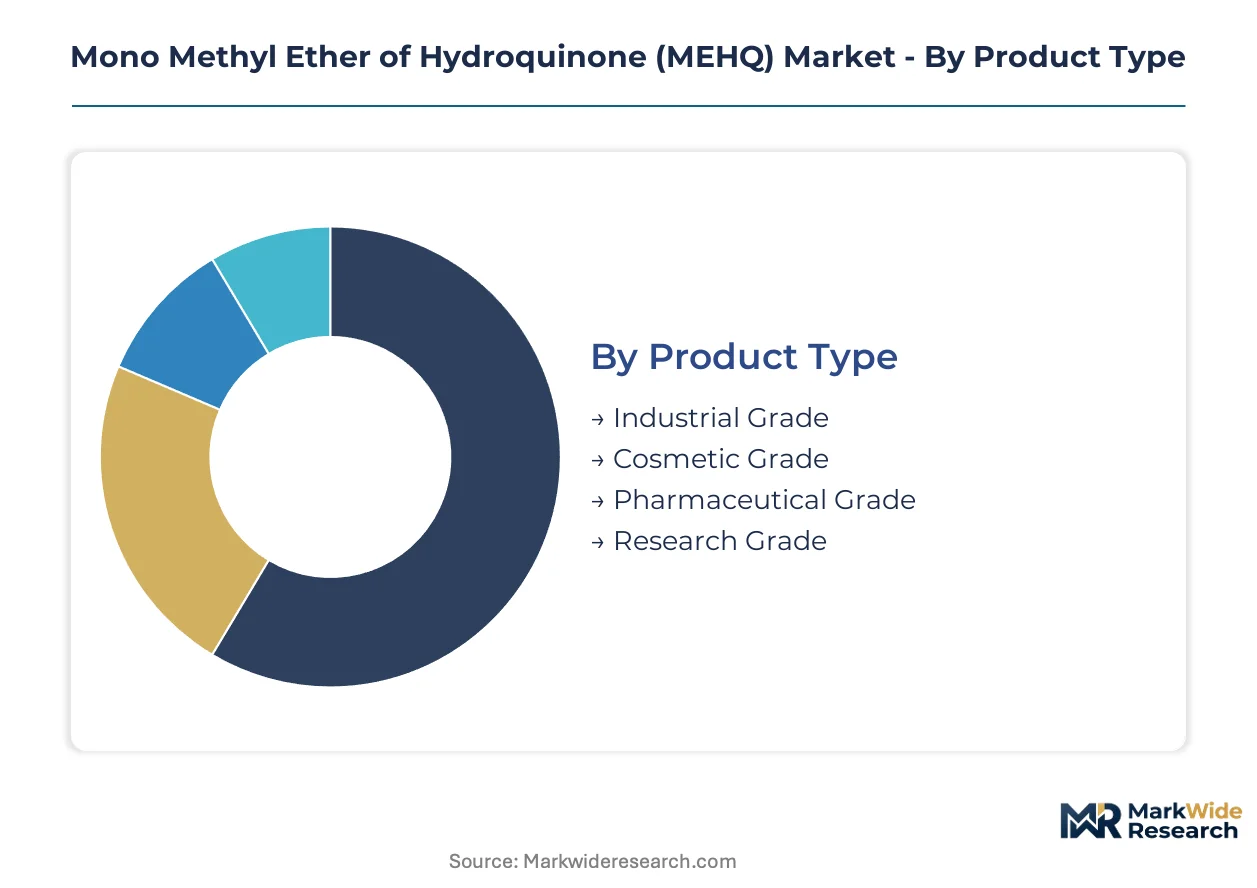
MEHQ segmentation reflects a bifurcation between certification-heavy grades serving regulated industries and commodity flows into bulk chemical applications. Purity specifications, packaging requirements, and end-use compliance burdens create distinct margin pools that reward specialized supply chain positioning.
Product Type:
Certification burden escalates sharply across this hierarchy, with pharmaceutical-grade material requiring ICH Q7 compliance and FDA/EMA facility inspections while industrial-grade operates under standard chemical handling protocols.
- Industrial Grade:Specifications typically specify 99.0-99.5% purity with controlled moisture content below 0.5%. Acrylic acid and methacrylate monomer producers in China's Jiangsu province absorb the majority of volume, driven by polymerization inhibitor demand in vinyl ester manufacturing.
- Pharmaceutical Grade:USP/EP-compliant material with 99.9%+ purity, residual solvent limits, and full batch traceability. API stabilization applications in oncology drug manufacturing concentrate demand in Basel, Switzerland and Cambridge, Massachusetts biotech clusters.
- Cosmetic Grade:Meets EC 1223/2009 cosmetic safety requirements with heavy metal and microbial specifications. Demand concentrates in French and Italian personal care formulation centers serving prestige skincare brands.
- Research Grade:Variable purity tiers for analytical and synthetic chemistry applications. Academic institutions and contract research organizations in Heidelberg, Germany and Boston, Massachusetts represent primary procurement channels.
Industrial grade sits at the top of the volume ranking, with pharmaceutical grade climbing the fastest.
Application:
Cost tier differentiation separates high-performance coatings formulations from bulk plastics compounding, with technical specifications determining substitution elasticity.
- Plastics:Unsaturated polyester resin stabilization in wind blade composites and automotive body panels. North American turbine manufacturers specify MEHQ loading rates in vinyl ester systems for carbon fiber adhesion.
- Coatings:UV-curable acrylate systems for automotive refinish and industrial maintenance applications. German automotive OEMs mandate SCIP database documentation for MEHQ incorporation in clearcoat formulations under REACH Article 33.
- Paints:Architectural alkyd and acrylic emulsion preservation. Water-based systems in Southeast Asian construction markets drive drum-scale procurement from regional distributors.
- Inks:Flexographic and gravure publication ink antioxidant protection. Japanese packaging printers specify low-color-forming grades for food-contact substrate applications.
Coatings command the highest per-kilogram pricing, with plastics generating the largest absolute tonnage.
End User:
Customer type determines contracting structure, with pharmaceutical and cosmetic buyers insisting on audit rights and chemical manufacturing customers favoring spot or annual frame agreements.
- Chemical Manufacturing:Acrylic acid, methacrylate, and vinyl ester resin producers represent the dominant consumption base. Integrated phenol derivative manufacturers leverage captive hydroquinone feedstock to defend margin position against merchant suppliers.
- Pharmaceuticals:API manufacturers and drug product formulators require DMF-supported supply with validated stability data. Oncology and biologic drug developers in Basel and Boston drive specification tightening for antioxidant applications.
- Cosmetics:European personal care formulators in Paris and Milan source cosmetic-grade material for premium skincare antioxidant systems. Clean beauty positioning is accelerating natural alternative substitution in mass-market segments.
- Research Laboratories:Academic and government research institutions purchase through specialty chemical distributors. Fragmented demand across thousands of small-scale users limits supplier direct engagement economics.
Chemical manufacturing sits at the top of the volume ranking, with pharmaceuticals climbing the fastest.
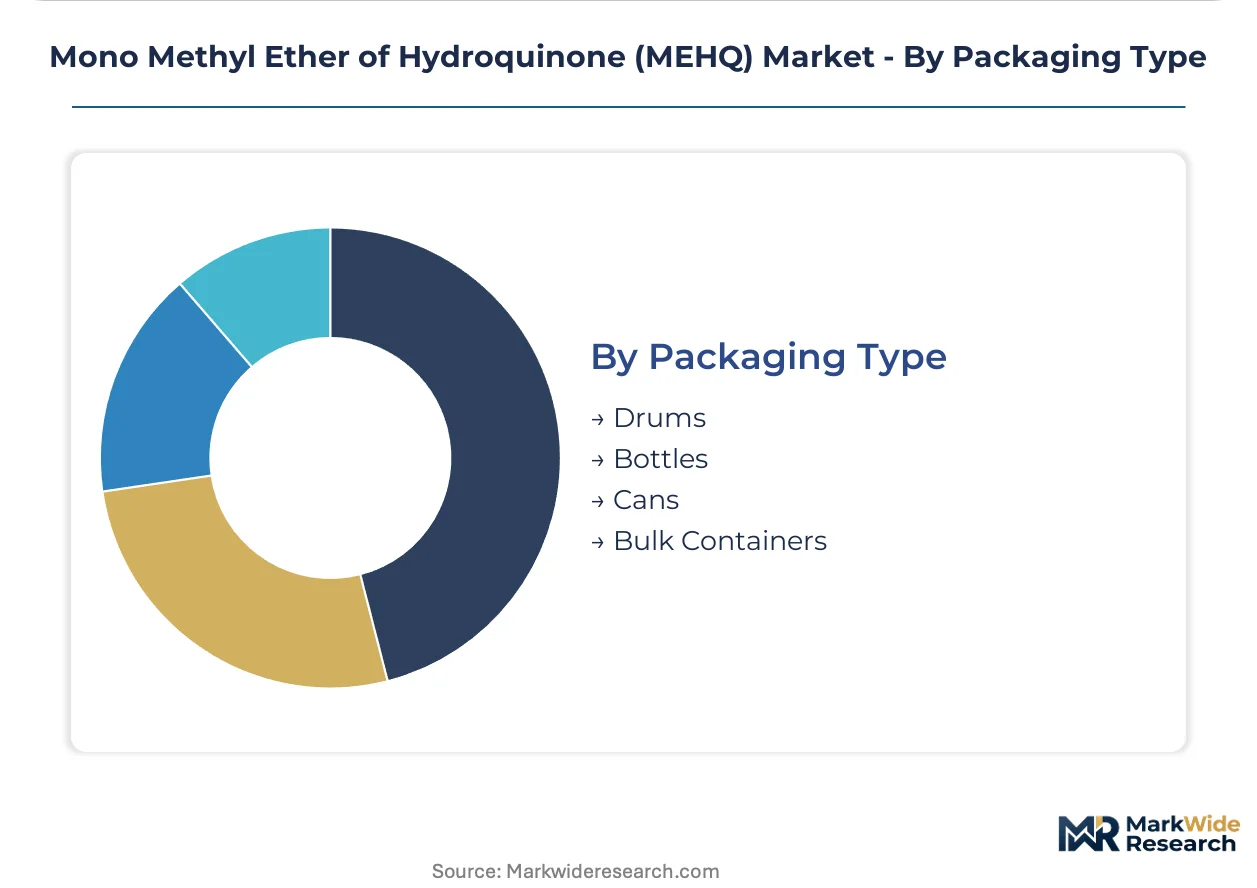
Packaging Type:
Supply concentration in methylation capacity shapes packaging economics, with bulk container flows tied to coastal chemical cluster proximity and drum shipments serving inland formulators.
- Bulk Containers:ISO tank and flexitank deliveries for acrylic acid producers with dedicated unloading infrastructure. Rotterdam and Houston port terminals handle transatlantic flows for vinyl ester resin manufacturers.
- Drums:200-liter steel and HDPE containers for mid-scale coatings formulators. Shandong province paint producers in China represent the densest regional demand cluster for drum-scale procurement.
- Bottles:Laboratory-scale packaging for research grade and pharmaceutical sampling. Amber glass specifications predominate for light-sensitive material protection.
- Cans:Small-format metal packaging for specialty ink and adhesive applications. Japanese printing chemical distributors favor 20-liter can configurations for just-in-time delivery.
Bulk containers sit at the top of the volume ranking, with bottles climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs substantially more MEHQ tonnage than the United States, yet German pharmaceutical-grade specifications command the highest per-kilogram premiums across all markets.
China
Jiangsu and Shandong province chemical clusters drive acrylic acid and vinyl ester resin demand for wind blade composites. MEE emission controls on methylation processes tighten compliance costs for producers near the Yangtze River Delta. Xiangshui county hosts multiple hydroquinone derivative manufacturers serving captive monomer production.
United States
Acrylic acid producers along the Gulf Coast consolidate procurement through long-term offtake contracts. EPA TSCA Section 5 pre-manufacture notification requirements filter import access for industrial-grade material. Houston port terminals handle transatlantic bulk container flows for vinyl ester resin manufacturers.
Germany
Automotive coatings formulators in Stuttgart and Munich mandate SCIP database documentation under REACH Article 33. ECHA authorization list expansion for hydroquinone derivatives tightens substance volume tracking across supply chains. BASF Ludwigshafen anchors phenol derivative production with backward integration into hydroquinone feedstock.
Japan
Mitsubishi Gas Chemical Company anchors Northeast Asian availability through captive hydroquinone production. METI chemical safety standards shape handling protocols for dimethyl sulfate methylation processes. Kawasaki industrial corridor concentrates polymerization inhibitor demand from vinyl monomer manufacturers.
Switzerland
Basel biotech clusters generate pharmaceutical-grade MEHQ demand for API stabilization in oncology drug manufacturing. Swissmedic facility inspection requirements enforce ICH Q7 compliance for antioxidant supply into drug products. Roche and Novartis procurement offices drive specification tightening for validated stability data.
Mono Methyl Ether of Hydroquinone (MEHQ) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across three distinct tiers. Integrated phenol derivative chains leverage captive hydroquinone feedstock to defend margin position against merchant suppliers. The vendor base separates into multinational chemical conglomerates, regional methylation specialists, and pharmaceutical-grade certification leaders. Capacity expansion and pharmacopeia compliance represent the dominant competitive moves.
Among Japanese chemical conglomerates, Mitsubishi Gas Chemical Company exemplifies the integrated feedstock archetype. Eastman Chemical Company and Solvay S.A. occupy positions on the multinational diversified tier, with the former representing North American phenol derivative integration and the latter anchoring European regulatory compliance depth. Chinese specialists including Xiangshui Henryda Tech Chemical Co., Ltd. and Jiangsu Evergreen Chemical Industry Co., Ltd. sit within the regional production cluster archetype serving Jiangsu province demand.
| Leading Market Players |
|---|
| Tokyo Chemical Industry Co., Ltd. |
| Mitsubishi Gas Chemical Company |
| Eastman Chemical Company |
| Xiangshui Henryda Tech Chemical Co., Ltd. |
| Jiangsu Evergreen Chemical Industry Co., Ltd. |
| Solvay S.A. |
| Camlin Fine Sciences |
| Arkema S.A. |
| TCI Chemicals |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap methylation specialists in China's Shandong province anchor regional supply discipline, translating captive hydroquinone access into pricing power that resists margin erosion from Japanese and Korean conglomerate spot dumping. This ownership pattern concentrates volume commitment leverage among Jiangsu acrylic acid producers who negotiate multi-year offtake floors.
Pricing Analysis
Capacity additions in Jiangsu province are reshaping price floors for industrial-grade material as membrane purification technology narrows the cost gap with pharmaceutical grades. Three-tier pricing structure across pharmaceutical, industrial, and research grades separates certification-burdened API stabilization supply from commodity polymerization inhibitor flows. Pricing pressure stems from phenothiazine substitution in vinyl ester applications where color stability requirements relax. Chemical manufacturing buyers exhibit highest price sensitivity, while Basel and Boston pharmaceutical clusters absorb premium spreads for validated stability data.
Supply Chain Analysis
China's MEE emission controls on methylation processes function as de facto local-content rules, favoring domestic producers with upgraded Yangtze River Delta facilities over import-dependent formulators. Supply concentrates in China, Japan, and Germany, with hydroquinone feedstock, dimethyl sulfate, and methylation catalysts as critical inputs. Single-source vulnerability runs through Mitsubishi Gas Chemical's captive Northeast Asian hydroquinone position. Distribution runs through Rotterdam and Houston port terminals for bulk vinyl ester resin manufacturers, with drum-scale flows via regional distributors serving Shandong paint formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MEHQ procurement arbitrage opportunities separate Jiangsu province spot markets from long-term Gulf Coast contracting, with EPA TSCA Section 5 compliance costs creating persistent access differentials for US-bound industrial-grade supply.
For Market Incumbents: Hedge phenol derivative feedstock exposure through backward integration into hydroquinone or strategic inventory positioning ahead of phenol pricing cycles. Mitsubishi Gas Chemical's captive feedstock model demonstrates defensive value against merchant supplier margin compression. Lock pharmaceutical-grade customers into 18-24 month ICH Q7 validation cycles that delay competitor qualification. For New Entrants and Emerging Players: Mid-scale coatings formulators in Southeast Asian construction markets represent an underserved buyer archetype seeking drum-scale procurement with shorter lead times than Chinese conglomerates provide. White-space targets include cosmetic-grade supply for Paris and Milan clean beauty formulators and research-grade distribution through Heidelberg and Boston academic clusters. Go-to-market via specialty chemical distributors with established laboratory relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among regional Chinese methylation specialists facing MEE compliance upgrade costs. Long-term viability centers on carbon-intensity labeling differentiation under EU Green Deal procurement guidelines. Acquisition target archetype: Jiangsu province producers with membrane purification technology and REACH dossier completion. Signal to watch: ECHA authorization list expansion for hydroquinone derivatives tightening substance volume tracking.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydroquinone | Captive feedstock secures margin buffers against phenol derivative volatility for Jiangsu producers. |
| Pharmaceutical-Grade Pharmacopeia Expansion | ICH Q7 compliance opens Basel and Boston oncology API stabilization demand with premium pricing. |
| Membrane Purification Technology Deployment | Shandong adopters compress industrial-pharmaceutical grade cost gaps, enabling tier repositioning. |
| Long-Term Offtake Contracting | US Gulf Coast wind blade composite producers lock supply security for multi-year turbine installations. |
| Carbon-Intensity Process Certification | Low-emission methylation differentiation aligns with EU Green Deal procurement guidelines for European buyers. |
Research Methodology
Coverage spans China, the United States, Germany, Japan, and Switzerland, with primary inputs from each region's chemical manufacturing and pharmaceutical procurement centers. Plant managers at Jiangsu acrylic acid facilities, procurement leads at Gulf Coast vinyl ester resin manufacturers, technical R&D directors at European coatings formulators, and regulatory affairs specialists at Basel biotech clusters contributed operational data. Secondary validation drew from customs and trade databases, SEC 10-K filings of listed chemical conglomerates, ECHA substance volume tracking disclosures, and MEE emission control enforcement records. Bottom-up capacity and consumption estimates triangulated against top-down industry association aggregates.
Granularity-level modeling distinguished pharmaceutical-grade, industrial-grade, cosmetic-grade, and research-grade tiers, with separate treatment of acrylic acid, methacrylate, and vinyl ester end-use applications across regional production hubs. CAGRs derived from segment-level volume trajectories calibrated to hydroquinone derivative demand elasticity and polymerization inhibitor substitution patterns. Forecast inputs incorporated REACH authorization list expansion timelines, EPA TSCA Section 5 enforcement intensity, and China's dual carbon goal methylation process upgrade adoption curves.
Underlying measurement precision varies by segment; pharmaceutical-grade consumption carries tighter precision than research-grade fragmentation across academic procurement channels. Forecasts reflect assumptions about phenothiazine substitution elasticity, phenol derivative pricing volatility, and regulatory compliance cost pass-through that could revise trajectories if ECHA or EPA action accelerates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
High-Value Chemicals
Hydroxynitrile Lyase Market
High-Value Chemicals
High Purity Silica Market
High-Value Chemicals
Global High Purity Oxygen Market
High-Value Chemicals
High Purity Lignin Market
High-Value Chemicals
High Temperature Plastic Market
High-Value Chemicals
Hydroxylamine Sulfate Market
High-Value Chemicals
Ultra-High Purity Hydrofluoric Acid Market
High-Value Chemicals
Global High Heat Foam Market
High-Value Chemicals
Global High Purity AHCL Market
High-Value Chemicals
High Methoxyl Pectin Market
High-Value Chemicals
Global High Dispersible Silica Market
High-Value Chemicals
Hydroquinone Market
High-Value Chemicals
High Performance Fluoropolymers Market
High-Value Chemicals
High Purity MTBE Market
High-Value Chemicals
Sodium Hexametaphosphate Market
High-Value Chemicals
High-Purity Hydrogen Fluoride Market