
 Electric Vehicle Permanent Magnet Synchronous Motors Market | 2026-2036
Electric Vehicle Permanent Magnet Synchronous Motors Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Permanent Magnet Synchronous Motors Market Insights
Buyer concentration among OEMs is shifting as established automakers diversify supplier bases while new EV entrants fragment procurement across specialized motor manufacturers. Bosch GmbH leverages its integrated powertrain systems to anchor long-term supply agreements with European OEMs. Nidec Corporation competes through high-volume production scale in axial flux and interior permanent magnet variants. BYD Company Limited sustains captive motor production for its vertically integrated vehicle platforms.
Electric Vehicle Permanent Magnet Synchronous Motors employ rare earth neodymium-iron-boron magnets arranged in interior or surface-mounted configurations to generate sinusoidal back-EMF waveforms, achieving torque densities exceeding 15 kW per kilogram in liquid-cooled architectures designed for direct-drive traction applications. Interior permanent magnet configurations dominate high-performance passenger vehicle platforms where field-weakening extends constant power speed ranges. Surface permanent magnet designs occupy cost-sensitive commercial vehicle segments with simpler manufacturing processes. Integrated motor drives with torque density optimization technology represent the fastest-expanding technology category as OEMs consolidate power electronics and thermal management.
China's MIIT enforces GB standards for motor efficiency and rare earth content disclosure, while the EU Green Deal and F-Gas Regulation phase down fluorinated coolant gases used in motor thermal systems. The US EPA and NHTSA coordinate tailpipe and fuel economy standards that indirectly mandate higher-efficiency drivetrain components including permanent magnet synchronous architectures. Stakeholders must monitor magnet recycling mandates and alternative ferrite-assisted motor topologies that reduce rare earth dependency without sacrificing power density targets.
Market Dynamics
Rare earth magnet supply concentration in China's processing corridors is forcing OEMs to reconfigure sourcing architectures and accelerate alternative magnet topology development. This structural dependency is reshaping competitive positioning across the entire motor value chain.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of fluorinated coolant gases in motor thermal systems is compressing design cycles for liquid-cooled architectures with higher torque density.
- Passenger vehicle platforms:Field-weakening capable interior permanent magnet configurations are displacing induction motor alternatives in premium electric drivetrains.
- Integrated motor drives:Consolidation of power electronics and thermal management into single housings is reducing assembly complexity for OEM powertrain divisions.
Market Restraints
- Neodymium price volatility:Rare earth oxide processing bottlenecks in China's Ganzhou and Baotou clusters create input cost unpredictability for magnet procurement.
- Single-source magnet dependence:Over 80% of separated heavy rare earth processing concentrates in Chinese state-controlled entities, creating geopolitical supply risk.
- Ferrite-assisted torque density gap:Reduced rare earth motor topologies sacrifice 15-20% power density versus full NdFeB architectures, limiting high-performance applications.
Strategic Opportunities
- Magnet recycling mandates:The EU's Critical Raw Materials Act creates regulatory tailwinds for closed-loop rare earth recovery from end-of-life motors.
- Commercial vehicle electrification:Surface permanent magnet designs with simplified manufacturing are penetrating bus and medium-duty truck segments previously served by induction motors.
- Axial flux convergence:Integration of axial flux topologies with silicon carbide inverters is opening packaging advantages for wheel-hub and in-wheel motor applications.
Industry Challenges
- Motor control algorithm expertise:Field-oriented control and sensorless vector control implementation requires embedded software capabilities scarce in traditional mechanical engineering organizations.
- Thermal validation cycles:Liquid-cooled stator housing validation against GB/T and IEC 60034 standards extends development timelines by 8-14 months.
- Legacy powertrain integration:Permanent magnet synchronous architectures face mechanical interface incompatibility with existing transmission and axle assemblies in retrofit applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Permanent Magnet Synchronous Motors Market |
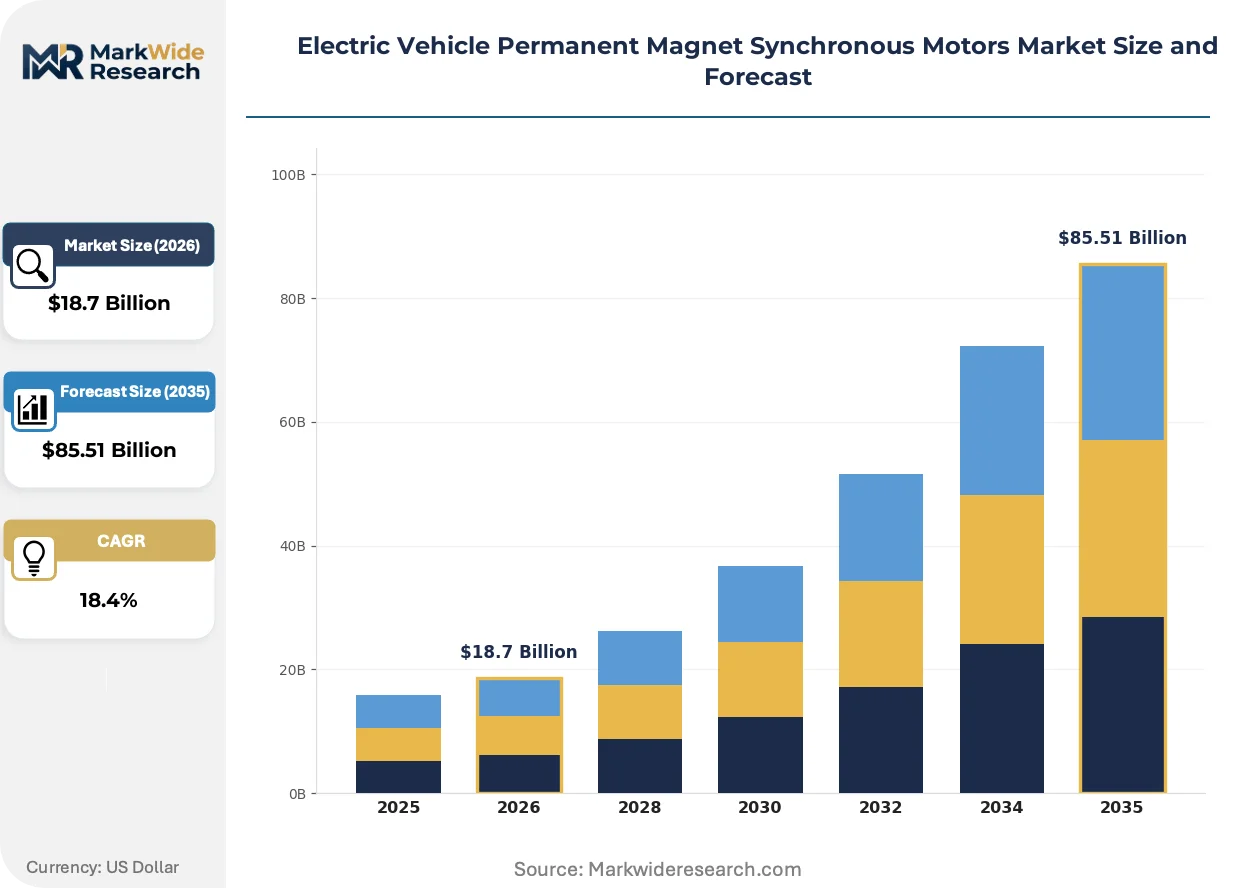
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $85.51 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interior Permanent Magnet, Surface Permanent Magnet, Transverse Flux, Axial Flux Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Off-Road Vehicles End User: OEMs, Tier-1 Suppliers, Fleets, Aftermarket Providers Technology: Brushless DC, Torque Density Optimization, Integrated Motor Drives, Cooling Systems |
| Companies Covered | Bosch GmbH, General Motors, Tesla, Parker Hannifin Corporation, Continental AG, Nidec Corporation, BYD Company Limited, Mitsubishi Electric Corporation, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Permanent Magnet Synchronous Motors Market Trends and Innovations
Silicon carbide power electronics and advanced thermal interface materials are compressing the boundary between motor and inverter design. These converging technologies are enabling new form factors that challenge conventional drivetrain packaging assumptions.
Hairpin winding stator construction is rewriting manufacturing economics for high-volume motor production. Automotive OEMs in Germany and China's manufacturing clusters are converting round-wire stator lines to hairpin configurations at scale. This topology shift is enabling slot fill factors above 70% while reducing copper losses and compressing motor length by 15-25%.
The EU F-Gas Regulation and China's GB standards for motor efficiency are creating divergent compliance architectures for global suppliers. European manufacturers must phase down hydrofluoroolefin coolants by 2030, accelerating adoption of dielectric fluid and direct oil cooling systems. Asian producers serving dual markets are developing modular thermal platforms that satisfy both regulatory regimes without complete redesign.
Fleet operators and leasing companies are consolidating motor procurement through powertrain-as-a-service contracts rather than component sourcing. This model transfers operational risk to motor suppliers and compresses upfront capital requirements for commercial vehicle electrification. The shift is most visible in European logistics corridors where total-cost-of-ownership calculations dominate procurement decisions.
Electric Vehicle Permanent Magnet Synchronous Motors Market Segmentation
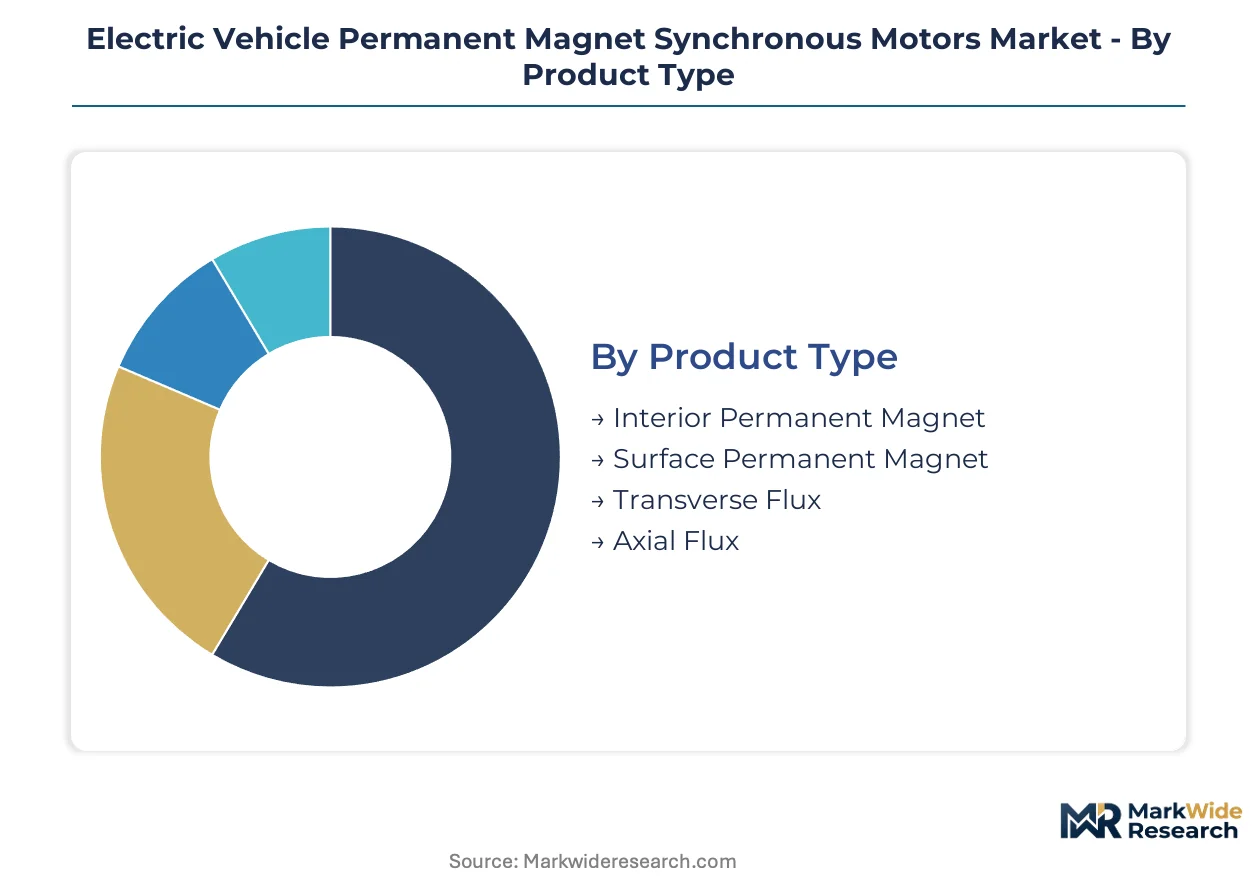
Segmentation in permanent magnet synchronous motors determines thermal management architectures, magnet topology selection, and regulatory compliance pathways. Each category carries distinct certification burdens and supply chain configurations that shape procurement decisions across OEM powertrain divisions.
Product Type:
Certification requirements diverge sharply across magnet configurations, with GB/T efficiency standards and EU F-Gas Regulation imposing distinct thermal validation protocols on interior versus surface-mounted designs.
- Interior Permanent Magnet:Buried magnet configurations enable field-weakening control strategies that extend constant power speed ranges beyond base speed by 2.5x. Demand concentrates in German premium passenger vehicle platforms where NHTSA crash safety standards and EU homologation requirements mandate torque density above 15 kW/kg. The embedded magnet geometry complicates rotor lamination assembly but eliminates magnet retention sleeves.
- Surface Permanent Magnet:Exposed neodymium-iron-boron segments bonded to rotor peripheries simplify manufacturing for cost-sensitive commercial vehicle procurement. China's MIIT GB standards for motor efficiency disclosure favor these designs in bus and medium-duty truck segments where manufacturing scale outweighs field-weakening performance requirements. Retention sleeves add 8-12% rotor mass but enable simpler stator winding automation.
- Transverse Flux:Concentrated winding topologies achieve exceptional torque density for direct-drive hub applications in off-road mining equipment.
- Axial Flux:Flat motor geometries suit wheel-hub packaging constraints in European electric two-wheeler platforms requiring compact powertrain integration.
Leading the category by volume: Interior Permanent Magnet. Expanding most quickly: Axial Flux.
Application:
Vehicle platform architecture dictates motor duty cycles, thermal envelopes, and the balance between continuous versus peak power ratings across procurement specifications.
- Passenger Vehicles:Multi-speed reduction gearboxes and liquid-cooled stator housings dominate 150-300 kW traction applications where EPA and NHTSA fuel economy standards indirectly mandate permanent magnet synchronous architectures over induction alternatives. Field-oriented control algorithms with sensorless vector estimation enable 20,000+ RPM maximum speeds for compact SUV and sedan platforms.
- Commercial Vehicles:Continuous duty cycles at 40-80 kW ratings prioritize thermal endurance over peak acceleration in urban bus and delivery truck segments. China's GB/T 18488 standards for electric commercial vehicle motors specify insulation class H and IP67 environmental sealing that surface permanent magnet designs satisfy at lower cost than interior configurations. Regenerative braking energy recovery exceeds 30% of traction energy in stop-and-go duty profiles.
- Two-Wheelers:Hub motor integration in Asian urban mobility platforms emphasizes compact axial flux geometries with direct rim mounting.
- Off-Road Vehicles:Mining and agricultural equipment demands sealed enclosures against dust ingress per ISO 20653 ratings.
Highest procurement value concentration: Passenger Vehicles. Steepest volume climb: Commercial Vehicles.
End User:
Procurement authority distribution across the value chain determines specification control, with OEM captive production contrasting against outsourced Tier-1 supply arrangements.
- OEMs:Vertically integrated powertrain divisions at BYD and Tesla specify proprietary motor geometries optimized for vehicle platform packaging constraints. In-house production enables rapid iteration cycles for thermal interface materials and magnet segmentation strategies that external suppliers cannot match. Design authority resides with vehicle engineering teams rather than component procurement.
- Tier-1 Suppliers:Bosch and Nidec manufacture standardized motor platforms serving multiple OEM customers with common stator laminations and customizable rotor magnet configurations. Economies of scale in hairpin winding equipment amortize across 500,000+ annual unit volumes. Warranty liability transfer to Tier-1s compresses margin structures but secures long-term supply agreements.
- Fleets:Logistics operators in European corridors negotiate powertrain-as-a-service contracts transferring operational risk to suppliers.
- Aftermarket Providers:Remanufactured motors and replacement controllers serve legacy vehicle parc maintenance requirements.
Dominant procurement channel: OEMs. Fastest contract model growth: Fleets.
Technology:
Subsystem integration depth separates commodity motor suppliers from powertrain solution providers capable of optimizing system-level efficiency.
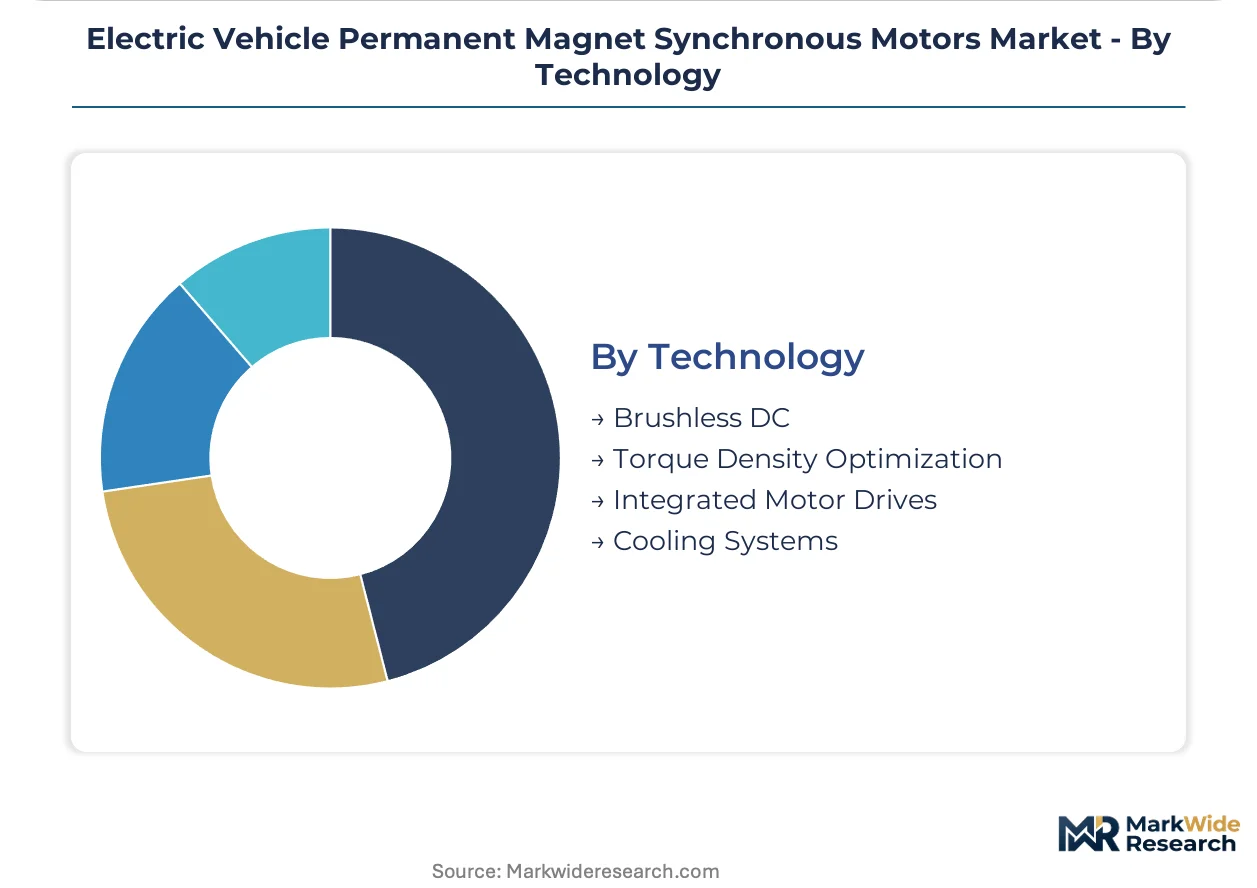
- Integrated Motor Drives:Consolidated housings combining silicon carbide inverters, DC-link capacitors, and liquid-cooled stators reduce assembly complexity and electromagnetic interference shielding mass. German automotive OEMs specify these architectures for 800V platforms where packaging density determines front-trunk and rear-cargo volume. The integration trend accelerates as GaN and SiC device costs decline below silicon IGBT parity.
- Torque Density Optimization:Advanced magnetic circuit design, high-strength electrical steel laminations, and direct oil cooling enable 20+ kW/kg continuous ratings in performance electric vehicles. China's MIIT motor efficiency GB standards create regulatory tailwinds for these premium architectures in domestic market premium SUVs. Computational fluid dynamics-driven thermal management replaces empirical design iteration.
- Brushless DC:Trapezoidal back-EMF controllers serve cost-optimized two-wheeler and auxiliary motor applications.
- Cooling Systems:Dielectric fluid and direct oil spray architectures replace hydrofluoroolefin refrigerants under EU F-Gas phasedown mandates.
Technology commanding premium pricing: Integrated Motor Drives. Gaining share fastest: Torque Density Optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth processing corridors in China's Ganzhou and Baotou clusters anchor magnet supply chains for permanent magnet synchronous motor production. German automotive engineering centers and US battery manufacturing zones compete for motor assembly capacity. Regulatory divergence between EU F-Gas phasedown mandates and China's GB efficiency standards is fragmenting thermal management design approaches.
China
MIIT enforces GB/T 18488 motor efficiency standards and rare earth content disclosure rules that reshape procurement specifications. The dual carbon goals accelerate domestic OEM electrification timelines. Manufacturing gravity concentrates in Shenzhen-Dongguan corridors where BYD and Nidec operate high-volume axial flux and interior permanent magnet lines.
Germany
NHTSA-aligned EU homologation requirements and KBA type-approval processes govern premium passenger vehicle motor certification. The EU Green Deal and F-Gas Regulation mandate dielectric fluid cooling system transitions by 2030. Stuttgart and Munich engineering clusters host Bosch powertrain divisions developing integrated motor drives for 800V platforms.
United States
EPA fuel economy standards and NHTSA tailpipe regulations indirectly mandate high-efficiency drivetrain component adoption. The Inflation Reduction Act domestic content provisions reshape magnet sourcing strategies. Michigan and Tennessee automotive corridors attract Tesla and General Motors motor assembly investments.
Japan
METI industrial policy and JIS standards govern motor efficiency benchmarking for export-oriented suppliers. Silicon carbide inverter integration receives government R&D subsidies. Nagoya and Osaka manufacturing zones concentrate Mitsubishi Electric and Nidec precision motor production for hybrid and battery-electric platforms.
South Korea
MFDS-equivalent automotive safety regulators coordinate with MOTIE industrial strategy on electrification component localization. Battery cell manufacturing expansion in Gyeonggi Province creates co-location opportunities for motor assembly. Seoul Capital Area engineering centers develop hairpin winding automation for Tier-1 export contracts.
Electric Vehicle Permanent Magnet Synchronous Motors Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue axial flux specialization and integrated drive architectures. The vendor base stratifies across three maturity levels: diversified industrial conglomerates with captive automotive divisions, dedicated motor manufacturers with scale-driven cost positions, and technology-focused specialists exploiting silicon carbide convergence. Consolidation pressure concentrates among mid-scale suppliers lacking hairpin winding equipment or thermal validation capabilities. Dominant competitive moves include backward integration into magnet recycling streams and strategic partnerships for 800V platform co-development.
Among diversified industrial conglomerates, Bosch GmbH and Siemens AG exemplify integrated powertrain solution providers spanning inverter design through thermal management. Nidec Corporation occupies a position among dedicated motor specialists with volume-driven production economics. Within the captive production tier, BYD Company Limited represents vertical integration into proprietary vehicle platforms. These archetypes illustrate divergent strategic postures: external supply relationships versus in-house design authority versus hybrid partnership models.
| Leading Market Players |
|---|
| Bosch GmbH |
| General Motors |
| Tesla |
| Parker Hannifin Corporation |
| Continental AG |
| Nidec Corporation |
| BYD Company Limited |
| Mitsubishi Electric Corporation |
| Siemens AG |
| Others |
Pricing and Supply Chain Analysis
OEM powertrain consolidation around 800V platform specifications is compressing supplier margins while demanding enhanced thermal validation and magnet traceability documentation. This specification escalation forces Tier-1 manufacturers to absorb upfront certification costs or cede procurement share to vertically integrated rivals.
Pricing Analysis
Warranty bundling separates premium motor suppliers from commodity producers, with extended thermal endurance guarantees now standard in German OEM contracts but unbundled in Chinese commercial vehicle procurement. Three-tier pricing structure across premium, standard, and economy levels reflects torque density certification tiers under GB/T and IEC 60034 standards. Cost compression in surface permanent magnet architectures is intensifying because hairpin winding equipment amortization demands volume commitments above 200,000 annual units. Fleet operators exhibit highest price sensitivity through powertrain-as-a-service negotiations, while premium passenger vehicle OEMs prioritize performance density over unit cost.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Los Angeles anchor hub-and-spoke patterns for magnet alloy and finished motor logistics. Rare earth oxide separation concentrates in China's Ganzhou and Baotou corridors, with silicon carbide wafer fabrication anchored in Taiwan, Japan, and Germany. Single-source vulnerability in heavy rare earth processing creates geopolitical exposure for NdFeB magnet procurement. Distribution runs through OEM captive facilities for BYD and Tesla, while Tier-1 suppliers maintain independent warehousing near Stuttgart, Nagoya, and Detroit automotive clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation's 2030 coolant phasedown deadline erects a compliance moat favoring suppliers with validated dielectric fluid architectures, freezing out late entrants lacking thermal validation cycles.
For Market Incumbents: Deploy magnet recycling infrastructure to secure closed-loop rare earth supply under the EU Critical Raw Materials Act. Bosch and Nidec must accelerate backward integration into end-of-life motor recovery streams before Chinese state entities consolidate secondary magnet processing. Field-weakening algorithm expertise represents a scarce capability that incumbents should hoard through targeted hiring from embedded software specialists. For New Entrants and Emerging Players: Capture commercial vehicle surface permanent magnet procurement in European logistics corridors where total-cost-of-service contracts transfer operational risk to suppliers. Axial flux topology specialization for wheel-hub applications in two-wheeler platforms offers the most penetrable entry vector, bypassing incumbent scale advantages in interior permanent magnet production. Partner with silicon carbide inverter specialists to offer integrated drive packages that OEM powertrain divisions cannot match. For Investors and Strategic Acquirers: The window for entry favors hairpin winding automation specialists with thermal validation capabilities certified to GB/T and IEC standards. Mid-scale suppliers lacking 800V platform development partnerships face consolidation pressure from diversified industrial conglomerates. Monitor EU magnet recycling mandate enforcement timelines as the inflection signal for secondary rare earth supply economics.| Strategic Initiative | Industry Significance |
|---|---|
| Magnet Recycling Infrastructure | Closed-loop NdFeB recovery secures supply independence from Chinese state-controlled processing corridors. |
| Hairpin Winding Conversion | Slot fill factors above 70% reduce copper losses and compress motor length for 800V platform packaging. |
| Dielectric Fluid Cooling Transition | EU F-Gas Regulation compliance enables continued market access for European OEM supply contracts. |
| Silicon Carbide Inverter Integration | Consolidated motor-drive housings reduce electromagnetic interference shielding mass in premium platforms. |
| Powertrain-as-a-Service Contracts | Risk transfer to suppliers accelerates commercial vehicle electrification without fleet capital burden. |
Research Methodology
Multi-period observation of motor efficiency certification timelines, magnet price indices, and OEM platform rollout schedules anchored the trend analysis, supplemented by interviews with Tier-1 supplier procurement directors, OEM powertrain platform engineers, thermal validation laboratory managers, and rare earth trading desk specialists. Secondary validation drew from MIIT GB standard filings, EU F-Gas Regulation implementation notices, SEC automotive segment disclosures, and vehicle production registration databases. Bottom-up unit economics triangulated against top-down OEM electrification capex projections.
Segment-weighting across magnet topology, vehicle application, cooling architecture, and regional regulatory cluster determined volume and value distributions throughout the forecast period. CAGRs derived from fitted growth curves applied to OEM electrification timelines and commercial vehicle fleet replacement cycles. Forecast inputs incorporated silicon carbide device cost trajectories, hairpin winding equipment installation rates, and EU magnet recycling infrastructure buildout assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare earth export licensing shifts, F-Gas Regulation enforcement variance, and 800V platform adoption speed. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Global EV Motor Controller Market
Electric Motor
Automotive Seat Motor Market
Electric Motor
Automotive Blower Motor Market
Electric Motor
Automotive in-Wheel Motors Market
Electric Motor
EV Traction Motor Market
Electric Motor
Intelligent Motor Controller Market
Electric Motor
US Solar E-Bike Market
Electric Motor
Automotive Electric Commutators Market
Electric Motor
Smart E-Drive Market
Electric Motor
Global Automotive Motor Market
Electric Motor
Asia-Pacific AC Electric Motor Market
Electric Motor
Motorcycle Lead Acid Battery Market
Electric Motor
Global Automotive Heating Fan Motor Market
Electric Motor
Implant Motors Market
Electric Motor
Global Vehicle Starter Motor Market
Electric Motor
Electric Motorcycle Market