
 Separately Excited Motor Market | 2026-2036
Separately Excited Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Separately Excited Motor Market Analytics
IE4 and IE5 efficiency-class upgrades is redrawing procurement criteria across the separately excited motor landscape. Sogears leverages permanent magnet integration to sustain premium positioning in precision drive applications. NER GROUP LIMITED anchors its competitive stance through captive wound-component manufacturing across European facilities. DOLANG competes aggressively on brushless motor customization for robotics OEMs in East Asian markets.
A separately excited motor employs independent field and armature winding circuits, enabling precise speed-torque control through external excitation voltage regulation rather than armature reaction dependence. The architecture permits field weakening above base speed, delivering constant-power operation critical to spindle drives and rolling mill stands. Brushless motor architectures now command the fastest expansion trajectory within the product type dimension, driven by maintenance elimination and semiconductor cost declines. Industrial automation applications concentrate the largest installed base, though transportation electrification—particularly rail traction and marine propulsion—generates the steepest growth gradient in current order books.
NEMA MG-1 standards in the United States, IEC 60034 efficiency tiers across European markets, and China's GB 18613 motor efficiency mandates collectively constrain market access for non-compliant equipment. These frameworks shift procurement specifications toward premium-efficiency designs and compel manufacturers to maintain dual-certification testing laboratories. Stakeholders must monitor evolving carbon-border adjustment mechanisms and their interaction with regional efficiency codes to anticipate sourcing cost shifts and qualification timelines.
Market Dynamics
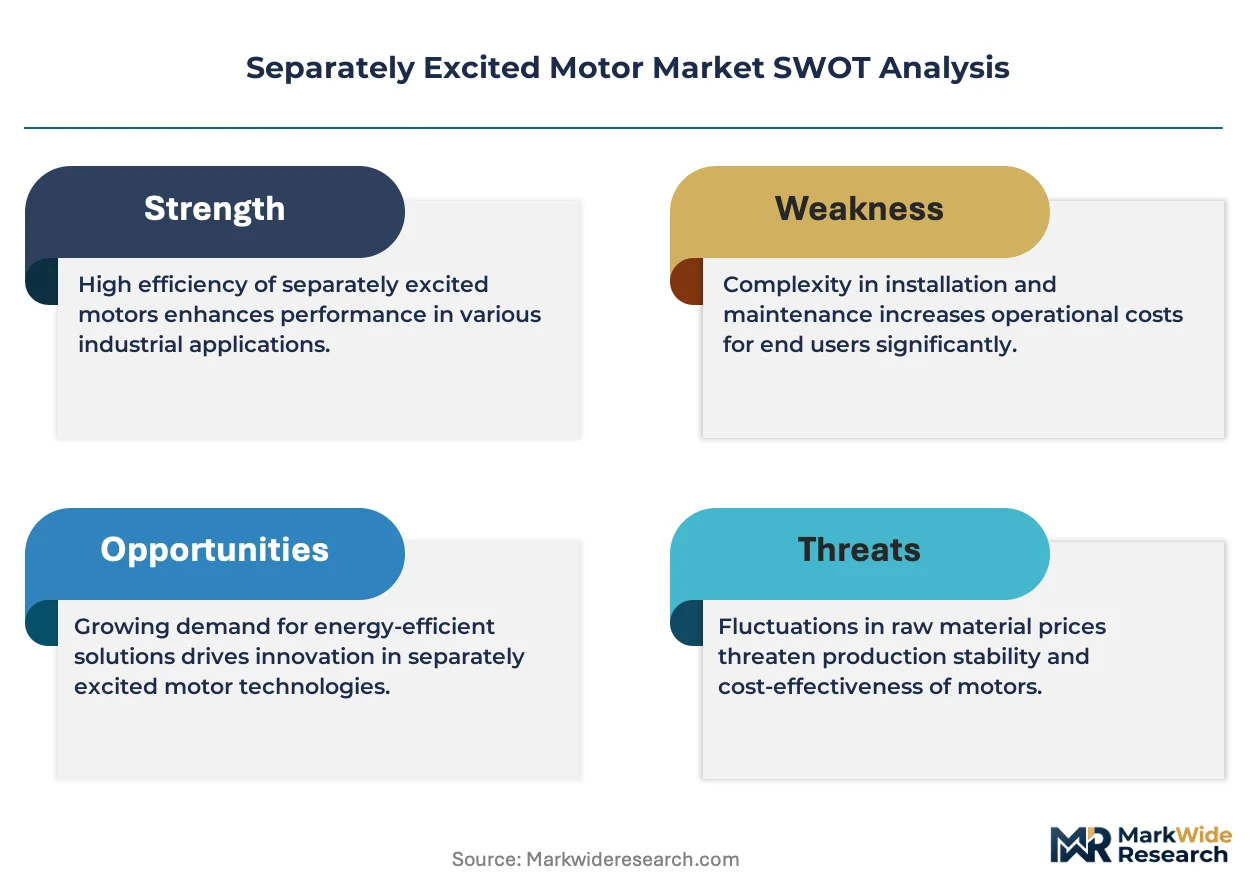
IE4 and IE5 efficiency-class upgrades are redrawing procurement criteria across the separately excited motor landscape, compelling manufacturers to redesign winding architectures and magnetic circuits while factory electrification programs in Germany, China, and the United States accelerate replacement cycles.
Growth Catalysts
- Industrial automation torque precision:Spindle drives and rolling mill stands demand field-weakening capabilities that only separately excited architectures deliver. Chinese factory electrification programs are mandating premium-efficiency motor retrofits.
- Brushless motor semiconductor cost declines:Power electronics integration is eliminating maintenance requirements in rail traction applications. Marine propulsion OEMs are specifying brushless separately excited designs for constant-power operation.
- IEC 60034 efficiency tier enforcement:European regulators are blocking non-compliant equipment from market access. GB 18613 motor efficiency mandates in China are tightening performance benchmarks for wound-field imports.
Market Restraints
- Copper and rare-earth magnet cost volatility:Wound-field construction requires substantial copper in armature and field windings. Price swings in neodymium and dysprosium for hybrid permanent magnet designs compress margin predictability.
- Dual-certification testing laboratory concentration:NEMA MG-1 and IEC 60034 compliance testing capacity clusters in Germany and the United States. Manufacturers face extended qualification timelines for multi-regional product launches.
- Permanent magnet synchronous motor substitution:Brushless PM designs are capturing precision drive applications where separately excited motors once dominated. Servo OEMs are defaulting to PM architectures for maintenance elimination.
Strategic Opportunities
- Carbon-border adjustment mechanism positioning:European importers will face embedded carbon tariffs on non-compliant motor imports. Manufacturers with low-carbon winding production can capture premium positioning.
- Marine propulsion electrification:Shipbuilders in Norway and Germany are specifying separately excited motors for azimuth thrusters. Field-weakening range matches vessel speed-torque requirements across operating profiles.
- Digital twin and predictive maintenance convergence:Sensor-integrated separately excited motors enable condition monitoring for high-value industrial assets. Mining and metals processors are piloting vibration-thermal fused diagnostics.
Industry Challenges
- Winding technician skill scarcity:Precision wound-field manufacturing requires specialized coil winding and impregnation expertise. European and North American vocational pipelines are producing insufficient replacement capacity.
- Multi-standard certification timeline compression:Simultaneous NEMA MG-1, IEC 60034, and GB 18613 qualification extends product development cycles. Testing backlog at accredited laboratories stretches commercialization schedules.
- Legacy DC drive infrastructure integration:Retrofit projects face compatibility constraints with existing thyristor and chopper control systems. Modern IGBT-based field supplies require signal interface adaptation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Separately Excited Motor Market |
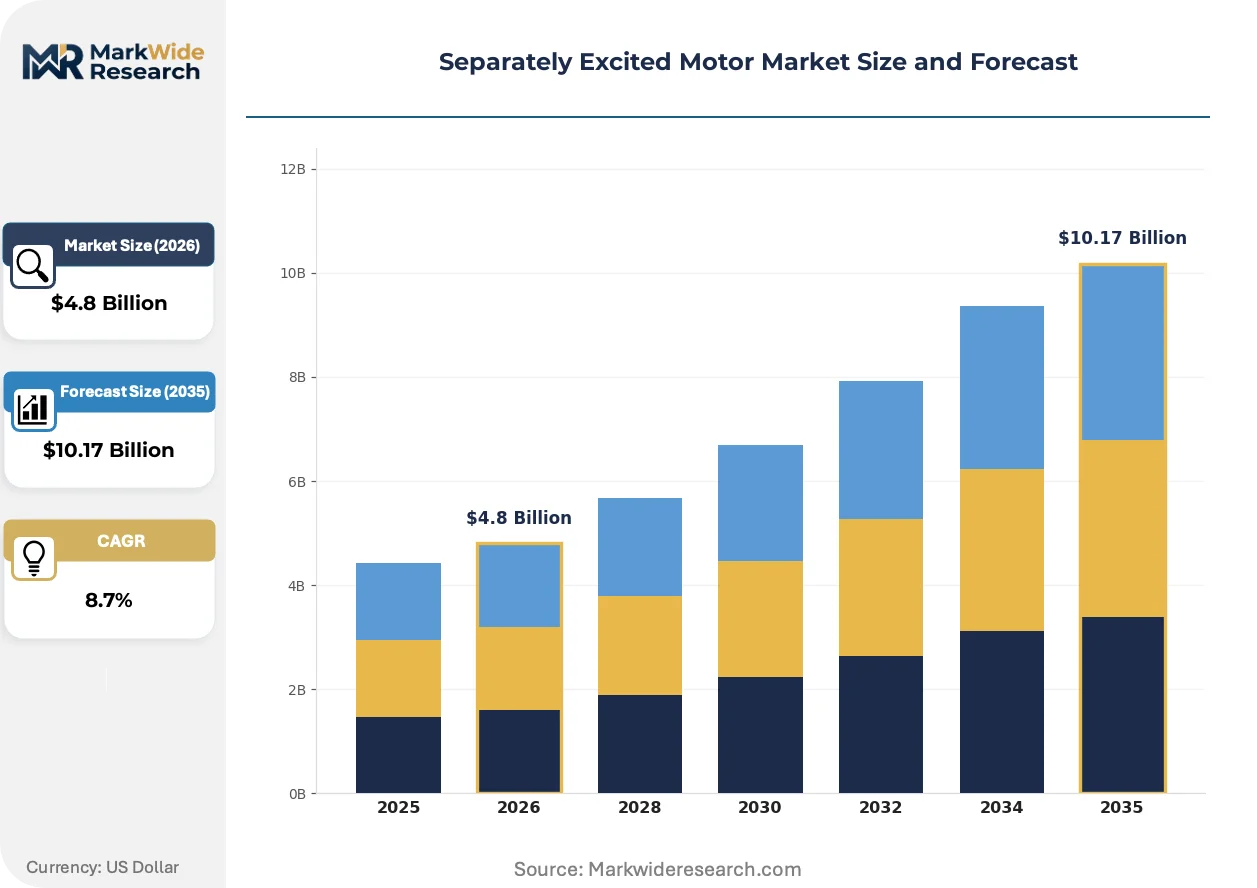
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DC Motors, AC Motors, Universal Motors, Brushless Motors End User: Manufacturing, Automotive, Mining, Aerospace Application: Industrial Automation, Robotics, HVAC, Transportation Service Type: Repair and Maintenance, Installation, Consulting, Customization |
| Companies Covered | Sogears, Horse Motors, Fuan Liyuan Electric Motor Co. Ltd., DOLANG, NER GROUP LIMITED, Impulse Drives And Motors, D&D Motor Systems Inc., Liyuan Motor Ltd, Apparatus Repair & Engineering, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Separately Excited Motor Market Evolving Landscape
Permanent magnet integration into wound-field architectures is fragmenting traditional product boundaries, while regulatory efficiency tier escalation and procurement model evolution are compressing technology adoption cycles across industrial buyer segments.
Silicon carbide power electronics are fragmenting the separately excited motor controller landscape. Rail traction OEMs in Germany and Japan are adopting SiC-based field supplies for switching frequency increases that reduce filter component mass. The technology is fragmenting procurement patterns as buyers separate motor and controller sourcing decisions.
China's GB 18613-2020 motor efficiency standard and its 2024 revision draft are tightening minimum efficiency values for wound-field industrial motors. Domestic manufacturers are accelerating IE4 and IE5 product line development to avoid market exclusion. Export-oriented Chinese motor producers are establishing IEC 60034 testing partnerships with European notified bodies.
Lifecycle service contracting is displacing unit-based procurement in heavy industrial verticals. Mining and metals processors in Australia and Canada are purchasing motor-drive systems with guaranteed availability commitments rather than capital equipment. This restructures supplier relationships toward performance accountability and remote monitoring infrastructure investment.
Separately Excited Motor Market Segmentation
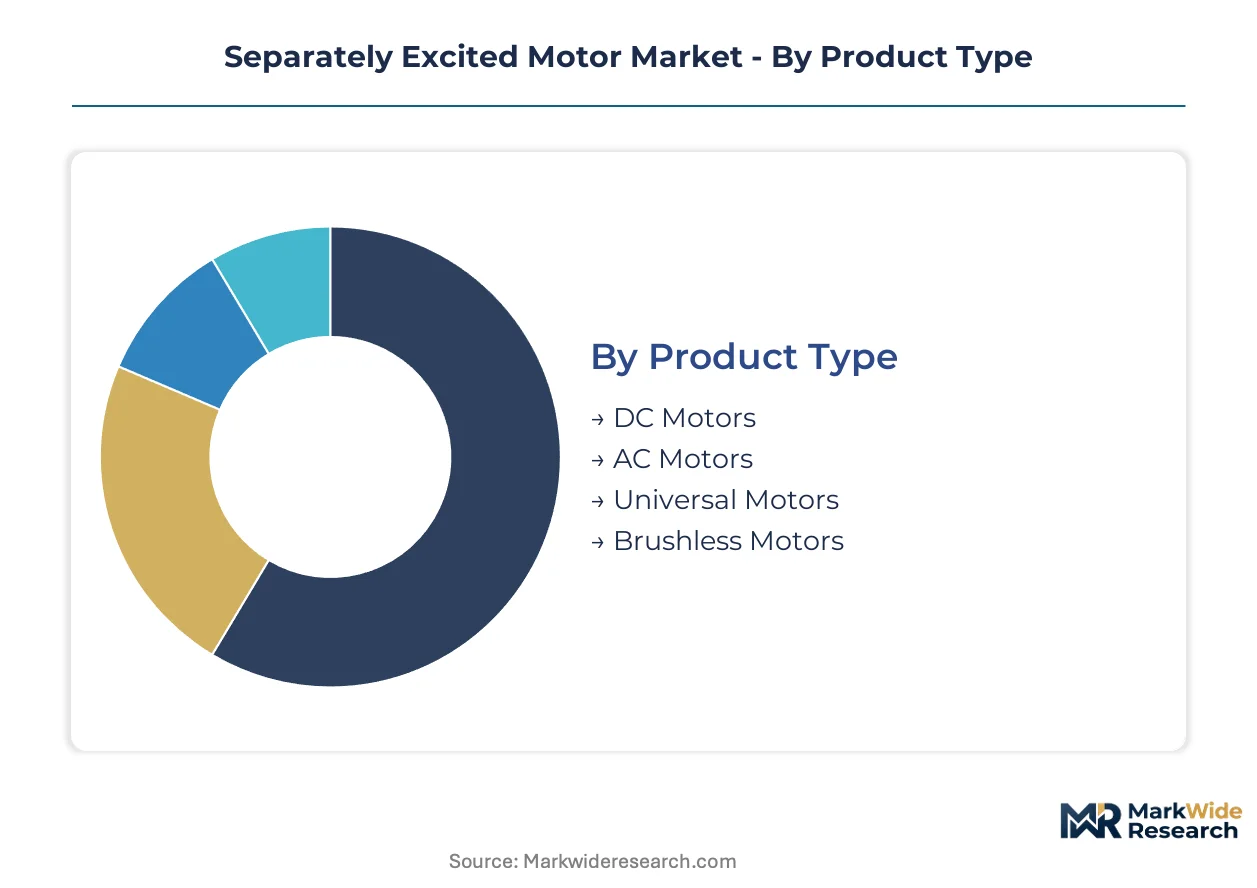
Separately excited motor procurement splits across multiple technical and commercial dimensions. Buyers select architectures based on field-weakening requirements, maintenance profiles, and regional efficiency mandates.
Product Type:
IEC 60034 and NEMA MG-1 efficiency tiers apply differentially across motor architectures, with brushless designs facing distinct semiconductor integration standards.
- Brushless Motors:Electronic commutation eliminates brush maintenance. Rail traction OEMs in Germany and Japan specify these for reduced lifecycle costs. SiC power electronics enable higher switching frequencies that cut filter mass.
- DC Motors:Traditional wound-field construction with independent armature and field circuits delivers precise speed-torque control. Rolling mill stands and spindle drives in Chinese factory electrification programs specify these for field-weakening above base speed.
- AC Motors:Induction-based separately excited variants serve constant-speed applications with simpler control requirements.
- Universal Motors:Series-wound designs operating on AC or DC power suit portable equipment with intermittent duty cycles.
Brushless motors handle the majority of throughput; DC motors are the fastest mover on share.
End User:
Customer scale and asset criticality determine service bundling and lifecycle contracting approaches across industrial verticals.
- Manufacturing:Factory automation lines demand precision torque control for spindle drives and positioning systems. Chinese electrification mandates are accelerating IE4 and IE5 retrofits in automotive component plants.
- Mining:Harsh operating environments favor brushless architectures for reduced maintenance. Australian and Canadian processors are piloting sensor-integrated motors with predictive diagnostics.
- Automotive:Production line conveyors and test stands require dynamic speed control.
- Aerospace:Ground support equipment and manufacturing tooling specify high-reliability wound-field designs.
Manufacturing captures the largest installed base; mining is climbing the fastest on replacement demand.
Application:
Operating duty cycles and speed range requirements dictate field-weakening specifications and thermal management architectures.
- Industrial Automation:Spindle drives, rolling mills, and positioning systems demand constant-power operation above base speed. German machine tool OEMs specify separately excited architectures for torque precision.
- Transportation:Rail traction and marine propulsion require wide field-weakening ranges. Norwegian and German shipbuilders specify these motors for azimuth thrusters across vessel speed profiles.
- Robotics:Articulated arms and gantry systems need dynamic torque response.
- HVAC:Fan and pump applications favor simpler control strategies with limited speed ranges.
Industrial automation maintains the deepest penetration; transportation is gaining share fastest on electrification programs.
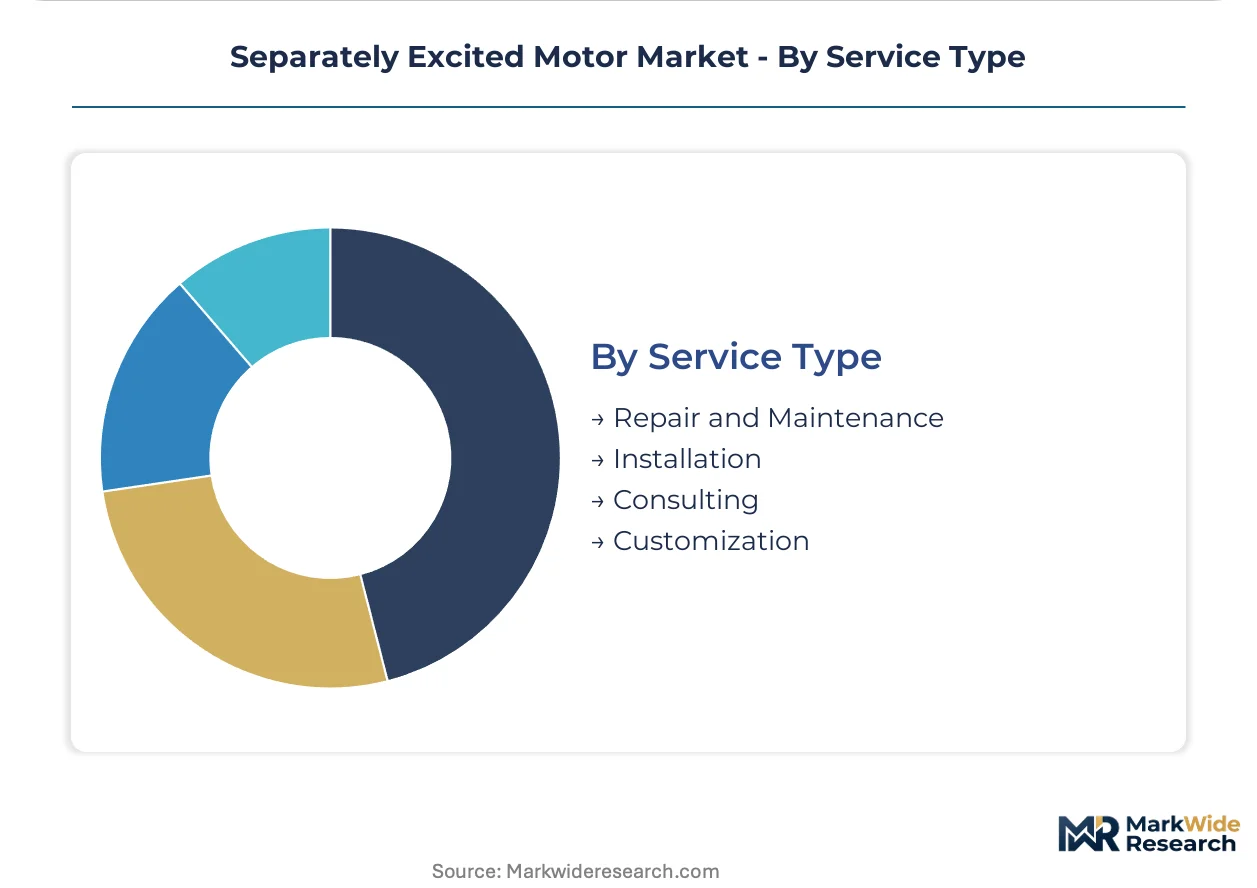
Service Type:
Procurement model evolution is restructuring supplier relationships from unit sales to performance accountability.
- Repair and Maintenance:Wound-field motor servicing requires specialized coil winding and impregnation expertise. European vocational pipelines are producing insufficient technician replacement capacity.
- Customization:Application-specific winding configurations and magnetic circuit modifications address unique torque-speed requirements. Robotics OEMs in East Asian markets specify tailored brushless designs.
- Installation:Commissioning services ensure proper alignment with existing drive infrastructure.
- Consulting:Efficiency audits and retrofit planning support compliance with tightening regulatory tiers.
Repair and maintenance generates the recurring revenue base; customization is expanding most quickly on OEM integration demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German motor exports supply precision drive systems to Chinese automotive plants and US machine tool builders. Factory electrification programs in these three markets are accelerating replacement demand for IE4 and IE5 efficiency-class equipment. Regulatory divergence across IEC, NEMA, and GB standards fragments certification requirements for multi-regional suppliers.
Germany
Rail traction OEMs in Berlin and Munich specify brushless separately excited motors for reduced lifecycle maintenance. The EU Green Deal and Ecodesign Directive tighten efficiency benchmarks for wound-field industrial equipment. Bavarian machine tool clusters around Augsburg and Nuremberg are retrofitting spindle drives with field-weakening capable architectures.
China
Automotive component plants in Shanghai and Guangzhou demand precision torque control for production line automation. GB 18613-2020 and its 2024 revision draft mandate IE4 minimum efficiency for wound-field motor imports. Yangtze River Delta factory electrification programs are replacing legacy DC drives with premium-efficiency retrofits.
United States
Steel rolling mills in Indiana and Ohio require constant-power operation above base speed for mill stand applications. NEMA MG-1 revisions establish stricter performance benchmarks for separately excited motor procurement. Detroit-area automotive OEMs are specifying field-weakening drives for test stand equipment.
Japan
Semiconductor fabrication equipment builders in Tokyo and Osaka need precise speed-torque control for wafer handling systems. METI efficiency standards and JIS C 4034 frameworks govern industrial motor performance tiers. Nagoya-area robotics manufacturers are integrating brushless separately excited motors into articulated arm drives.
Norway
Shipbuilders in Bergen and Stavanger specify separately excited motors for azimuth thruster electrification. The country's national maritime regulator enforces stringent efficiency and emissions standards for vessel propulsion systems. Norwegian marine clusters are piloting field-weakening drives across offshore supply vessel fleets.
Separately Excited Motor Market Competitive Landscape
Listed leaders compete with private specialists across efficiency certification and application customization dimensions. The vendor base clusters around three tiers: multinational electrical equipment conglomerates with captive testing laboratories, mid-scale wound-field specialists with regional certification depth, and brushless motor boutiques serving robotics OEMs. Consolidation pressure concentrates among European mid-caps seeking IEC 60034 testing capacity. Strategic moves center on dual-certification laboratory acquisition and permanent magnet winding integration partnerships.
Within the permanent magnet integration tier, Sogears and NER GROUP LIMITED exemplify divergent geographic anchoring strategies. Sogears occupies a position among precision drive specialists leveraging semiconductor cost declines for brushless expansion. NER GROUP LIMITED sits within the European wound-component manufacturing archetype, representing captive production depth across continental facilities. DOLANG anchors the East Asian customization vector for robotics OEM integration demands.
| Leading Market Players |
|---|
| Sogears |
| Horse Motors |
| Fuan Liyuan Electric Motor Co. Ltd. |
| DOLANG |
| NER GROUP LIMITED |
| Impulse Drives And Motors |
| D&D Motor Systems Inc. |
| Liyuan Motor Ltd |
| Apparatus Repair & Engineering, Inc. |
| Others |
Value Network & Pricing Analysis
Silicon carbide power module substitution for silicon IGBT field supplies simultaneously redraws procurement geography toward East Asian semiconductor foundries and compresses controller pricing premiums that wound-field motor manufacturers command. This input transition fragments traditional bundled motor-controller sourcing patterns as buyers separate component decisions.
Pricing Analysis
IE3-to-IE4 efficiency-class pricing gaps dominate procurement negotiations, with IE5 prototypes commanding substantial premiums over established IE4 wound-field designs. Pricing stratifies across premium, standard, and economy tiers based on IEC 60034 certification level and after-sales service bundling. Cost compression in standard-efficiency segments is intensifying because Chinese domestic manufacturers are flooding export markets with GB 18613-compliant alternatives. Mining and metals processors show least price sensitivity due to lifecycle contracting structures, while automotive component plants exhibit highest sensitivity amid electrification mandate compliance pressures.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are extending lead times for semiconductor-integrated brushless motor controllers sourced from Japanese and German power electronics specialists. Manufacturing concentrates in China, Germany, and the United States for wound-field stator and rotor assemblies. Copper wire and electrical steel laminations constitute critical input dependencies alongside neodymium for hybrid permanent magnet designs. Single-source vulnerability concentrates in IEC 60034 testing laboratory capacity clustered in Germany. Distribution runs through OEM direct procurement channels for rail traction and marine propulsion verticals, with industrial automation segments served by authorized distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IE5 efficiency-class commercialization represents a high-growth disruption as European Ecodesign Directive revisions and China's GB 18613-2024 draft mandate step-change performance thresholds. This regulatory inflection compresses technology adoption cycles and restructures competitive positioning across incumbent and entrant archetypes.
For Market Incumbents: Consolidate testing laboratory capacity to compress multi-standard certification timelines for simultaneous NEMA MG-1, IEC 60034, and GB 18613 qualification. Acquire captive winding production capabilities to offset copper cost volatility and technician skill scarcity threatening margin stability. Permanent magnet synchronous motor substitution in precision drive applications demands defensive positioning through brushless architecture integration partnerships.
For New Entrants and Emerging Players: Lead with marine propulsion electrification as the most penetrable vertical, where Norwegian and German shipbuilders specify separately excited motors for azimuth thruster applications with limited incumbent specialization. Target sensor-integrated predictive maintenance bundles for Australian and Canadian mining processors transitioning to lifecycle service contracting. Pursue robotics OEM integration through tailored brushless customization for East Asian articulated arm manufacturers.
For Investors and Strategic Acquirers: EU Green Deal implementation reshapes the acquisition landscape toward low-carbon winding production assets positioned for carbon-border adjustment mechanism compliance. Mid-scale European wound-field specialists with IEC 60034 testing depth represent prime consolidation targets over a five-to-ten year viability window. Monitor GB 18613 enforcement intensity in China as the signal indicating margin compression or expansion for export-oriented motor producers.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Laboratory Acquisition | Compresses NEMA MG-1 and IEC 60034 qualification timelines for multi-regional product launches. |
| Permanent Magnet Winding Integration Partnership | Enables brushless architecture development for rail traction OEMs specifying maintenance elimination. |
| Lifecycle Service Contracting Infrastructure | Captures recurring revenue from Australian mining processors purchasing availability guarantees. |
| Silicon Carbide Field Supply Development | Reduces filter mass for Japanese rail traction OEMs adopting higher switching frequencies. |
| Low-Carbon Winding Production Investment | Positions European manufacturers for carbon-border adjustment mechanism premium capture. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with maintenance directors at German steel rolling mills, OEM procurement teams in Chinese automotive plants, aftermarket service heads at European motor distributors, and marine propulsion engineers at Norwegian shipbuilders; alongside secondary validation through IEC 60034 testing laboratory disclosures, NEMA MG-1 revision documentation, GB 18613 regulatory filings, customs trade data for wound-field motor imports, and SEC filings from listed electrical equipment conglomerates. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Across the projection horizon, the analytical framework modeled segmentation dimensions including efficiency class tier, product architecture, end-use vertical, application duty cycle, and regional regulatory cluster. CAGRs derived from historical trajectory analysis adjusted for technology substitution elasticities and regulatory mandate implementation schedules. Forecast inputs incorporated semiconductor cost decline curves for brushless motor power electronics and carbon-border adjustment mechanism implementation probability assessments.
The analysis sits within stated boundaries; outcomes outside sustained factory electrification program funding levels, copper and rare-earth magnet price stability, and vocational technician pipeline recovery would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technology adoption S-curve positioning. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Electric Vehicle Motor (EVM) Controller Market
Electric Motor
Two Wheeler Electric Starter Magnet Market
Electric Motor
Europe Electric Commercial Vehicle Battery Pack Market
Electric Motor
Global Automotive Motor Market
Electric Motor
Traction Motors Market
Electric Motor
Electric Vehicle Motor Micro Controller Market
Electric Motor
Automotive in-Wheel Motors Market
Electric Motor
Europe Electric Motor Market
Electric Motor
Motorcycle Lead Acid Battery Market
Electric Motor
Intelligent Motor Controller Market
Electric Motor
EV Traction Motor Market
Electric Motor
Global Automotive Micro Motor Market
Electric Motor
Automotive Torque Actuator Motor Market
Electric Motor
Electric Vehicle Motor Control Unit Market
Electric Motor
Brazil Electrically Powered Hydraulic Steering Market
Electric Motor
Brush Motor Control Unit Market