
 Electric Vehicle Motor Shaft Market | 2026-2036
Electric Vehicle Motor Shaft Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Motor Shaft Market Insights
The EU's F-Gas Regulation is decoupling refrigerant-dependent cooling systems from motor thermal management, compelling shaft manufacturers to redesign hollow architectures for direct oil-cooling compatibility. GKN Automotive leverages its powder-forging expertise to sustain cost leadership in high-volume rotor shaft production. Robert Bosch GmbH anchors its position through integrated motor-shaft-inverter modules that reduce assembly complexity for passenger EV platforms. BYD Company Limited differentiates via captive vertical integration from rare-earth magnet sourcing through final shaft machining.
An electric vehicle motor shaft transmits torque between the rotor assembly and drivetrain while maintaining precise rotational alignment under electromagnetic and thermal loads, typically manufactured from induction-hardened medium-carbon steel or forged aluminum with surface tolerances below 5 micrometers to minimize NVH and bearing wear. Hollow shaft configurations now dominate premium passenger vehicle applications where unsprung mass reduction directly extends range, while solid shafts retain structural preference in commercial vehicle induction motor designs subjected to sustained peak torque. Permanent magnet motor technology leads value capture due to rare-earth magnet cost exposure, yet induction motor shafts in steel alloys occupy the fastest-growing material tier as OEMs seek supply chain de-risking.
The EPA's vehicle emissions standards and California's Advanced Clean Cars program shape North American demand by mandating zero-emission powertrains that require shaft designs validated to 500,000-mile durability cycles. China's GB standards for new energy vehicles and MIIT motor efficiency thresholds enforce domestic content ratios that redirect procurement toward local forging capacity. India's PLI scheme for automotive component manufacturing is building ancillary shaft-forging infrastructure adjacent to Tamil Nadu and Gujarat assembly clusters. Stakeholders must monitor how divergent thermal management regulations across these jurisdictions fragment platform standardization strategies.
Market Dynamics
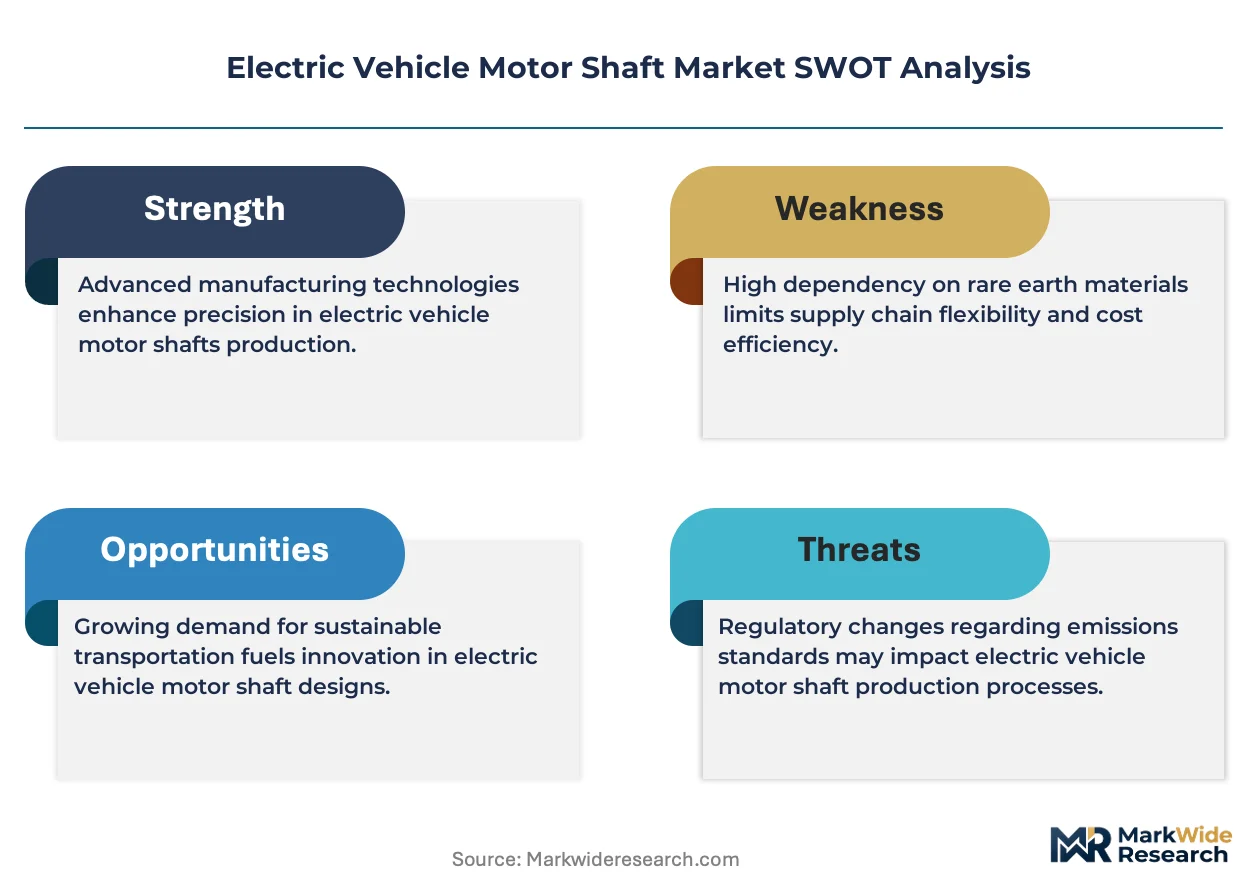
Hollow-shaft architectures are compressing material intensity per unit torque as fleet electrification mandates force redesign cycles below 24 months. The collision between rare-earth supply concentration and induction motor resurgence is fragmenting procurement strategies across passenger and commercial vehicle platforms.
Growth Catalysts
- EU F-Gas Regulation:Direct oil-cooling compatibility requirements in hollow-shaft designs are opening specification windows for forged aluminum suppliers serving German OEM assembly corridors.
- Commercial fleet electrification:High-torque motor shaft demand from logistics operators is accelerating as California's Advanced Clean Cars program mandates zero-emission powertrains for medium-duty vehicles.
- Powder-forging process maturation:Near-net-shape forming of rotor shafts is reducing machining waste and enabling hollow geometries previously uneconomical at volume scale.
Market Restraints
- Rare-earth magnet cost volatility:Permanent magnet motor shafts face input price instability from concentrated neodymium processing capacity in China's Jiangxi and Inner Mongolia refining corridors.
- Induction motor efficiency ceiling:Solid steel shafts in commercial vehicle applications confront thermal dissipation limits that constrain sustained peak torque duration below permanent magnet alternatives.
- Surface tolerance specification tightening:Sub-5-micrometer finishing requirements for NVH reduction are extending quality validation timelines and compressing supplier margins.
Strategic Opportunities
- India's PLI scheme:Automotive component manufacturing incentives are building shaft-forging infrastructure adjacent to Tamil Nadu and Gujarat EV assembly clusters, creating captive supply nodes for export markets.
- Integrated motor-shaft-inverter modules:Convergence of power electronics and mechanical transmission components is enabling assembly complexity reduction for passenger EV platforms.
- GB standards compliance services:China's MIIT motor efficiency thresholds and domestic content ratios are creating specification consulting demand for foreign suppliers seeking market access.
Industry Challenges
- Induction-hardening skill scarcity:Medium-carbon steel heat treatment expertise is concentrating among aging workforces in Germany's industrial corridor, constraining capacity expansion.
- 500,000-mile durability validation:EPA emissions-aligned testing protocols for commercial vehicle shafts are extending product development cycles and freezing design iterations.
- Platform standardization fragmentation:Divergent thermal management regulations across US, EU, and Chinese jurisdictions are preventing component reuse across regional vehicle programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Motor Shaft Market |
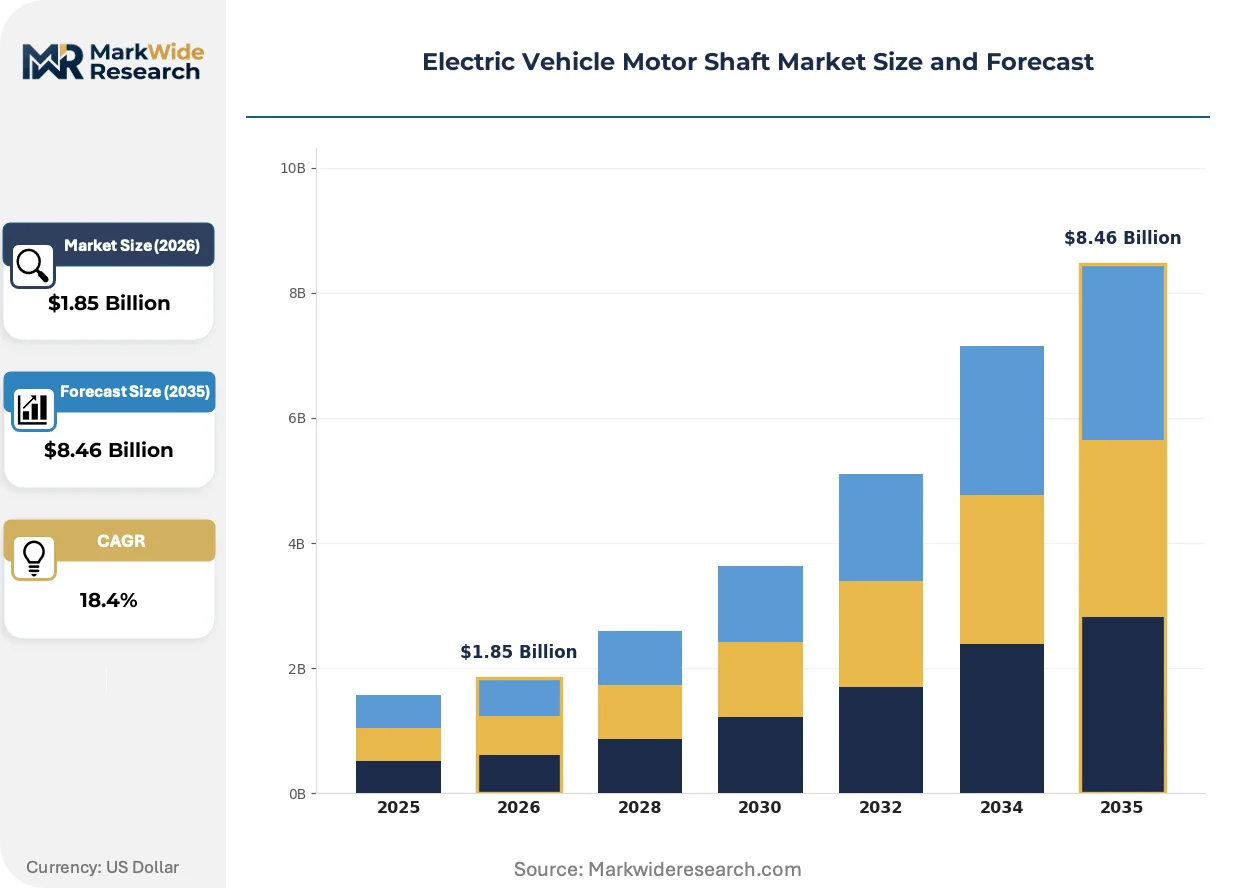
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $8.46 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotor Shaft, Stator Shaft, Hollow Shaft, Solid Shaft Material: Aluminum, Steel, Carbon Fiber, Composite Application: Passenger Vehicles, Commercial Vehicles, Buses, Two-Wheelers Technology: AC Motors, DC Motors, Permanent Magnet Motors, Induction Motors |
| Companies Covered | Tesla Inc., General Motors Company, Ford Motor Company, Volkswagen AG, BYD Company Limited, GKN Automotive, American Axle & Manufacturing, Robert Bosch GmbH, BorgWarner Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Motor Shaft Market Trends and Innovations
Material substitution and thermal management integration are compressing traditional shaft design paradigms. Three convergent developments are restructuring supplier capability requirements and buyer specification priorities.
Direct oil-cooling hollow shafts are consolidating thermal management functions previously handled by refrigerant-dependent systems. Passenger EV platforms in the 150-250 kW range are adopting these architectures to reduce unsprung mass and extend range. The technology is consolidating separate cooling loop components into the shaft housing itself, eliminating auxiliary hardware and assembly steps.
REACH substance restrictions and the EU F-Gas Regulation are eliminating hydrofluorocarbon-based cooling from motor thermal systems. Shaft manufacturers must redesign internal oil galleries and sealing interfaces to accommodate higher-temperature dielectric fluids. German Tier-1 suppliers are responding fastest, co-locating forging and precision machining to capture specification authority.
Fleet operators are compressing supplier qualification cycles from 18 months to 9 months as electrification mandates accelerate procurement timelines. Traditional three-tier supplier hierarchies are flattening as OEMs seek direct shaft-forging relationships to secure capacity. This behavior shift is most visible in North American commercial vehicle procurement, where EPA vehicle emissions standards are forcing rapid platform transitions.
Electric Vehicle Motor Shaft Market Segmentation
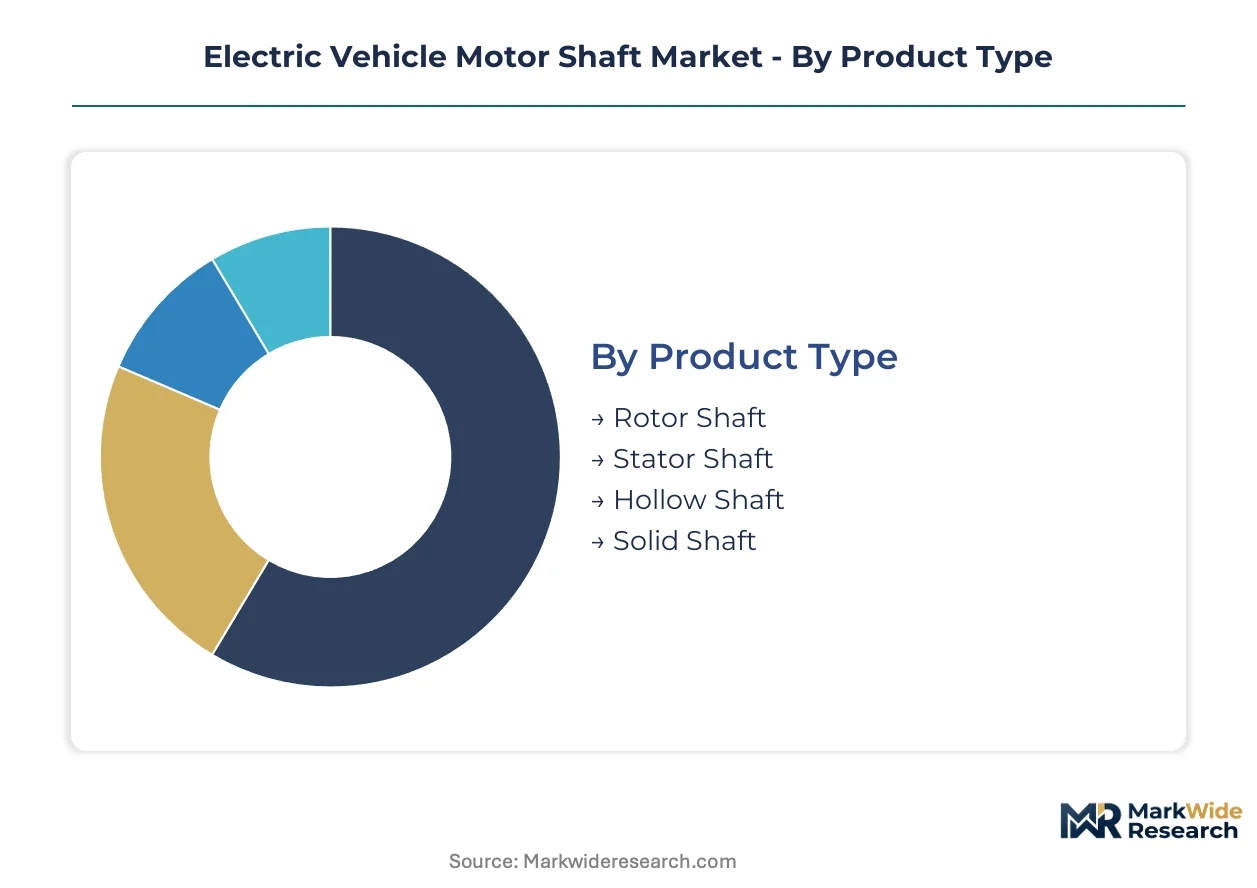
Shaft specification directly determines thermal management integration, mass reduction potential, and torque transmission efficiency across divergent EV powertrain architectures. Procurement strategies fragment along material-process boundaries as OEMs balance rare-earth exposure against induction motor efficiency ceilings.
Product Type:
Rotor-stator interface geometry and hollow-solid mass tradeoffs define the core engineering specification axis for motor shaft procurement.
- Hollow Shaft:Internal oil galleries enable direct cooling integration, eliminating refrigerant-dependent thermal loops. Demand concentrates in Germany's passenger EV corridor where GKN Automotive and Robert Bosch GmbH co-locate forging with precision machining to capture unsprung mass reduction specifications.
- Rotor Shaft:Powder-forged near-net-shape forming reduces machining waste while maintaining sub-5-micrometer surface tolerances critical for NVH performance. California's Advanced Clean Cars program is accelerating procurement from logistics operators seeking 500,000-mile durability validation.
- Solid Shaft:Structural preference persists in commercial vehicle induction motor designs subjected to sustained peak torque loads where thermal dissipation limits constrain hollow alternatives.
- Stator Shaft:Stationary housing component with lower rotational precision requirements, typically manufactured through conventional CNC machining rather than advanced forging processes.
Hollow shafts lead on scale; rotor shafts lead on momentum.
Material:
Alloy selection governs forging complexity, heat treatment protocols, and supply chain exposure to concentrated processing capacity.
- Steel:Induction-hardened medium-carbon grades dominate commercial vehicle applications requiring sustained peak torque durability. EPA vehicle emissions standards are extending validation cycles for solid shafts in North American medium-duty fleets.
- Aluminum:Forged aluminum hollow architectures enable direct oil-cooling compatibility mandated by EU F-Gas Regulation decoupling from hydrofluorocarbon refrigerants. German Tier-1 suppliers are consolidating specification authority through co-located forging and machining capacity.
- Carbon Fiber:Emerging ultra-lightweight option for premium passenger EV platforms where unsprung mass reduction directly extends range, constrained by cost and repairability limitations.
- Composite:Hybrid material systems combining fiber reinforcement with metallic cores for niche high-performance applications requiring exceptional stiffness-to-weight ratios.
Steel leads on scale; aluminum leads on momentum.
Application:
Vehicle duty cycle and electrification mandate timing create divergent specification priorities across end-use segments.
- Passenger Vehicles:150-250 kW platforms are adopting direct oil-cooling hollow shafts to consolidate thermal management functions. China's NEV credit system is forcing redesign cycles below 24 months as domestic OEMs compress supplier qualification timelines.
- Commercial Vehicles:High-torque solid shaft demand from logistics operators is accelerating as fleet electrification mandates tighten across major economies. India's PLI scheme is building shaft-forging infrastructure adjacent to Tamil Nadu and Gujarat assembly clusters.
- Buses:Transit authority procurement favors induction motor architectures with steel shafts to minimize rare-earth supply exposure in high-utilization fleet applications.
- Two-Wheelers:Cost-constrained segment prioritizing basic solid shaft designs with relaxed surface tolerance specifications compared to passenger vehicle tiers.
Passenger vehicles lead on scale; commercial vehicles lead on momentum.
Technology:
Motor topology determines shaft electromagnetic loading, thermal dissipation requirements, and rare-earth material exposure.
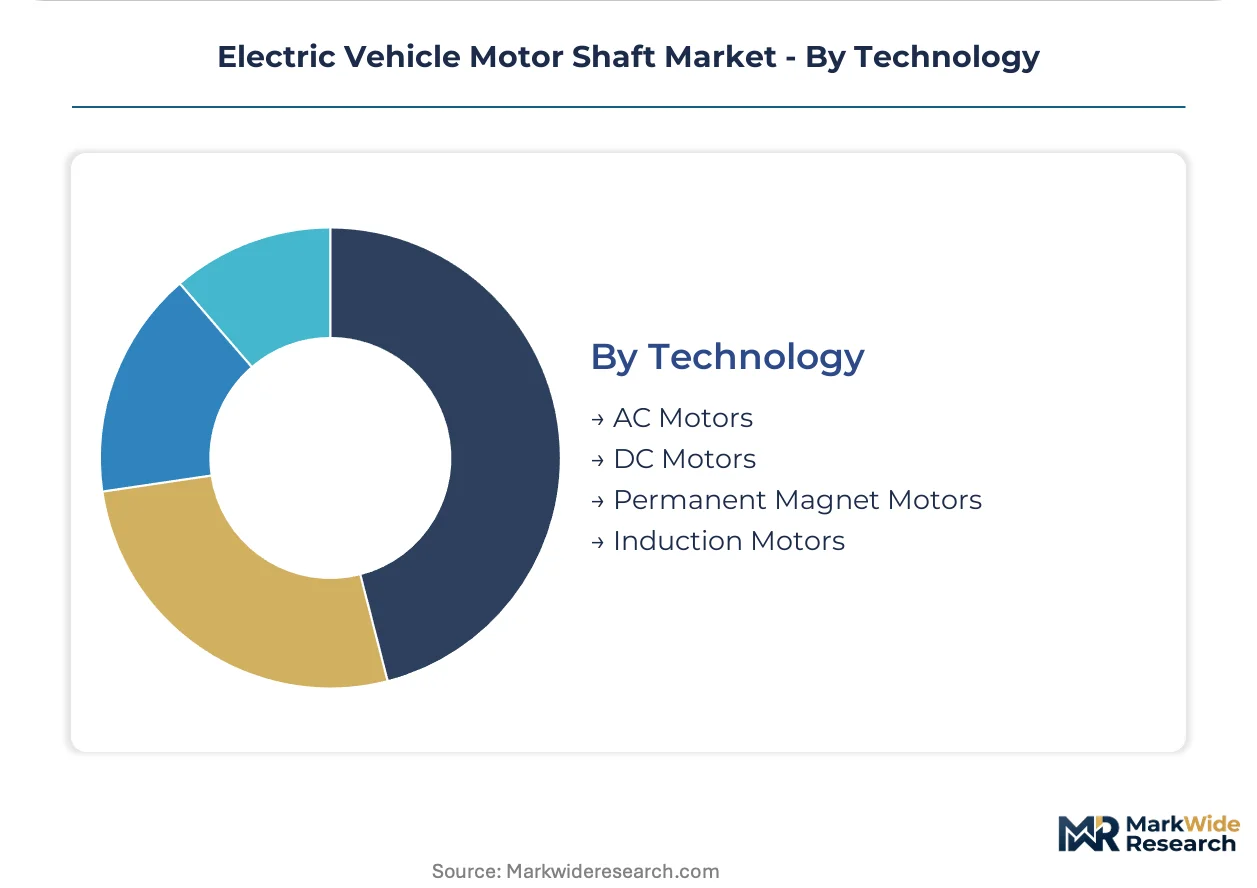
- Permanent Magnet Motors:Rare-earth magnet cost exposure concentrates value capture in this segment despite efficiency advantages. China's Jiangxi and Inner Mongolia refining corridors create input price instability that OEMs are seeking to de-risk through induction alternatives.
- Induction Motors:Solid steel shafts in commercial applications are climbing fastest as supply chain de-risking priorities displace permanent magnet dependence. GB standards and MIIT motor efficiency thresholds in China are redirecting procurement toward domestic forging capacity.
- AC Motors:Synchronous and asynchronous alternating current architectures requiring shaft designs validated to specific frequency and voltage operating envelopes.
- DC Motors:Declining share in mainstream automotive applications, persisting primarily in legacy conversions and specialized industrial vehicle adaptations.
Permanent magnet motors lead on scale; induction motors lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's aging induction-hardening workforce anchors European shaft-forging capacity, while Chinese rare-earth refining corridors and India's emerging PLI infrastructure reshape procurement geography across three continents.
Germany
Passenger EV platforms from BMW and Volkswagen drive hollow-shaft specifications for direct oil-cooling compatibility. The EU F-Gas Regulation mandates decoupling from hydrofluorocarbon refrigerants, forcing thermal management redesigns. Bavaria's industrial corridor concentrates GKN Automotive and Robert Bosch GmbH forging operations alongside precision machining capacity.
China
Domestic OEMs compress supplier qualification cycles below 24 months under NEV credit system pressure. MIIT motor efficiency thresholds and GB standards enforce domestic content ratios redirecting procurement toward Jiangxi and Inner Mongolia rare-earth processing clusters. Yangtze River Delta forging capacity expands to capture captive magnet-to-shaft vertical integration.
United States
Commercial fleet operators accelerate high-torque shaft procurement as California's Advanced Clean Cars program mandates zero-emission medium-duty powertrains. EPA vehicle emissions standards extend durability validation to 500,000-mile cycles. Michigan and Ohio assembly corridors attract Tier-1 forging investment for domestic medium-duty EV platforms.
India
Tamil Nadu and Gujarat EV assembly clusters drive ancillary shaft-forging infrastructure construction under the PLI scheme for automotive component manufacturing. Logistics operators pilot commercial vehicle electrification with induction motor architectures minimizing rare-earth exposure. Domestic forging capacity targets export market qualification alongside local OEM supply.
Electric Vehicle Motor Shaft Market Competitive Landscape
The competitive structure tilts toward integrated Tier-1 suppliers with captive forging and precision machining co-location. Three archetypes dominate: rare-earth-integrated Asian conglomerates, European precision-forging specialists, and North American drivetrain system integrators. Capacity expansion and strategic partnerships constitute the dominant competitive moves as OEMs flatten traditional supplier hierarchies.
Among Germany-based fabricators, Robert Bosch GmbH and GKN Automotive exemplify the precision-forging archetype through co-located operations serving passenger EV corridors. BYD Company Limited anchors the rare-earth-integrated tier with upstream magnet sourcing extending through final shaft machining. Tesla Inc. occupies a distinct position as a captive-demand OEM with in-house motor shaft specification authority.
| Leading Market Players |
|---|
| Tesla Inc. |
| General Motors Company |
| Ford Motor Company |
| Volkswagen AG |
| BYD Company Limited |
| GKN Automotive |
| American Axle & Manufacturing |
| Robert Bosch GmbH |
| BorgWarner Inc. |
| Others |
Pricing and Supply Chain Analysis
Captive upstream integration into rare-earth magnet sourcing and downstream shaft machining anchors pricing power for Asian conglomerates while European precision-forging specialists defend margin through co-located forging and finishing capacity adjacent to German OEM assembly corridors.
Pricing Analysis
Bundled shaft-inverter module sales command premium positioning against unbundled component procurement, with three-tier pricing structure across premium, standard, and economy levels differentiating on surface tolerance certification and thermal management integration depth. Cost compression in hollow aluminum shafts is intensifying because EU F-Gas Regulation compliance investments are concentrating specification authority among Tier-1 suppliers with captive forging capacity. Logistics operators exhibit highest price sensitivity due to 500,000-mile durability validation requirements extending total cost of ownership calculations, while premium passenger OEMs prioritize NVH performance over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from electrifying commercial fleets, while indirect distribution through Tier-2 component houses serves aftermarket and two-wheeler segments with lower volume thresholds. Supply concentrates in China's Jiangxi and Inner Mongolia rare-earth processing corridors, Germany's Bavarian industrial forging belt, and India's emerging Tamil Nadu-Gujarat shaft-forging clusters under PLI scheme incentives. Raw material dependencies draw from neodymium-iron-boron magnet feedstock, induction-hardened medium-carbon steel billets, and forged aluminum alloys. Single-source vulnerability in Chinese rare-earth refining creates structural risk exposure for permanent magnet motor shaft procurement strategies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA vehicle emissions standards and California's Advanced Clean Cars program are mandating zero-emission powertrain durability cycles that compress supplier qualification timelines and extend validation investment requirements.
For Market Incumbents: Anticipate induction motor resurgence threatening permanent magnet shaft volume by securing captive steel-forging capacity in India's PLI-subsidized Tamil Nadu corridor. Defend specification authority through co-located powder-forging and precision machining investments that reduce hollow-shaft production cost curves below 24-month redesign cycle pressure from China's NEV credit system. For New Entrants and Emerging Players: Capture commercial vehicle induction motor shaft demand from North American logistics operators facing EPA medium-duty electrification mandates. India's emerging Gujarat forging infrastructure presents the most penetrable geography for qualification against 500,000-mile durability protocols. Prioritize direct OEM relationships bypassing traditional three-tier supplier hierarchies flattened by accelerated procurement timelines. For Investors and Strategic Acquirers: Roll-up economics work for precision-forging specialists with captive heat-treatment expertise because Germany's aging induction-hardening workforce is constraining capacity expansion across the European supplier base. Five-to-ten year viability hinges on thermal management integration capabilities as direct oil-cooling architectures displace refrigerant-dependent systems. Monitor GB standards compliance service revenue as inflection signal for foreign supplier market access in China.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces hollow-shaft redesign costs across EU, US, and Chinese regulatory jurisdictions. |
| Battery Supply Agreement | Secures lithium-ion cell allocation for integrated motor-shaft-inverter module production. |
| Software-Defined Vehicle Investment | Enables predictive maintenance algorithms extending shaft durability validation cycles. |
| Geographic Manufacturing Footprint | Tamil Nadu and Gujarat capacity captures India's PLI scheme incentives for export qualification. |
| Charging Infrastructure Partnership | Aligns commercial fleet electrification timelines with high-torque shaft procurement cycles. |
Research Methodology
Bottom-up EV platform production modeling reconciled against top-down forging capacity tracking forms the analytical core, combining primary interviews with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and induction-hardening operations managers with secondary validation against EPA vehicle emissions filings, MIIT motor efficiency threshold disclosures, IHS Markit vehicle production databases, and EU F-Gas Regulation implementation guidance documents.
Input-output matrix framing connects rare-earth magnet price indices, steel alloy billet costs, and aluminum forging throughput rates to hollow-shaft, rotor-shaft, and solid-shaft volume projections across passenger vehicle, commercial vehicle, bus, and two-wheeler end-use segments. CAGRs derive from segment-level adoption curves and technology substitution dynamics, with permanent magnet versus induction motor topology mix serving as primary forecast sensitivity input alongside regulatory mandate timing across US, EU, and Chinese jurisdictions.
Regulatory enforcement delays, rare-earth supply disruption events, and induction-hardening workforce attrition are the dominant revision risks that could compress or extend the projection horizon. Periodic stress-testing of base assumptions against MIIT efficiency threshold updates and EPA durability protocol amendments is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Electric Vehicle Permanent Magnet Synchronous Motors Market
Electric Motor
Automotive ABS Motor Market
Electric Motor
Intelligent Motor Controller Market
Electric Motor
Implant Motors Market
Electric Motor
Trolling Motor Market
Electric Motor
Electric Vehicle Traction Motor Core Market
Electric Motor
Europe Electric Motor Market
Electric Motor
Electric Motor Sales Market
Electric Motor
Industrial Smart Motor Market
Electric Motor
Air Motor Market
Electric Motor
Power Tool Lithium Battery Market
Electric Motor
Outboard Electric Motors Market
Electric Motor
Global Automotive Odometer Stepping Motor Market
Electric Motor
Intelligent Motor Control Center Market
Electric Motor
France Alternating Current (AC) Motor Market
Electric Motor
UAE Electric Motor Market