
 Hub Drive Motor Market | 2026-2036
Hub Drive Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Hub Drive Motor Market Insights
Supplier consolidation toward in-house magnet and lamination production is consolidating procurement leverage across the hub motor value chain. Schaeffler Group anchors European precision manufacturing through captive stator winding operations in Germany. Robert Bosch GmbH leverages its automotive tier-one relationships to dominate OEM qualification cycles for integrated drive units. QS Motor competes on cost-engineered gearless architectures serving Asian electric two-wheeler brands.
A hub drive motor integrates the electric motor, reduction gearing, and braking hardware directly within the wheel hub, eliminating driveshafts and enabling flat-floor vehicle packaging with torque outputs typically ranging from 40 Nm to 1,500 Nm. Electric hub motors capture the largest volume share as bicycle and light EV OEMs prioritize unsprung weight reduction and simplified assembly. Brushless DC technology leads the technology split due to mature controller ecosystems and repair infrastructure, while permanent magnet synchronous motors represent the fastest-growing technology segment as automakers demand higher power density for passenger EV applications.
The EPA enforces motor efficiency standards under its ENERGY STAR framework for industrial equipment, while China's MIIT mandates GB/T efficiency tiers for drive motors used in new energy vehicles. The EU's F-Gas Regulation indirectly shapes thermal management choices in integrated hub units by restricting refrigerants used for motor cooling loops. Stakeholders must monitor how NHTSA evolving brake-by-wire standards will interface with hub motor regenerative braking architectures.
Market Dynamics
Axle architecture consolidation by electric vehicle OEMs is compressing supplier tiers and forcing motor manufacturers to absorb gearbox and brake integration functions previously handled by separate component specialists.
Growth Catalysts
- GB/T Efficiency Mandates:China's MIIT enforces tiered motor efficiency standards for new energy vehicles, compelling manufacturers to redesign winding configurations and magnetic circuits.
- Flat-Floor Packaging Demand:Light commercial vehicle OEMs specify hub motors to eliminate transmission tunnels and maximize cargo volume in electric vans.
- Suzhou-Tianjin Corridor Concentration:Magnet and lamination suppliers cluster around these manufacturing hubs, shortening procurement lead times for motor assemblers.
Market Restraints
- Neodymium Price Volatility:Permanent magnet raw material costs fluctuate with Chinese export quota policies, squeezing margin predictability for high-torque motor variants.
- Unsprung Weight Penalty:Hub motor mass concentrated at the wheel degrades ride quality and tire wear, limiting adoption in premium passenger vehicles.
- F-Gas Cooling Restrictions:The EU's F-Gas Regulation constrains refrigerant choices for liquid-cooled hub units, complicating thermal management system design.
Strategic Opportunities
- Indian Electric Two-Wheeler Expansion:PLI scheme subsidies for domestic EV manufacturing create localized demand for cost-optimized hub motor platforms.
- Regenerative-Brake-by-Wire Convergence:NHTSA evolving standards for brake-by-wire systems open integration contracts for hub motor suppliers with embedded braking hardware.
- Agricultural Robotics:Autonomous farm equipment manufacturers specify torque-dense hub motors for traction in variable terrain applications.
Industry Challenges
- Stator Winding Technician Scarcity:Precision coil winding for high-fill-factor motors requires skilled labor pools concentrated in Germany and Japan.
- OEM Qualification Cycle Duration:Automotive tier-one qualification protocols demand 18-24 month validation periods for integrated drive units.
- Cross-Domain IP Overlap:Motor control algorithms intersect with power electronics patents held by semiconductor suppliers, creating licensing friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hub Drive Motor Market |
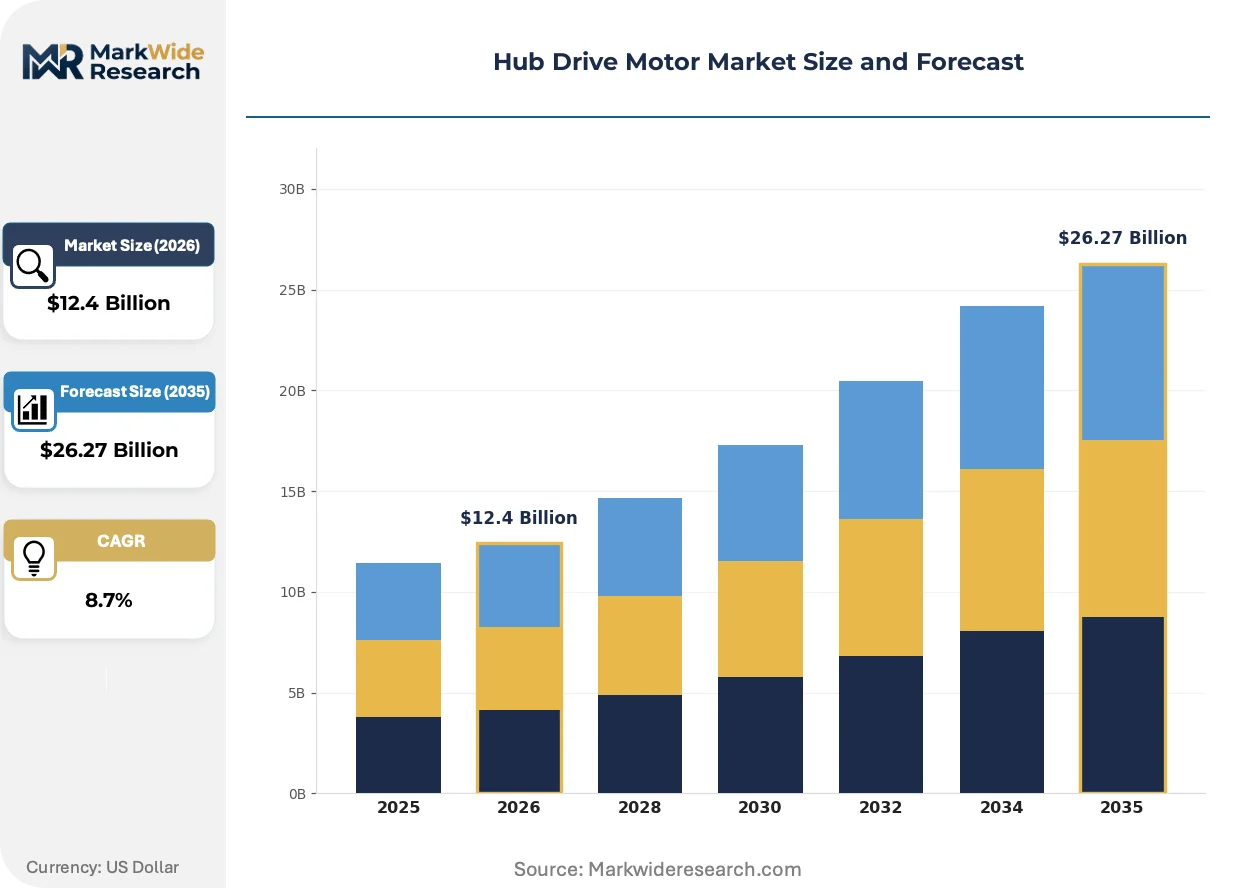
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $26.27 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Hub Motors, Mechanical Hub Motors, Integrated Drive Units, Gearless Hub Motors Application: Bicycles, E-scooters, Electric Vehicles, Load Carrying Robots End User: OEMs, Aftermarket Suppliers, Delivery Services, Fleet Operators Technology: Brushless DC, PMSM, Induction, Switched Reluctance |
| Companies Covered | QS Motor, Schaeffler Group, Robert Bosch GmbH, NTN Corporation, Elaphe Propulsion Technologies Ltd., Bafang Electric (Suzhou) Co., Ltd., Michelin, Protean Electric Ltd, Nidec Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hub Drive Motor Market Trends and Innovations
Power electronics miniaturization and silicon carbide inverter maturation are enabling motor controllers to migrate into the wheel hub itself, collapsing the traditional separation between drivetrain and power conversion subsystems.
Axial-flux motor topologies are decentralizing power delivery architectures in electric commercial vehicles. Daimler and Volvo Trucks specify pancake-style hub motors for urban delivery vans. This topology compresses axial length and enables direct wheel mounting without planetary reduction stages.
China's dual carbon policy framework is tightening embodied carbon accounting for motor manufacturing. MIIT rules now require disclosure of upstream magnet smelting emissions. Export-oriented suppliers in Ningbo and Shenzhen are retrofitting facilities with renewable electricity contracts to maintain EU market access under CBAM border adjustments.
Fleet procurement managers now specify total-cost-of-ownership contracts rather than unit-based motor purchasing. Leasing providers bundle hub motor maintenance into per-kilometer service agreements. This shift is most pronounced in European last-mile logistics, where DHL and Amazon contract operators demand uptime guarantees over component warranties.
Hub Drive Motor Market Segmentation
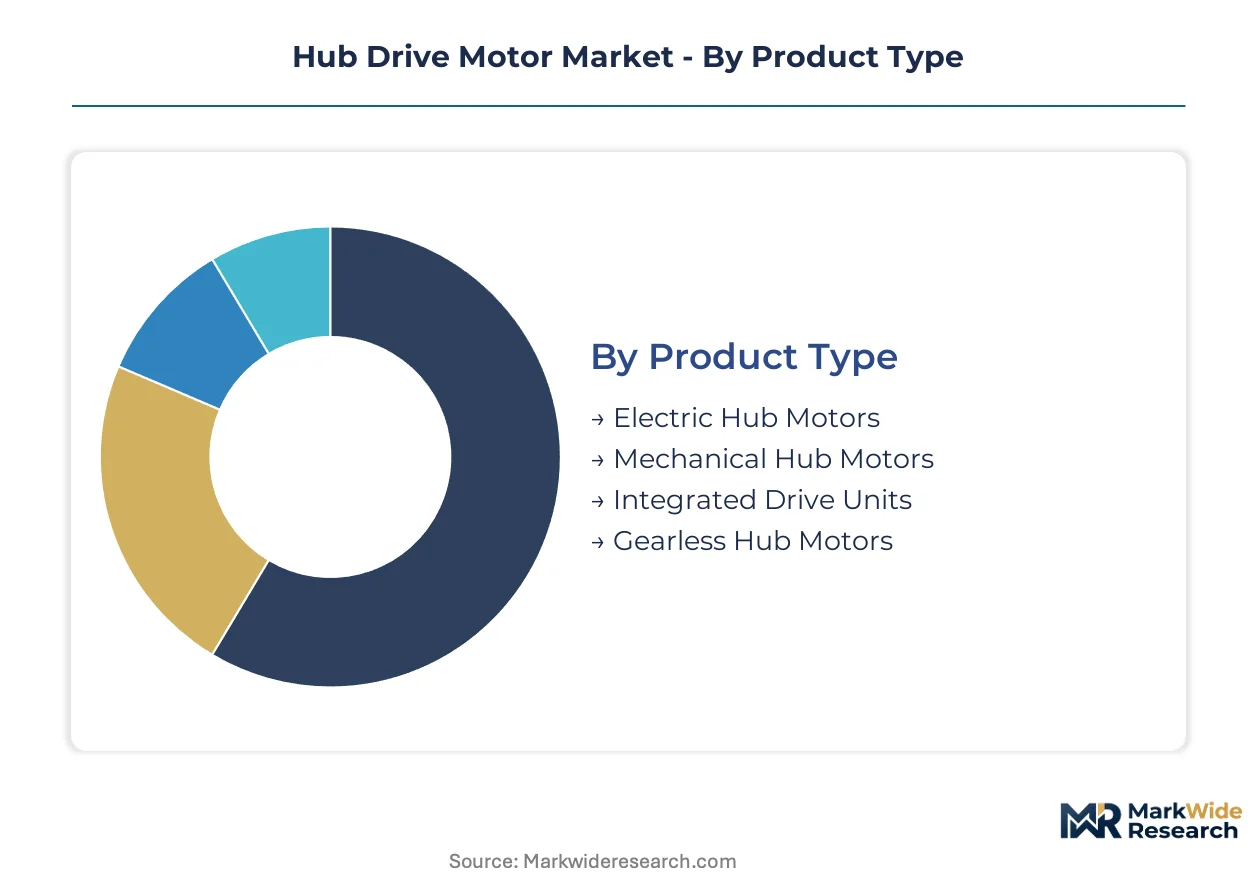
Hub drive motor procurement patterns diverge sharply across product architectures and end-use applications, with certification requirements varying from bicycle EN15194 compliance to automotive ISO 26262 functional safety. Understanding these segment boundaries clarifies where margin pools concentrate and which technical specifications gate market entry.
Product Type:
Certification burdens escalate from bicycle-grade EN15194 through automotive ISO 26262 and GB/T 18488 compliance, with each tier demanding distinct winding precision and thermal validation protocols.
- Electric Hub Motors:Brushless DC architectures dominate this segment, integrating rotor, stator, and Hall sensors within a sealed wheel-hub enclosure. Demand concentrates in Chinese electric two-wheeler OEMs supplying domestic and Southeast Asian markets, driven by GB/T efficiency mandates that disqualify lower-tier motor designs from new energy vehicle subsidies.
- Integrated Drive Units:These systems consolidate motor, planetary reduction, and brake hardware into a single wheel-mounted package. European light commercial vehicle manufacturers specify these for electric vans, prioritizing flat-floor cargo configurations and reduced assembly complexity at the OEM plant.
- Gearless Hub Motors:Direct-drive architectures eliminate mechanical reduction, trading torque multiplication for simplicity and reduced maintenance. Asian electric bicycle brands favor these for urban commuter models where weight and cost sensitivity outweigh acceleration performance.
- Mechanical Hub Motors:Brushed DC and early-generation permanent magnet designs persist in industrial material handling equipment and retrofit applications.
Electric hub motors sit at the top of the volume ranking, with integrated drive units climbing the fastest.
Application:
Application selection dictates thermal management requirements, with continuous-duty commercial vehicles demanding liquid cooling that bicycles and e-scooters avoid through intermittent duty cycles.
- Electric Vehicles:Passenger and commercial vehicle applications require ISO 26262 ASIL-D functional safety certification and NHTSA brake-by-wire compatibility. OEM qualification cycles extend 18-24 months, favoring suppliers with captive testing facilities in Germany and Japan.
- Bicycles:Pedelec and e-bike motors operate under lighter regulatory loads, primarily EN15194 mechanical safety and EMC compliance. European assembly plants in Portugal and Poland source these from Chinese suppliers to exploit cost-engineered magnet formulations.
- E-scooters:Shared mobility operators specify hub motors with enhanced sealing against water ingress and vandalism resistance. Indian and Southeast Asian fleet deployments drive volume here.
- Load Carrying Robots:Autonomous logistics platforms and agricultural equipment specify torque-dense variants with precise speed control for variable terrain traction.
Electric vehicle applications command the highest unit value, with load carrying robots expanding most quickly.
End User:
Procurement leverage varies dramatically across buyer types, with fleet operators extracting uptime guarantees that aftermarket channels cannot match.
- OEMs:Tier-one automotive and bicycle manufacturers impose qualification protocols, volume commitments, and engineering change control requirements. These buyers capture the largest share of integrated drive unit procurement.
- Fleet Operators:Last-mile delivery and logistics companies now specify total-cost-of-ownership contracts with per-kilometer maintenance bundling. DHL and Amazon contract operators in Europe demand 95% uptime guarantees.
- Aftermarket Suppliers:Independent distributors serve repair and retrofit demand, particularly for electric bicycle motor replacements in mature European markets.
- Delivery Services:Food and parcel delivery platforms in India and Southeast Asia procure cost-optimized hub motors through local assembly partners.
OEMs retain the dominant procurement position, with fleet operators gaining negotiating power fastest.
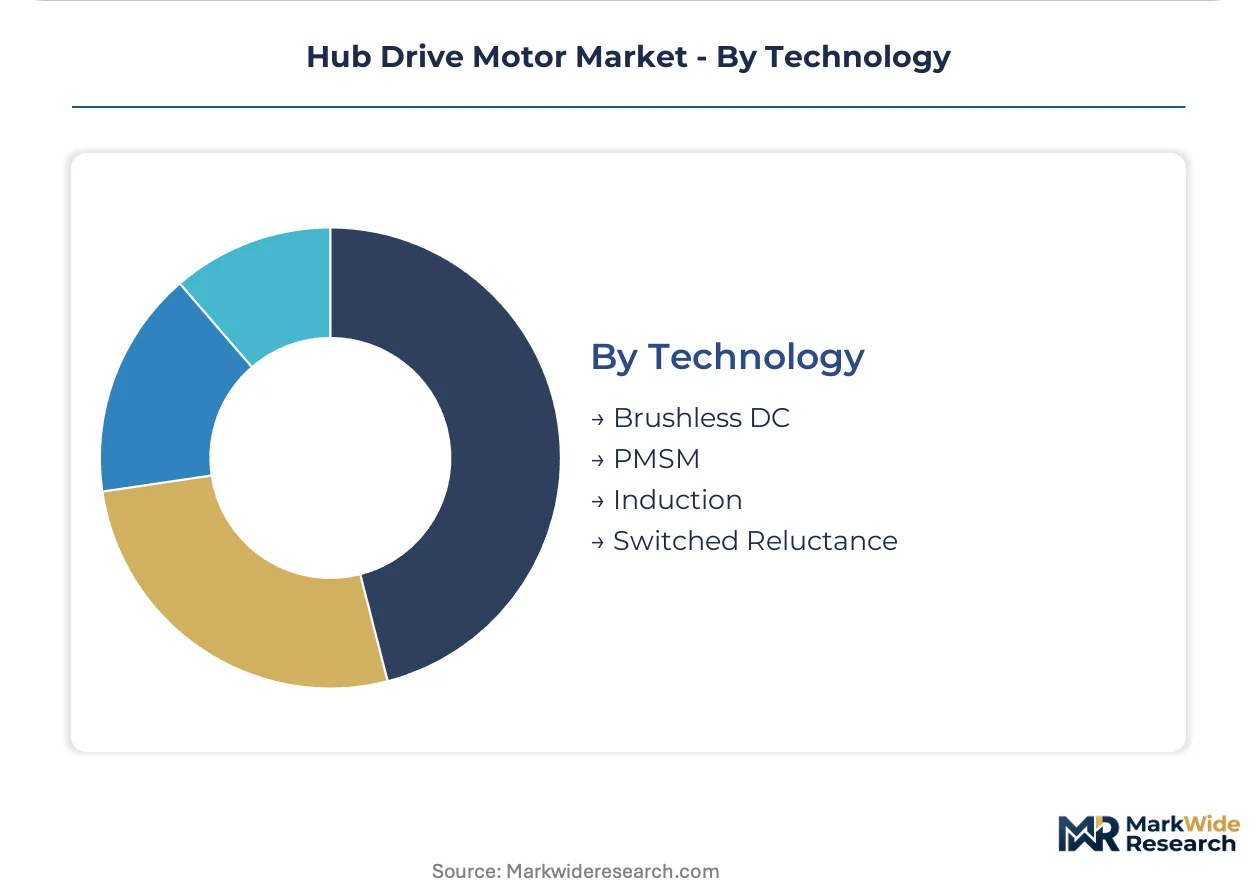
Technology:
Technology selection traces a direct path through controller ecosystem maturity and magnet supply security, with each topology presenting distinct trade-offs between power density and material risk.
- Brushless DC:Trapezoidal back-EMF designs with mature controller ecosystems dominate electric bicycle and light EV applications. Repair infrastructure and technician familiarity entrench this technology despite efficiency limitations.
- PMSM:Sinusoidal permanent magnet synchronous motors deliver superior power density and efficiency for passenger EV applications. Neodymium price volatility constrains adoption in cost-sensitive segments.
- Induction:Copper rotor designs eliminate rare earth dependencies, finding niche adoption in heavy commercial vehicles where weight penalties are acceptable.
- Switched Reluctance:Magnet-free architectures attract R&D investment for agricultural robotics and mining equipment where extreme temperature ranges degrade permanent magnet performance.
Brushless DC holds the volume lead, with PMSM gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Suzhou-Tianjin manufacturing corridor anchors production capacity for magnet and lamination supply chains serving hub motor assemblers across multiple end-use segments.
China
Domestic electric two-wheeler OEMs and light commercial vehicle manufacturers drive procurement volume as MIIT enforces GB/T 18488 efficiency tiers for new energy vehicle motors. The dual carbon policy framework tightens embodied carbon disclosure requirements for magnet smelting emissions. Ningbo and Shenzhen export-oriented suppliers retrofit facilities with renewable electricity contracts to preserve EU market access under CBAM border adjustments.
Germany
Automotive tier-one qualification protocols and captive stator winding operations concentrate precision manufacturing capability for integrated drive units. The KBA enforces type approval standards for brake-by-wire compatibility with hub motor regenerative architectures. Bavaria-based engineering centers validate motor designs for Daimler and Volvo Trucks urban delivery van specifications.
United States
Fleet operators in last-mile logistics specify total-cost-of-ownership contracts with uptime guarantees exceeding component warranties. The NHTSA evolves brake-by-wire standards that interface directly with hub motor regenerative braking systems. Midwest automotive supplier corridors around Detroit and Ohio host validation facilities for ISO 26262 ASIL-D functional safety certification.
India
Electric two-wheeler OEMs and food delivery platforms procure cost-optimized hub motor platforms as the PLI scheme subsidizes domestic EV manufacturing. The Bureau of Indian Standards develops motor efficiency benchmarks aligned with GB/T frameworks. Tamil Nadu and Gujarat assembly corridors attract magnet and lamination suppliers shortening procurement lead times for motor manufacturers.
Japan
Precision coil winding technician pools and automotive tier-one relationships sustain high-fill-factor motor production for passenger EV applications. METI oversees JIS standards harmonization with international efficiency protocols. Nagoya and Osaka industrial clusters maintain captive testing facilities compressing OEM qualification cycles for integrated drive units.
Hub Drive Motor Market Competitive Landscape
Global majors compete with regional champions across qualification cycle access and magnet supply security dimensions. The vendor base stratifies into three tiers: automotive tier-one suppliers with captive testing infrastructure, Asian cost-engineered specialists serving two-wheeler volume markets, and European precision manufacturers with backward integration into stator winding operations. Consolidation pressures intensify as axle architecture redesigns force motor manufacturers to absorb gearbox and brake integration functions. Strategic moves center on M&A for magnet supply security and capacity expansion around Suzhou-Tianjin corridor proximity.
Within the automotive tier-one tier, Robert Bosch GmbH and Schaeffler Group exemplify qualification-cycle dominance through European precision manufacturing footprints. QS Motor occupies a position among Asian cost-engineered specialists supplying gearless architectures to electric two-wheeler brands. These three anchors represent divergent competitive vectors: German engineering-intensive integration against Chinese volume-scale manufacturing.
| Leading Market Players |
|---|
| QS Motor |
| Schaeffler Group |
| Robert Bosch GmbH |
| NTN Corporation |
| Elaphe Propulsion Technologies Ltd. |
| Bafang Electric (Suzhou) Co., Ltd. |
| Michelin |
| Protean Electric Ltd |
| Nidec Corporation |
| Others |
Pricing and Supply Chain Analysis
Silicon carbide inverter maturation collapsing power electronics into wheel hubs simultaneously compresses controller costs and concentrates procurement leverage among integrated drive unit assemblers with captive winding operations. This technological consolidation reshapes both unit economics and supplier tier structures as motor manufacturers absorb functions previously handled by discrete component specialists.
Pricing Analysis
Neodymium magnet cost pass-through dominates pricing volatility for permanent magnet synchronous motor variants, with Chinese export quota policies directly squeezing margin predictability for high-torque applications. Three-tier pricing structure across premium, standard, and economy levels separates ISO 26262 ASIL-D certified automotive units from EN15194 bicycle-grade motors and industrial retrofit equipment. Cost compression in the economy tier intensifies as QS Motor and Bafang Electric compete on gearless architectures for Asian electric two-wheeler brands. Fleet operators in European last-mile logistics exhibit lowest price sensitivity due to total-cost-of-ownership contracting with uptime guarantees, while Indian food delivery platforms remain most price-sensitive.
Supply Chain Analysis
ISO 26262 and GB/T 18488 certification gating restricts qualified supplier pools to motor assemblers with captive testing facilities in Germany, Japan, and select Chinese engineering centers. Magnet and lamination supply concentrates in China, South Korea, and Japan, with the Suzhou-Tianjin corridor anchoring procurement lead times for East Asian manufacturing. Rare earth magnet smelting, copper winding wire, and silicon steel laminations constitute critical input dependencies. Single-source vulnerability in neodymium processing creates structural exposure to Chinese environmental compliance enforcement. Distribution runs through automotive tier-one qualification channels for integrated drive units and direct OEM procurement for electric bicycle motors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hub drive motor manufacturing presents a geographic-arbitrage play between China's MIIT efficiency mandates tightening domestic compliance costs and India's PLI scheme subsidies lowering effective production costs for export-oriented suppliers.
For Market Incumbents: Cement qualification-cycle dominance by expanding captive stator winding capacity in Bavaria and Nagoya industrial clusters before NHTSA brake-by-wire standards finalize. Absorb brake hardware integration functions to defend against axle architecture consolidation threatening discrete component suppliers. Prioritize backward integration into magnet supply through offtake agreements with Ningbo and Shenzhen smelters facing CBAM border adjustment pressure. For New Entrants and Emerging Players: Direct-to-fleet digital sales channels bypass tier-one automotive qualification barriers for last-mile logistics operators seeking per-kilometer maintenance bundling. Target Indian electric two-wheeler OEMs as the most penetrable segment given PLI scheme localization requirements and Bureau of Indian Standards efficiency benchmark development. Lead with cost-optimized gearless architectures validated for tropical climate sealing specifications. For Investors and Strategic Acquirers: Valuations sit cheapest among Asian cost-engineered specialists with Suzhou-Tianjin corridor proximity and unexploited European certification pathways. Long-term viability hinges on magnet supply security and thermal management IP for liquid-cooled integrated units. Monitor NHTSA brake-by-wire standard finalization as the inflection signal for regenerative braking integration contract awards.| Strategic Initiative | Industry Significance |
|---|---|
| Magnet Supply Backward Integration | Captive neodymium offtake insulates margin from Chinese export quota volatility. |
| Brake-by-Wire Certification Investment | Early KBA and NHTSA validation secures regenerative braking integration contracts. |
| Axial-Flux Topology R&D Expansion | Pancake motor development captures Daimler and Volvo Trucks urban van specifications. |
| Indian PLI Scheme Manufacturing Footprint | Tamil Nadu assembly localization exploits subsidy structures for two-wheeler export growth. |
| Fleet Operator TCO Contracting | Per-kilometer service agreements with DHL and Amazon operators lock in recurring revenue streams. |
Research Methodology
Multiple input streams — motor procurement directors at European automotive OEMs, stator winding technicians in German and Japanese precision manufacturing facilities, MIIT policy researchers, and fleet operations managers at last-mile logistics providers — were reconciled against customs records for magnet and lamination trade flows, GB/T standard disclosure filings, SEC 10-K supply chain disclosures from tier-one automotive suppliers, and IHS Markit electric vehicle production databases. Bottom-up unit shipment estimates by motor topology and application were cross-validated against top-down OEM platform engineering specifications.
Historical capacity utilization patterns across the Suzhou-Tianjin corridor were cross-referenced against panel input from procurement leads regarding qualification cycle durations and engineering change control frequencies. The forecast framework models segmentation across vehicle class, propulsion architecture, certification tier, and regional production cluster. CAGRs were derived from installed base replacement cycles and OEM platform rollout schedules. Industry-specific inputs include MIIT subsidy eligibility thresholds and NHTSA regulatory pathway assumptions for brake-by-wire integration.
The model assumes a particular technology adoption path; alternative pathways for switched reluctance magnet-free architectures would alter the outlook if rare earth price volatility exceeds modeled thresholds. Forecasts reflect assumptions regarding GB/T efficiency tier enforcement consistency and PLI scheme subsidy continuity. A model refresh is warranted upon material change in NHTSA brake-by-wire standard finalization or Chinese dual carbon policy implementation stringency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Traction Motors Market
Electric Motor
Automotive Electric Commutators Market
Electric Motor
Power Tool Lithium Battery Market
Electric Motor
Automotive Wiper Motor Market
Electric Motor
EV Traction Motor Control Unit Market
Electric Motor
UAE Electric Motor Market
Electric Motor
Automotive Induction Motors Market
Electric Motor
Global Automotive Micro Motor Market
Electric Motor
Frameless Motor Market
Electric Motor
High Speed Motor Market
Electric Motor
Intelligent Motor Control Center Market
Electric Motor
Global Automotive Onboard Charger Market
Electric Motor
Traction Motor Core Market
Electric Motor
Outboard Electric Motors Market
Electric Motor
Automotive Traction Motor Market
Electric Motor
Electric Drives Market