
 Implant Motors Market | 2026-2036
Implant Motors Market Size, Share, and Industry Trends Forecast 2026-2036
Implant Motors Market Insights
Dental technician training pipelines is reorganizing how manufacturers scale production capacity across Europe and Asia-Pacific. KaVo leverages its heritage in precision handpiece engineering to sustain premium positioning in high-torque systems. NSK anchors Japanese manufacturing standards while competing on brushless motor miniaturization for surgical applications.
Implant motors are electromechanical drive systems engineered to deliver controlled rotational speeds between 5 and 40 RPM with torque outputs up to 80 Ncm, primarily powering surgical drilling and osteotomy procedures in implantology and orthopedic fixation. Brushless motors command the widest installed base due to thermal efficiency and reduced maintenance cycles, while piezoelectric technology captures fastest-growing interest for bone-cutting applications requiring micron-level precision without thermal necrosis. Dental application generates the dominant revenue pool, though orthopedic demand is deepening as ambulatory surgery centers expand motor-assisted joint reconstruction.
FDA 510(k) clearance pathways and the EU Medical Device Regulation shape product development timelines and clinical evidence requirements for implant motor manufacturers seeking market access. ISO 13485 quality management certification functions as a baseline qualifier for supplier qualification by hospital procurement departments. Stakeholders must weigh regulatory divergence between FDA's predicate-based system and EMA's stricter clinical evaluation mandates when prioritizing geographic launch sequencing.
Market Dynamics
Brushless motor architectures are compressing maintenance cycles while EU MDR certification timelines are elongating product launch windows, creating a squeeze between technical capability and market access velocity.
Growth Catalysts
- EU MDR clinical evidence mandates:Stricter post-market surveillance requirements are filtering out marginal suppliers and consolidating procurement decisions around ISO 13485-certified manufacturers with established clinical data repositories.
- Ambulatory surgery center expansion:Same-day joint reconstruction protocols in the United States are multiplying motor-assisted orthopedic procedure volumes beyond traditional hospital settings.
- Piezoelectric bone-cutting systems:Micron-level precision without thermal necrosis is capturing interest from oral surgeons performing complex osteotomies near critical anatomical structures.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and samarium-cobalt sourcing dependencies on Chinese processing infrastructure create input cost volatility and geopolitical exposure for brushless motor producers.
- EMA clinical evaluation stringency:The EU's stricter evidence requirements compared to FDA's predicate-based pathway are extending certification timelines by 12-18 months and inflating regulatory compliance budgets.
- Manual surgical instrument persistence:Cost-conscious dental clinics in emerging markets continue favoring conventional handpieces for routine implant placements, limiting addressable market expansion.
Strategic Opportunities
- India's medical device PLI scheme:Production-linked incentives for domestic manufacturing are attracting component suppliers to establish brushless motor assembly capacity near Mumbai-Pune pharmaceutical corridors.
- Orthopedic robotics integration:Convergence of haptic feedback systems with high-torque implant motors is opening surgical navigation partnerships for next-generation joint reconstruction platforms.
- Direct-to-clinic digital distribution:Bypassing traditional dental dealer networks through manufacturer-owned e-commerce portals is capturing price-sensitive independent practitioners in Spain and Italy.
Industry Challenges
- Mechatronics engineering scarcity:Cross-functional expertise combining motor control algorithms with surgical ergonomics remains concentrated among German and Japanese technical universities, constraining R&D team scaling.
- Legacy handpiece compatibility:Ambulatory surgery centers face integration complexity when retrofitting existing surgical towers with next-generation motor systems requiring modified foot pedal interfaces.
- ISO 13485 audit backlogs:Certification body capacity constraints are delaying quality management system renewals and freezing new product submissions for mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Implant Motors Market |
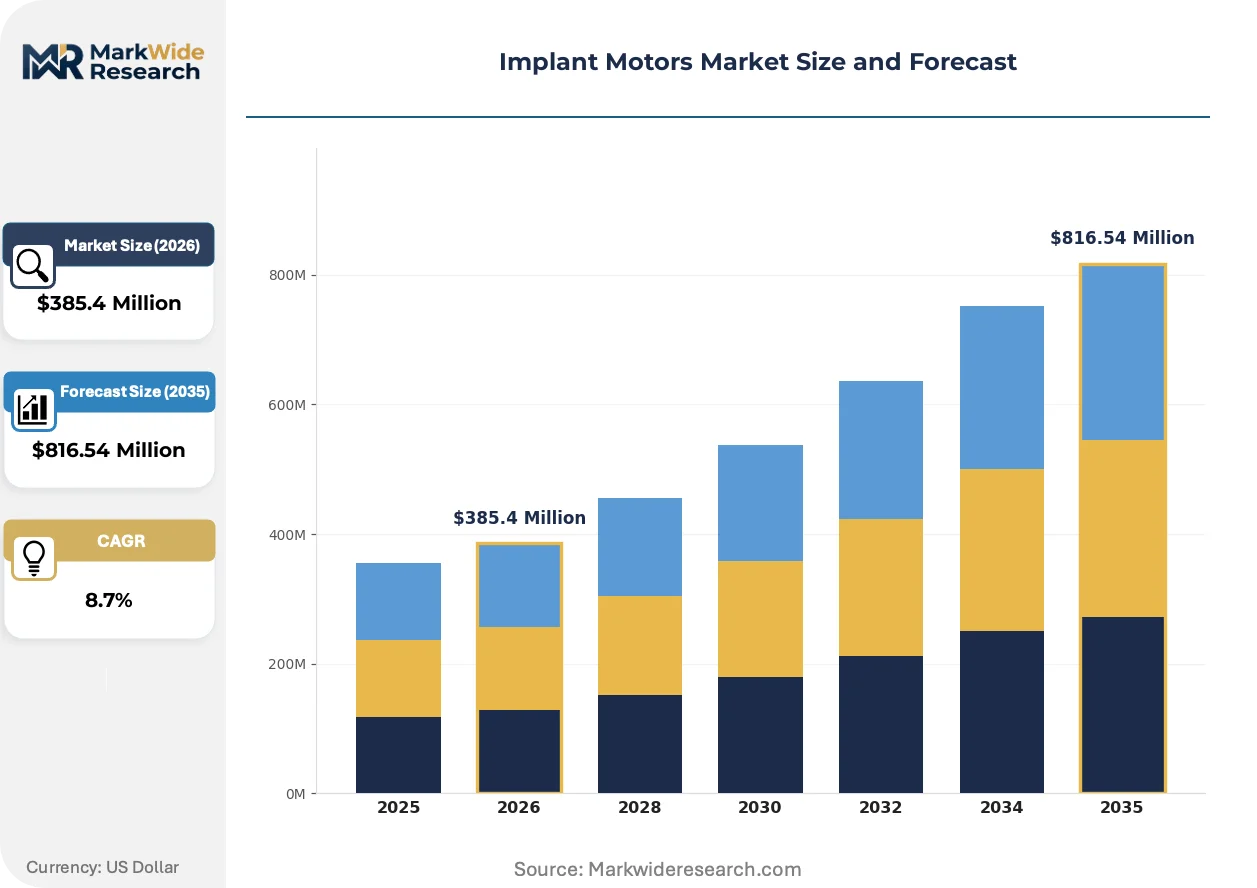
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DC Motors, Stepper Motors, Brushless Motors, Servo Motors End User: Hospitals, Research Laboratories, Clinics, Dental Practices Technology: Magnetic, Optical, Electromechanical, Piezoelectric Application: Orthopedic, Cardiac, Neurological, Dental |
| Companies Covered | KaVo, W&H Dentalwerk Bürmoos, NSK, Saeshin Precision, Bien-Air Dental, Aseptico, Anthogyr, Nouvag, Acteon Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Implant Motors Market Trends and Innovations
Piezoelectric ultrasonic systems are carving distinct positioning in bone surgery while regulatory divergence between FDA and EMA pathways is forcing geographic launch sequencing recalibration. Procurement behaviors are simultaneously fragmenting across channel types.
Brushless DC motor technology with integrated torque feedback is displacing brushed universal motor architectures in premium surgical handpieces. German dental manufacturers are adopting these systems fastest, driven by EU MDR reliability documentation requirements. The shift is compressing aftermarket service revenue pools while elevating initial equipment price points.
EU MDR's Unique Device Identification mandates and enhanced post-market surveillance obligations are restructuring clinical evidence portfolios for implant motor manufacturers. Companies must now maintain active implant registries rather than relying on predicate device equivalence. German notified bodies are experiencing the steepest audit queue growth, delaying CE mark acquisitions for novel torque-sensing handpieces.
Hospital procurement departments are unbundling after-sales service contracts from capital equipment purchases, forcing motor manufacturers to price maintenance separately. Independent service organizations are capturing calibration and repair volumes previously held by original equipment manufacturers. This pattern is most visible in French and Italian public hospital systems where tender regulations favor multi-vendor maintenance frameworks.
Implant Motors Market Segmentation
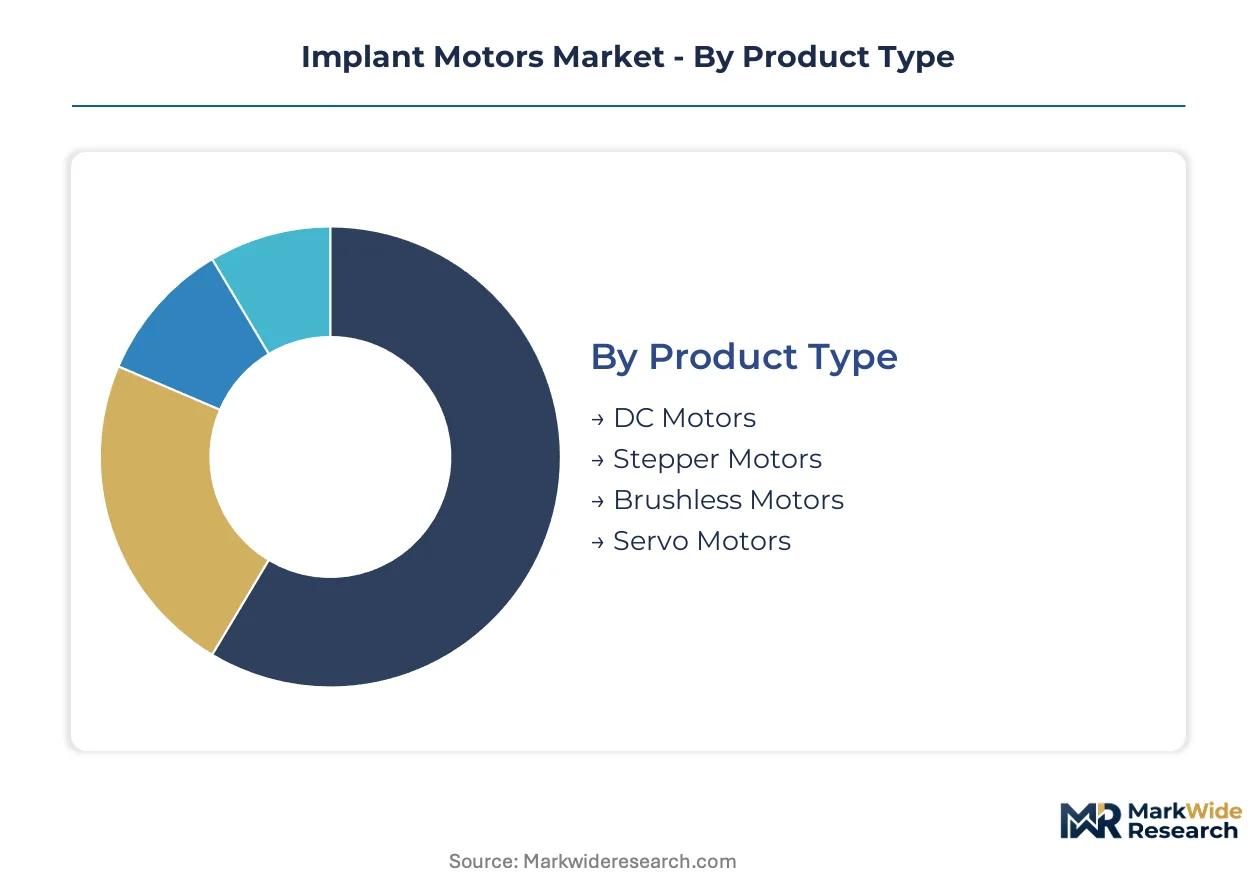
Implant motor manufacturers face divergent engineering requirements across surgical disciplines, forcing portfolio decisions between high-torque orthopedic systems and miniaturized dental handpieces. Segmentation clarity determines which technical specifications warrant R&D investment versus licensed component sourcing.
Product Type:
Brushless architectures face substitution pressure from piezoelectric alternatives in precision bone-cutting applications, while DC motor incumbents defend cost-sensitive entry segments.
- Brushless Motors:Electronically commutated architectures eliminate brush wear and thermal losses, sustaining 40,000+ hour service intervals. German dental manufacturers specify these for EU MDR reliability documentation requirements in torque-sensing handpieces.
- DC Motors:Brushed universal designs dominate price-sensitive emerging market clinics where maintenance infrastructure remains limited. Indian procurement tenders favor these for district hospital implantology suites under production-linked incentive frameworks.
- Stepper Motors:Discrete angular positioning suits robotic surgical navigation systems requiring repeatable osteotomy trajectories.
- Servo Motors:Closed-loop torque feedback integration enables haptic-enabled orthopedic robotics partnerships.
Brushless motors anchor the volume base while servo motor configurations gain share at the steepest rate through robotics integration partnerships.
End User:
Procurement authority fragmentation creates margin tiering: hospital systems negotiate enterprise pricing while independent dental practices pay list price for identical torque specifications.
- Dental Practices:Solo and group practices generate the dominant equipment refresh cycle, with German manufacturing corridors supplying precision handpieces to EU and Asia-Pacific markets. EU MDR compliance costs are consolidating procurement around ISO 13485-certified suppliers with established service networks.
- Hospitals:Integrated delivery networks bundle implant motors into orthopedic service line contracts, with French and Italian public systems unbundling maintenance from capital purchases through multi-vendor tender frameworks.
- Clinics:Ambulatory surgery centers in the United States are expanding motor-assisted joint reconstruction volumes beyond traditional hospital settings.
- Research Laboratories:Academic medical centers prototype next-generation torque feedback algorithms for surgical navigation platforms.
Dental practices anchor the volume base while ambulatory surgery centers gain share at the steepest rate through same-day joint reconstruction protocol expansion.
Technology:
Actuation mechanism selection determines thermal management requirements and precision thresholds across bone-cutting versus soft-tissue applications.
- Piezoelectric:Ultrasonic frequency oscillation cuts bone without rotational thermal necrosis, capturing oral surgeon interest for osteotomies near inferior alveolar nerves and maxillary sinuses.
- Electromechanical:Conventional rotary systems retain installed base dominance through instrument compatibility and technician familiarity.
- Magnetic:Contactless torque transmission reduces sterilization vulnerability in reusable handpiece designs.
- Optical:Encoder-based position feedback enables micron-level trajectory verification in robotic-assisted procedures.
Electromechanical systems anchor the volume base while piezoelectric configurations gain share at the steepest rate through complex osteotomy adoption.
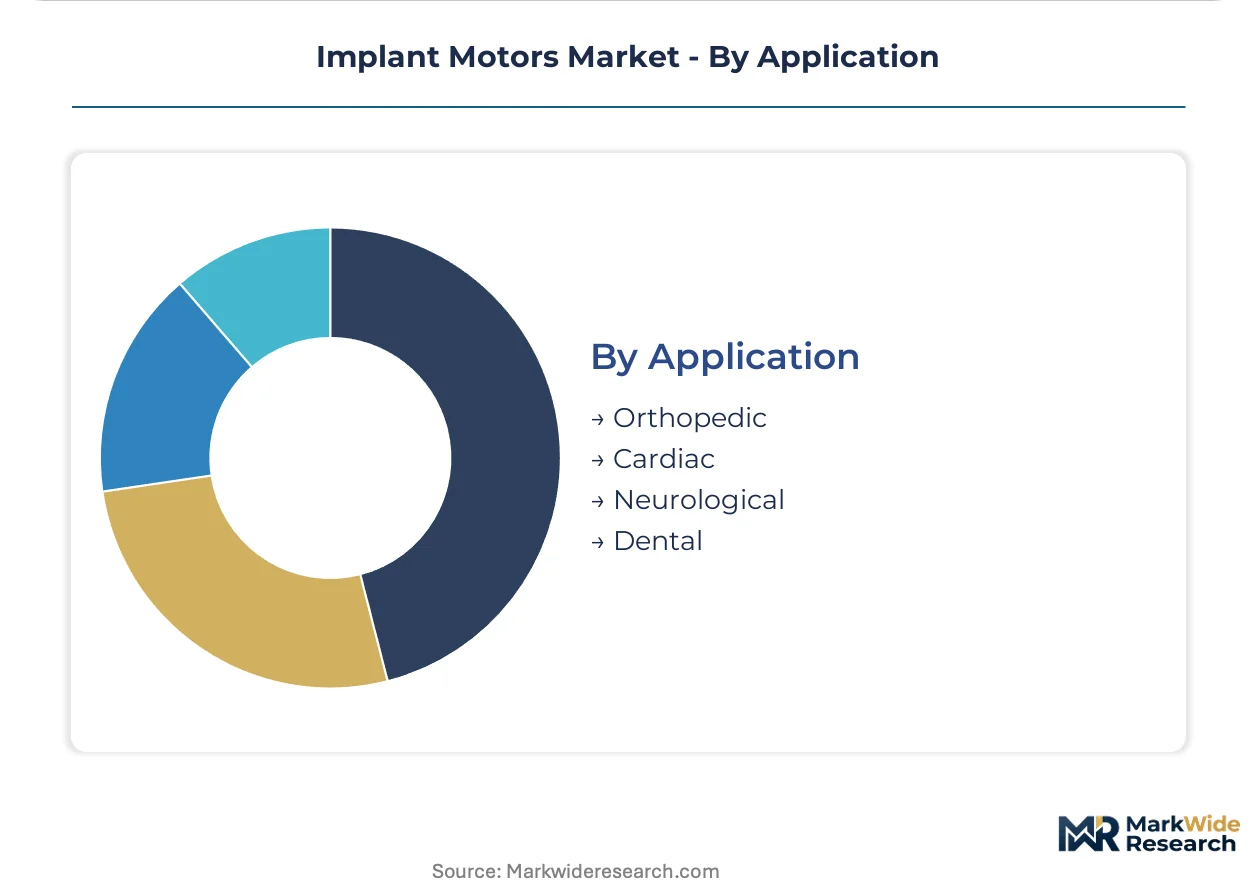
Application:
Surgical discipline dictates torque range, speed profile, and sterilization cycle requirements, creating distinct specification clusters.
- Dental:Implantology and oral surgery procedures require 5-40 RPM with 80 Ncm peak torque, with brushless miniaturization enabling ergonomic handpiece weights under 250 grams for extended procedures.
- Orthopedic:Joint reconstruction and trauma fixation demand higher torque outputs with haptic feedback integration for robotic navigation platforms in United States ambulatory settings.
- Neurological:Cranial fixation and spinal procedures require sub-millimeter positioning accuracy with electromagnetic interference shielding.
- Cardiac:Pacemaker and ICD lead placement utilize micro-motor systems for transvenous navigation.
Dental applications anchor the volume base while orthopedic applications gain share at the steepest rate through ambulatory surgery center expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways anchor the United States as the primary regulatory benchmark for implant motor manufacturers seeking rapid market entry, while EU MDR compliance timelines reshape competitive positioning across European manufacturing corridors.
United States
Ambulatory surgery centers in Texas and Florida are expanding same-day joint reconstruction protocols that require motor-assisted orthopedic systems. FDA maintains predicate-based clearance pathways that compress launch timelines relative to European counterparts. Minneapolis and Boston surgical device clusters host prototyping facilities for next-generation torque feedback platforms.
Germany
Dental manufacturing corridors around Stuttgart and Leipzig concentrate precision handpiece engineering capacity for EU and export markets. EU MDR notified bodies in Berlin and Munich are experiencing steep audit queue growth that delays CE mark acquisitions. Bavarian technical universities supply mechatronics engineering talent for brushless motor R&D teams.
Japan
PMDA marketing authorization requirements align with METI industrial standards for surgical device miniaturization. Tokyo and Osaka metropolitan areas host component suppliers specializing in rare earth magnet processing for brushless architectures. Japanese manufacturers compete on brushless motor miniaturization for surgical applications requiring ergonomic handpiece weights.
India
Production-linked incentive schemes under the CDSCO regulatory framework are attracting brushless motor assembly capacity near Mumbai-Pune pharmaceutical corridors. District hospital procurement tenders favor DC motor systems for cost-sensitive implantology suites. Karnataka and Telangana medical device parks offer tax incentives for component localization.
Switzerland
Swissmedic certification requirements for high-reliability surgical instruments sustain premium positioning for precision motor systems. Basel and Zurich clusters concentrate orthopedic robotics integration partnerships requiring haptic feedback capabilities. Swiss dental laboratories drive demand for piezoelectric bone-cutting systems in complex osteotomy procedures.
Implant Motors Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that competes on technical differentiation and regional service networks. The upper tier commands premium positioning through ISO 13485-certified quality systems and established clinical data repositories. Three archetypes populate the competitive map: heritage precision engineering houses with dental handpiece lineages, Japanese manufacturers leveraging miniaturization capabilities, and emerging Asia-Pacific fabricators exploiting production-linked incentive schemes. Consolidation pressure is mounting through M&A activity targeting torque-sensing technology assets, while geographic expansion into Indian manufacturing corridors accelerates among brushless motor producers seeking supply chain resilience.
Within the heritage engineering tier, KaVo and W&H Dentalwerk Bürmoos occupy positions anchored in German precision handpiece manufacturing traditions. NSK represents Japanese manufacturing standards while competing on brushless motor miniaturization for surgical applications requiring micron-level precision. These three exemplify how geographic origin and technical specialization archetypes determine competitive positioning rather than scale alone.
| Leading Market Players |
|---|
| KaVo |
| W&H Dentalwerk Bürmoos |
| NSK |
| Saeshin Precision |
| Bien-Air Dental |
| Aseptico |
| Anthogyr |
| Nouvag |
| Acteon Group |
| Others |
Pricing and Supply Chain Analysis
Piezoelectric actuation's displacement of conventional brushless architectures in precision osteotomy applications is simultaneously shifting component sourcing toward Japanese and Swiss specialty suppliers while compressing price premiums for thermal-efficient rotary systems. This substitution dynamic reconfigures procurement economics across dental and orthopedic equipment tiers.
Pricing Analysis
Long-term offtake contracts dominate procurement between German dental manufacturers and rare earth magnet processors, insulating premium brushless motor producers from spot-market volatility in neodymium pricing. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified torque-sensing systems from DC motor alternatives in Indian district hospitals and unbranded handpieces in Southeast Asian clinics. Cost compression in the standard tier is intensifying because EMA clinical evaluation timelines are extending working capital cycles for mid-tier manufacturers. Independent dental practices in Southern Europe exhibit the highest price sensitivity, while United States ambulatory surgery centers prioritize haptic feedback integration over unit economics.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg ports constrain just-in-time delivery schedules for Stuttgart-area dental manufacturing clusters dependent on Taiwanese semiconductor components for motor control systems. Brushless motor assembly draws from Chinese rare earth processing, Japanese precision bearing fabrication, and German mechatronics integration. Supply chain risk centers on single-source vulnerability for samarium-cobalt magnets processed through Chinese state-owned enterprises. Distribution runs through authorized dental dealer networks in Europe, direct-to-clinic portals in Mediterranean markets, and orthopedic service line contracts with United States integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The implant motors market is recovering from regulatory cycle compression, with EU MDR audit queue clearing and FDA predicate pathway stability restoring normalized product launch velocity. Equipment refresh demand from ambulatory surgery center expansion provides cyclical momentum.
For Market Incumbents: Secure exclusive supply agreements with Japanese rare earth magnet processors to buffer against Chinese export restriction scenarios. Capture calibration and repair volumes through captive service networks before independent service organizations consolidate French and Italian public hospital maintenance contracts. Invest in mechatronics engineering pipelines at Bavarian technical universities to counter talent scarcity constraining R&D scaling.
For New Entrants and Emerging Players: Lead with piezoelectric bone-cutting specialization targeting oral surgeons performing complex maxillofacial procedures near critical anatomical structures. India's production-linked incentive schemes offer the most penetrable manufacturing footprint for brushless motor assembly capacity. Deploy direct-to-clinic digital distribution to bypass entrenched dealer networks in price-sensitive Spanish and Italian independent practices.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed dental equipment platforms seeking torque-sensing technology tuck-ins to complete robotics integration roadmaps. Long-term viability hinges on regulatory compliance infrastructure rather than unit volume scale. Watch EMA audit queue duration as the inflection indicator for European market access velocity normalization.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | German notified body relationships compress EU MDR certification timelines for novel torque-sensing handpieces. |
| Hospital System Partnership | United States ambulatory surgery center alliances secure orthopedic robotics integration slots ahead of navigation platform consolidation. |
| Backward Integration into Rare Earth Magnet Supply | Captive neodymium sourcing buffers brushless motor producers against Chinese processing infrastructure volatility. |
| Software Companion Development | Torque feedback algorithm integration enables haptic-enabled surgical navigation partnerships with robotics platforms. |
| Reimbursement Strategy | Same-day joint reconstruction protocol coverage expansion drives ambulatory surgery center capital equipment procurement cycles. |
Research Methodology
Desk research of FDA 510(k) clearance databases, EU MDR notified body audit records, and hospital procurement contract filings preceded structured interviews with dental equipment product managers, orthopedic surgical navigation engineers, GPO contracts managers, and rare earth magnet procurement leads. Secondary validation drew from customs trade data for brushless motor component flows, ISO 13485 certification registries, and ambulatory surgery center capital expenditure disclosures. Bottom-up unit demand estimates triangulated against top-down market value reconstructions.
Variance decomposition across product type, end user procurement authority, and application-specific torque requirements shaped the analytical framework over the projection horizon. CAGRs were derived from segmented unit shipment trajectories and average selling price evolution patterns. Industry-specific forecast inputs included EMA audit queue duration assumptions and ambulatory surgery center same-day joint reconstruction protocol adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained EU MDR audit capacity expansion or abrupt rare earth export restriction scenarios would require recalibration. Forecasts reflect documented assumptions regarding regulatory pathway stability and orthopedic robotics partnership formation velocity. Recalibration cycles align with material shifts in notified body resource allocation and ambulatory surgery center reimbursement policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Automotive Blower Motor Market
Electric Motor
Motorcycle Battery Market
Electric Motor
Electric Trolling Motors Market
Electric Motor
Garden Tool Lithium Battery Market
Electric Motor
Automotive Traction Motor Market
Electric Motor
US Solar E-Bike Market
Electric Motor
Global Motor Management Market
Electric Motor
Automotive Seat Motor Market
Electric Motor
Outboard Electric Motors Market
Electric Motor
Electric Vehicle Motor Control Unit Market
Electric Motor
United States AC Motor Market
Electric Motor
Electric Vehicle Traction Motor Core Market
Electric Motor
Automotive Torque Actuator Motor Market
Electric Motor
Europe Automotive Torque Actuator Motor Market
Electric Motor
E-Bike Motor Market
Electric Motor
Electric Vehicle Permanent Magnet Synchronous Motors Market