
 Automotive Induction Motors Market | 2026-2036
Automotive Induction Motors Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Induction Motors Market Outlook
Chinese motor manufacturing capacity is hardening as domestic foundries scale laminated core production for EV traction applications. Siemens AG leverages its European automation footprint to supply winding equipment for tier-one stator lines. Nidec Corporation anchors the Asia-Pacific supply base with concentrated rotor die-casting operations in Japan and Vietnam. Robert Bosch GmbH competes through integrated inverter-motor systems that reduce assembly complexity for German OEM platforms.
Automotive induction motors are asynchronous AC machines that convert electrical energy into mechanical torque through electromagnetic induction between stator windings and a conductive rotor, typically operating at efficiencies above 90% in three-phase configurations for continuous-duty traction applications. Three-phase designs dominate OEM installations due to superior thermal management under variable load cycles, while single-phase variants retain niche presence in auxiliary pumps and fan drives. Medium power rating segments capture the largest share of current automotive demand, though ultra high ratings are expanding fastest in heavy-duty electric commercial vehicles where sustained torque output determines drivetrain selection.
The EPA enforces Corporate Average Fuel Economy standards that indirectly mandate motor efficiency gains across electrified vehicle platforms, while the EU Green Deal establishes carbon-border adjustments affecting imported motor components. China's MIIT administers GB standards for new energy vehicle motor efficiency that determine domestic market access for foreign suppliers. Stakeholders must monitor how divergent efficiency test cycles across these jurisdictions reshape product development roadmaps and certification costs.
Market Dynamics
Three-phase induction motor procurement is concentrating around EV powertrain platforms as OEMs eliminate redundant motor variants and consolidate supplier bases to reduce qualification overhead.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:Indirect efficiency mandates force electrified platform adoption, expanding addressable motor volumes for traction applications.
- Copper rotor die-casting:Improved conductivity over aluminum variants raises continuous power density, enabling downsized motor packages without thermal derating.
- China's MIIT GB efficiency standards:Domestic certification requirements create captive demand for locally manufactured stator assemblies and laminated core supply.
Market Restraints
- Neodymium price volatility:Permanent magnet alternatives in synchronous machines face rare earth cost swings that distort total motor system economics against induction designs.
- Stator lamination supply concentration:Premium electrical steel production clusters in Japan and South Korea, exposing motor manufacturers to single-source disruption risk.
- EU Green Deal carbon-border adjustments:Imported motor components face embedded emissions tariffs that compress margin structures for non-EU assembly operations.
Strategic Opportunities
- Heavy-duty electric commercial vehicles:Ultra high power rating segments remain underpenetrated, with sustained torque requirements favoring induction architectures over permanent magnet alternatives.
- Integrated inverter-motor systems:Power electronics convergence with traction motors reduces wiring harness complexity and assembly labor for OEM final integration.
- India's PLI scheme for automotive components:Production-linked incentives attract motor manufacturing capacity to serve domestic EV adoption and regional export positioning.
Industry Challenges
- Electromagnetic compatibility certification:Motor-inverter system validation against CISPR 25 and OEM-specific EMC protocols extends development timelines by 8-14 months.
- High-voltage insulation system qualification:800V platform migration requires redesigned slot liners and impregnation resins with limited validated supplier options.
- Legacy thermal management integration:Induction motor cooling circuits must interface with existing vehicle HVAC architectures without dedicated refrigerant loops.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Induction Motors Market |
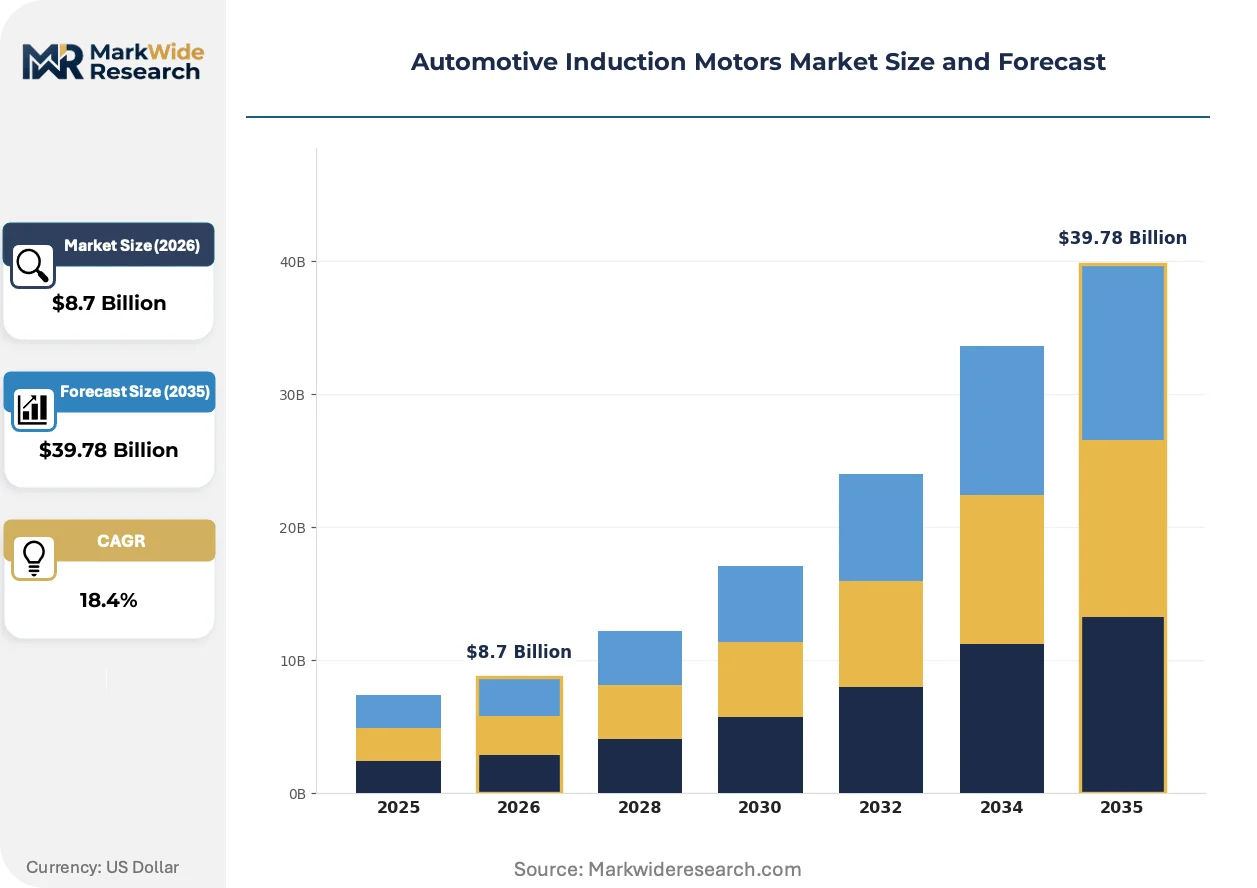
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-phase, Three-phase, Special-purpose, Submersible End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Fleet Operators Power Rating: Low, Medium, High, Ultra High Installation: Indoor, Outdoor, Scalable, Integrated |
| Companies Covered | ABB Ltd., Siemens AG, Nidec Corporation, WEG Industries, General Electric Company, Regal Beloit Corporation, Robert Bosch GmbH, Denso Corporation, Mitsubishi Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Induction Motors Market Strategic Shifts
Hairpin winding technology is compressing stator slot fill factors while automated insertion equipment reduces labor content in high-volume motor lines.
Hairpin conductor geometries replace traditional round-wire random windings with rectangular copper profiles that raise slot fill from 40% to 70%. Tier-one suppliers in Germany and China are retrofitting stator lines with laser welding stations for hairpin joint completion. The technology is unifying motor power density benchmarks across passenger car and light commercial platforms previously segmented by winding methodology.
The EU F-Gas Regulation phases down hydrofluorocarbon refrigerants used in motor cooling systems, forcing adoption of CO2-based thermal management. Motor manufacturers must redesign housing interfaces and sealing systems for 120-bar operating pressures. Heavy-duty segments in Scandinavia and Germany are first movers due to earlier fleet electrification mandates.
Fleet operators now specify motor remanufacturing clauses in procurement contracts rather than replacement-unit purchasing. Leasing structures and battery-electric truck deployments in California and the Netherlands embed residual value guarantees requiring stator rewind capabilities. This contractual shift pressures OEMs to design serviceable lamination stacks and accessible bearing cartridges.
Automotive Induction Motors Market Segmentation
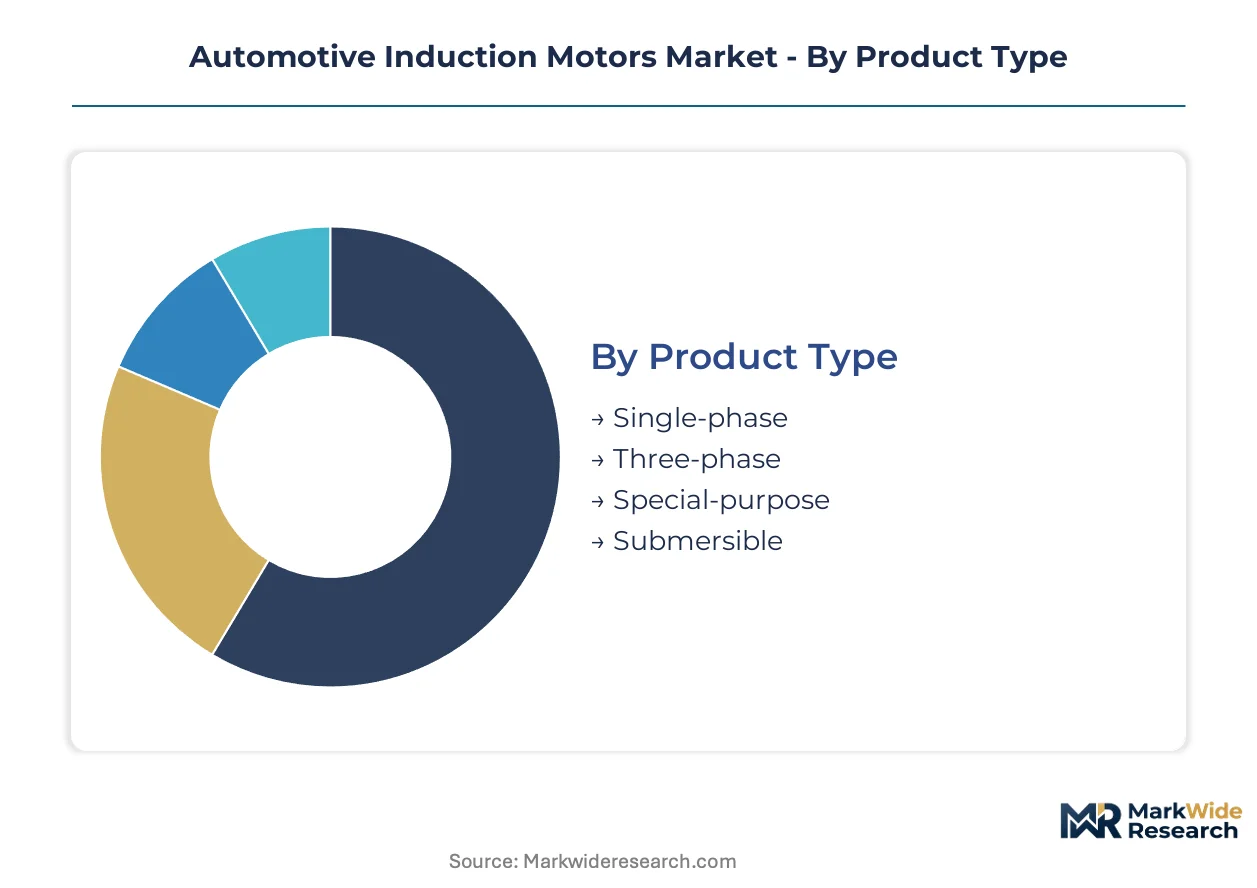
Segmentation in automotive induction motors reflects divergent technical requirements across vehicle platforms and procurement models. OEM consolidation of powertrain architectures is collapsing variant proliferation, while aftermarket service contracts are reshaping how motor longevity gets priced into fleet economics.
Product Type:
Standardization pressure from platform engineering teams is compressing the customization spectrum, yet special-purpose designs retain footholds in retrofit and niche commercial applications.
- Three-phase:Asynchronous AC machines with stator windings generating rotating magnetic fields for continuous-duty traction. Demand clusters in German and Chinese OEM powertrain platforms where thermal management under variable load cycles determines supplier selection. EPA Corporate Average Fuel Economy standards indirectly mandate electrified platform adoption, expanding addressable volumes for this configuration.
- Single-phase:Simpler winding topology operating without phase displacement, suited to auxiliary drives where torque ripple tolerance permits cost reduction. Auxiliary pumps and HVAC fan drives in light commercial vehicles represent the concentrated demand pocket, though platform consolidation is displacing this variant from new designs.
- Special-purpose:Custom winding configurations and housing geometries for retrofit hybridization programs and low-volume commercial conversions.
- Submersible:Hermetically sealed stator assemblies with epoxy-encapsulated windings for electric axle applications exposed to road spray and submersion risk.
Most installed capacity flows through Three-phase designs. Expansion is steepest in Special-purpose variants serving heavy-duty electrification retrofit demand.
End User:
Procurement authority is migrating upstream as vehicle assemblers absorb motor sourcing decisions previously decentralized across tier-one suppliers.
- OEMs:Original equipment manufacturers specifying motor performance envelopes for captive powertrain integration. German and US-based OEMs are consolidating supplier qualification lists to three or fewer motor vendors per platform generation, compressing qualification overhead but amplifying volume concentration risk.
- Vehicle Assemblers:Contract manufacturers and joint-venture operations executing final drivetrain marriage under OEM license. China's MIIT GB efficiency standards create captive demand for locally manufactured stator assemblies, favoring domestic foundry relationships over import-dependent sourcing.
- Fleet Operators:Battery-electric truck and bus purchasers embedding motor remanufacturing clauses in procurement contracts rather than replacement-unit purchasing.
- Aftermarket Providers:Independent service networks performing stator rewinds and bearing replacements for out-of-warranty vehicles.
Vehicle Assemblers capture the largest share of current procurement volume. Fleet Operators are expanding most quickly as residual value guarantees reshape contractual structures.
Power Rating:
Cost tier stratification follows vehicle mass and duty cycle intensity, with thermal boundary conditions determining feasible power density at each rating band.
- Medium:Continuous ratings between 50-150kW serving passenger car and light commercial traction. Hairpin winding technology adoption is compressing stator slot fill factors while automated insertion equipment reduces labor content in high-volume lines supplying this segment.
- Ultra High:Sustained outputs exceeding 250kW for heavy-duty electric commercial vehicles where continuous gradeability requirements favor induction architectures over permanent magnet alternatives. EU F-Gas Regulation phases down hydrofluorocarbon refrigerants used in motor cooling systems, forcing CO2-based thermal management redesigns for this rating band.
- Low:Sub-50kW outputs for micro-mobility and urban delivery applications with intermittent duty cycles.
- High:150-250kW ratings bridging passenger and commercial segments with intermittent peak loading tolerance.
Medium ratings dominate current automotive installations. Ultra High ratings are gaining share fastest in Scandinavian and German heavy-duty fleet electrification programs.
Installation:
Physical integration depth with vehicle architecture determines cooling circuit complexity and service accessibility trade-offs.
- Integrated:Motor-inverter systems sharing housing castings and thermal management circuits, reducing wiring harness complexity and assembly labor for OEM final integration. Robert Bosch GmbH competes through this architecture on German OEM platforms.
- Scalable:Modular motor designs permitting power rating adjustment through stator stack length variation without winding redesign.
- Indoor:Enclosed motor compartments within protected drivetrain bays, typical of passenger car applications with controlled thermal environments.
- Outdoor:Exposed axle-mounted configurations in commercial vehicles requiring enhanced sealing against pressure washing and road debris intrusion.
Integrated installations command the largest share of new platform engineering hours. Scalable designs are climbing the fastest as OEMs seek variant reduction across regional model lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where automotive induction motor production locates, with cost-of-compliance gaps between jurisdictions driving foundry investment toward markets offering efficiency-certification synergies and localized supply base proximity.
China
Domestic EV powertrain demand and MIIT GB efficiency standards are accelerating stator lamination foundry expansion in Jiangsu and Zhejiang provinces. The country's dual carbon goals tighten embedded emissions thresholds for motor imports, favoring captive supply chains. Nidec Corporation anchors rotor die-casting operations in Vietnam to serve Chinese tier-one assembly demand.
Germany
OEM platform consolidation around 800V architectures concentrates motor procurement decisions in Stuttgart and Munich engineering centers. The EU F-Gas Regulation phases down hydrofluorocarbon refrigerants, forcing CO2-based thermal management redesigns. Siemens AG leverages its European automation footprint to supply winding equipment for domestic stator lines.
United States
EPA Corporate Average Fuel Economy standards indirectly mandate electrified platform adoption across Detroit Three powertrain strategies. California Air Resources Board zero-emission vehicle mandates accelerate heavy-duty fleet electrification in the Central Valley logistics corridor. Fleet operators embed motor remanufacturing clauses in procurement contracts rather than replacement-unit purchasing.
Japan
METI technology roadmaps prioritize motor efficiency gains for export-oriented automotive component supply. Domestic laminated electrical steel production clusters in Tokyo Bay industrial zones, reducing import dependency for premium core materials. Hairpin winding automation equipment suppliers concentrate in Nagoya manufacturing technology corridors.
India
The PLI scheme for automotive components attracts motor manufacturing capacity to serve domestic EV adoption and regional export positioning. Tamil Nadu and Gujarat host emerging stator assembly operations targeting ASEAN market access. BIS efficiency certification requirements create compliance barriers for non-localized suppliers.
Automotive Induction Motors Market Competitive Environment
German and Japanese producers anchor one tier; Chinese and Southeast Asian specialists hold cost-optimized manufacturing positions. The vendor base stratifies across integrated powertrain suppliers, component-focused motor manufacturers, and automation equipment providers. Three archetypes dominate: diversified industrial conglomerates with automotive divisions, pure-play motor specialists with EV-dedicated capacity, and precision manufacturing equipment suppliers. Consolidation through strategic partnerships and geographic co-location with OEM assembly plants represent the dominant competitive vectors.
Among diversified industrial conglomerates, ABB Ltd. and Siemens AG exemplify the integrated automation-to-motor value chain archetype, while Robert Bosch GmbH occupies a position bridging component supply and systems integration. Nidec Corporation anchors the Asia-Pacific pure-play specialist tier. These entities represent how competitive positioning stratifies across geographic footprint breadth versus application-specific depth.
| Leading Market Players |
|---|
| ABB Ltd. |
| Siemens AG |
| Nidec Corporation |
| WEG Industries |
| General Electric Company |
| Regal Beloit Corporation |
| Robert Bosch GmbH |
| Denso Corporation |
| Mitsubishi Electric Corporation |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap motor specialists in Germany and Japan maintain pricing discipline through captive lamination sourcing and long-term OEM frame contracts that lock in volume commitments. Their ownership structure insulates margin targets from quarterly earnings pressure, allowing sustained investment in hairpin winding automation that commodity assemblers cannot match. This financial architecture concentrates supply-side bargaining power with incumbent tier-one suppliers while compressing margin recovery for import-dependent challengers facing EU carbon-border adjustment exposure.
Pricing Analysis
Direct-to-OEM contract pricing dominates volume transactions, with tier-one suppliers negotiating multi-year frame agreements that embed copper price escalation clauses and efficiency-certification milestones. Price differentiation separates GB-certified stator assemblies for the Chinese domestic market from CE-marked variants serving European OEM platforms, with the former commanding modest premiums due to MIIT compliance overhead. Pricing pressure stems from aluminum rotor substitution in cost-optimized auxiliary motor tiers, where Chinese foundries undercut copper die-casting economics. Fleet operators exhibit the highest price sensitivity, embedding remanufacturing clauses that shift lifetime cost calculations toward serviceability metrics; German OEM procurement teams show lowest sensitivity, prioritizing 800V platform compatibility and EMC validation speed over unit cost.
Supply Chain Analysis
Certification gating through MIIT GB standards, EPA Corporate Average Fuel Economy compliance, and EU F-Gas Regulation thermal management mandates fragments supplier qualification across jurisdictional boundaries. Geographic supply concentration centers on China for laminated core stamping and rotor die-casting, Japan for premium electrical steel production, and Germany for hairpin winding automation equipment. Raw material dependencies draw from copper cathode markets, electrical steel coils, and high-temperature insulation resins. Single-source vulnerability runs through Japanese electrical steel mills supplying high-frequency core grades for 800V traction applications. Distribution runs through tier-one system integrators marrying motors with inverters and gearboxes before OEM powertrain assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive induction motors market functions as a stable compounder, with regulatory efficiency mandates across the EPA, EU Green Deal, and China's MIIT creating irreversible replacement demand that underpins steady volume expansion.
For Market Incumbents: Deepen backward integration into electrical steel sourcing to insulate margin structures from Japanese mill concentration risk. Prioritize certification investment in MIIT GB efficiency tiers to secure Chinese domestic market access before carbon-border adjustments harden import barriers. The threat of permanent magnet synchronous motor substitution in passenger car platforms demands defensive R&D in copper rotor conductivity gains and hairpin winding cost parity. For New Entrants and Emerging Players: Digital-channel aftermarket platforms offering stator rewind services and bearing cartridge replacement kits present the most penetrable entry vector. Target fleet operator procurement contracts in California and the Netherlands where residual value guarantees create serviceable motor demand. White-space exists in heavy-duty electric commercial vehicle ultra-high power ratings, where induction architectures retain thermal advantages over permanent magnet alternatives. A direct sales model bypassing tier-one system integrators can capture margin otherwise absorbed by powertrain marriage operations. For Investors and Strategic Acquirers: Tier-one automotive suppliers with powertrain integration capabilities are the most active acquirer in this space, seeking motor specialists to complete inverter-motor system offerings. Long-term viability rests on 800V platform penetration and heavy-duty fleet electrification trajectories. Acquisition targets should display hairpin winding automation depth and GB/CE dual certification capacity. The signal to watch is EPA rulemaking on heavy-duty truck emissions standards, which would accelerate ultra-high power rating demand and reshape supplier valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | OEM consolidation around three-phase architectures reduces variant proliferation and qualification overhead for tier-one suppliers. |
| Copper Rotor Die-Casting Scale-Up | Conductivity improvements over aluminum variants enable downsized motor packages without thermal derating penalties. |
| Hairpin Winding Automation Investment | Laser welding stations in Jiangsu and Stuttgart raise slot fill factors while compressing labor content per stator. |
| Geographic Manufacturing Footprint | Vietnam rotor operations and Tamil Nadu stator lines position suppliers for ASEAN market access under India's PLI scheme. |
| Integrated Inverter-Motor System Development | Shared housing castings reduce wiring harness complexity and assembly labor for German OEM final integration. |
Study Parameters
Coverage spans Germany, China, the United States, Japan, and India, with primary inputs from each market informing demand calibration and regulatory impact assessment. The analysis combines structured interviews with OEM platform engineers, tier-one supplier procurement directors, stator line automation specialists, and aftermarket service network operators with secondary validation from vehicle production databases, IHS Markit registration data, MIIT GB standard filings, and EPA compliance disclosures. Bottom-up demand modeling triangulates against top-down powertrain electrification scenarios across the analysis window.
Granularity-level modeling captures power rating tiers, installation architectures, and end-user procurement authority as distinct forecast dimensions. The analytical framework projects volume and value outputs across the projection horizon by mapping OEM platform consolidation trajectories, fleet operator contract structures, and regional efficiency certification requirements. CAGRs derive from segment-level growth rate blending weighted by current installed base composition. Industry-specific forecast inputs include MIIT new energy vehicle production targets, EU F-Gas Regulation phase-down schedules, and EPA heavy-duty truck electrification timelines.
The model assumes a particular technology adoption path; alternative pathways for permanent magnet synchronous motor substitution or solid-state battery thermal management would alter the outlook for induction motor power density requirements. Forecasts reflect assumptions regarding copper price stability, electrical steel mill capacity expansion, and OEM 800V platform migration speed. Deviation in EPA rulemaking stringency or EU carbon-border adjustment implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Electric Motorcycle Market
Electric Motor
Electric Vehicle Motor Micro Controller Market
Electric Motor
Automotive Power Steering Motor Market
Electric Motor
Electric AC Motors Market
Electric Motor
Fluid Conveyance Products Motors Market
Electric Motor
Power Tool Lithium Battery Market
Electric Motor
North America Electric Motor Market
Electric Motor
Implant Motors Market
Electric Motor
Electric Propulsion Systems Market
Electric Motor
Voice Coil Motor Market
Electric Motor
Electric Drives Market
Electric Motor
High Speed Motor Market
Electric Motor
Automotive Traction Motor Market
Electric Motor
Europe Electric Motor Market
Electric Motor
Global Hub Motors Market
Electric Motor
Traction Motor Core Market