
 Intelligent Motor Control Market | 2026-2036
Intelligent Motor Control Market Size, Share, and Industry Trends Forecast 2026-2036
Intelligent Motor Control Market Foresight
Industrial distribution channels for motor control systems is tilting toward direct OEM partnerships and system integrator networks. ABB leverages its electrification portfolio to anchor large-scale manufacturing accounts across Europe. Siemens competes through its digital twin-integrated drive platforms that extend software-defined control capabilities. Rockwell Automation dominates North American factory automation channels with embedded servo and variable frequency drive solutions.
Intelligent motor control encompasses electronically governed drive systems that modulate torque, speed, and positioning through real-time feedback loops, typically operating across voltage classes from low-voltage to medium-voltage industrial power. These systems serve primarily to optimize energy conversion efficiency and enable precision motion in automated industrial processes. Variable frequency drives retain the largest installed base among product types, though integrated drive systems capture expanding margin pools through bundled control architecture. Field-oriented control technology leads in high-performance servo applications, while direct torque control gains traction in heavy-industry pump and conveyor installations where dynamic load response matters.
Regulators including the US Department of Energy, the EU Ecodesign Directive, and Japan's METI shape product standards through mandatory minimum efficiency tiers and harmonized testing protocols for industrial motor-drive combinations. Compliance with these frameworks determines market access for OEMs and influences procurement specifications across energy-intensive end users. Stakeholders must monitor evolving efficiency tier escalations and carbon-border adjustment mechanisms that will redefine competitive positioning in cross-border equipment supply.
Market Dynamics
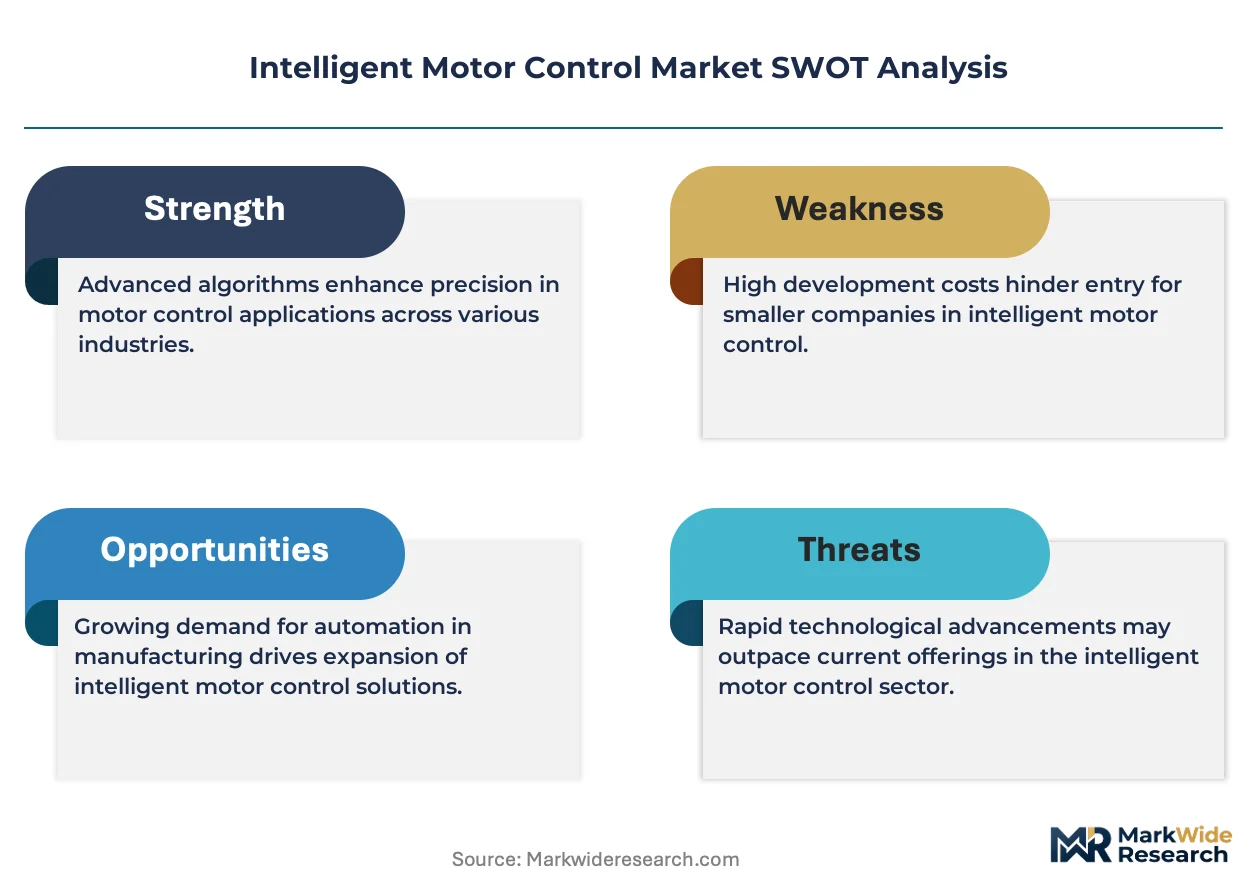
The EU Ecodesign Directive's tightening efficiency tiers are forcing OEMs to redesign motor-drive architectures around integrated power electronics rather than discrete component sourcing.
Growth Catalysts
- Industrial pump retrofits:Water treatment facilities across Germany and Japan are replacing fixed-speed motors with variable frequency drives to meet METI efficiency benchmarks and avoid carbon-border penalties on exported goods.
- REACH substance restrictions:The EU's phased limitations on rare-earth magnet processing are accelerating ferrite-permanent-magnet hybrid designs in servo motor manufacturing.
- Automotive assembly robotics:Precision conveyor systems in electric vehicle battery module production require field-oriented control systems with sub-millisecond torque response.
Market Restraints
- IGBT and SiC wafer concentration:Power semiconductor fabrication concentrates in Taiwan and South Korea, exposing drive manufacturers to single-source vulnerability for medium-voltage modules.
- Copper winding cost volatility:Stator and rotor material expenses fluctuate with London Metal Exchange pricing, compressing margin on low-voltage motor contracts.
- Functional safety certification delays:IEC 61508 SIL 3 validation timelines extend 14-18 months, freezing product launches for process industries.
Strategic Opportunities
- India PLI scheme for manufacturing:Production-linked incentives for industrial automation equipment are attracting drive system assembly capacity away from saturated European markets.
- Digital twin convergence:Siemens and ABB are bundling physics-based motor models with cloud-based condition monitoring, creating recurring software revenue streams alongside hardware sales.
- Direct-to-fleet service contracts:Mining operators in Australia are bypassing distributor networks for integrated drive-system maintenance agreements with performance-based uptime guarantees.
Industry Challenges
- Embedded software talent scarcity:Field-oriented control algorithm development requires specialized motor control engineers, with automotive and robotics sectors competing for the same limited pool.
- Legacy fieldbus integration:Brownfield manufacturing sites running PROFIBUS or DeviceNet require protocol gateway layers that add cost and failure points to new Ethernet/IP installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intelligent Motor Control Market |
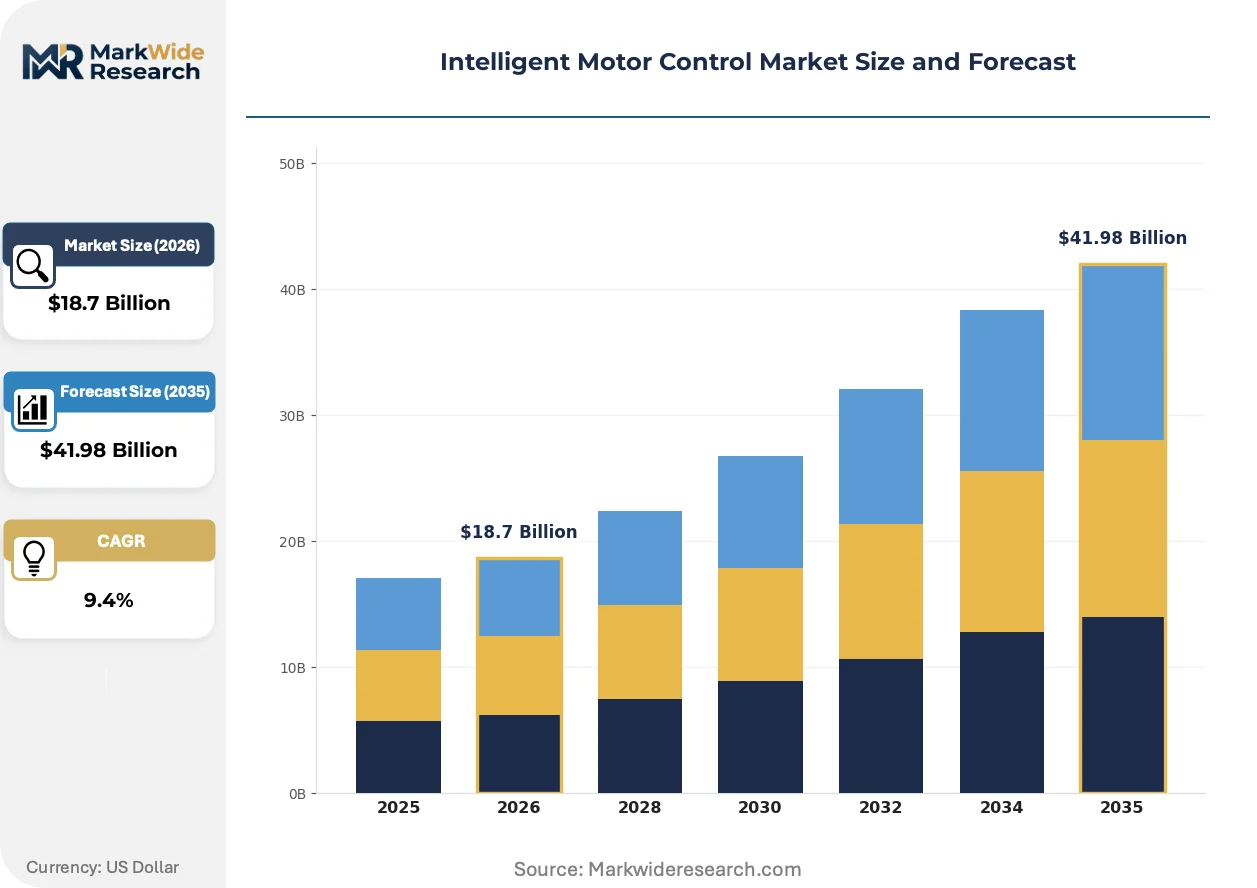
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Variable Frequency Drive, Servo Drive, Soft Starter, Integrated Drive Technology: Sensorless Control, Field-Oriented Control, Direct Torque Control, Model Predictive Control End User: Manufacturing, Automotive, Aerospace, Marine Application: Robotics, HVAC Systems, Conveyors, Pumps |
| Companies Covered | ABB, Siemens, Rockwell Automation, Schneider Electric, General Electric, Mitsubishi Electric Corporation, Larsen & Toubro, LSIS Co. Ltd, NXP Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intelligent Motor Control Market Shifts & Advancements
Intelligent motor control architectures are converging around software-defined functionality, with hardware commoditization pushing competitive differentiation toward predictive analytics and energy optimization algorithms.
Silicon carbide power modules are hybridizing with traditional IGBT platforms in medium-voltage drive designs, enabling switching frequencies above 20 kHz that reduce motor harmonic losses. Automotive tier-one suppliers are adopting these hybrid topologies for electric powertrain test benches. The technology is compressing thermal management costs while extending bearing life in high-speed spindle applications.
The EU's F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in liquid-cooled drive enclosures, compelling manufacturers to adopt dielectric fluid alternatives or air-cooled architectures. Industrial compressor OEMs in Germany face redesign cycles to maintain CE marking compliance. The regulation is accelerating adoption of heat-pipe thermal solutions in food and beverage processing lines.
Asset-as-a-service contracting is displacing capital purchase models in material handling, with warehouse operators paying per pallet-move rather than owning conveyor drive systems. System integrators in the United States are bundling installation, maintenance, and energy optimization into single-line-item subscriptions. The shift is most visible in e-commerce fulfillment centers where throughput volatility demands flexible capacity scaling.
Intelligent Motor Control Market Segmentation
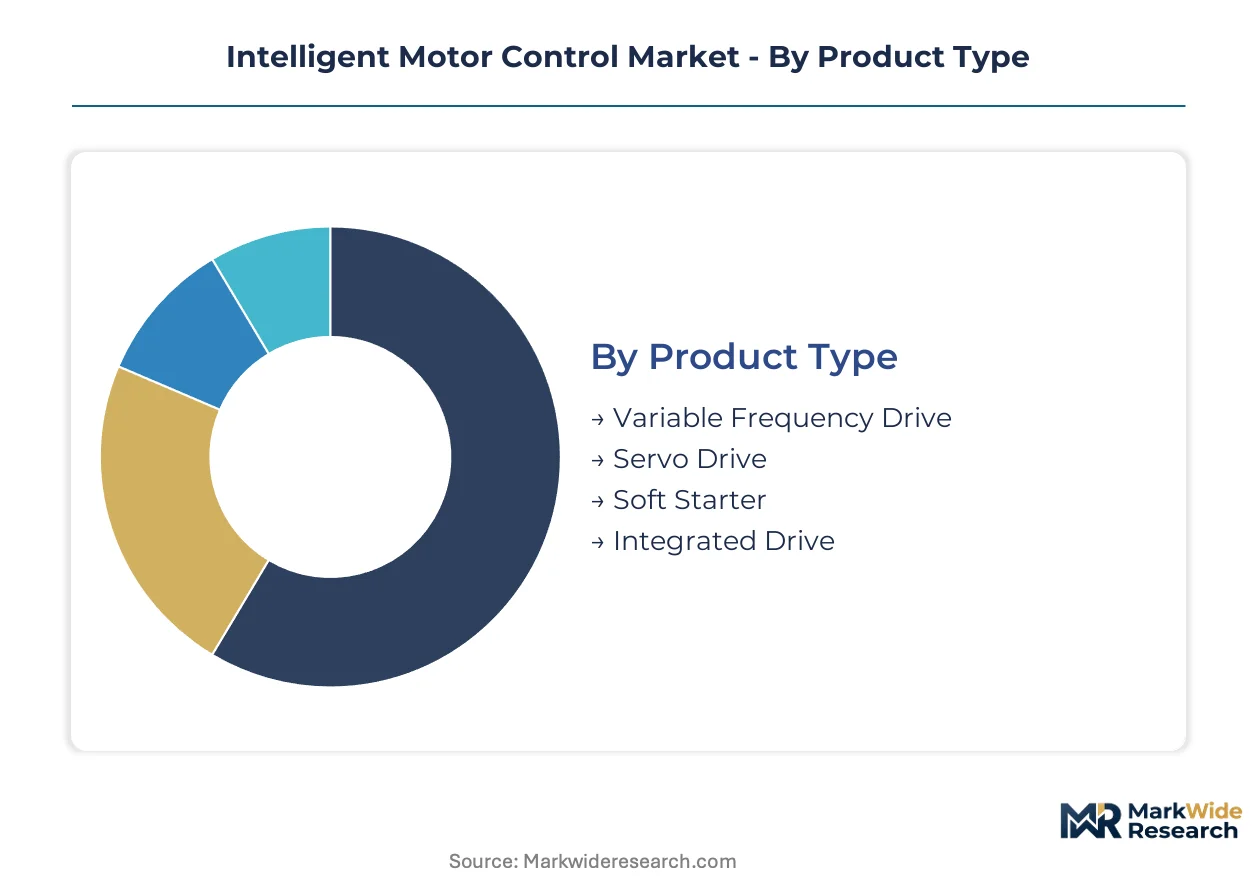
Intelligent motor control segmentation reveals how technology maturity and application intensity drive purchasing decisions across voltage classes and control architectures. Product type and technology choices determine energy recovery potential and precision capabilities, while end-user verticals impose distinct safety and environmental compliance burdens.
Product Type:
Mature hardware platforms dominate installed base volumes while integrated architectures capture expanding margin pools through bundled software control.
- Variable Frequency Drive:Electromechanical systems modulate AC motor speed by varying input frequency and voltage, retaining the largest installed base across industrial facilities. Water treatment plants in Germany deploy these drives to meet EU Ecodesign Directive efficiency tiers for pump retrofits.
- Integrated Drive:Bundled architectures combine power electronics, control logic, and communication interfaces in unified enclosures. Automotive battery module assembly lines specify these systems for sub-millisecond torque response in precision conveyor applications.
- Servo Drive:Closed-loop motor controllers execute precise position, velocity, and torque commands through encoder feedback.
- Soft Starter:Reduced-voltage starting equipment limits inrush current during motor acceleration.
Variable frequency drives handle the majority of throughput; integrated drive is expanding most quickly on share.
Technology:
Control algorithm selection hinges on dynamic load response requirements and computational resource availability at the edge.
- Field-Oriented Control:Vector-based algorithms decouple torque and flux components for high-performance servo applications. Electric vehicle powertrain test benches in Japan leverage this technology for precise dynamometer control under METI efficiency benchmarking protocols.
- Direct Torque Control:Hysteresis-based switching strategies deliver rapid torque response without coordinate transformations. Heavy-industry pump installations across Germany adopt this approach for conveyor systems facing abrupt load variations.
- Sensorless Control:Observer-based algorithms estimate rotor position without physical encoders.
- Model Predictive Control:Optimization-based strategies compute future state trajectories for constrained multivariable systems.
Field-oriented control anchors high-value precision applications; direct torque control is climbing the fastest on adoption curves.
End User:
Vertical-specific safety certifications and environmental operating conditions dictate control architecture durability and redundancy requirements.
- Manufacturing:General industrial automation spans material handling, packaging, and process equipment. German automotive tier-one suppliers specify IEC 61508 SIL 3 certified drives for robotic welding cells under EU machinery directive compliance.
- Automotive:Electric vehicle production and component testing demands precision motion control. Battery gigafactories in the United States deploy field-oriented servo systems for electrode coating and cell stacking operations.
- Aerospace:Flight control surface actuation and fuel pump systems require DO-178C software assurance.
- Marine:Propulsion and deck machinery applications face salt spray and vibration extremes.
Manufacturing commands the greatest installed volume; automotive is gaining share fastest on electrification capex.
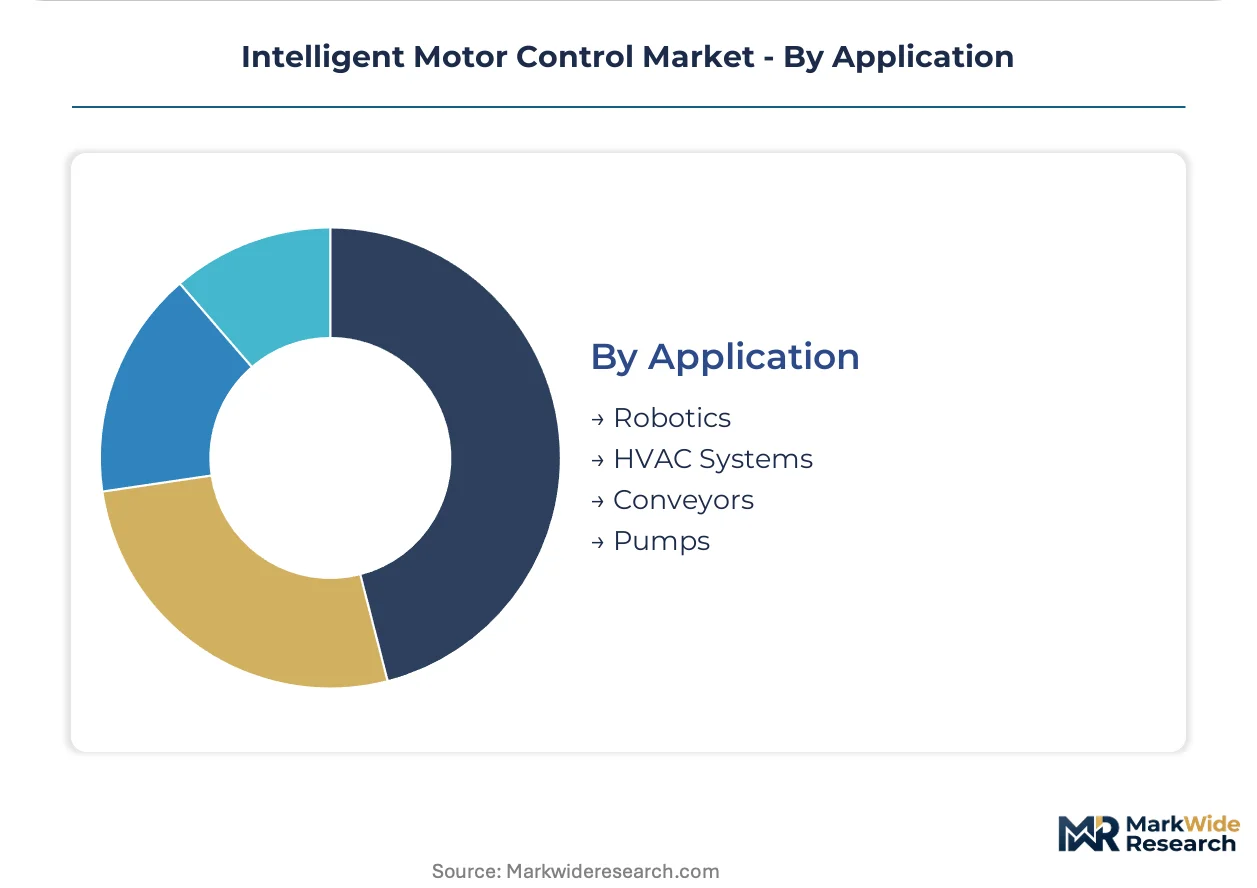
Application:
Motion profiles and duty cycle intensity determine thermal management requirements and bearing life expectations across equipment categories.
- Robotics:Multi-axis articulated systems demand synchronized servo control with path interpolation. Automotive assembly lines in Japan integrate these systems for electric vehicle battery module handling under METI automation incentives.
- Pumps:Centrifugal and positive displacement fluid handling dominates energy consumption in municipal infrastructure. German water utilities retrofit variable frequency drives to avoid carbon-border adjustment penalties on exported goods.
- HVAC Systems:Fan and compressor modulation for climate control in commercial buildings.
- Conveyors:Bulk material and unit handling systems require controlled acceleration profiles.
Pumps absorb the largest share of drive hardware shipments; robotics is expanding most steeply on precision automation demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Department of Energy anchors the regulatory framework shaping intelligent motor control procurement across North American manufacturing. Germany's EU Ecodesign Directive enforcement and Japan's METI efficiency benchmarks create parallel compliance corridors. Industrial clusters in automotive assembly and water treatment infrastructure concentrate demand across these three dominant geographies.
United States
Battery gigafactories in Michigan and Tennessee deploy field-oriented servo systems for electrode coating operations. The US Department of Energy mandates minimum efficiency tiers for industrial motor-drive combinations through federal procurement standards. Detroit-area automotive tier-one suppliers specify IEC 61508 SIL 3 certified drives for robotic welding cells under OSHA machinery safety coordination.
Germany
Water treatment facilities retrofit fixed-speed pumps with variable frequency drives to meet tightening EU Ecodesign Directive efficiency tiers. The F-Gas Regulation phases down hydrofluorocarbon refrigerants in liquid-cooled drive enclosures, compelling thermal architecture redesigns. Stuttgart's automotive assembly corridor integrates precision conveyor systems with sub-millisecond torque response for electric vehicle battery module handling.
Japan
Precision robotics manufacturers in Nagoya specify field-oriented control systems for automated assembly lines under METI automation incentives. Japan's efficiency benchmarking protocols for industrial motor-drive combinations shape product specifications for domestic and export markets. Yokohama's industrial automation cluster concentrates servo drive development for semiconductor manufacturing equipment.
India
Production-linked incentives under the PLI scheme attract drive system assembly capacity from saturated European markets. The Central Electricity Authority mandates efficiency standards for industrial motors deployed in energy-intensive manufacturing. Gujarat's industrial corridor hosts expanding variable frequency drive manufacturing for domestic infrastructure and export markets.
China
Dual carbon goals accelerate adoption of silicon carbide power modules in medium-voltage drive designs for steel and cement industries. The Ministry of Industry and Information Technology harmonizes testing protocols for motor-drive efficiency certification. Shanghai's Yangtze River Delta manufacturing cluster concentrates integrated drive system production for automotive and robotics export markets.
Intelligent Motor Control Market Competitive Landscape
Electrification conglomerates and automation specialists split the market into distinct capability tiers. The vendor base concentrates around integrated portfolio breadth rather than point-solution depth. Three archetypes dominate: diversified industrial electrification groups, pure-play factory automation vendors, and semiconductor-centric control platform developers. Competitive moves center on direct OEM partnership anchoring and system integrator network exclusivity arrangements.
Within the diversified electrification tier, ABB and Siemens exemplify integrated portfolio strategies spanning power electronics through cloud-based condition monitoring. Rockwell Automation occupies a position as the North American factory automation anchor with embedded servo and variable frequency drive solutions. Schneider Electric and General Electric represent additional conglomerate-tier participants with cross-regional manufacturing account penetration.
| Leading Market Players |
|---|
| ABB |
| Siemens |
| Rockwell Automation |
| Schneider Electric |
| General Electric |
| Mitsubishi Electric Corporation |
| Larsen & Toubro |
| LSIS Co. Ltd |
| NXP Semiconductors |
| Others |
Supply & Pricing Matrix
Taiwan's Hsinchu Science Park anchors silicon carbide wafer fabrication capacity, concentrating pricing power for medium-voltage drive modules among a handful of foundry operators. This geographic chokepoint transmits downstream into variable frequency drive and integrated system pricing across automotive and industrial automation procurement.
Pricing Analysis
Price spreads between German-manufactured and Chinese-assembled drive systems widen during periods of EU carbon-border adjustment enforcement. Three-tier pricing structure across premium, standard, and economy levels reflects IEC 61508 SIL certification grade and bundled after-sales service intensity. Cost compression in low-voltage motor contracts intensifies because copper winding expenses fluctuate with London Metal Exchange volatility. Municipal water utilities exhibit highest price sensitivity; battery gigafactories prioritize torque response precision over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates strategic sourcing decisions for power semiconductor modules. Manufacturing concentrates in Taiwan, South Korea, and Japan for IGBT and silicon carbide substrates. Raw material dependencies include rare-earth magnets, copper windings, and dielectric cooling fluids. Single-source vulnerability for medium-voltage modules threatens production continuity. Distribution runs through direct OEM partnerships and system integrator networks rather than traditional industrial distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The intelligent motor control market sits in early-cycle recovery as industrial electrification capex rebounds from efficiency mandate compliance deadlines. Automotive battery manufacturing expansion and water infrastructure retrofit programs provide the cyclical lift.
For Market Incumbents: Entrench position through backward integration into silicon carbide substrate supply and captive servo motor manufacturing. Lock in exclusive system integrator partnerships across Germany's automotive corridor to block emerging Asian competitors. Invest in IEC 61508 SIL 3 certification pipelines to maintain procurement specification control.
For New Entrants and Emerging Players: India's Gujarat industrial corridor offers underpenetrated variable frequency drive assembly demand under PLI scheme incentives. Target mid-tier manufacturing accounts in water treatment and food processing where brand loyalty remains weaker. Pursue asset-as-a-service subscription models to bypass incumbent distributor relationships.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors semiconductor-centric control platform developers with embedded software differentiation. Five-to-ten year viability hinges on field-oriented control algorithm IP and cloud-based condition monitoring integration. Watch for inflection when automotive OEMs consolidate drive system suppliers for platform standardization.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Substrates | Taiwanese wafer concentration creates margin capture opportunity for drive manufacturers with captive supply. |
| Digital Twin Platform Integration | Siemens and ABB bundling physics-based motor models generates recurring software revenue alongside hardware. |
| Asset-as-a-Service Contracting | Warehouse operators paying per pallet-move displaces capital purchase models in e-commerce fulfillment. |
| IEC 61508 SIL 3 Certification Investment | Fourteen-month validation timelines freeze competitors without pre-approved safety architectures. |
| Direct-to-Fleet Service Agreements | Australian mining operators bypass distributors for integrated drive-system maintenance with uptime guarantees. |
Research Methodology
Cross-validation between primary fieldwork and secondary regulatory filings anchors the qualitative findings. Plant engineers, OEM procurement teams, aftermarket service heads, and system integrator technical directors provided operational perspective. Secondary sources include EU Ecodesign Directive efficiency tier documentation, US Department of Energy federal procurement standards, METI benchmarking protocols, and customs trade data for motor-drive equipment. Bottom-up segment sizing triangulates against top-down industrial automation expenditure estimates.
Calibration against historical efficiency mandate compliance cycles and automotive electrification capex waves shapes the projection framework. Segmentation models span voltage class, control technology, end-user vertical, and application intensity across the analysis window. CAGRs derive from regression against industrial production indices and energy efficiency regulation escalation schedules. Silicon carbide adoption curves and embedded software talent availability constrain supply-side assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese semiconductor platform developers would shift outcomes. Material shifts in EU carbon-border adjustment mechanisms or REACH substance restriction timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Automotive Seat Motor Market
Electric Motor
North America Electric Motor Market
Electric Motor
Garden Tool Lithium Battery Market
Electric Motor
Europe Electric Commercial Vehicle Battery Pack Market
Electric Motor
Starter Motor Market
Electric Motor
Separately Excited Motor Market
Electric Motor
Canada Electric Motor for Electric Vehicle Market
Electric Motor
Europe Electric Motor Market
Electric Motor
Smart E-Drive Market
Electric Motor
North America Alternating Current (AC) Motor Market
Electric Motor
Global Automotive Motor Market
Electric Motor
Electric Traction Motor Market
Electric Motor
France Alternating Current (AC) Motor Market
Electric Motor
Electric Vehicle Motor Micro Controller Market
Electric Motor
Motors for Robot Body and Robot Wheels Market
Electric Motor
Europe Alternating Current (AC) Motor Market